
 North America Construction Market | 2026-2036
North America Construction Market Size, Share, and Industry Trends Forecast 2026-2036
North America Construction Market Outlook
The US Inflation Reduction Act is recalibrating the cost-of-entry calculus for contractors bidding on federally backed energy and infrastructure projects. Bechtel Corporation leverages its vertically integrated project delivery model to capture complex industrial and energy assignments. Turner Construction sustains market presence through technology leadership in sustainable building practices across commercial portfolios. Fluor Corporation anchors its competitive position in modular construction execution for large-scale energy infrastructure.
North America construction encompasses the planning, design, procurement, and physical assembly of buildings and civil infrastructure using materials such as reinforced concrete with specified compressive strengths of 3,000 to 6,000 psi, structural steel grades A992 and A572, and engineered wood products meeting ICC-ES evaluation criteria. Its primary commercial purpose is to create durable, code-compliant physical assets that support residential habitation, commercial enterprise, industrial production, and public service delivery. Residential buildings command the largest share of current investment flows, while green building technologies represent the fastest-expanding segment as energy code stringency tightens across jurisdictions. Concrete and steel retain dominant positions in material procurement volumes, though engineered wood and cross-laminated timber are gaining structural approval in mid-rise applications.
The US Environmental Protection Agency enforces emissions standards for construction equipment under Tier 4 Final regulations, while OSHA mandates fall protection and silica exposure limits that shape site safety protocols and labor costs. Canada's National Building Code and provincial variants in Ontario and British Columbia establish thermal performance minimums that filter material specifications and design choices. Mexico's CONAVI and federal housing agency standards influence cross-border project compliance for developers operating in integrated supply chains. Stakeholders must monitor evolving Buy America content requirements and carbon disclosure mandates as these rules increasingly determine bid eligibility and financing access for public projects.
Market Dynamics
The US Inflation Reduction Act is redirecting capital flows toward energy-efficient retrofits and clean manufacturing facilities, compressing project timelines and reshaping contractor qualification requirements across the continent.
Growth Catalysts
- Data center expansion:Cloud providers in Texas, Arizona, and Ontario are scaling infrastructure capacity to support AI compute loads and cloud storage demand.
- IRA tax incentives:Federal credits for energy-efficient building retrofits and domestic clean energy manufacturing are accelerating project pipelines.
- Semiconductor supply chain reshoring:CHIPS Act funding is driving fab construction and supporting infrastructure across the US Southwest and Ontario.
Market Restraints
- Structural steel price volatility:Fluctuations in A992 and A572 grade steel pricing compress margins on fixed-bid industrial projects.
- Skilled trades concentration:Electricians and welders cluster in legacy manufacturing regions, creating labor bottlenecks in emerging data center markets.
- Tier 4 Final compliance costs:EPA emissions standards for construction equipment add capital burden to fleet-dependent contractors.
Strategic Opportunities
- Cross-laminated timber structural approval:ICC-ES evaluation criteria expansion enables mid-rise commercial and residential applications previously reserved for concrete and steel.
- Mexico integrated supply chains:CONAVI and federal housing standards create cross-border project opportunities for US and Canadian contractors with compliance expertise.
- Modular construction convergence:Factory-built component integration with on-site assembly reduces weather risk and labor hour requirements.
Industry Challenges
- Buy America content verification:Domestic sourcing requirements for federally backed projects demand enhanced supply chain documentation and vendor qualification.
- Silica exposure compliance:OSHA permissible exposure limits require engineered controls and respiratory protection programs that extend mobilization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Construction Market |
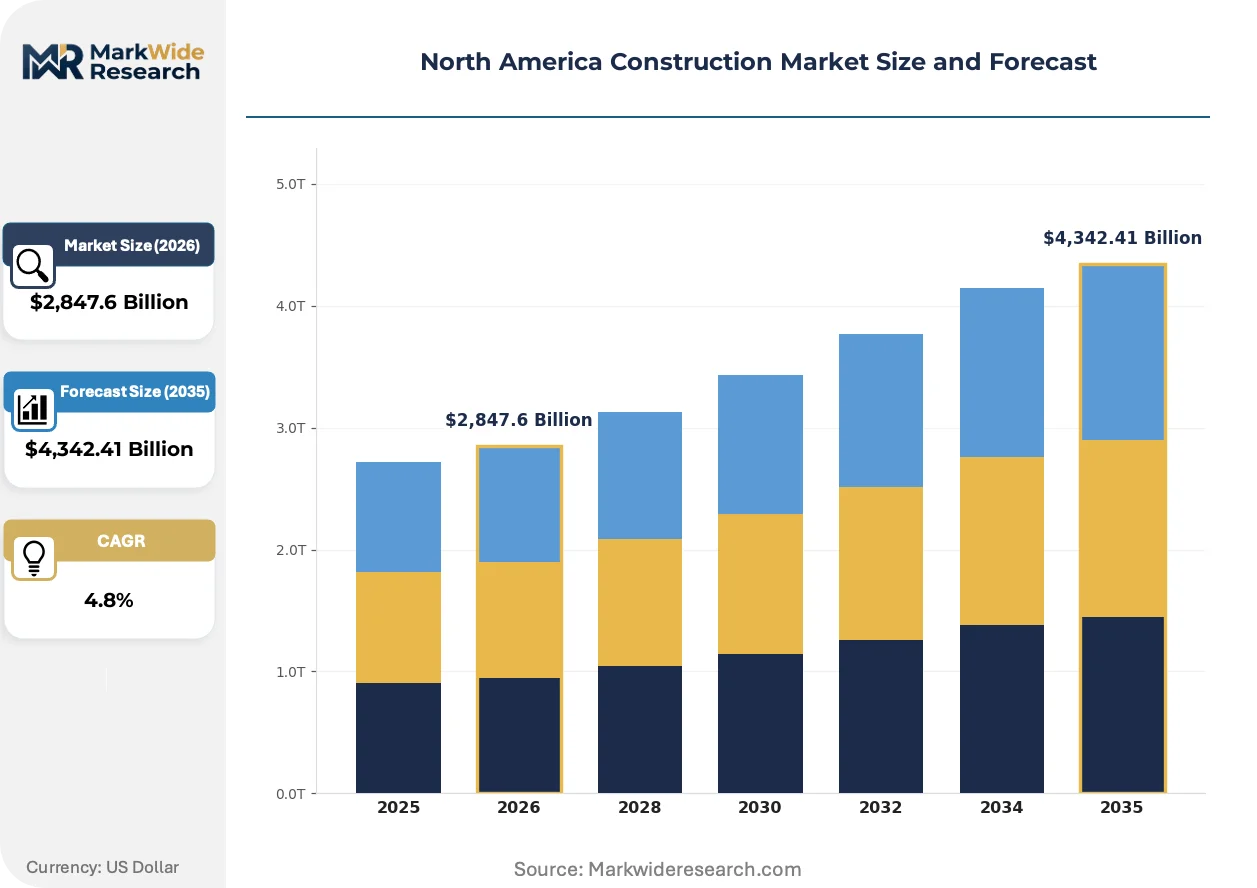
| Market Size in 2026 | $2,847.6 Billion |
| Market Size in 2035 | $4,342.41 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Buildings, Commercial Buildings, Infrastructure, Industrial Facilities Material: Concrete, Steel, Wood, Composites Technology: Modular Construction, Green Building, Smart Technologies, 3D Printing End User: Private Sector, Government, Real Estate Developers, Contractors |
| Companies Covered | Bechtel Corporation, Turner Construction, Fluor Corporation, Kiewit Corporation, SNC-Lavalin Group Inc., AECOM, PCL Construction Group Inc., Skanska USA, Clark Construction Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Construction Market Strategic Shifts
Digital fabrication and material science advances are compressing traditional construction timelines while regulatory pressure on embodied carbon forces specification changes across building portfolios.
Cross-laminated timber is expanding into mid-rise structural applications as ICC-ES evaluation criteria broaden approval scopes. Developers in British Columbia and the Pacific Northwest specify mass timber for commercial and institutional projects seeking carbon reduction credentials. This material shift is expanding into markets previously dominated by reinforced concrete and structural steel.
OSHA silica exposure mandates are tightening site safety protocols and reshaping material handling practices. Contractors must deploy engineered water suppression systems and respiratory protection programs to maintain compliance. Drywall installation and concrete cutting operations face the steepest compliance cost increases.
Design-build procurement is consolidating project delivery responsibility under single-contractor arrangements. Public sector clients in Texas and Ontario increasingly favor this model for complex industrial and infrastructure assignments. The shift compresses owner oversight requirements while transferring risk to contractors with integrated capabilities.
North America Construction Market Segmentation
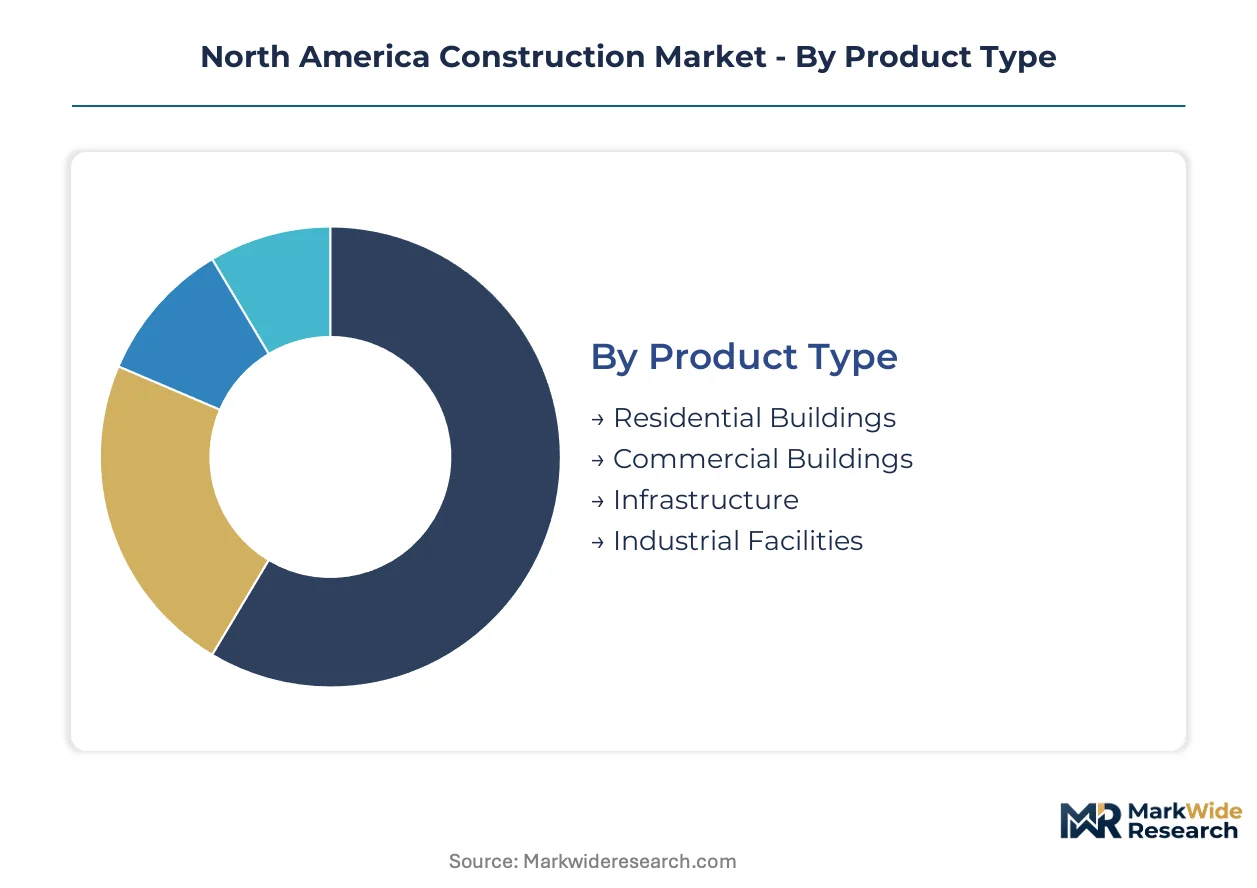
Construction procurement in North America fragments across asset classes with divergent code compliance burdens. Material specifications and delivery technologies determine which projects access IRA tax credits and which face Tier 4 Final equipment mandates.
Product Type:
Residential buildings carry ICC-ES evaluation and local zoning approvals. Commercial and industrial assets trigger additional OSHA fall protection and EPA emissions protocols.
- Residential Buildings:Single-family and multifamily structures using wood-frame and light-gauge steel systems. Demand clusters in Texas and Arizona where population migration strains housing supply. Builders face escalating lumber volatility and labor scarcity in electrical trades.
- Commercial Buildings:Office, retail, and hospitality assets with reinforced concrete cores and curtain wall envelopes. Ontario and British Columbia developers specify mass timber for carbon reduction credentials. Green building certification costs filter contractor qualification tiers.
- Infrastructure:Transportation, water, and utility assets governed by state DOT standards and federal Buy America content rules. Bridge and highway contractors document domestic steel sourcing for FHWA eligibility.
- Industrial Facilities:Manufacturing plants, warehouses, and data centers requiring heavy foundations and specialized mechanical systems. Semiconductor fabs in Arizona and battery plants in Ontario compress timelines to capture CHIPS Act and IRA incentives.
Leading the category by volume: Residential Buildings. Growing fastest: Industrial Facilities.
Material:
Cost tiers separate commodity inputs from engineered alternatives with performance certifications.
- Concrete:Ready-mix and precast products with specified compressive strengths of 3,000 to 6,000 psi. Data center slab-on-grade foundations in Texas consume high volumes. Supply constraints in desert markets extend pour schedules.
- Steel:Structural grades A992 and A572 for frames and rebar reinforcement. Industrial projects in Ontario and the US Southwest face A992 price volatility on fixed-bid contracts. Domestic mill capacity limits spot procurement flexibility.
- Wood:Dimensional lumber and engineered products including cross-laminated timber. British Columbia mass timber approvals expand into mid-rise commercial applications previously reserved for concrete.
- Composites:Fiber-reinforced polymers and advanced materials for corrosion-resistant infrastructure. Bridge deck overlays and coastal structures adopt these for lifecycle cost advantages.
Dominating procurement spend: Concrete and Steel. Expanding most quickly: Wood.
Technology:
Application maturity separates proven methods from pilot-stage innovations with limited vendor bases.
- Modular Construction:Factory-built components transported to sites for assembly integration. Data center builders in Texas deploy modular electrical rooms to compress energization timelines. Weather risk reduction drives adoption in northern climates.
- Green Building:Energy-efficient envelopes, renewable integration, and carbon reduction specifications. IRA tax credits accelerate retrofit pipelines for existing commercial stock. LEED and Passive House certifications filter material specifications.
- Smart Technologies:Building automation, IoT sensors, and digital twins for asset management. Commercial developers in Ontario embed these for operational efficiency claims.
- 3D Printing:Additive manufacturing for concrete walls and structural elements. Demonstration projects remain limited by code approval gaps and equipment capital requirements.
Widest deployment: Modular Construction. Steepest expansion trajectory: Green Building.
End User:
Customer type determines project scale, financing structure, and compliance documentation intensity.
- Private Sector:Corporate and institutional owners funding commercial, industrial, and residential assets. Technology firms in Arizona and Texas drive data center construction with accelerated capital deployment.
- Government:Federal, state, and municipal agencies procuring infrastructure and public buildings. Buy America content verification demands enhanced supply chain documentation for FHWA and GSA projects.
- Real Estate Developers:Speculative and build-to-suit commercial and residential sponsors. Market-rate multifamily developers in Ontario navigate provincial building code thermal performance minimums.
- Contractors:Design-build and construction management firms self-performing or subcontracting delivery. Tier 4 Final fleet compliance and silica exposure programs shape mobilization costs.
Generating largest project flow: Private Sector. Gaining procurement sophistication fastest: Government.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center and industrial construction demand concentrates in southwestern United States clusters, Ontario manufacturing corridors, and northern Mexico border zones. Federal tax incentives and supply chain reshoring mandates redirect capital flows toward these geographies. Regional regulatory divergence shapes contractor qualification requirements and material specification standards.
United States
Semiconductor fabrication and battery manufacturing facilities drive construction volume in Arizona, Texas, and the Southwest. CHIPS Act funding and IRA tax credits compress project timelines for federally backed energy infrastructure. Phoenix and Austin anchor the fastest-expanding data center clusters as cloud providers scale AI compute capacity.
Canada
Ontario's manufacturing corridor attracts electric vehicle battery plant investments with provincial and federal incentive stacking. The National Building Code and Ontario's thermal performance minimums filter material specifications for commercial and residential assets. Toronto and Vancouver developers specify mass timber for mid-rise carbon reduction credentials.
Mexico
Integrated supply chains with US and Canadian contractors expand cross-border project activity under CONAVI and federal housing agency standards. Nuevo León and the Bajío Region concentrate automotive and aerospace manufacturing construction. Nearshoring investments accelerate industrial facility development in northern border states.
North America Construction Market Competitive Environment
United States-based contractors anchor the premium-tier complex industrial segment; Canadian specialists hold positions in infrastructure and sustainable building delivery. The vendor base separates into three tiers: integrated EPC firms with self-perform capabilities, design-build specialists with technology platforms, and regional contractors with local regulatory expertise. Dominant competitive moves include design-build procurement consolidation and modular construction capability acquisition.
Within the integrated EPC tier, Bechtel Corporation and Fluor Corporation exemplify vertically structured project delivery models for energy and industrial assignments. Turner Construction occupies a position in technology-enabled sustainable building across commercial portfolios. These three entities represent distinct strategic archetypes: complex industrial execution, modular infrastructure deployment, and green building technology leadership.
| Leading Market Players |
|---|
| Bechtel Corporation |
| Turner Construction |
| Fluor Corporation |
| Kiewit Corporation |
| SNC-Lavalin Group Inc. |
| AECOM |
| PCL Construction Group Inc. |
| Skanska USA |
| Clark Construction Group |
| Others |
Value Chain & Pricing Dynamics
A992 structural steel price indices cascade through North American construction supply chains, compressing margins on fixed-bid industrial projects while rewarding contractors with captive fabrication capabilities or long-term mill contracts. This commodity volatility stratifies the vendor base into price-takers exposed to spot markets and price-makers with upstream integration.
Pricing Analysis
Volume concentration in residential and infrastructure segments runs on thin margins, while specialized industrial and data center projects command premium pricing through performance guarantees and accelerated delivery. Three-tier pricing structure across premium, standard, and economy levels separates design-build EPC firms with self-perform capabilities from regional contractors bidding commodity work. Cost compression in standard-tier commercial construction is intensifying because lumber volatility and labor scarcity erode predictable costing. Public sector infrastructure buyers exhibit highest price sensitivity due to competitive bidding mandates, while technology firms deploying data center capacity prioritize schedule certainty over unit cost.
Supply Chain Analysis
Electrician and welder availability constraints in Texas, Arizona, and Ontario bottleneck project execution even when material flows remain intact. Steel production draws from domestic mills in the US Midwest and Ontario, while engineered wood products feed from British Columbia and Pacific Northwest timber basins. Concrete supply rests on regional ready-mix plant networks with desert market capacity constraints. Single-source vulnerability in specialized electrical equipment for data centers creates procurement risk. Distribution runs through contractor-direct mill relationships for structural steel and builder merchant networks for commodity lumber and finishing materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American construction is consolidating around contractors with integrated capabilities and balance sheet depth, as Tier 4 Final compliance costs and silica exposure mandates force smaller players toward subcontractor roles or exit.
For Market Incumbents: Acquire modular fabrication facilities to capture factory-built component demand from data center and industrial clients facing compressed timelines. Secure captive steel supply through mill partnerships or backward integration into rebar fabrication. This counters margin erosion from A992 price volatility and protects against fixed-bid contract losses. For New Entrants and Emerging Players: Enter via cross-laminated timber specialization serving British Columbia and Pacific Northwest commercial developers seeking carbon reduction credentials. Target mid-rise institutional projects where ICC-ES evaluation criteria expansion has opened structural applications previously reserved for concrete and steel. Lead with design-assist procurement to reduce owner risk perception. For Investors and Strategic Acquirers: The window for entry favors contractors with modular construction capabilities and IRA-exposed project pipelines. Long-term viability hinges on exposure to federally backed energy infrastructure and data center construction rather than speculative residential development. Watch CHIPS Act funding disbursement velocity as the inflection signal for semiconductor fab construction demand.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fabrication Acquisition | Captures factory-built demand from cloud providers compressing data center energization timelines in Texas and Arizona. |
| Green Building Certification Investment | Unlocks IRA tax credit eligibility for energy-efficient retrofit pipelines across federally backed commercial portfolios. |
| Cross-Border Compliance Capability | Positions contractors for CONAVI-standard projects in Nuevo León as nearshoring accelerates northern Mexico industrial development. |
| Design-Build Procurement Consolidation | Compresses owner oversight requirements while transferring risk to integrated contractors in Ontario manufacturing corridors. |
| Mass Timber Specification Leadership | Captures mid-rise commercial work in Toronto and Vancouver where carbon reduction credentials filter contractor selection. |
Study Parameters
Independent corroboration across project developers, EPC contractors, and material procurement leads underwrites the qualitative findings on supply chain constraints and pricing dynamics. Primary fieldwork encompassed interviews with construction management executives, union training coordinators, and municipal building officials across Texas, Arizona, Ontario, and British Columbia. Secondary validation drew from EPA Tier 4 Final enforcement data, OSHA silica exposure compliance records, ICC-ES evaluation reports, and FHWA Buy America documentation requirements. Bottom-up project pipeline tracking and top-down regional construction spend estimates were reconciled through iterative triangulation.
Comparable historical periods spanning previous infrastructure stimulus cycles and commodity price volatility episodes anchored the forecast window. The analytical framework modeled construction spend across product type, material category, delivery technology, and end-user segments throughout the projection horizon. CAGRs were derived from regression analysis against macroeconomic drivers and policy incentive trajectories. Segment-specific inputs included CHIPS Act funding velocity, IRA tax credit uptake rates, and data center power allocation announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt interest rate shifts or federal incentive program modification. Material deviation in steel price trajectory, skilled trades availability, or Buy America content rule expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Middle East & Africa Infrastructure Construction Market
Building Construction
GCC Green Buildings Market
Building Construction
Indonesia Construction Market
Building Construction
Germany Commercial Construction Market
Building Construction
Eastern Europe Construction Market
Building Construction
Japan Construction Market
Building Construction
Ireland Data Center Construction Market
Building Construction
Egypt Residential Construction Market
Building Construction
Global Modular Fabrication Market
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
GCC Construction Market
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
Latin America Construction Market
Building Construction
Dominican Republic Construction Market
Building Construction
China Construction Market
Building Construction
Africa Construction Market