
 Marine HVAC System Market | 2026-2036
Marine HVAC System Market Size, Share, and Industry Trends Forecast 2026-2036
Marine HVAC System Market Foresight
Variable refrigerant flow integration with shipwide energy management platforms is tilting procurement specifications toward digitally native HVAC architectures. Wärtsilä Corporation leverages its marine propulsion heritage to bundle climate systems with vessel automation suites. Daikin Industries anchors its position through compressor technology leadership and captive refrigerant circuit production. Carrier Global Corporation competes on global service density, sustaining aftermarket revenue through port-level maintenance networks.
A marine HVAC system encompasses heating, ventilation, and air conditioning equipment engineered for salt-laden, space-constrained, and motion-affected maritime environments, typically constructed from corrosion-resistant alloys with redundant cooling loops to maintain pressurized compartments between 18°C and 25°C across sea states. These systems sustain crew habitability, protect electronic cargo, and preserve perishable freight across voyage profiles. Chiller systems command the largest installed base due to scalability across commercial vessel classes, while heat pumps represent the fastest-expanding technology segment as operators seek to reduce auxiliary engine load. Retrofit installations are gaining structural importance as regulatory deadlines force legacy fleet upgrades ahead of physical vessel replacement cycles.
The International Maritime Organization's MARPOL Annex VI and the EU MRV framework shape equipment specifications by mandating documented energy consumption and refrigerant containment protocols for vessels calling at European and North American ports. Classification societies including DNV and Lloyd's Register enforce HVAC redundancy and fire damper standards that filter market access to certified suppliers. Shipowners must weigh total lifecycle carbon intensity against upfront capital outlay as environmental compliance tightens across flag states and charterer requirements.
Market Dynamics
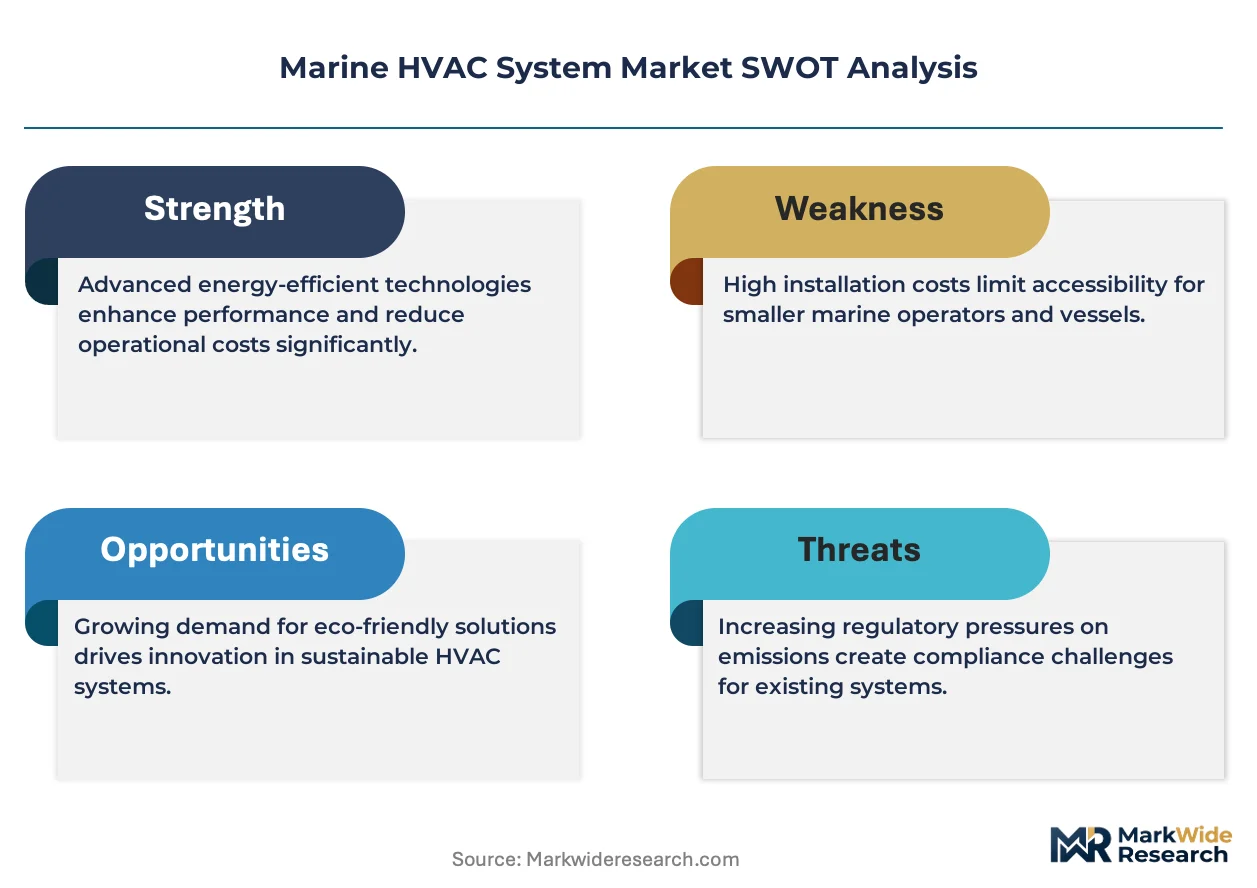
Energy efficiency mandates from the International Maritime Organization are compressing replacement cycles and forcing shipowners toward digitally integrated climate systems that reduce auxiliary engine load.
Growth Catalysts
- IMO EEDI Phase 3 compliance deadlines:Shipowners face mandatory efficiency thresholds that favor heat pump retrofits over conventional chiller expansions.
- Offshore wind service vessel expansion:North Sea and East Asian wind farm maintenance fleets require redundant HVAC for technician habitability in harsh environments.
- Copper-nickel alloy fabrication advances:Improved corrosion resistance extends system lifecycles in salt-laden engine room installations.
Market Restraints
- Refrigerant cost volatility:F-Gas Regulation quota reductions in Europe drive HFC price spikes that compress installer margins.
- East Asian shipyard concentration:Over 70 percent of newbuild contracting clusters in China, South Korea, and Japan, creating single-source dependency for integrated package procurement.
- Space constraints in legacy hulls:Retrofit installations face physical incompatibility with 1990s-era pipe routing and electrical load limits.
Strategic Opportunities
- Indian coastal cargo fleet modernization:The country's Sagarmala port development program triggers demand for climate-controlled coastal container vessels.
- Artificial intelligence predictive maintenance convergence:Machine learning algorithms applied to compressor vibration data enable condition-based overhaul scheduling.
- EU Green Deal maritime funding windows:Innovation subsidies for zero-emission auxiliary systems accelerate heat pump adoption in European-flagged fleets.
Industry Challenges
- Marine refrigeration technician scarcity:Specialized certification requirements for offshore electrical work limit qualified installer availability in secondary ports.
- Classification society recertification timelines:DNV and Lloyd's Register documentation reviews for HVAC modifications extend drydock schedules by two to four weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine HVAC System Market |
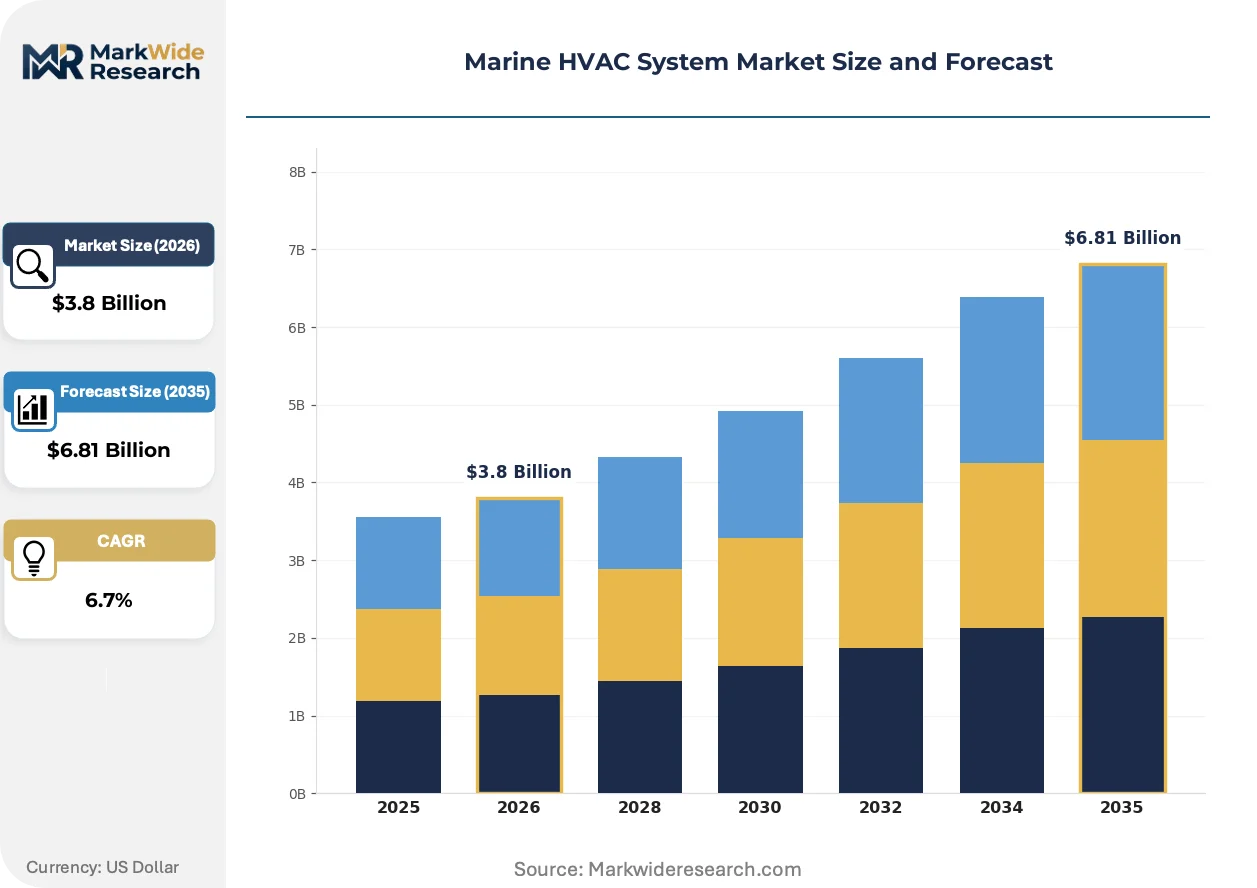
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Conditioning, Heating Units, Ventilation Fans, Control Systems End User: Commercial Vessels, Cargo Ships, Passenger Ships, Luxury Yachts Technology: Rooftop Units, Split Systems, Chiller Systems, Heat Pumps Installation Type: New Installation, Retrofit, Replacement, Maintenance |
| Companies Covered | Wärtsilä Corporation, Trane Technologies (Thermo King), Daikin Industries, Heinen & Hopman, Dometic Group, Carrier Global Corporation, Mitsubishi Electric Corporation, Fujitsu General Limited, Johnson Controls International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine HVAC System Market Shifts & Advancements
Digital integration and refrigerant chemistry shifts are restructuring how climate systems are specified, procured, and maintained across vessel classes.
Magnetic bearing centrifugal compressor technology is migrating from land-based commercial buildings to large cruise ship chiller plants. Carnival Corporation and Royal Caribbean International specify oil-free compression for reduced maintenance intervals. This migration from mechanical bearing systems eliminates lubricant contamination risks in redundant cooling loops.
Europe's F-Gas Regulation phasedown schedule forces refrigerant transition planning across EU-flagged fleets. Shipowners must document containment protocols and leak detection systems to maintain port access rights. The regulation most affects reefer vessel operators who face cascading retrofit costs across multiple cargo holds.
Charterer sustainability scorecards now embed HVAC energy intensity metrics alongside vessel speed and fuel consumption. Major commodity traders evaluate ship climate efficiency when fixing three to five year contracts. This behavioral shift appears most prominently in Australian iron ore and Middle Eastern LNG trades where cargo owners publish emission reduction targets.
Marine HVAC System Market Segmentation
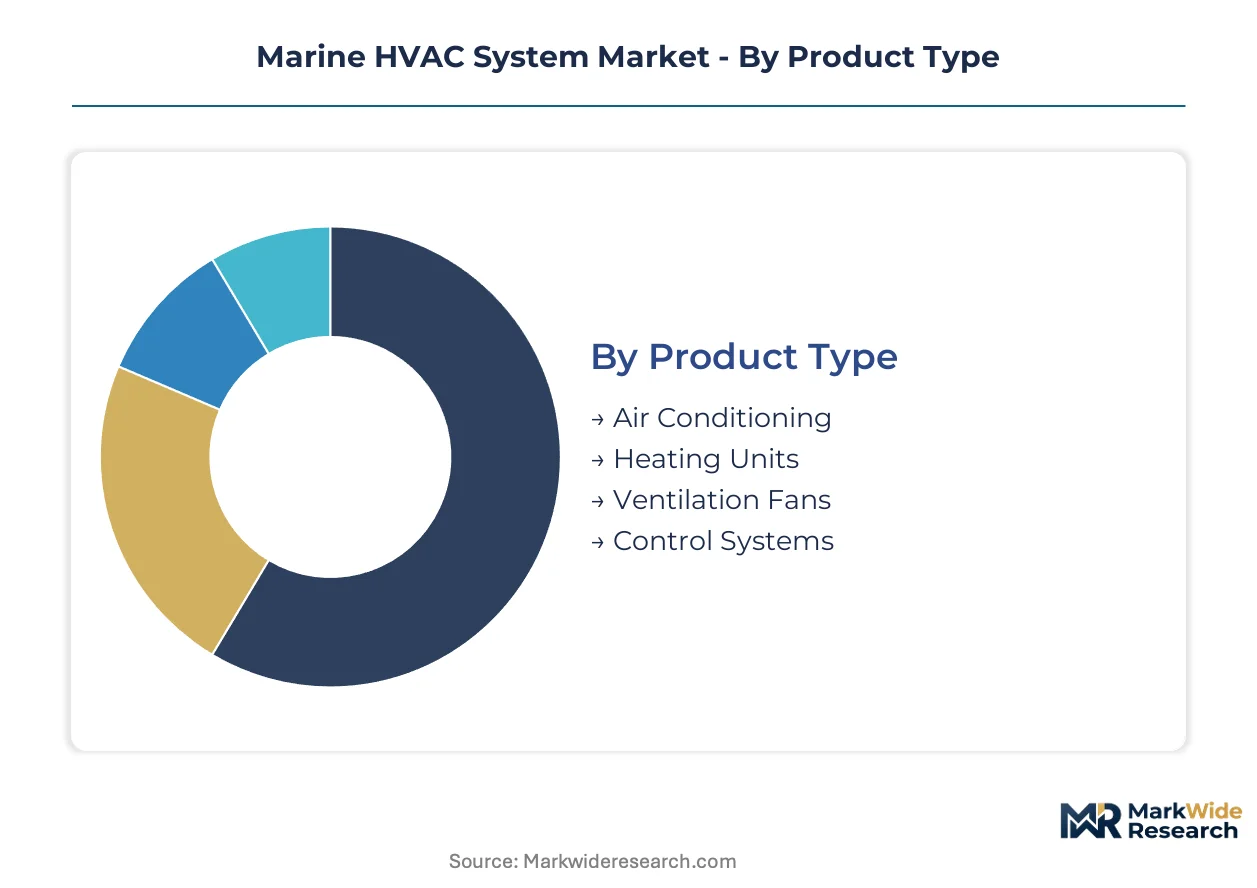
Marine HVAC procurement specifications diver sharply between newbuild shipyards and legacy fleet operators, with regulatory pressure and vessel lifecycle stage dictating technology choices across each segment boundary. Understanding these splits reveals where capital expenditure concentrates versus where operational budgets dominate.
Product Type:
Climate hardware spans comfort conditioning through environmental safety equipment, with salt corrosion resistance and redundant cooling loops as universal design requirements.
- Air Conditioning:Packaged DX systems and chilled water air handlers regulate crew quarters and passenger accommodations, with cruise operators in Miami and Barcelona demanding whisper-quiet compressor packages for premium cabin ratings.
- Heating Units:Electric resistance coils and hydronic boiler packages maintain engine room temperatures and prevent fuel gelling in Arctic routes; offshore supply vessels operating Norway's Barents Sea fields prioritize explosion-proof heating arrays.
- Ventilation Fans:Axial and centrifugal blowers manage smoke extraction and fresh air exchange, with fire damper integration mandated by Lloyd's Register for commercial certification.
- Control Systems:Building automation modules adapted for pitch-roll compensation enable remote monitoring from shore-based fleet centers.
Established volume favors Air Conditioning; emerging adoption favors Control Systems.
End User:
Customer archetypes range from price-sensitive bulk operators to specification-intensive superyacht builders, with charter contract duration directly correlating to HVAC investment intensity.
- Commercial Vessels:Ferries, tugs, and offshore support ships prioritize reliability over efficiency, with Greek and Turkish operators favoring standardized chiller packages for rapid parts availability in Piraeus and Istanbul.
- Cargo Ships:Container carriers and bulkers install minimal crew comfort systems, though reefer vessels demand precision temperature control across multiple cargo holds; Singapore-flagged fleets lead in heat pump retrofits for EEDI compliance.
- Passenger Ships:Cruise operators specify redundant capacity exceeding 150% of calculated load to ensure zero downtime during Caribbean and Mediterranean itineraries.
- Luxury Yachts:Custom fabrication dominates, with Dutch and Italian yards integrating concealed ducting and vibration isolation for owner-guest experience.
Passenger Ships command premium pricing tiers; Cargo Ships drive replacement volume through regulatory retrofit mandates.
Technology:
System architecture choices reflect vessel size, available machinery space, and shore power compatibility requirements at intended port calls.
- Rooftop Units:Self-contained weatherized packages suit small commercial craft and harbor patrol boats where below-deck space is unavailable.
- Split Systems:Condensing units paired with multiple evaporators serve mid-size offshore wind service vessels operating Germany's North Sea installations.
- Chiller Systems:Centralized chilled water plants with seawater heat rejection dominate cruise ship and large yacht applications; Carnival Corporation specifications require magnetic bearing compressors for oil-free operation.
- Heat Pumps:Reversible refrigeration cycles reducing auxiliary engine load are climbing the fastest as IMO efficiency deadlines approach, with Scandinavian ferry operators pioneering shore-to-ship heat pump integration.
Chiller Systems retain installed base dominance; Heat Pumps are gaining share fastest among newbuild specifications.
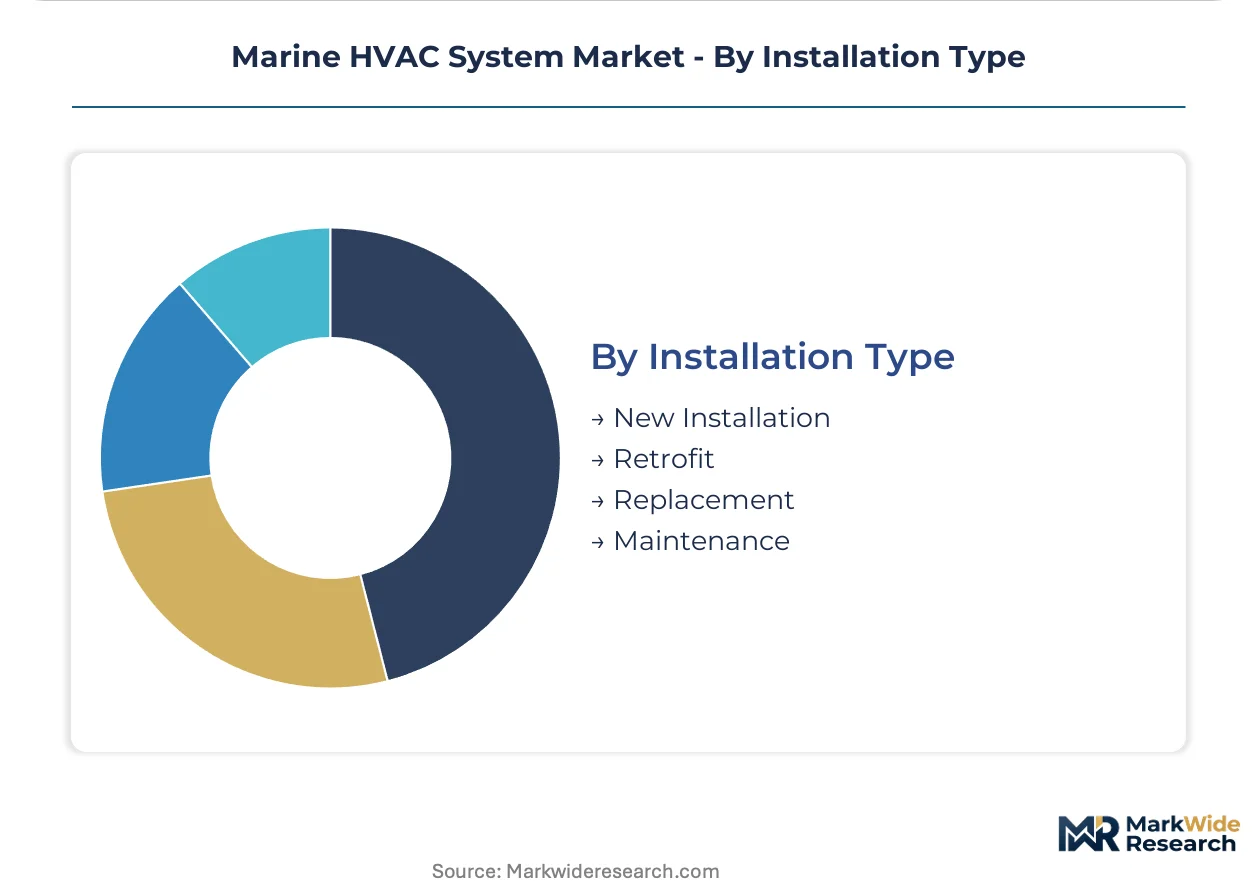
Installation Type:
Revenue timing splits between capital-intensive newbuild contracts and recurring service relationships tied to regulatory recertification cycles.
- New Installation:Shipyard-integrated packages during hull construction allow optimal pipe routing and electrical load balancing; Chinese yards in Shanghai and Guangzhou specify complete HVAC turnkey from steel cutting.
- Retrofit:Legacy vessel upgrades to meet MARPOL Annex VI and EU MRV requirements drive heat pump conversions, though 1990s-era hulls face physical space constraints in machinery rooms.
- Replacement:End-of-life compressor and chiller swaps occur during scheduled drydock periods, with DNV documentation reviews extending yard stays.
- Maintenance:Predictive service contracts using vibration analysis and refrigerant leak detection secure multi-year revenue streams for OEM service networks.
New Installation captures largest contract values; Maintenance delivers highest margin recurrence through captive parts supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean shipyards export integrated HVAC packages to European cruise operators and Middle Eastern offshore fleet owners, creating a trade corridor that concentrates manufacturing expertise in Busan-Ulsan while demand flows toward Hamburg, Dubai, and Oslo.
China
Shanghai and Guangzhou shipyards specify turnkey HVAC systems from steel cutting, absorbing over 60% of regional newbuild contracting. The country's MIIT enforces dual carbon goals that accelerate heat pump specifications in coastal vessel fleets. Yangtze River Delta fabricators now bundle climate systems with battery-hybrid propulsion packages for domestic ferry operators.
South Korea
DSME and Hyundai Heavy Industries anchor demand for magnetic bearing chillers in ultra-large cruise ship construction. The MFDS coordinates with Lloyd's Register on refrigerant containment certification for EU-flagged exports. Busan-Ulsan clusters specialize in redundant cooling loops for Arctic-class offshore vessels bound for Norway's Barents Sea fields.
Japan
Imabari Shipbuilding and Mitsubishi Heavy Industries specify precision climate control for LNG carriers and refrigerated cargo fleets. METI's efficiency benchmarks push compressor technology upgrades in legacy bulk carrier retrofits. Nagoya-Chubu manufacturers supply corrosion-resistant alloy heat exchangers to Southeast Asian ship repair hubs.
Germany
Meyer Werft in Papenburg and shipyards in Hamburg specify whisper-quiet compressor packages for premium cruise cabin ratings. The EU F-Gas Regulation forces refrigerant transition planning across German-flagged fleets operating Mediterranean and Caribbean itineraries. Northern German ports host specialized HVAC service networks for Scandinavian ferry operators.
Norway
Offshore wind service vessel operators in Stavanger and Bergen demand explosion-proof heating arrays and redundant habitability systems for North Sea technician accommodation. The country's petroleum regulator enforces auxiliary load reduction targets that favor shore-to-ship heat pump integration. Western Norway clusters pioneer predictive maintenance algorithms for compressor vibration monitoring.
Marine HVAC System Market Competitive Landscape
On the supply side, the industry is moderately consolidated around diversified industrial conglomerates with captive marine divisions, tiered between full-system integrators and component specialists. Three strategic archetypes dominate: propulsion-heritage bundlers who package climate with vessel automation, compressor-technology owners who control refrigerant circuit production, and service-density operators who capture aftermarket revenue through port-level maintenance networks. Competitive moves center on vertical integration into refrigerant chemistry and geographic expansion through shipyard co-location agreements.
Among Nordic-based system integrators, Wärtsilä Corporation exemplifies the propulsion-bundling archetype, while Daikin Industries anchors the compressor-technology tier through captive refrigerant circuit production. Carrier Global Corporation occupies the service-density position, sustaining recurring revenue relationships through classification society recertification cycles and drydock maintenance windows.
| Leading Market Players |
|---|
| Wärtsilä Corporation |
| Trane Technologies (Thermo King) |
| Daikin Industries |
| Heinen & Hopman |
| Dometic Group |
| Carrier Global Corporation |
| Mitsubishi Electric Corporation |
| Fujitsu General Limited |
| Johnson Controls International |
| Others |
Supply & Pricing Matrix
East Asian compressor manufacturing clusters in China, South Korea, and Japan concentrate refrigerant circuit production, anchoring margin capture at the component tier while system integrators compete on bundling and aftermarket density downstream.
Pricing Analysis
Current-generation magnetic bearing chillers command substantial premiums over conventional mechanical bearing systems, while prior-generation reciprocating compressors face accelerating price erosion as fleet operators retire legacy tonnage. Pricing stratifies across premium, standard, and economy tiers defined by certification grade from DNV and Lloyd's Register plus after-sales service bundling. Cost compression in standard-tier chiller packages is intensifying because F-Gas Regulation quota reductions drive refrigerant cost volatility. Cargo ship operators exhibit the highest price sensitivity, prioritizing rapid parts availability over efficiency specifications, whereas cruise operators accept premium positioning for redundant capacity and whisper-quiet operation.
Supply Chain Analysis
Copper-nickel alloy feedstock supply draws from Chilean mining operations, Indonesian smelting capacity, and Japanese metal fabrication, creating layered geographic exposure for corrosion-resistant heat exchanger production. Critical component dependencies include hermetic compressors from Japanese and South Korean OEMs, electronic expansion valves from German specialists, and marine-grade control systems from Nordic automation houses. Single-source vulnerability concentrates in magnetic bearing compressor technology where two suppliers dominate large-tonnage cruise ship applications. Distribution runs through shipyard-integrated procurement offices in Shanghai, Busan, and Papenburg, with aftermarket parts flowing via port-level service depots in Rotterdam, Singapore, and Houston.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine HVAC sits in early-cycle expansion as IMO EEDI Phase 3 deadlines force heat pump retrofits across legacy fleets ahead of physical replacement cycles, compressing adoption timelines from decades to single-drydock windows.
For Market Incumbents: Pre-empt margin erosion in standard-tier chiller packages by capturing captive refrigerant circuit production through backward integration into compressor manufacturing, while fortifying certification investment with DNV and Lloyd's Register to defend against emerging Asian system integrators bundling climate with battery-hybrid propulsion. For New Entrants and Emerging Players: Establish a beachhead in Indian coastal cargo fleet modernization under the Sagarmala port development program, where specification intensity remains low and local service density is underdeveloped. Target heat pump retrofits for 1990s-era bulk carriers as the most penetrable segment, leveraging shore-to-ship integration expertise as a differentiated go-to-market angle against incumbent automation bundlers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed marine automation specialists that acquired climate divisions from diversified industrial conglomerates during prior restructuring cycles. Long-term viability hinges on refrigerant chemistry transition execution and AI predictive maintenance capability buildout. Watch Scandinavian ferry operator procurement patterns as an inflection indicator, as these fleets pioneer shore-to-ship heat pump integration and condition-based overhaul scheduling.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Chemistry Transition | F-Gas Regulation compliance secures EU port access rights for reefer vessel operators. |
| Magnetic Bearing Compressor Scale-Up | Oil-free operation reduces maintenance intervals for Carnival Corporation and Royal Caribbean specifications. |
| AI Predictive Maintenance Deployment | Machine learning on compressor vibration data enables condition-based overhaul scheduling for offshore wind fleets. |
| Shipyard Co-Location Agreements | Proximity to Shanghai and Guangzhou construction sites secures newbuild package integration. |
| Shore-to-Ship Heat Pump Integration | Scandinavian ferry operators pioneer auxiliary load reduction through berthed power substitution. |
Research Methodology
Operator-level perspectives from shipyard procurement directors, fleet technical superintendents, classification society surveyors, and port facility engineers anchored the qualitative base, triangulated against customs trade records, IMO regulatory filings, Lloyd's Register certification databases, and shipbuilding orderbook trackers. Bottom-up vessel-by-vessel HVAC specification analysis was cross-referenced with top-down regional fleet composition modeling.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning vessel class, installation type, technology architecture, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and newbuild contracting velocity, incorporating refrigerant phaseout schedules and EEDI compliance deadlines as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in bunker fuel pricing, ship financing availability, or East Asian shipyard capacity utilization would shift the trajectory. Cross-checking against Lloyd's Register and DNV certification issuance data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Industrial Hood Ventilation Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
Greenhouse Ventilation System Market
HVAC Systems
Freeze and Thaw Systems Market
HVAC Systems
Global Building Thermal Insulation Material Market
HVAC Systems
Global Commercial Insulation Market
HVAC Systems
Global Chilled Beam System Market
HVAC Systems
Europe HVAC Services Market
HVAC Systems
Hydronic Control Market
HVAC Systems
Europe Boiler System Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
Water Saving Shower Heads Market
HVAC Systems
Thermostatic Faucet Market
HVAC Systems
HVAC Insulation Market
HVAC Systems
Hospital HVAC Systems Market
HVAC Systems
Ductless HVAC System Market