
 GCC Faucet Market | 2026-2036
GCC Faucet Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Faucet Market Foresight
Specialty bathroom retailers across the Gulf is reconfiguring as e-commerce platforms and project-direct channels capture specification flow for large developments. Jaquar Group leverages its Jebel Ali manufacturing base to anchor supply for Saudi megaprojects. Hansgrohe SE competes through design-led positioning in the UAE's luxury residential segment. Kohler Co. extends its distribution via dedicated showrooms in Dubai Design District and Riyadh's King Abdullah Financial District.
A faucet is a valve-controlled plumbing fixture that regulates water discharge through ceramic disc or compression cartridges, typically rated for pressures between 0.1 and 1.0 MPa and designed for basin, sink, or bath connections. Bathroom Faucets dominate value generation across the GCC as master-suite specifications trend toward thermostatic and sensor-activated variants. Stainless Steel commands premium positioning in coastal markets where salinity accelerates corrosion, while Brass sustains volume share through cost-performance balance in mid-market residential towers.
SASO's mandatory water-efficiency labels in Saudi Arabia and ESMA's conformity schemes in the UAE shape product certification requirements and market access timelines for imported fixtures. The region's national building codes increasingly reference LEED and Estidama water-performance thresholds, compelling manufacturers to redesign flow rates and aerator specifications. Stakeholders must monitor how Saudi giga-project procurement shifts between international specification and local content mandates.
Market Dynamics
Water-efficiency mandates from SASO and ESMA are compressing flow-rate specifications across the GCC, forcing manufacturers to redesign cartridge architectures while hospitality procurement accelerates in Dubai and Riyadh megaprojects.
Growth Catalysts
- SASO Water-Efficiency Labeling:Saudi Arabia's mandatory labeling scheme pushes specification toward low-flow ceramic disc cartridges, creating pull for compliant fixture portfolios in residential towers.
- Hospitality Construction:Hotel pipeline expansion in Dubai and Riyadh drives premium thermostatic and sensor-activated faucet procurement for master-suite specifications.
- Brass Cost-Performance Balance:Mid-market residential developers across the UAE specify brass-bodied fixtures for corrosion resistance at accessible price points.
Market Restraints
- Copper and Zinc Input Volatility:Brass alloy feedstock price swings compress margin predictability for manufacturers serving mid-market volume segments.
- Coastal Salinity Corrosion:High-salinity environments in Gulf coastal cities accelerate fixture degradation, elevating warranty costs and replacement frequency.
- Import Certification Timelines:ESMA conformity assessment and SASO quality mark procedures extend product registration cycles, delaying market entry for new suppliers.
Strategic Opportunities
- Kuwait and Bahrain Underpenetration:These markets lack the concentrated project pipelines of UAE and Saudi Arabia, offering first-mover positioning for specification-focused brands.
- LEED and Estidama Alignment:Green building certification adoption across Gulf commercial developments rewards fixtures meeting water-performance thresholds with specification preference.
- E-Commerce Specification Capture:Project-direct digital platforms are disintermediating traditional retailer channels for large-scale hospitality and residential developments.
Industry Challenges
- Plumbing Engineer Talent Scarcity:Shortage of professionals fluent in low-flow hydraulics and thermostatic mixing valve specification limits technical sales effectiveness.
- Legacy System Integration:Retrofit projects in aging Dubai and Jeddah building stock face compatibility friction between new water-efficient fixtures and existing pressure conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Faucet Market |
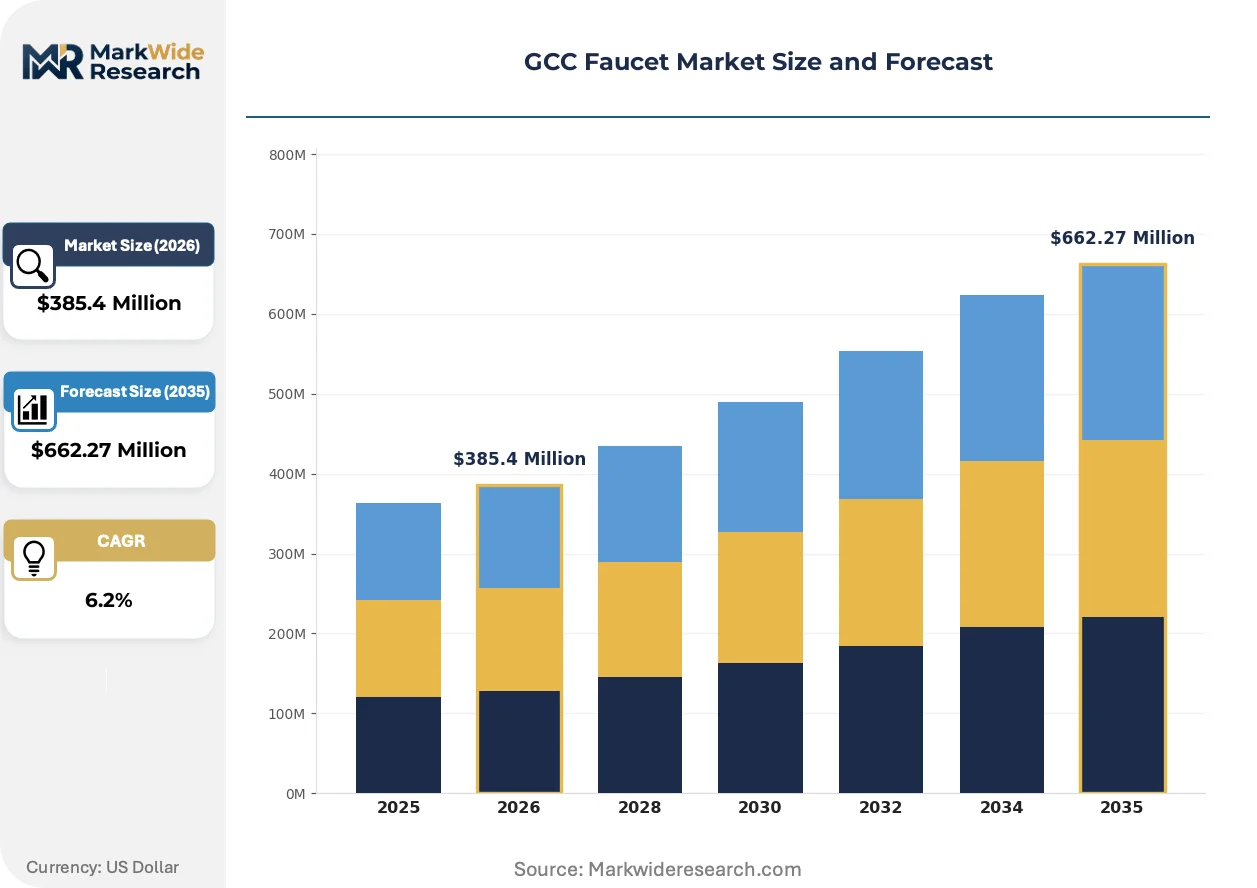
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kitchen Faucets, Bathroom Faucets, Lavatory Faucets, Shower Faucets Installation Type: Wall-mounted, Deck-mounted, Vessel, Pull-down Material: Stainless Steel, Brass, Plastic, Chrome End User: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | Jaquar Group, Hansgrohe SE, Grohe AG, Moen Incorporated, American Standard Brands, Delta Faucet Company, Kohler Co., Roca Sanitario S.A., AVK Saudi Valves Manufacturing Co. Ltd., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Faucet Market Shifts & Advancements
Digital specification platforms and sensor-activation technologies are restructuring how fixtures reach end-users, while regulatory water-performance thresholds compress traditional flow-rate architectures across Gulf markets.
Thermostatic mixing technology is hybridizing with IoT-enabled leak detection and usage analytics in high-end hospitality and healthcare specifications. Dubai's luxury hotel developers specify these systems for guest safety and operational monitoring. The convergence is compressing demand for purely mechanical thermostatic valves in premium segments.
ESMA's mandatory conformity assessment for plumbing fixtures is tightening product registration requirements for imports into the UAE. Manufacturers must submit to third-party testing for pressure rating and material safety verification. Mid-market residential tower developers now prioritize pre-certified fixture portfolios to accelerate project timelines.
Large-scale developers in Riyadh and Dammam are consolidating procurement through direct manufacturer relationships, bypassing traditional distributor networks. Specification decisions increasingly flow through project consultants rather than retail showrooms. This channel compression is most visible in Saudi giga-project residential and commercial developments.
GCC Faucet Market Segmentation
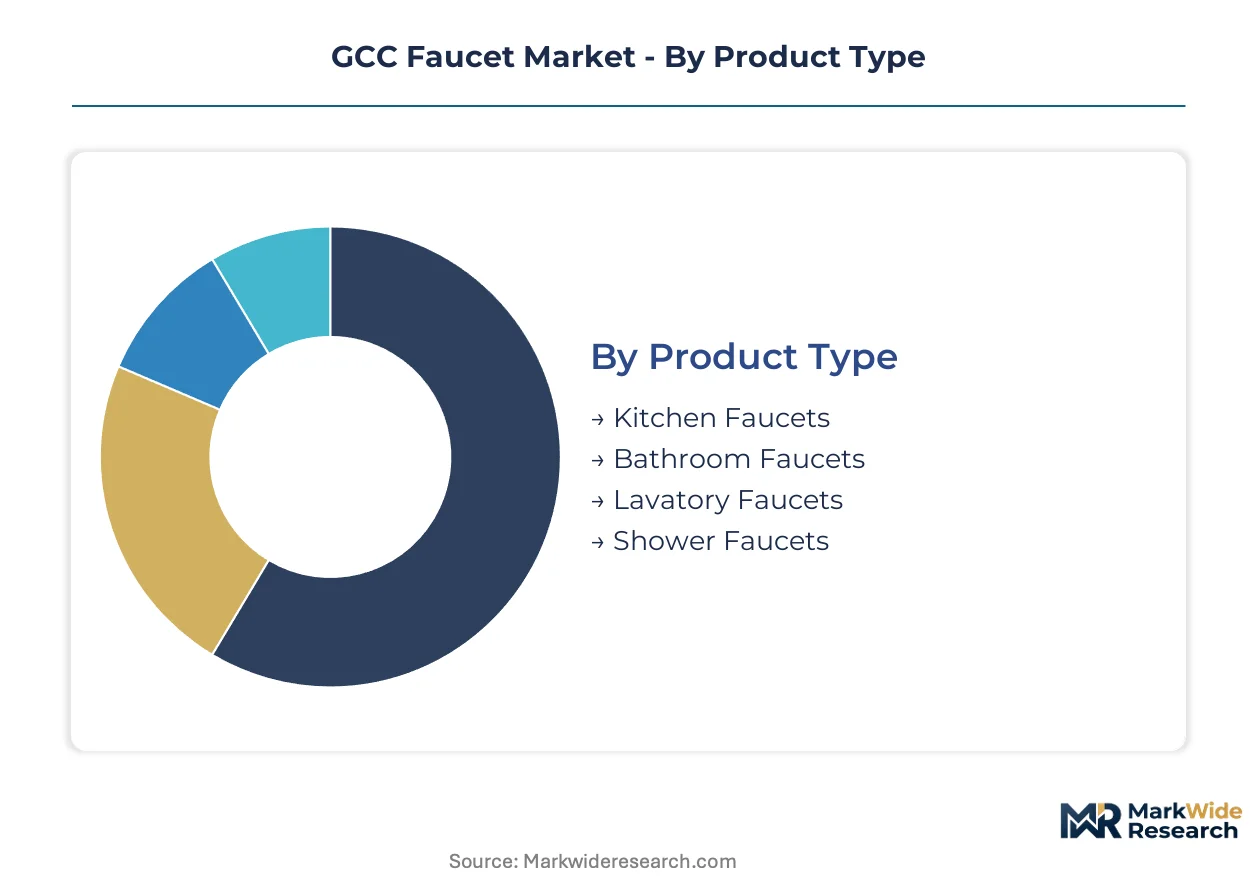
Fixture specification across the GCC diverges sharply by end-use environment and installation context. Saudi giga-projects and Dubai hospitality developments each impose distinct technical requirements on cartridge architecture, material selection, and flow-rate compliance.
Product Type:
Use cases span from high-frequency commercial kitchen environments to sensor-activated hospitality bathrooms, each demanding specialized valve engineering and durability specifications.
- Bathroom Faucets:Thermostatic and sensor-activated variants dominate master-suite specifications in Dubai's luxury residential towers. Riyadh hotel developers specify these for guest safety and water-efficiency compliance under SASO labeling mandates.
- Kitchen Faucets:Pull-down spray configurations with ceramic disc cartridges withstand high-frequency use in Saudi commercial food service installations. Procurement concentrates in Jeddah and Dammam hospitality developments where durability under continuous operation is non-negotiable.
- Lavatory Faucets:Compact single-lever designs serve mid-market UAE residential towers where cost-performance balance dictates specification.
- Shower Faucets:Pressure-balancing and thermostatic mixing valves address safety requirements in healthcare and senior living developments across Kuwait City.
The dominant share belongs to Bathroom Faucets, while Kitchen Faucets is closing the gap fastest.
Installation Type:
Mounting configuration directly correlates with building age and plumbing infrastructure vintage across Gulf cities.
- Deck-mounted:Standard bore-hole configurations dominate new construction across UAE residential towers. Saudi mid-market developers favor this format for compatibility with pre-fabricated countertop systems.
- Wall-mounted:Concealed cartridge systems enable clean aesthetic lines specified in Riyadh luxury apartments and Dubai Design District showrooms. Installation complexity elevates contractor skill requirements.
- Vessel:Tall spout architectures serve above-counter basin trends in Bahrain's emerging hospitality sector.
- Pull-down:Retractable hose systems concentrate in commercial kitchen specifications for Dammam hotel and healthcare food service operations.
Deck-mounted fixtures command the volume base, though Wall-mounted specifications are expanding most quickly in premium segments.
Material:
Corrosion resistance requirements vary dramatically between coastal high-salinity environments and inland urban centers.
- Brass:Copper-zinc alloys deliver cost-performance balance for mid-market residential towers across Abu Dhabi and Sharjah. SASO water-efficiency mandates are accelerating low-flow cartridge integration into brass-bodied platforms.
- Stainless Steel:Austenitic grades resist chloride attack in Dubai Marina and Jeddah Corniche coastal installations. Premium positioning reflects extended warranty terms and reduced replacement frequency.
- Chrome:Electroplated finishes provide aesthetic upgrade paths for budget-conscious Kuwait retail channel inventory.
- Plastic:Polymer constructions serve temporary and price-sensitive segments in Bahrain's construction labor accommodation sector.
Brass retains the volume anchor position, while Stainless Steel is gaining share fastest in coastal premium specifications.
End User:
Procurement authority is fragmenting across project-direct channels, e-commerce platforms, and legacy retail networks.
- Hospitality:Hotel developers in Dubai and Riyadh specify thermostatic and sensor-activated systems through consultant-led procurement. Master-suite and public restroom configurations demand distinct flow-rate and activation technologies.
- Residential:Saudi giga-project homebuilders consolidate fixture procurement through direct manufacturer relationships, bypassing traditional distributor markups.
- Commercial:Office and retail fit-outs in Abu Dhabi's new central business district prioritize ESMA pre-certified portfolios to accelerate project timelines.
- Industrial:Manufacturing and logistics facility specifications in Dammam and Jubail emphasize durability over aesthetic considerations.
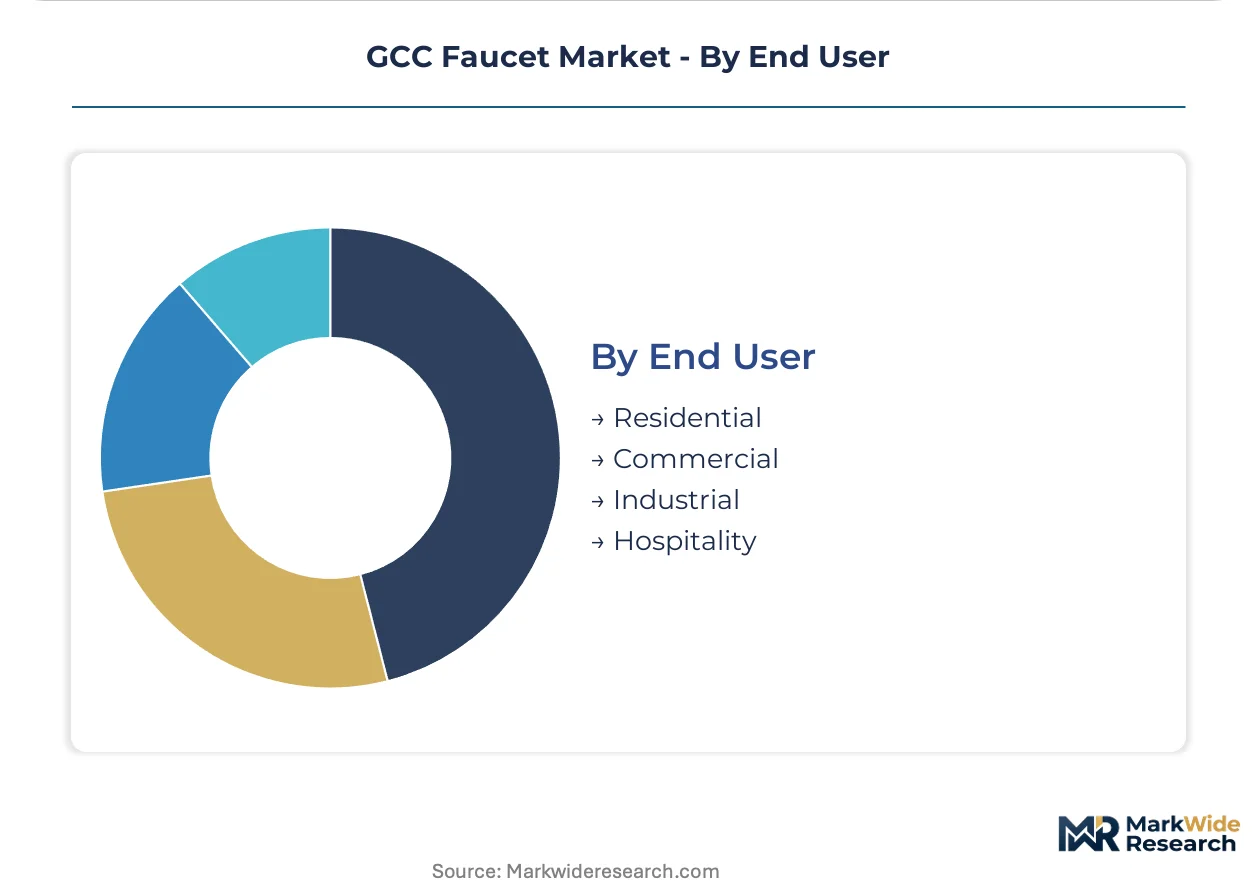
Hospitality captures the highest value per unit, while Residential is climbing the fastest on megaproject volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SASO water-efficiency labeling anchors Saudi Arabia's regulatory framework, compressing flow-rate specifications across the Gulf Cooperation Council. National building codes in member states increasingly reference green certification thresholds, reshaping procurement patterns for fixture manufacturers.
United Arab Emirates
Dubai's real estate pipeline drives premium thermostatic and sensor-activated faucet specifications for master-suite developments. ESMA conformity assessment mandates third-party testing for pressure rating and material safety verification. Abu Dhabi's new central business district prioritizes pre-certified fixture portfolios to accelerate commercial fit-out timelines.
Saudi Arabia
Riyadh and Dammam hotel developers specify thermostatic mixing systems for guest safety compliance under SASO labeling mandates. The Kingdom's giga-project residential developments consolidate procurement through direct manufacturer relationships, bypassing traditional distributor networks. Jeddah's coastal high-salinity environment accelerates stainless steel fixture adoption for corrosion resistance.
Kuwait
Healthcare and senior living developments across Kuwait City specify pressure-balancing and thermostatic mixing valves for safety requirements. The national construction regulator enforces building code compliance for plumbing fixture performance in commercial installations. Salmiya's emerging retail channel inventory favors chrome electroplated finishes for budget-conscious residential segments.
Bahrain
Above-counter basin trends in Manama's hospitality sector drive tall spout vessel faucet specifications. The country's underpenetrated market lacks concentrated project pipelines, offering first-mover positioning for specification-focused brands. Construction labor accommodation sectors in Muharraq specify polymer constructions for temporary price-sensitive installations.
Qatar
Lusail City's integrated developments demand concealed cartridge wall-mounted systems for clean aesthetic lines. The Supreme Committee for Delivery and Legacy established water-performance benchmarks for hospitality infrastructure tied to international sporting events. Doha's luxury residential towers specify brass-bodied fixtures balancing corrosion resistance with accessible price points.
GCC Faucet Market Competitive Landscape
Full-line manufacturers and design-led specialists split the market across specification tiers. The vendor base concentrates around regional manufacturing footprints and project-direct distribution capabilities. Three archetypes dominate: Jebel Ali-based fabricators serving Saudi megaprojects, European design houses capturing UAE luxury residential share, and North American brands extending through dedicated showroom networks. Competitive moves center on backward integration into cartridge manufacturing and e-commerce platform partnerships for large-development specification capture.
Among UAE-based fabricators, Jaquar Group anchors the mid-market volume tier through its Jebel Ali manufacturing base. European design specialists exemplified by Hansgrohe SE and Grohe AG occupy premium positioning in Dubai's luxury residential segment. These three represent distinct strategic postures: regional manufacturing scale, design-led specification capture, and European engineering heritage translated for Gulf market requirements.
| Leading Market Players |
|---|
| Jaquar Group |
| Hansgrohe SE |
| Grohe AG |
| Moen Incorporated |
| American Standard Brands |
| Delta Faucet Company |
| Kohler Co. |
| Roca Sanitario S.A. |
| AVK Saudi Valves Manufacturing Co. Ltd. |
| Others |
Supply & Pricing Matrix
Copper and zinc alloy feedstock concentration in China and India directly determines margin distribution across GCC faucet manufacturing tiers, with brass cost volatility compressing mid-market profitability while stainless steel premiums capture coastal replacement cycles.
Pricing Analysis
UAE-Saudi price spreads of 12-18% reflect ESMA pre-certification premiums versus SASO compliance costs. Three-tier pricing structure across premium, standard, and economy levels segments by cartridge technology grade and installation complexity. Cost compression in brass-bodied mid-market fixtures is intensifying because copper-zinc input volatility erodes manufacturer hedging capacity. Residential tower developers in Sharjah and Dammam exhibit highest price sensitivity, while Riyadh giga-project hospitality procurement prioritizes specification compliance over unit economics.
Supply Chain Analysis
Brass billet and ceramic disc cartridge supply draws from China, India, and Germany, with Jebel Ali fabrication hubs serving as GCC distribution anchors. Zinc concentrate and copper cathode dependencies expose manufacturers to London Metal Exchange price swings. Single-source vulnerability concentrates in thermostatic mixing valve cartridge supply from European engineering specialists. Distribution runs through project-direct channels for Saudi megaprojects and specialty retailer networks for UAE residential replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket cartridge replacement and warranty service contracts expand faster than fixture hardware across GCC coastal markets, with salinity-driven corrosion creating recurring revenue pools for specification-captured brands.
For Market Incumbents: Insulate margin position through backward integration into low-flow ceramic disc cartridge production and captive zinc-copper alloy sourcing from UAE free zone inventory buffers. Jaquar Group's Jebel Ali manufacturing footprint demonstrates how regional fabrication hedges against import certification delays from ESMA and SASO quality mark procedures.
For New Entrants and Emerging Players: Build out specification relationships with Kuwait City healthcare developers and Bahrain hospitality project consultants before incumbent showroom networks consolidate. Wall-mounted concealed cartridge systems in Doha and Manama present the most penetrable premium segment for design-led positioning without legacy distributor encumbrance.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with European design houses holding premium positioning in Dubai Marina and Riyadh luxury residential without GCC manufacturing footprint. Five-to-ten year viability hinges on regulatory alignment with tightening water-efficiency mandates across Saudi Arabia and the UAE. Monitor SASO label expansion timelines as inflection indicator for compliant portfolio valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cartridge Manufacturing | Captive low-flow ceramic disc production reduces ESMA certification exposure for UAE fabricators. |
| Project-Direct Digital Platform Partnership | E-commerce specification capture disintermediates traditional retailer markups in Saudi giga-projects. |
| Coastal Corrosion Warranty Extension | Stainless steel premium positioning in Jeddah and Dubai Marina commands replacement cycle capture. |
| SASO Pre-Certification Portfolio Investment | Pre-labeled fixture ranges accelerate Riyadh hospitality procurement timelines versus import registration. |
| Thermostatic-IoT Hybrid Development | Sensor-activated leak detection convergence addresses Dubai luxury hotel operational monitoring requirements. |
Research Methodology
Cross-validation between distributor procurement records and project consultant specification databases anchors the qualitative findings for GCC faucet demand segmentation. Primary interviews with plumbing engineers, hospitality procurement directors, Saudi giga-project contractors, and UAE retailer category managers combined with SASO regulatory filings, ESMA conformity assessment registers, Dubai Department of Economic Development trade data, and hotel development pipeline databases. Bottom-up project-level specification tracking and top-down national construction spend estimates provide triangulation across the analysis window.
Calibration against historical fixture penetration rates in completed Dubai residential towers and Riyadh hospitality developments shapes volume and value outputs across the projection horizon. Segmentation dimensions span product type, installation configuration, material grade, and end-user procurement channel. CAGRs derive from fitted growth curves applied to construction pipeline data and regulatory mandate phase-in schedules. Water-efficiency label adoption curves and coastal replacement frequency assumptions inform scenario-weighted projections.
Sensitivities concentrate around Saudi giga-project timeline adjustments and copper-zinc price volatility assumptions. Cross-checking against Dubai Land Department completion certificates and MEED project tracking databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Geofoam Market
Building & Construction Materials
Insulated Wall Panels Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
Bollard Market
Building & Construction Materials
Door System Market
Building & Construction Materials
Global Wall Putty Market
Building & Construction Materials
Concrete Sealer Market
Building & Construction Materials
Poland Ceramic Tiles Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
United States Gutter Guards Market
Building & Construction Materials
US Precast Concrete Market
Building & Construction Materials
Europe Faucet Market
Building & Construction Materials
Piping Systems Market
Building & Construction Materials
Residential Energy Efficient Windows Market
Building & Construction Materials
Concrete Cooling Market