
 Cement Sacks Market | 2026-2036
Cement Sacks Market Size, Share, and Industry Trends Forecast 2026-2036
Cement Sacks Market Outlook
Aftermarket service revenue for sack refurbishment and recycling logistics is narrowing as manufacturers integrate closed-loop recovery programs directly into supply contracts. Mondi leverages its European paper sack infrastructure to dominate high-barrier cement packaging across Central Europe. Smurfit Kappa competes through specialized kraft paper formulations that sustain load integrity under humid storage conditions. BillerudKorsnäs AB anchors Nordic supply through its DuraSack technology platform, extending product lifecycles for offshore cement transport.
Cement sacks are multi-layered containers engineered from kraft paper, woven polypropylene, or laminated composites, typically rated for 25kg to 100kg loads with burst strengths exceeding 200 kPa to prevent rupture during pneumatic filling and palletized distribution. Their primary purpose is to protect hygroscopic cement powder from moisture ingress while enabling mechanized handling across construction supply chains. Paper sacks command premium positioning in European markets where ECHA REACH compliance restricts plastic additives, while woven polypropylene sacks dominate price-sensitive bulk procurement in Middle Eastern and African markets. Multi-wall configurations represent the fastest-growing product type as ready-mix producers adopt valve-sealed designs for automated batching systems.
EPA industrial emissions standards in the United States pressure manufacturers toward water-based adhesives and reduced-VOC laminations in sack production. ECHA REACH restrictions on formaldehyde-based resins reshape kraft paper bonding chemistry across European supply chains. India's BIS IS 15153 standards mandate minimum tensile strength and moisture resistance thresholds for cement packaging used in monsoon-exposed regions. Stakeholders must monitor regulatory divergence between biodegradable mandates in Western Europe and cost-driven plastic tolerance in emerging Asian markets.
Market Dynamics
India's BIS IS 15153 certification mandates for tensile strength and moisture resistance are compressing supplier margins while elevating product performance floors across South Asian supply chains. Construction companies now specify valve-sealed multi-wall sacks as standard equipment for automated batching systems.
Growth Catalysts
- Multi-wall valve-sealed designs:Ready-mix concrete producers in Gujarat and Maharashtra are standardizing automated filling systems that require precision valve closures and burst resistance above 200 kPa.
- ECHA REACH compliance:European restrictions on formaldehyde-based resins in kraft paper bonding are accelerating migration toward water-based adhesive platforms.
- Western India manufacturing clusters:Cement production concentration around Ahmedabad and Mumbai generates localized procurement volumes that sustain dedicated sack converting operations.
Market Restraints
- Pulp price volatility:Kraft paper input costs fluctuate with Nordic softwood supply cycles, squeezing converter margins during Q4 inventory builds.
- Polypropylene substitution:Woven PP sacks at 40-60% lower unit costs capture bulk procurement in Middle Eastern and African markets where humidity exposure remains moderate.
- EPA emissions enforcement:Water-based adhesive transitions require capital-intensive dryer modifications that smaller converters cannot finance.
Strategic Opportunities
- Closed-loop recovery programs:Integrated logistics contracts for sack refurbishment and recycling are replacing fragmented aftermarket service revenue streams.
- Offshore cement transport:Extended product lifecycle demands for Nordic and Baltic Sea routes favor high-barrier laminated composites over standard kraft construction.
- Monsoon-specific formulations:BIS certification for moisture resistance in India's coastal states creates premium tier segmentation against inland-standard products.
Industry Challenges
- Adhesive chemistry requalification:ECHA REACH substance restrictions force 18-24 month reformulation cycles that delay new product introductions.
- Pneumatic filling compatibility:Automated batching systems require precise sack dimensional tolerances that legacy converting equipment cannot achieve without retrofit investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cement Sacks Market |
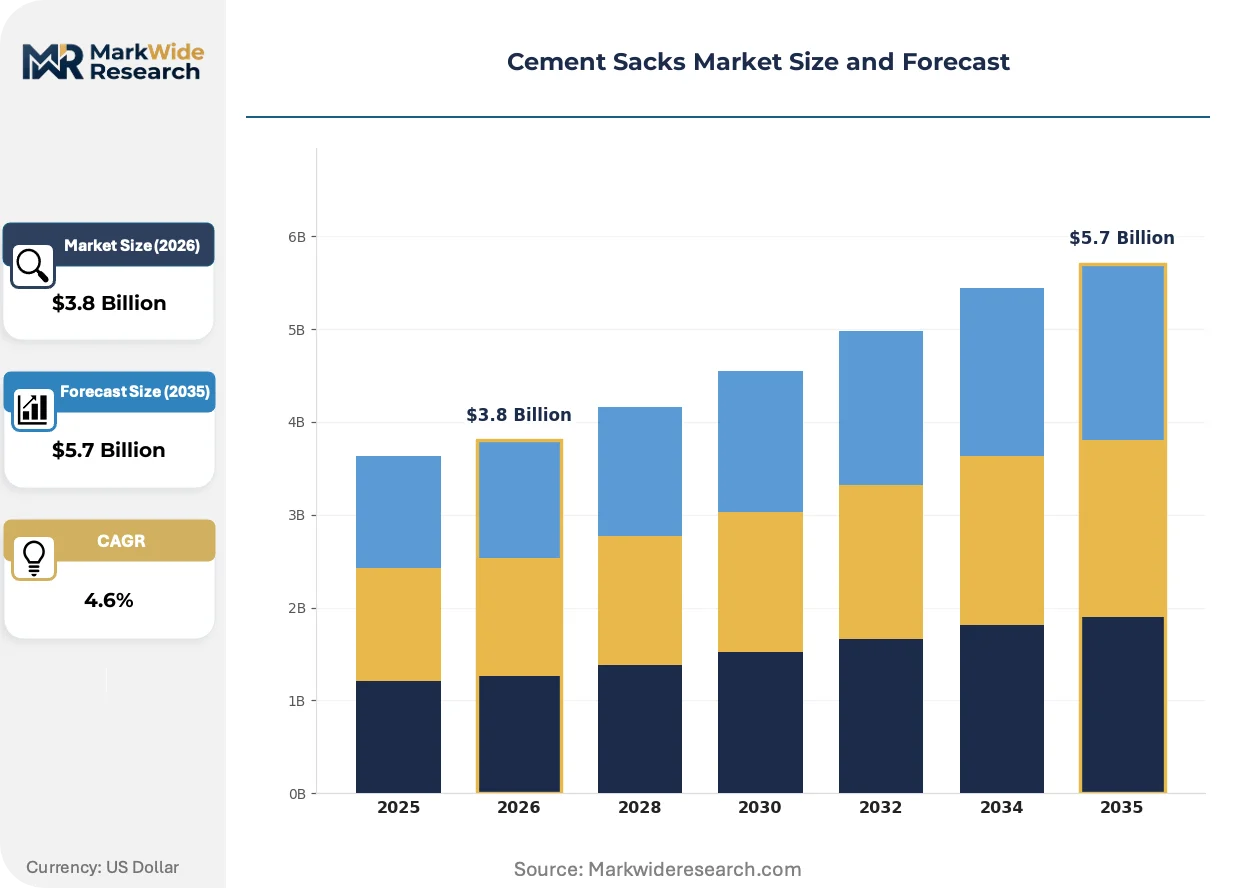
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Sacks, Plastic Sacks, Woven Sacks, Multi-Wall Sacks End User: Construction Companies, Ready-Mix Producers, Retailers, DIY Enthusiasts Capacity: 25kg, 40kg, 50kg, 100kg Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Mondi, Smurfit Kappa, BillerudKorsnäs AB, LC Packaging, Berry Global, Sonoco Products Company, Uflex Ltd, NNZ Group, ProAmpac LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cement Sacks Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are converging to reshape sack construction standards. Automated handling infrastructure is compressing tolerance specifications while sustainability mandates drive adhesive platform transitions.
High-barrier laminated composites are collapsing the performance gap between traditional kraft paper and woven polypropylene. Ready-mix concrete producers in Germany and Poland are adopting these structures for outdoor storage applications. The technology is collapsing price premiums for moisture-resistant packaging across Central European procurement contracts.
ECHA REACH restrictions on formaldehyde-based resins are mandating water-borne adhesive systems across European kraft paper supply chains. Manufacturers face 12-18 month requalification timelines for bonding chemistry that maintains 200 kPa burst strength. Nordic converters are responding with hybrid starch-PVA formulations that satisfy both regulatory thresholds and pneumatic filling stress requirements.
Construction companies are consolidating procurement through integrated supply contracts that bundle sack delivery with closed-loop recovery logistics. Traditional distributor networks in France and Italy are losing volume to direct manufacturer relationships. This pattern is most visible in German ready-mix markets where three national producers now specify single-source packaging partnerships with quarterly sustainability reporting obligations.
Cement Sacks Market Segmentation
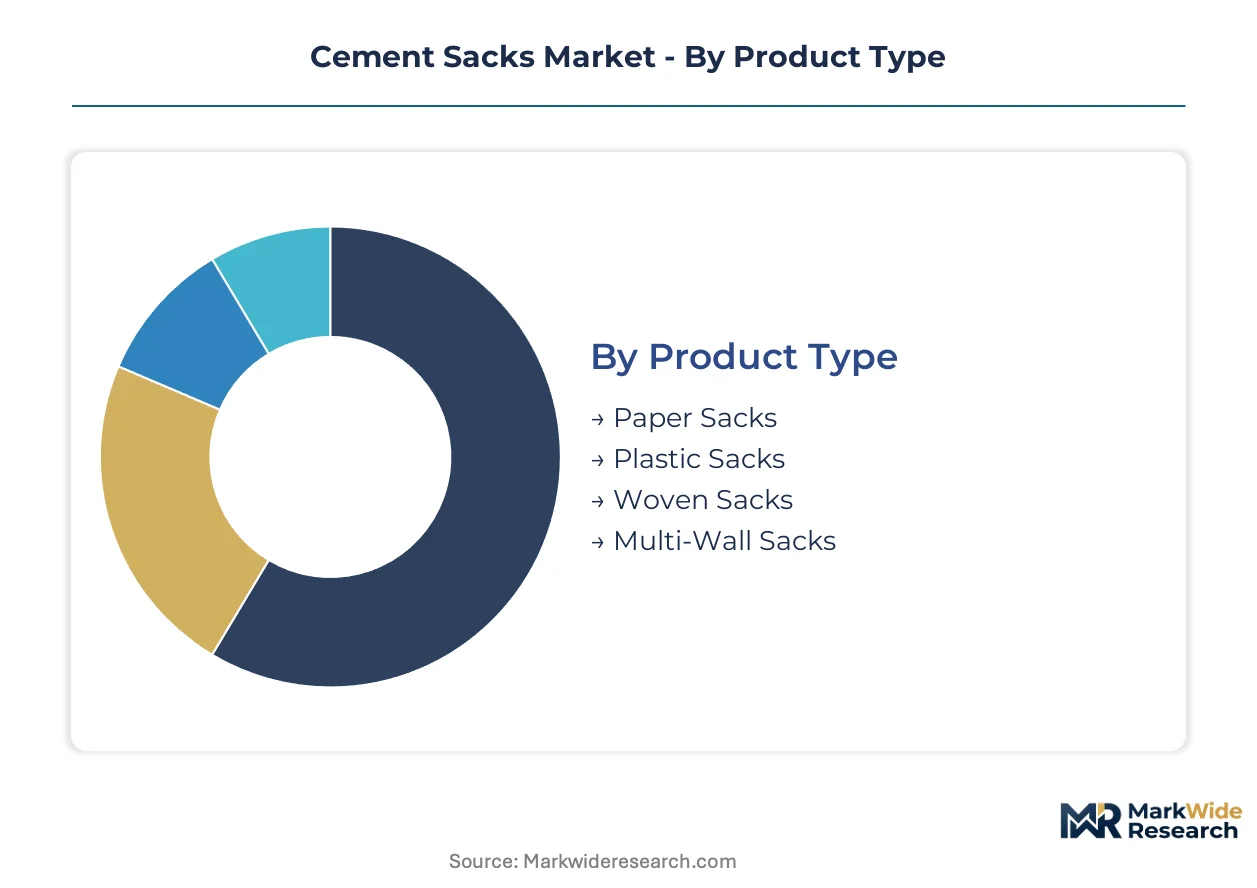
Cement sack procurement patterns diverge sharply across product construction, end-use application, and load capacity specifications. Understanding these segment boundaries reveals where converter margins concentrate and which technical standards drive specification changes.
Product Type:
Inventory velocity varies dramatically across material platforms, with laminated composites turning fastest in automated batching environments while standard kraft cycles slowest due to seasonal construction patterns.
- Multi-Wall Sacks:Valve-sealed configurations integrate three to five plies of kraft paper with polyethylene barrier layers, achieving burst resistance above 200 kPa for pneumatic filling systems. Ready-mix producers in Gujarat and Maharashtra specify these designs for automated batching operations where dimensional tolerance prevents line stoppages. ECHA REACH restrictions on formaldehyde-based resins are forcing 18-month adhesive requalification cycles that compress supplier margins.
- Paper Sacks:Two-ply kraft construction with stitched or glued closures dominates European procurement where ECHA REACH compliance restricts plastic additives. Construction companies in Germany and Poland specify these for indoor storage applications with moderate humidity exposure. Premium positioning persists despite woven PP encroachment in adjacent geographies.
- Plastic Sacks:Polyethylene film constructions with heat-sealed seams serve specialty applications requiring chemical resistance or extended outdoor exposure.
- Woven Sacks:Polypropylene tape fabrications at 40-60% lower unit costs capture bulk procurement in Middle Eastern and African markets where humidity remains moderate and price sensitivity dominates.
Woven sacks anchor the volume base in emerging markets while multi-wall configurations gain share at the steepest rate in automated production environments.
End User:
Specification complexity escalates with operational scale, from standardized retail SKUs to custom-engineered batching interfaces.
- Ready-Mix Producers:Automated batching systems demand precise valve tolerances and burst resistance certification for continuous pneumatic filling. These operators consolidate procurement through direct manufacturer contracts with quarterly sustainability reporting obligations, bypassing traditional distributor networks. BIS IS 15153 certification for moisture resistance is becoming a mandatory specification in India's monsoon-exposed coastal states.
- Construction Companies:Project-based procurement varies by contract scale, with national developers specifying multi-wall valve designs while regional contractors accept stitched paper sacks. Western India's manufacturing clusters around Ahmedabad and Mumbai generate localized volumes that sustain dedicated converting operations.
- Retailers:Standardized 25kg and 50kg SKUs with printed branding requirements for consumer-facing cement sales.
- DIY Enthusiasts:Small-lot procurement through hardware channels with minimal technical specification beyond load rating.
Construction companies represent the deepest volume pool while ready-mix producers are expanding most quickly through automation-driven specification upgrades.
Capacity:
Load rating determines handling infrastructure compatibility and freight economics across distribution modes.
- 50kg:The dominant construction standard globally, optimized for manual handling limits and pallet cube efficiency. Indian BIS standards mandate minimum tensile strength thresholds at this capacity for monsoon-exposed regions.
- 25kg:Retail and DIY channel standard enabling single-person lift compliance in European markets with strict manual handling regulations.
- 40kg:Intermediate specification serving regional markets with mixed manual-mechanized handling infrastructure.
- 100kg:Bulk transport configuration for industrial batching with dedicated lifting equipment, common in offshore cement logistics.
Fifty-kilogram ratings anchor the volume base while twenty-five-kilogram formats climb the fastest in retail channel expansion.
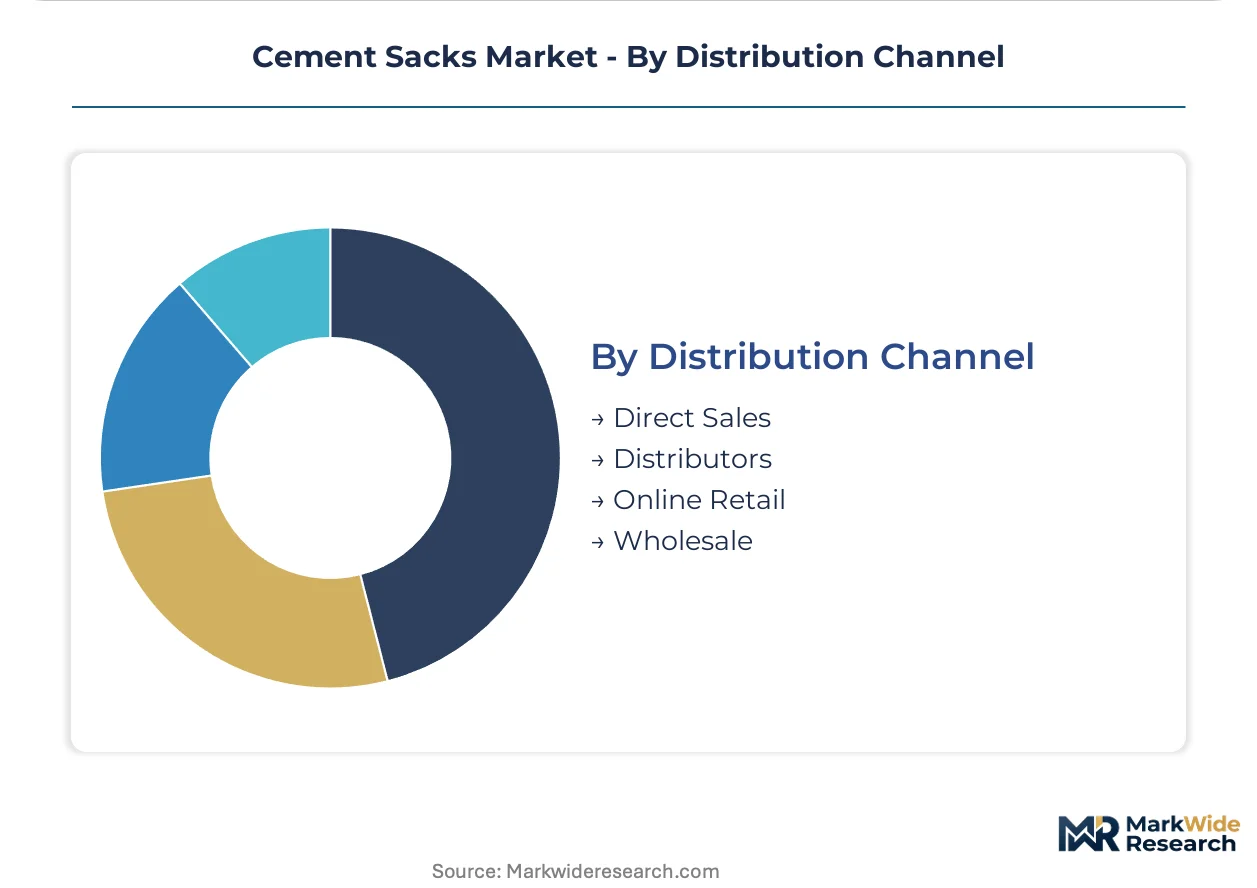
Distribution Channel:
Channel selection reflects customer scale and technical service requirements, with direct relationships capturing specification-intensive accounts.
- Direct Sales:National ready-mix producers and major construction groups negotiate integrated supply contracts bundling sack delivery with closed-loop recovery logistics. These arrangements replace fragmented aftermarket service revenue with manufacturer-controlled refurbishment programs.
- Distributors:Regional stocking operations serve mid-tier construction companies with standard SKU availability and credit terms. Traditional networks in France and Italy are losing volume to direct manufacturer relationships as procurement consolidates.
- Wholesale:Volume aggregation for project-based procurement with limited technical support.
- Online Retail:Emerging channel for small-lot DIY procurement with logistics constraints on heavy-goods delivery.
Distributors retain the broadest volume base while direct sales channels are gaining share fastest through integrated contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys multi-wall valve-sealed sacks for automated batching at scale, while Middle Eastern markets favor woven polypropylene for bulk procurement economics. European converters navigate ECHA REACH adhesive restrictions that Asian producers rarely encounter.
India
Construction companies in Gujarat and Maharashtra drive multi-wall sack procurement for continuous pneumatic filling systems. BIS IS 15153 certification mandates minimum tensile strength and moisture resistance thresholds for monsoon-exposed coastal states. Ahmedabad and Mumbai host dense cement manufacturing clusters that sustain dedicated sack converting operations with localized supply contracts.
Germany
Ready-mix concrete producers specify two-ply kraft paper sacks with ECHA REACH-compliant water-based adhesives for indoor storage applications. The country's national chemical regulator enforces 18-24 month requalification cycles for formaldehyde-free bonding chemistry. Industrial regions around Düsseldorf and Hamburg concentrate high-barrier laminated composite production for automated batching interfaces.
United States
EPA industrial emissions standards pressure manufacturers toward reduced-VOC laminations and water-based adhesive platforms. Construction supply chains in Texas and California exhibit divergent humidity exposure profiles that shape material selection. The Southeast corridor shows expanding procurement of 50kg rated sacks for residential construction batching operations.
Saudi Arabia
Woven polypropylene sacks dominate bulk cement transport for infrastructure megaprojects with moderate humidity exposure tolerance. The country's national standards body aligns product specifications with Gulf Cooperation Council technical regulations for construction materials. Eastern Province cement terminals generate concentrated demand for 100kg bulk configurations with dedicated lifting equipment.
Brazil
Construction companies in São Paulo and Rio de Janeiro balance cost sensitivity with mechanized handling requirements across mixed infrastructure projects. The national quality regulator maintains voluntary certification programs for packaging strength that influence procurement specifications. Southeastern industrial corridors anchor woven sack converting capacity serving both domestic distribution and Mercosur export routes.
Cement Sacks Market Competitive Environment
Capability concentration sits with European converters mastering ECHA REACH-compliant adhesive chemistry; scale advantage sits with Asian producers leveraging integrated pulp-to-sack operations. The vendor base organizes around three archetypes: integrated paperboard multinationals with barrier technology platforms, regional woven polypropylene specialists serving price-sensitive bulk markets, and mid-tier converters focused on valve-sealed automation compatibility. Dominant competitive moves include backward integration into kraft paper supply and captive refurbishment logistics for closed-loop recovery contracts.
Within the integrated paperboard tier, Mondi and Smurfit Kappa exemplify European infrastructure leverage for high-barrier cement packaging. BillerudKorsnäs AB anchors Nordic supply positioning through specialized durability formulations. These three entities represent distinct geographic anchoring strategies—Central European market density, humid-climate storage optimization, and extended-lifecycle offshore transport—rather than overlapping competitive territory.
| Leading Market Players |
|---|
| Mondi |
| Smurfit Kappa |
| BillerudKorsnäs AB |
| LC Packaging |
| Berry Global |
| Sonoco Products Company |
| Uflex Ltd |
| NNZ Group |
| ProAmpac LLC |
| Others |
Value Chain & Pricing Dynamics
Nordic-Baltic pulp freight corridors transmit cost volatility directly into converter margins while cement manufacturers in Gujarat and Maharashtra exploit geographic supply concentration to extract tiered pricing concessions. Long-term offtake contracts with integrated paperboard multinationals insulate procurement teams from quarterly kraft price swings, though spot-market exposure persists for regional converters lacking backward integration into softwood supply.
Pricing Analysis
Long-term offtake agreements dominate procurement for national ready-mix producers, while project-based spot purchasing serves regional construction companies with irregular volume needs. Price differentiation rests on BIS IS 15153 certification grade and valve-seal automation compatibility, with monsoon-rated formulations commanding substantial premiums over inland-standard products. Cost compression in woven polypropylene tiers is intensifying because Middle Eastern bulk importers exploit 40-60% unit cost advantages. Regional contractors represent the most price-sensitive segment, whereas automated batching operators prioritize dimensional tolerance over per-unit economics.
Supply Chain Analysis
Extended payment terms from Nordic pulp suppliers strain working capital for mid-tier converters, forcing reliance on supply-chain finance facilities backed by cement manufacturer receivables. Geographic supply concentration centers on Sweden, Finland, and Germany for kraft paper feedstock, while India and China anchor woven polypropylene tape fabrication. Raw material dependencies draw from bleached softwood pulp, polyethylene barrier films, and polypropylene resin. Single-source vulnerability in adhesive chemistry requalification cycles presents structural risk as ECHA REACH restrictions force 18-24 month bonding reformulations. Distribution runs through direct manufacturer relationships for automated batching accounts, with regional distributors serving fragmented construction procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cement sack procurement is consolidating around integrated logistics platforms where packaging delivery, automated filling interface compatibility, and closed-loop recovery obligations merge into single-source contracts. This interoperability shift rewards converters with captive refurbishment infrastructure and penalizes fragmented distributor networks.
For Market Incumbents: Insulate margin position through captive kraft paper supply and ECHA REACH-compliant adhesive chemistry platforms that emerging Asian competitors cannot replicate. Prioritize backward integration into Nordic softwood pulp to neutralize Q4 inventory build cost spikes. Defend against woven polypropylene substitution in African markets by embedding durability guarantees into multi-wall laminate specifications.
For New Entrants and Emerging Players: Build out valve-sealed automation compatibility as the most penetrable technical wedge against established paperboard converters. Target India's coastal states where BIS IS 15153 monsoon certification creates premium tier white space against inland-standard incumbents. Pursue direct supply contracts with mid-size ready-mix producers bypassed by multinational single-source partnerships.
For Investors and Strategic Acquirers: Regional woven polypropylene specialists with Gulf Cooperation Council certification pathways represent the most attractive acquisition archetype for exposure to infrastructure megaproject procurement. Long-term viability hinges on adhesive chemistry requalification capabilities and automated batching interface engineering depth. Watch for inflection where closed-loop recovery program penetration exceeds distributor network volume as signal of platform consolidation maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp Supply | Nordic softwood captive sourcing neutralizes Q4 price volatility for European converters. |
| ECHA REACH-Compliant Adhesive Platform | Water-borne bonding chemistry requalification creates 18-month regulatory moat against Asian competitors. |
| Valve-Sealed Automation Compatibility Investment | Precision dimensional tolerance captures ready-mix producer direct contract consolidation. |
| Closed-Loop Recovery Logistics Buildout | Integrated refurbishment programs displace fragmented aftermarket service revenue streams. |
| BIS IS 15153 Monsoon Certification | Moisture resistance tiering unlocks premium positioning in India's coastal construction markets. |
Study Parameters
A standing panel of cement plant procurement directors, sack converting operations managers, ready-mix batching system engineers, and ECHA regulatory compliance officers provided ongoing calibration across primary interview cycles. Secondary validation drew from BIS certification registries, EPA emissions compliance filings, Nordic timber trade associations, and cement industry association technical standards. Bottom-up volume modeling triangulated against top-down construction spending elasticity estimates.
Scenario-bracketing framed sensitivity analysis across adhesive chemistry transition timelines and pulp price volatility bands throughout the projection horizon. Segmentation dimensions modeled include material construction platform, end-use automation intensity, load capacity rating, and regional regulatory cluster. CAGRs derived from elasticity-adjusted construction output forecasts and packaging intensity coefficients. Industry-specific inputs incorporated pneumatic filling system deployment rates and BIS certification penetration curves.
Sensitivities concentrate around ECHA REACH substance restriction expansion, Nordic softwood supply disruption, and Indian monsoon severity variation. Forecasts embed assumptions regarding regulatory enforcement consistency and construction sector capital expenditure continuity. Macroeconomic contraction, accelerated biodegradable mandate adoption, or breakthrough woven polypropylene barrier technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
Construction Bolts Market
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
Global Wooden Formwork Systems Market
Building & Construction Materials
North America Metallic Barn Doors Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Plastic Fencing Market
Building & Construction Materials
Africa Vinyl Windows Market
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
Building Insulation Market
Building & Construction Materials
US Plywood Market
Building & Construction Materials
Commercial Glazing Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
EMEA Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Steel Casing Pipes Market