
 Noise Insulation Jackets Market | 2026-2036
Noise Insulation Jackets Market Size, Share, and Industry Trends Forecast 2026-2036
Noise Insulation Jackets Market Foresight
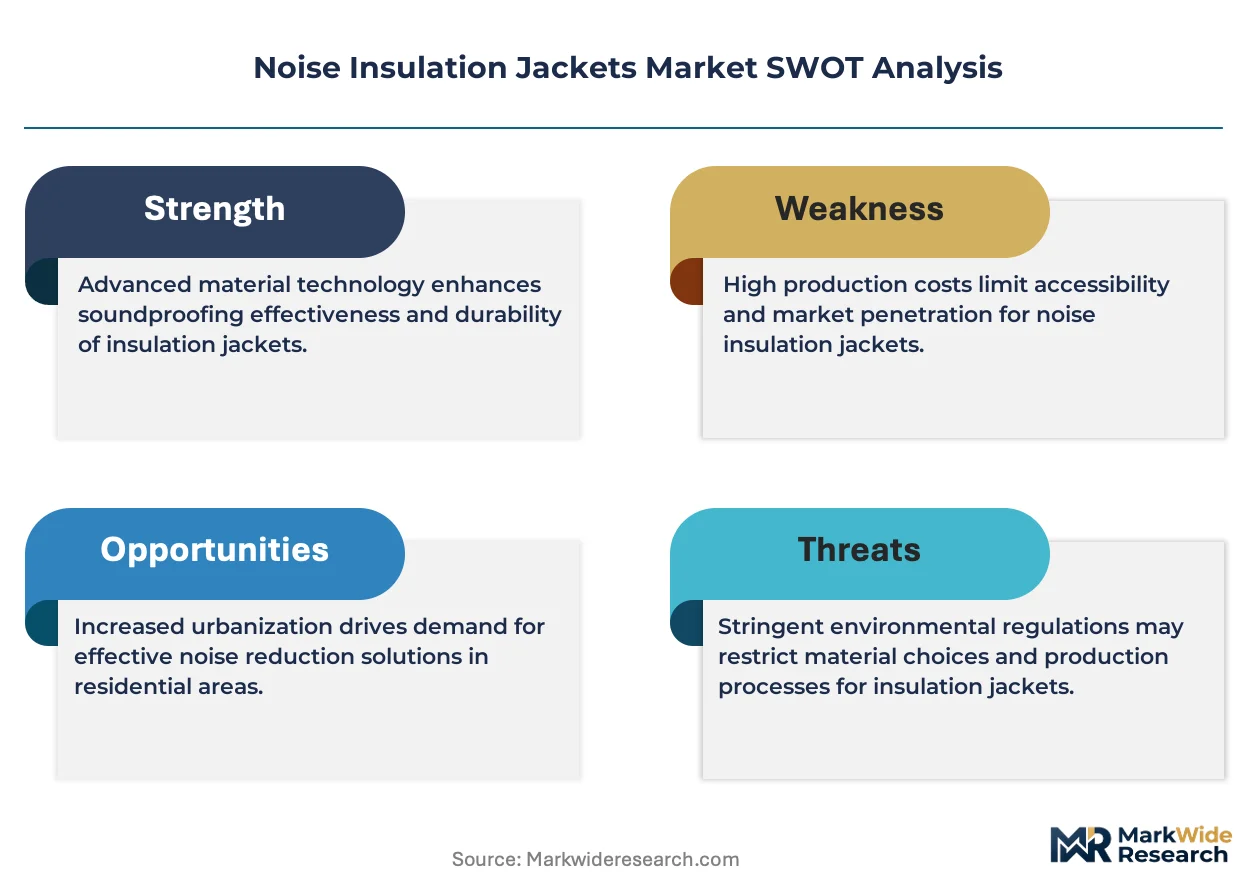
A certified industrial sewing workforce shortage is redrawing competitive boundaries for custom-fit jacket fabrication across North America and Europe. Thermaxx Jackets leverages in-house patterning capabilities to sustain turnaround advantages on complex pipe geometries. ADVANCED INSULATION LIMITED anchors its position through geographic dominance in UK offshore energy clusters, while Firwin Corporation differentiates via specialized high-temperature composite assemblies for exhaust systems.
Noise insulation jackets are engineered textile enclosures, typically fabricated from multi-layer constructions incorporating fiberglass batting, mass loaded vinyl barriers, and silicone-impregnated outer fabrics, designed to attenuate airborne and structure-borne acoustic energy in mechanical systems. These assemblies achieve noise reduction coefficients between 0.75 and 1.10 while withstanding continuous operating temperatures from minus 40 to 550 degrees Celsius in process environments. Foam barriers lead the product type category due to established supply chains and lower installed cost profiles in commercial HVAC retrofit applications. Mass loaded vinyl represents the fastest-expanding material segment as specifiers prioritize thinner profiles with higher surface density for space-constrained automotive underhood and industrial skid packages.
OSHA permissible exposure limits for occupational noise, EPA community noise regulations near industrial zones, and ISO 15665 piping acoustic insulation standards collectively mandate documented attenuation performance for jacket procurement. Compliance documentation requirements from these frameworks are shifting procurement criteria toward certified third-party test data and traceable material compositions. Stakeholders must monitor evolving MEE acoustic emission guidelines in China and dual carbon enforcement timelines that could redirect material substitution toward lower-embodied-carbon textile substrates.
Market Dynamics
Certified industrial sewing workforce scarcity across North America and Europe is compressing fabrication capacity for custom-fit acoustic enclosures, forcing buyers to extend lead times or accept standardized geometries that compromise attenuation performance on complex mechanical systems.
Growth Catalysts
- OSHA permissible exposure limits:Tightened enforcement timelines for occupational noise in US manufacturing and energy facilities are mandating documented attenuation performance for jacket procurement across turbine housings and compressor stations.
- Data center construction acceleration:Hyperscale facility buildouts in the United States are specifying removable insulation blankets for chiller and generator acoustic mitigation to meet EPA community noise standards near suburban zones.
- Mass loaded vinyl innovation:Thinner-profile high-density barriers are enabling space-constrained installations in automotive underhood and industrial skid packages where envelope dimensions previously excluded acoustic treatment.
Market Restraints
- Silicone-impregnated fabric input volatility:Specialty textile substrate pricing fluctuates with petrochemical feedstock costs, compressing margin stability for custom fabrication shops dependent on consistent material quoting.
- UK offshore cluster supply concentration:Geographic dominance by single-source fabricators in North Sea energy corridors creates vulnerability for European buyers seeking rapid turnaround on emergency retrofits.
- ISO 15665 compliance documentation burden:Traceable material composition requirements and third-party test data mandates are extending procurement cycles and disqualifying smaller vendors lacking certification infrastructure.
Strategic Opportunities
- China MEE acoustic emission guidelines:Evolving enforcement timelines for industrial noise near urban boundaries are creating specification pull for attenuation assemblies in power generation and process manufacturing facilities.
- Dual carbon material substitution:Lower-embodied-carbon textile substrates are opening procurement channels with state-owned enterprises under pressure to document supply chain emissions reductions.
- Digital patterning convergence:Integration of 3D scanning with automated cutting systems is collapsing turnaround times for complex pipe geometries previously requiring manual templating.
Industry Challenges
- Certified industrial sewing workforce gap:Patterning and fabrication expertise concentrated among aging technicians in North America and Europe is constraining output scaling without apprenticeship pipeline investment.
- Multi-layer assembly integration complexity:Aligning fiberglass batting, mass loaded vinyl barriers, and outer fabric specifications across varying temperature and acoustic performance requirements demands specialized engineering capacity.
- Legacy system retrofit measurement friction:Field verification of irregular mechanical geometries for custom-fit enclosures requires skilled deployment of scanning equipment, extending project initiation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Noise Insulation Jackets Market |
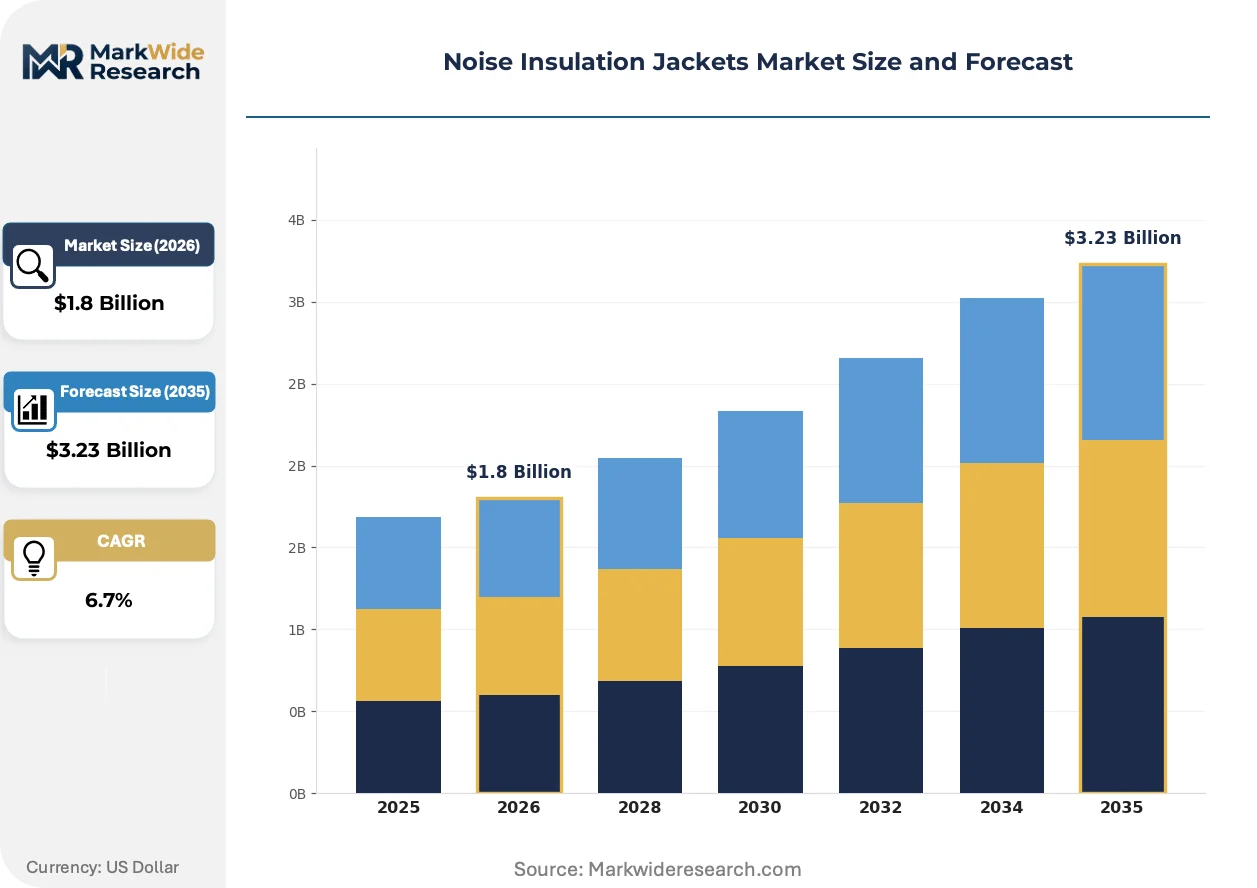
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acoustic Panels, Soundproof Curtains, Foam Barriers, Insulation Blankets Material: Polyester, Fiberglass, Rubber, Mass Loaded Vinyl Application: Residential, Commercial, Automotive, Industrial Installation Type: Permanent, Temporary, Removable, Integrated |
| Companies Covered | Unionfull (Insulation) Group Ltd., Insultech, LLC, Thermaxx Jackets, ADVANCED INSULATION LIMITED, Firwin Corporation, ATHALYE GROUP, Barrier Group, NK Group, ISC Insulated Soft Covers LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Noise Insulation Jackets Market Shifts & Advancements
Material science advances and regulatory documentation requirements are reshaping competitive advantage in acoustic enclosure fabrication, favoring suppliers with integrated testing capabilities and digital manufacturing infrastructure over traditional cut-and-sew operations.
Aerogel-infused composite barriers are supplanting conventional fiberglass batting in high-temperature exhaust applications, delivering equivalent noise reduction coefficients at reduced thickness and weight. US power generation operators are specifying these assemblies for turbine housings where space constraints previously limited acoustic treatment options. The structural consequence is compression of incumbent multi-layer constructions in temperature-critical segments above 400 degrees Celsius.
EU F-Gas Regulation phase-down schedules are accelerating specification of lower-global-warming-potential blowing agents in foam barrier products used across commercial HVAC retrofit markets. Industrial operators in Germany and France are now requiring documented environmental product declarations for acoustic insulation procurement. This regulatory pressure is most acute in data center and pharmaceutical manufacturing verticals where sustainability credentials factor into vendor selection scoring.
Specification-driven procurement is consolidating buyer decision authority among centralized engineering functions, displacing the distributed maintenance-purchasing model that historically dominated industrial acoustic retrofits. Third-party certified test data and traceable material compositions are becoming gatekeeping criteria rather than value-add differentiators. This behavioral shift is most visible in US refinery and petrochemical facilities where OSHA compliance documentation requirements have elevated procurement sophistication.
Noise Insulation Jackets Market Segmentation
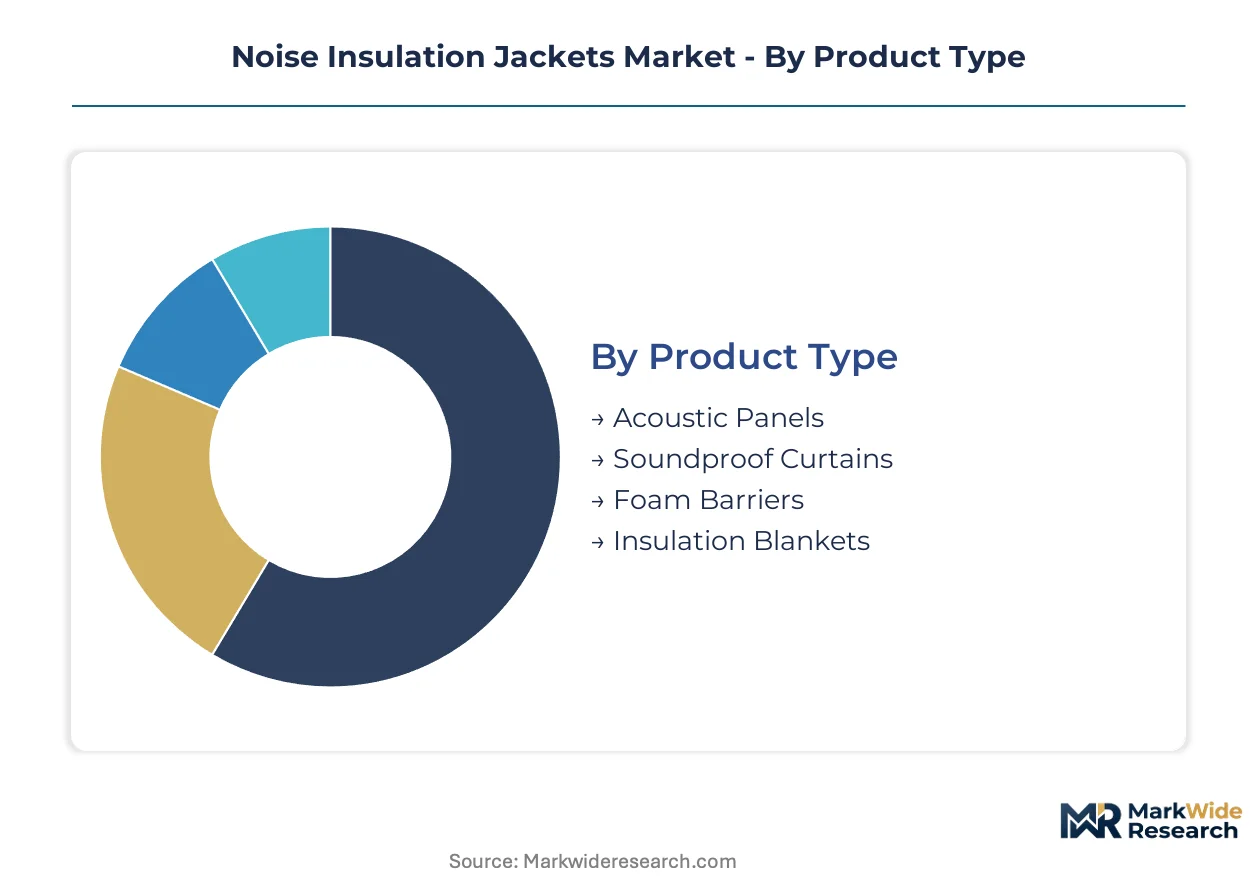
Segmentation in noise insulation jackets determines procurement channel selection, installation labor requirements, and compliance documentation burdens. Product type and material composition dictate whether specifications flow through MRO distributors, direct OEM contracts, or specialized acoustic engineering firms.
Product Type:
Channel mix varies sharply: insulation blankets and foam barriers move through industrial distributors serving maintenance departments, while acoustic panels and soundproof curtains specification concentrates with architectural acoustic consultants.
- Acoustic Panels:Rigid framed assemblies incorporating perforated metal facings over mineral wool cores achieve noise reduction coefficients above 0.85. Demand concentrates in US data center construction where hyperscale operators mandate documented attenuation performance for chiller plant enclosures.
- Soundproof Curtains:Flexible textile barriers with mass loaded vinyl interlayers deploy on rolling track systems for temporary noise containment. German automotive manufacturers specify these for paint booth and assembly line reconfigurations where permanent walls impede workflow flexibility.
- Foam Barriers:Open-cell polyurethane or melamine foam constructions absorb mid-to-high frequency noise in HVAC plenum applications.
- Insulation Blankets:Multi-layer removable enclosures dominate power generation turbine retrofits requiring OSHA compliance without permanent modification.
By volume, foam barriers lead. By growth pace, insulation blankets are climbing the fastest.
Material:
Cost tier stratification separates specification pathways: commodity materials flow through volume distributors, while engineered composites require direct technical sales engagement.
- Mass Loaded Vinyl:High-density flexible barriers deliver superior surface density at reduced thickness, enabling space-constrained installations. US refinery operators specify these for compressor skids where envelope dimensions previously excluded acoustic treatment, driven by EPA community noise enforcement near suburban boundaries.
- Fiberglass:Batt and board constructions provide thermal-acoustic dual functionality across process piping. UK offshore energy clusters specify fiberglass-core jackets for North Sea platform turbine housings, constrained by certified industrial sewing workforce scarcity.
- Polyester:Recycled-content fiber constructions serve commercial HVAC retrofit markets with lower embodied carbon profiles.
- Rubber:Elastomeric barriers excel in vibration damping applications for automotive underhood and heavy equipment enclosures.
By installed base, fiberglass dominates. By specification momentum, mass loaded vinyl is gaining share fastest.
Application:
Customer type determines procurement sophistication: industrial buyers mandate certified test data, while residential and commercial segments prioritize installed cost and aesthetic integration.
- Industrial:Process manufacturing, power generation, and petrochemical facilities specify engineered enclosures with traceable material compositions. US refinery operators drive demand for removable insulation blankets complying with OSHA permissible exposure limits and ISO 15665 documentation requirements.
- Automotive:Electric vehicle powertrain packaging creates space-constrained acoustic challenges. German and Japanese OEMs specify thinner-profile mass loaded vinyl barriers for underhood applications where thermal management competes for envelope volume.
- Commercial:Office buildings, hospitality, and retail spaces prioritize aesthetic integration and rapid installation.
- Residential:Home theater and mechanical room applications represent price-sensitive specification with limited compliance documentation requirements.
By revenue contribution, industrial applications anchor the market. By expansion trajectory, automotive is accelerating most sharply.
Installation Type:
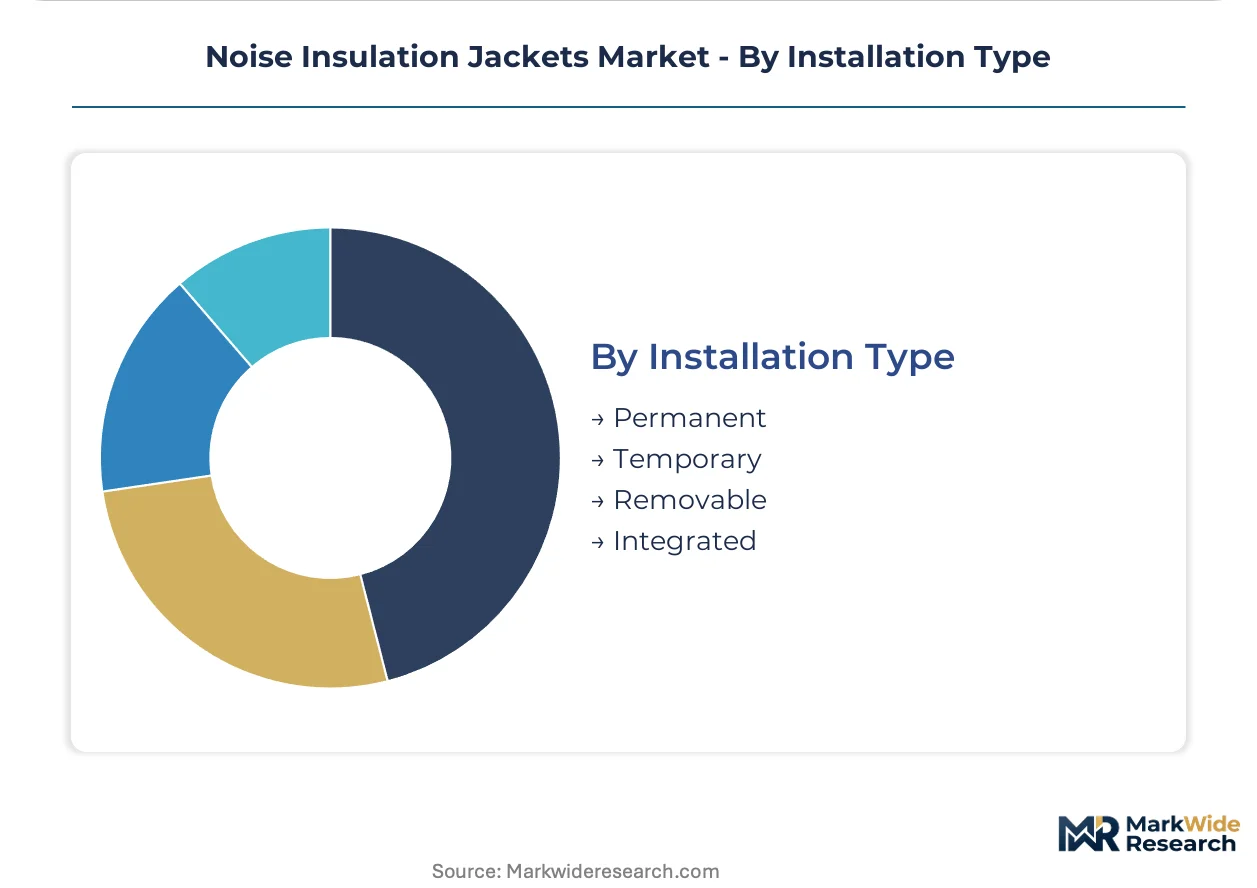
Project lifecycle stage dictates installation approach: new construction favors permanent and integrated systems, while retrofit markets drive removable and temporary specification.
- Removable:Fastener-attached blankets and jackets enable maintenance access without acoustic performance degradation. US data center operators specify these for generator and chiller enclosures requiring EPA community noise compliance with service accessibility.
- Permanent:Welded or bonded constructions deliver maximum durability in high-vibration exhaust and turbine applications. UK offshore platforms specify permanent installations for North Sea assets where weather exposure precludes removable fastening systems.
- Temporary:Modular barriers deploy for construction phase noise mitigation and emergency retrofit scenarios.
- Integrated:Factory-installed acoustic treatments within OEM equipment enclosures streamline field commissioning.
By specification frequency, removable installations lead. By structural shift, integrated systems are advancing most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA enforcement timelines in the United States are compressing procurement cycles for industrial acoustic mitigation. Facility operators across power generation, refining, and data center verticals now prioritize documented attenuation performance and traceable material compositions in vendor selection.
United States
Refinery retrofits along the Gulf Coast and hyperscale data center construction in Northern Virginia drive specification rates for removable insulation blankets. EPA community noise standards near suburban boundaries mandate acoustic treatment for chiller and generator enclosures. Houston and Dallas-Fort Worth industrial clusters concentrate demand for custom-fit turbine housing solutions.
Germany
Automotive OEMs in Stuttgart and Munich specify thinner-profile mass loaded vinyl barriers for electric vehicle underhood packaging where thermal management competes for envelope volume. EU F-Gas Regulation phase-down schedules accelerate demand for lower-global-warming-potential foam barrier constructions. The Ruhr industrial corridor sustains procurement for process manufacturing acoustic retrofits.
United Kingdom
North Sea offshore energy platforms require certified industrial sewing capacity for turbine housing jackets in Aberdeen and Scottish coastal clusters. ADVANCED INSULATION LIMITED anchors supply relationships through geographic proximity to these assets. UK Health and Safety Executive noise exposure guidelines tighten compliance documentation burdens for platform operators.
China
Power generation facility expansion in the Yangtze River Delta and Pearl River Delta creates specification pull for attenuation assemblies. MEE acoustic emission guidelines for industrial noise near urban boundaries redirect procurement toward certified third-party test data. State-owned enterprises under dual carbon enforcement timelines prioritize lower-embodied-carbon textile substrates.
Japan
Automotive and precision manufacturing facilities in the Nagoya and Osaka industrial zones specify space-constrained acoustic treatments for automated production lines. METI industrial noise guidelines mandate documented attenuation performance for mechanical system retrofits. Japanese OEMs prioritize thinner-profile barriers enabling envelope volume reduction in underhood and skid-mounted equipment.
Noise Insulation Jackets Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in custom-fit acoustic enclosure fabrication. The upper tier commands specification authority through in-house patterning capabilities and certified testing infrastructure. Below this, regional fabricators compete on turnaround velocity for standardized geometries. Three archetypes dominate: vertically integrated patterning specialists, geographic cluster anchors, and high-temperature composite assemblers. Competitive moves concentrate on digital patterning convergence and apprenticeship pipeline investment to address certified sewing workforce scarcity.
Among North American fabricators, Thermaxx Jackets exemplifies the patterning-integrated archetype through sustained turnaround advantages on complex pipe geometries. ADVANCED INSULATION LIMITED occupies the geographic anchor position serving UK offshore energy clusters. Firwin Corporation represents the high-temperature composite specialization vector for exhaust system applications. These three illustrate how capability concentration in certified industrial sewing, geographic proximity to demand clusters, and material science depth respectively defend competitive position in a capacity-constrained market.
| Leading Market Players |
|---|
| Unionfull (Insulation) Group Ltd. |
| Insultech, LLC |
| Thermaxx Jackets |
| ADVANCED INSULATION LIMITED |
| Firwin Corporation |
| ATHALYE GROUP |
| Barrier Group |
| NK Group |
| ISC Insulated Soft Covers LTD |
| Others |
Supply & Pricing Matrix
Sixteen-week lead times for custom-fit acoustic enclosures concentrate pricing power among North American fabricators with captive patterning capabilities, compressing margins for regional shops dependent on standardized geometries and spot-market textile inputs.
Pricing Analysis
Geographic price spreads of 25-40 percent separate Gulf Coast refinery procurement from European offshore platform contracting, reflecting certified sewing workforce scarcity and logistics cost differentials. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 15665 certification grade and traceable material documentation. Price differentiation hinges on third-party test data availability and customization depth. Cost compression in standard-grade foam barriers intensifies as commodity melamine supply expands, while premium-tier mass loaded vinyl assemblies retain pricing resilience due to thin-profile engineering complexity.
Supply Chain Analysis
Strategic stockpiling of silicone-impregnated fabrics characterizes procurement behavior among tier-one fabricators, insulating against petrochemical feedstock volatility that disrupts just-in-time operations at smaller shops. Supply concentrates in the United States, United Kingdom, and Germany for certified industrial sewing capacity, while mass loaded vinyl barrier production draws from South Korean and Japanese specialty chemical suppliers. Raw material dependencies span fiberglass batting from Chinese state-owned enterprises, mass loaded vinyl resins from German chemical conglomerates, and high-temperature outer fabrics from Italian textile mills. Single-source vulnerability in UK offshore cluster fabrication creates bottleneck risk for North Sea emergency retrofits. Distribution runs through MRO industrial distributors for maintenance-driven procurement, direct OEM contracts for integrated installations, and specialized acoustic engineering firms for complex custom geometries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification-driven procurement is consolidating buyer decision authority, transforming acoustic enclosure markets from distributed maintenance purchasing toward centralized engineering platforms with embedded compliance documentation workflows.
For Market Incumbents: Consolidate patterning capabilities through apprenticeship pipeline investment and digital scanning infrastructure to defend against emerging automated cutting entrants. Lock in long-term supply agreements for mass loaded vinyl resins before dual carbon enforcement timelines redirect state-owned enterprise procurement toward lower-embodied-carbon substrates. Vertical integration into certified third-party testing laboratories secures specification gatekeeping power as ISO 15665 documentation requirements harden. For New Entrants and Emerging Players: ISO 15665 certification fast-track through accredited European testing houses opens specification channels with German automotive OEMs and US data center operators currently constrained by incumbent capacity scarcity. Target automotive underhood applications where electric vehicle powertrain packaging creates space-constrained demand for thinner-profile barriers underserved by legacy multi-layer constructions. White-space opportunity concentrates in China MEE guideline compliance for Yangtze River Delta power generation facilities lacking indigenous certified fabrication capacity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital patterning and automated cutting infrastructure, favoring acquisition targets with installed 3D scanning capabilities over traditional cut-and-sew operations. Five-to-ten year viability framing prioritizes fabricators with demonstrated apprenticeship pipelines addressing certified industrial sewing workforce gaps. Signal to watch: OSHA enforcement timeline acceleration compressing procurement cycles toward documented attenuation performance vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Apprenticeship Pipeline Investment | Addresses certified industrial sewing workforce scarcity constraining North American and European fabrication capacity expansion. |
| Digital Patterning Convergence | Integrates 3D scanning with automated cutting to collapse turnaround times for complex pipe geometries requiring custom-fit enclosures. |
| Third-Party Testing Laboratory Acquisition | Secures ISO 15665 compliance documentation capabilities becoming mandatory gatekeeping criteria in specification-driven procurement. |
| Mass Loaded Vinyl Resin Supply Agreement | Locks in specialty chemical feedstock before dual carbon enforcement redirects state-owned enterprise sourcing priorities. |
| China MEE Certification Fast-Track | Captures specification pull from Yangtze River Delta power generation facilities under tightening acoustic emission guidelines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade association filings, customs data, and regulatory enforcement disclosures through structured interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads. Bottom-up demand estimation triangulates against top-down supply-side capacity assessments across certified industrial sewing installations. Primary fieldwork encompassed facility audits at US Gulf Coast refineries, German automotive assembly plants, and UK North Sea platform operators. Secondary validation drew from OSHA enforcement timelines, EPA community noise standard updates, EU F-Gas Regulation phase-down schedules, and China MEE acoustic emission guideline drafts.
Segmentation dimensions modeled span product type, material composition, application vertical, and installation approach across the projection horizon. Analytical framework derives expansion trajectories from documented specification rates in power generation retrofits, data center construction, and automotive underhood packaging. Forecast inputs incorporate OSHA permissible exposure limit enforcement acceleration, EPA community noise standard adoption curves, and ISO 15665 procurement documentation penetration rates. CAGRs reflect triangulated output from demand-side build-up and supply-side capacity constraints.
Decision-makers should treat outputs as directional under sustained OSHA enforcement timelines and stable petrochemical feedstock pricing; material deviation would warrant model refresh. Specific risk factors include MEE guideline acceleration in China, dual carbon enforcement redirection of state-owned enterprise procurement, and certified industrial sewing workforce pipeline collapse. Revision becomes warranted when mass loaded vinyl resin supply concentration crosses critical dependency thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US Metal Stadium Seating Market
Building & Construction Materials
Vietnam Ceramic Tiles Market
Building & Construction Materials
Acoustic Plasterboard Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
Steel Roofing Market
Building & Construction Materials
United States Gutter Guards Market
Building & Construction Materials
Concrete Protective Liners Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
Israel Ceramic Tiles Market
Building & Construction Materials
Decorative Tiles Market
Building & Construction Materials
Acoustic Panel Market
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market
Building & Construction Materials
Limestone Aggregates Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
Roofing Liners Market