
 US Prefabricated Steel Market | 2026-2036
US Prefabricated Steel Market Size, Share, and Industry Trends Forecast 2026-2036
US Prefabricated Steel Market Insights
AISC 360 certification for structural steel buildings is rotating market access toward fabricators with verified quality management systems. Nucor Building Systems leverages its captive steel supply from Electric Arc Furnace operations to control input costs. Butler Manufacturing sustains dominance in rigid-frame agricultural and commercial structures through extensive dealer networks. Varco Pruden Buildings differentiates via specialized clear-span designs for manufacturing facilities.
Prefabricated steel comprises structural members fabricated off-site to precise dimensional tolerances, typically using ASTM A992 wide-flange sections with yield strengths of 50 ksi, then assembled using bolted or welded connections for rapid field erection. Structural steel leads product type demand due to its load-bearing efficiency in mid-rise commercial frames, while sheet steel is displacing conventional cladding in warehousing applications. Building frames capture the largest application share as developers prioritize speed-to-occupancy, though equipment supports for manufacturing automation are gaining traction.
OSHA steel erection standards and AISC seismic provisions govern fabrication tolerances and field safety protocols, with FHWA Buy America requirements mandating domestic melt-and-manufacture origin for federally funded infrastructure. The Department of Energy's efficiency codes for commercial envelopes are pressuring insulation-integrated panel designs. Stakeholders must track evolving EPA emissions rules for Electric Arc Furnace operations that could reshape cost structures for domestic mills supplying the fabrication chain.
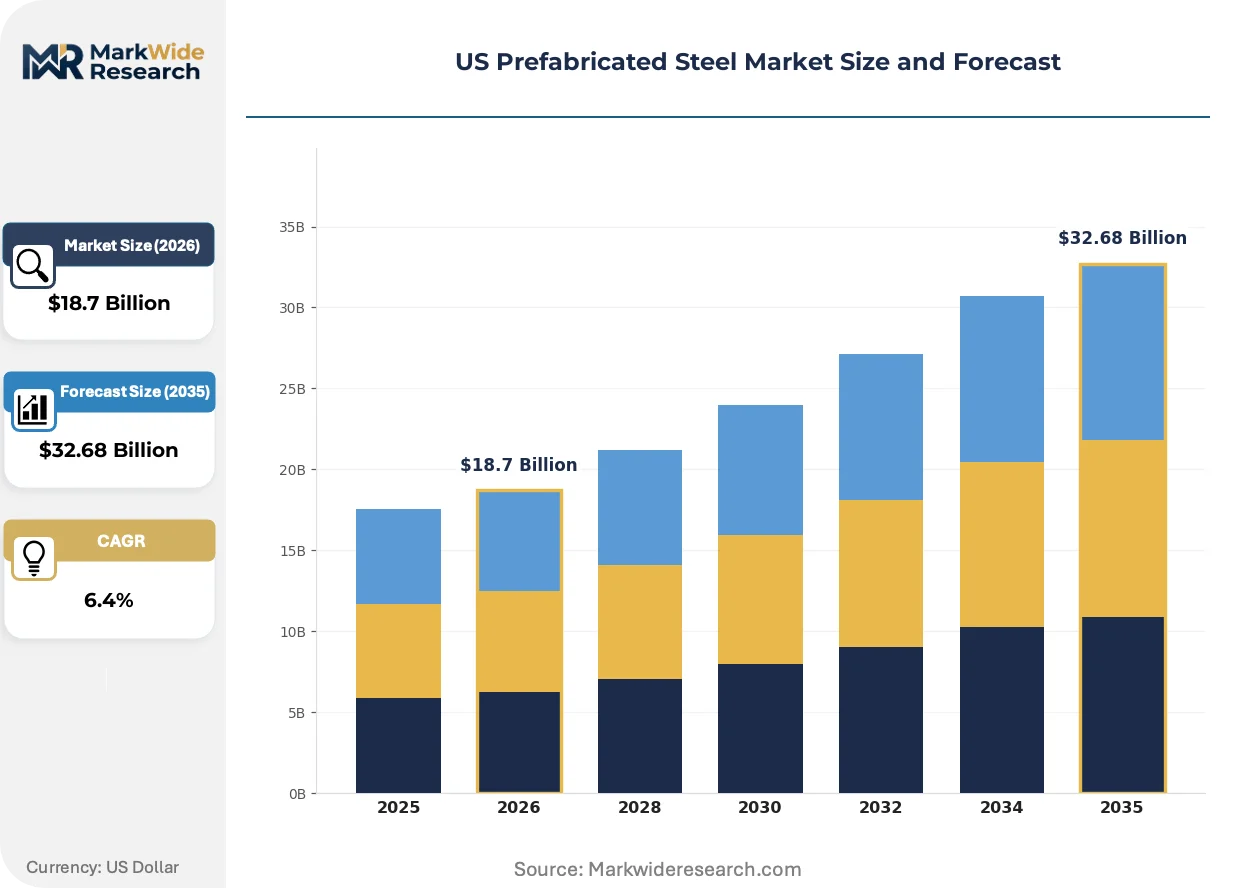
Market Dynamics
Federal infrastructure spending is compressing project timelines and forcing procurement officers toward pre-engineered systems that slash field erection schedules. The Infrastructure Investment and Jobs Act channels billions toward bridge replacement and transit facilities, with FHWA Buy America requirements mandating domestic melt-and-manufacture origin for structural steel components.
Growth Catalysts
- Data center construction:Hyperscale cloud providers in Texas and Virginia are accelerating procurement of clear-span metal buildings to house server farms with rapid occupancy requirements.
- FHWA Buy America mandates:Federally funded bridge programs specify domestically fabricated steel, rotating volume toward US-based Electric Arc Furnace mills.
- Petrochemical facility expansions:Gulf Coast corridor projects demand rapid-delivery structural systems for process equipment enclosures and pipe rack structures.
Market Restraints
- Scrap price volatility:Electric Arc Furnace operations depend on ferrous scrap feedstock, exposing fabricators to commodity swings that compress margin predictability.
- Domestic mill concentration:Structural wide-flange production concentrates among a handful of US mills, creating supply vulnerability during capacity constraints.
- Concrete substitution in low-rise:Tilt-up concrete construction retains cost advantages for single-story warehousing in markets with abundant ready-mix supply.
Strategic Opportunities
- Modular data center integration:Prefabricated steel frames paired with factory-installed MEP systems are capturing hyperscale contracts in Northern Virginia's Loudoun County corridor.
- Department of Energy envelope codes:Stricter commercial building efficiency standards are pressuring demand for insulated metal panels with integrated thermal breaks.
- Reshoring manufacturing footprints:Industrial developers in Ohio and Michigan are specifying pre-engineered structures for automated production facilities requiring column-free spans.
Industry Challenges
- Certified welder shortages:AWS D1.1 structural welding certification requirements are constraining fabrication shop capacity expansion in tight labor markets.
- Seismic detailing complexity:AISC 341 moment frame specifications demand specialized engineering resources that smaller regional fabricators struggle to retain.
- OSHA steel erection compliance:Subcontractor safety protocols for fall protection and hoisting operations extend project mobilization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Prefabricated Steel Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Steel, Sheet Steel, Reinforcing Steel, Expanded Metal End User: Construction, Industrial, Residential, Infrastructure Application: Building Frames, Roofing, Bridges, Equipment Supports Manufacturing Stage: Fabrication, Surface Treatment, Pre-Assembly, Distribution |
| Companies Covered | Nucor Building Systems, American Buildings Company, Varco Pruden Buildings, Star Building Systems, Butler Manufacturing, Mueller, Inc., General Steel, Rigid Global Buildings, Steel Dynamics, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Prefabricated Steel Market Trends and Innovations
BIM-to-fabrication workflows are collapsing design-to-delivery cycles and enabling just-in-sequence steel delivery for complex commercial frames. Three forces are restructuring competitive positioning: digital fabrication integration, regulatory pressure on embodied carbon, and buyer consolidation among national developers.
Building Information Modeling is decomposing traditional sequential workflows between architects, engineers, and fabricators. National retail and logistics developers are mandating Level of Development 400 models that drive CNC plasma cutting and robotic welding directly. This compression is eliminating redraw cycles and reducing field RFIs by enabling clash detection before shop drawings release.
EPA emissions rules for Electric Arc Furnace operations are tightening particulate and greenhouse gas thresholds for domestic mills. The regulatory pressure is elevating capital requirements for pollution control retrofits and favoring larger integrated producers with environmental compliance resources. Gulf Coast and Midwest fabricators dependent on regional mill supply are tracking permit timelines that could constrain input availability.
Consolidated national developers are unbundling design-build contracts and bringing pre-construction services in-house. General contractors with captive steel procurement teams are displacing traditional broker relationships and negotiating direct mill contracts. This concentration is most visible in Texas and Florida markets where institutional capital deploys speculative industrial product at scale.
US Prefabricated Steel Market Segmentation
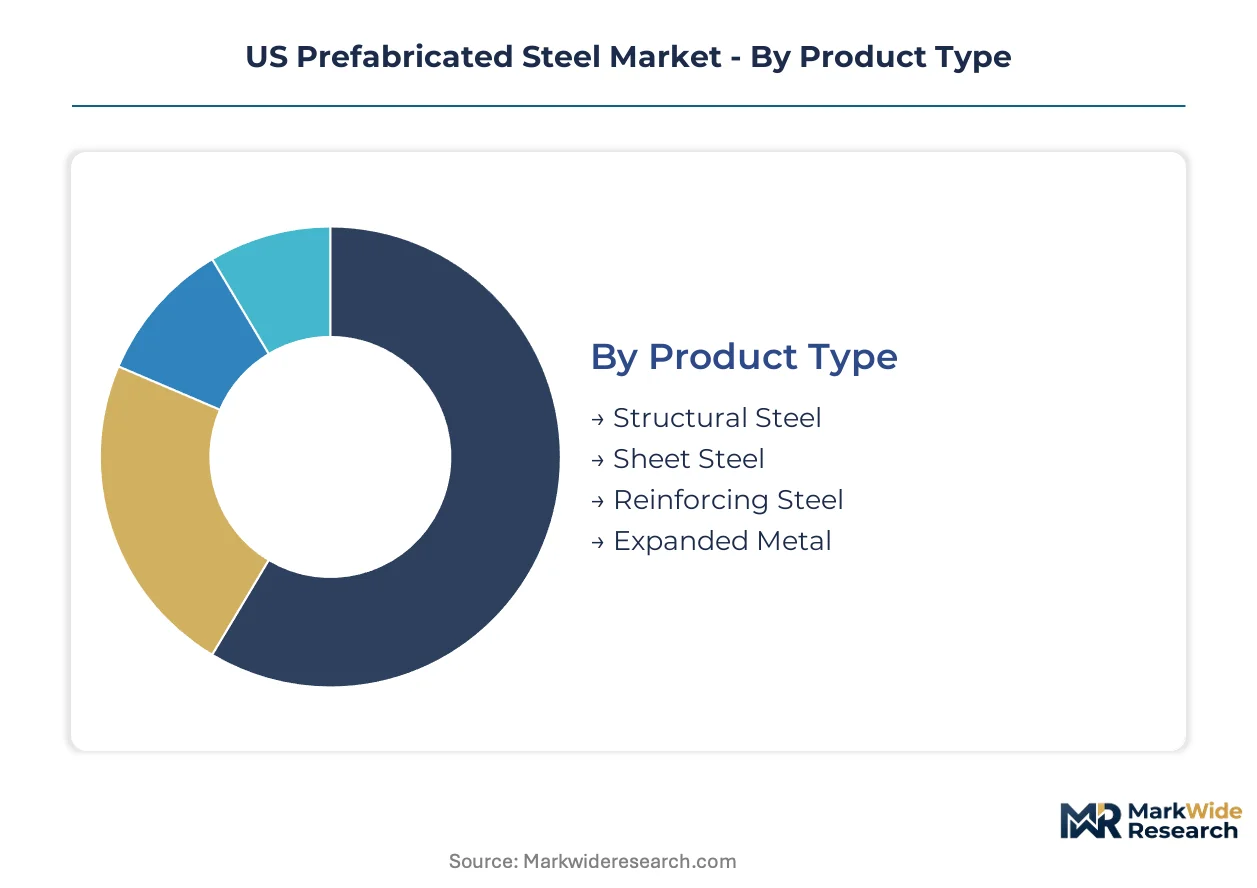
Segmentation reveals how prefabricated steel demand fractures across product specifications, end-use requirements, and fabrication complexity. Procurement patterns diverge sharply between federally funded infrastructure and private commercial development.
Product Type:
Structural steel dominates domestic fabrication output while sheet steel serves export-adjacent cladding markets. Reinforcing steel and expanded metal occupy specialized niches with distinct supply chain footprints.
- Structural Steel:ASTM A992 wide-flange sections with 50 ksi yield strength form the backbone of commercial and industrial frames. Texas and Virginia data center developers specify these members for rapid field bolting in clear-span configurations.
- Sheet Steel:Cold-formed galvanized panels displace conventional cladding in warehousing across the Gulf Coast corridor. Petrochemical facility enclosures drive specification of corrosion-resistant coatings for process equipment housing.
- Reinforcing Steel:Rebar and welded wire mesh integrate with concrete tilt-up systems in hybrid construction. Bridge replacement programs under FHWA jurisdiction specify domestically melted deformed bar.
- Expanded Metal:Diamond-pattern mesh serves safety grating and architectural screening applications. Industrial platforms and mezzanines in Ohio and Michigan manufacturing facilities specify slip-resistant surfaces.
Structural steel commands the established base. The steepest expansion runs through sheet steel as insulated panel systems penetrate commercial envelopes.
End User:
Cost tier differentiation separates high-specification industrial buyers from price-sensitive residential developers. Infrastructure procurement operates under distinct regulatory compliance requirements.
- Construction:Commercial developers prioritize speed-to-occupancy through pre-engineered building systems. National retail and logistics operators in Texas and Florida specify rigid-frame structures for speculative industrial product.
- Industrial:Automated manufacturing facilities in the Midwest demand column-free spans exceeding 100 feet for robotic production lines. Reshoring initiatives in Ohio and Michigan accelerate specification of pre-engineered structures.
- Residential:Barndominium and accessory dwelling unit markets in rural Texas and Florida adopt light-gauge steel framing. Cost competition with wood platform construction constrains penetration in suburban markets.
- Infrastructure:FHWA Buy America mandates rotate bridge and transit procurement toward domestic Electric Arc Furnace mills. Federal funding compression forces procurement officers toward pre-assembled truss systems.
Construction absorbs the volume base. Industrial end-use is climbing the fastest as reshoring manufacturing footprints multiply.
Application:
Application segmentation tracks load-bearing hierarchy from primary structural systems through secondary support elements. Volume concentration favors building frames while specialized engineering resources concentrate in bridge applications.
- Building Frames:Rigid-frame and braced-frame systems dominate mid-rise commercial construction. Northern Virginia's Loudoun County data center corridor specifies clear-span frames with integrated MEP routing.
- Roofing:Standing seam and through-fastened panels serve agricultural and commercial envelopes. Department of Energy efficiency codes pressure adoption of insulated metal panels with thermal breaks.
- Bridges:Modular steel truss and girder systems accelerate field erection for FHWA-funded replacement programs. Domestic melt-and-manufacture certification requirements constrain eligible fabricator pools.
- Equipment Supports:Pipe racks and process equipment platforms serve Gulf Coast petrochemical expansions. Rapid-delivery requirements favor pre-assembled modular structures over field-fabricated alternatives.
Building frames command the established base. Equipment supports are gaining share fastest as process industry automation intensifies.
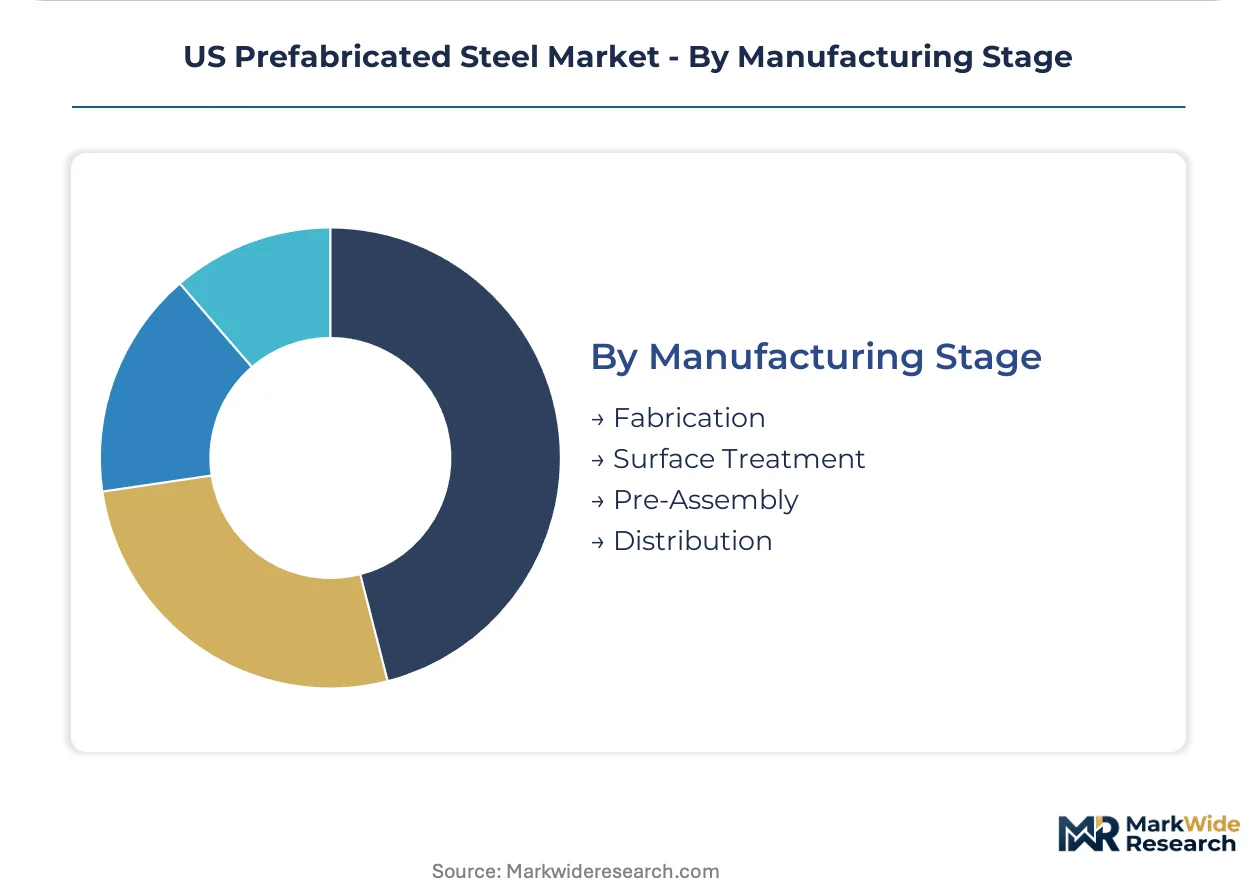
Manufacturing Stage:
Supply concentration varies across fabrication, surface treatment, and pre-assembly stages. Margin capture shifts downstream toward integrated providers controlling multiple stages.
- Fabrication:CNC plasma cutting and robotic welding transform mill-rolled sections into precise structural members. AWS D1.1 certified welder shortages constrain shop capacity expansion in tight labor markets.
- Surface Treatment:Hot-dip galvanizing and intumescent coating application extend corrosion and fire resistance. EPA emissions rules for coating operations elevate capital requirements for pollution control.
- Pre-Assembly:Factory-bolted subassemblies reduce field erection schedules for complex commercial frames. BIM-to-fabrication workflows enable just-in-sequence delivery to congested urban sites.
- Distribution:Dealer networks and direct mill relationships compete for contractor procurement loyalty. Consolidated national developers increasingly negotiate direct contracts bypassing traditional broker channels.
Fabrication commands the established base. Pre-assembly is expanding most quickly as developers compress construction schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Infrastructure Investment and Jobs Act is channeling federal funds toward bridge replacement and transit facilities across multiple states, compressing project timelines and accelerating procurement of pre-engineered structural systems. State-level energy codes and seismic provisions are creating differentiated demand patterns that favor fabricators with region-specific engineering capabilities.
Texas
Hyperscale data center construction in the Dallas-Fort Worth and Austin corridors is driving procurement of clear-span metal buildings with rapid occupancy requirements. ERCOT grid reliability concerns are pushing developers toward steel-framed facilities with integrated backup power enclosures. The Permian Basin petrochemical expansion sustains demand for process equipment structures and pipe rack systems.
Virginia
Northern Virginia's Loudoun County data center cluster specifies rigid-frame buildings with factory-installed MEP routing for server farm deployment. Dominion Energy interconnection queues are forcing developers toward pre-assembled electrical substation enclosures. State procurement guidelines for public facilities reference AISC 360 certification requirements that filter eligible fabricator pools.
Ohio
Reshoring manufacturing initiatives in the Cleveland-Akron corridor are accelerating specification of column-free pre-engineered structures for automated production lines. Ohio EPA air quality permits for coating operations are elevating capital requirements for regional fabricators. The Toledo-Lima industrial belt sustains demand for equipment support structures serving automotive supplier facilities.
Louisiana
Gulf Coast petrochemical facility expansions require rapid-delivery structural systems for process enclosures and flare stack supports. Louisiana Department of Environmental Quality emissions rules for surface treatment operations constrain shop capacity expansion. The Lake Charles industrial corridor concentrates procurement of corrosion-resistant modular structures for chemical processing applications.
California
Seismic detailing requirements under AISC 341 moment frame specifications are concentrating demand among fabricators with specialized engineering resources. California Energy Commission Title 24 envelope standards are pressuring adoption of insulated metal panels with thermal breaks. The Central Valley logistics corridor sustains procurement of rigid-frame warehousing for e-commerce distribution networks.
US Prefabricated Steel Market Competitive Landscape
Player mix skews toward integrated steel producers with captive melt capacity and specialized building system fabricators with regional dealer networks. Market structure concentrates volume among a handful of national providers while fragmenting across regional specialists serving local construction markets. Two strategic archetypes dominate: vertically integrated mills controlling raw material through finished building systems, and engineering-intensive fabricators differentiating through design-build capabilities. Competitive dynamics center on direct mill contract negotiations by consolidated developers and certified welder recruitment for fabrication shop expansion.
Among integrated producers with captive steel supply, Nucor Building Systems exemplifies the mill-forward archetype leveraging Electric Arc Furnace operations for input cost control. Butler Manufacturing occupies a position within the rigid-frame commercial segment through extensive dealer network coverage. Varco Pruden Buildings represents the engineering-specialist tier with clear-span design capabilities for manufacturing facility applications.
| Leading Market Players |
|---|
| Nucor Building Systems |
| American Buildings Company |
| Varco Pruden Buildings |
| Star Building Systems |
| Butler Manufacturing |
| Mueller, Inc. |
| General Steel |
| Rigid Global Buildings |
| Steel Dynamics, Inc. |
| Others |
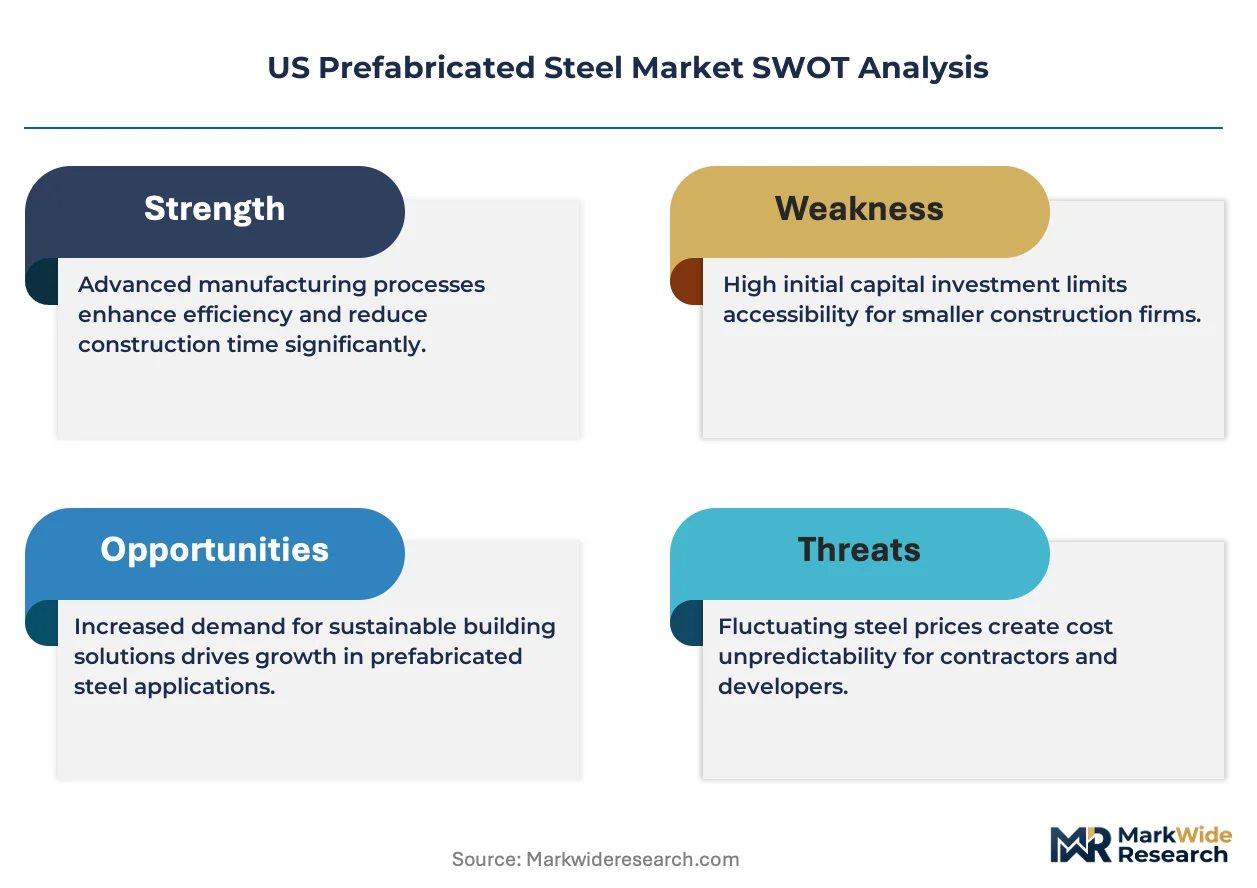
Pricing and Supply Chain Analysis
Long-term offtake contracts between Electric Arc Furnace mills and national building system providers lock in scrap feedstock access while stabilizing input cost visibility across multi-year project pipelines. These arrangements concentrate pricing power among integrated producers with captive melt capacity, forcing independent fabricators toward spot market exposure.
Pricing Analysis
AISC 360 certification grade creates the primary spread between premium and standard fabrication tiers, with seismic-compliant moment frame systems commanding substantial premiums over conventional rigid-frame structures. Project-based pricing dominates commercial construction procurement, while federally funded infrastructure contracts incorporate FHWA Buy America compliance premiums. Cost compression in standard-grade structural steel is intensifying due to concrete substitution pressure in single-story warehousing. National developers with direct mill relationships exhibit the lowest price sensitivity, whereas regional contractors dependent on dealer networks face margin erosion from intermediary markups.
Supply Chain Analysis
The United States anchors structural wide-flange production, with domestic Electric Arc Furnace mills supplying ASTM A992 sections to fabrication shops concentrated in the Gulf Coast and Midwest corridors. Ferrous scrap feedstock draws from industrial recycling networks across the Rust Belt, while zinc for galvanizing operations sources from Canadian and Australian mining operations. Single-source vulnerability concentrates in structural wide-flange production, where capacity constraints at domestic mills create procurement bottlenecks during infrastructure spending surges. Distribution runs through manufacturer-direct contracts with consolidated developers and regional dealer networks serving contractor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AWS D1.1 certified welder scarcity constrains fabrication shop expansion, creating a bottleneck that favors incumbents with established training pipelines and locking out smaller regional competitors from high-specification work.
For Market Incumbents: Consolidate fabrication capacity in Texas and Virginia corridors where data center demand concentrates, capturing direct contracts with hyperscale developers that displace dealer-mediated relationships. Invest in robotic welding systems to offset certified welder shortages while deepening upstream control over Electric Arc Furnace supply through equity stakes or long-term offtake arrangements. For New Entrants and Emerging Players: AISC 341 seismic certification fast-track offers entry into California's high-specification commercial market, where engineering-intensive moment frame demand outstrips qualified fabricator supply. Target equipment support structures for Gulf Coast petrochemical expansions, where rapid-delivery requirements favor agile specialists over integrated giants. Pursue design-build partnerships with regional engineering firms lacking captive fabrication assets. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale fabricators with established AWS D1.1 certification pipelines and proximity to Northern Virginia or Dallas-Fort Worth data center corridors. Long-term viability hinges on positioning for reshoring manufacturing facility demand in the Midwest, where column-free span requirements favor pre-engineered steel over conventional construction. Monitor EPA emissions permit timelines for Electric Arc Furnace operations as an inflection indicator for input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Supply | Captive ferrous feedstock access insulates margin from commodity volatility at Nucor-scale operations. |
| Robotic Welding Deployment | Automated fabrication cells offset AWS D1.1 certified welder scarcity constraining shop capacity expansion. |
| AISC 341 Seismic Certification Investment | Specialized moment frame engineering capabilities unlock California commercial and infrastructure procurement. |
| Direct Developer Contract Negotiation | Bypassing dealer networks captures margin from consolidated national retail and logistics operators. |
| Insulated Metal Panel Manufacturing Expansion | Department of Energy envelope code compliance positions fabricators for efficiency-mandated commercial retrofits. |
Research Methodology
The analysis maps structural steel fabrication, sheet steel cladding, and pre-engineered building systems, each validated through primary interviews with fabrication shop managers, structural engineers at national design firms, procurement officers at hyperscale data center developers, and FHWA program administrators. Secondary validation draws from AISC certification databases, EPA emissions filings for Electric Arc Furnace operations, SEC 10-K disclosures from integrated steel producers, and Infrastructure Investment and Jobs Act obligation tracking. Bottom-up project pipeline enumeration triangulates against top-down steel consumption estimates from domestic mill shipment reports.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models demand by product type, end-user sector, application hierarchy, and manufacturing stage complexity, with regional disaggregation tracking state-level energy codes and seismic provisions. CAGRs derive from regression analysis of historical mill shipments against construction put-in-place data, with forecast inputs incorporating petrochemical facility expansion timelines and data center interconnection queue progression.
Underlying assumptions cover scrap price stabilization, certified welder pipeline replenishment, and federal infrastructure funding continuity, with deviation risk concentrated in EPA emissions rule stringency and Electric Arc Furnace capacity utilization swings. Recalibration cycles align with material shifts in infrastructure appropriations, hyperscale cloud provider capex announcements, and regional seismic code amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
Global Fiber Cement Board Market
Building & Construction Materials
Global Stucco Market
Building & Construction Materials
Clean Room Panels Market
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
Masonry Sealers Market
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Spray Foam Market
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Travertine Market
Building & Construction Materials
Steep Slope Roofing Materials Market