
 Pre-Insulated Pipes Market | 2026-2036
Pre-Insulated Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Insulated Pipes Market Analysis
The EU Green Deal is rebalancing procurement criteria toward lifecycle carbon performance in district energy infrastructure. LOGSTOR A/S leverages its Danish manufacturing base to dominate Nordic district heating contracts. Isoplus Fernwaermetechnik GmbH anchors Central European project pipelines with specialized polyurethane foam expertise. Uponor Oyj competes through cross-linked polyethylene flexibility in residential hydronic networks.
Pre-insulated pipes comprise carrier pipes sheathed in rigid polyurethane foam insulation and protected by polyethylene or steel outer jackets, engineered to minimize thermal loss across fluid transport distances exceeding 30 kilometers. Polyurethane insulation leads value capture due to superior lambda values and established spray-deposition manufacturing, while polyethylene jackets extend service life in buried installations against groundwater ingress. District heating applications occupy the largest demand share among end users, though industrial process cooling represents the fastest-expanding application segment as data centers and pharmaceutical facilities adopt closed-loop thermal management.
EMA's construction product regulation and REACH chemical compliance frameworks govern material composition and environmental release thresholds across European installations, with CE marking mandatory for market access. Germany's KBA and France's ANSM coordinate with national building codes to enforce minimum insulation thickness for underground utility crossings. Stakeholders must monitor evolving national transpositions of the EU Energy Performance of Buildings Directive as these reshape tender specifications and retrofit timelines.
Market Dynamics
Polyurethane foam chemistry constraints and REACH chemical compliance thresholds are compressing supplier margins while forcing reformulation investments across European manufacturing bases.
Growth Catalysts
- EU Green Deal building mandates:The Energy Performance of Buildings Directive tightens thermal efficiency minimums for underground distribution retrofits, accelerating municipal tender volumes.
- Nordic district heating densification:Copenhagen and Stockholm utility operators are expanding fourth-generation low-temperature network footprints, driving large-diameter pre-insulated pipe contracts.
- Data center liquid cooling adoption:Hyperscale facilities in Frankfurt and Amsterdam are deploying closed-loop pre-insulated circuits to manage chip thermal loads, creating industrial demand outside traditional heating.
Market Restraints
- Isocyanate feedstock volatility:MDI and polyol pricing swings tied to European petrochemical capacity constrain polyurethane insulation cost predictability for project developers.
- Specialized installer scarcity:Certified welding technicians for steel carrier pipe fusion remain concentrated in Germany and Denmark, creating bottleneck risk for cross-border deployments.
- Rigid polyurethane lambda limits:Current material science boundaries prevent further thermal conductivity reduction without vacuum panel substitution, capping efficiency gains.
Strategic Opportunities
- Eastern European district heating rehabilitation:Polish and Romanian municipal grids built during Soviet-era industrialization require complete pipe replacement, opening greenfield contract pipelines.
- Industrial waste heat recovery networks:Steel and chemical plants in Belgium and the Netherlands are monetizing excess thermal energy through pre-insulated distribution to nearby residential clusters.
- Cross-linked polyethylene flexibility expansion:Uponor's PEX-a technology enables trenchless installation in dense urban cores where rigid steel carriers face right-of-way constraints.
Industry Challenges
- CE marking timeline compression:EMA construction product regulation testing protocols extend certification cycles to 18-24 months, delaying project-ready inventory availability.
- Legacy asbestos pipe identification:Danish and German urban renewal sites encounter unmapped 1970s-era insulation materials, triggering hazardous material handling cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Insulated Pipes Market |
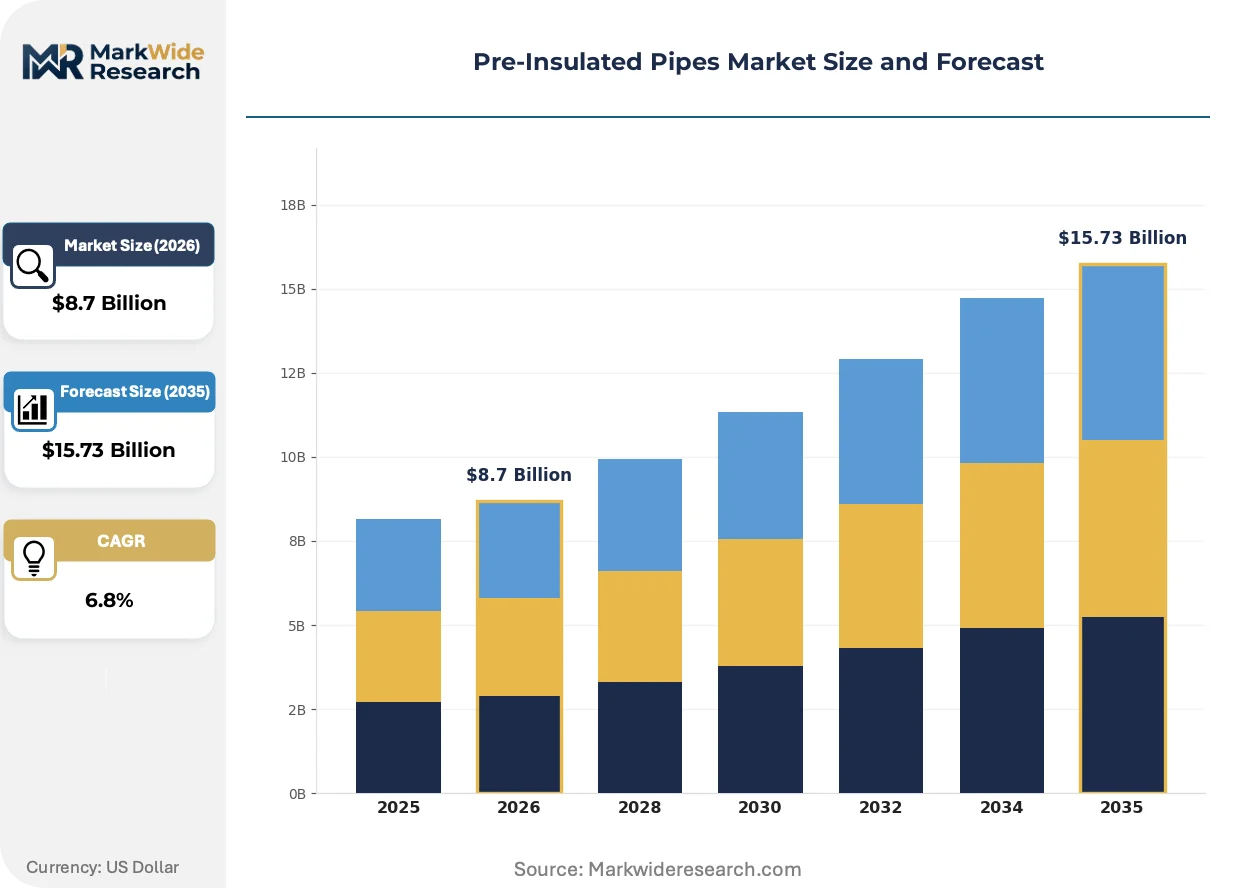
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Polyethylene, PVC, Steel Application: District Heating, Industrial Processes, Refrigeration, Oil & Gas End User: Construction, Utilities, Manufacturing, Energy Sector Installation Type: Onshore, Offshore, Buried, Above Ground |
| Companies Covered | LOGSTOR A/S, Isoplus Fernwaermetechnik GmbH, Uponor Oyj, Aquatherm GmbH, Polypipe Group PLC, Perma-Pipe International Holdings, Inc., BRUGG Rohrsystem AG, Watts Water Technologies, Inc., GF Piping Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Insulated Pipes Market Emerging Trajectories
Digital twin integration and sensor-embedded pipe monitoring are redefining lifecycle value propositions, shifting buyer evaluation from upfront capital cost to total thermal performance accountability.
Sensor-embedded pre-insulated pipes are integrating fiber-optic leak detection and thermal gradient monitoring directly into polyurethane foam layers. District heating operators in Aarhus and Hamburg are piloting these smart circuits to pinpoint insulation degradation before thermal loss thresholds breach contract penalties. Real-time telemetry is integrating predictive maintenance workflows, compressing outage response windows from days to hours.
REACH chemical compliance is tightening allowable blowing agent formulations for polyurethane foam production. ECHA's 2023 restriction proposals target hydrofluorocarbon residual content, forcing insulation manufacturers toward pentane or water-based alternatives with higher lambda values. German KBA enforcement of updated environmental release thresholds is accelerating reformulation timelines for suppliers serving Central European infrastructure tenders.
Lifecycle carbon accounting is displacing first-cost procurement in Nordic municipal tenders. Copenhagen's utility procurement now mandates embodied carbon disclosure across pipe manufacturing, insulation production, and end-of-life recycling pathways. Danish and Swedish project developers are bundling installation contracts with 30-year thermal performance guarantees, transferring operational risk from public balance sheets to contractor obligations.
Pre-Insulated Pipes Market Segmentation
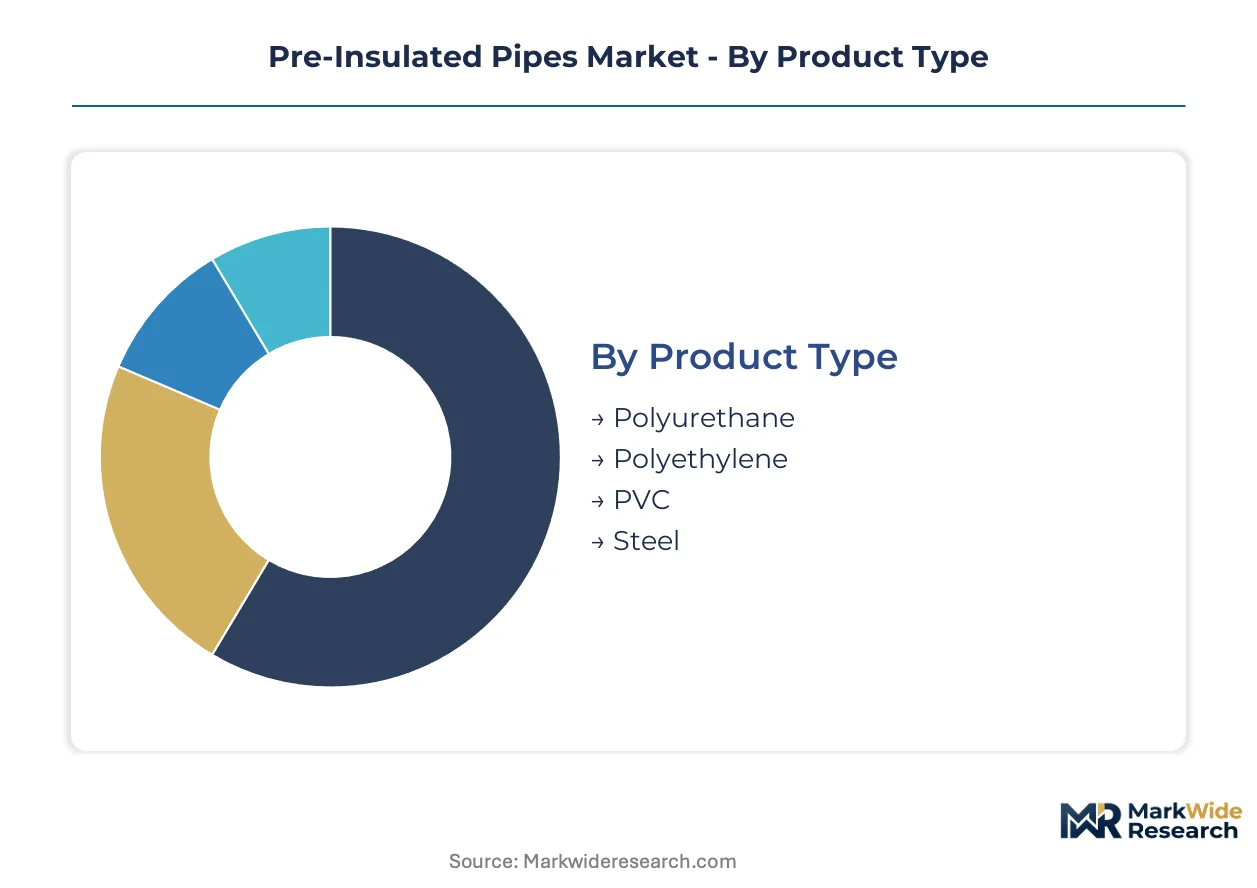
Pre-insulated pipe procurement decisions pivot on thermal performance specifications, installation constraints, and lifecycle carbon accountability. Material chemistry and jacket durability determine suitability across buried district heating networks, exposed industrial corridors, and subsea energy infrastructure.
Product Type:
Customization intensity spans rigid polyurethane foam systems demanding precise lambda calibration to commodity-grade polyethylene jackets suitable for standardized trench deployments.
- Polyurethane:Rigid closed-cell foam delivers superior thermal resistance with lambda values below 0.025 W/mK, making it indispensable for Copenhagen and Stockholm fourth-generation low-temperature district heating networks where heat loss minimization drives tender specifications. REACH chemical compliance and ECHA blowing agent restrictions are forcing reformulation toward pentane-based alternatives with margin-compressing qualification timelines.
- Polyethylene:High-density outer jackets provide moisture barriers and mechanical protection for buried installations, with cross-linked variants enabling trenchless deployment in dense German urban cores where right-of-way constraints block rigid steel carriers. Demand concentrates in residential hydronic retrofits across Central European municipal utility portfolios.
- PVC:Cost-effective jacket material for above-ground industrial cooling circuits in pharmaceutical and food processing facilities where UV exposure and mechanical impact risks remain minimal.
- Steel:Corrosion-resistant carrier pipes and outer jackets serve high-pressure steam distribution and offshore oil and gas pipelines requiring structural integrity across temperature cycling and marine environments.
Leading the category by volume: Polyurethane. Growing fastest: Cross-linked polyethylene variants gaining share in urban infill projects.
Application:
Revenue concentration follows heat density gradients, with municipal district heating commanding project scale and data center liquid cooling delivering premium pricing per linear meter.
- District Heating:Fourth-generation low-temperature networks in Nordic cities deploy large-diameter pre-insulated circuits exceeding 30 kilometers to distribute waste heat and renewable thermal sources, with Copenhagen's utility procurement now mandating 30-year performance guarantees and embodied carbon disclosure across manufacturing pathways.
- Industrial Processes:Closed-loop thermal management for hyperscale data centers in Frankfurt and Amsterdam represents the steepest expansion trajectory, as chip thermal densities exceed air-cooling limits and drive liquid cooling infrastructure investment.
- Refrigeration:Cold chain distribution networks and pharmaceutical storage facilities deploy pre-insulated ammonia and CO2 piping to maintain sub-zero temperatures with minimal energy input.
- Oil & Gas:Subsea production flowlines and onshore gathering systems require steel-carrier pre-insulated pipes to manage waxy crude viscosity and hydrate formation across arctic and deepwater developments.
District Heating retains the largest installed base. Industrial Processes climb fastest on data center buildouts.
End User:
Procurement sophistication diverges between municipal utilities with lifecycle cost frameworks and manufacturing facilities prioritizing first-cost minimization.
- Construction:Residential and commercial building developers specify pre-insulated hydronic piping for underfloor heating and domestic hot water distribution, with EU Green Deal building mandates tightening thermal efficiency minimums for new build and retrofit installations.
- Utilities:Municipal district heating operators in Germany, Denmark, and Poland drive large-diameter contract volumes, bundling installation with decades-long thermal performance guarantees that transfer operational risk to contractors.
- Manufacturing:Steel and chemical plants in Belgium and the Netherlands monetize waste heat through pre-insulated distribution to nearby residential clusters, creating industrial-to-urban thermal networks.
- Energy Sector:Oil and gas producers and geothermal developers deploy pre-insulated gathering systems and injection pipelines across temperature-extreme environments.
Utilities dominate contract value. Manufacturing expands most quickly on industrial symbiosis networks.
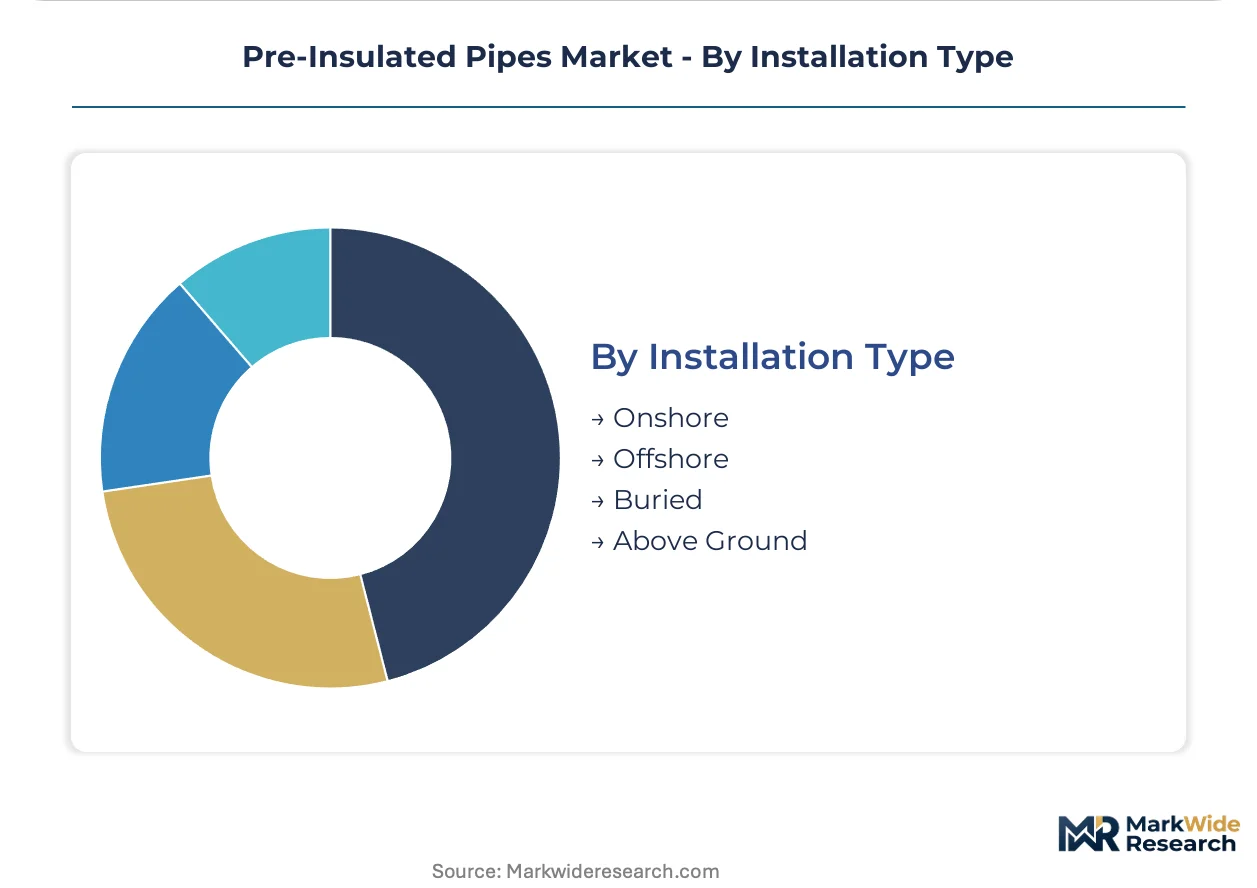
Installation Type:
Subsurface deployment complexity determines contractor specialization requirements and project margin structures.
- Onshore:Buried and above-ground installations across industrial sites and municipal corridors, with German KBA enforcement of minimum insulation thickness for utility crossings creating compliance-driven specification tiers.
- Offshore:Subsea pre-insulated flowlines for oil and gas production and coastal district heating intakes, requiring corrosion-resistant steel carriers and concrete weight coatings.
- Buried:Dominant urban deployment mode for district heating and cooling networks, with polyethylene jacket integrity against groundwater ingress determining service life.
- Above Ground:Industrial process piping and temporary construction heating where trenching costs exceed aerial support structure investment.
Buried installations lead by linear meters installed. Offshore commands highest unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of pre-insulated pipes clusters in Northern European manufacturing corridors while consumption concentrates in German municipal retrofits and Nordic district heating densification. Danish and German fabricators supply polyurethane-insulated systems across borders, with transport economics favoring regional sourcing for large-diameter contracts. The EU Green Deal's building decarbonization mandates are synchronizing tender specifications across member states, compressing procurement cycles for cross-border infrastructure projects.
Germany
Municipal utilities in North Rhine-Westphalia and Bavaria are replacing Soviet-era cogeneration piping with fourth-generation low-temperature networks. KBA enforcement of updated insulation thickness minimums for utility crossings is tightening specification tiers. Frankfurt's data center cluster is deploying closed-loop liquid cooling circuits, creating industrial demand outside traditional heating applications.
Denmark
Copenhagen's utility procurement mandates 30-year thermal performance guarantees and embodied carbon disclosure across manufacturing pathways. Danish manufacturers leverage pentane-based polyurethane reformulation to meet ECHA blowing agent restrictions. Aarhus operators are piloting sensor-embedded pipes with fiber-optic leak detection to compress outage response windows.
Sweden
Stockholm's fourth-generation district heating expansion is driving large-diameter pre-insulated pipe contracts exceeding 30 kilometers. Swedish building codes transposing the EU Energy Performance of Buildings Directive are accelerating retrofit timelines. Malmö's industrial symbiosis networks monetize steel plant waste heat through pre-insulated distribution to residential clusters.
Poland
Municipal grids in Silesia and Warsaw built during Soviet-era industrialization require complete pipe replacement, opening greenfield contract pipelines. Polish national building codes are tightening thermal efficiency minimums for underground utility retrofits. Krakow's utility operators are bundling installation with decades-long performance guarantees that transfer operational risk to contractors.
Netherlands
Chemical plants in Rotterdam and Eindhoven are deploying pre-insulated networks to monetize excess thermal energy through residential distribution. Dutch environmental release thresholds under REACH compliance frameworks are accelerating reformulation timelines for insulation suppliers. Amsterdam's hyperscale data centers are adopting closed-loop thermal management as chip densities exceed air-cooling limits.
Pre-Insulated Pipes Market Vendor Landscape
The competitive structure tilts toward vertically integrated polyurethane specialists with captive foam production and established district heating installation partnerships. Danish and German manufacturers anchor premium-tier positioning through Nordic municipal relationships, while mid-scale fabricators compete on polyethylene jacket flexibility for residential hydronic retrofits. Two strategic archetypes dominate: insulation chemistry specialists controlling blowing agent reformulation pipelines, and system integrators bundling pipe supply with decades-long performance guarantees. Consolidation pressure is concentrating around cross-border installation capabilities and REACH-compliant material science portfolios.
Among Danish and German specialists, LOGSTOR A/S and Isoplus Fernwaermetechnik GmbH occupy positions exemplifying the integrated manufacturing archetype, with Uponor Oyj representing the flexibility-focused tier through cross-linked polyethylene expertise. These three anchors illustrate how competitive positioning splits between rigid polyurethane dominance in large-scale district heating and PEX-a adaptability in dense urban infill. Geographic origin and corporate structure—A/S, GmbH, and Oyj suffixes—signal divergent regulatory and capital market exposures that shape strategic optionality.
| Leading Market Players |
|---|
| LOGSTOR A/S |
| Isoplus Fernwaermetechnik GmbH |
| Uponor Oyj |
| Aquatherm GmbH |
| Polypipe Group PLC |
| Perma-Pipe International Holdings, Inc. |
| BRUGG Rohrsystem AG |
| Watts Water Technologies, Inc. |
| GF Piping Systems |
| Others |
Supply Flow & Price Mechanics
EU Green Deal building decarbonization mandates gate qualified supply and premium-tier pricing access, as REACH-compliant polyurethane reformulation and CE marking timelines compress margins for non-compliant fabricators while rewarding Nordic and German manufacturers with established district heating partnerships.
Pricing Analysis
Lifecycle thermal performance guarantees anchor value-based pricing, with Copenhagen and Stockholm utilities bundling 30-year contracts that transfer operational risk to installers. Price differentiation separates REACH-compliant pentane-foam systems from legacy HFC-based alternatives, with certification grade and volume scale driving tier spreads. Cost compression in standard-grade polyethylene jackets intensifies as Central European fabricators compete for residential hydronic retrofits. Municipal utilities exhibit lowest price sensitivity due to lifecycle cost frameworks, while manufacturing facilities prioritize first-cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with German and Danish polyurethane specialists controlling blowing agent reformulation pipelines. Raw material flows draw from Belgian petrochemical corridors for MDI and polyol feedstocks, with steel carrier pipes sourced from regional mills in Poland and the Czech Republic. Supply chain risk centers on isocyanate price volatility tied to European cracker capacity. Distribution runs through project-specific contracting channels where certified welding technicians in Germany and Denmark anchor cross-border deployment capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-embedded pre-insulated pipes with fiber-optic monitoring are displacing passive pipe systems, as district heating operators shift procurement criteria from upfront capital to predictive maintenance accountability.
For Market Incumbents: Anticipate REACH chemical compliance timeline compression by accelerating pentane-based foam qualification and securing captive MDI supply agreements. Backward integration into blowing agent chemistry and expansion of certified welding training programs in Poland and Romania defend against installer scarcity bottlenecks threatening cross-border project execution. For New Entrants and Emerging Players: Launch via specialized industrial symbiosis networks in Belgium and the Netherlands, where steel and chemical plants seek pre-insulated distribution partners for waste heat monetization. Eastern European district heating rehabilitation offers the most penetrable geography, with Polish municipal grids requiring complete Soviet-era pipe replacement and bundled performance guarantees creating service-based differentiation angles. For Investors and Strategic Acquirers: Copenhagen's 30-year thermal performance guarantee mandate is the leading indicator that operational risk transfer contracts will spread across Nordic and Central European tenders. Targets with REACH-compliant material science portfolios and cross-border installation capabilities offer strongest acquisition profiles. Watch for ECHA restriction finalization on residual HFC content as the signal for accelerated industry consolidation around reformulation-ready assets.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Foam Reformulation | ECHA blowing agent restrictions force qualification investments that reshape competitive tiers across European manufacturing bases. |
| Sensor-Embedded Pipe Deployment | Aarhus and Hamburg pilots demonstrate fiber-optic leak detection compressing outage response from days to hours. |
| Cross-Border Installation Capability Buildout | Polish and Romanian municipal retrofits demand certified welding capacity expansion beyond German and Danish concentration. |
| Industrial Symbiosis Network Partnership | Belgian steel plants monetize waste heat through pre-insulated distribution to nearby residential clusters. |
| 30-Year Performance Guarantee Bundling | Copenhagen procurement mandates transfer operational risk from public balance sheets to contractor obligations. |
Methodological Framework
Trade databases, EU regulatory filings, and district heating utility procurement records formed the secondary backbone, supplemented by primary interviews with polyurethane foam chemists, municipal utility planning officers, certified pipeline welding contractors, and EPC project developers. Bottom-up and top-down triangulation validated segment-level estimates against aggregate market sizing.
Bottom-up volume modeling tracked carrier pipe diameter, insulation thickness, and jacket material specifications across application segments, while top-down cross-checks anchored totals to European construction product regulation compliance data. CAGRs derived from fitted trend extrapolation across the projection horizon, with inputs including Nordic fourth-generation network deployment timelines and data center liquid cooling adoption curves in Frankfurt and Amsterdam clusters.
Feedstock price volatility, REACH restriction implementation delays, and municipal budget cycle interruptions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology adoption pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market
Building & Construction Materials
Thin Wall Mould Market
Building & Construction Materials
Global Steel Service Centers Market
Building & Construction Materials
Building Acoustic Insulation Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market
Building & Construction Materials
I-Joist Market
Building & Construction Materials
Nordic Solar Shades Market
Building & Construction Materials
Saudi Arabia Tiles Market
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
India UPVC Doors and Windows Market
Building & Construction Materials
Door Hardware Market
Building & Construction Materials
Ready-Mix Concrete Market
Building & Construction Materials
Global Wall Putty Market
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
Calcium Sulphate Board Raised Access Floor Market