
 South America Ready Mix Concrete Market | 2026-2036
South America Ready Mix Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
South America Ready Mix Concrete Market Insights
A chronic shortage of certified concrete technicians is unwinding capacity expansion across the Andean region. Votorantim Cimento leverages its integrated quarry-to-delivery network to secure raw material continuity. Argos Group competes through specialized high-strength formulations for bridge and tunnel projects. Holcim anchors its position with digital batching systems that reduce waste and improve mix consistency.
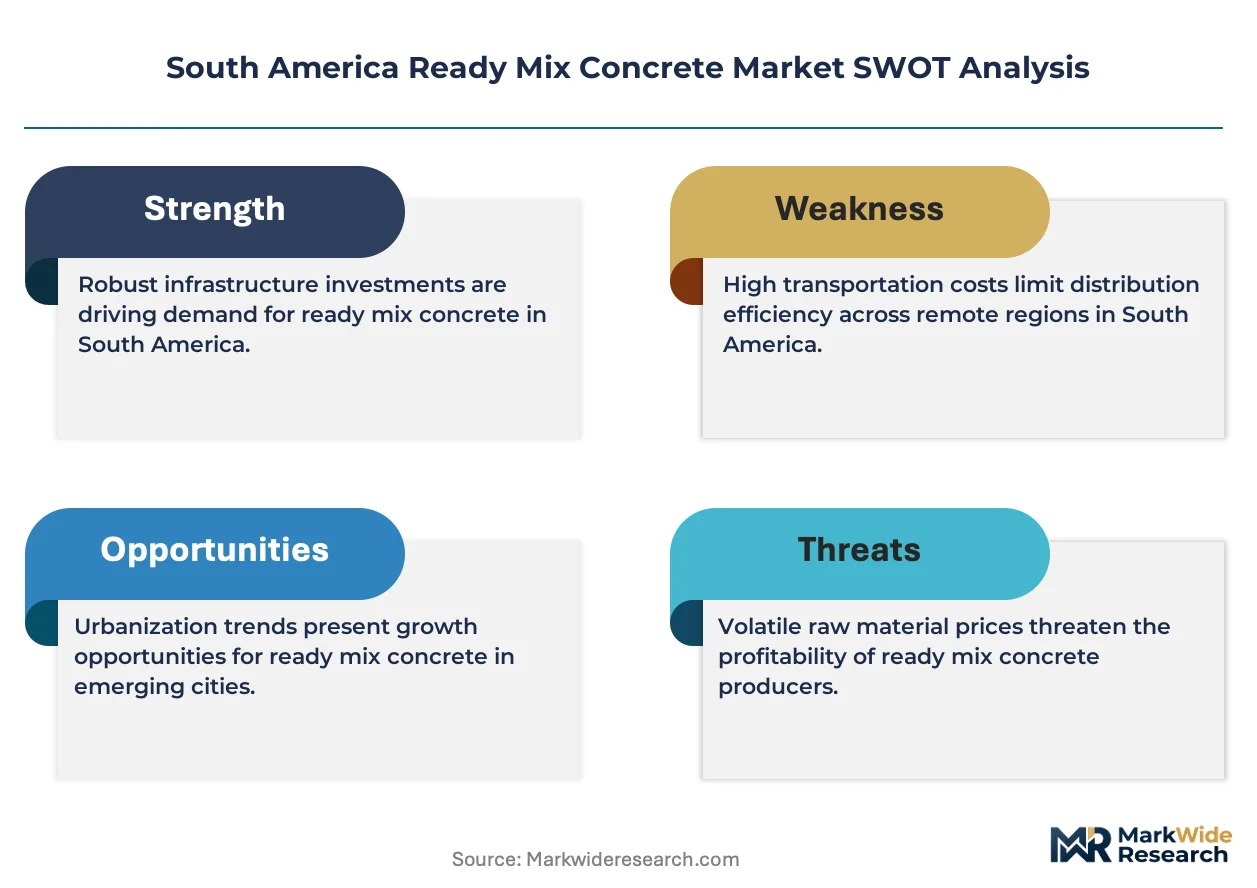
Ready mix concrete is a factory-blended composite of Portland cement, aggregates, water, and admixtures, produced under controlled conditions to achieve specified compressive strengths ranging from 20 MPa to over 60 MPa for engineered applications. It eliminates on-site batching variability and accelerates construction schedules for large-scale developments. Standard Ready Mix occupies the volume base across price-sensitive residential markets, while Eco-Friendly Mix captures premium positioning as green building certifications spread through São Paulo and Santiago. Infrastructure Projects channel the fastest throughput growth, driven by highway and hydropower investments.
Brazil's ABNT standards, Colombia's NSR-10 seismic codes, and Peru's SENCICO technical regulations collectively enforce strength grading and environmental compliance for ready mix suppliers. These frameworks raise entry barriers for informal producers while rewarding certified batch plants with public works eligibility. Stakeholders must track how evolving national carbon accounting rules affect cement content limits and admixture substitution economics.
Market Dynamics
Brazil's updated national building code and sustainability mandates are compressing specification windows for ready mix suppliers, forcing simultaneous compliance with seismic performance standards and carbon content ceilings while residential developers accelerate pour schedules.
Growth Catalysts
- Sustainability mandates:Brazil's revised ABNT standards require lower clinker-to-cement ratios, pushing admixture substitution and creating demand for supplementary cementitious materials in São Paulo's high-rise residential towers.
- Highway corridors:Colombia's 4G and 5G infrastructure programs channel continuous volume through specialized high-strength formulations for bridge decks and tunnel linings across the Andean trunk routes.
- Digital batching:Automated moisture sensing and real-time slump adjustment reduce waste and accelerate truck turnaround, tightening delivery windows for just-in-time pours at Minas Gerais mining facilities.
Market Restraints
- Clinker cost volatility:Energy price swings and petcoke import dependence compress margins for independent batch plants lacking captive kiln capacity in Peru's coastal zones.
- Quarry concentration:Quality aggregate deposits cluster in Brazil's southeastern corridor, forcing long-haul logistics costs onto projects in the arid northeast where local sources fail strength grading.
- Labor certification gaps:Peru's SENCICO technical regulations require certified technicians for public works eligibility, yet training pipeline capacity lags project awards by 18-24 months.
Strategic Opportunities
- Colombia's Pacific coast:Buenaventura port expansion and Pacifico 3 highway construction create unserved demand for marine-grade sulfate-resistant formulations in a market dominated by Bogotá-centric suppliers.
- Carbon accounting rules:Emerging national frameworks for embodied carbon in construction materials reward suppliers with verified Environmental Product Declarations, unlocking public procurement preference in Santiago and São Paulo.
- 3D printing convergence:Pumpable ultra-high-performance mixes compatible with robotic deposition systems open prefabrication channels for affordable housing modules in Argentina's Buenos Aires periphery.
Industry Challenges
- Technician scarcity:Chronic shortage of certified concrete technicians unwinds capacity expansion across Ecuador and Bolivia, forcing plant operators to limit shifts or absorb overtime premiums.
- Batch plant capex cycles:Mobile versus fixed plant investment decisions require precise demand forecasting as municipal permits for permanent installations face 12-18 month approval timelines in Brazilian secondary cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Ready Mix Concrete Market |
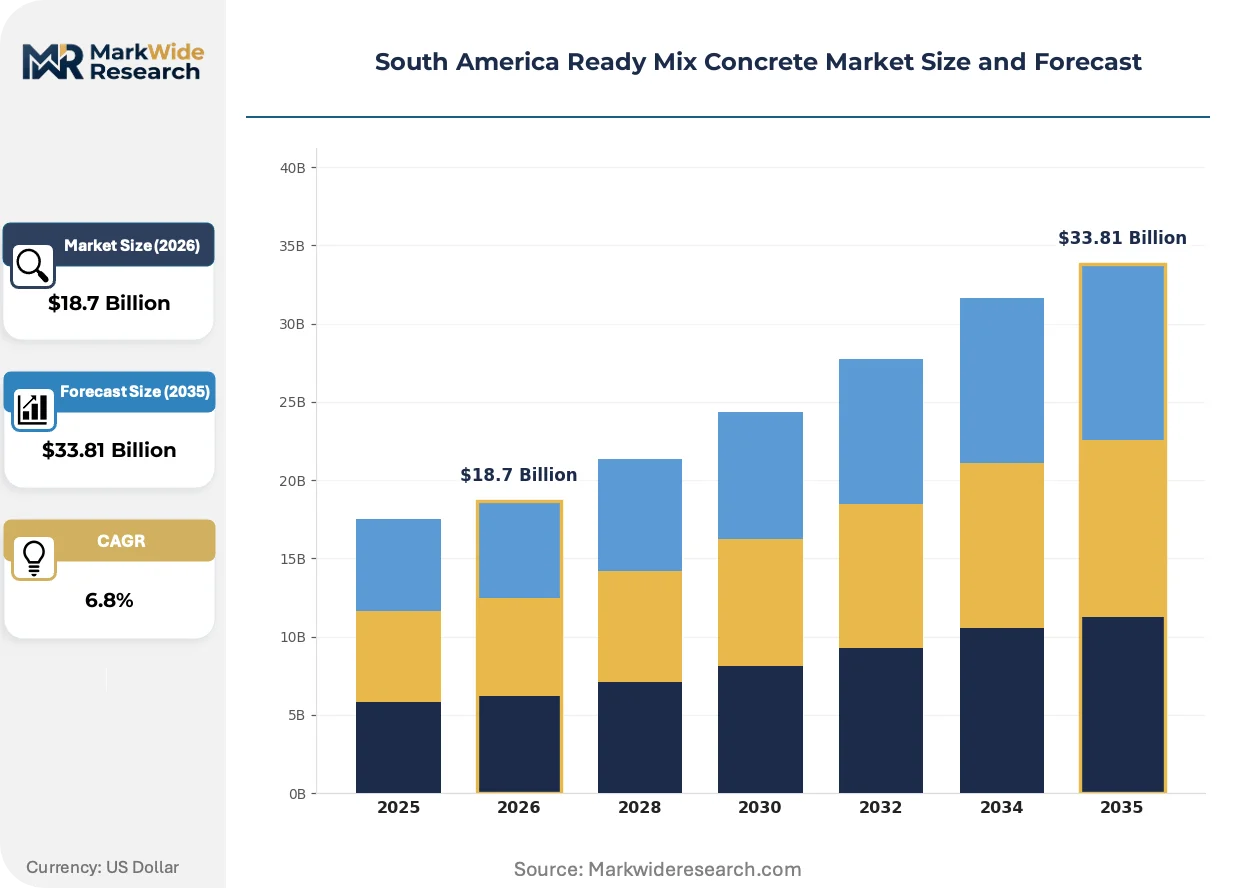
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Ready Mix, High-Strength Concrete, Eco-Friendly Mix, Pumpable Concrete Application: Residential Construction, Commercial Buildings, Infrastructure Projects, Industrial Facilities Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Construction Suppliers Customer Type: Contractors, Builders, Architects, Developers |
| Companies Covered | CEMEX S.A.B. de C.V., Votorantim Cimento, Argos Group, Holcim, UNACEM, Melón S.A., Polimix Concreto, Supermix, LenoBetão, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Ready Mix Concrete Market Trends and Innovations
Digital instrumentation and low-carbon formulation chemistry are compressing traditional supply relationships while opening premium positioning for certified sustainable products across South America's major metropolitan corridors.
Self-consolidating concrete with engineered viscosity-modifying admixtures is bifurcating the ready mix landscape. High-density residential developers in São Paulo's vertical construction boom specify these mixes for accelerated formwork stripping. The technology compresses skilled labor dependence while enabling thinner structural sections that reduce total material volume per floor plate.
ANVISA's environmental licensing requirements for industrial facilities are tightening effluent and dust emission thresholds for cement grinding and batch plant operations. Plants must install continuous particulate monitoring and closed-loop water recycling to maintain operating permits. This regulatory pressure falls heaviest on older wet-batch facilities in Rio de Janeiro's Baixada Fluminense industrial belt, accelerating capital replacement cycles.
Buyers are unbundling concrete supply from traditional general contractor packages and contracting directly with certified batch plants for major developments. Large residential developers in Santiago's Ñuñoa and Providencia districts now issue purchase orders tied to specific strength grades and delivery windows, bypassing intermediary markup. This disintermediation compresses price discovery transparency and rewards plants with real-time scheduling visibility through customer-facing logistics platforms.
South America Ready Mix Concrete Market Segmentation
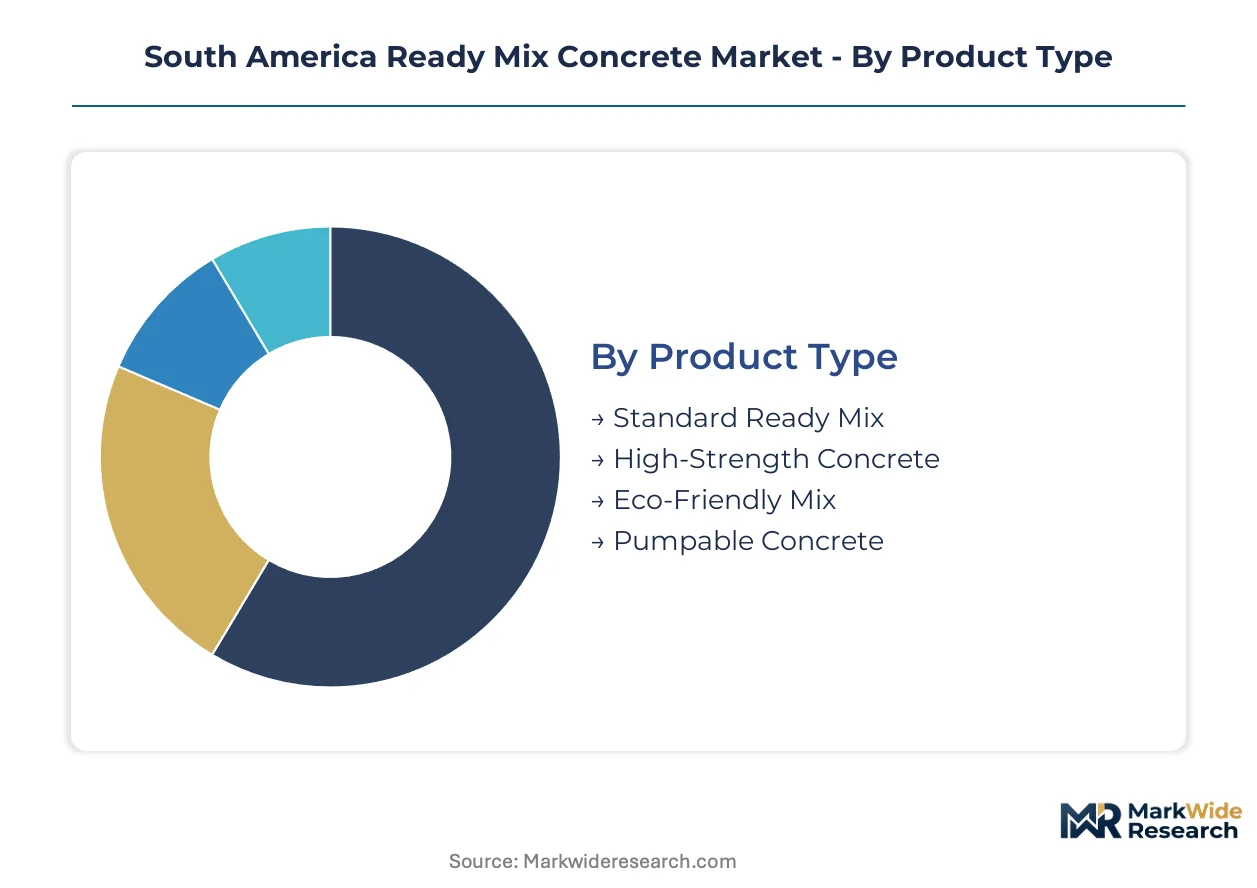
Ready mix concrete segmentation in South America reflects divergent technical specifications enforced by national building codes. Suppliers must align product portfolios with ABNT strength grading, NSR-10 seismic performance tiers, and emerging carbon accounting thresholds.
Product Type:
ANVISA environmental licensing and Brazil's revised ABNT standards create tiered compliance burdens that separate commodity producers from certified sustainable suppliers.
- Standard Ready Mix:Factory-blended composite of Portland cement, aggregates, and water achieving 20-40 MPa compressive strength for slabs, foundations, and non-structural elements. Demand concentrates in Brazil's northeastern residential developments where cost sensitivity dominates specification decisions and long-haul logistics from southeastern quarries inflate delivered prices.
- Eco-Friendly Mix:Incorporates supplementary cementitious materials and lower clinker-to-cement ratios to meet green building certification requirements. Santiago's Ñuñoa district and São Paulo's vertical construction boom drive premium positioning as developers pursue carbon reduction targets for public procurement eligibility.
- High-Strength Concrete:Engineered for 50-60+ MPa applications in high-rise cores and heavy industrial foundations.
- Pumpable Concrete:Viscosity-modified admixtures enable vertical placement without segregation in dense urban sites.
Established volume favors Standard Ready Mix; emerging adoption favors Eco-Friendly Mix.
Application:
Project scale and public works eligibility criteria determine batch plant certification requirements across customer segments.
- Infrastructure Projects:Highway corridors, hydropower installations, and bridge decks require specialized high-strength formulations with documented quality assurance. Colombia's 4G and 5G programs channel continuous volume through certified suppliers capable of meeting continuous pour schedules across Andean trunk routes where seismic performance standards apply.
- Residential Construction:Single-family housing and mid-rise apartments specify standard grades with accelerated delivery windows. Brazil's southeastern corridor—São Paulo, Rio de Janeiro, Minas Gerais—generates concentrated demand as developers compress construction schedules and eliminate on-site batching variability.
- Commercial Buildings:Office towers and retail centers specify self-consolidating mixes for complex formwork geometries.
- Industrial Facilities:Mining operations in Minas Gerais and manufacturing plants require abrasion-resistant and chemical-resistant formulations.
Public procurement eligibility favors Infrastructure Projects; private development velocity favors Residential Construction.
Distribution Channel:
Customer scale and scheduling precision requirements fragment procurement pathways across the value chain.
- Direct Sales:Large residential developers in Santiago's Providencia district and São Paulo's corporate construction sector contract directly with certified batch plants. Real-time logistics platforms enable just-in-time pour coordination that bypasses intermediary markup and compresses price discovery transparency.
- Construction Suppliers:Regional material yards aggregate small-project demand across secondary Brazilian cities and Andean municipalities. Permit timelines for permanent batch installations—12-18 months in Brazilian secondary cities—force reliance on mobile plants channeled through established supply relationships.
- Wholesale Distributors:Volume aggregation for mid-tier contractors without direct plant relationships.
- Online Retail:Emerging platform-based ordering for standardized grades with predictable delivery windows.
Scale economies favor Direct Sales; geographic coverage favors Construction Suppliers.
Customer Type:
Technical sophistication and certification requirements stratify buyer relationships with batch plant operators.
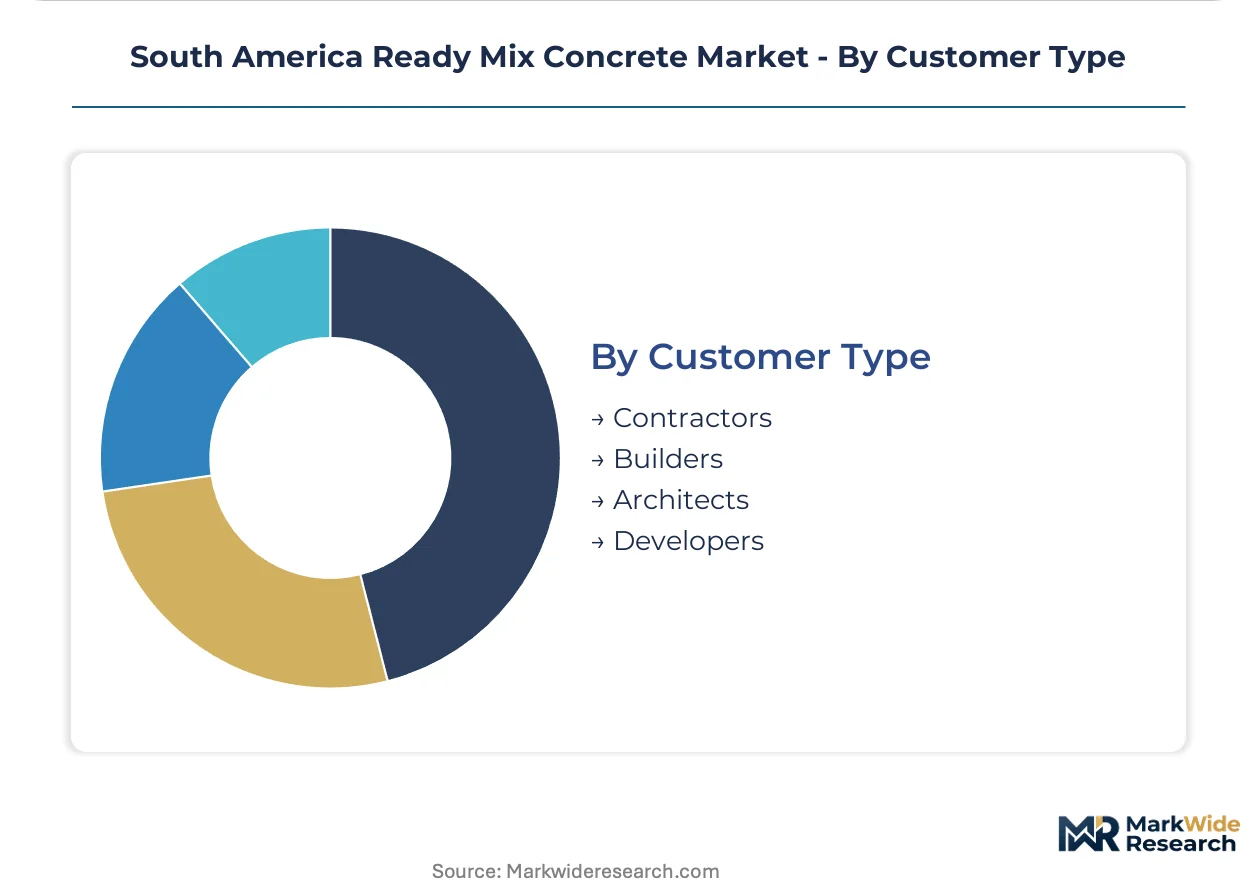
- Developers:Large integrated firms unbundle concrete procurement from general contractor packages and issue purchase orders tied to specific strength grades, slump specifications, and delivery windows. Buenos Aires periphery affordable housing modules and Santiago high-rise towers demand verified Environmental Product Declarations for carbon accounting compliance.
- Contractors:Project-based firms require flexible scheduling and volume scalability across multiple simultaneous sites. Peru's SENCICO regulations restrict public works eligibility to certified technicians, forcing contractor reliance on plants with documented training pipelines that lag project awards by 18-24 months.
- Builders:Small-scale operators prioritize price and availability over technical specification depth.
- Architects:Design-phase influence over aesthetic and structural concrete selections.
Procurement control favors Developers; scheduling flexibility favors Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's environmental licensing requirements and Brazil's revised ABNT standards anchor the continent's regulatory framework, while national building codes across the Andean corridor enforce divergent compliance burdens for ready mix suppliers.
Brazil
São Paulo's vertical construction boom and Rio de Janeiro's residential rehabilitation generate concentrated demand for self-consolidating mixes. ABNT strength grading and lower clinker-to-cement ratio mandates compress specification windows for suppliers. The southeastern corridor—spanning Minas Gerais mining facilities—channels premium volumes through digital batching systems.
Colombia
Bogotá-centric suppliers face displacement as Buenaventura port expansion and Pacifico 3 highway construction create unserved demand for marine-grade formulations. The 4G and 5G infrastructure programs enforce continuous pour schedules across Andean trunk routes where NSR-10 seismic codes apply. Bridge decks and tunnel linings in the Antioquia region absorb specialized high-strength output.
Peru
Lima's coastal construction and northern mining operations drive specification diversity from standard grades to abrasion-resistant formulations. SENCICO technical regulations restrict public works eligibility to certified technicians, yet training pipeline capacity lags project awards by 18-24 months. The coastal zones suffer margin compression from petcoke import dependence and energy price volatility.
Chile
Santiago's Ñuñoa and Providencia districts unbundle concrete procurement from general contractor packages, with developers issuing direct purchase orders tied to carbon reduction targets. Emerging national frameworks for embodied carbon reward suppliers with verified Environmental Product Declarations. The metropolitan corridor concentrates premium positioning for eco-friendly mixes.
Argentina
Buenos Aires periphery affordable housing modules and Patagonian infrastructure gaps create bifurcated demand patterns. Pumpable ultra-high-performance mixes compatible with robotic deposition systems open prefabrication channels for modular construction. Local batch plant operators struggle with clinker cost volatility absent captive kiln capacity.
South America Ready Mix Concrete Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with quarry-to-delivery networks determining raw material continuity across geographically dispersed markets. The structure rewards backward integration into captive aggregate deposits while penalizing independent batch plants lacking kiln capacity. Three archetypes dominate: integrated cement producers with owned distribution, regional specialists in high-strength formulations, and technology-forward operators deploying digital batching systems. Competitive moves concentrate on M&A to secure quarry access and strategic partnerships to extend logistics reach into underserved corridors.
Within the integrated producer tier, CEMEX S.A.B. de C.V. and Votorantim Cimento exemplify scale-driven positioning through quarry ownership and vertical distribution control. Argos Group occupies a specialist position, representing the high-strength formulation archetype for engineered infrastructure applications. Holcim anchors the technology-forward vector, with its S.A. de C.V. structure signaling Mexican-origin integration into broader regional networks.
| Leading Market Players |
|---|
| CEMEX S.A.B. de C.V. |
| Votorantim Cimento |
| Argos Group |
| Holcim |
| UNACEM |
| Melón S.A. |
| Polimix Concreto |
| Supermix |
| LenoBetão |
| Others |
Pricing and Supply Chain Analysis
Forty-eight to seventy-two hour batch-to-pour lead times concentrate pricing power with quarry-integrated producers in Brazil's southeastern corridor, while long-haul logistics inflate delivered costs for northeastern projects beyond São Paulo's supply radius. This temporal compression rewards plants with captive aggregate deposits and real-time scheduling platforms, squeezing independent operators dependent on spot-market clinker.
Pricing Analysis
Delivered price spreads of 15-25% separate Brazil's southeastern quarry belt from Peru's coastal zones and Argentina's Buenos Aires periphery, with contract-based long-term offtake dominating infrastructure procurement. Price differentiation rests on certification grade—ANVISA environmental licensing and ABNT carbon thresholds—and volume scale, with large developers extracting schedule premiums through direct plant relationships. Cost compression in standard-grade residential supply intensifies as petcoke import dependence and energy volatility squeeze coastal independent plants. Small-scale builders exhibit highest price sensitivity, while infrastructure contractors with public procurement eligibility absorb premium formulations for seismic performance compliance.
Supply Chain Analysis
Just-in-time pour coordination through customer-facing logistics platforms is displacing strategic stockpiles across São Paulo's vertical construction boom, compressing inventory buffers to 4-6 hours of truck-cycle coverage. Geographic supply concentrates in Brazil, Colombia, and Peru, with quality aggregate deposits clustering in Brazil's Minas Gerais corridor and Colombia's Antioquia region. Raw material dependencies center on Portland cement clinker, limestone aggregates, and viscosity-modifying admixtures. Single-source vulnerability runs through petcoke supply for coastal kilns lacking captive energy assets. Distribution feeds from integrated quarry-to-delivery networks into direct developer contracts and construction supplier intermediaries for secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America ready mix concrete market sits in early-cycle expansion as Colombia's Pacific coast infrastructure and Argentina's modular housing adoption create penetration headroom absent from mature southeastern Brazilian corridors.
For Market Incumbents: Compound quarry access advantages through targeted capacity additions in Colombia's Buenaventura corridor and Peru's northern mining zones, where SENCICO certification gaps delay competitor entry. Deepen backward integration into supplementary cementitious materials to meet ABNT clinker-ratio mandates while defending margin position against admixture substitution economics. Prioritize digital batching deployments that compress truck turnaround and lock in just-in-time relationships with large developers unbundling procurement from general contractors. For New Entrants and Emerging Players: Anchor in Colombia's Pacific coast marine-grade sulfate-resistant segment, where Bogotá-centric incumbents face logistics disadvantages for port and highway projects. Target Peru's certified technician training pipeline bottlenecks by partnering with SENCICO-accredited institutes to accelerate public works eligibility. Pursue direct sales platforms with real-time scheduling visibility as the primary go-to-market angle, bypassing construction supplier markups in Santiago's Ñuñoa and Providencia districts. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because quarry-to-delivery network density determines raw material continuity across geographically dispersed Andean markets. Acquisition candidates include regional specialists with captive aggregate deposits in Brazil's northeastern expansion zones and technology-forward operators with verified Environmental Product Declarations for Santiago carbon accounting. Monitor Colombia's 5G infrastructure award velocity as the signal indicating premium formulation demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Quarries | Secures aggregate continuity for plants in Brazil's northeastern corridor beyond Minas Gerais supply radius. |
| Environmental Product Declaration Certification | Unlocks public procurement preference in Santiago and São Paulo under emerging embodied carbon frameworks. |
| Digital Batching System Deployment | Reduces waste and accelerates truck turnaround for just-in-time pours at Minas Gerais mining facilities. |
| SENCICO Technician Training Partnership | Accelerates public works eligibility for contractors facing 18-24 month certification pipeline lags in Peru. |
| Marine-Grade Formulation Development | Captures unserved demand from Buenaventura port expansion and Pacifico 3 highway construction in Colombia. |
Research Methodology
Initial hypotheses were tested against primary input from batch plant operators, residential development procurement directors, infrastructure project engineers, and ANVISA regulatory compliance officers, then refined through secondary validation. Sources included ABNT technical standards filings, ANVISA environmental licensing records, SENCICO technician certification databases, and customs data on petcoke and clinker imports. Bottom-up volume estimates from individual plant capacity and utilization rates were triangulated with top-down construction sector expenditure flows.
Variance decomposition across product type, application segment, distribution channel, and customer sophistication tier structured the analytical framework over the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating national building code evolution, carbon accounting rule adoption trajectories, and infrastructure program award pipelines. Forecast inputs centered on Colombia's 4G and 5G highway commitments and Brazil's ABNT clinker-ratio compliance timelines.
Decision-makers should treat outputs as directional under assumptions of sustained infrastructure program execution and stable energy input costs; material deviation would warrant model refresh. Revision becomes warranted when SENCICO certification pipeline capacity materially closes technician gaps or when Pacific coast logistics infrastructure accelerates competitor entry into Colombia's marine-grade segment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Central & South America Iron Casting Market
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
Global Raised Access Floor Systems Market
Building & Construction Materials
Modular Commercial Building System Market
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
Prefabricated Bathroom Modules Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
Cleanroom Flooring Market
Building & Construction Materials
US Geosynthetics Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
Composite Roof Shingle Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
Softwood Lumber Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Global Aluminum Cladding Panels Market
Building & Construction Materials
Drywall and Gypsum Board Market