
 Canada HVAC Equipment Market | 2026-2036
Canada HVAC Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Canada HVAC Equipment Market Outlook
A shift from single-source to multi-source component procurement is rebalancing supply relationships across the Canada HVAC Equipment Market. Rheem leverages its distribution network to sustain presence in residential retrofits across Ontario and Quebec. Carrier anchors its position through technology leadership in variable refrigerant flow systems for commercial installations. Daikin differentiates via ductless system specialization targeting high-density urban projects in Vancouver and Toronto.
Canada HVAC equipment encompasses heating, ventilation, and air conditioning systems engineered to maintain indoor thermal comfort and air quality across residential, commercial, and industrial environments, with units typically rated by seasonal energy efficiency ratio and annual fuel utilization efficiency metrics. The primary purpose centers on climate control, humidity management, and ventilation compliance within buildings subject to Canadian energy codes. Heat pumps represent the fastest-expanding product category as electrification mandates intensify, while furnaces retain volume dominance in legacy residential stock across prairie provinces. Commercial installation types command premium margin pools due to complex zoning requirements and extended service contracts, whereas residential retrofit activity generates consistent replacement demand from aging infrastructure in established urban centers.
Health Canada and Natural Resources Canada enforce energy efficiency standards that directly shape product eligibility for federal incentive programs, while provincial regulators in Ontario and British Columbia layer additional building code requirements that filter equipment specifications. The Canadian Standards Association certifies electrical and gas-fired HVAC components, creating a compliance gateway that manufacturers must clear before market entry. Stakeholders must monitor evolving federal clean technology investment tax credits and provincial carbon pricing mechanisms that will redirect procurement decisions toward electrified heating solutions.
Market Dynamics
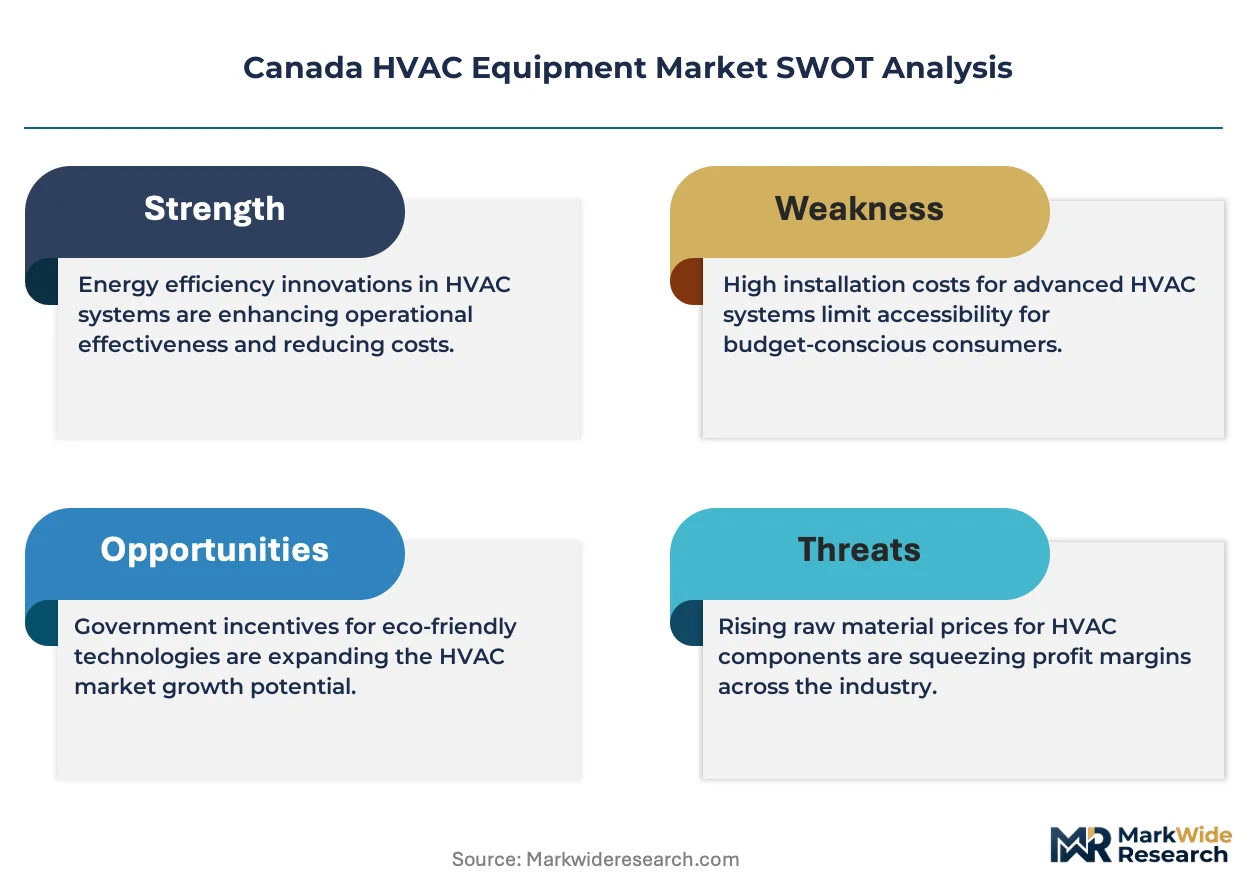
Electrification mandates from Natural Resources Canada are compressing the replacement cycle for gas-fired furnaces while redirecting capital toward heat pump manufacturing capacity and cold-climate certification programs.
Growth Catalysts
- Clean Technology Investment Tax Credit:Federal incentives covering up to thirty percent of eligible heat pump installation costs are accelerating residential retrofit decisions across Ontario and British Columbia.
- Multi-unit residential construction:High-rise development in the Greater Toronto Area and Vancouver corridor is generating concentrated demand for centralized VRF systems and energy recovery ventilators.
- Natural Resources Canada efficiency tiers:Tightening minimum performance standards for seasonal energy efficiency ratio ratings are filtering lower-efficiency equipment from federal procurement channels.
Market Restraints
- Copper and aluminum input volatility:Raw material price swings for heat exchanger components are compressing margin predictability for equipment manufacturers serving the prairie provinces.
- Refrigerant supply concentration:Dependence on imported HFC blends subject to Environment and Climate Change Canada phase-down schedules creates formulation transition risk for domestic assembly operations.
- Cold-climate performance limitations:Air-source heat pumps face efficiency degradation below minus twenty-five degrees Celsius, constraining penetration in northern Quebec and Manitoba markets.
Strategic Opportunities
- Indigenous community housing programs:Federal infrastructure commitments to remote and northern settlements are opening dedicated procurement channels for modular HVAC systems with off-grid power compatibility.
- Building automation convergence:Integration of IoT-enabled diagnostics with heat pump controls is creating subscription revenue streams for contractors serving the commercial sector.
- Provincial carbon pricing mechanisms:British Columbia's cleanBC incentives and Quebec's carbon levy are tilting lifecycle cost calculations toward electrified heating in multi-family retrofits.
Industry Challenges
- Red Seal refrigeration technician scarcity:Certification bottlenecks for heat pump installation specialists are extending project timelines in Atlantic Canada and rural Ontario.
- Canadian Standards Association testing backlog:Extended approval queues for novel cold-climate heat pump designs are delaying product launches by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada HVAC Equipment Market |
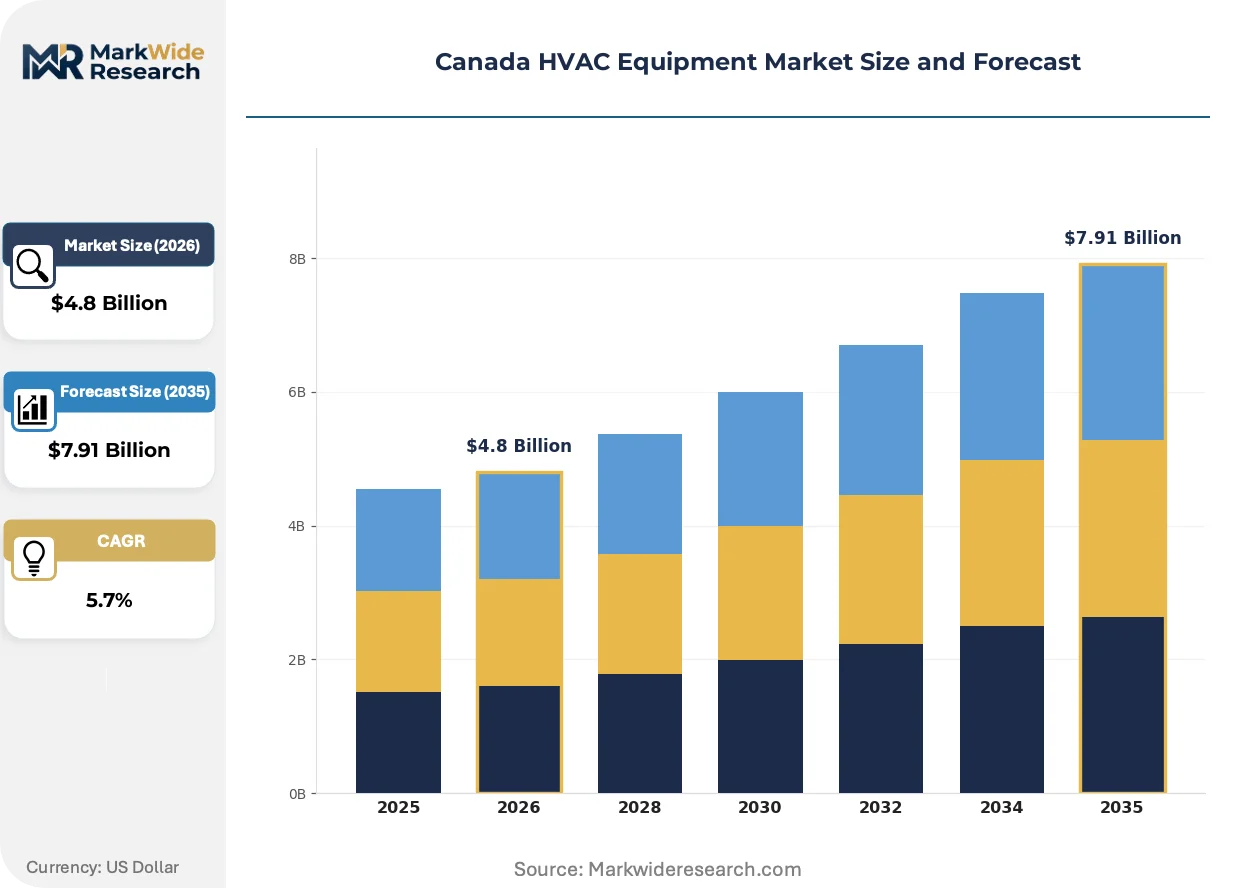
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furnaces, Air Conditioners, Heat Pumps, Ductless Systems Installation Type: Residential, Commercial, Industrial, Retrofit End User: Homeowners, Building Contractors, Facility Managers, Property Developers Service Type: Maintenance, Repair, Replacement, Consultation |
| Companies Covered | Rheem, ICP, Carrier, Johnson Controls, Nortek, Lennox Industries Canada Ltd., Goodman Company Canada, Daikin, Trane and American Standard Heating and Air Conditioning, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada HVAC Equipment Market Strategic Shifts
Equipment intelligence and refrigerant chemistry are converging to redefine performance benchmarking, while procurement relationships between manufacturers and mechanical contractors are restructuring around energy outcome guarantees rather than unit sales.
Variable-capacity compressor technology is absorbing market share from fixed-speed equivalents by modulating output to match thermal load rather than cycling on-off. Multi-unit residential developers in Vancouver and Toronto are specifying these systems to meet stringent energy step code requirements. The technology is absorbing margin pressure from escalating electricity rates by delivering measurable utility savings that justify premium first costs.
Natural Resources Canada's forthcoming amendments to minimum energy performance standards will prohibit non-condensing gas furnace sales by 2028. Equipment distributors are clearing legacy inventory ahead of compliance deadlines while accelerating training programs for heat pump transition. The regulatory compression is most acute in Ontario's residential replacement market, where contractors are bundling electrical panel upgrades with system installations.
Mechanical contractors are consolidating purchasing power through buying groups to negotiate direct manufacturer relationships, bypassing traditional wholesale distributors. Large multi-residential developers in the Greater Toronto Area are centralizing HVAC procurement at the portfolio level rather than project-by-project. The concentration is most visible in Vancouver's tower construction segment, where national property managers are standardizing on single-source VRF platforms across their entire Canadian holdings.
Canada HVAC Equipment Market Segmentation
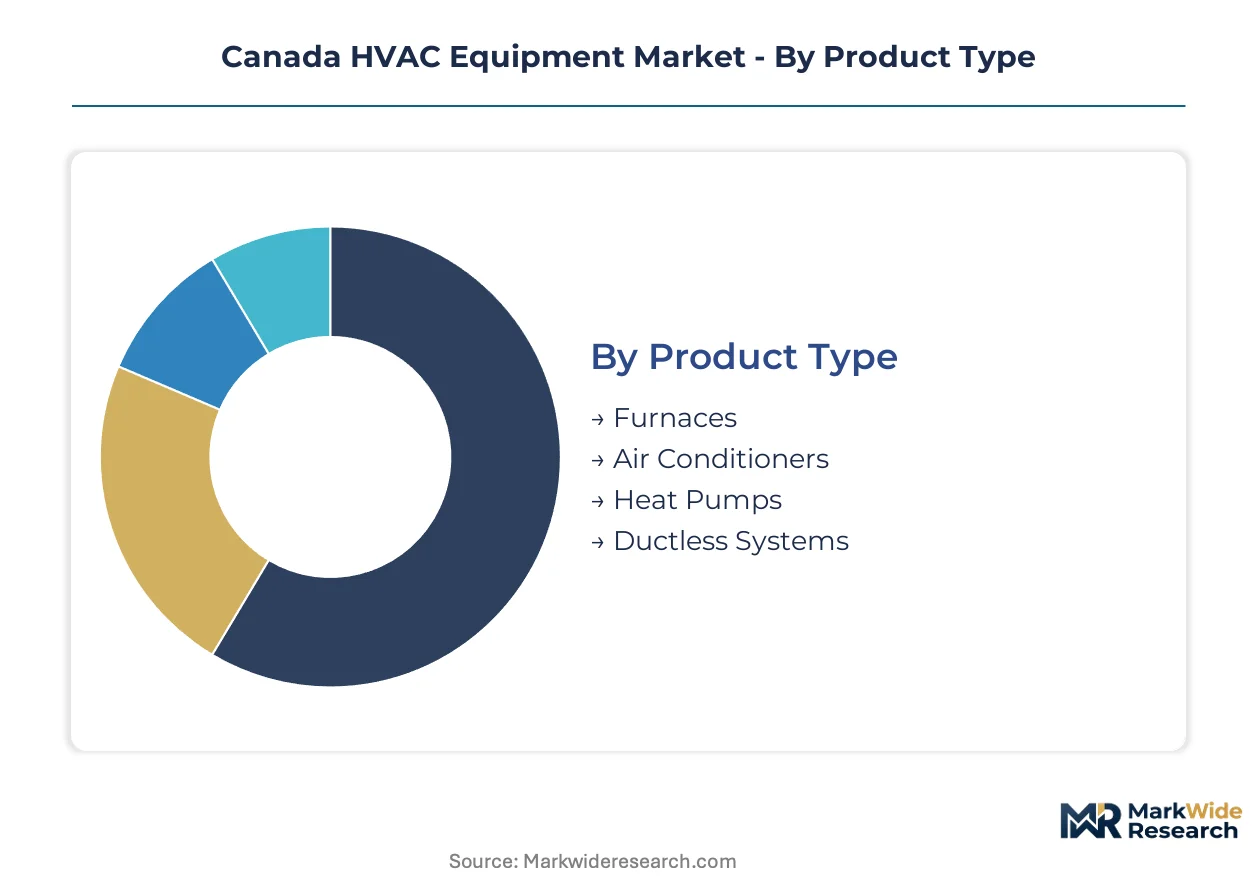
Segmentation across the Canada HVAC Equipment Market reveals how electrification mandates, construction cycles, and service intensity concentrate value in distinct pockets. Understanding these divisions exposes where procurement budgets flow and where regulatory pressure reshapes equipment specifications fastest.
Product Type:
Technology differentiation determines efficiency compliance thresholds and cold-climate suitability across Canadian provinces.
- Heat Pumps:Electrified systems using vapor-compression refrigeration cycles for both heating and cooling. Demand concentrates in British Columbia and Quebec where provincial carbon pricing and clean technology tax credits compress payback periods for residential retrofits. Cold-climate certification programs from Natural Resources Canada are expanding operational ranges below minus twenty-five degrees Celsius.
- Furnaces:Gas-fired forced-air heating units rated by annual fuel utilization efficiency metrics. Legacy installations dominate prairie provinces where natural gas infrastructure remains dense and electricity rates exceed national averages. Replacement cycles are compressing ahead of federal prohibitions on non-condensing models.
- Air Conditioners:Centralized cooling systems paired with forced-air distribution networks. Peak demand aligns with Ontario and Quebec summer humidity loads in suburban single-family stock.
- Ductless Systems:Mini-split and multi-split configurations eliminating ductwork losses. Vancouver and Toronto high-density multi-unit residential projects specify these for energy step code compliance.
Furnaces lead on scale; heat pumps lead on momentum.
Installation Type:
Project scale and margin structure diverge sharply between greenfield construction and existing building intervention.
- Commercial:Centralized systems serving office, retail, and institutional footprints with complex zoning requirements. Extended service contracts and building automation integration generate recurring revenue streams for mechanical contractors in the Greater Toronto Area.
- Residential:Single-family and multi-unit equipment deployment governed by provincial building codes and federal incentive eligibility. Retrofit activity dominates volume as aging infrastructure across established urban centers drives replacement demand.
- Industrial:Process cooling and ventilation systems for manufacturing and resource extraction facilities. Specifications prioritize reliability over efficiency metrics in remote northern operations.
- Retrofit:Equipment replacement within existing building envelopes requiring electrical panel upgrades and distribution modifications. Ontario contractors bundle these services to capture federal clean technology investment tax credits.
Residential commands volume concentration; commercial captures margin premium.
End User:
Purchasing authority and technical sophistication shape how equipment specifications flow from decision-makers to installed systems.
- Property Developers:Multi-unit residential and mixed-use project sponsors standardizing HVAC platforms across portfolios. National managers in Vancouver's tower construction segment centralize procurement at portfolio level rather than project-by-project.
- Building Contractors:Mechanical and general contractors executing installation with equipment sourced through distributor or direct manufacturer relationships. Buying group consolidation is shifting bargaining power toward larger regional players.
- Facility Managers:Commercial and institutional building operators prioritizing lifecycle cost and predictive maintenance capabilities. IoT-enabled diagnostics integration is becoming a procurement criterion.
- Homeowners:Individual residential purchasers responding to equipment failure or energy cost pressure. Federal incentive awareness and contractor recommendations drive technology selection.
Property developers concentrate procurement volume; facility managers concentrate service contract value.
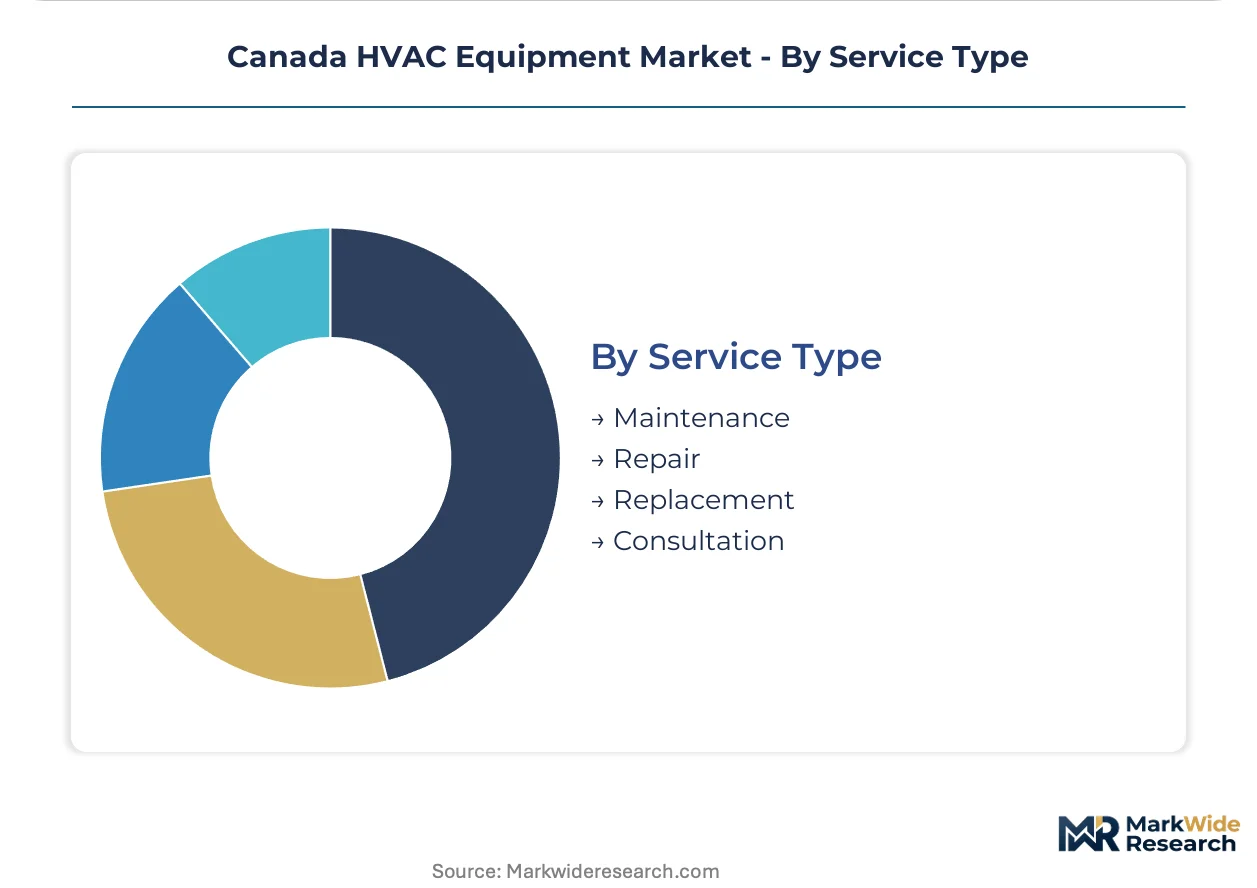
Service Type:
Revenue recurrence and labor intensity separate transactional equipment moves from ongoing maintenance relationships.
- Replacement:Full system swap-outs triggered by equipment failure or efficiency regulation compliance deadlines. Ontario and Quebec markets show accelerated activity ahead of federal minimum energy performance standard amendments.
- Maintenance:Scheduled inspection, filter replacement, and performance verification preserving warranty coverage and efficiency ratings. Red Seal refrigeration technician scarcity is extending service intervals in Atlantic Canada.
- Repair:Component-level intervention addressing refrigerant leaks, compressor failure, or control system malfunction. Parts availability constraints for legacy refrigerant formulations are elevating replacement versus repair economics.
- Consultation:Energy audit, load calculation, and system design services preceding equipment specification. Demand is rising where electrification transitions require electrical infrastructure assessment.
Replacement dominates revenue scale; consultation is climbing fastest as electrification complexity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Toronto Area concentrates the highest procurement intensity for commercial VRF installations and multi-unit residential heat pump deployments.
Ontario
Multi-unit residential construction in Toronto and Ottawa is driving centralized system specifications. Natural Resources Canada efficiency tier upgrades are filtering non-compliant equipment from federal procurement channels. The Golden Horseshoe corridor anchors replacement demand from aging suburban housing stock.
Quebec
Provincial carbon pricing and hydroelectric rate advantages are compressing heat pump payback periods in Montreal and Quebec City. The province's building code amendments mandate electrification readiness in new construction. Cold-climate certification programs are expanding operational ranges for air-source systems in Sherbrooke and Trois-Rivières.
British Columbia
Vancouver's energy step code is mandating high-performance HVAC in tower construction. CleanBC incentives layer with federal clean technology investment tax credits to accelerate residential retrofits. The Lower Mainland dominates ductless system specifications for high-density urban projects.
Alberta
Natural gas price volatility is shifting lifecycle cost calculations toward hybrid heating systems in Calgary and Edmonton. Commercial office retrofits are prioritizing building automation integration. The province's industrial corridor maintains process cooling demand from resource extraction facilities.
Prairie Provinces
Legacy furnace installations dominate replacement cycles in Manitoba and Saskatchewan. Cold-climate performance limitations constrain air-source heat pump penetration below minus twenty-five degrees Celsius. Federal Indigenous community housing programs are opening procurement channels for modular off-grid systems in remote northern settlements.
Canada HVAC Equipment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue cold-climate specialization and IoT-enabled service models. The vendor base clusters around three strategic archetypes: integrated manufacturers with captive distribution, component specialists leveraging buying group consolidation, and technology licensors partnering with regional assemblers. Dominant competitive moves include vertical integration into installation services and strategic partnerships with multi-residential developers for portfolio-level standardization.
Among North American integrated manufacturers, Carrier and Rheem exemplify scale-driven archetypes with established distribution networks across Ontario and Quebec. Daikin occupies a position within the technology-specialist tier, representing Japanese engineering presence in ductless and VRF system categories. These three anchors illustrate how geographic coverage, product breadth, and regulatory compliance capabilities stratify competitive positioning in a market shaped by federal efficiency mandates and provincial carbon pricing mechanisms.
| Leading Market Players |
|---|
| Rheem |
| ICP |
| Carrier |
| Johnson Controls |
| Nortek |
| Lennox Industries Canada Ltd. |
| Goodman Company Canada |
| Daikin |
| Trane and American Standard Heating and Air Conditioning |
| Others |
Value Chain & Pricing Dynamics
Natural Resources Canada's cold-climate certification requirements gate qualified supply and premium-tier pricing access for heat pump manufacturers targeting northern provinces. Equipment lacking this designation faces exclusion from federal procurement channels and provincial incentive programs, compressing margins for non-compliant producers while elevating price floors for certified alternatives.
Pricing Analysis
Input-cost pass-through from copper and aluminum volatility is reshaping margin structures across equipment tiers. Three-tier pricing structure across premium, standard, and economy levels reflects cold-climate certification status and Natural Resources Canada efficiency tier compliance. Cost compression in the economy tier is intensifying because raw material swings hit undifferentiated producers hardest. Residential retrofit contractors show highest price sensitivity, while multi-unit residential developers prioritize lifecycle cost certainty over first cost.
Supply Chain Analysis
Workforce availability constraints in Ontario and Quebec manufacturing geographies are extending lead times for heat pump assembly operations. Supply concentrates in the United States, Mexico, and China for compressor components, heat exchangers, and control systems. Domestic assembly draws from imported HFC refrigerant blends and copper tubing subject to commodity price volatility. Single-source vulnerability around cold-climate compressor technology creates bottleneck risk. Distribution runs through wholesale distributors and direct manufacturer relationships with buying group consolidation shifting power toward larger mechanical contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada HVAC Equipment Market represents a late-cycle quality story as electrification mandates shift procurement toward cold-climate certified, high-efficiency specifications that command sustained premium positioning.
For Market Incumbents: Anticipate regulatory compression by accelerating cold-climate certification investment ahead of Natural Resources Canada's 2028 non-condensing furnace prohibition. Backward integration into heat pump compressor sourcing mitigates single-source vulnerability from Asian suppliers. Channel control through captive distribution networks in Ontario and Quebec defends against buying group consolidation. R&D priority centers on minus thirty degrees Celsius operational ranges to extend addressable market into Manitoba and northern Quebec. For New Entrants and Emerging Players: Enter via Indigenous community housing programs where federal infrastructure commitments create dedicated procurement channels with reduced incumbent presence. Remote northern settlements in the Prairie Provinces present the most penetrable geography given cold-climate performance limitations of existing air-source systems. Modular off-grid HVAC with solar compatibility addresses unmet need. Go-to-market angle emphasizes off-grid power integration and simplified installation protocols for communities lacking Red Seal technician density. For Investors and Strategic Acquirers: Roll-up economics work for regional mechanical contractors with Red Seal certification capabilities because technician scarcity creates defensive moats and recurring service revenue visibility. The five-to-ten year viability window favors platform consolidation in Ontario's Golden Horseshoe corridor where replacement cycle acceleration concentrates demand. Target acquisition archetype: mid-cap contractors with established multi-residential developer relationships and heat pump installation track records. Signal to watch: Canadian Standards Association testing queue lengths as inflection indicator for product launch velocity and competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Climate Certification Investment | Natural Resources Canada tier compliance unlocks federal procurement channels and provincial incentive eligibility. |
| Backward Integration into Compressor Sourcing | Captive supply of critical components mitigates single-source concentration risk from Asian manufacturers. |
| Buying Group Consolidation Participation | Aggregated purchasing power shifts bargaining position toward direct manufacturer relationships in Ontario. |
| Indigenous Community Housing Program Alignment | Federal infrastructure commitments open dedicated procurement channels for modular off-grid systems. |
| IoT-Enabled Diagnostics Integration | Building automation convergence creates subscription revenue streams for commercial sector contractors. |
Study Parameters
Coverage spans Ontario, Quebec, British Columbia, Alberta, and the Prairie Provinces, with primary inputs from each regional cluster. The approach combines primary interviews with mechanical contractors, equipment distributors, multi-unit residential developers, facility managers, and Red Seal refrigeration technicians alongside secondary validation. Secondary sources include Natural Resources Canada efficiency tier databases, Canadian Standards Association certification records, provincial building code amendments, and federal clean technology incentive program documentation. Bottom-up equipment shipment analysis triangulates with top-down construction permit and retrofit activity estimates.
Granularity-level framing applies province-level modeling for heat pump, furnace, and ductless system categories, with installation type disaggregation across new construction, replacement, and retrofit channels. End-user segmentation captures property developer, contractor, facility manager, and homeowner purchasing authority patterns. CAGRs derive from equipment lifecycle assumptions, regulatory compliance deadline impacts, and electrification mandate penetration curves. Industry-specific forecast inputs include cold-climate certification adoption rates and Red Seal technician graduation pipeline data across the analysis window.
Inputs from Natural Resources Canada, provincial energy regulators, and industry associations were available through the study window; gaps in real-time distributor inventory positioning introduce uncertainty bands around quarterly shipment estimates. Forecasts reflect assumptions regarding regulatory timeline adherence, copper price trajectory stability, and Indigenous housing program execution pace. Material deviation in named triggers—accelerated refrigerant phase-down schedules, dramatic technician training program expansion, or abrupt carbon pricing mechanism revision—warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Scrubber Dryer Market
HVAC Equipment
Blowers Market
HVAC Equipment
Japan HVAC Market
HVAC Equipment
Centrifugal Fan Wheels Market
HVAC Equipment
Compressor Controllers Market
HVAC Equipment
Variable Refrigerant Flow (VRF) System Market
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
Heating Radiator Market
HVAC Equipment
HVAC Chillers Market
HVAC Equipment
Europe HVAC Market
HVAC Equipment
Foamer Pump Market
HVAC Equipment
Europe Dehumidifier Market
HVAC Equipment
Water Chiller Market
HVAC Equipment
Japan Commercial HVAC Market
HVAC Equipment
Hybrid Air Conditioner Market
HVAC Equipment
Automatic Ducting Machine Market