
 North America Laminated Veneer Lumber Market | 2026-2036
North America Laminated Veneer Lumber Market Size, Share, and Industry Trends Forecast 2026-2036
North America Laminated Veneer Lumber Market Intelligence
The International Building Code is repositioning engineered wood products as mainstream structural alternatives across North American jurisdictions. Boise Cascade leverages captive timberlands and integrated veneer mills to sustain cost leadership in structural LVL. Weyerhaeuser Company anchors its position through scale manufacturing in the Pacific Northwest, while Louisiana-Pacific Corporation differentiates via proprietary adhesive systems and builder-direct distribution channels.
Laminated Veneer Lumber consists of dried wood veneers bonded under heat and pressure with exterior-grade adhesives, typically achieving modulus of elasticity values exceeding 1.9 million psi for structural grades. The product serves primarily as load-bearing beams, headers, and rim boards in light-frame construction where dimensional stability and span capability exceed solid sawn lumber. Structural LVL dominates volume flows across residential and commercial channels, while cross-laminated timber captures premium positioning in multi-story mass timber projects where code recognition is expanding fastest. Non-structural LVL occupies narrower furniture and millwork applications with flatter growth trajectories.
US building codes adopted from the International Code Council, Canadian standards administered by the Canadian Standards Association, and APA – The Engineered Wood Association performance ratings collectively govern product certification and market access across the region. These frameworks mandate third-party quality assurance that elevates compliance costs for entrants while insulating incumbent manufacturers with established testing protocols. Stakeholders must monitor pending ANSI standard revisions and provincial code harmonization efforts that could recalibrate competitive positioning between US and Canadian supply bases.
Market Dynamics
The International Building Code's engineered wood recognition clauses are compressing approval timelines for structural alternatives, pulling specification authority from municipal inspectors toward third-party certification bodies and rewriting competitive access rules across US and Canadian jurisdictions.
Growth Catalysts
- Multi-story mass timber code expansion:The International Building Code's Type IV-C construction allowances are unlocking mid-rise commercial applications previously reserved for steel and concrete.
- US Southeast veneer mill clustering:Softwood supply concentration near timberland assets is shortening feedstock transit distances and stabilizing raw material access for regional producers.
- Canadian Standards Association harmonization:Cross-border performance rating alignment is reducing dual-certification burdens and accelerating product portability between US and Canadian construction markets.
Market Restraints
- Phenol-formaldehyde resin cost volatility:Petrochemical feedstock exposure creates margin pressure during crude price spikes, squeezing producers without adhesive formulation control.
- Pacific Northwest production concentration:Weyerhaeuser's scale dominance in this geography creates supply vulnerability during regional weather disruptions or labor actions.
- Cross-laminated timber substitution:CLT's superior fire rating and architectural visibility is capturing premium multi-story projects where LVL cannot compete on aesthetics or code performance.
Strategic Opportunities
- Canadian provincial code adoption gaps:British Columbia and Quebec's advancing mass timber mandates present first-mover positioning ahead of full national harmonization.
- Builder-direct distribution bypass:Louisiana-Pacific's channel model demonstrates margin recovery potential by circumventing traditional lumber yard markups in residential construction.
- Moisture-resistant adhesive convergence:Hybrid phenol-resorcinol formulations meeting both APA performance ratings and green building certification requirements are opening specification in humid climate zones.
Industry Challenges
- Third-party quality assurance capacity:APA – The Engineered Wood Association testing backlog is extending certification timelines and delaying new product launches.
- Veneer drying energy intensity:Natural gas-fired kiln operations face carbon pricing exposure under Canadian federal fuel charge mechanisms and emerging US state-level clean heat standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Laminated Veneer Lumber Market |
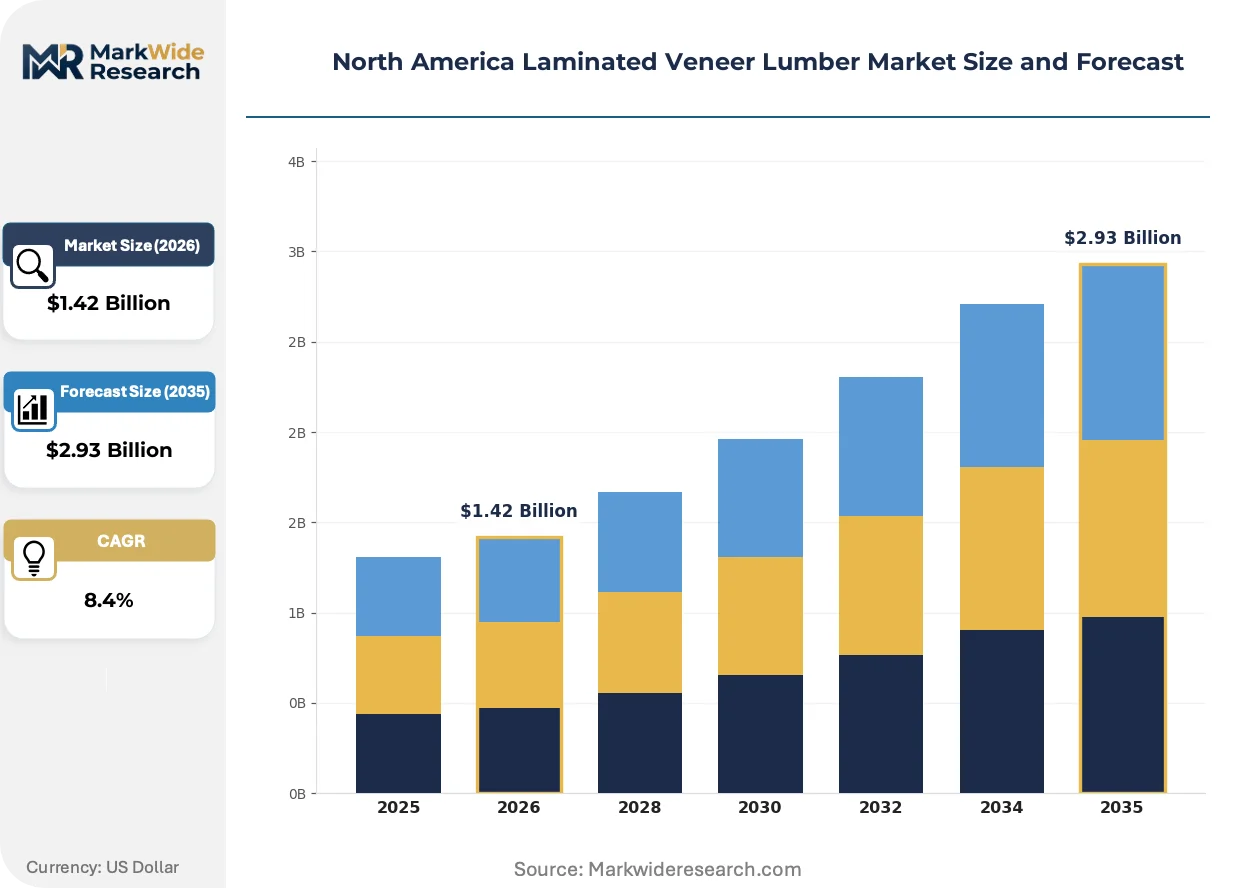
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural LVL, Non-Structural LVL, Glulam, Cross-Laminated Timber End User: Residential Construction, Commercial Construction, Industrial Applications, Furniture Manufacturing Distribution Channel: Direct Sales, Online Retail, Wholesalers, Specialty Stores Application: Flooring, Wall Framing, Roof Systems, Decorative Elements |
| Companies Covered | Resolute Forest Products Inc., Universal Forest Products, Boise Cascade, Anderson Lumber Company, Huber Engineered Woods, Weyerhaeuser Company, Louisiana-Pacific Corporation, MJB Wood Group, LP Building Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Laminated Veneer Lumber Market Strategic Shifts & Innovations
Digital fabrication workflows and adhesive chemistry advances are compressing the gap between engineered wood commodity production and project-specific structural optimization, shifting competitive advantage toward manufacturers with integrated design-to-delivery capabilities.
Mass timber connection systems are modularizing around standardized LVL beam-to-column interfaces, enabling off-site prefabrication of structural modules. Multi-story developers in Vancouver and Toronto are specifying these interfaces to accelerate crane-time schedules on constrained urban sites. This standardization is compressing engineering review cycles and displacing project-specific connection detailing previously handled by structural consultants.
The International Building Code's 2024 Type IV-C height allowances are triggering municipal fire department training investments across US jurisdictions previously hostile to combustible construction. Seattle and Portland have issued early adopter guidance documents clarifying inspection protocols, while Chicago and New York remain in code amendment review. Commercial developers in code-progressive cities are pre-qualifying LVL suppliers ahead of full market opening.
Specification authority is migrating from general contractors toward design-build entities with in-house structural engineering capabilities. These consolidated buyers are unbundling traditional lumber yard service bundles and negotiating direct mill relationships for volume residential projects. The US Southeast and Pacific Northwest markets exhibit the most advanced buyer consolidation, with national homebuilders centralizing procurement through regional distribution centers.
North America Laminated Veneer Lumber Market Segmentation
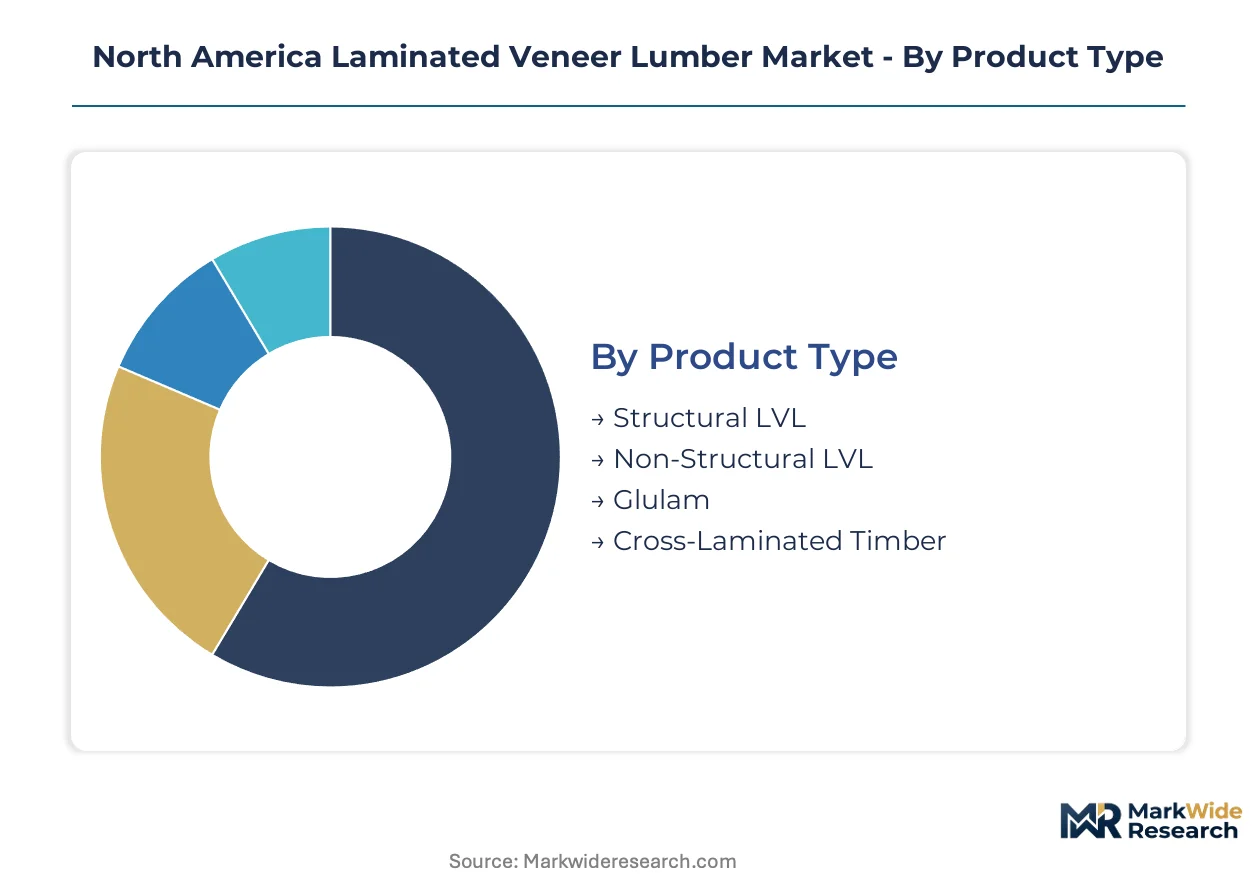
Segmentation in the North America Laminated Veneer Lumber Market reveals how specification authority migrates between product grades, end-use channels, and procurement pathways. Understanding these divisions exposes where margin compression and pricing power concentrate across the value chain.
Product Type:
Upgrade cycles in residential and commercial construction are pulling specification toward higher-performance engineered wood grades as building codes tighten structural requirements.
- Structural LVL:Dried wood veneers bonded under heat and pressure with exterior-grade adhesives, achieving modulus of elasticity values exceeding 1.9 million psi. Demand concentrates in US Southeast residential floor and roof systems where International Building Code updates accelerate engineered wood approvals over solid sawn lumber.
- Non-Structural LVL:Lower-grade veneers for furniture cores and millwork applications with reduced mechanical performance requirements. Applications cluster in Pacific Northwest cabinetry manufacturing where dimensional stability outweighs load-bearing specifications.
- Glulam:Laminated timber beams for long-span commercial and institutional projects. Architects specify these for exposed structural aesthetics in mass timber buildings across Vancouver and Toronto.
- Cross-Laminated Timber:Orthogonally layered solid-sawn lumber panels competing with LVL in mid-rise applications. Superior fire ratings and architectural visibility capture premium multi-story projects where code recognition is expanding fastest.
Volume placements concentrate in Structural LVL; the faster expansion belongs to Cross-Laminated Timber.
End User:
Cost tier differentiation separates commodity-specified projects from performance-driven applications where engineering review cycles justify premium material selection.
- Residential Construction:Single-family and multi-family builders specifying LVL for headers, beams, and rim boards. US Southeast production clustering near softwood veneer mills shortens lead times for regional homebuilders.
- Commercial Construction:Mid-rise office and retail developers leveraging Type IV-C code allowances for mass timber structures. Municipal fire department training investments in Seattle and Portland accelerate inspection protocol clarity.
- Industrial Applications:Warehouse and manufacturing facilities requiring long-span roof systems. These buyers prioritize total installed cost over material aesthetics.
- Furniture Manufacturing:Millwork producers using non-structural grades for core materials. Demand tracks housing starts and renovation activity with lagged correlation.
Residential Construction commands the largest shipment volumes; Commercial Construction is climbing the fastest as code harmonization unlocks mid-rise applications.
Distribution Channel:
Channel selection directly determines margin recovery potential and buyer relationship depth across fragmented procurement landscapes.
- Direct Sales:Mill-direct relationships with national homebuilders and design-build entities. Consolidated buyers in the US Southeast and Pacific Northwest centralize procurement through regional distribution centers.
- Online Retail:Digital platforms serving small contractors and renovation professionals. These channels compete on availability and delivery speed rather than technical support.
- Wholesalers:Traditional lumber yards bundling engineered wood with commodity framing materials. These intermediaries face margin pressure from builder-direct bypass strategies.
- Specialty Stores:Regional distributors targeting custom homebuilders and architects with value-added cutting and engineering services.
Wholesalers retain the highest transaction frequency; Direct Sales is gaining share fastest as buyer consolidation accelerates.
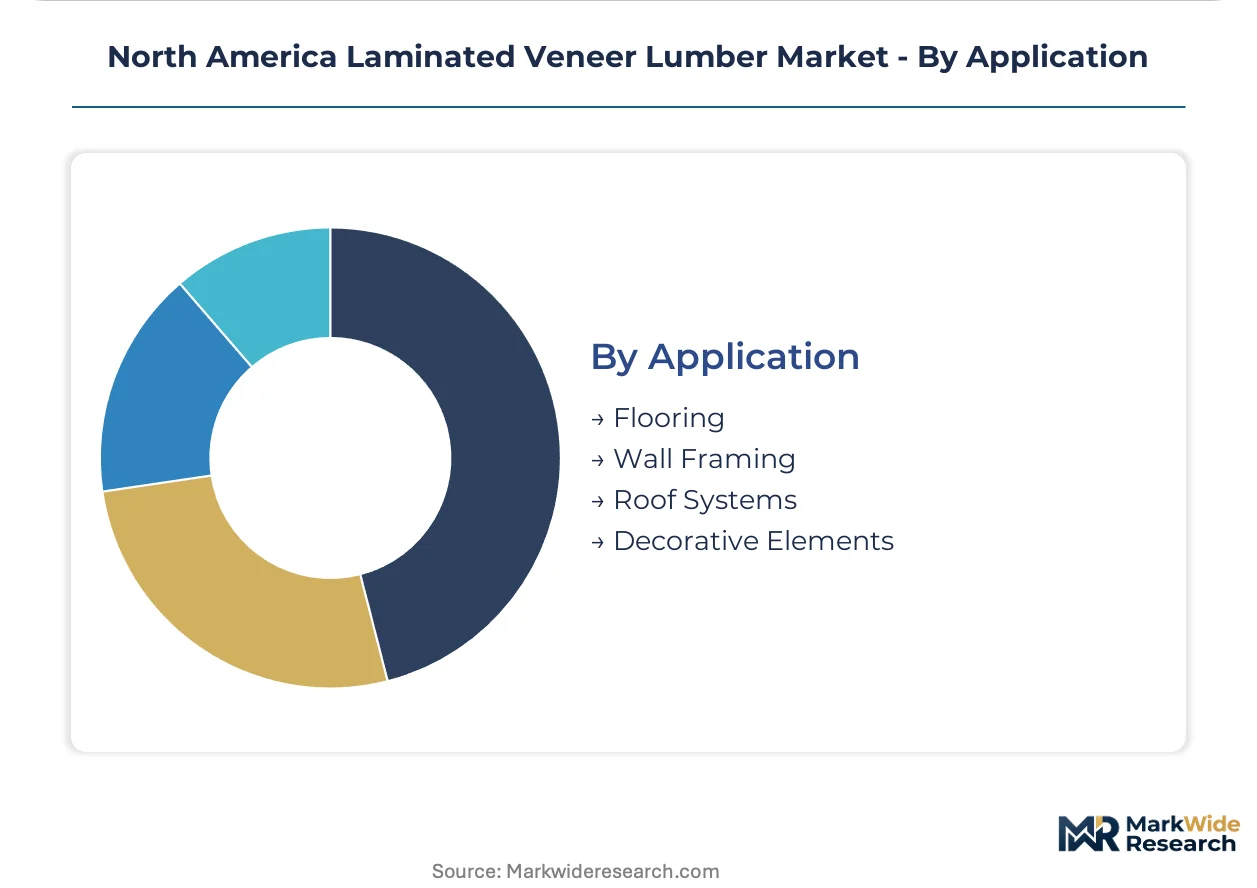
Application:
Application-specific performance requirements dictate adhesive formulation, veneer grade selection, and certification tier across installation environments.
- Flooring:Load-bearing subfloor and finished floor systems requiring stiffness and dimensional stability. Moisture-resistant adhesive specifications open placement in humid climate zones.
- Wall Framing:Headers and studs in light-frame construction. Canadian Standards Association harmonization reduces dual-certification burdens for cross-border product portability.
- Roof Systems:Rafters, ridge beams, and hip beams spanning open living spaces. Long-span capability exceeds solid sawn lumber alternatives.
- Decorative Elements:Exposed beams and architectural features where appearance grade matters. These applications command premium positioning in custom residential and hospitality projects.
Roof Systems generate the highest unit volumes; Decorative Elements carries the steepest expansion trajectory as mass timber aesthetics penetrate mainstream commercial design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for laminated veneer lumber concentrates in the US Southeast and Pacific Northwest, where softwood veneer mill clustering shortens feedstock transit distances and stabilizes raw material access for regional producers. Canadian supply bases in British Columbia and Quebec leverage advancing mass timber mandates to capture premium multi-story applications. Mexico's construction sector remains underpenetrated by engineered wood standards, creating latent expansion potential as cross-border code harmonization progresses.
United States
Residential construction builders in the Southeast are expanding LVL adoption for floor and roof systems as International Building Code updates accelerate engineered wood approvals over solid sawn lumber. The US Southeast hosts concentrated softwood veneer mill operations near timberland assets, shortening lead times for regional homebuilders and stabilizing raw material procurement.
Canada
British Columbia and Quebec's advancing mass timber mandates present first-mover positioning ahead of full national harmonization, with Vancouver and Toronto developers specifying standardized LVL beam-to-column interfaces. Canadian Standards Association performance rating alignment reduces dual-certification burdens and accelerates product portability between US and Canadian construction markets.
Mexico
Industrial warehouse and manufacturing facility construction in Nuevo León and Mexico City Metro generates demand for long-span roof systems where buyers prioritize total installed cost over material aesthetics. The country's national building code administration has yet to fully adopt International Building Code engineered wood recognition clauses, delaying specification migration from steel and concrete.
North America Laminated Veneer Lumber Market Key Industry Players
US Southeast producers anchor one tier; Pacific Northwest specialists hold scale-driven positions in structural grades. The vendor base organizes around three strategic archetypes: integrated timberland-veneer operators, adhesive-technology differentiators, and builder-direct distribution innovators. Dominant competitive moves include backward integration into captive timberland assets and geographic expansion through regional mill acquisitions.
Among US-based producers, Boise Cascade exemplifies the integrated timberland-veneer archetype through captive supply control. Weyerhaeuser Company occupies a scale-driven position in Pacific Northwest manufacturing. Louisiana-Pacific Corporation represents the adhesive-technology and builder-direct distribution model, circumventing traditional lumber yard intermediaries.
| Leading Market Players |
|---|
| Resolute Forest Products Inc. |
| Universal Forest Products |
| Boise Cascade |
| Anderson Lumber Company |
| Huber Engineered Woods |
| Weyerhaeuser Company |
| Louisiana-Pacific Corporation |
| MJB Wood Group |
| LP Building Solutions |
| Others |
Cost & Logistics Intelligence
Consolidated national homebuilders in the US Southeast and Pacific Northwest centralize procurement through regional distribution centers, compressing margins for intermediaries and anchoring contract-based long-term offtake pricing as the dominant model. This buyer concentration feeds back into mill-level capacity decisions, favoring producers with captive timberland assets over merchant veneer purchasers.
Pricing Analysis
Premium pricing for compressed lead times separates rush-order residential projects from standard commercial timelines, with three-tier pricing structure across premium, standard, and economy levels stratifying by APA performance rating and veneer grade. Price differentiation hinges on certification tier and geographic delivery cost, with moisture-resistant adhesive formulations commanding tier premiums. Cost compression in standard grades is intensifying because phenol-formaldehyde resin volatility squeezes producers without adhesive formulation control. National homebuilders exhibit lowest price sensitivity; small contractors purchasing through online retail channels show highest sensitivity.
Supply Chain Analysis
Fuel and freight cost exposure concentrates in cross-border movements between US and Canadian production bases, with rail and truck rates fluctuating with diesel pricing. Geographic supply concentration centers on the United States, Canada, and Mexico, with raw material dependencies on softwood timber, phenol-formaldehyde resins, and exterior-grade adhesives. Supply chain risk rests on single-source vulnerability for petrochemical-derived adhesives during crude price spikes. Distribution runs through builder-direct channels, traditional lumber yards, and regional specialty distributors serving custom homebuilders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around producers with integrated timberland-veneer operations, as third-party quality assurance capacity constraints and APA testing backlogs force weaker merchant veneer purchasers toward exit or acquisition.
For Market Incumbents: Deploy backward integration into captive timberland assets to insulate against softwood supply volatility and merchant veneer price spikes. Anchor scale positions in the US Southeast and Pacific Northwest through regional mill acquisitions that compress feedstock transit distances. Cross-laminated timber substitution in mid-rise commercial applications threatens structural LVL volume; counter with moisture-resistant adhesive convergence that opens humid climate specification. For New Entrants and Emerging Players: The International Building Code's Type IV-C construction allowances in the United States open a window for first-mover positioning in municipal fire department training investment cycles across code-progressive jurisdictions. Target British Columbia and Quebec's advancing mass timber mandates ahead of full Canadian national harmonization. Penetrate through design-build entities with in-house structural engineering capabilities, bypassing traditional lumber yard intermediaries entirely. For Investors and Strategic Acquirers: The window for entry favors integrated timberland-veneer operators with established APA certification protocols and regional mill density in the US Southeast. Long-term viability hinges on carbon pricing exposure management under Canadian federal fuel charge mechanisms and emerging US state-level clean heat standards. Watch veneer drying energy intensity regulations as the inflection signal for margin compression among natural gas-dependent kiln operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timberland Assets | Captive softwood supply insulates against merchant veneer price volatility and stabilizes raw material access. |
| Moisture-Resistant Adhesive Development | Hybrid phenol-resorcinol formulations unlock humid climate specification and green building certification eligibility. |
| Builder-Direct Distribution Expansion | Circumventing lumber yard markups recovers margin compression from consolidated national homebuilder procurement. |
| Regional Mill Acquisition in US Southeast | Clustering near softwood veneer mills shortens lead times and deepens relationships with regional homebuilders. |
| APA Certification Capacity Investment | Expanding third-party quality assurance throughput accelerates new product launches amid testing backlogs. |
Research Approach
Independent corroboration across mill operations executives, national homebuilder procurement directors, APA – The Engineered Wood Association technical staff, and regional lumber yard distributors underwrites the qualitative findings. Secondary validation draws from International Code Council building code amendments, Canadian Standards Association performance rating documents, US Census Bureau construction spending data, and timberland asset disclosures. Bottom-up shipment estimates triangulate against top-down construction activity indices.
Rate-of-change decomposition separates volume growth from price movement across product type, end user, distribution channel, and application segments throughout the forecast period. CAGRs derive from regression analysis of historical engineered wood penetration rates against residential and commercial construction starts. Modeled inputs include International Building Code adoption timelines, veneer mill capacity utilization, and cross-laminated timber substitution elasticities in mid-rise applications.
The model assumes a particular technology adoption path; alternative pathways for mass timber connection system standardization would alter the outlook for LVL beam-to-column interface specification. Forecasts reflect assumptions about code harmonization progress, adhesive chemistry cost curves, and carbon pricing implementation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Concrete Surface Retarders Market
Building & Construction Materials
Artificial Bowling Surface Market
Building & Construction Materials
US Retractable Roofing System Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
Moisture Resistant Gypsum Board Market
Building & Construction Materials
Concrete Resurfacer Market
Building & Construction Materials
Global Stucco Market
Building & Construction Materials
Poland Ceramic Tiles Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
Concrete Floating Floors System Market
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
UPVC Doors and Windows Market
Building & Construction Materials
Masonry Sealers Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market