
 Power Capacitors Market | 2026-2036
Power Capacitors Market Size, Share, and Industry Trends Forecast 2026-2036
Power Capacitors Market Outlook
The EU Green Deal is consolidating demand for grid-stabilizing components across European transmission networks. ABB Ltd. leverages its high-voltage capacitor portfolio to anchor utility contracts in Nordic and German markets. Siemens AG competes through integrated power-quality solutions that combine capacitors with digital monitoring platforms.
Power capacitors store and release electrical energy using dielectric materials such as polypropylene film or aluminum oxide layers, typically rated from microfarads to thousands of farads for industrial-scale applications. Film-type units dominate medium-voltage power factor correction due to self-healing properties and extended operational life. Ceramic segments lead compact filtering applications in automotive inverters, while electrolytic variants occupy bulk energy storage roles in renewable integration projects.
EMA, IEC, and CE marking frameworks enforce dielectric withstand, thermal cycling, and fire-safety thresholds that determine product eligibility across European markets. IEEE and local grid codes in North America impose harmonic tolerance limits that shape capacitor bank design specifications. Stakeholders must monitor evolving efficiency mandates and material sourcing constraints as polymer supply chains face competing demand from battery and packaging sectors.
Market Dynamics
Grid-scale renewable integration is compressing capacitor duty cycles and forcing dielectric material upgrades across utility procurement specifications. IEC 60871 and IEEE 18 revisions are tightening loss-tangent requirements while polymer supply constraints from packaging and battery sectors squeeze film availability for industrial-grade units.
Growth Catalysts
- EU Green Deal grid stabilization mandates:Transmission operators in Germany and Nordic markets are procuring synchronized capacitor banks for voltage regulation across high-renewable penetration zones.
- China's state-backed ultra-high-voltage DC expansion:State Grid Corporation procurement programs are driving volume demand for DC-link film capacitors in converter stations.
- Self-healing metallized polypropylene technology:Extended operational life in power factor correction applications is displacing oil-impregnated units in medium-voltage industrial installations.
Market Restraints
- Polypropylene resin supply concentration:Three Asian petrochemical suppliers control majority feedstock for biaxially oriented film, exposing capacitor manufacturers to raw material allocation risk.
- Aluminum foil tariff exposure:Electrode material imports face trade policy friction in multiple jurisdictions, compressing margin structures on electrolytic variants.
- Electrochemical double-layer substitution:Supercapacitor modules are capturing frequency regulation applications previously served by traditional capacitor banks.
Strategic Opportunities
- India's transmission infrastructure buildout:Power Grid Corporation of India and state utilities are tendering for 765kV substation capacitor banks under CEA technical standards.
- DC fast-charging station integration:Automotive OEMs and charge point operators are specifying compact DC-link capacitors for 350kW+ charging modules.
- Digital twin convergence with power quality monitoring:Capacitor-embedded sensor networks are enabling predictive maintenance contracts for industrial facility operators.
Industry Challenges
- High-voltage testing certification timelines:IEC 60871 type-testing protocols require 12-18 month qualification cycles, delaying product launches for new dielectric formulations.
- Legacy oil-filled unit remediation:PCB-contaminated capacitor bank decommissioning is imposing hazardous waste handling costs on utilities with 1970s-1980s installed bases.
- Harmonic environment modeling complexity:Non-linear load proliferation in industrial facilities is forcing custom filter design for each capacitor bank installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Capacitors Market |
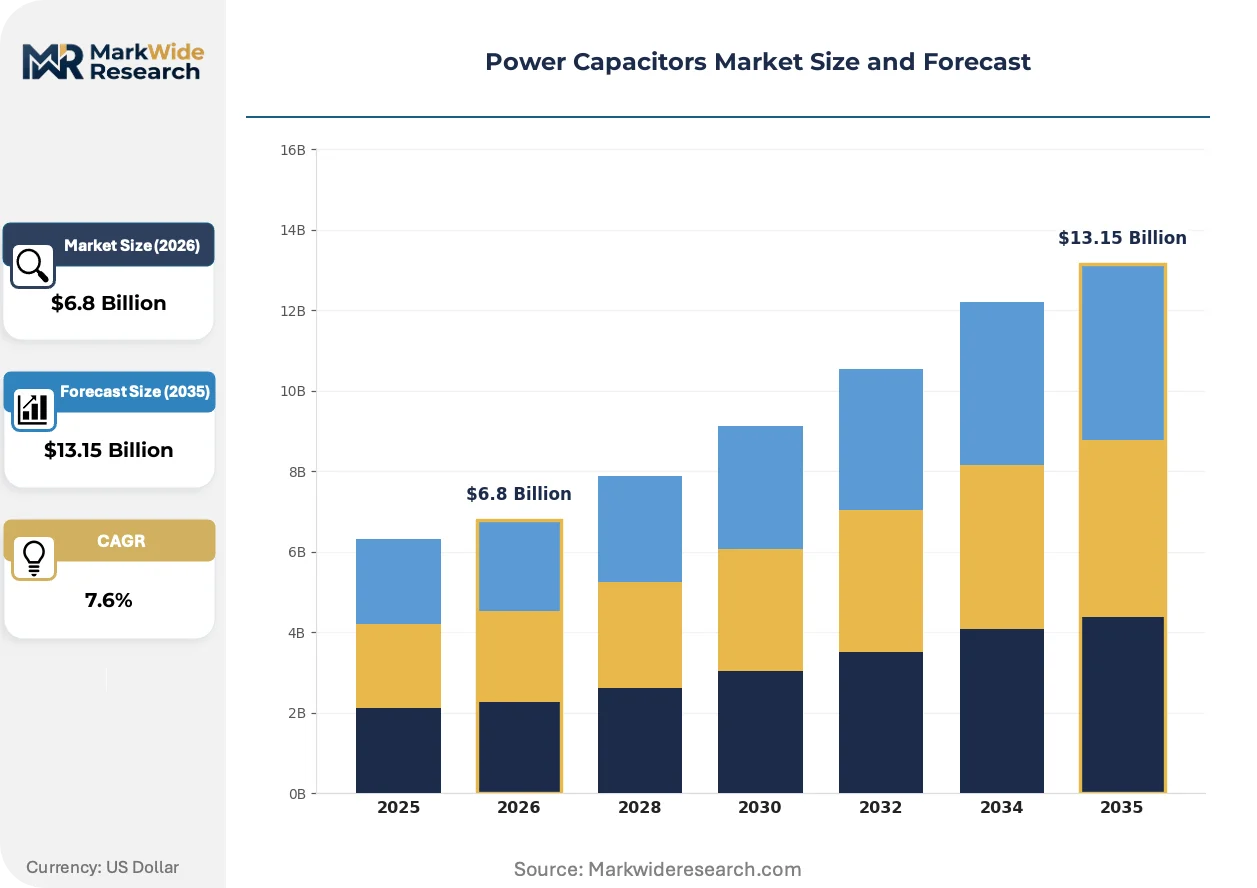
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electrolytic, Film, Ceramic, Tantalum Application: Power Factor Correction, Energy Storage, Filtering, Voltage Regulation End User: Industrial, Commercial, Utilities, Automotive Capacitance: Low, Medium, High, Ultra-High |
| Companies Covered | ABB Ltd., Schneider Electric SE, Eaton Corporation PLC, Siemens AG, Murata Manufacturing Co., Ltd., TDK Corporation, Vishay Intertechnology, Inc., Nippon Chemi-Con Corporation, KYOCERA AVX Components Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Capacitors Market Strategic Shifts
Dielectric material science and embedded intelligence are converging to redefine capacitor lifecycle economics. Three developments are compressing traditional procurement patterns and opening new value-capture mechanisms for component suppliers.
Metallized segmented electrode designs with controlled self-clearing properties are extending field life in harsh thermal environments. Wind turbine OEMs in Denmark and Spain are specifying these units for converter cabinet applications with 25-year design horizons. The technology is decentralizing maintenance schedules from fixed-interval replacement to condition-based intervention, compressing aftermarket revenue pools for conventional suppliers.
REACH restrictions on perfluorinated compounds are forcing reformulation of impregnation fluids used in high-voltage paper-film units. ECHA substance evaluation processes are extending approval timelines for alternative dielectric liquids, compressing product development pipelines. German and French transmission asset owners are accelerating dry-type capacitor bank specifications to preempt regulatory exposure.
Utility procurement teams are unbundling capacitor supply from turnkey installation contracts, creating direct manufacturer-to-utility channels. Nordic and German grid operators are establishing framework agreements with component specialists for standardized bank configurations. This disintermediation is most visible in transmission sector procurement, where engineering-procurement-construction contractors previously captured margin on bundled capacitor packages.
Power Capacitors Market Segmentation
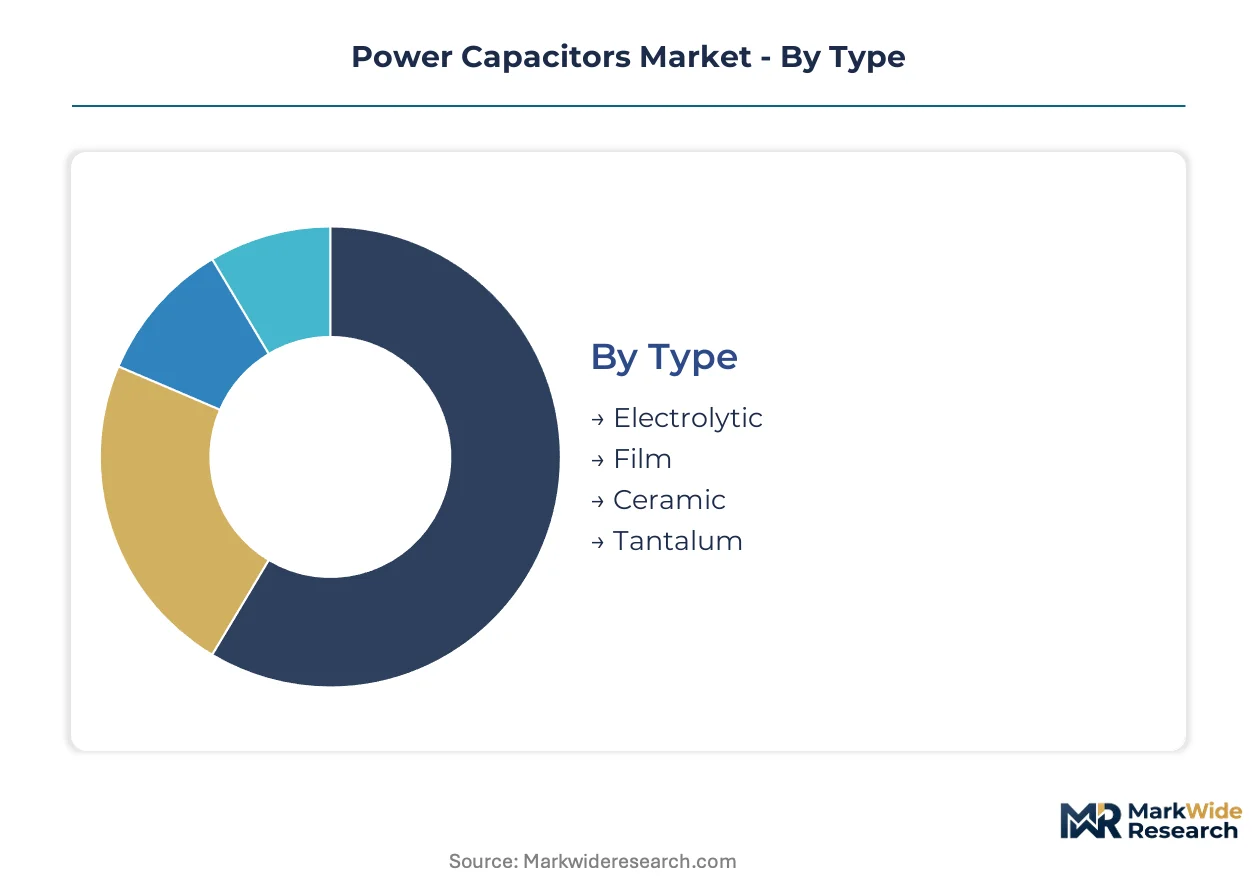
Power capacitor procurement patterns diverge sharply across dielectric technologies and duty-cycle requirements. Industrial buyers prioritize self-healing film units for medium-voltage correction banks, while automotive OEMs specify ceramic and film hybrids for compact inverter modules.
Type:
Upgrade cycles for legacy oil-impregnated units are compressing replacement timelines across utility fleets, with metallized film technologies capturing displacement volume.
- Film:Metallized polypropylene constructions with segmented electrode patterns enable controlled self-clearing after dielectric breakdown. State Grid Corporation procurement programs in China specify these units for 800kV DC converter stations requiring 25-year operational horizons. Polypropylene resin supply constraints from Asian petrochemical suppliers are forcing manufacturers to secure multi-year feedstock contracts.
- Electrolytic:Aluminum oxide dielectric layers with liquid electrolyte impregnation deliver high capacitance density for bulk energy storage roles. Renewable integration projects in Germany and Spain specify these units for DC-link buffering in solar inverters and wind turbine converters. Aluminum foil tariff exposure across multiple jurisdictions is compressing margin structures on high-capacitance variants.
- Ceramic:Multi-layer barium titanate constructions serve compact filtering applications in automotive traction inverters.
- Tantalum:Manganese dioxide cathode systems occupy niche high-reliability military and aerospace applications.
Film sits at the top of the volume ranking, with ceramic climbing the fastest.
Application:
Application selection tracks directly to grid-code compliance requirements and harmonic environment severity.
- Power Factor Correction:Medium-voltage capacitor banks compensate reactive power draw from industrial motor loads and arc furnaces. German transmission operators under EU Green Deal mandates are procuring synchronized banks for voltage regulation across high-renewable penetration zones. IEC 60871 and IEEE 18 revisions are tightening loss-tangent requirements for new installations.
- Energy Storage:DC-link capacitors buffer power fluctuations between generation and grid connection points. Utility-scale solar developers in India specify high-capacitance electrolytic units under CEA technical standards for 765kV substation integration. Electrochemical double-layer supercapacitors are capturing frequency regulation applications previously served by traditional banks.
- Filtering:Harmonic filter networks suppress voltage distortion from variable-frequency drives and rectifier loads.
- Voltage Regulation:Series capacitor banks modify line impedance for reactive power flow control.
Power Factor Correction commands the largest installed base, while Energy Storage expands most quickly.
End User:
End-user procurement authority is shifting from engineering-procurement-construction contractors to direct utility framework agreements.
- Utilities:Transmission and distribution operators specify standardized bank configurations for grid stabilization. Nordic grid operators are unbundling capacitor supply from turnkey installation contracts, creating direct manufacturer channels. Legacy oil-filled unit remediation is imposing hazardous waste handling costs on utilities with 1970s-1980s installed bases.
- Industrial:Manufacturing facilities deploy power factor correction banks to avoid utility penalty charges for reactive power draw. Steel and cement producers in China specify high-duty-cycle units for arc furnace and kiln applications. Non-linear load proliferation is forcing custom filter design for each installation.
- Automotive:OEMs and charge point operators specify compact DC-link capacitors for 350kW+ fast-charging modules.
- Commercial:Data centers and hospitals deploy uninterruptible power systems with capacitor-backed filtering stages.
Utilities dominate procurement volume, with Automotive gaining share fastest.
Capacitance:
Capacitance tier selection correlates with voltage rating and physical packaging constraints.
- High:Thousands of farads in industrial-scale units serve bulk energy storage for renewable integration. Wind turbine OEMs in Denmark specify high-capacitance film units for converter cabinets with extended design horizons. REACH restrictions on perfluorinated compounds are forcing reformulation of impregnation fluids for paper-film constructions.
- Medium:Hundreds of microfarads to single-digit farads occupy power factor correction and motor run applications. Industrial facilities across Germany and France are accelerating dry-type specifications to preempt regulatory exposure to alternative dielectric liquid approval delays.
- Low:Sub-microfarad to microfarad ranges serve signal coupling and decoupling in control electronics.
- Ultra-High:Specialized units for pulsed power and research applications.
High capacitance leads deployment scale, with Medium expanding most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power capacitor manufacturing first scaled in Germany and Switzerland during the 1920s-1930s electrification wave, with ABB and Siemens establishing the foundational high-voltage dielectric technologies that still dominate utility procurement specifications today.
China
State Grid Corporation procurement programs for 800kV ultra-high-voltage DC converter stations drive volume demand for DC-link film capacitors. MIIT and GB standards enforce localized content requirements for grid infrastructure components. Converter station clusters in the Yangtze River Delta and Sichuan-Chongqing corridor absorb the majority of domestic film capacitor output.
Germany
Transmission operators under EU Green Deal mandates procure synchronized capacitor banks for voltage regulation in high-renewable penetration zones. ECHA REACH restrictions on perfluorinated compounds accelerate dry-type specifications. Industrial capacitor demand concentrates in Bavaria and Baden-Württemberg, where automotive OEMs specify compact DC-link units for inverter modules.
United States
FERC Order 2023 grid reliability standards and state-level renewable portfolio standards expand procurement for utility-scale energy storage capacitors. IEEE 18 harmonic tolerance limits shape bank design specifications. Texas ERCOT interconnection projects and California ISO transmission upgrades represent the primary demand nodes for high-voltage installations.
India
Power Grid Corporation of India tenders for 765kV substation capacitor banks under CEA technical standards. PLI scheme incentives for power electronics manufacturing attract component suppliers to Gujarat and Tamil Nadu. Arc furnace installations in Maharashtra and steel belt regions in Odisha drive industrial power factor correction demand.
Japan
METI carbon neutrality roadmaps mandate grid stabilization investments for renewable integration. JIS standards govern dielectric performance testing protocols. Automotive capacitor demand clusters in Aichi Prefecture around Toyota and Nagoya-based inverter suppliers, with Murata and TDK anchoring ceramic and film component supply.
Power Capacitors Market Competitive Environment
Premium-margin players sit above commodity-margin players across dielectric material sophistication and certification depth. The vendor base organizes into three tiers: integrated electrical conglomerates with captive utility relationships, specialized capacitor manufacturers with focused dielectric expertise, and regional fabricators serving price-sensitive industrial replacement markets. Consolidation pressure operates through M&A activity among mid-cap film specialists and strategic partnerships between automotive OEMs and component suppliers for DC-fast-charging specifications.
Within the integrated conglomerate tier, ABB Ltd. and Siemens AG exemplify the utility-contract anchoring archetype, leveraging high-voltage portfolios and turnkey installation capabilities. Schneider Electric SE occupies a position bridging industrial power quality and building automation segments. Among specialized manufacturers, TDK Corporation and Murata Manufacturing Co., Ltd. represent the automotive and electronics-focused dielectric expertise cluster, with ceramic and film hybrid technologies for compact inverter applications.
| Leading Market Players |
|---|
| ABB Ltd. |
| Schneider Electric SE |
| Eaton Corporation PLC |
| Siemens AG |
| Murata Manufacturing Co., Ltd. |
| TDK Corporation |
| Vishay Intertechnology, Inc. |
| Nippon Chemi-Con Corporation |
| KYOCERA AVX Components Corp. |
| Others |
Value Chain & Pricing Dynamics
Metallized film manufacturing migration from oil-impregnated legacy processes compresses unit economics while concentrating feedstock bargaining power among Asian petrochemical suppliers. This technological transition simultaneously elevates performance premiums for self-healing electrode designs and exposes capacitor producers to polypropylene resin allocation bottlenecks from packaging sector competition.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by IEC 60871 certification grade and 25-year operational warranty coverage. Price differentiation hinges on dielectric material pedigree and volume commitment scale, with German transmission operators least sensitive and Indian state utilities most price-constrained. Pricing pressure stems from aluminum foil tariff exposure across North American and European jurisdictions, compressing electrolytic variant margins.
Supply Chain Analysis
MIIT localized content requirements and India's PLI scheme incentives are reshaping sourcing patterns toward domestic electrode winding and impregnation capacity. Manufacturing gravity centers on China, Germany, and Japan for high-voltage film production, with biaxially oriented polypropylene, aluminum foil, and dielectric impregnation fluids as critical inputs. Single-source vulnerability concentrates in Asian petrochemical feedstock, while distribution runs through direct utility framework agreements disintermediating EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power capacitors function as a stable compounder anchored by irreversible grid modernization spending across renewable integration mandates. State-backed transmission infrastructure programs in China and India provide visible demand floors.
For Market Incumbents: Anchor utility relationships through captive high-voltage testing certification capacity, compressing 12-18 month IEC 60871 qualification timelines for competitors. Secure multi-year polypropylene resin offtake agreements to preempt feedstock allocation risk from battery sector demand. Defend against supercapacitor substitution in frequency regulation by bundling digital twin monitoring services with hardware supply.
For New Entrants and Emerging Players: The mid-tier pricing gap between ABB-Siemens premium positioning and regional Chinese fabricators opens white-space in India's 765kV substation buildout under CEA standards. Target automotive DC-fast-charging module specifications where compact DC-link capacitor demand outpaces established supplier capacity. Pursue joint development agreements with wind turbine OEMs in Denmark and Spain for 25-year design horizon converter cabinet applications.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized film capacitor manufacturers lacking utility direct channels but holding segmented electrode metallization expertise. The 5-10 year viability window favors targets with REACH-compliant dry-type formulations and automotive qualification progress. Monitor ECHA substance evaluation timelines for alternative dielectric liquid approvals as inflection signal for paper-film unit obsolescence acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Film | Captive biaxially oriented film production insulates against Asian petrochemical allocation risk. |
| Digital Twin Platform Integration | Capacitor-embedded sensor networks enable predictive maintenance contracts with German transmission operators. |
| REACH-Compliant Dry-Type Certification | ECHA restrictions on perfluorinated compounds accelerate specification shifts away from impregnated units. |
| Automotive DC-Link Capacity Expansion | 350kW+ fast-charging module demand from OEMs outstocks current compact film capacitor supply. |
| Direct Utility Framework Agreements | Nordic and German grid operator procurement unbundling disintermediates EPC contractor margin capture. |
Study Parameters
Multiple input streams — primary interviews with utility planning officers, EPC procurement leads, and capacitor manufacturing technical directors, alongside secondary validation through IEC standard revision drafts, State Grid Corporation tender databases, and FERC Order 2023 compliance filings — were reconciled through bottom-up and top-down triangulation. Trade data from customs authorities and petrochemical feedstock allocation reports provided material flow verification.
Historical capacity utilization patterns were cross-referenced against panel input from transmission asset owners and renewable project developers across the projection horizon. Segmentation modeling incorporated dielectric technology type, application duty cycle, end-user procurement authority, and regional grid code stringency. CAGRs were derived from installer pipeline visibility and equipment replacement cycle analysis, with aluminum foil tariff exposure and supercapacitor substitution rates as industry-specific sensitivity inputs.
Caveats apply where polypropylene resin supply disruptions, ECHA impregnation fluid approval delays, or supercapacitor cost curves could materially shift the outlook for traditional capacitor bank deployment. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Green UPS Market
Power
Direct Current Power System Market
Power
Solar UPS Market
Power
Portugal Power Market
Power
Equatorial Guinea Power Market
Power
Brunei Power Market
Power
Iran Power Market
Power
Global Marine Power Systems Market
Power
Smart Power Market
Power
Power Sled Market
Power
Controllable Shunt Reactor for UHV Market
Power
Middle-East and Africa Power Market
Power
Flue Gas Desulfurization Unit Market
Power
Brazil Power Market
Power
Combined Heat and Power (CHP) Systems Market
Power
Russian Federation Power Market