
 North America Fuel Cell Market | 2026-2036
North America Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fuel Cell Market Analysis
A capital-intensity divergence between integrated stack manufacturers and balance-of-plant assemblers is unwinding competitive hierarchies across the North American supply base. Bloom Energy sustains manufacturing scale through captive solid oxide electrolyzer production in California. Plug Power leverages vertical integration into green hydrogen generation to anchor fleet fueling contracts. Ballard Power Systems specializes in heavy-duty PEMFC modules, competing primarily on power density metrics for transit bus and truck OEMs.
A fuel cell electrochemically converts hydrogen or hydrocarbon fuels into electricity through an anode-cathode reaction, with proton exchange membrane variants operating at 60-80°C and solid oxide variants reaching 800-1,000°C for distributed generation. The technology delivers baseload power without combustion emissions, serving applications where grid reliability or carbon intensity constraints block conventional alternatives. Stationary power applications dominate installed capacity, while transportation segments represent the fastest-growing demand pool as PEMFC costs decline. Hydrogen fuel type commands premium positioning due to zero-emission profiles, though natural gas-fed SOFC systems occupy margin-rich commercial and industrial baseload niches.
The US Inflation Reduction Act hydrogen production tax credits and California Air Resources Board fleet mandates collectively shape deployment timelines and technology selection across the value chain. EPA stationary source standards and DOE hydrogen and fuel cell program targets further constrain project design choices for developers. Stakeholders must monitor state-level hydrogen hub funding allocations and ISO pipeline interconnection rules to anticipate capacity buildout sequencing.
Market Dynamics
The US Inflation Reduction Act hydrogen production tax credits are compressing project payback periods for fuel cell developers, while California's Low Carbon Fuel Standard creates asymmetric pull for zero-emission fleet conversions that other states cannot replicate.
Growth Catalysts
- IRA Hydrogen Production Tax Credits:The 45V credit structure reshapes economics for electrolyzer-fed fuel cell installations, reducing levelized cost of hydrogen by up to three dollars per kilogram for qualified clean hydrogen projects.
- California Fleet Mandates:The California Air Resources Board Advanced Clean Trucks regulation compels heavy-duty fleet operators to phase in zero-emission vehicles, with fuel cells capturing long-haul segments where battery weight penalties disqualify electric alternatives.
- Hydrogen Corridor Infrastructure:The Department of Energy Regional Clean Hydrogen Hubs program funds refueling networks along I-5 and I-10 corridors, enabling coast-to-coast fuel cell truck operations by the mid-2030s.
Market Restraints
- Platinum Group Metal Cost Volatility:PEMFC stack manufacturing depends on platinum and iridium catalyst loadings, with spot price swings in Johannesburg and Moscow-sourced materials compressing stack margins unpredictably.
- Electrolyzer Supply Concentration:Proton exchange membrane electrolyzer manufacturing concentrates in European and Japanese facilities, exposing North American project timelines to trans-Pacific shipping bottlenecks and currency hedging costs.
- Natural Gas SOFC Carbon Intensity:Solid oxide systems running on reformed natural gas face emissions accounting scrutiny under evolving EPA stationary source standards, limiting their eligibility for federal procurement preferences.
Strategic Opportunities
- Texas Industrial Clusters:The Gulf Coast petrochemical corridor offers stranded hydrogen assets and existing pipeline rights-of-way for fuel cell baseload power serving refineries and ammonia plants.
- Data Center Backup Power:Hyperscale operators in Northern Virginia and Phoenix are piloting fuel cells against diesel generators to meet carbon-neutral commitments while maintaining sub-ten-second failover requirements.
- SOFC-CHP Convergence:Solid oxide fuel cell combined heat and power systems capture waste heat for district heating networks in Canadian municipalities, doubling effective efficiency versus simple-cycle generation.
Industry Challenges
- Electrochemist Talent Scarcity:Stack engineering and membrane electrode assembly process development require specialized PhD-level expertise that North American universities produce at insufficient rates for manufacturing scale-up timelines.
- NFPA 2 Compliance Complexity:Hydrogen fueling station permitting under evolving National Fire Protection Association codes varies by municipality, creating unpredictable approval timelines that stall fleet deployment schedules.
- Legacy Grid Interconnection Queues:ISO New England and CAISO interconnection backlogs delay stationary fuel cell projects by thirty-six to forty-eight months, eroding offtake contract viability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fuel Cell Market |
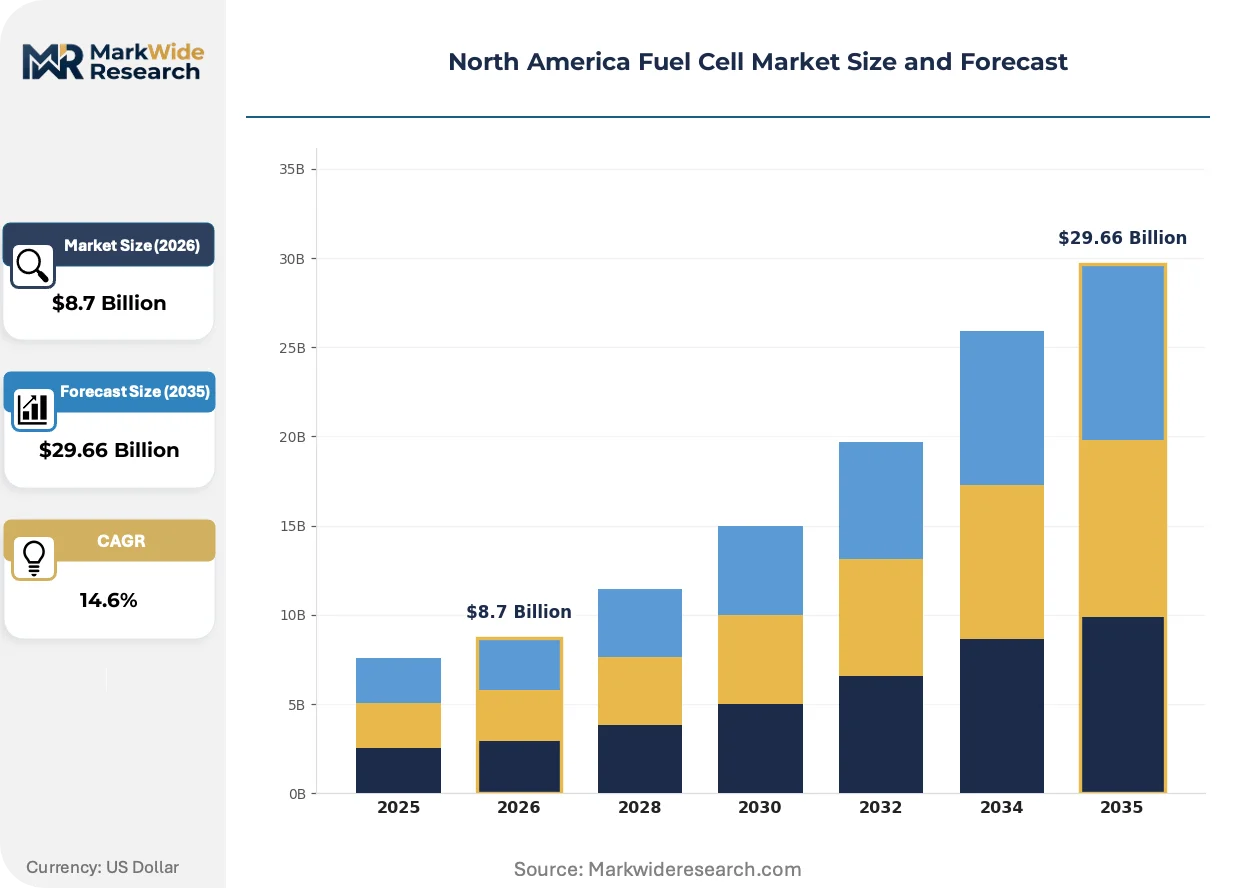
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Transportation, Stationary Power, Portable Power, Backup Power Fuel Type: Hydrogen, Natural Gas, Methanol, Biogas End User Sector: Automotive, Aerospace, Industrial, Residential Technology: PEMFC, SOFC, AFC, MCFC |
| Companies Covered | Ballard Power Systems, Plug Power, Bloom Energy, FuelCell Energy, Cummins, Doosan Fuel Cell America, Nuvera Fuel Cells, General Motors, Loop Energy, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fuel Cell Market Emerging Trajectories
Electrolyzer technology maturation is bifurcating the fuel cell value chain, with stack manufacturers racing to integrate upstream hydrogen production while project developers seek captive supply security through long-term offtake contracting structures.
Solid oxide electrolyzer technology is fragmenting the historical PEM-alkaline duopoly in hydrogen production equipment. Industrial gas suppliers and utility-scale developers are adopting SOEC systems for high-temperature steam electrolysis in refinery and steel applications. The technology's superior efficiency at elevated temperatures is compressing the capital cost gap with incumbent alkaline systems, forcing incumbent electrolyzer vendors to accelerate stack durability improvements or cede the high-capacity segment.
The US Department of Energy Hydrogen and Fuel Cell Technologies Office updated its Million Mile Fuel Cell Truck target, accelerating OEM powertrain development timelines for Class 8 long-haul applications. The technical specifications require fifty-thousand-hour stack durability and sub-two-dollar-per-kilogram hydrogen delivery costs. Heavy-duty truck manufacturers are responding with dedicated fuel cell engineering centers in Michigan and California, shifting R&D resources from battery-electric platforms.
Fleet operators are consolidating procurement through hydrogen-as-a-service contracting models that bundle vehicle lease, fuel, and maintenance into single per-mile rates. This unbundles capital risk from operational expertise, allowing smaller logistics companies to adopt fuel cell trucks without balance sheet exposure to fueling infrastructure. The model is most visible in California's San Joaquin Valley agricultural haulage sector, where seasonal revenue volatility previously blocked technology transitions.
North America Fuel Cell Market Segmentation
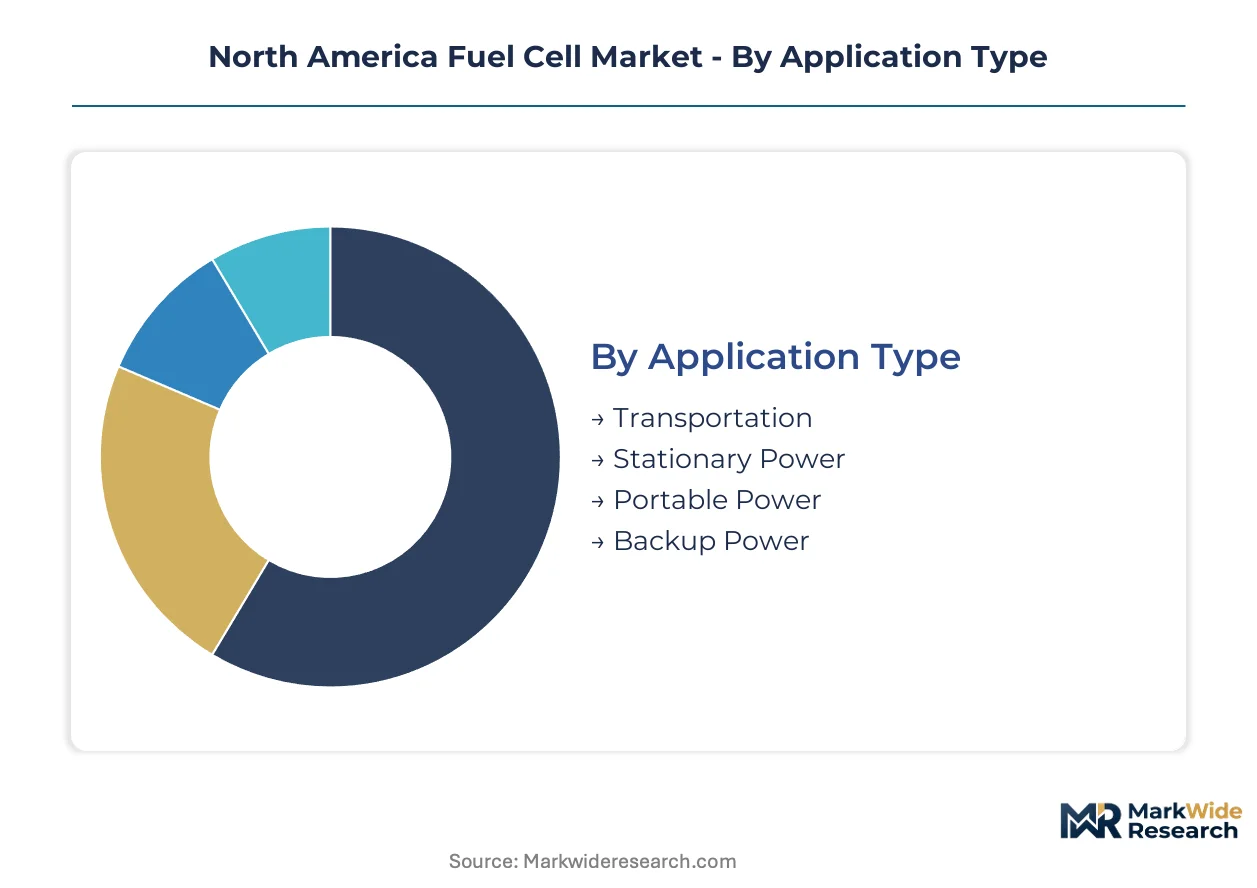
Fuel cell market segmentation reveals divergent competitive pressures across application contexts, with each dimension exposing distinct substitution threats from battery-electric alternatives and conventional combustion systems. Technology selection and fuel sourcing decisions cascade through project economics, regulatory eligibility, and infrastructure requirements in ways that reshape vendor positioning across the value chain.
Application Type:
Transportation applications face the most acute substitution pressure from lithium-ion battery systems, forcing fuel cell developers to defend long-haul niches where energy density requirements exclude electrochemical storage.
- Transportation:Heavy-duty trucking and transit bus deployments concentrate in California's I-5 corridor, where fleet mandates and hydrogen hub funding offset battery-electric competition in 500+ mile duty cycles. CARB Advanced Clean Trucks regulation compels zero-emission conversion timelines that favor fuel cells for weight-sensitive Class 8 operations.
- Stationary Power:Distributed generation installations serve data centers, hospitals, and industrial facilities requiring sub-ten-second failover reliability. Solid oxide systems capture baseload contracts in Texas petrochemical clusters where grid instability and carbon accounting requirements block conventional alternatives.
- Portable Power:Military field units and remote construction sites deploy compact PEMFC units for silent operation beyond generator noise restrictions.
- Backup Power:Telecommunications infrastructure and emergency response systems prioritize fuel cells over diesel generators for indoor air quality compliance.
Stationary Power anchors the volume base while Transportation gains share at the steepest rate.
Fuel Type:
Cost tier stratification separates premium zero-emission hydrogen from margin-compressed natural gas reforming, with biogas pathways capturing sustainability premiums in constrained feedstock markets.
- Hydrogen:Electrolyzer-fed supply chains command price premiums for transportation and export-oriented industrial applications. IRA 45V production tax credits compress levelized costs for qualified clean hydrogen projects serving California and Texas corridors.
- Natural Gas:Reformed methane feeds solid oxide systems in commercial baseload installations where pipeline access eliminates hydrogen logistics costs. EPA stationary source emissions scrutiny limits federal procurement eligibility for carbon-intensive feedstocks.
- Methanol:Liquid fuel logistics enable portable and marine applications lacking compressed gas infrastructure.
- Biogas:Landfill and anaerobic digester methane captures waste-to-energy premiums in agricultural and municipal procurement.
Hydrogen dominates revenue concentration while biogas climbs the fastest on sustainability-linked contracting.
End User Sector:
Customer type fragmentation splits procurement between capital-intensive industrial operators and fleet-as-a-service platforms that unbundle technology risk from operational expertise.
- Automotive:Light-duty vehicle deployments remain marginal as battery-electric platforms capture consumer and commercial segments. Heavy-duty truck OEMs maintain Michigan and California engineering centers focused on 50,000-hour durability targets.
- Aerospace:Ground support equipment and unmanned aerial system prototypes test hydrogen propulsion for airport emissions compliance.
- Industrial:Refineries, ammonia plants, and steel facilities anchor stationary demand through captive hydrogen utilization and process heat integration.
- Residential:Combined heat and power micro-cogeneration penetrates limited markets in cold-climate Canadian municipalities with district heating infrastructure.
Industrial anchors the volume base while Automotive expands most quickly on fleet mandate enforcement.
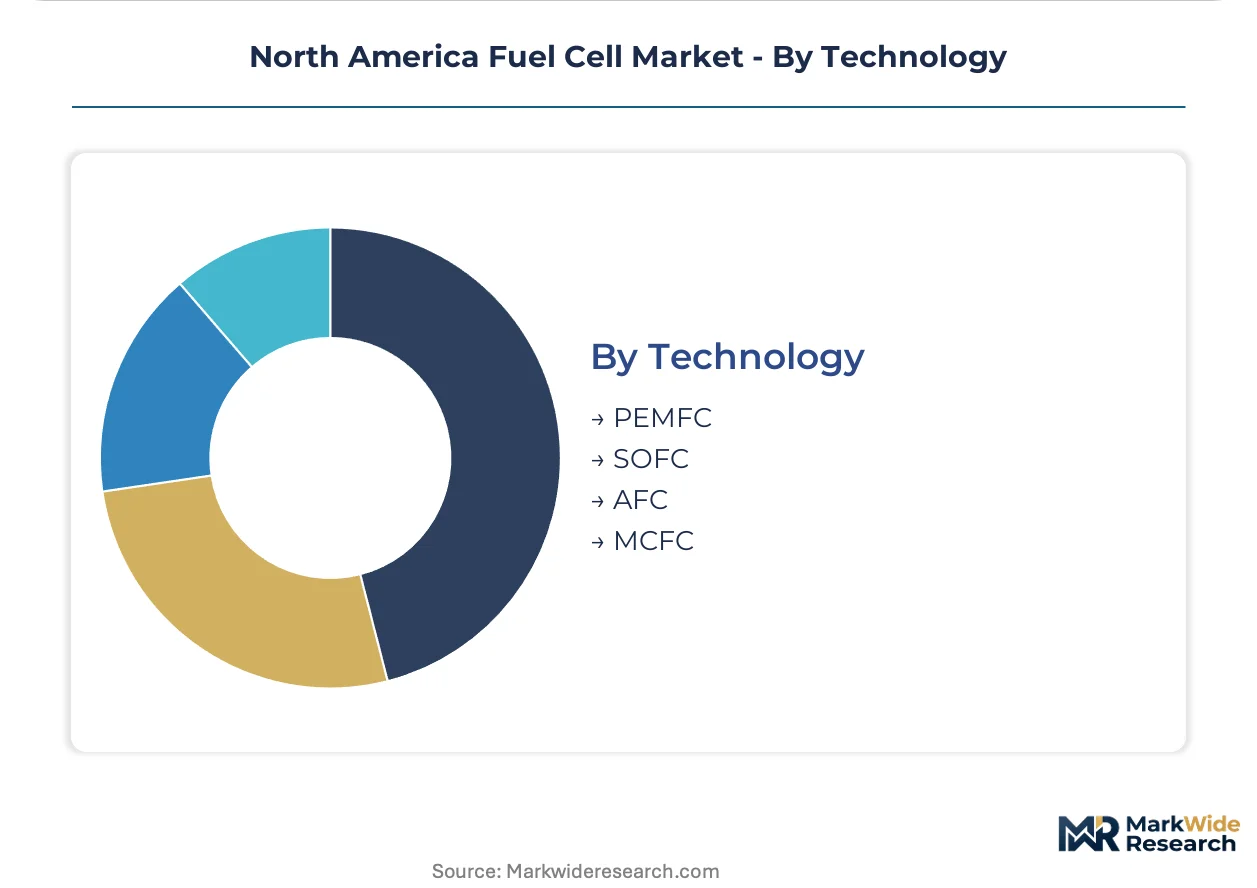
Technology:
Supply concentration in membrane electrode assembly and ceramic stack manufacturing creates divergent scaling constraints across electrochemical architectures.
- PEMFC:Proton exchange membrane systems operate at 60-80°C with platinum catalyst loadings that expose manufacturers to Johannesburg and Moscow-sourced metal volatility. Transportation applications dominate PEMFC demand as power density metrics satisfy transit bus and truck OEM requirements.
- SOFC:Solid oxide fuel cells reach 800-1,000°C for distributed generation with combined heat and power efficiency advantages. Bloom Energy's California manufacturing and Plug Power's electrolyzer integration anchor North American supply capacity.
- AFC:Alkaline fuel cell technology retains niche aerospace and stationary applications with reduced precious metal dependence.
- MCFC:Molten carbonate systems occupy large-scale stationary installations above 1 MW capacity with high-temperature waste heat recovery.
PEMFC anchors the volume base while SOFC gains share fastest on industrial baseload expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates North American fuel cell deployment through hydrogen hub investments and fleet mandates, while Canada advances solid oxide combined heat and power in cold-climate municipalities. Mexico's industrial corridor offers stranded hydrogen assets for cross-border supply integration.
United States
California's Low Carbon Fuel Standard and hydrogen corridor infrastructure anchor transportation demand along the I-5 and I-10 freight routes. The Department of Energy Regional Clean Hydrogen Hubs program funds refueling networks enabling coast-to-coast fuel cell truck operations. Texas Gulf Coast petrochemical clusters repurpose existing pipeline rights-of-way for fuel cell baseload power serving refineries and ammonia plants.
California
CARB Advanced Clean Trucks regulation compels heavy-duty fleet operators to phase in zero-emission vehicles, with fuel cells capturing long-haul segments where battery weight penalties disqualify electric alternatives. State-level hydrogen hub funding allocations concentrate in the San Joaquin Valley agricultural haulage sector. Bloom Energy's captive solid oxide electrolyzer production in California sustains manufacturing scale for stationary power developers.
Texas
The Gulf Coast petrochemical corridor offers stranded hydrogen assets and existing pipeline infrastructure for fuel cell baseload power. EPA stationary source standards constrain natural gas-fed solid oxide carbon intensity accounting, limiting federal procurement eligibility. Industrial clusters in Houston and Beaumont pilot fuel cell systems for refinery process heat integration and grid instability mitigation.
Canada
Solid oxide fuel cell combined heat and power systems capture waste heat for district heating networks in Ontario and Quebec municipalities. Canadian cold-climate conditions favor high-temperature electrochemical architectures over proton exchange membrane alternatives for residential micro-cogeneration. Provincial clean energy procurement programs prioritize fuel cell deployments in remote mining and indigenous community applications lacking grid access.
North America Fuel Cell Market Vendor Landscape
Concentration sits with integrated stack manufacturers and balance-of-plant assemblers competing through divergent capital intensity models. The vendor base splits between captive electrolyzer producers and fleet fueling contractors unbundling operational risk from capital deployment. Two strategic archetypes dominate: vertical integrators controlling upstream hydrogen generation, and specialized module suppliers competing on power density metrics. Competitive moves center on backward integration into green hydrogen production and long-term offtake contracting for fleet-as-a-service platforms.
Among North American fuel cell developers, Ballard Power Systems, Plug Power, and Bloom Energy exemplify contrasting strategic positions. Ballard Power Systems represents the specialized heavy-duty module archetype, competing primarily on power density metrics for transit bus and truck OEMs. Plug Power anchors the vertical integration model, leveraging upstream control over green hydrogen generation to secure fleet fueling contracts. Bloom Energy occupies the solid oxide manufacturing position, sustaining scale through captive electrolyzer production for stationary power applications.
| Leading Market Players |
|---|
| Ballard Power Systems |
| Plug Power |
| Bloom Energy |
| FuelCell Energy |
| Cummins |
| Doosan Fuel Cell America |
| Nuvera Fuel Cells |
| General Motors |
| Loop Energy |
| Others |
Supply Flow & Price Mechanics
Manufacturing scale advantages at Bloom Energy's California solid oxide facilities and Ballard Power Systems' Canadian PEMFC module plants compress unit economics for stack producers while elevating price floors for smaller balance-of-plant assemblers lacking captive electrolyzer integration. This scale divergence concentrates pricing power among integrated manufacturers and forces modular suppliers toward hydrogen-as-a-service contracting to escape commodity margin compression.
Pricing Analysis
Industrial OEM buyers anchor project-based contract pricing for heavy-duty fuel cell modules, with three-tier pricing structure across premium, standard, and economy levels differentiated by stack durability guarantees and IRA 45V tax credit eligibility. Cost compression in the standard tier is intensifying because platinum group metal volatility from Johannesburg and Moscow sources squeezes membrane electrode assembly margins. Fleet operators purchasing through hydrogen-as-a-service platforms exhibit the highest price sensitivity due to per-mile rate benchmarking against diesel alternatives, while data center backup power buyers show the lowest sensitivity given carbon-neutral commitment deadlines.
Supply Chain Analysis
Japan and Germany anchor proton exchange membrane electrolyzer manufacturing, while the United States and South Korea concentrate solid oxide stack fabrication for stationary power applications. North American fuel cell production draws from iridium catalysts sourced through South African refiners, ceramic powders from Japanese suppliers, and compressed hydrogen storage vessels manufactured in South Korea. Single-source vulnerability in membrane electrode assembly equipment exposes project timelines to trans-Pacific shipping bottlenecks. Distribution runs through regional hydrogen hub networks funded by Department of Energy corridor investments, with final-mile fueling infrastructure deployed via fleet-as-a-service platform operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against lithium-ion battery systems capturing short-haul fleet segments and stationary power niches where energy density constraints do not apply. Incumbents must navigate battery-electric encroachment while exploiting regulatory windows that favor fuel cells for weight-sensitive Class 8 operations.
For Market Incumbents: Compound manufacturing scale through backward integration into green hydrogen generation, securing captive supply for fleet fueling contracts. Lock in long-term offtake agreements with San Joaquin Valley agricultural haulers before battery-electric alternatives satisfy seasonal range requirements. Prioritize IRA 45V credit stacking to defend margin position against European electrolyzer imports. For New Entrants and Emerging Players: Lead with hydrogen-as-a-service platform development targeting mid-size logistics operators lacking balance sheet capacity for infrastructure ownership. White-space opportunity concentrates in Texas Gulf Coast petrochemical clusters where stranded hydrogen assets enable fuel cell baseload power at grid-competitive rates. Pursue equipment-leasing partnerships with existing industrial gas distributors to bypass direct OEM competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet-as-a-service platforms bundling vehicle lease, fuel, and maintenance into single per-mile contracts. Long-term viability favors electrolyzer-integrated stack manufacturers with demonstrated 50,000-hour durability validation for Class 8 applications. Monitor California Air Resources Board mandate enforcement timelines as the primary inflection indicator for transportation segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Manufacturing Scale-Up | Captive hydrogen production secures fleet fueling contracts under IRA 45V credit structures. |
| Long-Term Hydrogen Offtake Agreements | Contracted supply de-risks project finance for Texas petrochemical corridor deployments. |
| Stack Durability Certification Investment | 50,000-hour validation unlocks CARB Advanced Clean Trucks compliance for heavy-duty OEMs. |
| Hydrogen Corridor Infrastructure Partnership | Department of Energy hub funding enables I-5 and I-10 refueling network completion. |
| Fleet-as-a-Service Platform Launch | Per-mile contracting unbundles capital risk for agricultural haulage operators in California. |
Methodological Framework
The analysis maps PEMFC transportation modules, SOFC stationary power systems, and alkaline fuel cell aerospace applications, each validated through fuel cell engineering directors, fleet procurement managers at Class 8 operators, hydrogen hub program officers, and stationary power project developers. Primary interview findings triangulate against Department of Energy hydrogen hub funding disclosures, California Air Resources Board regulatory filings, EPA stationary source standard updates, and SEC 10-K filings from publicly traded stack manufacturers. Bottom-up unit economics modeling reconciles with top-down market sizing across technology and application dimensions.
Consistency checks validate volume and value outputs against Department of Energy hydrogen production targets, California Low Carbon Fuel Standard credit pricing trajectories, and ISO New England interconnection queue data across the projection horizon. Segmentation dimensions modeled include electrochemical architecture, fuel feedstock type, application context, end-user sector, and regional regulatory framework. CAGRs derive from installed capacity buildout curves and electrolyzer cost decline trajectories. Key forecast inputs incorporate IRA 45V credit eligibility thresholds and NFPA 2 hydrogen fueling station permitting velocity by municipality.
Forecasts assume regulatory continuity in IRA hydrogen production tax credits and CARB fleet mandate enforcement; material policy shifts would require re-modeling transportation segment penetration rates and stationary power procurement eligibility. Recalibration cycles align with Department of Energy hydrogen hub funding allocation announcements and EPA stationary source standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Fuel Cell Market
Fuel Cell Technology
Aircraft Fuel Cell Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
Japan Fuel Cell Market
Fuel Cell Technology
Asia-Pacific Fuel Cell Market
Fuel Cell Technology
Fuel Cells for CHP Application Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
Fuel Cell for Data Center Market
Fuel Cell Technology
Microbial Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cells Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
Global Fuel Cell Balance of Plant (BOP) Market
Fuel Cell Technology
Solid Oxide Fuel Cell Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
France Fuel Cell Market