
 Electric Arc Furnaces Market | 2026-2036
Electric Arc Furnaces Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Arc Furnaces Market Analysis
Scrap steel is broadening the feedstock base for Electric Arc Furnaces as mills reduce dependence on iron ore and coking coal. Danieli & C. Officine Meccaniche S.p.A. leverages its Q-Smart digital platform to optimize melt shop energy consumption. SMS group GmbH sustains technology leadership through its X-Pact electrical and automation systems for AC and DC furnace architectures. Primetals Technologies Limited anchors its position with integrated secondary metallurgy packages that extend furnace output quality to flat steel grades.
An Electric Arc Furnace is a steelmaking vessel that melts charged material—predominantly scrap metal, direct reduced iron, or pig iron—using graphite electrodes to generate arcs reaching temperatures above 3,500 degrees Celsius, with typical unit capacities ranging from 30 tonnes to 400 tonnes per heat. The primary purpose is to produce liquid steel for casting or further refining with lower carbon intensity than the blast furnace-basic oxygen furnace route. DC Electric Arc Furnace configurations command premium positioning due to reduced electrode consumption and lower flicker impact on grid stability. Steel Manufacturing as an end user dominates installed base value, while Metal Recycling applications represent the fastest-growing demand pool as circular economy mandates tighten across industrial economies.
The US EPA enforces Maximum Achievable Control Technology standards for particulate emissions from EAF operations, while the EU F-Gas Regulation constrains refrigerant and process gas alternatives in auxiliary systems. China's MEE implements ultra-low emission retrofit deadlines for steel plants in the Yangtze River and Beijing-Tianjin-Hebei clusters. India's CEA mandates energy consumption norms for designated consumers including large steel producers. Stakeholders must monitor how carbon border adjustments and scrap export restrictions reshape furnace economics and regional competitiveness.
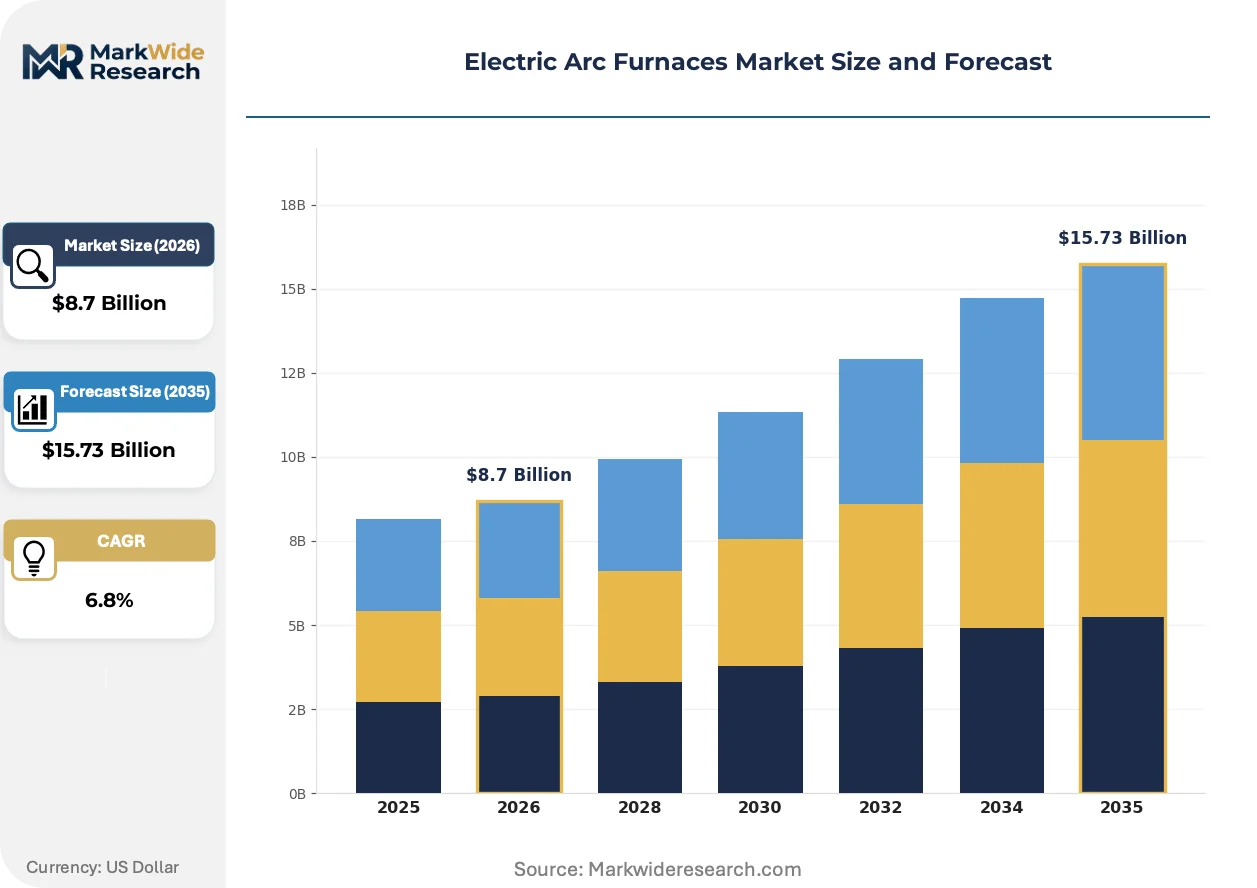
Market Dynamics
The Electric Arc Furnaces Market pivots on the structural divergence between carbon-intensive blast furnace routes and scrap-based electric melting, with regulatory carbon pricing mechanisms now dicting capital allocation across steelmaking geographies.
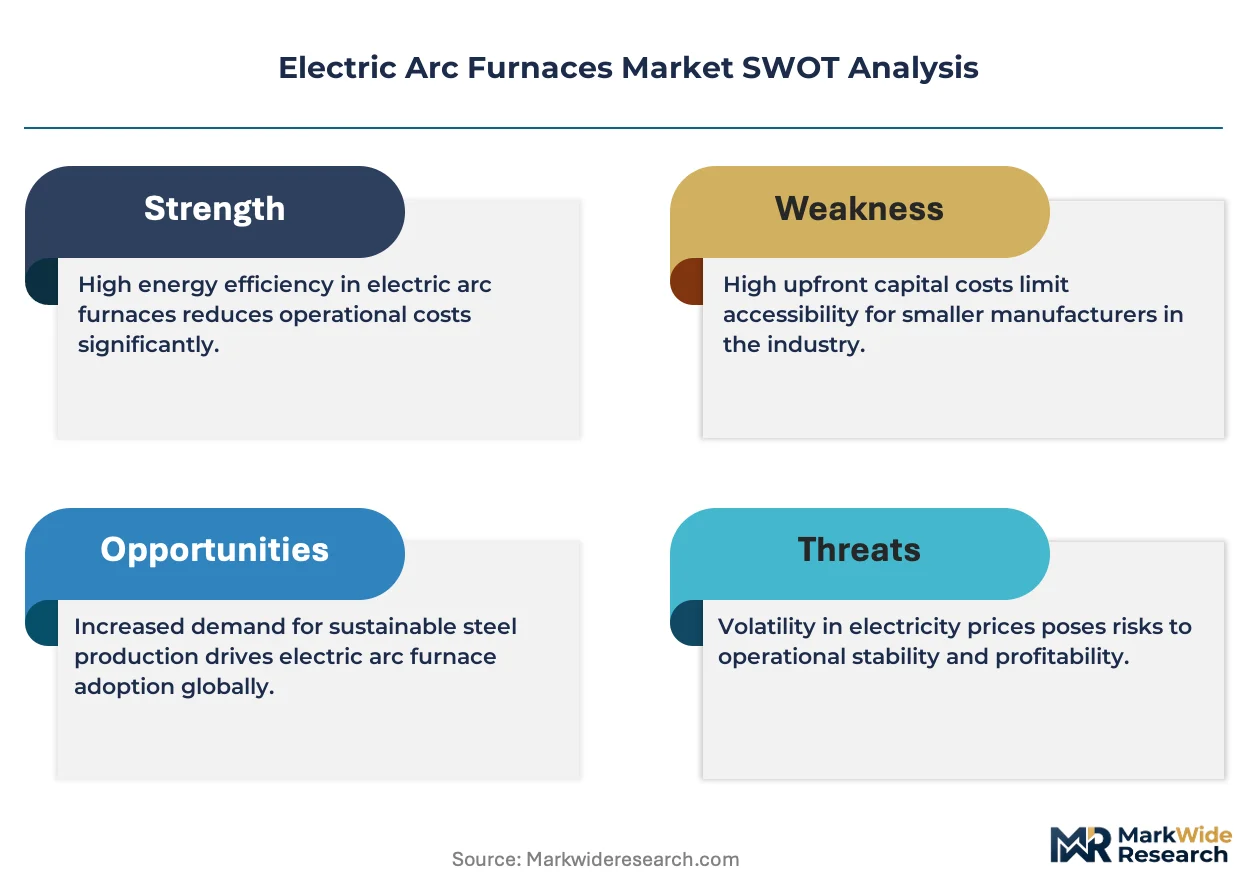
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:Import charges on embodied carbon in steel products redirect investment toward EAF capacity within European borders, accelerating facility announcements in Poland and Italy.
- Automotive lightweighting mandates:Vehicle OEMs specify higher recycled content thresholds, pulling flat steel demand toward EAF-sourced grades with verified scrap provenance.
- Direct reduced iron technology maturation:DRI pellet quality improvements enable EAF operators to dilute residual copper and tin in scrap charges, expanding feedstock flexibility.
Market Restraints
- Graphite electrode supply concentration:Chinese and Indian electrode manufacturers control roughly seventy percent of global capacity, exposing EAF operators to price volatility and export restriction risk.
- Scrap quality degradation:Post-consumer steel streams carry rising contamination from copper wiring and galvanized coatings, elevating refining costs and off-grade penalties.
- Grid interconnection delays:Utility approval timelines for high-capacity furnace connections extend eighteen to thirty-six months in Germany and Japan, throttling brownfield expansion.
Strategic Opportunities
- India infrastructure build-out:National highway and rail corridor programs create captive demand for long products, justifying greenfield EAF complexes in Odisha and Karnataka.
- Hydrogen-reduced iron integration:Hybrit-style DRI-EAF coupling eliminates Scope 3 emissions from coal-based reduction, positioning Nordic producers for premium green steel contracts.
- Industrial scrap aggregation platforms:Digital marketplaces connecting demolition contractors with melt shops compress collection radius and improve charge predictability.
Industry Challenges
- Electrical engineer scarcity:Specialized expertise in high-current power systems and harmonic filtering for DC furnaces commands premium wages and extended recruitment cycles.
- Refractory performance optimization:Slag chemistry variations between scrap-heavy and DRI-heavy heats accelerate sidewall and roof lining degradation, demanding predictive maintenance investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Arc Furnaces Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Electric Arc Furnace, DC Electric Arc Furnace, Mini Electric Arc Furnace, Large Electric Arc Furnace End User: Steel Manufacturing, Foundries, Metal Recycling, Ferroalloy Production Technology: Hybrid Technology, Induction Heating, Automated Control Systems, Advanced Melting Technologies Application: Steel Production, Scrap Melting, Alloy Production, Casting |
| Companies Covered | Siemens AG, Tenova S.p.A., Danieli & C. Officine Meccaniche S.p.A., China First Heavy Industries, Mitsubishi Heavy Industries Ltd., SMS group GmbH, Electrotherm (India) Limited, Primetals Technologies Limited, Nippon Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Arc Furnaces Market Emerging Trajectories
Digital twin deployment and artificial intelligence are compressing energy intensity curves while regulatory disclosure requirements force transparency through the steel value chain.
Advanced process control using real-time spectral analysis is converging with predictive slag modeling to optimize foaming practices and reduce tap-to-tap times. Tier-one mills in South Korea and Brazil deploy these systems to hold electrical consumption within three percent of theoretical minimums. The technology is converging with legacy distributed control architectures, requiring middleware investments that favor greenfield installations over retrofits.
The EU F-Gas Regulation phases down hydrofluorocarbon use in EAF auxiliary cooling and compressed gas systems, compelling operators to specify ammonia or CO2-based alternatives in new builds. Implementation timelines vary by system type, with cold repair windows in 2027-2028 driving near-term procurement decisions. German and Dutch plants face the most compressed compliance schedules due to earlier national transposition deadlines.
Steel buyers now mandate third-party verified Environmental Product Declarations before contract award, displacing self-reported carbon claims. Automotive and construction procurement teams in Japan and California embed EPD thresholds directly into technical specifications. This certification-driven preference shift concentrates contract awards among EAF operators with integrated scrap traceability systems and ISO 14025-compliant lifecycle data.
Electric Arc Furnaces Market Segmentation
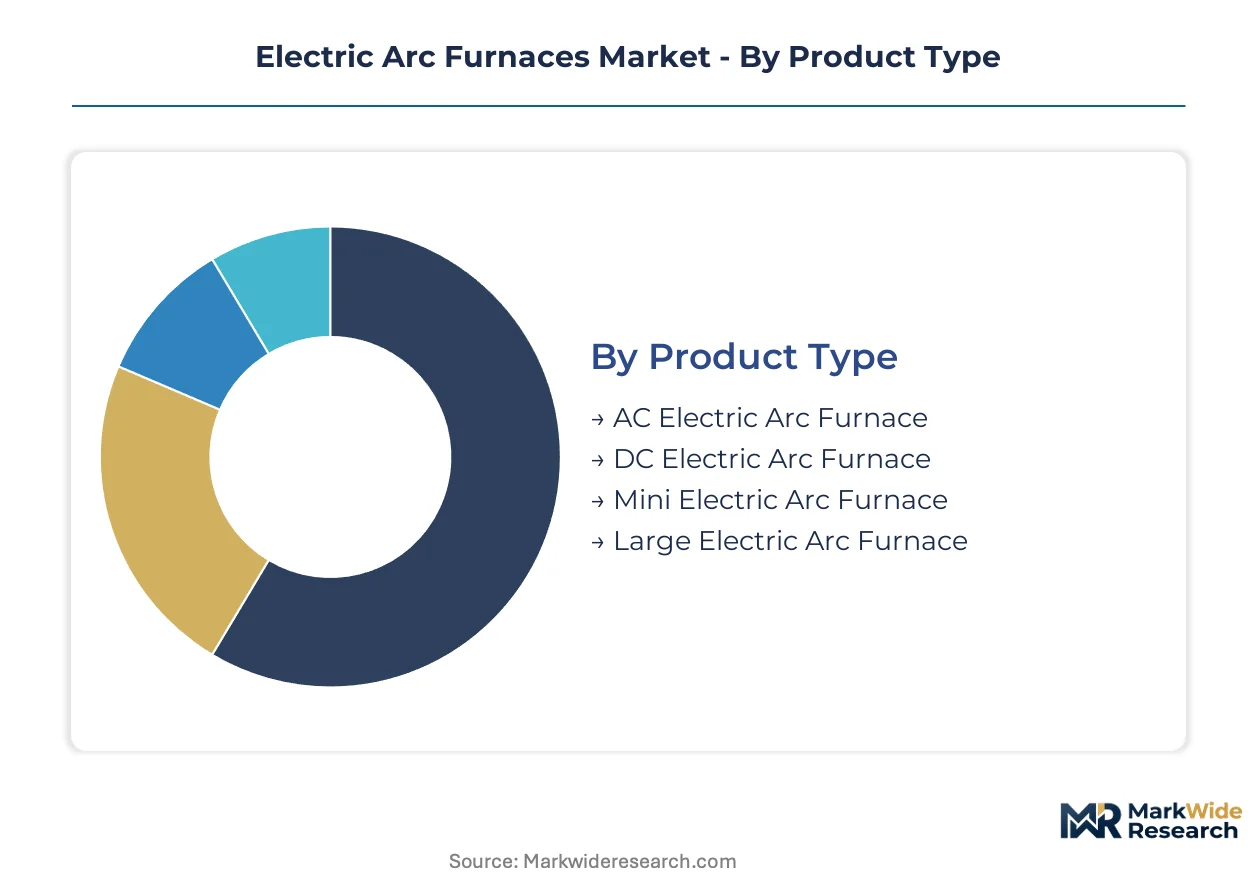
Electric arc furnace segmentation reveals how technical specifications align with feedstock chemistry, power grid constraints, and end-product quality requirements. Distinct furnace architectures serve different scales of steel production while technology tiers separate legacy operations from digitally integrated melt shops.
Product Type:
AC and DC architectures diverge on electrode economics and power quality, while capacity sizing reflects scrap availability and product mix strategy.
- AC Electric Arc Furnace:Three-phase alternating current systems dominate installed capacity through lower capital outlay and proven refractory designs. Steel producers in India and Poland favor AC units for long-product mills serving construction rebar demand.
- DC Electric Arc Furnace:Single electrode configurations cut graphite consumption by 40-50 percent and reduce flicker disturbances on weak grids. German and Japanese utilities mandate DC technology for connections above 100 MVA to stabilize distribution networks.
- Mini Electric Arc Furnace:Units below 50 tonnes per heat serve specialty alloy producers and regional scrap processors with limited feedstock radius.
- Large Electric Arc Furnace:300-400 tonne vessels anchor flat steel complexes requiring consistent chemistry for automotive exposed panels.
AC Electric Arc Furnace leads on scale; DC Electric Arc Furnace leads on momentum.
End User:
Customer segments separate commodity volume players from quality-sensitive specialty producers and circular economy enablers.
- Steel Manufacturing:Integrated mills and minimills produce construction longs and flat-rolled automotive grades. China's Baowu and Japan's Nippon Steel deploy EAF capacity to meet corporate carbon neutrality pledges ahead of regulatory deadlines.
- Metal Recycling:Dedicated scrap melters supply foundries and billet casters without downstream rolling assets. EU Circular Economy Action Plan mandates boost this segment's expansion trajectory across Italy, Spain, and the Netherlands.
- Foundries:Grey and ductile iron producers use smaller furnaces for engineered castings in automotive powertrain and agricultural equipment.
- Ferroalloy Production:Silicon and manganese alloy smelters require specialized slag chemistry control for deoxidant and desulfurizer markets.
Steel Manufacturing commands absolute volume; Metal Recycling climbs the fastest on policy tailwinds.
Technology:
Technology tiers distinguish power delivery methods and process control sophistication.
- Hybrid Technology:Combined oxygen-fuel burner and electrical heating cuts tap-to-tap times and power demand peaks. Brazilian mills deploy hybrid systems to manage grid constraints during dry-season hydroelectric shortfalls.
- Automated Control Systems:Real-time spectral analysis and predictive slag modeling optimize energy intensity. South Korean producers achieve sub-300 kWh per tonne through integrated sensor networks.
- Induction Heating:Auxiliary channel and coreless furnaces handle precise alloy adjustments and holding functions.
- Advanced Melting Technologies:Continuous charging and shaft furnace preheating recover waste gas energy for scrap preheating.
Automated Control Systems leads on margin capture; Hybrid Technology gains share fastest on energy cost pressure.
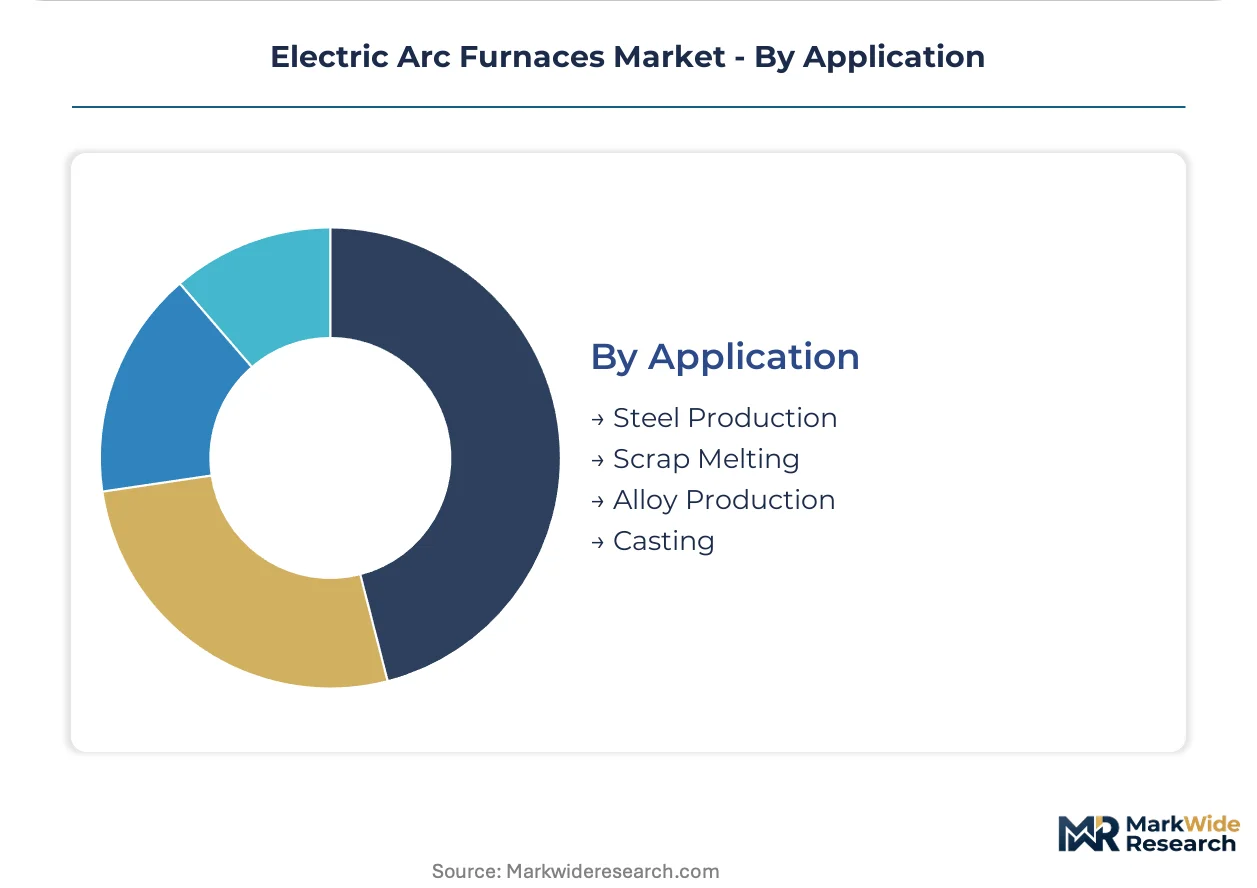
Application:
Application segmentation tracks how furnace output flows to distinct metallurgical transformation stages.
- Steel Production:Liquid steel for continuous casting of slabs, blooms, and billets constitutes the dominant value flow. Indian infrastructure programs drive demand for rebar and structural sections.
- Scrap Melting:Intermediate liquid metal supply to foundries and specialty steel producers without integrated melting. US demolition contractors feed this channel through regional aggregation hubs.
- Alloy Production:Stainless and tool steel grades requiring precise chromium, nickel, and molybdenum additions.
- Casting:Direct pouring into molds for ingots and engineered castings bypassing continuous casting.
Steel Production anchors revenue; Scrap Melting shows steepest expansion trajectory on circular economy mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors electric arc furnace deployment through Baowu's carbon neutrality investments and provincial ultra-low emission mandates. Steelmakers across five continents face diverging grid capacities, scrap availability, and carbon border pressures that reshape furnace economics.
China
Baowu Steel and Shagang Group expand EAF capacity to meet 2030 carbon peak commitments under MEE ultra-low emission deadlines. The Yangtze River and Beijing-Tianjin-Hebei clusters face mandatory retrofit timelines that accelerate furnace procurement. Jiangsu Province hosts the densest concentration of new AC and DC installations serving construction rebar demand.
India
JSW Steel and Tata Steel commission multi-million-tonne EAF complexes to supply national highway and rail corridor programs. The CEA mandates energy consumption norms for designated steel producers above specified output thresholds. Odisha and Karnataka emerge as greenfield EAF hubs with captive scrap aggregation infrastructure.
United States
Nucor and Steel Dynamics expand flat-rolled EAF capacity to capture automotive lightweighting contracts with recycled content thresholds. The EPA enforces Maximum Achievable Control Technology standards for particulate emissions from melt shop operations. Texas and Alabama host the fastest-growing EAF clusters with direct reduced iron integration.
Germany
Salzgitter and thyssenkrupp deploy DC furnace technology to stabilize grid connections above 100 MVA under utility mandates. The EU Carbon Border Adjustment Mechanism redirects import flows toward domestic EAF-sourced flat steel. North Rhine-Westphalia concentrates retrofit activity with hydrogen-reduced iron pilot coupling.
Japan
Nippon Steel and JFE Steel balance EAF investments against blast furnace asset life extensions under METI decarbonization roadmaps. Grid interconnection delays of eighteen to thirty-six months throttle brownfield expansion in industrial prefectures. Chubu and Kansai regions concentrate specialty steel EAF capacity for automotive exposed panel grades.
Electric Arc Furnaces Market Vendor Landscape
Global majors compete with regional champions across furnace architecture and digital integration depth. The vendor base stratifies into three tiers: full-line metallurgical equipment builders, electrical and automation specialists, and regional fabrication houses serving emerging markets. Consolidation pressures favor players with integrated secondary metallurgy packages and predictive maintenance platforms. Capacity expansion and technology licensing dominate competitive moves as scrap-based routes capture investment flows from carbon-intensive alternatives.
Among European full-line builders, Danieli & C. Officine Meccaniche S.p.A., Tenova S.p.A., and SMS group GmbH occupy positions defined by digital platform differentiation and AC or DC furnace specialization. Danieli exemplifies the automation-integrated archetype through melt shop energy optimization systems. Tenova represents the technology-licensing vector with furnace rebuild and upgrade service penetration. SMS group anchors the electrical systems tier with power delivery and harmonic filtering expertise for grid-sensitive installations. Primetals Technologies Limited sits within the quality-extension archetype, linking furnace output to flat steel grade requirements through secondary metallurgy integration.
| Leading Market Players |
|---|
| Siemens AG |
| Tenova S.p.A. |
| Danieli & C. Officine Meccaniche S.p.A. |
| China First Heavy Industries |
| Mitsubishi Heavy Industries Ltd. |
| SMS group GmbH |
| Electrotherm (India) Limited |
| Primetals Technologies Limited |
| Nippon Steel Corporation |
| Others |
Supply Flow & Price Mechanics
China's dual carbon goals and the EU's Carbon Border Adjustment Mechanism gate both qualified graphite electrode supply and premium-tier pricing access for furnace operators with verified low-carbon scrap provenance and ISO 14025-compliant Environmental Product Declarations. These sustainability mandates bifurcate the procurement landscape, rewarding integrated mills with traceability systems while exposing commodity producers to margin compression from carbon-adjusted import competition.
Pricing Analysis
Input-cost pass-through from graphite electrode volatility dominates furnace economics, with Chinese and Indian manufacturers controlling roughly seventy percent of global electrode capacity and exposing operators to export restriction risk. Price differentiation hinges on DC furnace premium positioning for grid-stability compliance and secondary metallurgy integration for flat steel grade output. Pricing pressure stems from scrap quality degradation elevating refining costs, while automotive OEMs with recycled content mandates show least price sensitivity versus construction rebar buyers.
Supply Chain Analysis
Single-source vulnerability sits with Chinese graphite electrode production and Indian scrap processing infrastructure, creating concentrated dependency for critical furnace inputs. Raw material flows draw from Australia iron ore, Middle East direct reduced iron pellets, and EU demolition scrap streams. Tariff exposure on electrode imports threatens cost predictability for North American operators. Distribution runs through regional equipment builders for furnace shells, electrical specialists for power delivery systems, and integrated metallurgical houses for turnkey melt shop packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electric Arc Furnaces Market functions as a geographic-arbitrage play where EU carbon border charges and China's ultra-low emission retrofit deadlines create divergent capital cost structures and margin profiles across steelmaking geographies.
For Market Incumbents: Anchor market position through backward integration into scrap aggregation infrastructure and captive DRI supply to offset electrode price volatility. Danieli and SMS group defend technology leadership by embedding predictive maintenance platforms into furnace automation architectures. Incumbents must secure grid interconnection priority in Germany and Japan where utility approval timelines throttle brownfield expansion. For New Entrants and Emerging Players: Capture white-space opportunity in India's Odisha and Karnataka greenfield corridors where national infrastructure programs justify multi-million-tonne EAF complexes without legacy blast furnace asset stranding. Foundry-grade mini furnace segments in Southeast Asia offer penetrable entry points with lower capital thresholds. New entrants should lead with hydrogen-reduced iron coupling to secure premium green steel contracts from automotive OEMs. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabrication houses lacking digital twin integration and secondary metallurgy packaging capability. Long-term viability across the projection horizon rests on scrap-based route economics displacing carbon-intensive integrated steelmaking. Investors should monitor EU Carbon Border Adjustment Mechanism implementation scope as the critical inflection signal for EAF capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Aggregation | JSW Steel and Tata Steel build captive collection infrastructure to secure feedstock radius and charge predictability. |
| DC Furnace Technology Licensing | SMS group GmbH transfers power delivery expertise to grid-constrained markets requiring flicker mitigation. |
| Hydrogen-Reduced Iron Pilot Coupling | Salzgitter and thyssenkrupp eliminate Scope 3 emissions through Hybrit-style DRI-EAF integration in North Rhine-Westphalia. |
| Digital Twin Platform Deployment | Danieli's Q-Smart system compresses energy intensity curves for South Korean mills holding consumption within three percent of theoretical minimums. |
| Long-Term Electrode Supply Agreement | Nucor and Steel Dynamics lock in graphite electrode offtake to insulate Texas and Alabama flat-rolled expansions from Chinese export restriction risk. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with melt shop managers, electrical engineers at furnace OEMs, scrap procurement leads at integrated mills, and utility interconnection planners with secondary validation from SEC filings, customs trade data, and national energy regulator disclosures. Bottom-up furnace shipment tallies and top-down steel capacity investment tracking were triangulated against regional carbon policy implementation schedules.
Segment-weighting approaches distributed value across AC and DC furnace architectures, capacity tiers from mini to large vessels, and technology tiers distinguishing hybrid burner systems from automated control platforms. CAGRs were derived from installed base replacement cycles and greenfield announcement pipelines across the analysis window, with scrap availability curves and grid interconnection timelines as steel-specific forecast inputs.
Electrode supply disruption, scrap export restriction enforcement, and carbon border adjustment scope expansion are the dominant revision risks that could compress or extend projected capacity deployment trajectories. Forecasts reflect documented assumptions about regulatory implementation timelines and technology cost curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Mexico Power Market
Power
Japan Power Market
Power
Power Rental Market
Power
Compact Substation Market
Power
Recloser Control Market
Power
Digital Power Utility Market
Power
Single-Phase Microinverter Market
Power
Saudi Arabia Power Market
Power
Spain Power Market
Power
Critical Power Market
Power
Robotic Power Source Market
Power
Smart PV Inverters Market
Power
Power Purchase Agreement Market
Power
Resonant Power Converters Market
Power
Electric Power Sports Market
Power
Kuwait Power Market