
 North America Oil Country Tubular Goods Market | 2026-2036
North America Oil Country Tubular Goods Market Size, Share, and Industry Trends Forecast 2026-2036
North America Oil Country Tubular Goods Market Analytics
Modular threading configurations with premium semi-premium couplings is shifting buyer preference away from standard API connections in high-pressure horizontal wells. Tenaris S.A. leverages its Bay City, Texas seamless mill to anchor North American supply for integrated operators. United States Steel Corporation sustains volume leadership in ERW line pipe through its Fairfield and Lone Star facilities. National-Oilwell Varco Inc. differentiates via proprietary double-shoulder connection technology for extended-reach drilling.
Oil country tubular goods comprise seamless and welded steel pipe products manufactured to API 5CT, API 5L, and proprietary specifications, with outer diameters ranging from 2.375 inches to 26 inches and wall thicknesses engineered to withstand internal pressures exceeding 15,000 psi in sour hydrogen sulfide environments. These products form the structural pressure envelope of hydrocarbon wells, isolating formation fluids from surrounding geology while enabling controlled production flow. Casing segments dominate value capture as operators drill deeper and deploy more strings per wellbore, while tubing demand tracks artificial lift installations in mature basins. Steel material grades command the majority of procurement spend, though composite liner trials in corrosive CO2 flood projects represent an emerging specialty niche.
API Monogram licensing and NACE MR0175/ISO 15156 sour-service standards govern product qualification across the United States and Canada, with PHMSA pipeline safety regulations further shaping line pipe specifications for gathering and transmission infrastructure. The EPA's methane emissions rules and state-level flaring restrictions in Texas Railroad Commission and New Mexico OCD jurisdictions indirectly stimulate workover activity and replacement tubing demand. Buyers must monitor API specification ballot revisions and evolving state casing integrity mandates as lateral lengths stretch beyond 15,000 feet.
Market Dynamics
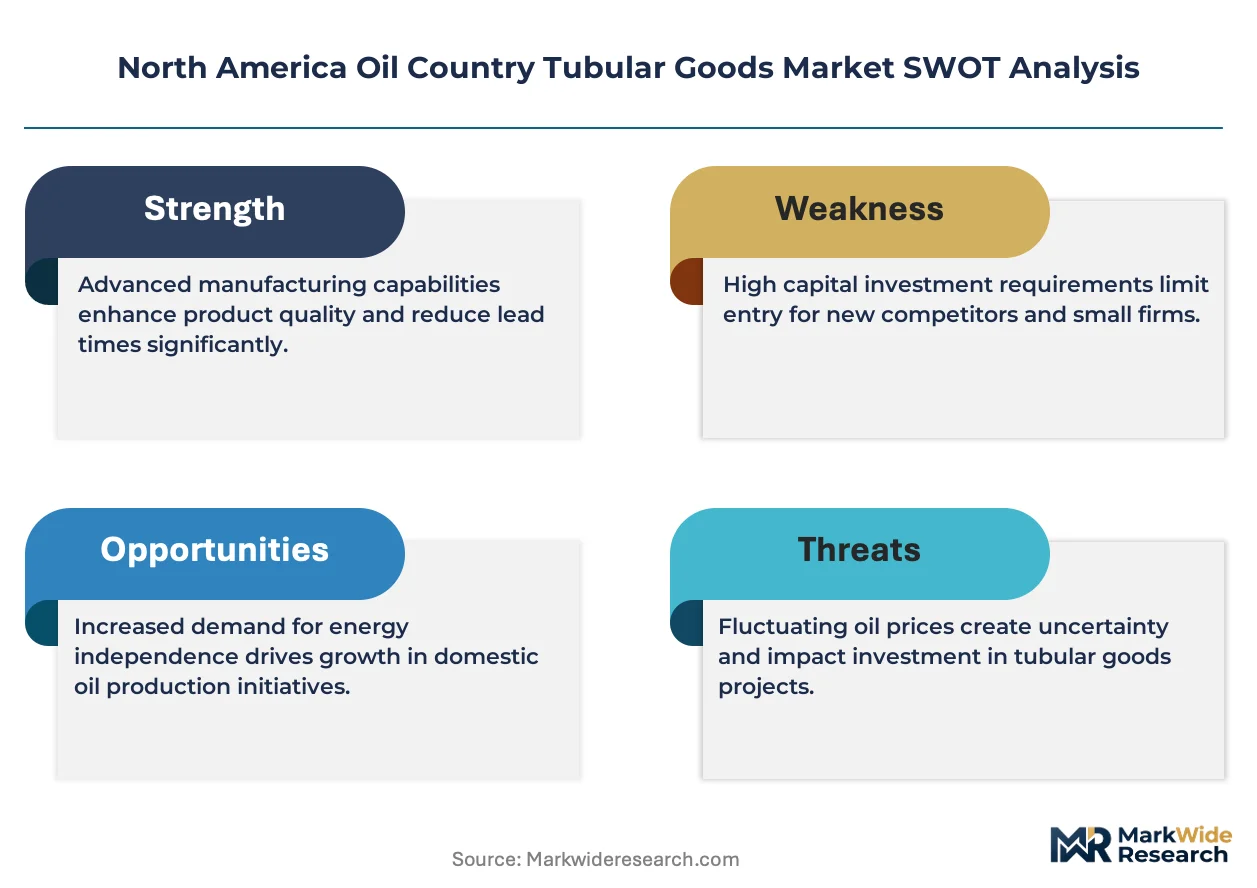
Horizontal drilling economics in the Permian Basin and Eagle Ford are compressing connection specification cycles as operators push laterals beyond three miles, forcing tubular goods suppliers to accelerate qualification timelines for premium threaded designs.
Growth Catalysts
- API 5CT Specification Revisions:Updated material grade requirements for sour-service environments are expanding addressable demand for high-alloy casing strings in hydrogen sulfide formations.
- Extended-Reach Horizontal Wells:Lateral lengths exceeding 15,000 feet in the Delaware Basin are multiplying casing strings per wellbore and driving premium connection adoption.
- Texas and New Mexico:Concentrated drilling activity in these states is absorbing surplus domestic seamless mill capacity and stabilizing regional pricing.
Market Restraints
- Scrap Steel Volatility:Electric arc furnace operators face margin compression when shredded scrap prices spike above $400 per ton, eroding seamless pipe cost competitiveness.
- Import Dependency for Specialized Alloys:Chromium and molybdenum supply concentration in South Africa and Kazakhstan exposes domestic mills to geopolitical disruption risk.
- NACE MR0175 Certification Bottlenecks:Limited third-party testing laboratory capacity in Houston and Calgary is extending qualification timelines for sour-service grades.
Strategic Opportunities
- Carbon Capture Injection Wells:Class VI well construction requirements under EPA Underground Injection Control rules are creating new demand for corrosion-resistant tubing in depleted oil fields.
- Geothermal Heat Pumps:Closed-loop geothermal systems in the Rocky Mountain states are absorbing surplus drilling equipment and tubular inventory during oil patch downturns.
- Composite Liner Trials:Hybrid carbon fiber-steel liners for CO2 flood projects in West Texas offer differentiation for suppliers with materials science capabilities.
Industry Challenges
- Connection Engineering Talent Scarcity:Retiring API thread design specialists and finite element analysts are constraining R&D velocity at mid-tier manufacturers.
- Legacy Mill Equipment Modernization:Converting seamless rolling mills for ultra-high-strength grades requires capital outlays exceeding $50 million per facility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Oil Country Tubular Goods Market |
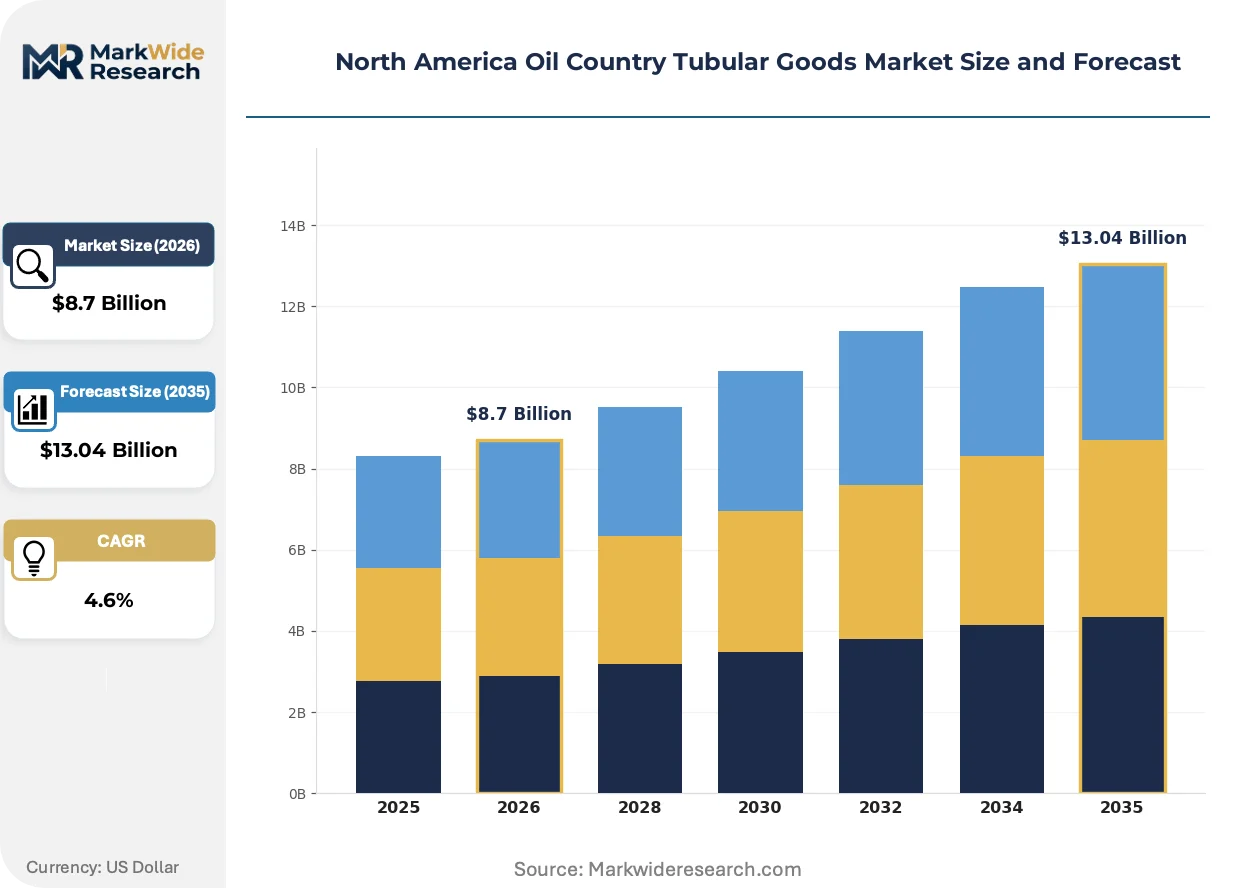
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drill Pipe, Casing, Tubing, Line Pipe Material: Steel, Aluminum, Composite, Others End User: Exploration, Production, Refining, Transportation Distribution Channel: Direct Sales, Wholesalers, Online Retail, Distributors |
| Companies Covered | United States Steel Corporation, TMK PAO, National-Oilwell Varco Inc., ArcelorMittal S.A., ILJIN Steel Co., Tenaris S.A., Nippon Steel Corporation, JFE Steel Corporation, Vallourec S.A., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Oil Country Tubular Goods Market Evolving Landscape
Premium threaded connection technology is fragmenting into modular, field-configurable designs that reduce inventory carrying costs while accommodating pressure ratings from 10,000 to 20,000 psi in a single coupling family.
Double-shoulder connection architecture is modularizing field assembly protocols by eliminating the need for separate torque-turn monitoring equipment. Operators in the Midland Basin are standardizing on these designs for multi-pad drilling programs where rig mobilization costs dominate economics. This standardization is compressing connection specification variety from twelve proprietary designs to four dominant platforms across the major independents.
EPA methane emissions regulations and Texas Railroad Commission flaring restrictions are tightening casing integrity requirements for new completions. These rules are accelerating workover activity in legacy Permian fields, stimulating replacement tubing demand for artificial lift conversions. Sour-service grades certified to NACE MR0175 are capturing disproportionate share in these remediation programs.
Integrated procurement contracts bundling casing, tubing, and accessories are displacing spot-market purchasing for multi-well development programs. Large independents in the Delaware Basin are consolidating supplier relationships to three-year framework agreements with volume commitments. This concentration is visible most acutely in Reeves County, Texas, where pad drilling economics favor single-source accountability over price competition.
North America Oil Country Tubular Goods Market Segmentation
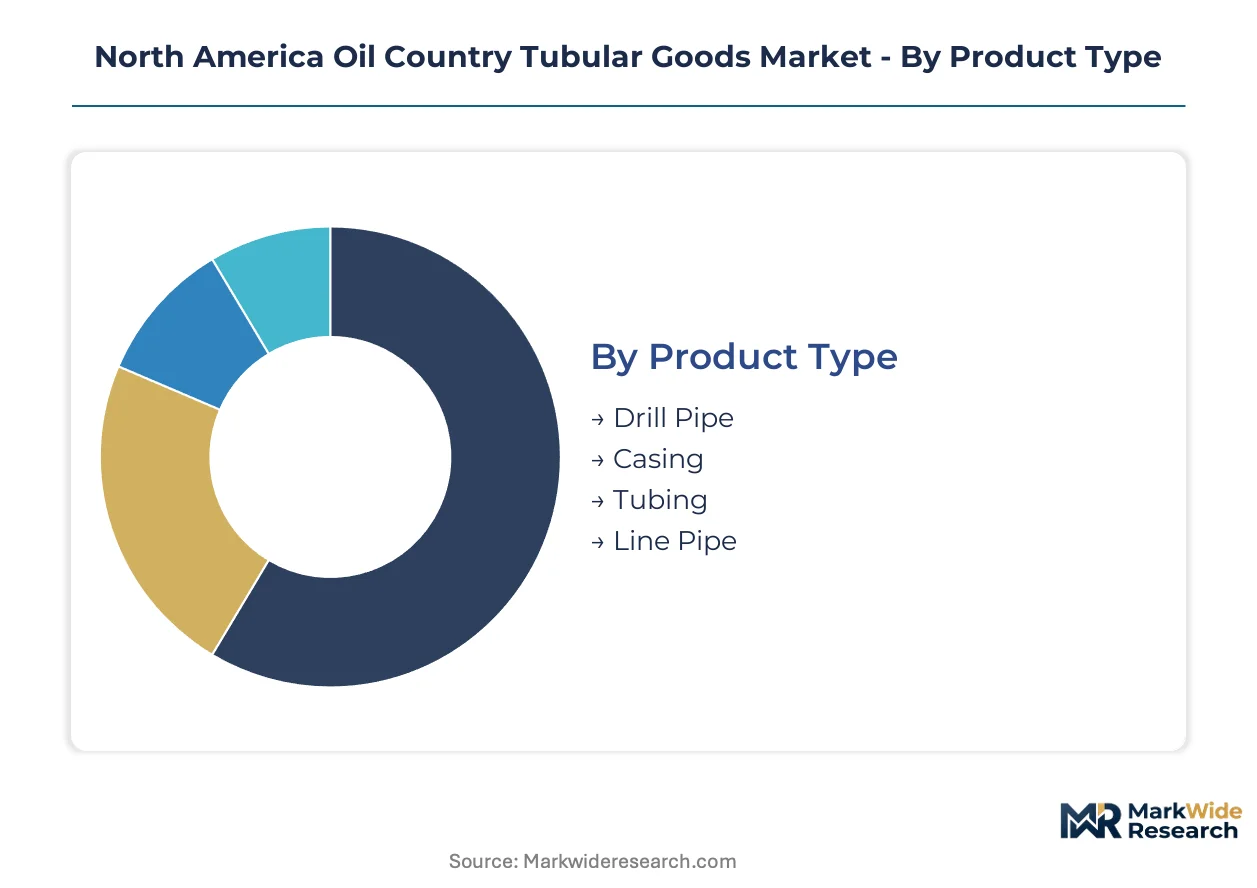
Segmentation in the North America Oil Country Tubular Goods Market reveals how upgrade cycles and replacement demand concentrate procurement spend across distinct technical specifications. Understanding these divisions enables suppliers to align mill capacity with the specific pressure ratings, material grades, and connection types dominating Permian Basin and Eagle Ford drilling programs.
Product Type:
Replacement and upgrade cycles in horizontal drilling operations concentrate procurement decisions around pressure envelope performance and connection reliability as laterals extend beyond three miles.
- Casing:Seamless and welded steel pipe forming the primary structural pressure barrier of the wellbore, manufactured to API 5CT specifications with outer diameters from 4.5 to 20 inches. Demand concentrates in Texas and New Mexico as operators deploy multiple casing strings per extended-reach well to isolate formation pressures exceeding 15,000 psi in sour hydrogen sulfide environments.
- Tubing:Production conduit installed inside casing to enable controlled hydrocarbon flow, subject to artificial lift conversions and workover activity in mature Permian fields. Sour-service grades certified to NACE MR0175 capture disproportionate share in remediation programs driven by EPA methane regulations and Texas Railroad Commission flaring restrictions.
- Drill Pipe:Heavy-wall seamless steel conduit transmitting torque and drilling fluid to the bit during horizontal drilling operations.
- Line Pipe:API 5L-specified pipe for gathering and transmission infrastructure connecting wellheads to processing facilities.
Volume placements concentrate in Casing; the faster expansion belongs to Tubing.
Material:
Cost tier differentiation in material selection separates premium sour-service applications from standard well construction as alloy pricing volatility reshapes procurement economics.
- Steel:Carbon and alloy grades dominating procurement spend across seamless and electric-resistance-welded manufacturing processes. Demand clusters in high-chromium, high-molybdenum grades for hydrogen sulfide resistance, though import dependency for these alloying elements from South Africa and Kazakhstan exposes domestic mills to supply disruption.
- Composite:Hybrid carbon fiber-steel liner systems trialed in CO2 flood projects across West Texas fields. These configurations offer corrosion resistance differentiation for suppliers with advanced materials science capabilities in carbon capture injection well applications.
- Aluminum:Lightweight alternative for specific corrosive environments requiring reduced string weight.
- Others:Specialty alloys and experimental materials for ultra-high-pressure or ultra-sour service conditions.
Steel commands the dominant placement volume; Composite is climbing the fastest as carbon capture infrastructure scales.
End User:
Application-driven segmentation separates exploration drilling demand from production maintenance and infrastructure replacement cycles across the well lifecycle.
- Production:Artificial lift installations, workover activity, and tubing replacement in mature basins sustaining recurring demand independent of new drilling cycles. EPA methane emissions rules and state-level flaring restrictions in Texas and New Mexico jurisdictions stimulate this segment through accelerated casing integrity remediation.
- Exploration:Greenfield drilling programs in the Delaware and Midland basins driving premium connection adoption for extended-reach horizontal wells. Multi-pad development programs favor integrated procurement contracts bundling casing, tubing, and accessories under three-year framework agreements.
- Refining:Downstream processing facility construction and maintenance requiring specialized pipe specifications.
- Transportation:Midstream gathering and transmission infrastructure subject to PHMSA pipeline safety regulations.
Production absorbs the highest placement volume; Exploration shows the steepest expansion trajectory.
Distribution Channel:
Customer type and procurement scale determine channel preference as integrated operators consolidate supplier relationships versus independent operators maintaining spot-market flexibility.
- Direct Sales:Mill-direct procurement by large independents and integrated operators in Reeves County, Texas and surrounding Delaware Basin counties. Three-year framework agreements with volume commitments displace spot purchasing for multi-well pad drilling programs requiring single-source accountability.
- Distributors:Regional inventory holders providing technical support and just-in-time delivery for smaller operators without captive supply chain infrastructure.
- Wholesalers:Volume aggregators serving mid-tier operators with standardized API connections and commodity grades.
- Online Retail:Digital procurement platforms for consumable items and standard specifications in non-critical applications.
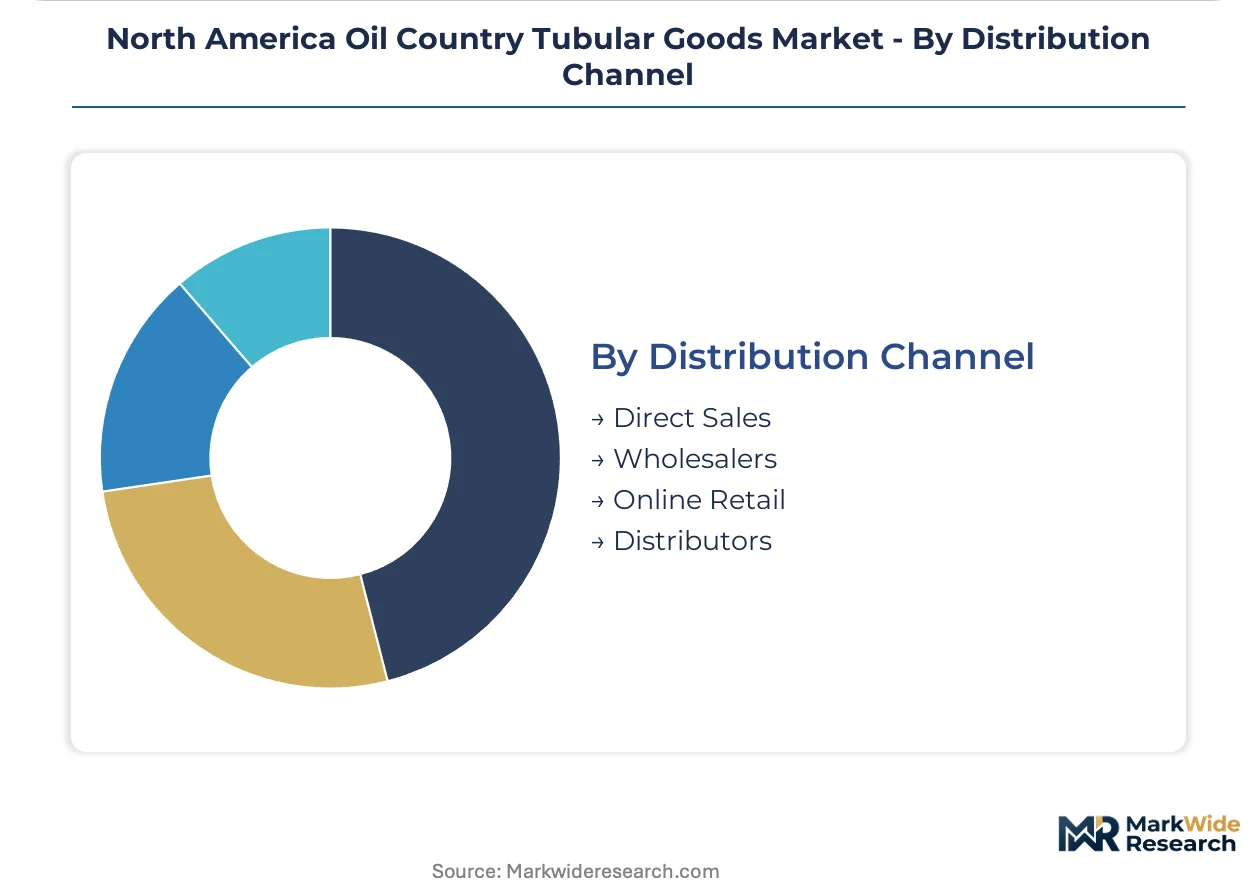
Direct Sales captures the dominant placement volume; Distributors are gaining share fastest among independent operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic seamless mill capacity concentrates in Texas and surrounding states while Canadian distributors and Mexican fabricators absorb overflow demand. United States production anchors North American supply, with cross-border trade flows shaped by tariff structures and specialized alloy requirements.
United States
Permian Basin drilling in Texas and New Mexico consumes the majority of premium casing strings as laterals stretch beyond 15,000 feet. EPA methane emissions rules and Texas Railroad Commission flaring restrictions accelerate workover activity and replacement tubing demand. Bay City, Texas hosts seamless mill capacity serving integrated operators with mill-direct procurement frameworks.
Canada
Alberta's oil sands and conventional drilling sustain steady casing demand despite slower growth than shale basins south of the border. NACE MR0175 certification bottlenecks in Calgary extend qualification timelines for sour-service grades destined for hydrogen sulfide formations. Distributors in Edmonton and Calgary hold regional inventory for operators without captive supply chain infrastructure.
Mexico
State-operator drilling programs and private investment in onshore conventional fields drive import dependency for specialized alloy grades. Energy reform implementation and Pemex procurement cycles shape demand timing for premium connections in deepwater exploration. Fabricators in Monterrey and Tamaulipas process imported seamless pipe for domestic oilfield service companies.
North America Oil Country Tubular Goods Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Steel manufacturers with integrated mining-to-pipe operations anchor supply for large independents, while mid-tier electric-resistance-welded producers capture line pipe and gathering system demand. Three archetypes dominate: seamless mill operators with captive alloy supply, ERW specialists serving midstream infrastructure, and technology licensors monetizing proprietary connection designs. Capacity expansion in Texas and strategic partnerships for sour-service qualification represent the dominant competitive vectors.
Among the seamless mill operators, Tenaris S.A. and United States Steel Corporation occupy positions shaped by geographic proximity to Permian demand. National-Oilwell Varco Inc. exemplifies the technology-licensing archetype through proprietary connection systems. TMK PAO and Vallourec S.A. represent European-originated conglomerates with North American distribution presence. ArcelorMittal S.A. anchors the diversified steel group with cross-sector mill flexibility.
| Leading Market Players |
|---|
| United States Steel Corporation |
| TMK PAO |
| National-Oilwell Varco Inc. |
| ArcelorMittal S.A. |
| ILJIN Steel Co. |
| Tenaris S.A. |
| Nippon Steel Corporation |
| JFE Steel Corporation |
| Vallourec S.A. |
| Others |
Value Network & Pricing Analysis
Integrated operators in the Delaware Basin anchor procurement volume through mill-direct framework agreements, concentrating pricing power with seamless mill operators possessing captive alloy supply. Three-year volume commitments displace spot-market purchasing for multi-pad drilling programs, compressing margin capture for distributors and mid-tier ERW producers.
Pricing Analysis
Margin tightening in premium sour-service grades reflects chromium and molybdenum import dependency from South Africa and Kazakhstan. Contract-based long-term offtake dominates large independents, while spot transactions persist among smaller operators lacking supply chain infrastructure. Price differentiation rests on NACE MR0175 certification tier and API Monogram licensing status. Smallest independents exhibit highest price sensitivity; integrated operators prioritize connection reliability over unit cost.
Supply Chain Analysis
Freight costs from South Africa and Kazakhstan for alloying elements compound margin pressure on domestic electric arc furnace operators. Seamless mill capacity concentrates in the United States, with Canadian distributors and Mexican fabricators absorbing overflow demand. Raw material inputs draw from shredded scrap, ferrochrome, and ferromolybdenum supply streams. Single-source vulnerability for specialized alloys exposes mills to geopolitical disruption. Distribution runs through mill-direct frameworks for large operators and regional inventory holders for independents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Limited third-party testing laboratory capacity in Houston and Calgary constrains sour-service grade qualification velocity, propping pricing for certified suppliers. This bottleneck sustains margin premiums for incumbents with established NACE MR0175 credentials.
For Market Incumbents: Cement market position through backward integration into alloying element supply chains and expansion of Houston-based testing partnerships. Accelerate mill equipment modernization for ultra-high-strength grades before connection engineering talent scarcity worsens. Defend against composite liner substitution threats in CO2 flood applications by investing in hybrid carbon fiber-steel R&D capabilities.
For New Entrants and Emerging Players: Capture share in carbon capture injection well tubing demand under EPA Class VI Underground Injection Control rules, where corrosion-resistant specifications create white-space opportunity. Target geothermal heat pump applications in Rocky Mountain states during oil patch downturns, absorbing surplus drilling equipment inventory. Pursue technology licensing arrangements with retiring API thread design specialists to bypass finite element analyst scarcity.
For Investors and Strategic Acquirers: Distressed-cycle entries favor electric arc furnace operators with scrap procurement flexibility in Texas and surrounding states, where regional pricing stabilizes against import volatility. Long-term viability hinges on Class VI well construction scaling and carbon capture infrastructure buildout. Monitor EPA methane emissions enforcement intensity and Texas Railroad Commission flaring restriction tightening as inflection signals for replacement tubing demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Seamless mill additions in Texas anchor supply for Permian Basin extended-reach drilling programs. |
| Backward Integration | Captive ferrochrome and ferromolybdenum supply mitigates South Africa and Kazakhstan disruption exposure. |
| Technology Licensing | Proprietary double-shoulder connection patents monetize R&D investment across multi-pad drilling standardization. |
| Long-term Supply Agreement | Three-year framework contracts with Delaware Basin operators displace spot-market volatility. |
| Joint Venture | Testing laboratory partnerships in Houston accelerate NACE MR0175 qualification timelines for sour-service grades. |
Research Methodology
API specification bulletins, EPA regulatory filings, and PHMSA pipeline safety records formed the secondary backbone, cross-referenced with customs data on chromium and molybdenum import flows. Primary interviews with seamless mill procurement directors, drilling engineers at Permian Basin operators, NACE certification laboratory managers, and electric arc furnace plant managers validated demand assumptions. Bottom-up and top-down triangulation reconciled well count projections with tubular goods consumption per lateral foot.
Bottom-up modeling segmented demand across casing, tubing, drill pipe, and line pipe categories, with further disaggregation by steel grade tier, connection type, and end-use application. Top-down validation employed energy sector capital expenditure patterns and rig count trajectories across the projection horizon. CAGRs derived from regression analysis against lateral length extension trends and well complexity indices. Forecast inputs incorporated API 5CT specification revision timing and state-level casing integrity mandate evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to scrap steel price volatility, alloying element supply disruption, and composite liner technology maturation. Forecasts reflect documented assumptions on lateral length extension rates and regulatory enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Well Cementing Market
Oil & Gas
Qatar Oilfield Chemicals Market
Oil & Gas
Downhole Tools Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Brazil Oil and Gas Midstream Market
Oil & Gas
Dry Natural Gas Market
Oil & Gas
Uzbekistan Oil and Gas Market
Oil & Gas
Qatar Oilfield Service Market
Oil & Gas
Kuwait Oil and Gas Upstream Market
Oil & Gas
Copper Mining Market
Oil & Gas
Microbial Enhanced Oil Recovery Market
Oil & Gas
Oil and Gas MIC Testing Market
Oil & Gas
Methane Hydrate Extraction Market
Oil & Gas
Chad Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Engineering Services Market
Oil & Gas
Flexible Pipes for Oil and Gas Market