
 Off-Grid Solar Generator Market | 2026-2036
Off-Grid Solar Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Grid Solar Generator Market Insights
Modular battery expansion packs paired with portable power stations is pivoting buyer choice toward scalable systems rather than fixed-capacity units. EcoFlow leverages proprietary X-Stream charging architecture to sustain premium positioning in the above-2000W residential segment. Jackery Inc. anchors its competitive stance through dominant Amazon marketplace presence and direct-to-consumer channel control. Renogy specializes in DIY solar kit bundling for off-grid cabin and RV applications, occupying a distinct niche between mass-market portability and professional installation.
An off-grid solar generator converts photovoltaic energy into stored electrical power through integrated solar panels, charge controllers, and battery banks, typically delivering AC output between 110V and 240V with pure sine wave inverters for sensitive electronics. These systems serve primary power needs in locations beyond grid infrastructure, from remote telecommunications towers to disaster relief field operations. Portable generators and backup systems command the largest revenue pools today, though hybrid systems incorporating wind or fuel cell augmentation represent the fastest-growing configuration as buyers seek multi-source reliability. The 1001-2000W capacity band captures disproportionate margin attention because it balances mobility with sufficient output for small commercial loads such as mobile medical clinics and construction site tools.
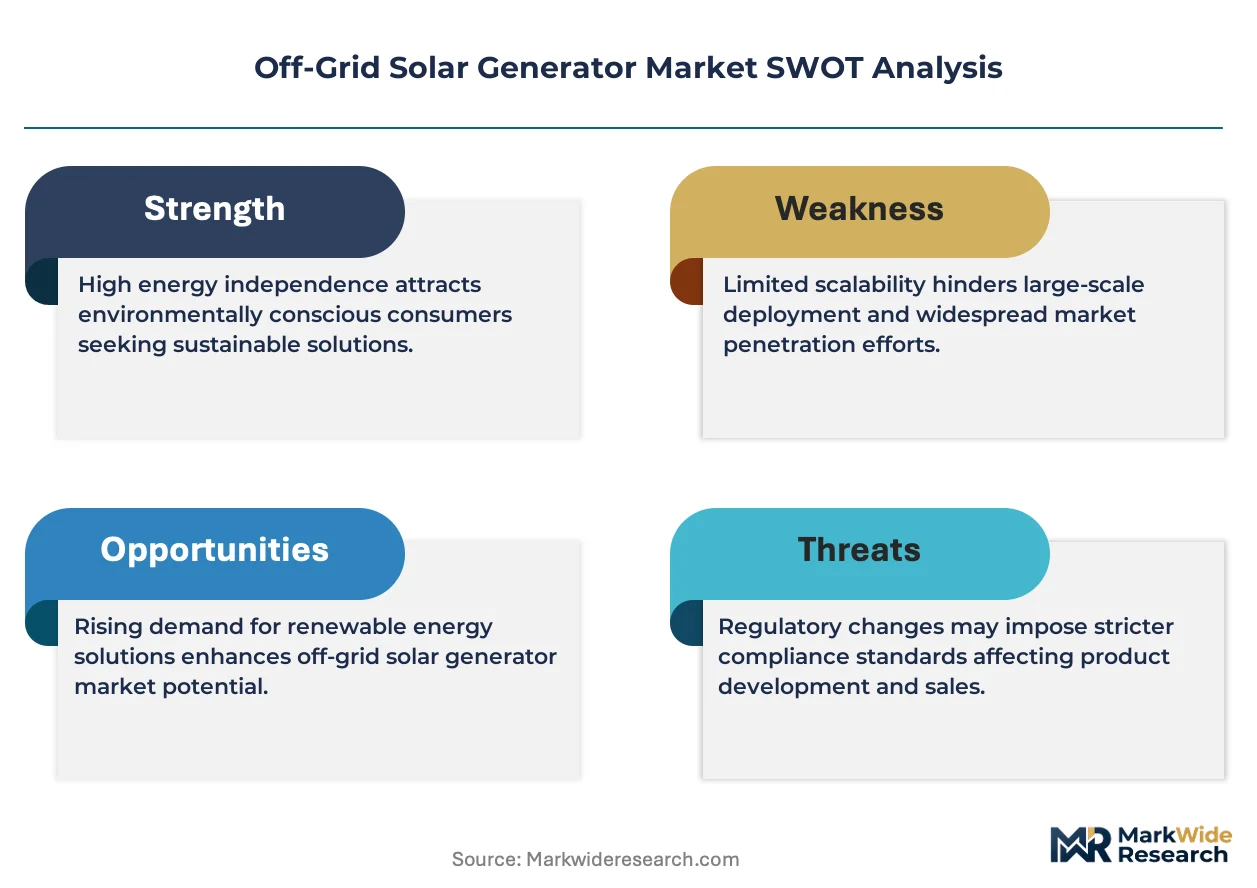
FCC certification requirements govern electromagnetic emissions for units sold in the United States, while EU Green Deal directives and CE marking obligations shape product efficiency benchmarks and recyclability mandates across European markets. India's BIS standards and MNRE off-grid solar program specifications determine eligibility for subsidy-backed rural electrification tenders, directly filtering which manufacturers access institutional procurement channels. Stakeholders must monitor evolving battery chemistry regulations and national storage incentive structures to anticipate which product configurations will retain market access.
Market Dynamics
Lithium iron phosphate battery chemistry is absorbing procurement preference from lead-acid configurations across mid-capacity off-grid solar generators, compressing incumbent supply chains and rewiring competitive positioning around energy density and cycle life metrics.
Growth Catalysts
- Rural electrification procurement:Kenya's Rural Electrification Authority and India's MNRE off-grid solar program specifications are channeling institutional budgets toward decentralized renewable energy systems for agricultural cooperatives and remote health clinics.
- Battery chemistry transition:Lithium iron phosphate configurations are displacing lead-acid in portable power stations, driven by thermal stability requirements and lifecycle cost advantages in tropical operating conditions.
- Hybrid system adoption:Wind and fuel cell augmentation is expanding addressable load profiles for telecommunications towers and disaster relief operations seeking multi-source reliability.
Market Restraints
- Input cost volatility:Lithium carbonate and cobalt price swings compress margin predictability for battery pack assemblers, particularly affecting the 1001-2000W capacity segment where cell costs dominate bill-of-materials.
- Supply concentration risk:Pure sine wave inverter semiconductor fabrication concentrates in East Asian foundries, exposing non-integrated generator manufacturers to lead time volatility and allocation constraints.
- Technical limitation:Energy density tradeoffs in solid-state battery alternatives delay commercialization timelines for sub-50kg portable units targeting military and emergency responder mobility requirements.
Strategic Opportunities
- Underpenetrated rural health infrastructure:Cold chain equipment electrification for vaccine storage in Nigerian primary health centers represents unmet demand for 500-1500W solar generator configurations with 48-hour autonomy.
- Regulatory tailwind:EU Green Deal recyclability mandates and extended producer responsibility frameworks are creating first-mover advantage for manufacturers with modular battery replacement architectures and closed-loop material recovery.
- Distribution innovation:Pay-as-you-go financing platforms are unlocking consumer adoption in East African informal settlements, displacing upfront capital barriers through mobile money-integrated hardware leasing.
Industry Challenges
- Certification timeline compression:FCC electromagnetic emissions testing and CE marking obligations for new battery chemistries extend product launch cycles, particularly for manufacturers pivoting from lead-acid to lithium iron phosphate platforms.
- Integration complexity:Legacy diesel generator interconnection standards and grid-forming inverter compatibility requirements complicate hybrid system deployment for commercial and industrial microgrids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Grid Solar Generator Market |
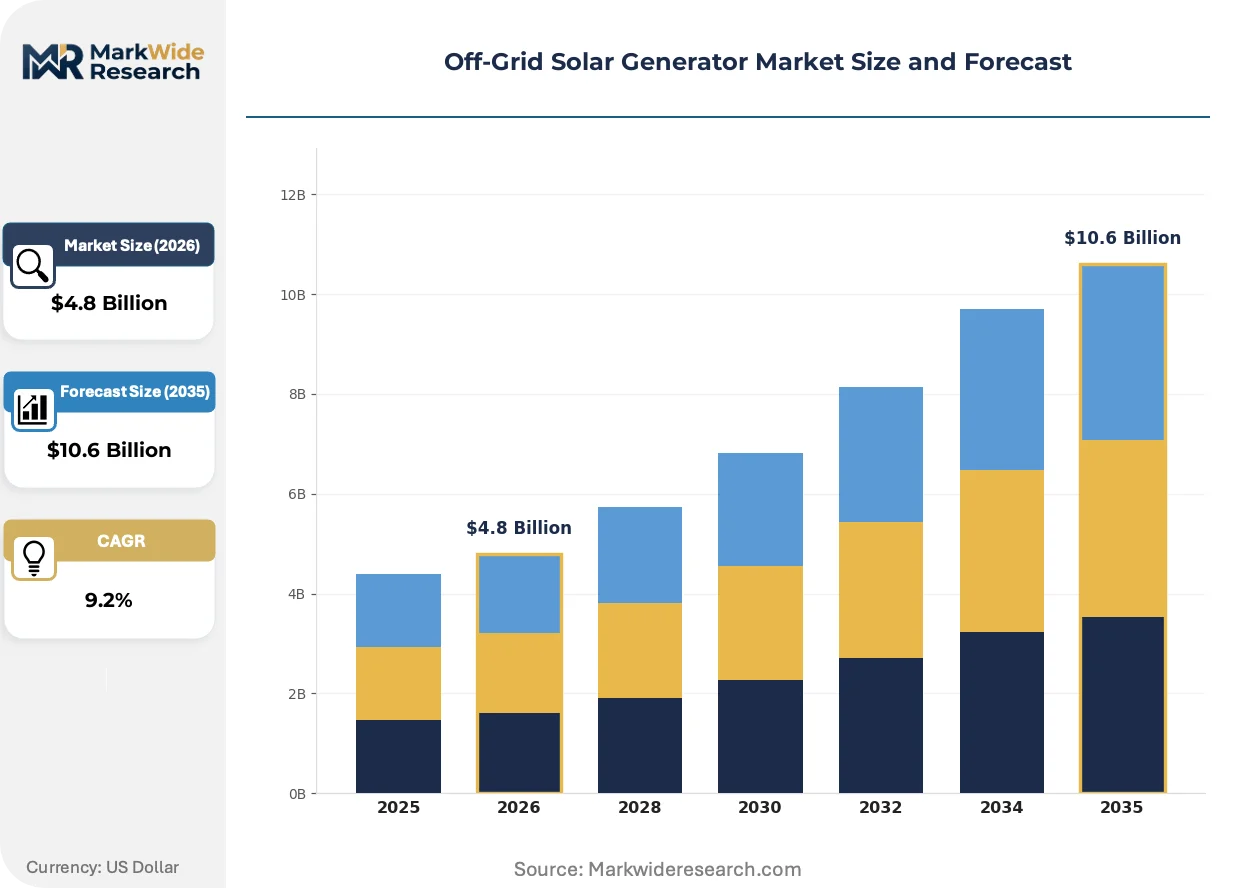
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Backup Systems, Hybrid Systems, Fixed Installations Capacity: 1-500W, 501-1000W, 1001-2000W, Above 2000W End User: Residential, Commercial, Industrial, Emergency Services Technology: Photovoltaic, Lithium-ion, Lead-acid, Smart Grid |
| Companies Covered | Goal Zero, Jackery Inc., BioLite, Bluetti, EcoFlow, Renogy, Anker Solix, Growatt, Powerenz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Grid Solar Generator Market Trends and Innovations
Product architecture is pivoting from fixed-capacity units toward scalable systems with modular battery expansion, while regulatory pressure on recyclability and supply chain transparency is reshaping design priorities and material selection criteria.
Solid-state battery research is absorbing venture funding and pilot manufacturing investment, though commercial deployment remains constrained by interface stability and manufacturing scale challenges. Telecommunications infrastructure operators and defense procurement agencies are tracking development timelines for field validation. This technology is absorbing technical risk capital that might otherwise flow to incremental lithium-ion improvements, stretching incumbents' R&D allocation decisions.
EU Green Deal battery passport requirements and CE marking recyclability mandates are forcing design-for-disassembly protocols and material provenance documentation across European market entry strategies. Manufacturers must reconfigure supply chain visibility systems to trace cobalt, lithium, and rare earth sourcing through tier-three suppliers. The 1001-2000W commercial segment faces disproportionate compliance burden given higher cell count and multi-source material aggregation complexity.
Buyer preference is rotating from ownership toward service-based access models, with agricultural cooperatives and remote clinic operators prioritizing uptime guarantees over hardware title. Equipment-as-a-service contracts with integrated maintenance and battery replacement clauses are displacing traditional distributor inventory sales in Kenyan and Nigerian procurement channels. This shift concentrates vendor selection criteria around regional service network density and spare parts logistics capability rather than unit cost alone.
Off-Grid Solar Generator Market Segmentation
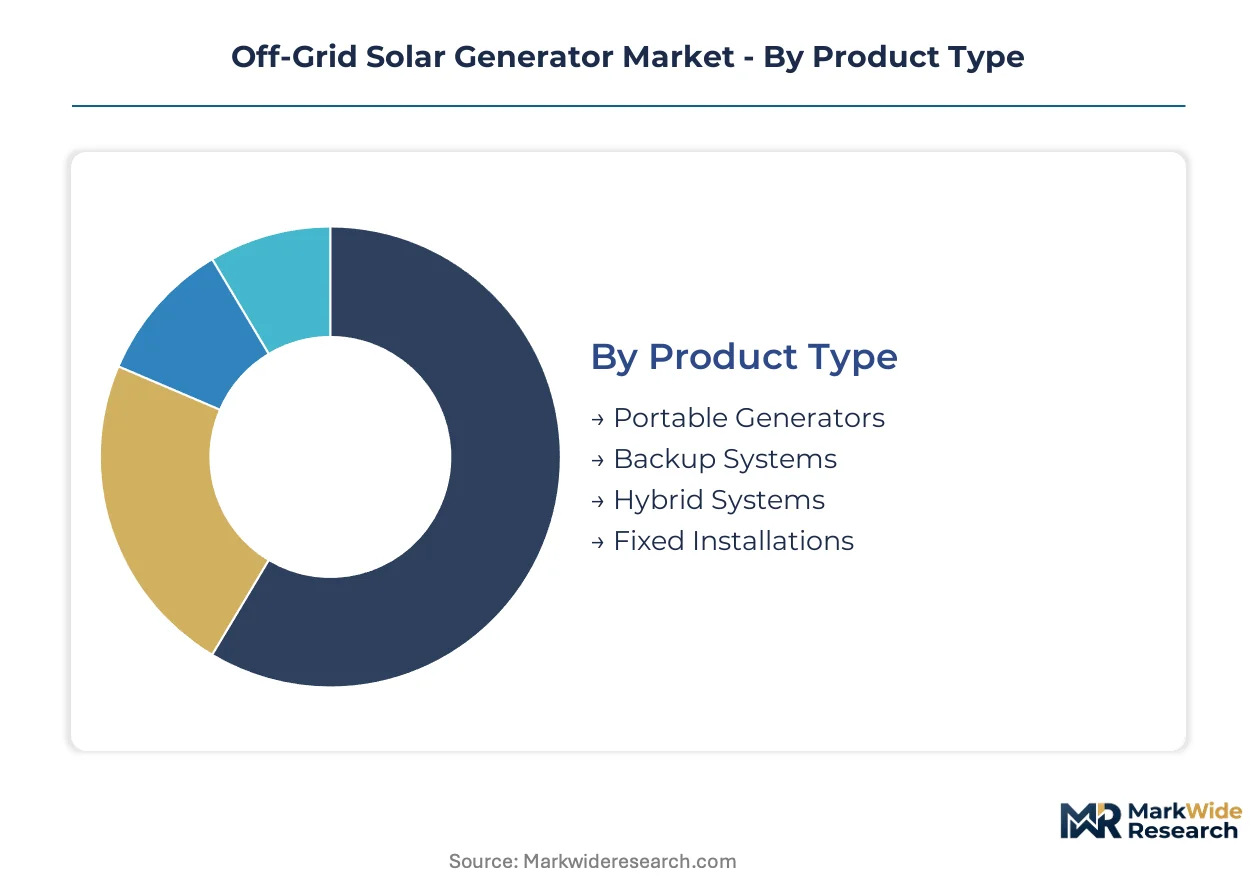
Segmentation reveals how procurement patterns diverge between mobility-driven applications and stationary infrastructure investments. Buyers in sub-Saharan Africa and rural India prioritize different configurations than disaster response agencies or telecommunications operators.
Product Type:
Standalone units dominate remote deployment scenarios where grid interconnection is impossible, while embedded systems integrate with existing diesel or wind infrastructure for commercial microgrids.
- Portable Generators:Self-contained units under 50kg with integrated panels and battery banks, designed for rapid deployment. Agricultural cooperatives in Kenya and mobile medical clinics in Nigeria concentrate procurement here due to transport constraints and intermittent relocation needs.
- Backup Systems:Stationary battery-inverter assemblies paired with roof-mounted photovoltaic arrays for grid-adjacent properties. Indian residential buyers in Bihar and Uttar Pradesh drive volumes through MNRE-subsidized rural electrification channels.
- Hybrid Systems:Multi-source configurations combining solar with wind turbines or fuel cells.
- Fixed Installations:Permanent ground-mounted or rooftop systems with concrete foundations and weatherized enclosures.
Backup systems lead volumes today; hybrid configurations are gaining share fastest.
Capacity:
Cost tiers separate consumer recreational purchases from commercial reliability investments, with mid-capacity bands capturing institutional procurement budgets.
- 1001-2000W:Commercial-grade systems balancing mobility with sustained output for power tools and medical equipment. Construction sites in Lagos and cold chain operations in Kenyan health centers anchor demand, with lithium iron phosphate chemistry displacing lead-acid for tropical cycle life requirements.
- 1-500W:Entry-level units for phone charging and LED lighting in off-grid households. Pay-as-you-go financing platforms in Nairobi and Kampala unlock adoption among informal settlement residents lacking upfront capital.
- 501-1000W:Mid-tier residential systems for small appliance loads.
- Above 2000W:Heavy-duty configurations for industrial and telecommunications applications.
The 1001-2000W band leads volumes today; sub-500W units are expanding most quickly through mobile money leasing.
End User:
Customer type determines whether procurement flows through government tenders, corporate capital expenditure, or consumer retail channels.
- Residential:Individual household purchases for primary electrification or backup power. Rural Indian families in Rajasthan and Maharashtra access units through state nodal agency distribution networks tied to MNRE off-grid solar specifications.
- Emergency Services:Rapid-deployment requirements for disaster relief and field operations. Nigerian National Emergency Management Agency and international NGOs stockpile portable configurations for flood and conflict response scenarios.
- Commercial:Small business and agricultural processing loads.
- Industrial:Mining operations and large-scale telecommunications infrastructure.
Residential leads volumes today; emergency services are climbing the fastest as climate adaptation budgets expand.
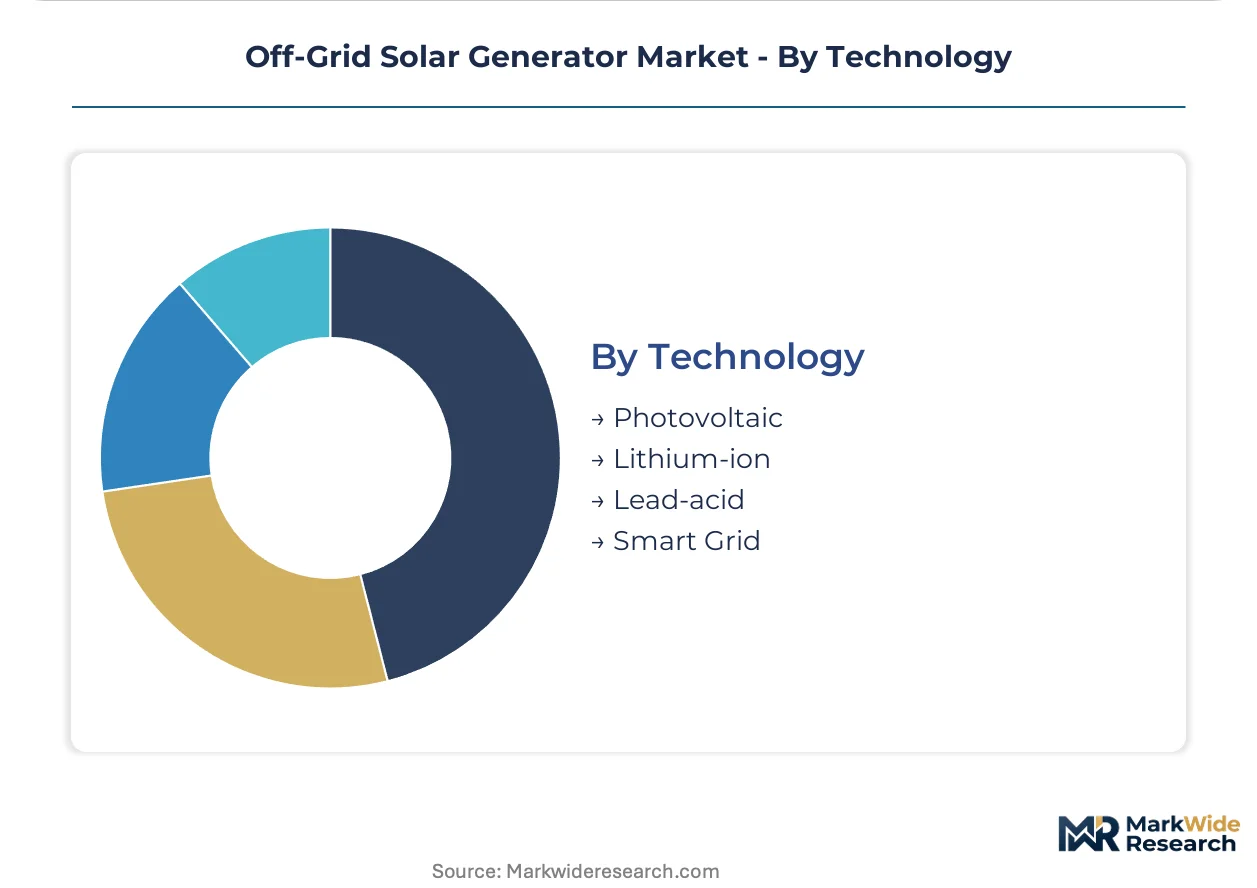
Technology:
Supply concentration around battery chemistry and inverter semiconductors creates divergent margin structures across technology platforms.
- Lithium-ion:Energy-dense cells with high cycle life, predominantly lithium iron phosphate for thermal stability. East Asian cell manufacturing concentration exposes non-integrated assemblers to allocation risk during demand surges.
- Photovoltaic:Crystalline silicon and thin-film panel technologies for energy capture. Kenyan Rural Electrification Authority tenders specify module efficiency thresholds that filter supplier eligibility.
- Lead-acid:Mature chemistry with lower upfront cost but reduced cycle life.
- Smart Grid:Grid-forming inverters with remote monitoring and load management capabilities.
Lithium-ion leads volumes today; smart grid integration is showing the steepest expansion trajectory as telecommunications operators prioritize uptime visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Off-grid solar generator manufacturing originated in Chinese industrial clusters before expanding through East Asian electronics supply chains into distributed assembly networks serving tropical electrification markets.
United States
FCC certification requirements govern electromagnetic emissions for portable power stations sold through Amazon and direct-to-consumer channels. California's SB 100 clean energy mandates and wildfire resilience programs channel procurement toward backup systems for grid-adjacent properties. The Los Angeles-San Diego corridor anchors distribution logistics for North American fulfillment.
China
Shenzhen and Dongguan manufacturing clusters supply lithium iron phosphate cells and pure sine wave inverters to global generator assemblers. MIIT battery safety standards and dual carbon goals accelerate domestic transition from lead-acid configurations. The Pearl River Delta concentrates R&D investment for solid-state battery pilot production targeting military mobility requirements.
India
MNRE off-grid solar program specifications filter supplier eligibility for subsidy-backed rural electrification tenders in Bihar and Uttar Pradesh. BIS standards determine product efficiency benchmarks for residential backup systems. Rajasthan's solar irradiance clusters anchor ground-mounted fixed installation deployment for agricultural processing loads.
Kenya
The Rural Electrification Authority channels institutional budgets toward portable generators for agricultural cooperatives and mobile medical clinics in Rift Valley and Eastern provinces. Pay-as-you-go financing platforms integrated with M-Pesa unlock consumer adoption in Nairobi and Kampala informal settlements. Mombasa port logistics concentrate import distribution for East African procurement channels.
Germany
EU Green Deal battery passport requirements and CE marking recyclability mandates reshape design-for-disassembly protocols for modular battery expansion systems. REACH and RoHS obligations filter material provenance documentation through tier-three supplier networks. Bavarian industrial automation clusters support precision manufacturing for grid-forming inverter components.
Off-Grid Solar Generator Market Competitive Landscape
Premium-margin players sit above commodity-margin players across battery chemistry sophistication and charging architecture differentiation. The vendor base organizes into three tiers: integrated cell manufacturers with captive semiconductor sourcing, pack assemblers dependent on external inverter supply, and brand marketers outsourcing entire bill-of-materials. Strategic archetypes include fast-charging technology specialists, DIY solar kit bundlers, and Amazon-native direct-to-consumer operators. Dominant competitive moves center on modular battery architecture licensing and pay-as-you-go financing platform partnerships.
Within the premium-tier charging architecture segment, EcoFlow and Jackery Inc. exemplify divergent channel strategies—one sustaining technical differentiation through proprietary X-Stream systems, the other anchoring volume through marketplace presence. Renogy occupies a position between mass-market portability and professional installation, representing the DIY solar kit bundler archetype for off-grid cabin and RV applications. These three companies illustrate how competitive positioning fragments across technical specialization, channel control, and niche application focus.
| Leading Market Players |
|---|
| Goal Zero |
| Jackery Inc. |
| BioLite |
| Bluetti |
| EcoFlow |
| Renogy |
| Anker Solix |
| Growatt |
| Powerenz |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap pack assemblers in Dongguan and Shenzhen anchor supply-side discipline through captive lithium iron phosphate cell sourcing, translating upstream concentration into pricing power for modular expansion systems while compressing margins for non-integrated brand marketers dependent on spot-market procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates X-Stream fast-charging architectures from generic inverter platforms and entry-level lead-acid alternatives. Price differentiation rests on FCC certification tier and cycle life guarantees, with thermal stability specifications commanding premium positioning. Cost compression in the sub-500W entry tier is intensifying because M-Pesa-integrated pay-as-you-go financing shifts buyer focus from unit cost toward monthly payment thresholds. Agricultural cooperatives in Kenya exhibit highest price sensitivity; telecommunications operators in Nigeria prioritize uptime guarantees over capital expenditure.
Supply Chain Analysis
Freight cost volatility through Mombasa and Lagos ports is reshaping inventory positioning for East African distribution. Lithium iron phosphate cell fabrication concentrates in China, South Korea, and Japan, with pure sine wave inverter semiconductors drawing from Taiwanese foundries. Raw material dependencies span lithium carbonate, cobalt sulfate, and rare earth magnets for magnetic components. Single-source vulnerability in East Asian semiconductor fabrication exposes non-integrated assemblers to allocation constraints during demand surges. Distribution runs through MNRE-authorized nodal agencies in India and Rural Electrification Authority tender channels in Kenya.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU Green Deal battery passport compliance costs in Germany create margin headroom for manufacturers with established material provenance systems versus competitors scrambling to retrofit supply chain visibility.
For Market Incumbents: Anticipate solid-state battery commercialization timelines by locking lithium iron phosphate supply agreements through 2030, while defending against pay-as-you-go financing platforms through direct M-Pesa partnership integration. Certification investment in BIS standards and MNRE specifications filters competitor access to Indian institutional procurement. Channel control through Amazon marketplace dominance anchors volume retention against DTC-native challengers. For New Entrants and Emerging Players: Capture cold chain electrification for Nigerian primary health centers, where 48-hour autonomy requirements and 500-1500W specifications remain underpenetrated by incumbent portable specialists. Mobile medical clinic operators in sub-Saharan Africa represent the most penetrable buyer archetype, lacking established vendor relationships with construction-grade suppliers. Go-to-market execution should anchor on equipment-as-a-service contracts with integrated battery replacement clauses rather than unit sales. For Investors and Strategic Acquirers: Valuations sit cheapest among pack assemblers with backward integration into cell manufacturing but without captive semiconductor sourcing, as inverter allocation risk discounts their enterprise value relative to fully integrated competitors. Long-term viability over the five-to-ten year window hinges on modular architecture licensing revenue streams displacing hardware margin dependence. Watch solid-state battery pilot production announcements from Pearl River Delta manufacturers as the inflection signal for chemistry transition timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Battery Architecture Licensing | Generates recurring revenue from EcoFlow and Jackery Inc. competitors seeking scalable expansion compatibility. |
| Pay-as-you-Go Financing Platform Partnership | Unlocks M-Pesa-integrated consumer adoption in Nairobi informal settlements lacking upfront capital. |
| Backward Integration into LFP Cell Production | Reduces lithium carbonate price exposure for 1001-2000W commercial segment assemblers. |
| EU Battery Passport Compliance Program | Secures first-mover advantage in German and French markets under Green Deal recyclability mandates. |
| Cold Chain Electrification Product Line | Targets Nigerian National Primary Health Care Development Agency vaccine storage procurement specifications. |
Research Methodology
Multiple input streams — primary interviews with Rural Electrification Authority procurement officers, MNRE nodal agency distribution managers, and lithium iron phosphate cell manufacturing executives; secondary validation through BIS standards documentation, Kenya Power grid interconnection data, and SEC filings from listed energy storage companies; plus customs trade records from Mombasa and Lagos ports — were reconciled through bottom-up unit shipment modeling and top-down addressable market sizing.
Segmentation-level projections across product type, capacity band, battery chemistry, and end-user category were developed through elasticity analysis of historical MNRE tender awards and Kenyan agricultural cooperative procurement patterns, with CAGR derivation anchored in rural electrification budget allocation trajectories and pay-as-you-go financing penetration curves. Solid-state battery commercialization timelines and cobalt price volatility scenarios served as sensitivity inputs.
Lithium carbonate price swings, East Asian semiconductor foundry allocation constraints, and EU Green Deal implementation timing are the dominant revision risks to installed base forecasts. Stakeholders should weight assumptions against their own operating context and supply contract structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Australia Solar Market
Solar Power Systems
Greece Renewable Energy Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Flat Plate Solar Collector Market
Solar Power Systems
Solar Laminator Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Off-Grid Solar Lighting Market
Solar Power Systems
Solar PV Junction Box Market
Solar Power Systems
Solar Collector Panels Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market
Solar Power Systems
Floating Solar System Market
Solar Power Systems
AR Photovoltaic Glass Market
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
Global Micro Solar Inverter Market
Solar Power Systems
Venezuela Solar Energy Market