
 Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market | 2026-2036
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market Outlook
Marine equipment leasing channels is rewriting how seismic contractors access capital-intensive streamer and source arrays. CGG SA leverages its multi-client library to sustain cash flow without full asset ownership. Schlumberger Ltd. anchors integrated seismic-to-drilling workflows through proprietary acquisition platforms. TGS ASA competes by dominating data licensing in frontier basins where exploration companies prefer risk-shared survey models.
Offshore oil and gas seismic equipment encompasses air guns, geophones, streamers, and hydrophone arrays designed to generate and record acoustic reflections from subsurface geological formations, with systems typically operating at depths exceeding 3,000 meters and pressure tolerances above 300 bar for deepwater deployment. The primary commercial purpose involves de-risking hydrocarbon exploration by mapping reservoir geometry, porosity, and fluid content before capital-intensive drilling commitments. 3D seismic technology leads absolute revenue generation due to its established role in field development planning, while 4D seismic represents the fastest-expanding segment as operators prioritize reservoir monitoring over greenfield discovery. Multi-client surveys concentrate margin pools through pre-funded acquisition models that shift exploration risk from contractors to data purchasers.
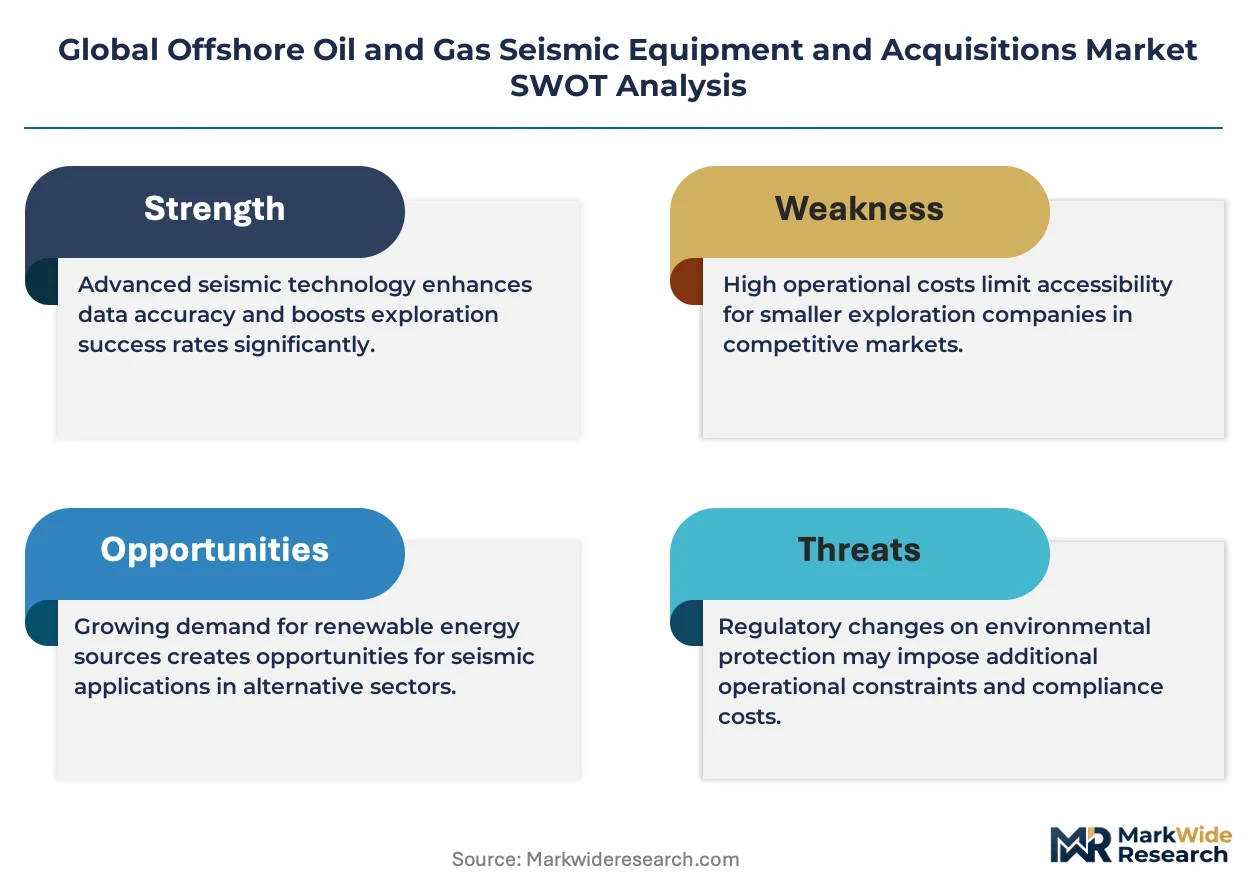
The US Bureau of Ocean Energy Management enforces strict marine mammal observation protocols that constrain air gun operational windows and elevate equipment redundancy requirements. Norway's Petroleum Safety Authority mandates continuous seismic source calibration documentation, shaping manufacturer service revenue streams. The EU Marine Strategy Framework Directive imposes noise pollution thresholds that accelerate demand for reduced-impulse source technologies. Stakeholders must monitor how regulatory fragmentation between the Gulf of Mexico, North Sea, and Brazilian regulatory zones reshapes equipment certification standards and survey economics.
Market Dynamics
Deepwater exploration economics are compressing survey cycle times, forcing contractors to deploy denser receiver arrays and real-time processing architectures that trade capital intensity for faster reservoir characterization turnaround.
Growth Catalysts
- Brazil's pre-salt province:Petrobras and international operators sustain multi-year seismic commitments that absorb high-capacity streamer fleets. Basin complexity demands repeated 4D monitoring surveys.
- EU F-Gas Regulation:Phase-down mandates for hydrofluorocarbons in marine acoustic systems are accelerating equipment replacement cycles. Manufacturers redesign source arrays to comply with tightening emission thresholds.
- 4D seismic technology:Reservoir monitoring applications displace greenfield discovery as the primary value driver. Operators prioritize production optimization over exploration risk in mature basins.
Market Restraints
- Specialized vessel scarcity:Ice-class and dynamically positioned seismic ships concentrate among Nordic and Asian shipyards. Newbuild delivery timelines extend beyond thirty-six months.
- Marine mammal observation protocols:The US Bureau of Ocean Energy Management constrains air gun operational windows through mandatory observer coverage. Survey economics suffer from intermittent shutdowns.
- High-density streamer costs:Solid-state hydrophone arrays and multi-sensor streamers require capital outlays that strain contractor balance sheets. Leasing channels partially offset ownership burdens.
Strategic Opportunities
- Reduced-impulse source technologies:Marine vibroseis and alternative acoustic generators address EU Marine Strategy Framework Directive noise thresholds. Early movers capture regulatory preference in North Sea licensing rounds.
- Multi-client survey models:Pre-funded acquisition shifts exploration risk from contractors to data purchasers. Frontier basins in West Africa and the Eastern Mediterranean attract risk-shared capital.
- Integrated seismic-to-drilling workflows:Proprietary acquisition platforms anchor full-field development decisions. Service bundling deepens contractor relationships with national oil companies.
Industry Challenges
- Geophysicist talent scarcity:Specialized processing expertise for full-waveform inversion and depth migration concentrates among aging practitioner cohorts. Training pipelines fail to replenish technical depth.
- Legacy data integration:Decades of 2D and early 3D surveys resist reprocessing into modern interpretive frameworks. Asset owners face sunk-cost dilemmas on data refresh decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market |
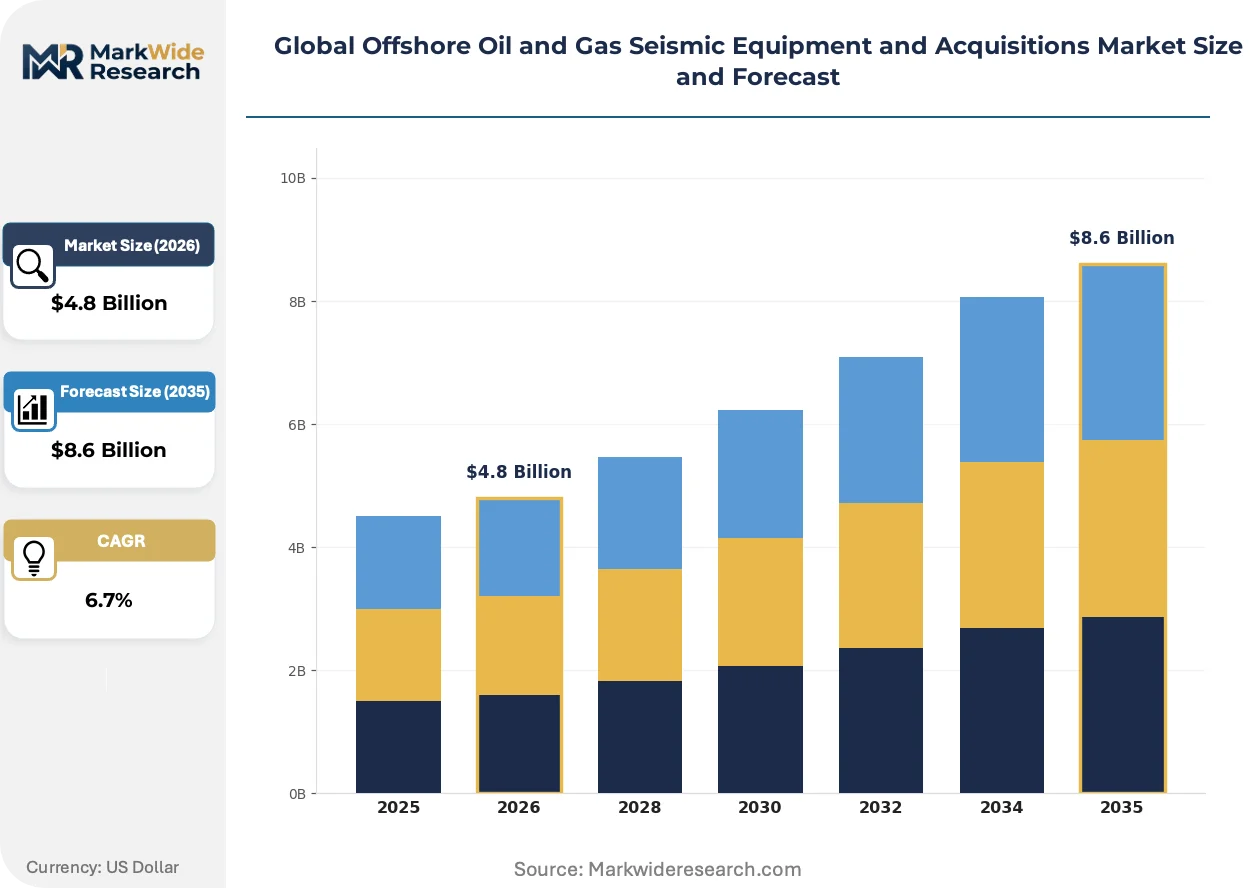
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Guns, Geophones, Streamers, Hydrophone Arrays Technology: 2D Seismic, 3D Seismic, 4D Seismic, Multi-Client Surveys Installation: Fixed, Mobile, Semi-Submersible, Drillships End User: Exploration Companies, Service Providers, Government Agencies, Research Institutions |
| Companies Covered | CGG SA, Magseis Fairfield, Schlumberger Ltd., Geospace Technologies, SAExploration Holdings Inc., PGS (Petroleum Geo-Services), China Oilfield Services Limited, ION Geophysical Corporation, TGS ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market Strategic Shifts
Marine seismic acquisition is undergoing a sensor-density revolution that compresses survey duration while expanding subsurface illumination. Contractors and operators are renegotiating risk allocation as technology shifts reshape economic boundaries.
Digital twin architectures are digitizing vessel, source, and streamer performance through continuous telemetry feedback. Deepwater contractors deploy these systems to optimize sail-line efficiency and predict maintenance intervals. Real-time quality control is compressing the gap between data acquisition and preliminary interpretation deliverables.
The EU Green Deal and tightening F-Gas Regulation are mandating refrigerant phase-downs in marine acoustic source cooling systems. Equipment manufacturers face redesign imperatives for air gun compressor units and associated thermal management hardware. Norwegian and UK North Sea operators are prioritizing compliant equipment in tender evaluations, accelerating fleet refresh cycles.
Exploration companies are unbundling after-sales processing from acquisition contracts, treating seismic data as a tradable asset rather than a service output. Multi-client libraries and data marketplaces are displacing proprietary survey ownership in frontier basins. This pattern is most visible in Brazil and West Africa, where international operators prefer licensing pre-existing broadband data over commissioning new shoots.
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market Segmentation
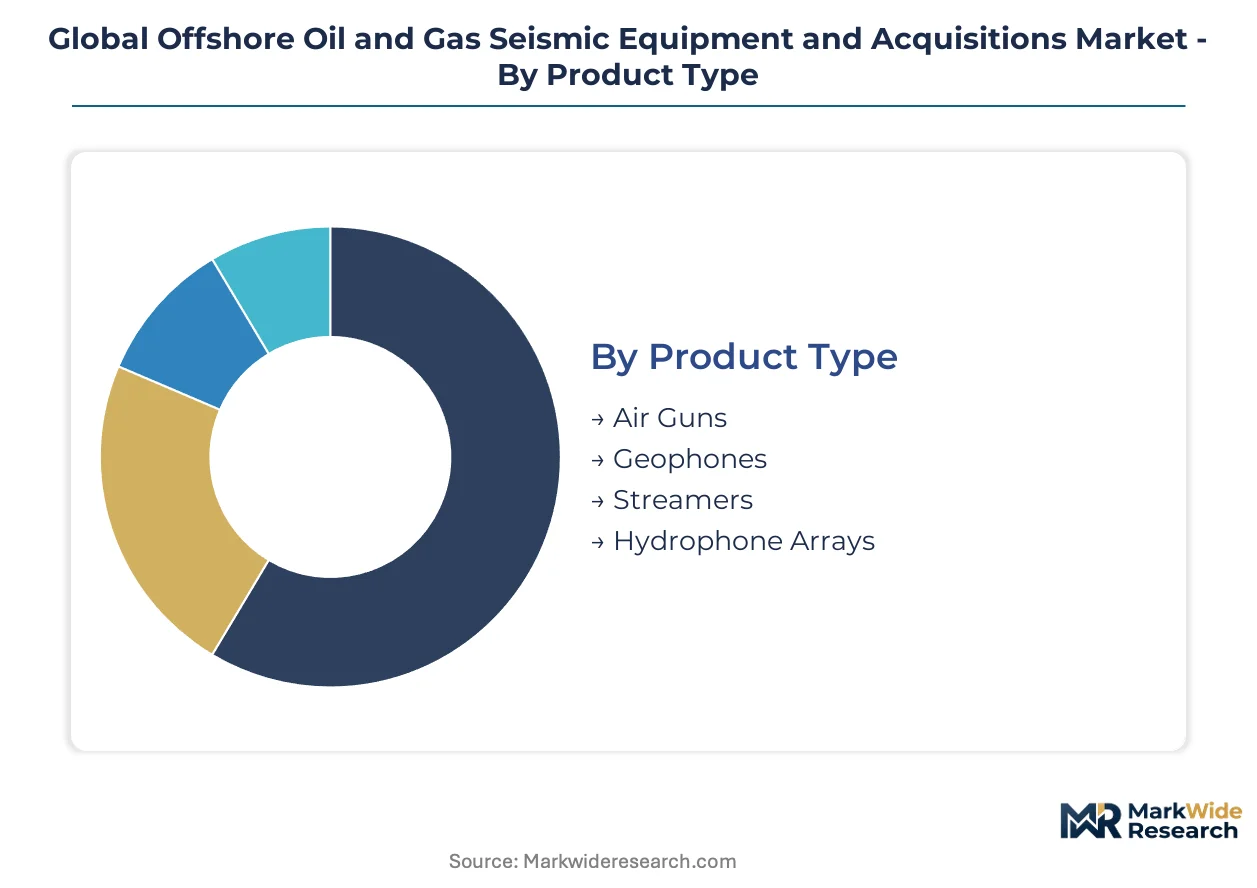
Seismic equipment segmentation reflects divergent capital deployment strategies across exploration phases. Contractors balance ownership economics against leasing flexibility while operators prioritize reservoir monitoring over greenfield discovery.
Product Type:
Equipment selection traces water depth, source energy requirements, and vessel integration constraints.
- Air Guns:Compressed nitrogen or compressed air systems generate high-amplitude acoustic pulses for deep-penetration surveys. Petrobras pre-salt operations in Brazil sustain demand for large-volume tuned arrays capable of 3,000-meter penetration.
- Streamers:Solid-state hydrophone arrays with pressure tolerances exceeding 300 bar dominate deepwater deployment. Norway's North Sea operators favor multi-sensor streamers combining hydrophone, geophone, and accelerometer elements for full-waveform inversion processing.
- Geophones:Velocity sensors deployed in ocean-bottom cable configurations for permanent reservoir monitoring installations.
- Hydrophone Arrays:Pressure-sensitive detectors forming the acoustic sensing backbone of towed marine streamers.
Established volume favors streamers; emerging adoption favors air gun retrofits for reduced-impulse compliance.
Technology:
Survey dimensionality determines data resolution, repeatability economics, and contractor revenue models.
- 3D Seismic:Multi-azimuth acquisition with dense receiver spacing generates volumetric subsurface models for field development planning. Brazil's pre-salt province absorbs the majority of high-capacity 3D shoots.
- 4D Seismic:Time-lapse monitoring tracks fluid displacement, pressure depletion, and gas cap expansion across production cycles. North Sea mature basins drive replacement of legacy 3D surveys with repeatable 4D acquisition.
- 2D Seismic:Single-sail-line reconnaissance surveys for frontier basin screening.
- Multi-Client Surveys:Pre-funded acquisition models shift exploration risk to data licensees.
Revenue concentration anchors 3D seismic; steepest expansion trajectory belongs to 4D reservoir monitoring.
Installation:
Platform mobility dictates operational flexibility, weather windows, and crew rotation economics.
- Mobile:Dynamically positioned seismic vessels deploy streamer spreads exceeding 12 kilometers. Nordic and Asian shipyards face thirty-six-month delivery backlogs for newbuild tonnage.
- Semi-Submersible:Stable platforms for harsh-environment 4D monitoring in the UK and Norwegian North Sea sectors.
- Fixed:Permanent ocean-bottom installations for continuous reservoir surveillance.
- Drillships:Dual-purpose vessels combining exploration drilling with seismic source deployment.
Contractor fleets concentrate in mobile configurations; frontier basin economics favor semi-submersible endurance.
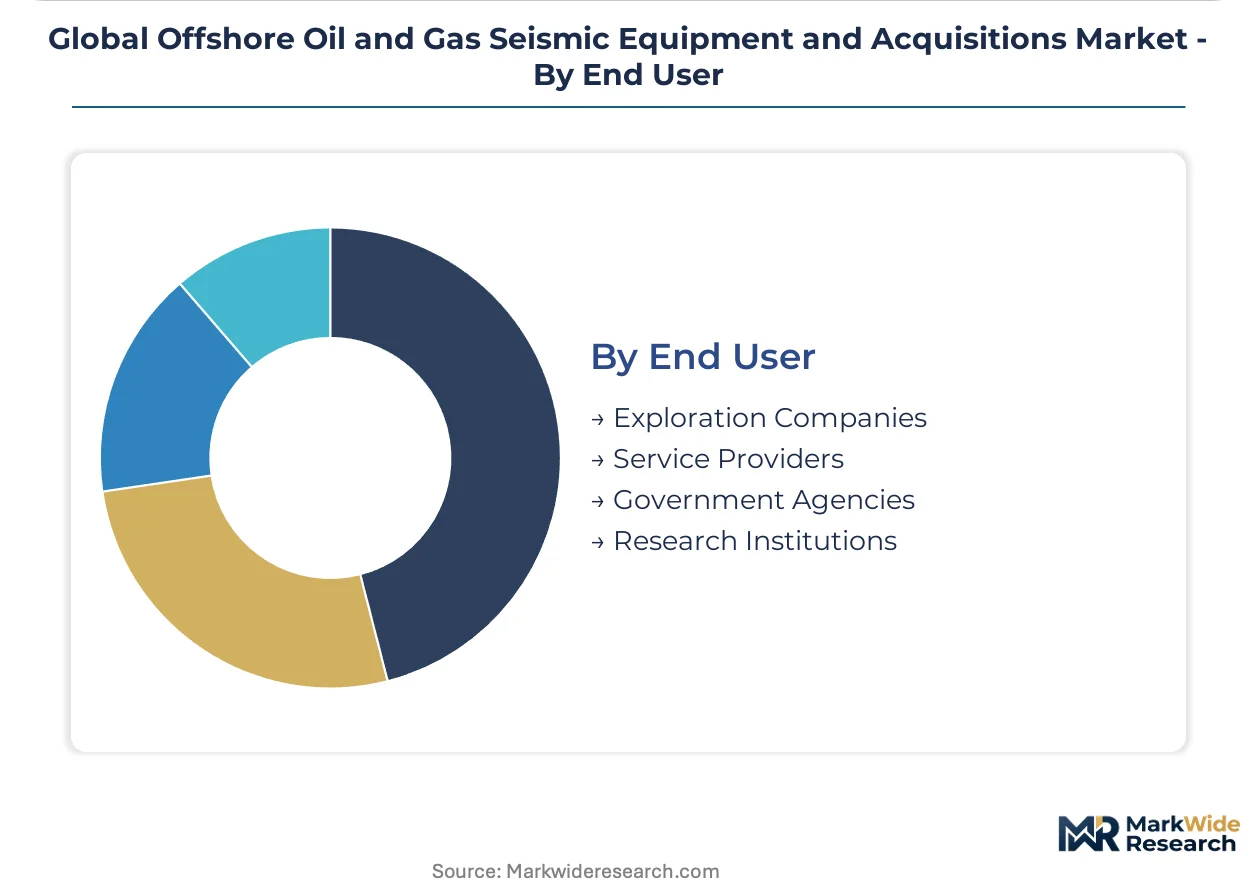
End User:
Procurement authority splits between capital-deploying operators and service-integrating contractors.
- Exploration Companies:International oil companies and independents commission proprietary surveys or license multi-client data. West Africa licensing rounds attract risk-shared survey participation.
- Service Providers:Seismic contractors own and operate acquisition assets, bundling processing and interpretation deliverables. CGG SA and TGS ASA compete through differentiated library depth and frontier basin coverage.
- Government Agencies:National regulators mandate pre-drill seismic coverage for environmental impact assessment.
- Research Institutions:Academic consortia access legacy data for crustal structure and geohazard studies.
Contract spend flows through exploration companies; data licensing growth concentrates with service providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward Norwegian contractors commanding premium rates for ice-class vessel deployment, while Brazilian operators absorb cost compression through multi-year volume commitments. Equipment certification standards diverge sharply between the EU F-Gas Regulation zone and the Gulf of Mexico regulatory environment.
Norway
North Sea mature basin operators drive 4D seismic replacement cycles for reservoir monitoring. The Petroleum Safety Authority mandates continuous source calibration documentation that elevates manufacturer service revenue. Stavanger anchors contractor engineering clusters where digital twin architectures optimize vessel sail-line efficiency.
Brazil
Petrobras sustains multi-year streamer fleet commitments across pre-salt province complexity. ANVISA environmental licensing intersects with IBAMA marine mammal protocols that constrain operational windows. Rio de Janeiro concentrates service provider headquarters managing frontier basin multi-client survey deployment.
United States
Gulf of Mexico deepwater exploration compresses survey cycle times through denser receiver array deployment. The Bureau of Ocean Energy Management enforces marine mammal observation protocols requiring redundant equipment coverage. Houston hosts integrated seismic-to-drilling workflow engineering centers.
United Kingdom
North Sea decommissioning timelines accelerate 4D monitoring adoption for production optimization. The North Sea Transition Authority imposes noise pollution thresholds through environmental permitting. Aberdeen maintains subsea equipment fabrication clusters serving semi-submersible platform integration.
China
South China Sea territorial exploration drives state-backed seismic vessel newbuild programs. MEE marine environmental standards tighten acoustic source emission thresholds for domestic operators. Shanghai and Qingdao shipyards concentrate dynamically positioned seismic vessel construction facing thirty-six-month delivery backlogs.
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market Competitive Environment
Integrated service conglomerates and specialized seismic contractors split the market through divergent capital deployment models. Consolidation concentrates among Nordic and French equipment lessors holding multi-client data libraries. Three archetypes dominate: vessel-owning acquisition specialists, data-licensing library operators, and integrated oilfield service platforms. Competitive moves center on fleet renewal partnerships and frontier basin pre-funding consortiums.
Within the integrated service tier, Schlumberger Ltd. anchors proprietary acquisition platform development, while CGG SA exemplifies multi-client library monetization without full asset ownership. TGS ASA occupies the data-licensing archetype through frontier basin risk-shared survey models. These three entities represent contrasting responses to capital intensity pressures reshaping contractor economics.
| Leading Market Players |
|---|
| CGG SA |
| Magseis Fairfield |
| Schlumberger Ltd. |
| Geospace Technologies |
| SAExploration Holdings Inc. |
| PGS (Petroleum Geo-Services) |
| China Oilfield Services Limited |
| ION Geophysical Corporation |
| TGS ASA |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp heavy-lift corridors feed Nordic shipyards assembling ice-class seismic vessels, concentrating capital equipment costs among three contracting clusters while forcing price differentiation between standard streamer configurations and Arctic-rated arrays.
Pricing Analysis
The customization-premium spread separates standard air gun arrays from tuned multi-chamber systems configured for Brazil's pre-salt penetration requirements. Project-based contracting dominates, with price differentiation driven by certification grade (EU F-Gas Regulation compliance tier) and after-sales calibration service bundling. Cost compression in standard equipment tiers is intensifying because Chinese shipyard newbuilds are expanding mobile vessel supply. Exploration companies commissioning proprietary surveys exhibit lowest price sensitivity; independent contractors leasing legacy fleets face the highest.
Supply Chain Analysis
Contract manufacturing concentrates among Norwegian, South Korean, and Chinese shipyards fabricating dynamically positioned hulls and solid-state hydrophone arrays. Raw material dependencies include high-grade steel plate, rare-earth magnet components for source positioning systems, and specialized polymer compounds for streamer flotation. Single-source vulnerability runs through South Korean marine engine suppliers. Distribution runs through equipment lessors maintaining multi-client libraries rather than direct manufacturer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seismic data is transitioning toward platform economics as multi-client libraries displace proprietary survey ownership, with interoperability between acquisition formats and processing software ecosystems determining contractor competitive position.
For Market Incumbents: Harden data format interoperability to lock in processing software dependencies among exploration company clients. Defend against emerging pure-play data licensors by anchoring integrated seismic-to-drilling workflows through proprietary vessel-source integration. Prioritize certification investment in EU F-Gas Regulation-compliant source cooling systems to capture North Sea tender preference.
For New Entrants and Emerging Players: Build out reduced-impulse source technology portfolios targeting EU Marine Strategy Framework Directive compliance gaps in frontier West African basins. The most penetrable segment sits between legacy 3D survey refresh cycles and first-mover 4D monitoring adoption in mature North Sea fields. Go-to-market execution should anchor risk-shared pre-funding consortiums with national oil companies.
For Investors and Strategic Acquirers: Library-heavy data licensors with frontier basin coverage represent the optimal acquisition archetype for long-term viability across the energy transition window. These entities capture recurring licensing revenue without vessel capital intensity. Monitor Brazil's ANVISA environmental licensing velocity as the critical inflection signal for pre-salt survey demand durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Renewal Partnership | Nordic shipyard alliances secure ice-class vessel delivery slots ahead of thirty-six-month backlogs. |
| Multi-Client Pre-Funding Consortium | Frontier basin risk-sharing shifts exploration exposure from contractors to data licensees in West Africa. |
| Reduced-Impulse Source Development | Marine vibroseis prototypes address EU noise thresholds and accelerate North Sea equipment refresh cycles. |
| Digital Twin Integration | Real-time telemetry architectures compress survey duration and optimize maintenance intervals for deepwater contractors. |
| Regulatory Certification Program | F-Gas Regulation compliance documentation elevates manufacturer service revenue in Norwegian licensing rounds. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with seismic vessel fleet managers, exploration company geoscience directors, shipyard procurement leads, and marine regulatory compliance officers. Secondary validation drew from Bureau of Ocean Energy Management permitting databases, EU Marine Strategy Framework Directive implementation reports, Norwegian Petroleum Safety Authority calibration documentation, and customs records of seismic equipment imports. Bottom-up equipment unit economics were triangulated against top-down contractor revenue aggregation across the analysis window.
Calibration against historical vessel day-rate movements and multi-client library licensing volumes anchored the projection framework. Segmentation dimensions modeled include technology tier (2D, 3D, 4D), installation mobility class, and end-user procurement authority. CAGRs were derived from equipment replacement cycle analysis and regulatory phase-down timelines. Forecast inputs incorporated Petrobras pre-salt commitment visibility and EU F-Gas Regulation equipment refresh mandates.
Stress conditions across Brazilian environmental licensing delays, South Korean shipyard delivery slippage, and North Sea 4D adoption velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding contractor fleet utilization and exploration company capital allocation priorities. Quarterly review of ANVISA permit issuance rates and Nordic shipyard order backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Floating Production Storage and Offloading Market
Offshore Oil and Gas
Global Subsea Systems Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market
Offshore Oil and Gas
Oman Oil and Gas Downstream Market
Offshore Oil and Gas
Gulf of Mexico Oil & Gas Decommissioning Market
Offshore Oil and Gas
Oil Rig Market
Offshore Oil and Gas
North Sea Offshore Decommissioning Market
Offshore Oil and Gas
Oil and Gas Fishing Market
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Deepwater and Ultra-Deepwater Drilling Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Midstream Market
Offshore Oil and Gas
Offshore Drilling Riser Market