
 Germany Solar Inverter Market | 2026-2036
Germany Solar Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Solar Inverter Market Insights
Stringent grid-code compliance tiers is rotating procurement standards upward across the Germany Solar Inverter Market. SMA Solar Technology AG leverages its domestic manufacturing footprint to sustain rapid fulfillment of utility-scale projects. Kostal Solar Electric GmbH anchors premium residential demand through integrated battery inverter architectures. Fronius Deutschland GmbH competes on welding-to-inverter technology cross-pollination, extending brand credibility into commercial segments.
A solar inverter converts direct current from photovoltaic modules into grid-synchronized alternating current, with efficiency thresholds typically exceeding 98% and maximum power point tracking across variable irradiance conditions. Its primary purpose is enabling safe, code-compliant interconnection of solar generation assets to distribution networks or behind-the-meter loads. Hybrid inverters command widening share as battery attachment rates climb, while string inverter configurations dominate ground-mounted utility installations where centralized monitoring and lower balance-of-system costs concentrate margin pools. Smart inverter technology with reactive power capability and ride-through functions is displacing basic grid-tie units in regions with high renewable penetration.
The Bundesnetzagentur enforces medium-voltage directive requirements that shape inverter certification pathways, while VDE-AR-N 4105 and VDE-AR-N 4110 standards define low-voltage and medium-voltage connection technical minimums. These frameworks mandate frequency-watt and volt-watt response curves, forcing manufacturers to embed advanced grid support functions as baseline rather than premium features. Stakeholders must monitor forthcoming revisions to the EEG auction design and FCR prequalification rules, as these will determine whether storage-coupled inverters capture incremental revenue streams beyond energy arbitrage.
Market Dynamics
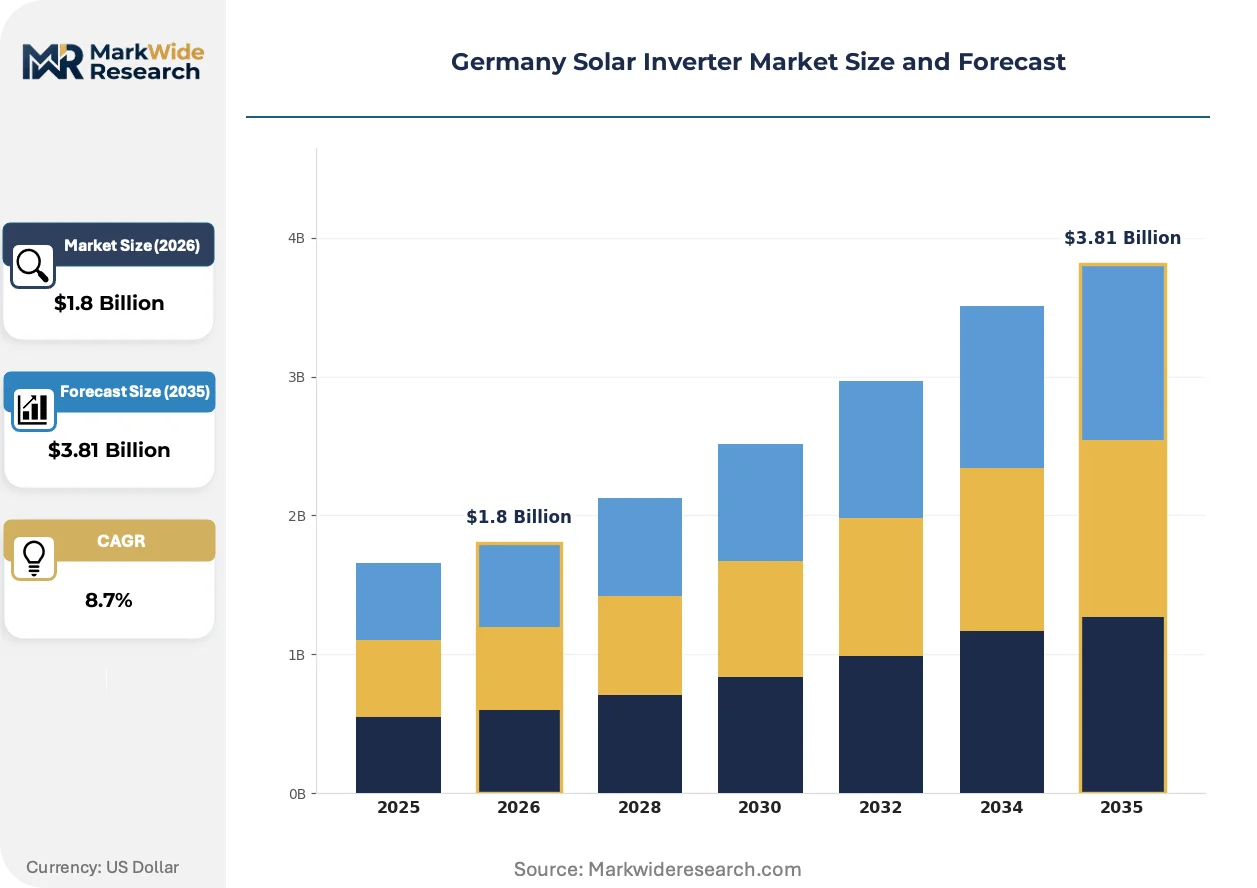
The EEG reform and VDE-AR-N 4110 grid-code upgrades are compressing certification timelines while rotating procurement toward storage-coupled architectures. Manufacturers must embed reactive power capability and frequency-watt response curves as baseline features rather than premium add-ons.
Growth Catalysts
- EEG Auction Mechanism:The reformed feed-in tariff structure incentivizes hybrid inverter configurations, pulling battery attachment rates above 60% in residential segments across Bavaria and Baden-Württemberg.
- Utility-Scale Pipeline:Ground-mounted solar parks in North Rhine-Westphalia concentrate procurement volumes for central inverters above 5 MW capacity, anchoring manufacturing scale for domestic producers.
- Silicon Carbide Semiconductors:Wide-bandgap power electronics enable efficiency thresholds exceeding 99%, reducing thermal management costs and footprint for three-phase string architectures.
Market Restraints
- IGBT Supply Concentration:Power module sourcing concentrates among East Asian foundries, exposing lead-time volatility for European inverter assemblers lacking captive semiconductor capacity.
- Grid-Code Fragmentation:Bundesnetzagentur medium-voltage directives diverge from neighboring TSO requirements, forcing redundant certification expenditures for cross-border project developers.
- Electrolyzer Competition:Green hydrogen production assets are capturing interconnection priority and grid capacity allocations that would otherwise flow to solar expansion.
Strategic Opportunities
- Agricultural PV Deployment:Agrivoltaic installations across Lower Saxony and Brandenburg create demand for elevated-mount string inverters with enhanced environmental sealing.
- FCR Prequalification Pathways:Pending revisions to frequency containment reserve rules would unlock ancillary revenue streams for storage-coupled inverters beyond energy arbitrage.
- Heat Pump Convergence:Sector coupling mandates are creating integrated home-energy-system opportunities combining solar generation, battery storage, and thermal load management.
Industry Challenges
- Power Electronics Talent Scarcity:Embedded firmware engineering for grid-forming inverters faces acute recruitment gaps across Saxony and Thuringia technical universities.
- Type Certification Backlogs:VDE testing laboratory queues for VDE-AR-N 4105 compliance extend beyond 14 months, delaying product launches for new market entrants.
- Legacy String Inverter Retrofit:Existing commercial rooftop fleets lack communication protocols for modern energy management systems, complicating battery retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Solar Inverter Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Inverters, Micro Inverters, Power Optimizers, Hybrid Inverters End User: Residential, Commercial, Industrial, Utilities Technology: PV Grid-Tie, Off-Grid, Battery Storage, Smart Inverters Installation Type: Rooftop, Ground-Mounted, Building-Integrated, Floating |
| Companies Covered | SMA Solar Technology AG, KACO New Energy GmbH, Fronius Deutschland GmbH, Siemens Energy AG, Kostal Solar Electric GmbH, REFU Elektronik GmbH, Schneider Electric SE, Kontron Solar GmbH, Steca Elektronik GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Solar Inverter Market Trends and Innovations
Gallium nitride power semiconductors and AI-driven maximum power point tracking algorithms are compressing inverter form factors while elevating grid support functionality. These shifts reshape competitive differentiation around thermal performance and predictive maintenance capability.
Silicon carbide MOSFET arrays in three-phase string inverters are miniaturizing heat sink volumes by 40% while maintaining 1500 V DC input compatibility. Commercial installers across southern Germany are specifying these compact architectures for rooftop projects with constrained mechanical loading capacity. The footprint reduction enables higher power density per square meter of roof area, compressing balance-of-system costs for multi-megawatt commercial portfolios.
The Bundesnetzagentur's forthcoming revision to VDE-AR-N 4110 will mandate enhanced fault ride-through capability for medium-voltage connected assets. This regulatory pressure forces manufacturers to embed synchronous condenser emulation functions previously reserved for utility-scale central inverters. Project developers in Bavaria are pre-emptively specifying compliant hardware to avoid retrofit obligations during mid-life asset refurbishment cycles.
Direct procurement from manufacturer digital platforms is displacing traditional electrical wholesale channels for residential systems below 20 kW. Installers in North Rhine-Westphalia are configuring complete inverter-plus-battery packages through online portals with 48-hour fulfillment guarantees. This channel shift compresses distributor margins while capturing end-customer data for aftermarket service attachment and warranty extension revenue.
Germany Solar Inverter Market Segmentation
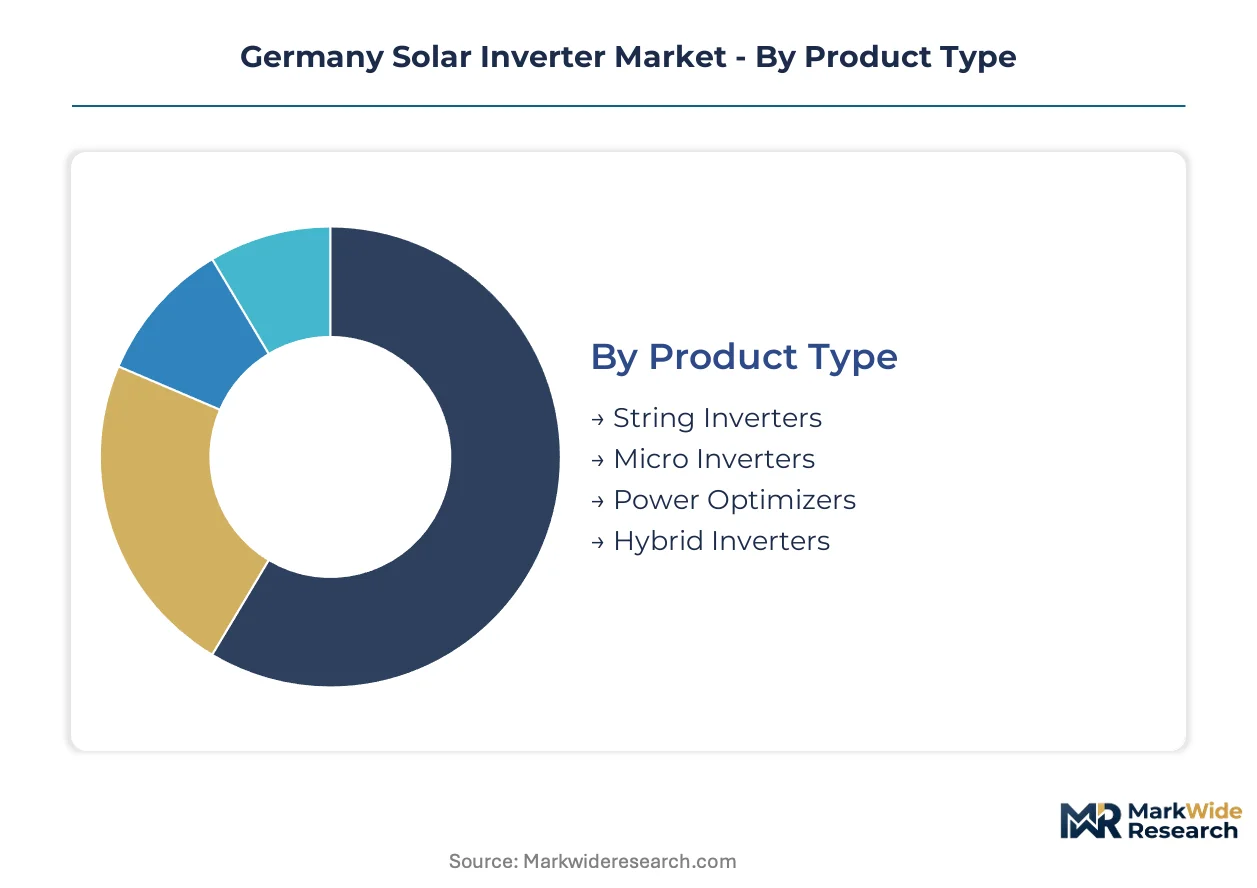
Segmentation reveals how procurement standards diverge across voltage classes and installation contexts in the Germany Solar Inverter Market. Margin pools concentrate where grid-code compliance complexity intersects with scale economics.
Product Type:
Margin pools concentrate in architectures that simplify balance-of-system engineering while embedding storage-ready functionality.
- String Inverters:Three-phase string architectures dominate ground-mounted utility parks across North Rhine-Westphalia, leveraging silicon carbide MOSFET arrays to compress heat sink volumes by 40%. Procurement volumes anchor here for projects above 5 MW capacity where centralized monitoring reduces O&M overhead.
- Hybrid Inverters:Integrated battery inverter architectures command premium positioning in Bavaria and Baden-Württemberg residential segments, pulling attachment rates above 60% through EEG reform incentives. VDE-AR-N 4105 compliance mandates frequency-watt response curves as baseline features.
- Micro Inverters:Module-level power electronics serve shading-constrained rooftops in urban Munich and Stuttgart clusters.
- Power Optimizers:DC-DC conversion at module level enables retrofit compatibility for legacy string inverter fleets lacking modern communication protocols.
String inverters hold installed capacity. Hybrid inverters are rotating up the share rankings.
End User:
Customer archetypes split procurement priorities between LCOE minimization and energy autonomy objectives.
- Residential:Behind-the-meter demand in southern Germany concentrates on sub-20 kW hybrid systems with 48-hour digital fulfillment guarantees. Battery attachment rates climb fastest here as sector coupling mandates integrate heat pump loads.
- Commercial:Rooftop portfolios across Baden-Württemberg specify compact three-phase strings where mechanical loading constraints limit equipment weight. Multi-megawatt installations drive silicon carbide adoption for footprint reduction.
- Industrial:C&I offtakers in Bavaria prioritize FCR prequalification pathways for ancillary revenue capture beyond energy arbitrage.
- Utilities:Ground-mounted solar parks anchor central inverter procurement above 5 MW, with synchronous condenser emulation functions mandated under forthcoming VDE-AR-N 4110 revisions.
Utility-scale deployment holds installed capacity. Residential is climbing the fastest.
Technology:
Technology selection determines grid support functionality depth and revenue stack eligibility.
- Smart Inverters:Reactive power capability and ride-through functions displace basic grid-tie units in high-renewable-penetration zones. AI-driven maximum power point tracking algorithms compress form factors while elevating predictive maintenance capability.
- Battery Storage:Storage-coupled architectures capture incremental revenue streams pending FCR prequalification rule revisions, with embedded firmware enabling grid-forming operation.
- PV Grid-Tie:Basic synchronization functions face displacement as VDE-AR-N 4105 and 4110 standards mandate advanced response curves.
- Off-Grid:Island-capable configurations serve agricultural PV installations across Lower Saxony where grid extension economics fail.
PV Grid-Tie holds installed capacity. Smart Inverters are expanding most quickly.
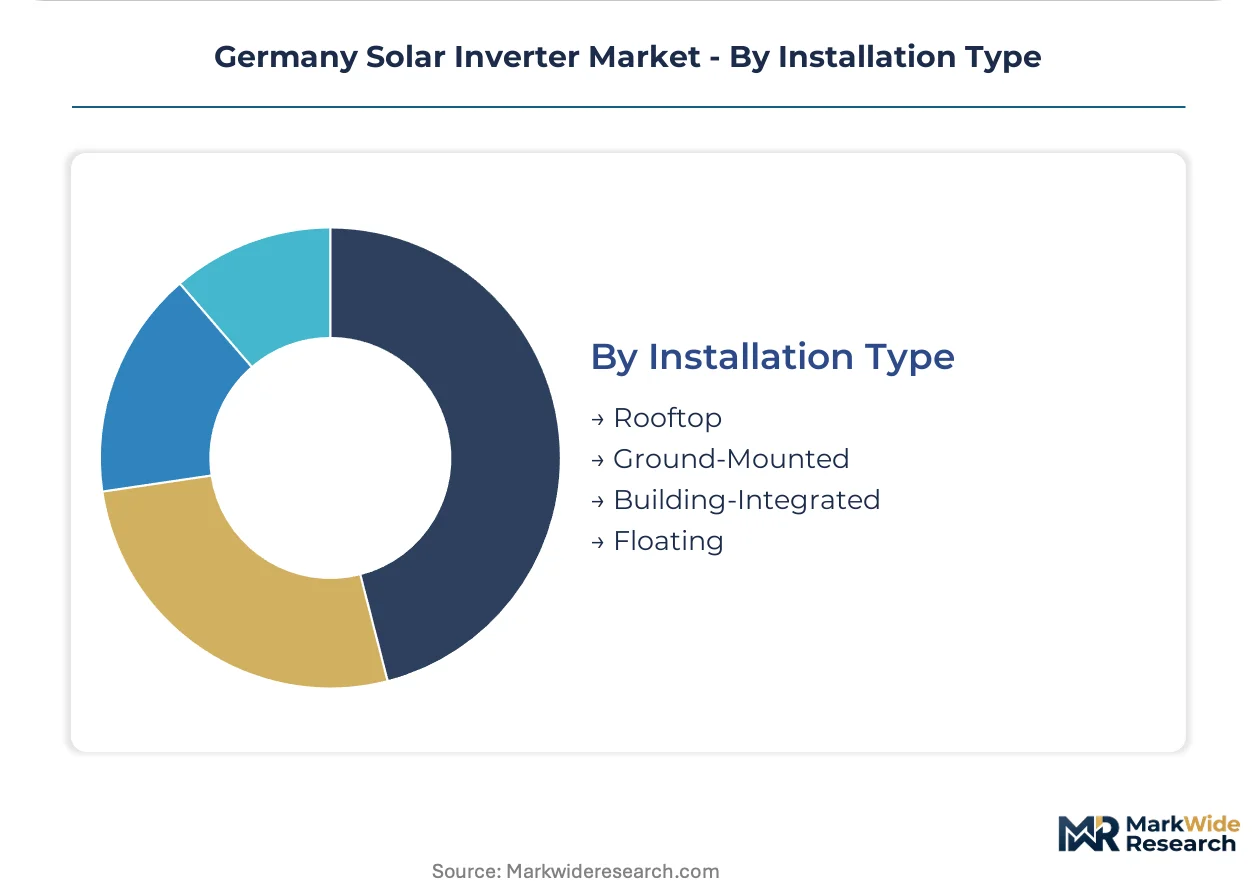
Installation Type:
Physical mounting context shapes environmental sealing requirements and thermal management specifications.
- Ground-Mounted:Utility-scale parks across Bavaria and North Rhine-Westphalia concentrate procurement for central inverters with enhanced fault ride-through capability. Elevated equipment pads reduce flood exposure.
- Rooftop:Commercial installations in southern Germany drive demand for compact three-phase strings with 1500 V DC input compatibility and reduced mechanical loading.
- Building-Integrated:Façade-mounted systems in urban cores require specialized thermal derating for reduced ventilation.
- Floating:Reservoir-based agrivoltaic pilots across Brandenburg test elevated-mount string inverters with IP66+ sealing against humidity corrosion.
Ground-mounted deployment holds installed capacity. Rooftop is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across German states. Bavarian residential buyers absorb premium hybrid systems while North Rhine-Westphalia utility developers squeeze central inverter margins through volume aggregation.
Bavaria
Residential battery attachment rates exceed sixty percent across Munich and Nuremberg metropolitan zones. The Bundesnetzagentur enforces VDE-AR-N 4105 frequency-watt response mandates that elevate baseline inverter specifications. SMA Solar Technology AG anchors manufacturing scale in Niestetal to serve this premium demand cluster.
North Rhine-Westphalia
Ground-mounted solar parks concentrate procurement volumes for central inverters above five megawatts. The state's industrial load centers drive C&I rooftop deployment where mechanical loading constraints favor compact three-phase string architectures. Dortmund and Cologne anchor installer networks with forty-eight-hour digital fulfillment capabilities.
Baden-Württemberg
Stuttgart's automotive supplier ecosystem supplies precision manufacturing talent for power electronics assembly. The EEG auction mechanism pulls battery-coupled inverter demand through reformed feed-in tariff structures. Freiburg's solar research institutes accelerate silicon carbide MOSFET validation cycles for commercial rooftop portfolios.
Lower Saxony
Agrivoltaic pilots across Hanover and Brunswick test elevated-mount string inverters with IP66-plus environmental sealing. Agricultural land use regulations create dual-revenue stream opportunities that justify premium equipment procurement. The state's grid extension backlogs favor island-capable configurations in rural deployment zones.
Brandenburg
Berlin's periphery concentrates floating solar reservoir pilots requiring humidity-corrosion resistant architectures. The Bundesnetzagentur's medium-voltage directive shapes certification pathways for projects interconnecting to 50Hertz transmission networks. Cottbus and Potsdam anchor regional installer capacity for utility-scale procurement rounds.
Germany Solar Inverter Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Germany Solar Inverter Market. Domestic manufacturers with captive assembly capacity compete against modular importers on fulfillment speed versus unit economics. The vendor base stratifies into utility-scale central inverter specialists, residential hybrid system integrators, and commercial three-phase string providers. Consolidation pressure intensifies through silicon carbide semiconductor sourcing requirements and VDE certification backlog bottlenecks.
Among Germany-based fabricators, SMA Solar Technology AG, Kostal Solar Electric GmbH, and Fronius Deutschland GmbH occupy distinct positioning tiers. SMA Solar Technology AG represents the scale-driven archetype with domestic manufacturing footprint. Kostal Solar Electric GmbH exemplifies premium residential specialization through integrated battery architectures. Fronius Deutschland GmbH anchors commercial segment credibility through cross-industrial technology heritage. Each sits within a differentiated procurement channel rather than competing head-to-head on identical specifications.
| Leading Market Players |
|---|
| SMA Solar Technology AG |
| KACO New Energy GmbH |
| Fronius Deutschland GmbH |
| Siemens Energy AG |
| Kostal Solar Electric GmbH |
| REFU Elektronik GmbH |
| Schneider Electric SE |
| Kontron Solar GmbH |
| Steca Elektronik GmbH |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between utility-scale developers and inverter manufacturers lock in silicon carbide module supply while stabilizing unit costs across multi-year project horizons. These contractual structures anchor price visibility for ground-mounted solar parks in North Rhine-Westphalia while constraining margin flexibility for European assemblers exposed to Asian foundry pricing.
Pricing Analysis
VDE-AR-N 4110 dictates the pricing tier structure across the Germany Solar Inverter Market, separating certified medium-voltage units from basic low-voltage alternatives. Three-tier pricing stratifies across grid-forming hybrid architectures, standard string configurations, and entry-level residential units, with certification grade and volume scale as primary differentiation drivers. Cost compression in central inverter tiers is intensifying because silicon carbide MOSFET sourcing concentrates among East Asian suppliers. Utility-scale developers exhibit lowest price sensitivity, while residential installers in Bavaria absorb premium positioning for battery-coupled systems.
Supply Chain Analysis
Inventory buffers for IGBT and silicon carbide power modules currently extend beyond fourteen months, constraining fulfillment velocity for new market entrants. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, while precision manufacturing of thermal management assemblies rests on German and Austrian metalworking capacity. Raw material dependencies span rare earth substrates, copper busbars, and aluminum heat sink extrusions. Single-source vulnerability in wide-bandgap semiconductor wafer supply presents structural risk. Distribution runs through manufacturer-direct digital platforms for residential tiers below twenty kilowatts, with electrical wholesale channels retaining utility-scale project coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany Solar Inverter Market sits in early-cycle expansion, with battery attachment rates climbing past sixty percent in southern residential segments as EEG reform incentives deepen storage integration.
For Market Incumbents: Secure captive semiconductor sourcing through backward integration into silicon carbide module assembly or multi-year foundry partnerships, insulating margin pools from East Asian lead-time volatility. Reinforce domestic manufacturing footprint in Niestetal and Kassel production zones to sustain rapid fulfillment of utility-scale tenders. Channel control through installer certification programs defends positioning against modular importers. For New Entrants and Emerging Players: Anchor in agrivoltaic deployment across Lower Saxony and Brandenburg, where elevated-mount string inverter specifications remain underpenetrated by established residential specialists. Target commercial rooftop retrofits in Baden-Württemberg requiring DC-DC power optimizer compatibility for legacy fleet upgrades. Digital-native fulfillment platforms with forty-eight-hour configuration guarantees unlock installer network access without wholesale channel dependency. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with VDE-AR-N 4105 certification backlog clearance and embedded firmware engineering teams in Saxony technical corridors. Long-term viability over the next decade hinges on grid-forming inverter capability and FCR prequalification pathway readiness. The signal to watch is Bundesnetzagentur revision timing for ancillary revenue rule changes that would revalue storage-coupled hardware portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Captive wafer access insulates SMA and Kostal from Taiwan foundry bottlenecks. |
| VDE-AR-N 4110 Pre-Certification | Early compliance locks in Bavarian utility-scale procurement before mandate enforcement. |
| Agrivoltaic Product Line Launch | IP66-plus sealing specifications capture Lower Saxony dual-revenue stream pilots. |
| Digital Platform Integration | Direct procurement portals displace wholesale margins in North Rhine-Westphalia residential. |
| Heat Pump Convergence Partnership | Sector coupling mandates create integrated home-energy-system bundling opportunities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Bundesnetzagentur regulatory filings, VDE certification databases, EEG auction results, and European solar project development trackers. Utility planning officers, EPC contractors, inverter procurement leads at IPPs, and grid operators at 50Hertz provided structured interviews. Bottom-up unit shipment estimates triangulate against top-down market value reconstruction across product type, end user, and installation dimensions.
Segmentation dimensions modeled span string versus hybrid versus central inverter architectures, residential versus commercial versus utility end-use tiers, ground-mounted versus rooftop versus floating installation contexts, and smart versus basic grid-tie technology categories. CAGRs derive from regression analysis of historical procurement volumes against EEG policy phase transitions and silicon carbide adoption curves. Forecast inputs incorporate VDE certification queue dynamics and Bundesnetzagentur grid-code revision timelines.
Material uncertainties — semiconductor supply disruption, EEG auction design changes, and electrolyzer interconnection priority shifts — sit outside the modeled envelope. Forecasts reflect assumptions regarding policy continuity and technology cost trajectories without claiming predictive precision. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Global UPS Market
Power
North America Microturbine Market
Power
Digital Power Utility Market
Power
High Voltage DC Power System Market
Power
Mexico Power Market
Power
Norway Power Market
Power
Asia-Pacific Package Substation Market
Power
Power Rental Market
Power
Marine Thermal Fluid Heaters Market
Power
Asia-Pacific Power Purchase Agreement Market
Power
Middle-East and Africa Power Market
Power
North America Micro CHP Market
Power
Europe Frequency Converter Market
Power
Static Synchronous Compensator (STATCOM) Market
Power
Steam Turbine MRO Market
Power
Angola Power EPC Market