
 Norway Power Market | 2026-2036
Norway Power Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Power Market Outlook
Grid stability grade specifications for frequency response and inertia provision is collapsing as a meaningful market differentiator between legacy hydro and new renewable entrants. Statkraft AS leverages its reservoir capacity to anchor ancillary service revenue across Nordic bidding zones. Norsk Hydro ASA sustains captive generation scale through long-term power purchase agreements tied to aluminum smelter load. Equinor ASA positions its offshore wind development pipeline to compete for seabed leases in the North Sea.
Norway power encompasses electricity generated, transmitted, distributed, and retailed across a system dominated by run-of-river and reservoir hydro plants with installed turbine ratings typically spanning 1 MW to 1,000 MW, serving industrial baseload, residential heating, and emerging electrified transport applications. Hydroelectric generation occupies the mature margin pool given sunk infrastructure and regulated watercourse concessions, while wind and solar segments capture development velocity through technology cost curves and licensing queue priority. Service type segmentation shows transmission and distribution as structurally regulated with stable returns, whereas retail faces margin compression from supplier switching platforms and spot-price-linked contract structures.
The Norwegian Water Resources and Energy Directorate sets grid codes and licensing terms that shape generator market access and connection cost allocation across voltage levels. NVE's integration with Nord Pool Spot exchange rules and the EU Clean Energy Package acquis through EEA alignment determines cross-border capacity pricing and renewable support scheme eligibility. Stakeholders must monitor seabed licensing rounds, hydrogen offtake contract formation, and interconnector commissioning timelines to time capital deployment.
Market Dynamics
Data center load concentration in southern Norway is compressing grid connection timelines and forcing NVE to rewrite integration standards for variable renewable assets.
Growth Catalysts
- EU Clean Energy Package alignment:EEA adoption unlocks cross-border capacity pricing mechanisms that improve Norwegian generator economics in Nordic bidding zones.
- Aluminum smelter electrification:Industrial baseload demand from Vestland county facilities sustains long-term power purchase agreement volumes.
- Fjord-based pumped storage:Topography in Vestland enables reservoir capacity expansion that anchors ancillary service revenue pools.
Market Restraints
- Grid code tightening:NVE frequency response requirements raise connection costs for run-of-river entrants without reservoir flexibility.
- Seabed lease scarcity:North Sea offshore wind licensing rounds face bidder congestion that extends development timelines.
- Interconnector bottlenecks:Cross-border transmission capacity limits arbitrage opportunities into continental European price zones.
Strategic Opportunities
- Hydrogen offtake formation:Electrolyzer load contracts in Rogaland create new demand anchor for surplus renewable generation.
- Electrified transport load:Ferry fleet battery charging and road transport infrastructure expand distribution network utilization.
- Offshore wind technology convergence:Floating platform maturation unlocks deeper North Sea lease zones beyond fixed-foundation limits.
Industry Challenges
- Grid integration timelines:Variable asset connection queues stretch 18-36 months as NVE processes voltage stability studies.
- Reservoir management complexity:Multi-year water inflow variability complicates forward contract hedging for hydro operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Power Market |
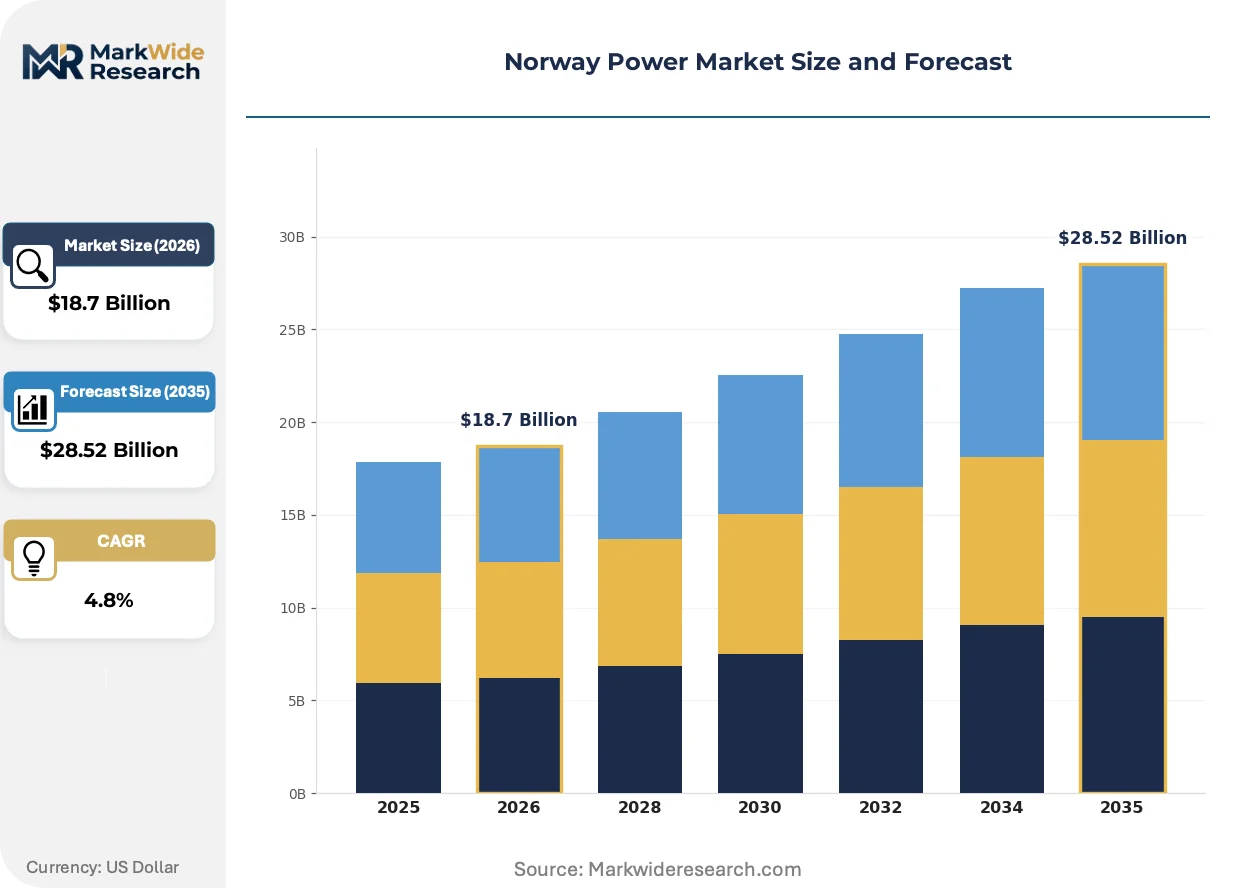
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hydroelectric, Wind, Solar, Thermal Service Type: Generation, Distribution, Transmission, Retail End User: Residential, Commercial, Industrial, Municipal Technology: Smart Grid, Energy Storage, Microgrid, IoT |
| Companies Covered | Hafslund Eco, Norsk Hydro ASA, Statkraft AS, Vattenfall AB (Norway), Statnett SF, Agder Energi AS, BKK (Bergen Kraft), Siemens Energy AS (Norway), Equinor ASA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Power Market Strategic Shifts
Battery energy storage is compressing ancillary service margins while offshore wind scale-up reconfigures generation geography.
Grid-scale lithium-ion battery systems are decomposing the historical monopoly of hydro reservoirs on frequency containment reserves. Statnett procures synthetic inertia services from battery operators in Oslofjord load centers. This technology is decomposing the revenue premium previously captured by fast-ramping hydro units.
NVE grid code revisions mandate enhanced fault ride-through capabilities for wind and solar connections above 50 MW. The regulation forces retrofit investments from existing renewable operators and delays greenfield project commissioning. Offshore wind developers in North Sea lease zones face the steepest compliance cost escalation.
Spot-price-linked retail contracts are displacing fixed-price agreements as the default residential offering. Supplier switching platforms in Oslo and Bergen reduce customer acquisition costs for new market entrants. This channel shift concentrates margin pressure on legacy utilities with large fixed-price book remnants.
Norway Power Market Segmentation
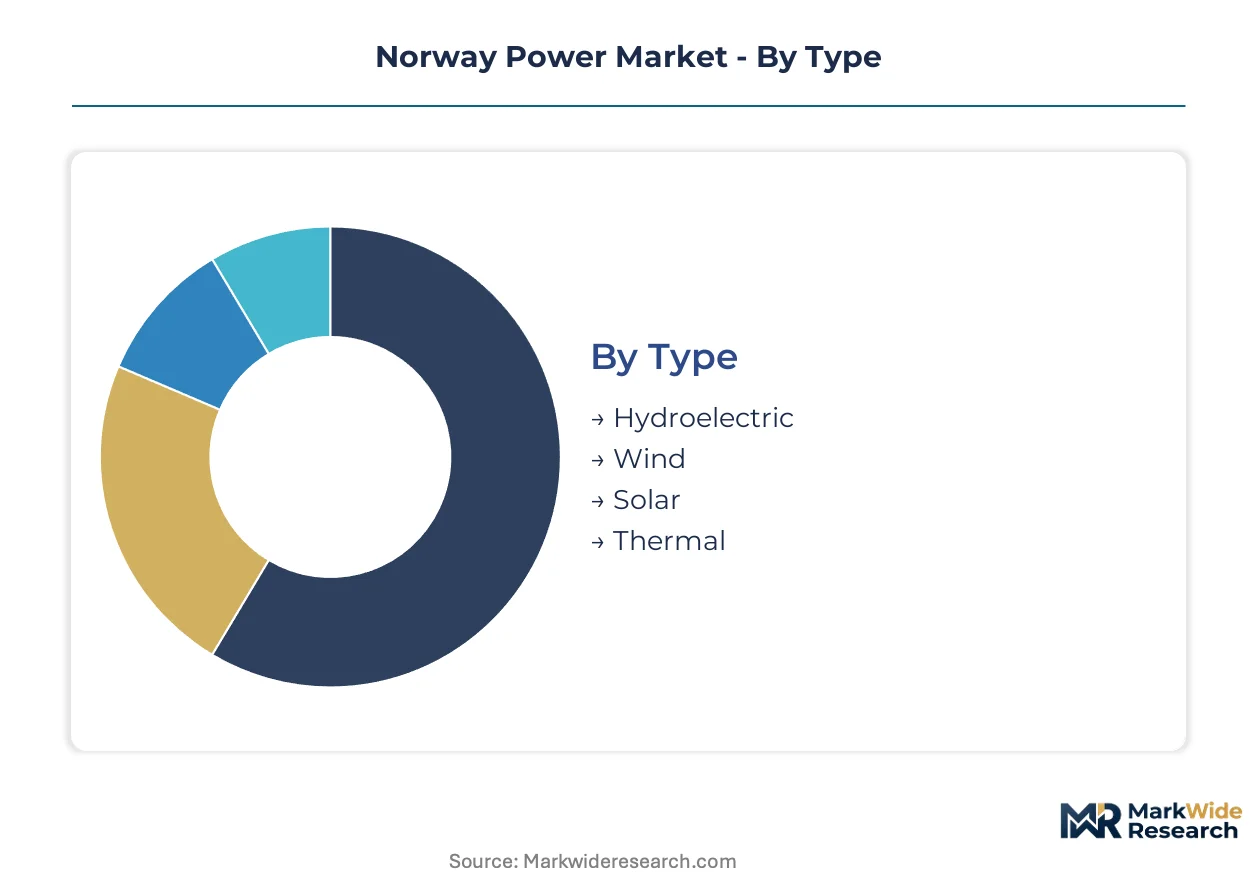
Segmentation reveals how Norway's hydro-dominated generation stack competes against variable renewable entrants across regulated service tiers and customer categories. Understanding these divisions clarifies where technology substitution pressure concentrates and which revenue pools remain structurally protected.
Type:
Wind and solar entrants face the steepest substitution pressure as reservoir hydro defends its cost position through sunk infrastructure and regulated watercourse access.
- Hydroelectric:Run-of-river and reservoir plants with turbine ratings spanning 1 MW to 1,000 MW anchor baseload supply. Vestland county facilities sustain captive aluminum smelter demand through long-term power purchase agreements, while Statkraft leverages reservoir flexibility to capture ancillary service revenue across Nordic bidding zones.
- Wind:Onshore installations face tightening NVE grid codes for frequency response, raising connection costs for entrants lacking reservoir backup. Offshore developments in North Sea lease zones compete for seabed access against Equinor's floating platform pipeline.
- Solar:Distributed rooftop systems gain traction in southern Norway where data center load concentration improves project economics. Intermittency limits grid-scale deployment without co-located storage.
- Thermal:Peaking gas plants retain marginal dispatch role during reservoir inflow deficits. Carbon pricing through EU ETS alignment erodes residual competitiveness.
Hydroelectric retains volume leadership; wind holds the steepest expansion curve.
Service Type:
Margin compression differentiates the regulated monopoly tiers from competitive segments exposed to supplier switching and spot-price volatility.
- Generation:Asset ownership spans state-controlled reservoirs, independent wind developers, and industrial captive plants. Technology cost curves favor new renewable entrants despite grid integration delays.
- Transmission:Statnett's national grid monopoly operates under NVE revenue caps with stable regulated returns. Cross-border interconnector bottlenecks limit arbitrage into continental European price zones.
- Distribution:Regional network operators face stranded asset risk as distributed generation and electrified transport reshape load profiles. Oslofjord load centers drive battery storage procurement for synthetic inertia services.
- Retail:Supplier switching platforms in Oslo and Bergen compress customer acquisition costs for new entrants. Spot-price-linked contracts displace fixed-price agreements as the default residential offering.
Transmission commands the most stable returns; retail faces the deepest margin erosion.
End User:
Industrial baseload anchors long-term contracting while residential and commercial segments absorb spot-price exposure.
- Residential:Electric heating dominance creates winter peak demand patterns. District heating networks in Bergen and Trondheim compete for thermal load share.
- Commercial:Data center operators in southern Norway compress grid connection timelines and force NVE to rewrite integration standards. Facility scale drives direct high-voltage connections bypassing distribution tariffs.
- Industrial:Aluminum smelters in Vestland sustain the largest captive power purchase agreement volumes. Norsk Hydro's integrated generation assets provide supply security against Nordic price volatility.
- Municipal:Ferry fleet electrification and public building retrofits expand distribution network utilization. Rogaland municipalities anchor hydrogen offtake contract formation for electrolyzer load.
Industrial load retains contract volume leadership; commercial data center demand climbs fastest.
Technology:
Smart grid deployment concentrates where variable renewable penetration strains legacy voltage stability frameworks.
- Smart Grid:Advanced metering infrastructure and demand response platforms enable real-time price signals. NVE mandates enhanced fault ride-through capabilities above 50 MW connection thresholds.
- Energy Storage:Grid-scale lithium-ion systems decompose hydro's historical monopoly on frequency containment reserves. Battery operators in Oslofjord load centers capture synthetic inertia procurement from Statnett.
- Microgrid:Islanded systems serve remote coastal communities and offshore platforms. Fjord-based pumped storage projects in Vestland enable reservoir capacity expansion for ancillary services.
- IoT:Sensor networks optimize reservoir inflow forecasting and turbine maintenance scheduling. Multi-year water variability complicates forward contract hedging despite predictive analytics deployment.
Energy storage gains share fastest; smart grid retains infrastructure spend leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian power exports flow primarily through subsea interconnectors to Denmark, Germany, the Netherlands, and the United Kingdom, with Nord Pool Spot exchange integration enabling cross-border capacity pricing across Nordic bidding zones.
Vestland County
Aluminum smelter baseload demand from Norsk Hydro facilities anchors long-term power purchase agreement volumes. The Norwegian Water Resources and Energy Directorate regulates reservoir management concessions across regulated watercourses. Fjord-based pumped storage projects cluster near Bergen, expanding reservoir capacity for ancillary service revenue pools.
Oslofjord Load Centers
Data center electricity offtake compresses grid connection timelines across southern Norway. Statnett procures synthetic inertia services from battery energy storage operators under revised grid codes. Urban distribution networks in Oslo and Drammen face stranded asset risk from distributed generation and electrified transport load growth.
Rogaland
Hydrogen offtake contracts from electrolyzer installations create new demand anchors for surplus renewable generation. Municipal ferry fleet electrification expands distribution network utilization along coastal corridors. Stavanger anchors offshore wind supply chain development for North Sea floating platform deployment.
Trøndelag
Run-of-river hydro entrants face tightening NVE frequency response requirements that raise connection costs without reservoir flexibility. District heating networks in Trondheim compete with electric heating for residential thermal load share. Grid integration queues stretch 18-36 months as voltage stability studies delay variable asset commissioning.
Nordland
Offshore wind lease zones beyond fixed-foundation limits unlock deeper North Sea development as floating platform technology matures. Interconnector bottlenecks limit arbitrage opportunities into continental European price zones from northern generation assets. Bodø serves as logistics hub for seabed licensing round preparation and marine construction staging.
Norway Power Market Competitive Environment
Listed leaders compete with private specialists across generation asset ownership and regulated grid infrastructure. State-controlled entities dominate reservoir hydro capacity through legacy concession holdings, while independent developers capture wind and solar project pipelines. Three archetypes define competitive positioning: integrated aluminum producers with captive generation, state-owned reservoir operators monetizing ancillary services, and offshore wind specialists competing for seabed leases. Capacity expansion through fjord-based pumped storage and strategic partnerships for hydrogen offtake formation represent dominant competitive moves.
Among state-owned generation champions, Statkraft AS exemplifies the reservoir-flexibility archetype leveraging watercourse concessions for frequency containment reserves. Norsk Hydro ASA occupies a position as the integrated industrial consumer with captive supply security against Nordic price volatility. Equinor ASA represents the offshore wind developer archetype positioning for floating platform maturation in deeper North Sea lease zones.
| Leading Market Players |
|---|
| Hafslund Eco |
| Norsk Hydro ASA |
| Statkraft AS |
| Vattenfall AB (Norway) |
| Statnett SF |
| Agder Energi AS |
| BKK (Bergen Kraft) |
| Siemens Energy AS (Norway) |
| Equinor ASA |
| Others |
Value Chain & Pricing Dynamics
Battery energy storage substitution for hydro reservoir flexibility is simultaneously compressing ancillary service premiums in Oslofjord load centers and relocating supply chain investment toward lithium-ion manufacturing hubs outside Norway. This technology displacement redraws procurement geography for grid stability services while eroding the historical pricing power of reservoir-backed generators.
Pricing Analysis
Next-generation battery storage, legacy hydro reservoirs, and emerging offshore wind assets occupy distinct pricing tiers for frequency containment services. Contract-based long-term offtake agreements dominate industrial baseload segments, with aluminum smelters in Vestland commanding volume discounts unavailable to smaller commercial buyers. Price differentiation hinges on reservoir flexibility certification and direct high-voltage connection status. Cost compression in synthetic inertia procurement is intensifying because Statnett's battery procurement programs bypass traditional hydro intermediaries. Data center operators demonstrate lowest price sensitivity given facility scale and uptime requirements, while municipal ferry electrification projects face strict budget constraints.
Supply Chain Analysis
China, South Korea, and Japan anchor lithium-ion cell and module manufacturing for Norwegian grid-scale storage deployments. Turbine and generator equipment draws from Germany, Denmark, and domestic suppliers with long-standing hydropower relationships. Rare earth magnet supply for offshore wind drivetrains rests on Chinese processing concentration. Single-source vulnerability in battery cell supply creates exposure to export licensing disruptions. Distribution runs through EPC contractors with Nordic grid integration expertise, linking component sourcing to NVE certification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among data center operators and aluminum smelters, with long-term contract consolidation compressing margins for generators lacking direct industrial relationships.
For Market Incumbents: Compound reservoir flexibility advantages through fjord-based pumped storage expansion in Vestland before battery storage captures remaining ancillary service share. Secure direct high-voltage connections with data center developers in southern Norway to bypass distribution tariff erosion. Statnett's synthetic inertia procurement programs threaten hydro's frequency containment monopoly without countervailing capacity investments. For New Entrants and Emerging Players: Lead with floating offshore wind development in deeper North Sea lease zones beyond Equinor's fixed-foundation footprint where seabed scarcity has stalled incumbent timelines. Target Rogaland hydrogen offtake contracts from municipal electrolyzer projects as the most penetrable demand anchor. Go-to-market positioning should emphasize NVE grid code pre-compliance to compress 18-36 month connection queues. For Investors and Strategic Acquirers: Capital is best deployed toward reservoir-flexible generation assets with existing watercourse concessions and direct industrial offtake relationships, given their defensive positioning against battery substitution. Long-term viability hinges on ancillary service revenue diversification across Nordic bidding zones. Watch for Statnett battery procurement volume acceleration as the inflection signal for hydro premium erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Fjord-Based Pumped Storage Expansion | Vestland reservoir capacity additions anchor frequency containment revenue pools against battery encroachment. |
| Direct High-Voltage Data Center Connections | Southern Norway facility bypasses distribution tariffs and compresses grid integration timelines with NVE. |
| Floating Offshore Wind Platform Deployment | North Sea lease zones beyond fixed-foundation limits unlock deeper water development as technology matures. |
| Hydrogen Offtake Contract Formation | Rogaland electrolyzer load creates new demand anchor for surplus renewable generation outside spot markets. |
| Grid-Scale Battery Storage Procurement | Oslofjord synthetic inertia services decompose hydro's historical monopoly on ancillary service revenue. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across Nordic bidding zones. Secondary validation drew from NVE licensing databases, Nord Pool Spot exchange price records, Statnett transmission data, and seabed leasing round documentation. Bottom-up project pipeline assessments triangulated against top-down macro demand forecasts for electrified transport and industrial load.
Across the analysis window, the forecasting framework modeled generation source segmentation, project capacity tiers, and regional grid integration complexity alongside regulatory framework variations. CAGRs were derived from installed capacity buildout trajectories and load growth assumptions. Key inputs included reservoir inflow variability patterns, interconnector commissioning schedules, and hydrogen offtake contract formation velocity.
Forecasts assume regulatory continuity in Norwegian Water Resources and Energy Directorate grid codes and EU Clean Energy Package EEA alignment; material policy shifts would require re-modeling connection cost allocations and cross-border capacity pricing mechanisms. Recalibration cycles align with material shifts in NVE integration timelines, seabed licensing round outcomes, and battery storage procurement volumes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Nigeria Power Market
Power
Global Advanced Marine Power Supply Market
Power
Solar UPS Market
Power
Static Synchronous Compensator (STATCOM) Market
Power
Marine Thermal Fluid Heaters Market
Power
Power Sled Market
Power
Smart Power Market
Power
Asia-Pacific Turbomachinery Control Systems Market
Power
Kuwait Power Market
Power
Gas Freeing Fan Market
Power
Power Shelf Market
Power
Malaysia Power EPC Market
Power
Substation Automation System Market
Power
Power Rental Market
Power
Modified Sine Wave Home Inverters Market
Power
Existent Gum Steam Generator Market