
 Europe Frequency Converter Market | 2026-2036
Europe Frequency Converter Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Frequency Converter Market Intelligence
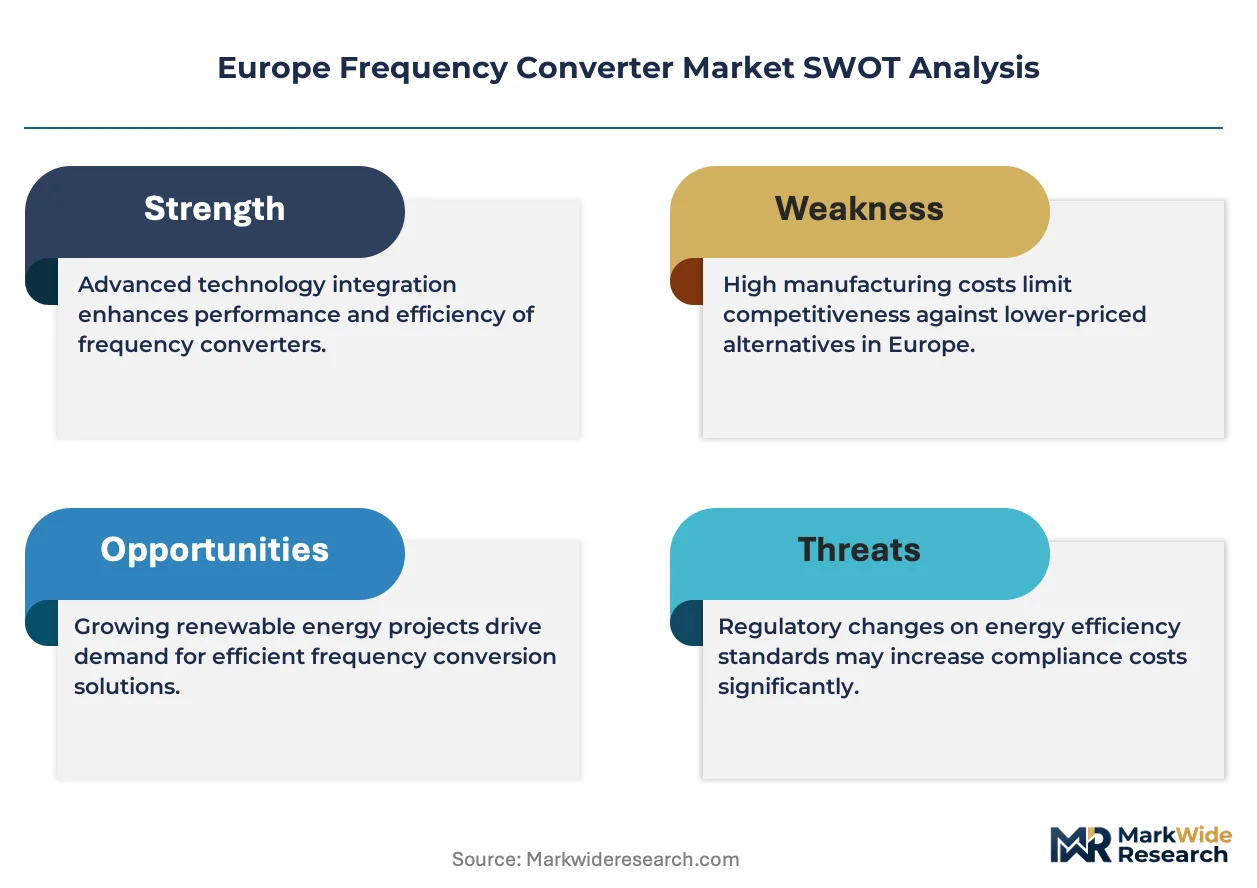
The Europe frequency converter market is recalibrating around a widening gap between premium integrated systems for renewable energy installations and commodity static converters serving standard industrial motor drives. Siemens AG leverages its automation software stack to anchor premium positioning in offshore wind grid connections. Danfoss competes through thermal management specialization that sustains converter reliability in marine propulsion applications. ABB Ltd. dominates high-power rotary converter segments for aerospace ground support equipment across Nordic defense procurement channels.
A frequency converter transforms electrical power from one frequency to another, typically converting 50 Hz grid supply to 60 Hz (or inverse) through rectifier-inverter stages with output waveform fidelity measured by total harmonic distortion below 5 percent. Static frequency converter deployments lead volume in European industrial motor retrofit programs where variable-speed drives cut energy consumption in pumping and compressed air systems. Rotary frequency converters retain structural importance in aerospace ground power units where galvanic isolation and ride-through capability justify higher capital outlays. Integrated technology installations are gaining fastest in renewable energy as turbine OEMs specify converter-transformer combinations that streamline grid compliance.
The EU Ecodesign Directive and F-Gas Regulation shape product standards by mandating minimum efficiency classes and restricting refrigerant choices in converter cooling systems. CE marking requirements under the Low Voltage Directive and Electromagnetic Compatibility Directive govern market access for all equipment sold within the European Economic Area. Germany's KBA and France's ANSM apply sector-specific testing protocols for marine and medical converter applications respectively. Stakeholders must monitor how the EU AI Act's risk classification framework extends to autonomous converter diagnostics in predictive maintenance architectures.
Market Dynamics
The EU Green Deal's energy efficiency mandates are compressing replacement cycles for electromechanical drive systems, forcing industrial operators across Germany's Ruhr cluster and northern Italy's manufacturing corridor to accelerate static frequency converter adoption.
Growth Catalysts
- Industrial Motor Retrofit Mandates:The EU Ecodesign Directive's updated efficiency tiers require variable-speed drives in pumping and compressed air systems across European manufacturing facilities.
- REACH Compliance:Chemical substance restrictions are eliminating legacy converter cooling fluids, creating replacement demand for refrigerant-compliant thermal management systems in marine propulsion applications.
- Offshore Wind Grid Integration:Converter-transformer combinations streamline grid compliance for turbine OEMs connecting North Sea installations to continental transmission networks.
Market Restraints
- Semiconductor Supply Concentration:IGBT and SiC module fabrication concentrates in East Asian foundries, exposing European converter assemblers to input volatility and extended lead times.
- CE Marking Complexity:The Low Voltage Directive and Electromagnetic Compatibility Directive impose multi-stage conformity assessment costs that disproportionately burden sub-50 kW equipment producers.
- Rotary Converter Substitution:Static converter reliability improvements are displacing galvanic-isolation rotary units in aerospace ground power applications, eroding premium segment margins.
Strategic Opportunities
- Polish Industrial Corridor:Underpenetrated manufacturing automation in Silesia's automotive supply chain offers volume expansion for mid-power static converter suppliers.
- Predictive Maintenance Convergence:The EU AI Act's risk classification framework creates first-mover advantage for converter OEMs integrating autonomous diagnostics with edge computing architectures.
- Marine Electrification:France's ANSM testing protocols for medical-grade converters can extend to harbor tugboat propulsion systems as port authorities mandate shore-power compatibility.
Industry Challenges
- Power Electronics Talent Scarcity:European engineering programs produce insufficient specialists in wide-bandgap semiconductor gate drive design, constraining R&D throughput for next-generation SiC inverters.
- Legacy System Integration:Retrofit installations in Germany's brownfield manufacturing plants require custom firmware adaptation to interface with 1990s-era PLC architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Frequency Converter Market |
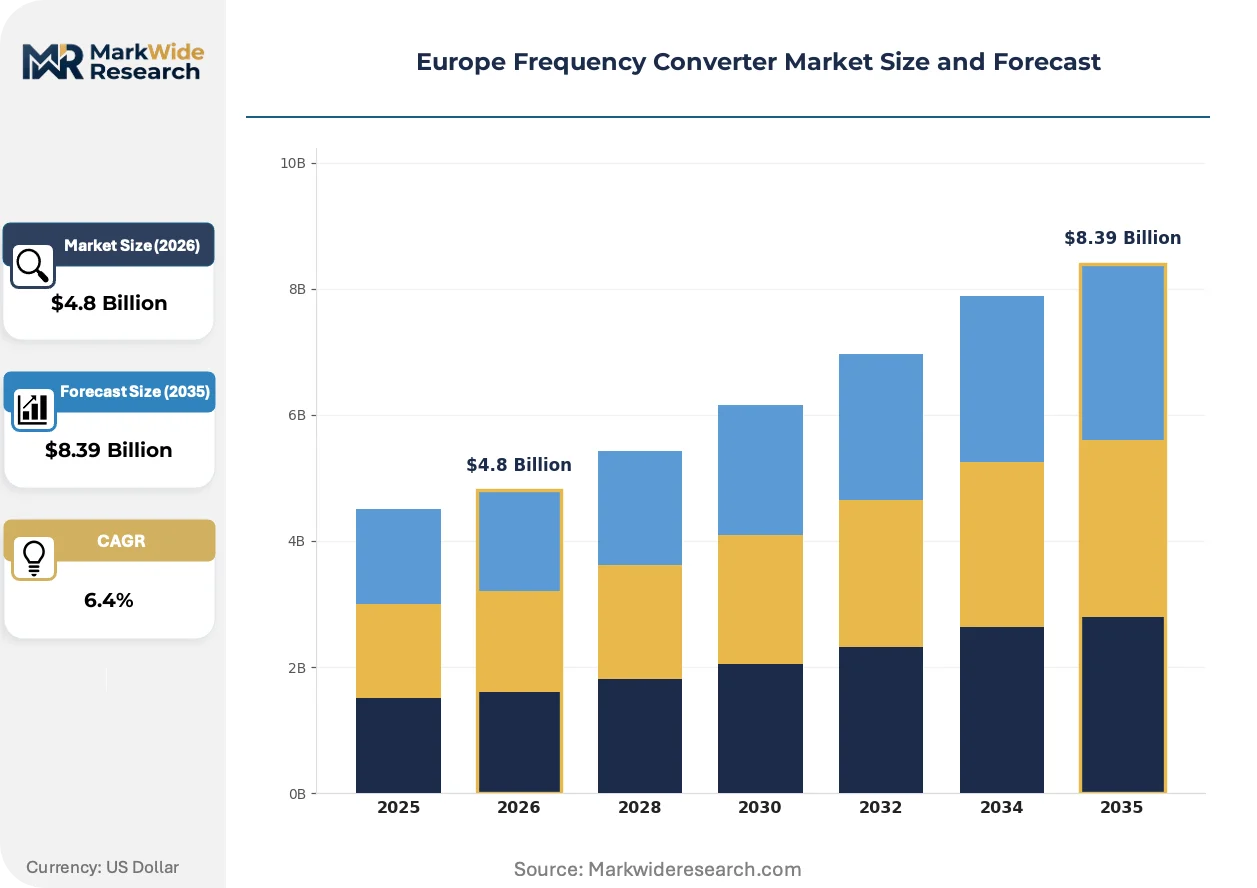
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Frequency Converter, Rotary Frequency Converter, Electronic Frequency Converter, Hybrid Frequency Converter End User: Aerospace, Marine, Industrial, Renewable Energy Technology: Inverter Technology, Transformer Technology, Electromechanical Technology, Integrated Technology Installation: Indoor, Outdoor, Portable, Permanent |
| Companies Covered | Siemens AG, ABB Ltd., General Electric Company, Danfoss, Schneider Electric, Piller Group GmbH, Aplab Limited, Sinepower, Magnus Power Pvt. Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Frequency Converter Market Strategic Shifts & Innovations
Solid-state power conversion architectures are compressing the functional boundary between frequency conversion and grid-forming inverters, enabling new equipment categories that serve multiple electrical domains simultaneously.
Silicon carbide (SiC) MOSFET modules are replacing silicon IGBTs in high-frequency inverter stages, cutting switching losses by half. Offshore wind turbine OEMs in the North Sea basin are specifying SiC-based converter-transformer combinations for 66 kV collection grid connections. This semiconductor transition is unifying medium-voltage drive and renewable grid-tie product lines into single platform architectures.
The F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing thermal management redesigns across converter cooling systems. Manufacturers must validate dielectric fluid alternatives through ECHA substance registration while maintaining IP ratings for marine and outdoor installations. Nordic defense procurement channels are prioritizing converters with natural convection or liquid-cooled architectures that eliminate refrigerant dependence entirely.
Buyer concentration among European wind turbine OEMs is compressing converter procurement into multi-year framework agreements with embedded service provisions. Equipment vendors are unbundling hardware from predictive maintenance subscriptions, shifting revenue recognition toward recurring performance guarantees. This contractual evolution is most visible in Denmark's Vestas-dominated supply chain, where converter suppliers now compete on availability metrics rather than unit pricing alone.
Europe Frequency Converter Market Segmentation
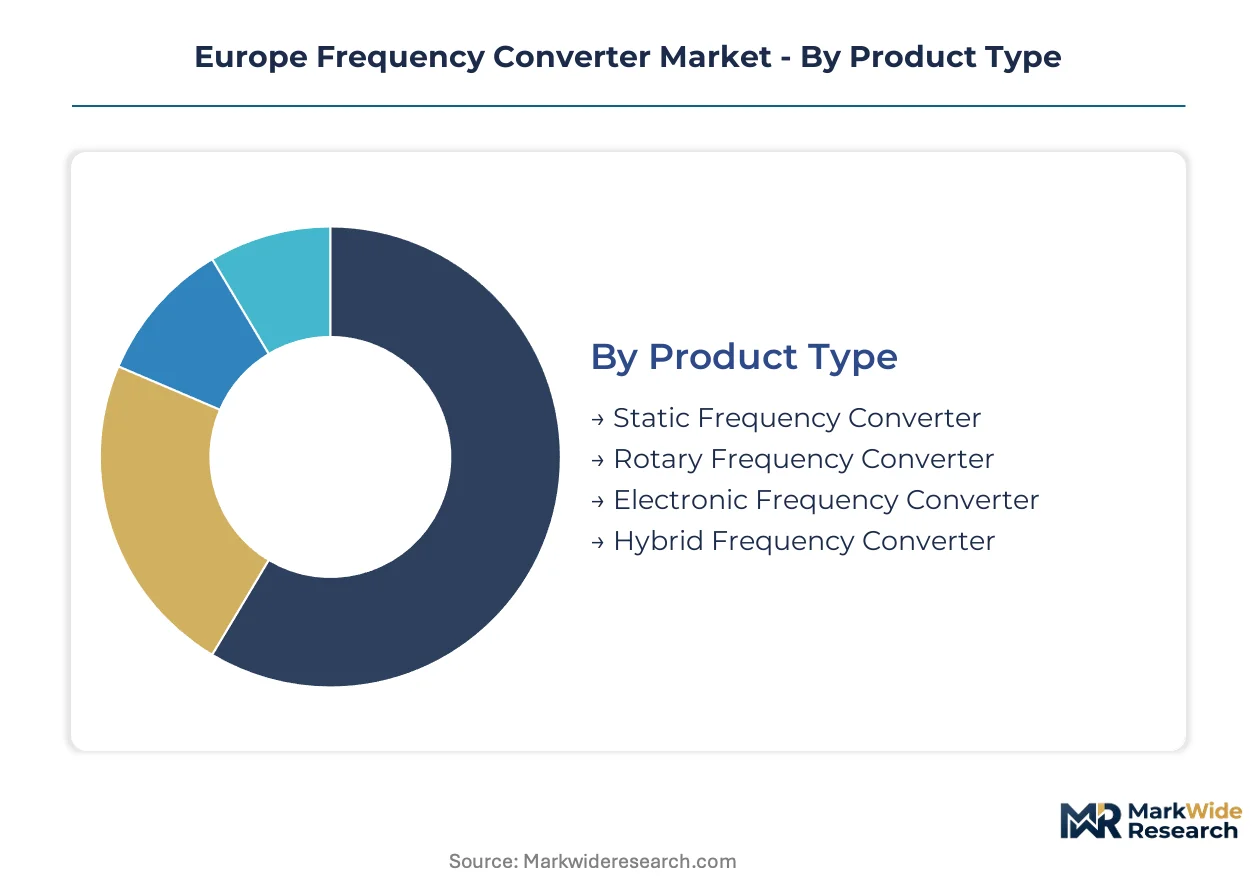
Frequency converter procurement patterns diverge sharply across application contexts, with industrial motor retrofits demanding standardized static units while offshore wind installations require integrated converter-transformer combinations. Equipment specification cascades through multiple technical dimensions that determine thermal management, enclosure ratings, and semiconductor architecture choices.
Product Type:
Supply concentration tilts toward static converter platforms where semiconductor module standardization enables volume manufacturing economies.
- Static Frequency Converter:Rectifier-inverter architectures using IGBT or SiC power modules dominate industrial motor drive retrofits. Germany's Ruhr manufacturing cluster and northern Italy's automotive supply chain absorb the majority of sub-500 kW installations for pumping and compressed air systems.
- Rotary Frequency Converter:Motor-generator sets with galvanic isolation sustain demand in aerospace ground power units where ride-through capability outweighs efficiency penalties. Nordic defense procurement channels specify these units for reliability-critical applications despite higher capital outlays.
- Electronic Frequency Converter:Solid-state designs without rotating components serve medical imaging and laboratory equipment requiring frequency stability below 0.1 percent deviation.
- Hybrid Frequency Converter:Combined electromechanical and electronic stages address specialized marine propulsion applications in France's harbor tugboat electrification programs.
Static frequency converters absorb the bulk of installed capacity; integrated technology variants are expanding most quickly through offshore wind grid connections.
End User:
Application context dictates cooling system architecture, with marine and renewable energy installations requiring IP-rated enclosures absent in standard industrial deployments.
- Industrial:Variable-speed drives for motor retrofit programs dominate volume, concentrated in Germany's brownfield manufacturing plants and Poland's Silesian automotive corridor. The EU Ecodesign Directive's efficiency tiers mandate these installations in pumping and compressed air systems.
- Renewable Energy:Converter-transformer combinations streamline grid compliance for North Sea wind turbine OEMs connecting to continental transmission networks. SiC-based architectures are displacing silicon IGBTs in 66 kV collection grid applications.
- Aerospace:Ground support equipment specifications prioritize rotary converter reliability for aircraft power during maintenance operations.
- Marine:Thermal management specialization dominates procurement, with Danfoss and competitors optimizing for salt-air corrosion resistance in propulsion systems.
Industrial end users absorb the bulk of installed capacity; renewable energy applications are climbing the fastest as turbine OEMs consolidate procurement into multi-year framework agreements.
Technology:
Semiconductor transition economics favor inverter technology adoption where SiC MOSFET module costs have reached parity with silicon IGBTs in medium-voltage applications.
- Inverter Technology:PWM-controlled switching stages using IGBT or SiC modules enable variable-frequency output with harmonic distortion below 5 percent. Offshore wind OEMs in the North Sea basin specify these for direct grid-forming capability.
- Integrated Technology:Combined converter-transformer units reduce footprint and installation complexity for renewable energy connections. Equipment vendors unbundle hardware from predictive maintenance subscriptions in Denmark's Vestas-dominated supply chain.
- Transformer Technology:Line-frequency magnetics provide galvanic isolation in legacy industrial installations requiring minimal harmonic content.
- Electromechanical Technology:Rotating machinery retains niche applications where electromagnetic compatibility isolation exceeds solid-state capabilities.
Inverter technology absorbs the bulk of installed capacity; integrated technology platforms are gaining share fastest through renewable energy procurement consolidation.
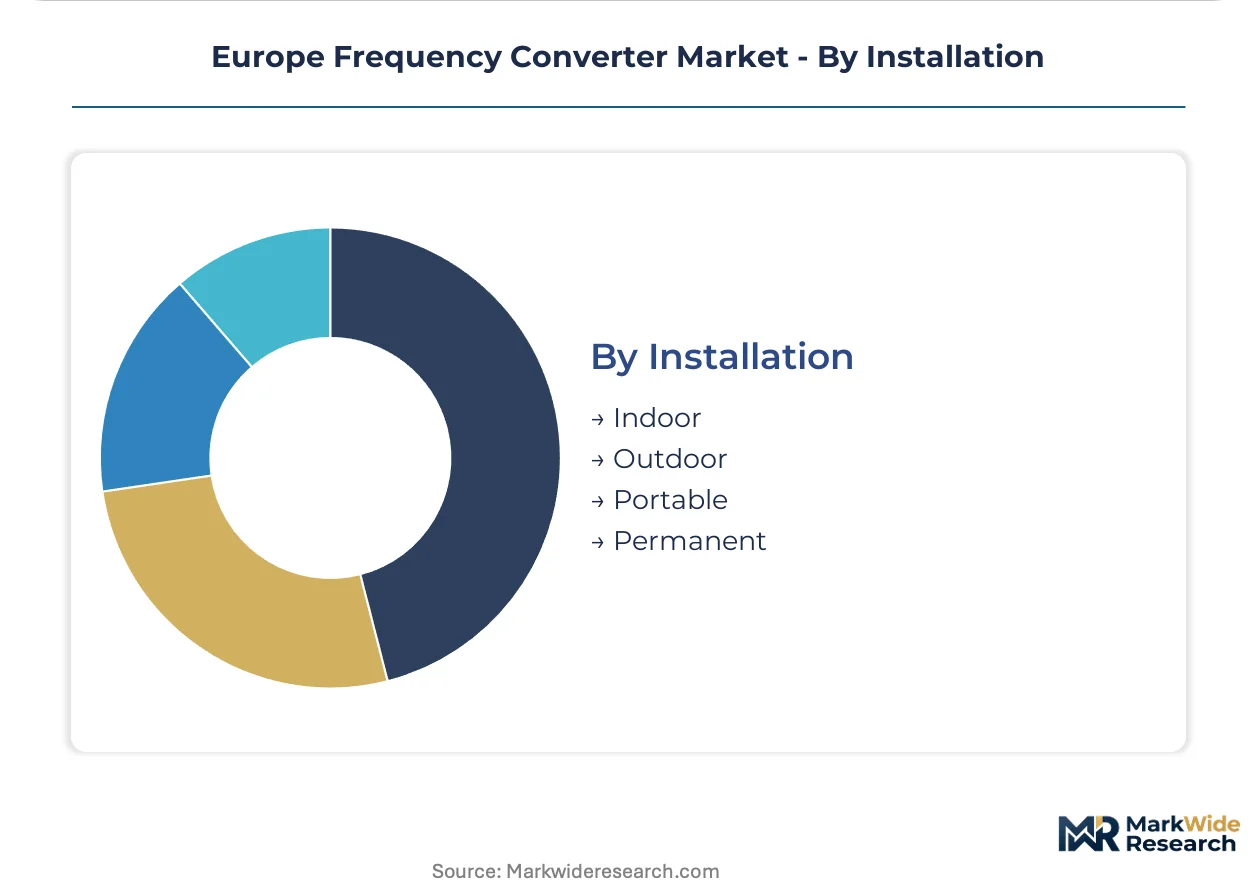
Installation:
Enclosure specification tracks environmental exposure, with outdoor and marine installations demanding dielectric fluid alternatives compliant with the F-Gas Regulation's hydrofluorocarbon phasedown.
- Indoor:Standard NEMA/IP20 enclosures serve climate-controlled manufacturing facilities across Germany's industrial heartland. These installations dominate replacement cycles for electromechanical drive systems under EU Green Deal efficiency mandates.
- Outdoor:Weatherproof housings with active cooling sustain North Sea offshore wind converter installations exposed to salt spray and temperature cycling.
- Portable:Mobile units serve temporary power applications in construction and event infrastructure where grid connection is unavailable.
- Permanent:Fixed installations in industrial process lines require custom firmware adaptation to interface with legacy PLC architectures from the 1990s.
Indoor installations absorb the bulk of installed capacity; outdoor configurations are expanding most quickly through offshore wind deployment acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial cluster anchors frequency converter deployment across Europe, with variable-speed drive retrofits absorbing the majority of static converter installations in brownfield manufacturing facilities.
Germany
The Ruhr manufacturing belt and Bavaria's automotive corridor drive static converter demand for pumping and compressed air system retrofits. Germany's KBA enforces sector-specific testing protocols for marine propulsion applications. Siemens AG leverages its Nuremberg automation hub to anchor premium positioning in offshore wind grid connections.
France
Harbor tugboat electrification programs in Marseille and Le Havre create specialized demand for hybrid converter configurations. France's ANSM applies medical-grade testing standards that extend to marine propulsion certification pathways. The Provence-Alpes-Côte d'Azur region concentrates procurement for shore-power compatible systems.
Italy
Northern Italy's manufacturing corridor from Milan to Turin absorbs mid-power static converters for automotive supply chain automation. The EU Ecodesign Directive's efficiency tiers mandate variable-speed drives across Emilia-Romagna's packaging machinery sector. Lombardy's industrial automation cluster leads replacement cycles for legacy electromechanical systems.
Poland
Silesia's automotive supply chain offers underpenetrated volume expansion for mid-power static converter suppliers. REACH compliance requirements eliminate legacy cooling fluids from converter installations in Gdansk shipyards. The Warsaw industrial zone accelerates automation adoption as EU Green Deal funding reaches central European manufacturing.
Denmark
Vestas-dominated wind turbine supply chains consolidate converter procurement into multi-year framework agreements with embedded service provisions. The F-Gas Regulation's hydrofluorocarbon phasedown forces thermal management redesigns across North Sea offshore installations. Copenhagen's procurement channels prioritize predictive maintenance subscriptions over unit pricing alone.
Europe Frequency Converter Market Key Industry Players
Premium-margin players sit above commodity-margin players across semiconductor architecture and thermal management specialization. The vendor base organizes into three tiers: diversified industrial conglomerates with automation software stacks, power electronics specialists with thermal management expertise, and regional fabricators serving retrofit installation channels. Two dominant competitive moves are reshaping positioning: unbundling hardware from predictive maintenance subscriptions, and backward integration into wide-bandgap semiconductor gate drive design.
Among Germany-based industrial conglomerates, Siemens AG exemplifies premium-tier positioning through integrated automation platforms. ABB Ltd. occupies a position within high-power rotary converter segments for defense-critical applications. Danfoss represents thermal management specialization that sustains converter reliability in marine environments.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd. |
| General Electric Company |
| Danfoss |
| Schneider Electric |
| Piller Group GmbH |
| Aplab Limited |
| Sinepower |
| Magnus Power Pvt. Ltd. |
| Others |
Cost & Logistics Intelligence
IGBT and SiC semiconductor module costs cascade through three distinct pricing tiers for European frequency converter assemblers, with wide-bandgap gate drive designs commanding premium positioning against commodity silicon architectures serving standard industrial motor retrofits.
Pricing Analysis
Availability-based pricing anchors procurement frameworks for offshore wind turbine OEMs, where converter suppliers compete on uptime guarantees rather than unit economics. Three-tier pricing structure across premium integrated systems, standard static converters, and economy rotary units differentiates by semiconductor architecture and thermal management sophistication. Cost compression in sub-50 kW equipment intensifies because CE marking complexity disproportionately burdens smaller producers. Industrial end users in Germany's Ruhr cluster exhibit highest price sensitivity, while Nordic defense procurement channels absorb premium margins for reliability-critical rotary units.
Supply Chain Analysis
Dual-sourcing mandates from Vestas and Siemens Gamesa force converter OEMs to qualify IGBT and SiC modules from both East Asian and European foundries. Module fabrication concentrates in Taiwan, South Korea, and China, exposing European assemblers to input volatility and extended lead times. Supply chain risk centers on single-source vulnerability for 1700V SiC MOSFETs in medium-voltage applications. Distribution runs through direct framework agreements with wind turbine OEMs and industrial automation distributors serving retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wide-bandgap semiconductor fabrication capacity constraints prop pricing power for converter OEMs with captive gate drive design capabilities, insulating premium tiers from commodity erosion.
For Market Incumbents: Deploy predictive maintenance subscription unbundling to defend recurring revenue streams against static converter commoditization. Backward integration into SiC module packaging secures supply continuity as East Asian foundry allocation tightens. Certification investment in France's ANSM marine pathways creates defensible positioning in harbor electrification programs. For New Entrants and Emerging Players: Begin with Poland's Silesian automotive corridor, where underpenetrated automation demand absorbs mid-power static converters without entrenched incumbent relationships. Target brownfield manufacturing facilities requiring custom firmware adaptation for 1990s-era PLC architectures. Pursue white-label partnerships with German industrial distributors lacking in-house converter engineering. For Investors and Strategic Acquirers: Distressed-cycle entries favor thermal management specialists with F-Gas-compliant cooling architectures in Denmark and Germany. Five-to-ten year viability hinges on SiC inverter platform consolidation eliminating electromechanical rotary alternatives. Monitor Vestas procurement framework renewal timing as inflection indicator for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Module Packaging | Captive supply of wide-bandgap semiconductors insulates margins from East Asian foundry volatility. |
| Predictive Maintenance Subscription Unbundling | Revenue recognition shifts from hardware sales to availability guarantees in Vestas-dominated supply chains. |
| F-Gas-Compliant Thermal Management Redesign | Dielectric fluid alternatives unlock marine and offshore wind procurement channels under EU regulation. |
| Polish Industrial Corridor Market Entry | Silesia's automotive supply chain automation gap absorbs volume without entrenched competitor presence. |
| Custom Firmware Adaptation Capability | Legacy PLC integration expertise captures Germany's brownfield manufacturing retrofit demand. |
Research Approach
Document review covered EU Ecodesign Directive filings, F-Gas Regulation substance registrations, and Nordic defense procurement databases, complemented by interviews with converter OEM product managers, wind turbine procurement directors, and marine classification society engineers. Secondary validation drew from ECHA chemical substance data, CE marking conformity assessment records, and offshore wind project development pipelines. Bottom-up installation counts across Germany's Ruhr cluster and Poland's Silesian corridor were triangulated against top-down semiconductor module import statistics.
Cross-referencing historical retrofit adoption curves with expert panel input on EU Green Deal implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user application, semiconductor architecture, and installation environment. CAGRs were derived from unit shipment trajectories weighted by average selling price evolution in integrated versus standalone converter configurations. Forecast inputs incorporated REACH compliance-driven replacement cycles and SiC cost-parity assumptions in medium-voltage applications.
Underlying measurement precision varies by segment; offshore wind installations carry tighter precision than dispersed industrial retrofits due to consolidated buyer visibility. Forecasts reflect assumptions on semiconductor supply normalization and EU AI Act diagnostic software classification pathways. Deviation in East Asian foundry allocation policies or F-Gas Regulation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Nigeria Power Market
Power
Power Sled Market
Power
Rotating Phase Converter Market
Power
Water Turbine Market
Power
Mexico Power EPC Market
Power
Gabon Power Market
Power
Controllable Shunt Reactor for UHV Market
Power
Flue Gas Desulfurization Unit Market
Power
Europe Solar Inverter Market
Power
Modified Sine Wave Home Inverters Market
Power
Smart Power Market
Power
Existent Gum Steam Generator Market
Power
Global Ancillary Services Power Market
Power
Sudan Power EPC Market
Power
Europe Power Purchase Agreement Market
Power
Wind Alarm Controller Market