
 LNG Power Barge Market | 2026-2036
LNG Power Barge Market Size, Share, and Industry Trends Forecast 2026-2036
LNG Power Barge Market Insights
Marine engineering talent scarcity is reorganizing how vessel integrators approach project execution, with specialized welders and LNG systems technicians commanding premium deployment terms. Karpowership anchors its competitive stance through captive fleet availability and rapid mobilization protocols for utility offtakers. Wison Group leverages Chinese shipyard capacity and modular fabrication methods to compress delivery schedules for Asian buyers. MODEC sustains technology leadership through deepwater mooring expertise transferred from its FPSO portfolio.
An LNG power barge is a flat-hulled marine vessel housing gas-fired generation equipment, typically incorporating dual-fuel reciprocating engines or aeroderivative gas turbines with outputs ranging from 30 MW to 500 MW, designed for grid-connected or island-mode power delivery. The primary commercial purpose is to provide utility-scale electricity in locations where land-based construction faces geographic, regulatory, or economic barriers. Combined cycle technology configurations capture the fastest-growing share of new orders as operators prioritize fuel efficiency and heat-rate performance over simple-cycle alternatives. Power generation applications dominate current deployment value, though renewable integration segments are gaining traction as hybrid barge designs incorporate battery storage and solar augmentation to firm intermittent output.
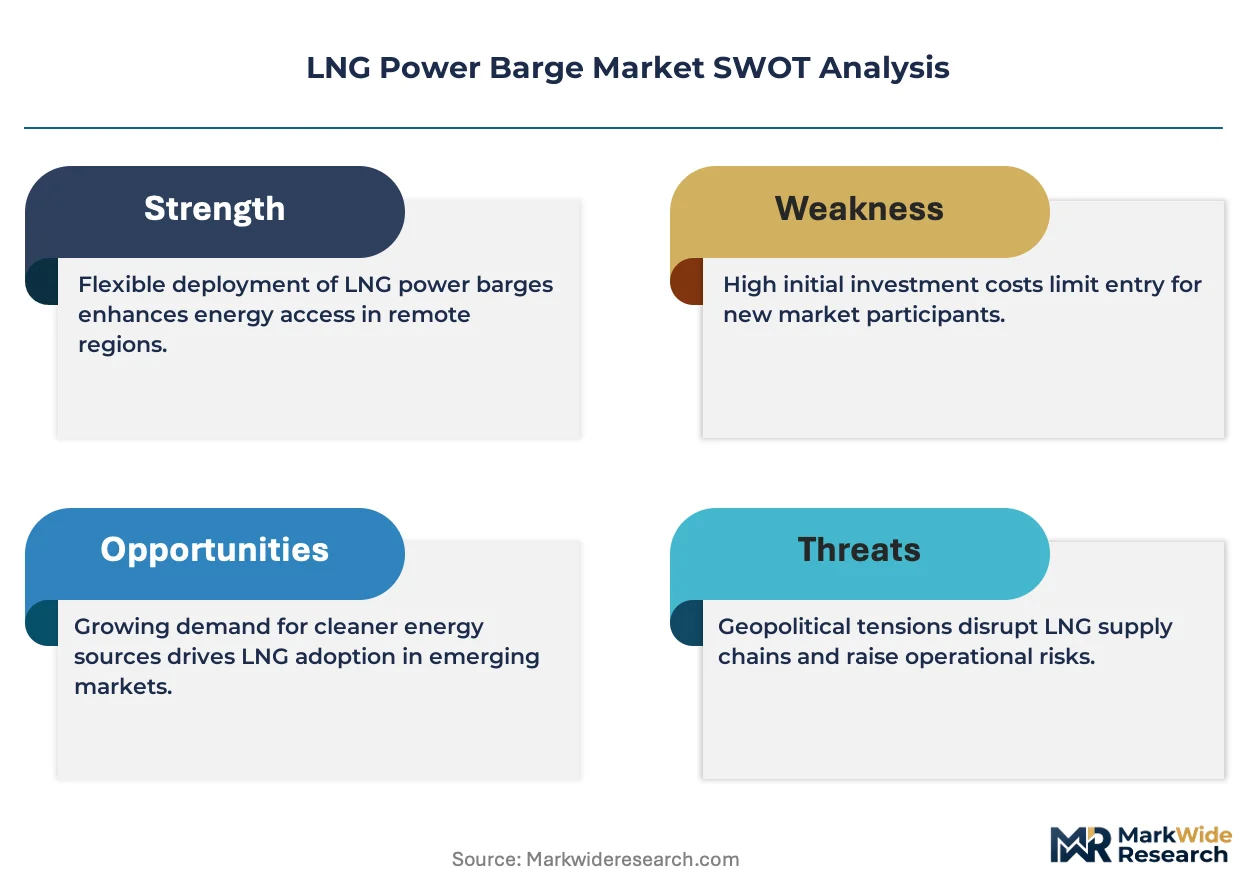
IMO Tier III standards and MARPOL Annex VI enforcement by flag-state administrations are elevating capital requirements for onboard emissions abatement systems, directly shaping vessel specification decisions. The US Coast Guard and classification societies including DNV and Bureau Veritas impose structural and containment standards that determine market access for builders without prior LNG carrier or offshore unit credentials. Stakeholders must monitor evolving carbon-border adjustment mechanisms and local content mandates that threaten to fragment procurement strategies across jurisdictions.
Market Dynamics
Dual-fuel engine technology is compressing project timelines and reshaping how utilities evaluate floating power assets against land-based alternatives. Marine classification requirements from DNV and Bureau Veritas now mandate emissions abatement systems that alter vessel economics and procurement criteria.
Growth Catalysts
- IMO Tier III Compliance:Flag-state administrations enforce nitrogen oxide limits that drive replacement of aging diesel barges with LNG-fueled alternatives in Southeast Asian archipelagos.
- Island Grid Extension Economics:Remote coastal utilities in the Caribbean and West Africa deploy floating assets where submarine cable interconnection costs exceed $3 million per kilometer.
- Heat Rate Performance:Combined cycle configurations achieve thermal efficiencies above 50 percent, compelling procurement officers to favor gas turbine integration over reciprocating engine alternatives.
Market Restraints
- Specialized Welder Scarcity:Cryogenic containment fabrication requires ASME Section IX-certified welders commanding premium deployment terms that extend yard schedules.
- Chinese Shipyard Concentration:Modular fabrication capacity clusters in Yangtze River delta facilities, creating single-source vulnerability for Asian buyers.
- Battery Storage Substitution:Lithium-ion containerized systems paired with solar arrays threaten simple-cycle barge economics in 50-100 MW demand segments.
Strategic Opportunities
- Hybrid Renewable Integration:Battery augmentation and photovoltaic deck-mounted arrays create firming capability that expands addressable demand beyond pure backup power.
- West African Coastal Zones:Nigerian and Ghanaian utilities lack transmission infrastructure to connect stranded gas reserves, creating captive demand for floating regasification-power combinations.
- EU Carbon Border Adjustment:CBAM implementation elevates lifecycle emissions scrutiny that advantages LNG barges over coal-fired alternatives in European overseas territories.
Industry Challenges
- LNG Systems Technician Shortage:Cryogenic cargo handling and boil-off gas management expertise resides with fewer than twelve specialized training centers worldwide.
- Classification Society Coordination:Bureau Veritas, DNV, and Lloyd's Register maintain divergent containment system standards that complicate multi-jurisdiction deployment planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LNG Power Barge Market |
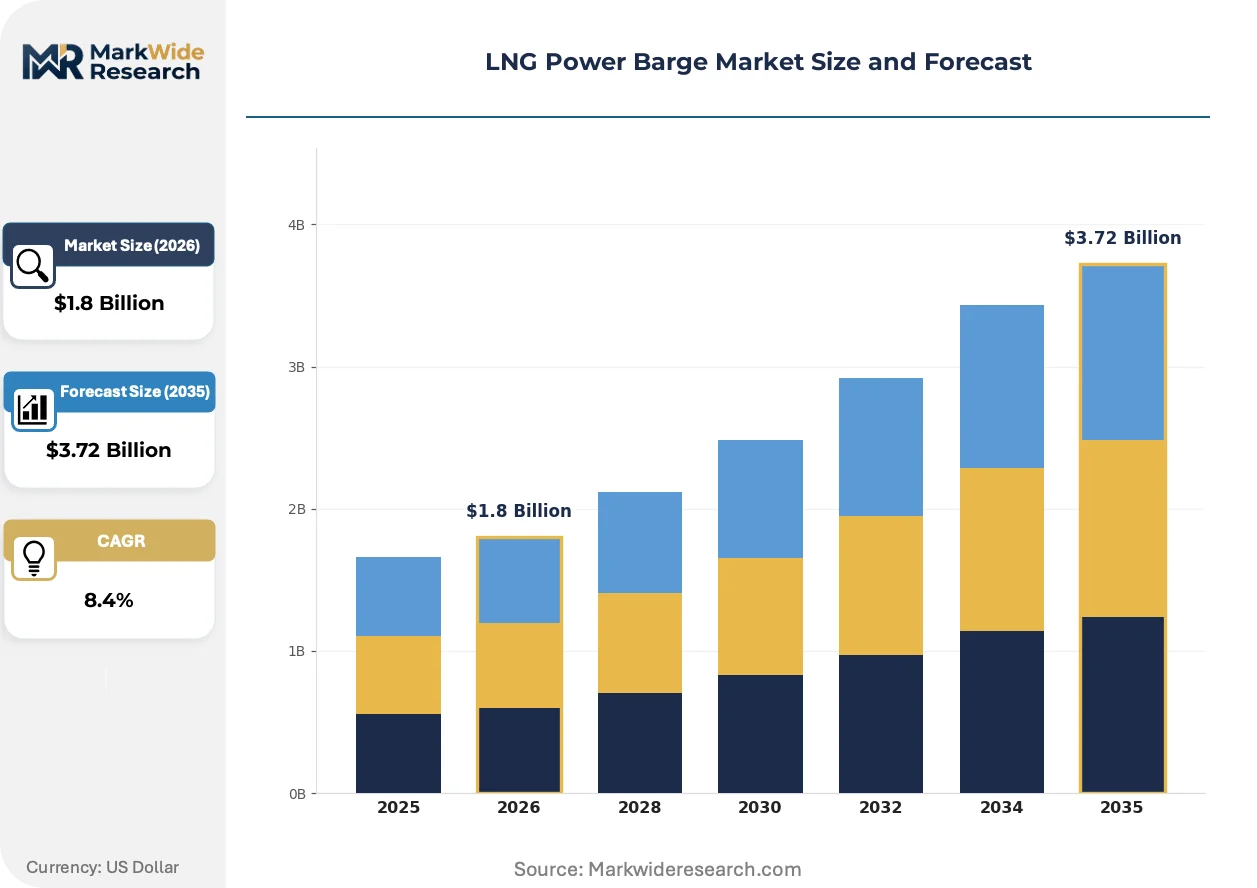
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Power Generation, Emergency Backup, Renewable Integration, Hybrid Systems Technology: Floating Storage, Gas Turbines, Reciprocating Engines, Combined Cycle End User: Utility Companies, Industrial Facilities, Remote Communities, Offshore Operations Deployment: Onshore, Offshore, Temporary, Permanent |
| Companies Covered | MODEC, Wison Group, Crowley, Golar LNG, SBM Offshore, Fincantieri Bay Shipbuilding, Karpowership, Seaside LNG, Shell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LNG Power Barge Market Trends and Innovations
Technology trajectories in floating power generation center on fuel flexibility, emissions containment, and modular integration methods that compress delivery schedules. Regulatory enforcement patterns and procurement model evolution are simultaneously reshaping competitive positioning.
Aeroderivative gas turbine packages configured for dual-fuel operation are supplanting medium-speed diesel engines in 100-300 MW barge specifications. Southeast Asian independent power producers prioritize these systems for their rapid start capability and 10-minute grid synchronization. The technology is supplanting reciprocating engine dominance in baseload applications where heat rate economics outweigh capital cost sensitivity.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing refrigerant selection changes in onboard regasification systems. Vessel integrators now specify ammonia or CO2 cascade cycles for boil-off gas reliquefaction rather than conventional HFC-based equipment. European-flagged units and those serving EU overseas territories face the most stringent retrofit obligations, compressing technology refresh cycles.
Utility offtakers increasingly specify availability-based contracting with fuel-pass-through structures rather than traditional capacity payment mechanisms. This transfers operational risk to vessel owners while locking in heat rate guarantees. Indonesian and Philippine distribution utilities pioneered this structure, which now spreads to Caribbean procurement frameworks.
LNG Power Barge Market Segmentation
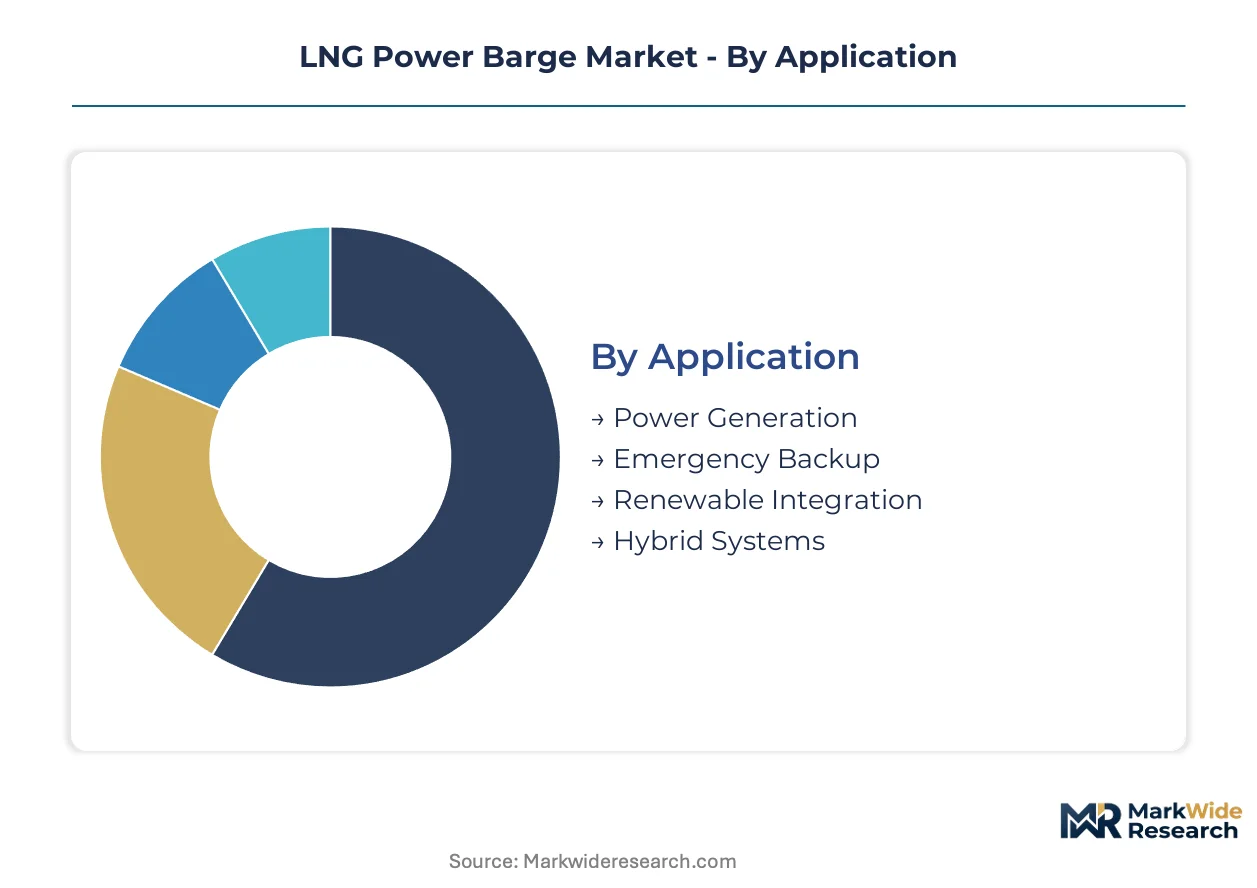
Floating gas-to-power assets serve heterogeneous demand profiles that fragment procurement specifications across output scale, fuel flexibility, and mooring permanence. Segment boundaries determine vessel engineering priorities, contracting structures, and regulatory compliance pathways for integrators and offtakers.
Application:
Margin pools concentrate in baseload power generation contracts with 15-20 year tenors, while shorter-cycle emergency and hybrid applications command premium day-rates for fleet flexibility.
- Power Generation:Continuous electricity delivery to island grids and coastal utilities anchors commercial volumes. Indonesian and Philippine distribution utilities specify 100-300 MW units with heat rate guarantees above 50 percent thermal efficiency, locking in fuel pass-through structures that transfer price risk to vessel operators.
- Emergency Backup:Rapid-mobilization contracts for disaster response and grid stabilization capture scarcity premiums. Caribbean utilities facing hurricane seasonality procure these assets with 72-hour activation clauses, paying availability fees that exceed baseload tariffs by 40-60 percent during peak risk windows.
- Renewable Integration:Battery-augmented barges firm intermittent solar and wind output.
- Hybrid Systems:Dual-fuel configurations with photovoltaic deck arrays serve remote industrial loads.
Power Generation holds installed capacity. Renewable Integration is rotating up the share rankings.
Technology:
Technology selection pivots on tradeoffs between capital intensity, thermal efficiency, and operational flexibility that vary by offtaker fuel access and grid synchronization requirements.
- Combined Cycle:Heat recovery steam turbines paired with aeroderivative gas turbines achieve thermal efficiencies above 55 percent. Southeast Asian independent power producers prioritize these systems for baseload procurement where fuel economics dominate lifecycle cost calculations over 15-year contract horizons.
- Gas Turbines:Aeroderivative packages configured for dual-fuel operation enable 10-minute grid synchronization. Nigerian utilities specify these for stranded gas field development where rapid ramping compensates for transmission infrastructure deficits.
- Reciprocating Engines:Medium-speed dual-fuel units dominate 30-80 MW specifications for remote community electrification.
- Floating Storage:Regasification-power combinations integrate LNG cargo handling with generation equipment.
Combined Cycle commands pricing premiums. Reciprocating Engines is rotating up the share rankings.
End User:
Customer type determines contracting sophistication, credit support requirements, and operational interface complexity for vessel operators.
- Utility Companies:State-owned distribution utilities in Indonesia, the Philippines, and Ghana procure through competitive tenders with availability-based payment structures. These offtakers demand 95 percent reliability guarantees and impose liquidated damages for non-performance that shape vessel maintenance protocols.
- Industrial Facilities:Mining and petrochemical operators in West Africa specify captive power barges for processing plant electrification. Ghanaian bauxite and gold producers contract directly with vessel owners, bypassing grid interconnection queues that extend 3-5 years for land-based generation permits.
- Remote Communities:Island municipalities in the Caribbean procure smaller units through development finance intermediaries.
- Offshore Operations:Platform electrification and drilling support vessels create specialized demand for motion-compensated units.
Utility Companies hold installed capacity. Industrial Facilities is rotating up the share rankings.
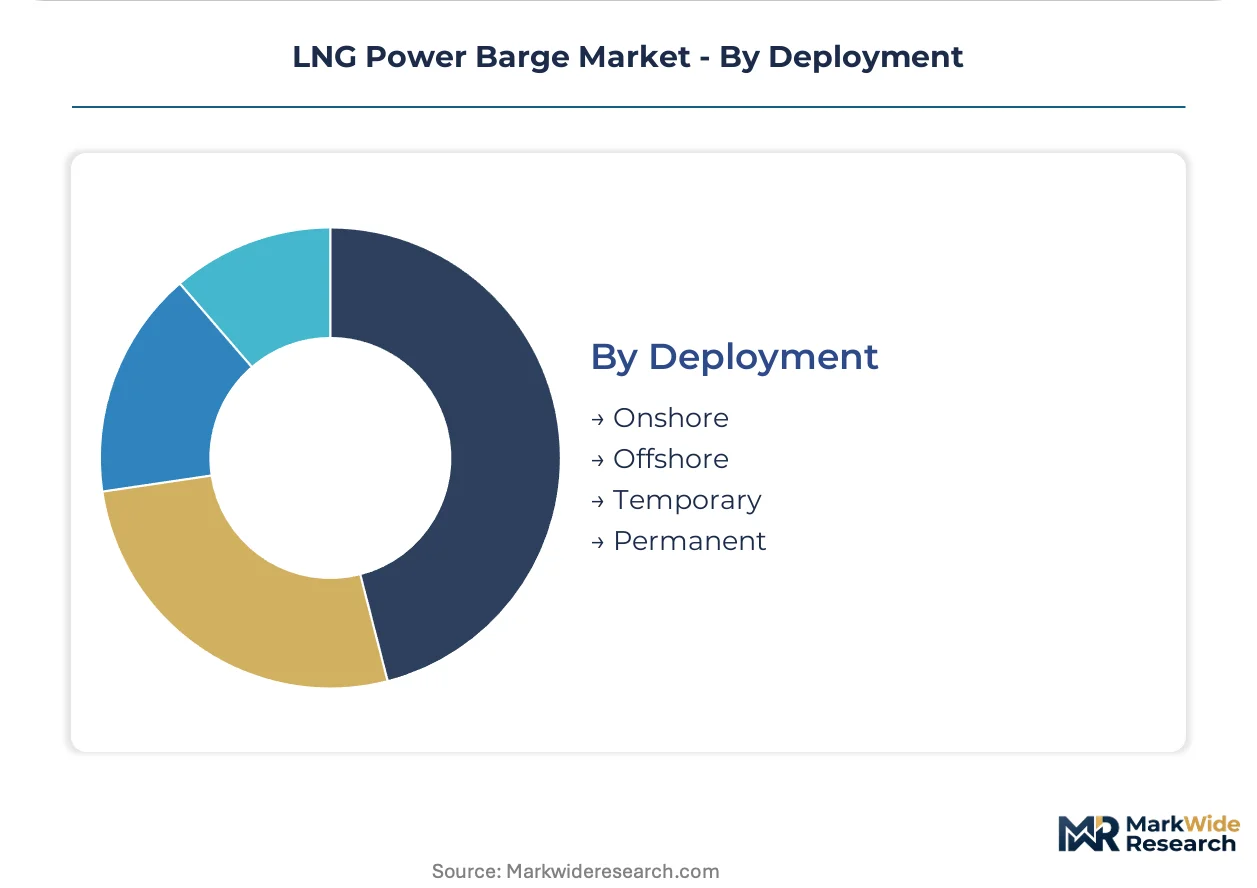
Deployment:
Mooring permanence and jurisdictional location determine classification society requirements, insurance pricing, and local content compliance exposure.
- Permanent:Fixed-moored installations with 20-25 year asset lives dominate Southeast Asian procurement. Indonesian utilities at Benoa and Nusantara specify permanent moorings with submerged pipelines to onshore regasification terminals, amortizing capital costs across extended contract tenors.
- Offshore:Dynamic positioning and spread-mooring configurations serve platform electrification and stranded gas field development. Ghanaian offshore oil operations deploy these units where pipeline tieback costs exceed floating asset economics at water depths beyond 50 meters.
- Temporary:Rapid-mobilization contracts for seasonal peak shaving and emergency response.
- Onshore:Quayside-connected units at existing port infrastructure serve harbor facilities and coastal manufacturing.
Permanent holds installed capacity. Offshore is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Indonesian and Philippine procurement offices where utility tenders command heat-rate guarantees, while West African buyers absorb freight premiums for rapid-mobilization contracts. This asymmetry fragments contracting sophistication across archipelagic and coastal markets.
Indonesia
State-owned utility PLN tenders 100-300 MW units for Nusantara and Benoa anchorages where submarine cable economics fail. The country's Ministry of Energy and Mineral Resources mandates local content thresholds that shape vessel specification decisions. Java-Bali grid interconnection gaps drive procurement at Surabaya and Makassar port clusters.
Philippines
Distribution utilities in Visayas and Mindanao procure floating assets where transmission infrastructure spans volcanic island chains. The Philippine Energy Regulatory Commission imposes reliability standards that determine maintenance protocol investments. Batangas and Subic Bay anchorages concentrate permanent-mooring specifications for industrial zone electrification.
Ghana
Stranded gas field development offshore Tema and Takoradi creates demand for regasification-power combinations where pipeline tieback costs prove prohibitive. The country's Petroleum Commission regulates local participation requirements that alter vessel ownership structures. Mining operators in the Ashanti belt contract directly for captive power barges bypassing grid queues.
Nigeria
Transmission infrastructure deficits across the Niger Delta compel offshore oil operators to deploy dynamic-positioning units at water depths exceeding 50 meters. The Nigerian Electricity Regulatory Commission oversees offtake agreements that transfer operational risk to vessel owners. Lagos and Port Harcourt harbor facilities anchor quayside-connected specifications for manufacturing electrification.
Caribbean Island Chain
Hurricane seasonality drives 72-hour activation clauses across Puerto Rico, Dominican Republic, and Jamaican utility procurement. The US Coast Guard and classification societies impose structural standards that determine market access for non-traditional builders. San Juan and Kingston port authorities concentrate temporary-mooring contracts for seasonal peak shaving.
LNG Power Barge Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with deepwater mooring specialists commanding premium positioning against modular fabricators competing on delivery compression. The vendor base spans three tiers: integrated energy majors with captive LNG portfolios, specialized marine contractors with FPSO heritage, and Asian shipyard-affiliated integrators leveraging production scale. Competitive dynamics center on fleet availability guarantees and heat-rate performance contracting rather than pure capital cost competition. Strategic moves concentrate on hybrid renewable integration partnerships and West African market entry through local content joint ventures.
Among specialized marine contractors, MODEC and SBM Offshore exemplify the technology-leadership archetype through transferred deepwater expertise, while Karpowership anchors the rapid-mobilization tier with captive fleet positioning. Wison Group occupies a distinct cost-leadership position within Asian procurement corridors. These three players represent divergent strategic bets on contracting sophistication, geographic concentration, and technology integration depth.
| Leading Market Players |
|---|
| MODEC |
| Wison Group |
| Crowley |
| Golar LNG |
| SBM Offshore |
| Fincantieri Bay Shipbuilding |
| Karpowership |
| Seaside LNG |
| Shell |
| Others |
Pricing and Supply Chain Analysis
Availability-based contracting with fuel-pass-through structures locks in supply access for utility offtakers while anchoring price visibility across 15-20 year tenors. Indonesian and Philippine distribution utilities pioneered this mechanism, transferring operational risk to vessel owners and compressing procurement negotiation cycles.
Pricing Analysis
The customization-premium spread separates configured-to-order barges with hybrid renewable integration from standard simple-cycle specifications. Contract structures stratify across premium tier with combined cycle guarantees, standard tier with dual-fuel reciprocating engines, and economy tier with refurbished diesel conversions. Pricing pressure stems from lithium-ion containerized systems paired with solar arrays threatening 50-100 MW barge economics. Industrial facilities in West African mining belts exhibit highest price sensitivity due to captive power alternatives, while Caribbean utilities facing hurricane seasonality absorb scarcity premiums with least negotiation leverage.
Supply Chain Analysis
China and South Korea anchor modular fabrication capacity for hull construction and engine package integration. Cryogenic containment systems draw from specialized ASME Section IX-certified welder pools concentrated in Yangtze River delta facilities. Single-source vulnerability concentrates in Chinese shipyard clustering for Asian buyers. Distribution runs through vessel integrators with captive fleet positioning or EPC contractors managing utility tender execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term service contracts for heat-rate performance monitoring and predictive maintenance represent a recurring-revenue layer expanding faster than hardware deployment, as utility offtakers transfer operational risk to vessel owners under availability-based structures.
For Market Incumbents: Fortify competitive moats through captive fleet availability guarantees and rapid mobilization protocols that emerging Asian shipyard-affiliated integrators cannot replicate. Deepen backward integration into cryogenic containment fabrication to offset ASME-certified welder scarcity premiums. Invest in hybrid renewable integration partnerships before battery storage substitution erodes simple-cycle barge economics in mid-scale demand segments. For New Entrants and Emerging Players: Differentiate on West African coastal zone specialization where Nigerian and Ghanaian utilities lack transmission infrastructure for stranded gas field connection. Target regasification-power combination specifications in 100-300 MW segments where incumbent FPSO heritage players maintain less cost-competitive positioning. Pursue local content joint venture structures to satisfy Petroleum Commission participation requirements. For Investors and Strategic Acquirers: The market sits at a fleet-expansion phase that favors vessel operators with captive LNG portfolios and utility offtaker relationships over pure fabrication plays. Acquisition targets with permanent-mooring installation expertise in Indonesian and Philippine anchorages offer strongest 5-10 year contract visibility. Monitor IMO Tier III enforcement acceleration across Southeast Asian flag-state administrations as inflection indicator for replacement demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Renewable Integration Partnership | Battery augmentation and photovoltaic deck arrays expand addressable demand beyond pure backup power for Caribbean utilities. |
| West African Local Content Joint Venture | Petroleum Commission participation requirements in Ghana and Nigeria alter vessel ownership structures for market entry. |
| Cryogenic Containment Fabrication Investment | ASME Section IX-certified welder scarcity commands premium deployment terms that extend yard schedules. |
| Availability-Based Contracting Structure | Indonesian and Philippine utilities pioneered fuel-pass-through mechanisms now spreading to Caribbean procurement frameworks. |
| Combined Cycle Technology Licensing | Heat recovery steam turbine integration achieves thermal efficiencies above 55 percent for Southeast Asian IPP procurement. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and marine classification surveyors and refined through secondary validation. Vessel specification databases, FERC filings for US-connected assets, IEA power generation reports, and project development tracking platforms supplied quantitative anchors. Bottom-up contract aggregation triangulated against top-down regional demand modeling.
Variance decomposition across fuel flexibility tiers, generation capacity brackets, and mooring permanence categories structured the analytical framework over the projection horizon. CAGRs derived from installed capacity buildout trajectories and replacement cycle timing. Forecast inputs incorporated IMO regulatory enforcement patterns and local content mandate evolution across Indonesian and Philippine procurement offices.
Material uncertainties — flag-state administration enforcement variability, boil-off gas price volatility, and carbon-border adjustment mechanism implementation — sit outside the modeled envelope. Forecasts reflect assumptions about LNG infrastructure buildout pacing and utility credit support availability. Recalibration cycles align with material shifts in IMO Tier III adoption timelines and hybrid renewable integration cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
North America Micro CHP Market
Power
Europe Power Purchase Agreement Market
Power
Marine Thermal Fluid Heaters Market
Power
Telecom Power Rental Market
Power
Power Shelf Market
Power
Solar UPS Market
Power
Vietnam Power Market
Power
Asia-Pacific Turbomachinery Control Systems Market
Power
Italy Power Market
Power
Egypt Uninterruptible Power Supply (UPS) Market
Power
Combined Heat and Power (CHP) Systems Market
Power
China Power Market
Power
Rotating Phase Converter Market
Power
Power Purchase Agreement Market
Power
Europe Microturbine Market
Power
Digital Power Utility Market