
 Doubly Fed Induction Generator (DFIG) Market | 2026-2036
Doubly Fed Induction Generator (DFIG) Market Size, Share, and Industry Trends Forecast 2026-2036
Doubly Fed Induction Generator (DFIG) Market Insights
A capital-intensity divergence between integrated turbine OEMs and standalone generator suppliers is bifurcating competitive dynamics in the DFIG landscape. Siemens AG leverages captive converter engineering to bundle generator and power electronics packages, while GE Vernova anchors its position through in-house rotor design capabilities that reduce dependency on third-party slip-ring vendors. CRRC competes primarily on manufacturing scale, sustaining cost advantages in stator lamination production that smaller rivals cannot replicate.
A doubly fed induction generator employs a wound rotor connected to the grid through back-to-back power converters rated at roughly 30% of total machine capacity, enabling variable-speed operation across a limited slip range while maintaining synchronous connection. Wind turbines dominate DFIG deployment, though hydro generator applications are gaining traction as pumped-storage projects require adjustable-speed pump-turbine units. Control systems technology leads product differentiation, with advanced vector control algorithms commanding margin premiums, while offshore installation types represent the fastest-growing demand pool as floating platform projects proliferate.
Germany's Federal Network Agency enforces fault-ride-through standards under the Renewable Energy Sources Act that DFIG-equipped turbines satisfy through crowbar and chopper circuits, while China's National Energy Administration mandates grid-support capabilities under GB/T 19963 that shape domestic procurement specifications. IEEE 1547 interconnection standards in the United States further constrain market access for generators lacking reactive power control functionality. Stakeholders must monitor evolving converter semiconductor supply chains and silicon carbide module availability as these materials determine whether DFIG architectures retain cost advantages against full-converter synchronous alternatives.
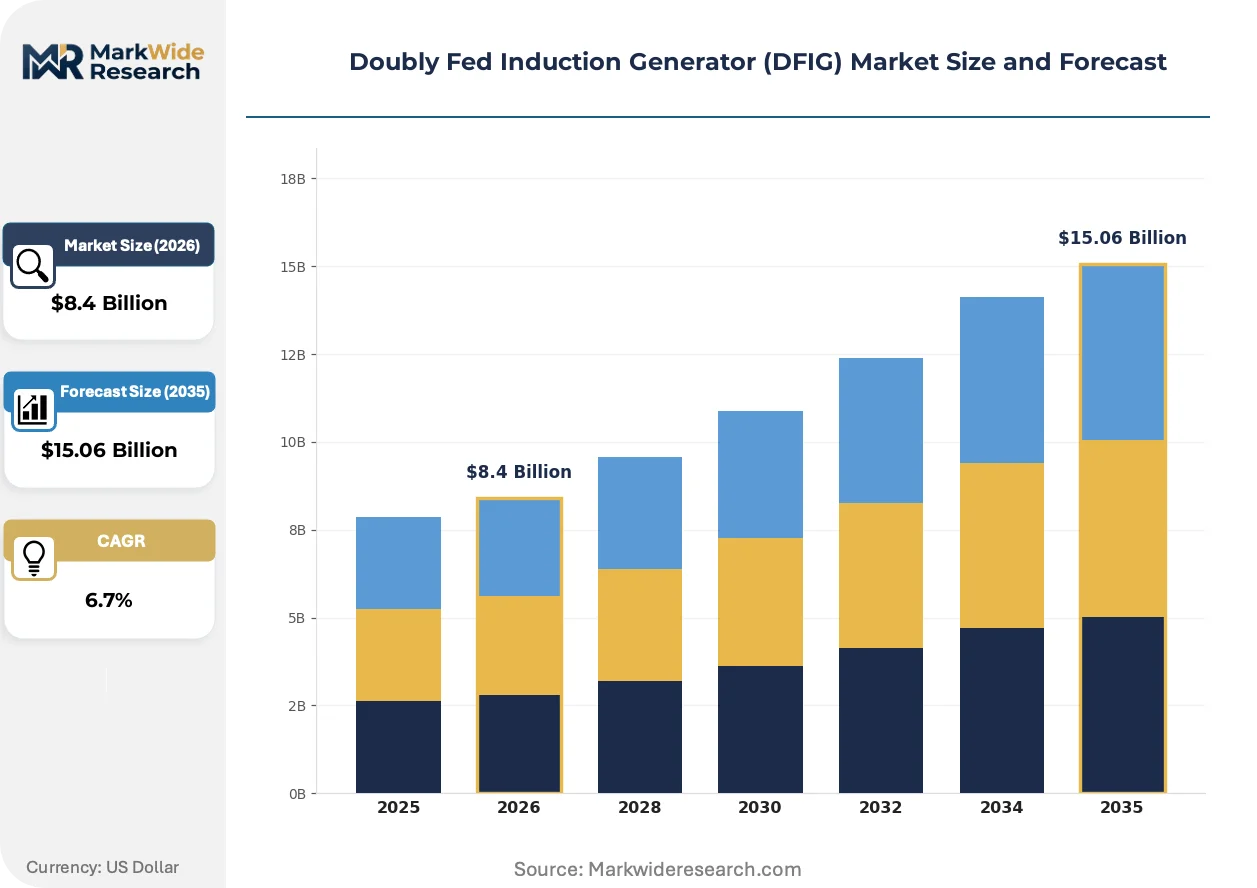
Market Dynamics
Grid code harmonization across major wind markets is forcing generator suppliers to engineer fault-ride-through capabilities as baseline specifications rather than premium add-ons. This regulatory convergence is compressing product differentiation timelines and concentrating procurement decisions around converter-integrated system architectures.
Growth Catalysts
- GB/T 19963 grid-support mandates:China's National Energy Administration requires reactive power control and low-voltage ride-through capabilities that DFIG topology delivers cost-effectively versus full-converter alternatives.
- Silicon carbide module maturation:Wide-bandgap semiconductor availability is reducing converter losses in partial-scale power electronics, extending DFIG competitive viability against synchronous generator architectures.
- Floating offshore wind proliferation:Adjustable-speed generation requirements for platform-mounted turbines in North Sea and East Asian developments favor DFIG variable-speed characteristics.
Market Restraints
- Copper and rare-earth magnet cost volatility:Wound rotor construction depends on copper windings whose price fluctuations compress margin predictability for generator manufacturers.
- Converter semiconductor supply concentration:IGBT and SiC module fabrication concentrates in East Asian foundries, creating single-source dependency risks for European and North American generator assemblers.
- Full-converter synchronous generator substitution:Permanent magnet synchronous machines with complete power electronic interfaces are capturing offshore turbine specifications above 5 MW rating.
Strategic Opportunities
- Pumped-storage hydro modernization:Adjustable-speed pump-turbine projects in Alpine and Himalayan geographies require DFIG-based motor-generator sets for grid stabilization services.
- India's renewable purchase obligations:State-level wind energy targets under CEA guidelines create procurement pull for cost-optimized variable-speed generation in Gujarat and Tamil Nadu wind corridors.
- Digital twin integration:Convergence of physics-based rotor modeling with SCADA analytics enables predictive maintenance contracts that extend generator service revenue streams.
Industry Challenges
- Power electronics firmware specialization:Vector control algorithm development requires scarce expertise in rotating reference frame transformations and grid synchronization protocols.
- Type certification timeline compression:IEC 61400-21 measurement campaigns for grid code compliance extend product qualification cycles by 12-18 months for new DFIG platform introductions.
- Slip-ring maintenance protocol standardization:Brush-gear replacement intervals vary widely across operating environments, complicating service contract pricing and customer expectation management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Doubly Fed Induction Generator (DFIG) Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wind Turbines, Hydro Generators, Solar Inverters, Synchronous Generators End Use: Power Generation, Industrial Applications, Renewable Energy, Grid Integration Technology: Control Systems, Power Electronics, Rotor Design, Machine Learning Installation Type: Onshore, Offshore, Hybrid, Retrofitting |
| Companies Covered | XEMC, CRRC, ABB, Siemens AG, CSIEM, VEM, Shandong Huali Motor, GE Vernova, Shanghai Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Doubly Fed Induction Generator (DFIG) Market Trends and Innovations
Modular converter architectures are fragmenting traditional system boundaries between generator and power electronics suppliers. This decomposition is creating new interface standards and reshaping competitive positioning around software-defined control rather than electromagnetic hardware alone.
Silicon carbide MOSFET technology is decomposing the cost-performance tradeoff that historically favored DFIG partial-scale converters over full-rated alternatives. Offshore wind developers in the North Sea and East Asian waters are specifying SiC-based back-to-back converters for floating platform projects. The technology is decomposing incumbent supply relationships as turbine OEMs pursue direct semiconductor procurement strategies.
Germany's Federal Network Agency enforces fault-ride-through standards under the Renewable Energy Sources Act that mandate crowbar and chopper circuit integration. These requirements have elevated converter engineering capabilities to primary supplier selection criteria. Onshore wind farm developers in Schleswig-Holstein and Lower Saxony now specify integrated generator-converter packages rather than discrete component procurement.
Utility procurement departments are consolidating vendor relationships around full-system suppliers capable of warranting combined generator-converter performance. This concentration is displacing component-specialist business models that historically supplied rotors or stators separately. The shift is most visible in Chinese coastal provinces where state-backed wind bases require single-point accountability for grid code compliance.
Doubly Fed Induction Generator (DFIG) Market Segmentation
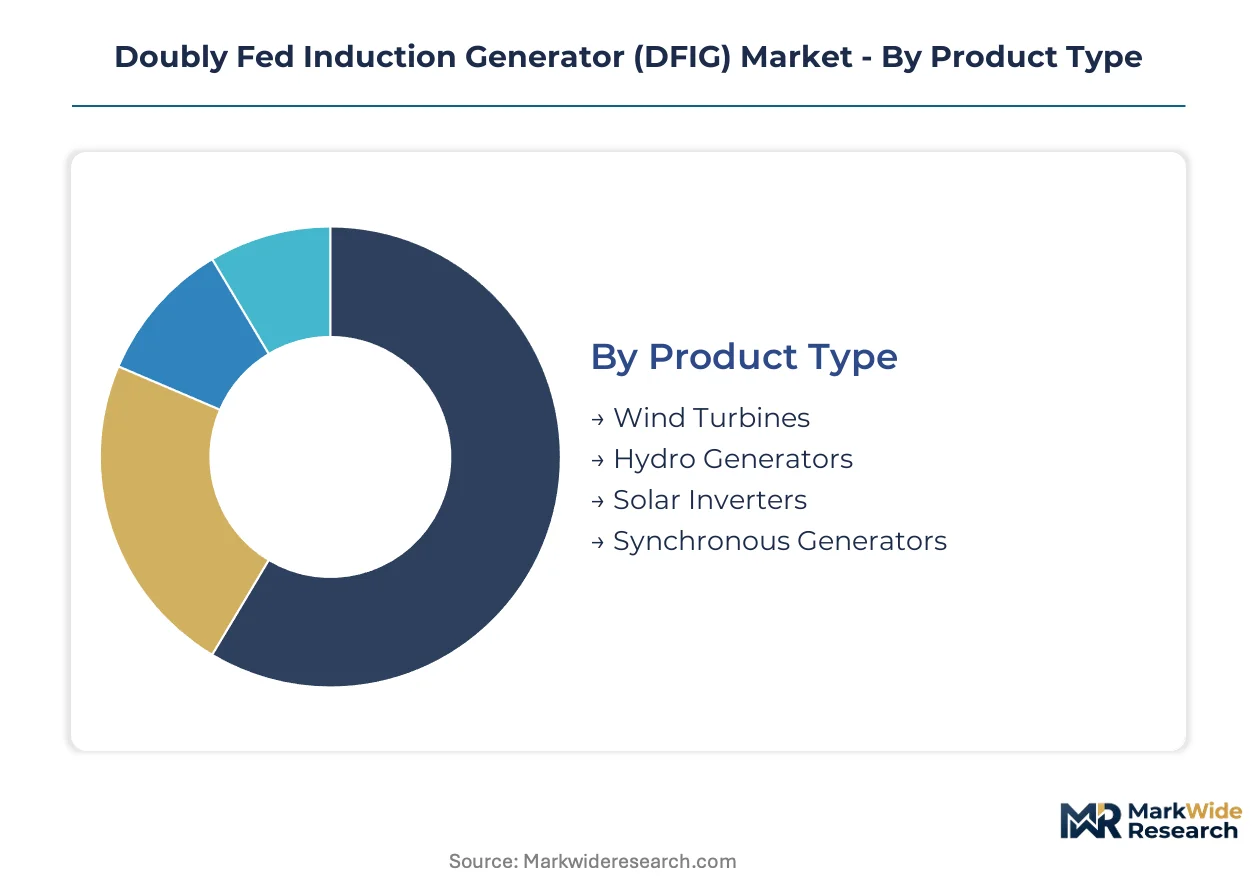
DFIG market segmentation reveals how variable-speed generation technology adapts across power system architectures. Product type and installation location determine converter sizing requirements, while end-use applications dictate control system complexity and grid code compliance specifications.
Product Type:
Wind turbines face the strongest substitution pressure from permanent magnet synchronous generators above 5 MW ratings, while hydro generators encounter limited alternative technologies for adjustable-speed pump-turbine applications.
- Wind Turbines:Variable-speed operation across limited slip range enables partial-scale converter deployment rated at roughly 30% of machine capacity. Coastal provinces of China concentrate procurement for megawatt-class supply chains as state-backed wind bases expand capacity.
- Hydro Generators:Adjustable-speed motor-generator sets serve pumped-storage modernization in Alpine and Himalayan geographies where grid stabilization services require bidirectional power flow. DFIG topology dominates this segment due to absence of cost-competitive alternatives for variable-speed hydro.
- Solar Inverters:Photovoltaic applications employ DFIG architectures in concentrated solar power plants with thermal storage integration.
- Synchronous Generators:Full-converter alternatives compete directly with DFIG in high-power applications above 10 MW.
Wind turbines anchor the volume base while hydro generators gain share at the steepest rate as pumped-storage projects proliferate.
End Use:
Power generation applications command premium pricing for fault-ride-through capabilities, whereas industrial applications prioritize cost optimization over grid-support functionality.
- Power Generation:Utility-scale wind farms require crowbar and chopper circuit integration under Germany's Federal Network Agency standards. Schleswig-Holstein and Lower Saxony developers specify integrated generator-converter packages warranting combined performance.
- Renewable Energy:India's state-level wind targets under CEA guidelines pull procurement for cost-optimized variable-speed generation across Gujarat and Tamil Nadu corridors.
- Industrial Applications:Cogeneration and process heat applications favor DFIG for adjustable-speed drive compatibility.
- Grid Integration:Reactive power control specifications under IEEE 1547 constrain market access for generators lacking synchronous connection capability.
Power generation dominates absolute revenue while renewable energy expands most quickly under national clean energy procurement mandates.
Technology:
Control systems differentiate margin performance, with power electronics determining cost competitiveness against full-converter alternatives.
- Control Systems:Vector control algorithms using rotating reference frame transformations command premium pricing. Advanced implementations integrate physics-based rotor modeling with SCADA analytics for predictive maintenance contracts.
- Power Electronics:Silicon carbide MOSFET modules reduce converter losses and extend DFIG viability against synchronous architectures. East Asian foundry concentration creates supply dependency risks for European and North American assemblers.
- Rotor Design:Wound rotor construction with copper windings faces cost volatility that compresses manufacturer margin predictability.
- Machine Learning:Digital twin convergence enables condition monitoring algorithms that extend service revenue streams.
Power electronics anchors technology investment while control systems climb the fastest as firmware specialization becomes the primary vendor selection criterion.
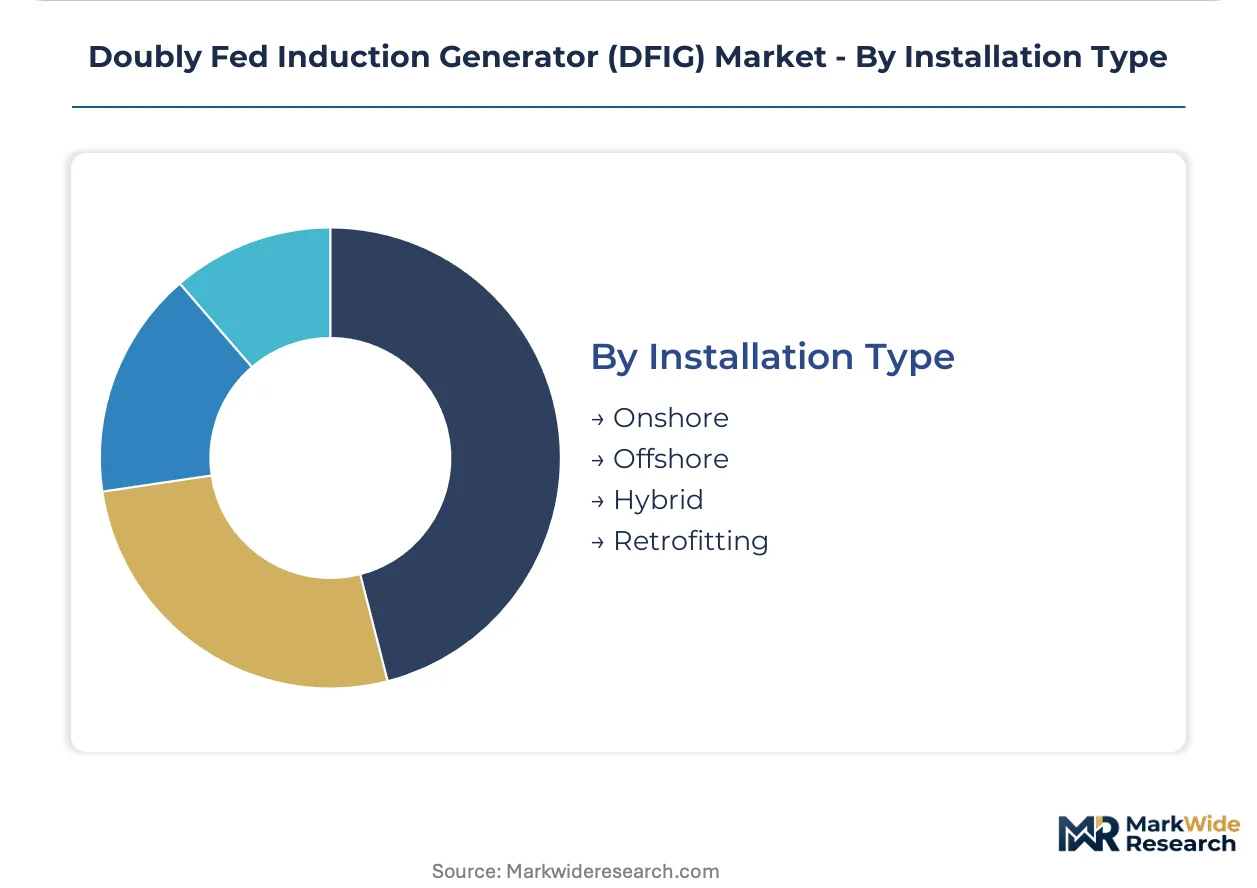
Installation Type:
Offshore specifications drive converter semiconductor upgrades, whereas onshore procurement prioritizes capital cost minimization.
- Offshore:Floating platform projects in the North Sea and East Asian waters specify SiC-based back-to-back converters for platform-mounted turbines. Siemens AG and GE Vernova compete through integrated generator-converter packages warranting combined performance.
- Onshore:Schleswig-Holstein and Lower Saxony wind corridors anchor European demand as Germany's Federal Network Agency enforces fault-ride-through standards.
- Hybrid:Co-located storage integration requires enhanced grid-support functionality beyond baseline DFIG specifications.
- Retrofitting:Existing fixed-speed turbine upgrades to variable-speed operation face crowbar integration challenges.
Onshore installations anchor current deployment volume while offshore projects show the steepest expansion trajectory as floating foundation technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive procurement in coastal Chinese provinces contrasts with premium-tolerance among North Sea offshore developers, while German onshore buyers occupy a mid-point valuing grid-code compliance over capital cost minimization.
China
State-backed wind bases in Jiangsu and Guangdong provinces drive megawatt-class generator procurement. The National Energy Administration enforces GB/T 19963 grid-support mandates that specify reactive power control and low-voltage ride-through capabilities. Turbine OEMs in the Yangtze River Delta region concentrate converter-integrated system sourcing to satisfy single-point accountability requirements.
Germany
Schleswig-Holstein and Lower Saxony wind corridors anchor European onshore demand as developers modernize aging turbine fleets. The Federal Network Agency enforces Renewable Energy Sources Act standards mandating crowbar and chopper circuit integration for fault-ride-through compliance. Hamburg-based engineering clusters specialize in vector control algorithm development for grid synchronization protocols.
United States
Texas and Iowa wind installations prioritize capital cost optimization for utility-scale procurement. FERC interconnection guidelines and IEEE 1547 standards constrain market access to generators with demonstrated reactive power control functionality. Midwest turbine assembly plants source partial-scale converter packages from domestic power electronics suppliers.
India
Gujarat and Tamil Nadu state corridors expand capacity under Central Electricity Authority renewable purchase obligations. State-level wind energy targets create procurement pull for cost-optimized variable-speed generation with partial-scale power electronics. Domestic generator fabricators in Maharashtra and Karnataka scale stator lamination production to capture import substitution opportunities.
United Kingdom
North Sea floating platform projects specify SiC-based converter architectures for platform-mounted turbines above 5 MW ratings. The Offshore Wind Sector Deal framework shapes domestic content requirements for generator supply chains. Scottish coastal development zones concentrate demand for integrated generator-converter packages warranting combined offshore performance.
Doubly Fed Induction Generator (DFIG) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive converter engineering separating the upper echelon from component-focused competitors. Turbine OEMs with in-house rotor design capabilities reduce dependency on third-party slip-ring vendors, while standalone generator suppliers compete on manufacturing scale in stator lamination production. Strategic moves concentrate on backward integration into power electronics and predictive maintenance service contract expansion.
Among integrated industrial conglomerates, Siemens AG and GE Vernova exemplify the converter-captive archetype, while CRRC represents scale-driven manufacturing specialization. XEMC and Shanghai Electric occupy positions within Chinese state-backed supply chains serving domestic wind base procurement. ABB anchors European power electronics integration across industrial generator applications.
| Leading Market Players |
|---|
| XEMC |
| CRRC |
| ABB |
| Siemens AG |
| CSIEM |
| VEM |
| Shandong Huali Motor |
| GE Vernova |
| Shanghai Electric |
| Others |
Pricing and Supply Chain Analysis
Stator lamination capacity utilization in Chinese coastal provinces sets price floors that European and North American generator assemblers cannot match without captive converter engineering. This scale concentration compresses margin predictability for standalone suppliers while rewarding integrated OEMs with bundled generator-converter packages.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions drive lifetime value capture beyond initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates Siemens AG and GE Vernova's integrated packages from CRRC's manufacturing-scale offerings and regional fabricators' commodity stator supplies. Cost compression in standard-tier partial-scale converters is intensifying because silicon carbide module availability remains concentrated in East Asian foundries. Utility procurement departments in China's state-backed wind bases exhibit the highest price sensitivity, while North Sea offshore developers tolerate premium pricing for SiC-based fault-ride-through capabilities.
Supply Chain Analysis
IGBT and silicon carbide module fabrication chokepoint in Taiwan, South Korea, and Japan underwrites supply security concerns for European generator assemblers. Wound rotor construction draws from copper winding suppliers in Chile and Peru, while rare-earth magnet alternatives for competing synchronous architectures hinge on Chinese processing capacity. Single-source vulnerability in wide-bandgap semiconductor procurement exposes converter-integrated system suppliers to allocation risk during demand surges. Distribution runs through turbine OEM direct procurement channels rather than independent distributor networks, concentrating vendor relationship power with Siemens AG, GE Vernova, and CRRC.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against permanent magnet synchronous generators capturing offshore turbine specifications above 5 MW ratings. Incumbents must navigate technology transition risk while defending installed base service revenue.
For Market Incumbents: Consolidate backward integration into silicon carbide module sourcing to secure converter semiconductor supply against East Asian foundry allocation constraints. Deepen captive rotor design capabilities to reduce dependency on third-party slip-ring vendors as brush-gear maintenance contracts become margin anchors. Defend against full-converter synchronous substitution by warranting combined generator-converter grid code compliance under Germany's Federal Network Agency standards.
For New Entrants and Emerging Players: Lead with digital twin integration for predictive maintenance contracts in India's Gujarat and Tamil Nadu wind corridors where CEA renewable purchase obligations expand procurement volume. Target pumped-storage hydro modernization in Alpine geographies where adjustable-speed motor-generator sets lack cost-competitive alternatives. Establish go-to-market partnerships with regional EPC contractors rather than competing for direct utility relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converter-captive integrated suppliers over standalone generator fabricators as grid code harmonization accelerates. Five-to-ten year viability rests on silicon carbide cost curves and floating offshore wind deployment rates. Target acquisition archetypes combine physics-based rotor modeling software with established stator lamination scale. The signal to watch is IEEE 1547 revision timing for reactive power control mandates that would extend DFIG competitive window against synchronous alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Module Sourcing | Secures wide-bandgap semiconductor supply against Taiwan and South Korea foundry concentration risks. |
| Digital Twin Platform Development | Enables predictive maintenance contracts extending service revenue under GB/T 19963 grid-support mandates. |
| Pumped-Storage Hydro Partnership | Captures adjustable-speed motor-generator demand in Alpine and Himalayan grid stabilization projects. |
| Floating Offshore Certification Investment | Qualifies integrated packages for North Sea and East Asian platform-mounted turbine specifications. |
| Vector Control Algorithm Acquisition | Addresses scarce firmware expertise in rotating reference frame transformations and grid synchronization protocols. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of IEC 61400-21 certification databases, FERC interconnection filings, and customs trade records for copper winding and semiconductor module flows. Primary interviews engaged wind farm development executives, turbine OEM procurement directors, converter engineering leads, and aftermarket service managers across Germany's Schleswig-Holstein corridor, China's Jiangsu province, and India's Tamil Nadu state. Bottom-up unit economics for generator-converter packages triangulate against top-down market sizing from national renewable energy agency capacity announcements.
Segmentation dimensions modeled span product type, installation location, end-use application, and technology tier across the projection horizon. CAGRs derive from installed base replacement cycles, grid code compliance timeline compression, and floating offshore wind deployment trajectories. Forecast inputs incorporate silicon carbide module cost curves, copper price volatility bands, and fault-ride-through standard evolution under Germany's Federal Network Agency and China's National Energy Administration.
The analysis sits within stated boundaries; outcomes outside sustained wide-bandgap semiconductor supply expansion or accelerated full-converter synchronous substitution would require recalibration. Forecasts reflect documented assumptions regarding GB/T 19963 enforcement continuity and IEEE 1547 reactive power control adoption. Practitioners should keep alternative scenarios live as floating platform project economics and rare-earth magnet price trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Europe Power Market
Power
Resonant Power Converters Market
Power
Italy Power EPC Market
Power
Electric Power Sports Market
Power
Global Power Line Communication (PLC) Systems Market
Power
Rotating Phase Converter Market
Power
Modified Sine Wave Home Inverters Market
Power
Japan Uninterrupted Power Supply (UPS) Market
Power
Global Diesel Power Engine Market
Power
Qatar Power Market
Power
Egypt Uninterruptible Power Supply (UPS) Market
Power
Brazil Power Market
Power
Static Synchronous Compensator (STATCOM) Market
Power
Electric Arc Furnaces Market
Power
Distribution Feeder Protection System Market
Power
Angola Power EPC Market