
 Saudi Arabia Power Market | 2026-2036
Saudi Arabia Power Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Power Market Analytics
IEC 61850 certification for substation automation is rotating procurement criteria toward vendors with proven digital grid integration. ACWA Power leverages its independent power producer model to dominate greenfield renewable developments across the Kingdom. Saudi Electricity Company anchors transmission and distribution infrastructure through its regulated monopoly over the national grid. Engie SA competes in concentrated solar power technology leadership through its operational experience at the Waad Al-Shamal plant.
The Saudi Arabia Power sector encompasses the production, conveyance, and delivery of electrical energy across generation, transmission, and distribution stages, with thermal efficiency ratings for combined-cycle gas turbines typically exceeding 60 percent and solar photovoltaic installations now achieving capacity factors above 25 percent in the kingdom's high-irradiance desert regions. Its primary purpose is to supply reliable baseload and peaking electricity to industrial, commercial, and residential consumers while supporting the national economic diversification agenda away from hydrocarbon dependency. Generation capacity expansion tilts heavily toward solar and wind technology segments as the Public Investment Fund channels capital into utility-scale renewable projects. Transmission infrastructure investment concentrates on high voltage and ultra high voltage power rating categories to reduce losses across the vast desert geography connecting load centers in Riyadh and Jeddah to remote generation sites.
SFDA and the Saudi Standards, Metrology and Quality Organization govern electrical equipment safety and grid code compliance, while the Electricity and Cogeneration Regulatory Authority sets tariff structures and licensing terms that shape independent power producer economics and market access conditions. The Saudi Building Code and Energy Efficiency Center standards mandate minimum performance thresholds for industrial and commercial installations, directly influencing demand for medium voltage distribution equipment and smart metering systems. Stakeholders must monitor how the kingdom's renewable energy localization requirements and grid code revisions will reshape supplier qualification criteria and capital allocation priorities across the project development pipeline.
Market Dynamics
The Saudi Arabia Power Market pivots on the Electricity and Cogeneration Regulatory Authority's renewable energy localization mandates, which redirect procurement toward domestic manufacturing capacity and reshape supplier qualification criteria for grid infrastructure projects.
Growth Catalysts
- SFDA grid code compliance:Stricter electrical equipment safety standards under Saudi Standards, Metrology and Quality Organization protocols accelerate replacement cycles for aging distribution transformers and switchgear across industrial zones.
- Petrochemical load expansion:Jubail and Yanbu industrial cities drive electricity offtake growth as integrated refining and chemical complexes expand captive power demand and seek grid interconnection upgrades.
- Desert solar irradiance:Utility-scale photovoltaic developers exploit capacity factors above 25 percent in the kingdom's high-insolation regions, attracting Public Investment Fund capital toward greenfield renewable generation.
Market Restraints
- Gas turbine supply concentration:Original equipment manufacturers for combined-cycle units face extended lead times for hot gas path components, constraining thermal generation expansion timelines.
- SFDA certification bottlenecks:Electrical equipment testing and approval queues at Saudi Standards, Metrology and Quality Organization laboratories delay project commissioning for imported medium voltage switchgear.
- Water-energy nexus constraints:MARAFIQ's integrated power and water infrastructure in the Eastern Province faces cooling water availability limits that cap thermal plant output during peak summer loads.
Strategic Opportunities
- Eastern Province industrial clustering:Concentrated demand around Jubail and Yanbu creates economies of scale for dedicated high-voltage transmission corridors and localized equipment service networks.
- IEC 61850 substation automation:Digital grid integration standards open procurement pathways for vendors with proven SCADA and protection relay interoperability credentials.
- Saudi Energy Efficiency Center mandates:Stricter building codes for commercial and industrial installations drive replacement demand for smart metering systems and energy management platforms.
Industry Challenges
- IEC 61850 integration complexity:Legacy substation protection systems require costly retrofitting to achieve protocol compatibility with new digital grid automation architectures.
- High-voltage technician scarcity:Specialized skills for ultra high voltage transmission maintenance remain concentrated among a limited pool of experienced contractors, inflating labor costs for remote desert installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Power Market |
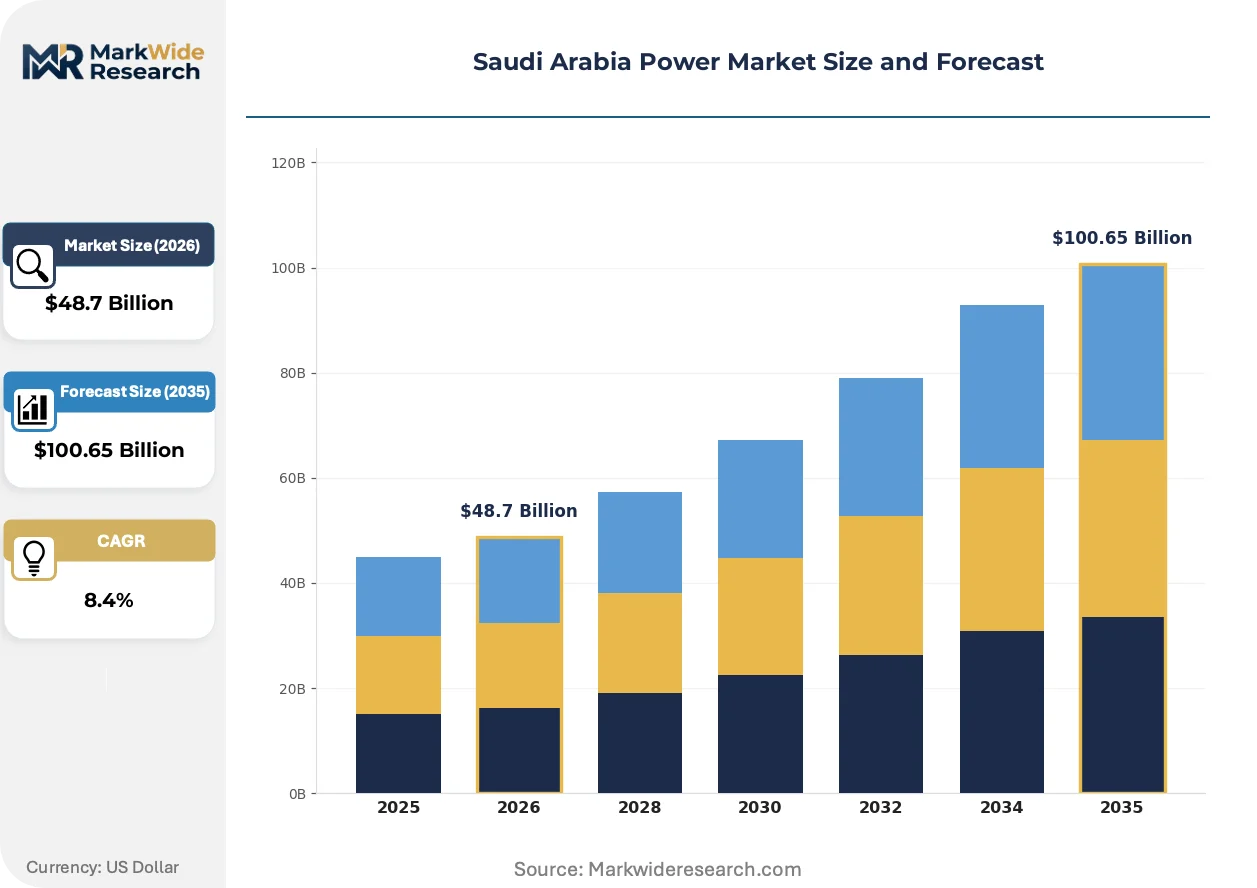
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Generation, Transmission, Distribution, Renewable Technology: Solar, Wind, Gas Turbine, Hydropower End User: Residential, Commercial, Industrial, Government Power Rating: High Voltage, Medium Voltage, Low Voltage, Ultra High Voltage |
| Companies Covered | Engie SA, Nour Energy (ASTRA Group), Saudi Electricity Company (SEC), Masdar Abu Dhabi Future Energy Co., Arabian Electrical Transmission Line Construction Company (AETCON), ACWA Power, EDF SA, NEOM Energy & Water Co., MARAFIQ Power and Water Utility Company for Jubail and Yanbu (MARAFIQ), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Power Market Evolving Landscape
Digital substation architectures and renewable generation integration are compressing traditional equipment procurement cycles and forcing requalification of vendor technical competencies across the Saudi power sector.
Gas-insulated switchgear is supplanting air-insulated alternatives in 132 kV and above substation deployments. Saudi Electricity Company specifications now prioritize GIS for coastal and desert installations where space constraints and environmental contamination risks dominate. This technology shift is compressing substation footprints by 70 percent while elevating capital cost thresholds that filter out smaller equipment vendors.
Saudi Energy Efficiency Center mandates under the Saudi Building Code now require minimum performance thresholds for industrial motor systems and HVAC loads. The regulations force retrofits across existing commercial buildings and influence specification decisions for new petrochemical facilities. Eastern Province industrial developers respond by embedding power quality monitoring into medium voltage distribution designs from project inception.
Integrated power and water service contracts are consolidating procurement authority under single-source operators like MARAFIQ in the kingdom's industrial cities. Large industrial offtakers now negotiate bundled electricity, steam, and desalinated water agreements rather than discrete utility purchases. This consolidation concentrates vendor relationships and compresses equipment supplier margins through volume-based pricing structures in Jubail and Yanbu.
Saudi Arabia Power Market Segmentation
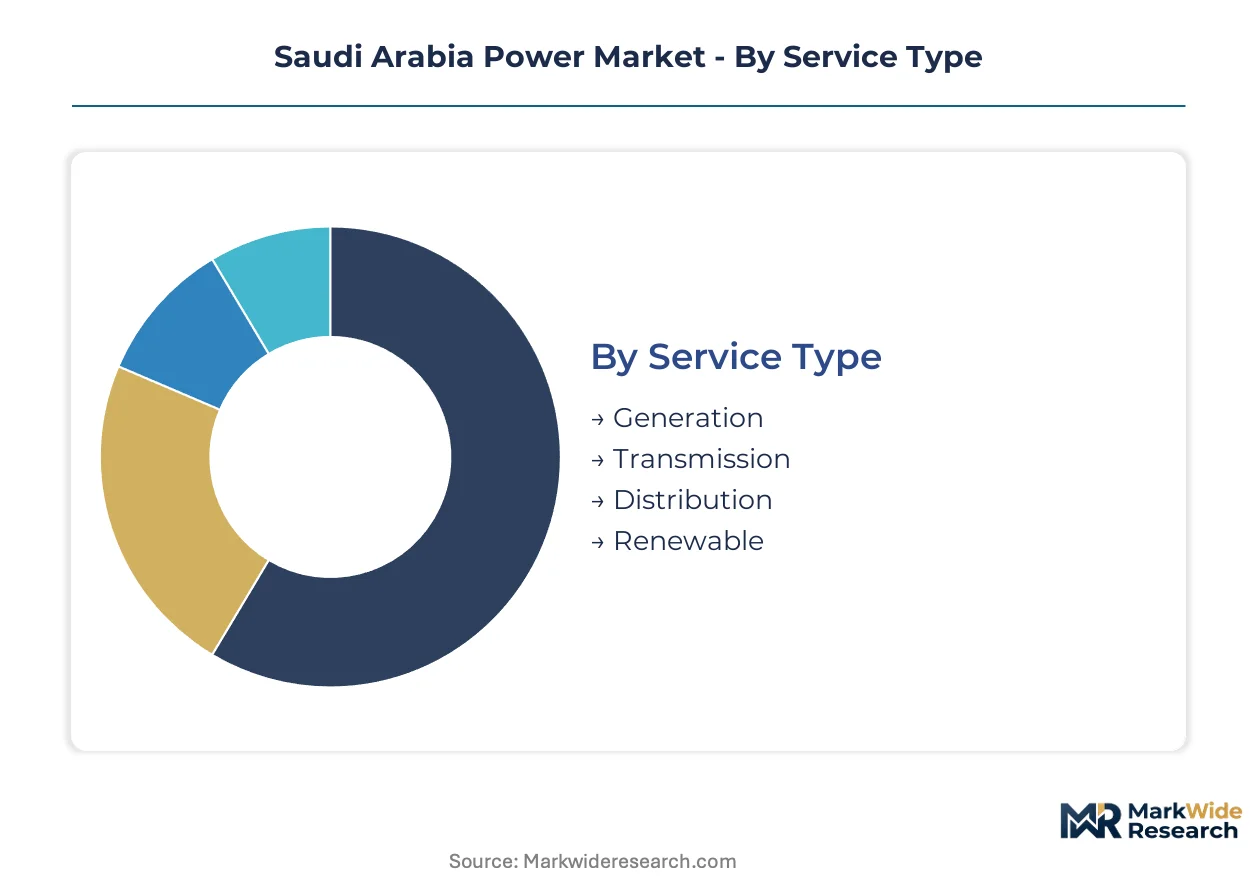
Segmentation reveals where capital flows concentrate across Saudi Arabia's power infrastructure buildout. The Public Investment Fund's renewable mandates and SEC grid expansion priorities reshape equipment procurement patterns by service type, technology, and voltage class.
Service Type:
Margin pools concentrate in generation assets where IPP concession terms and PIF equity participation create sustained equipment demand cycles.
- Generation:Combined-cycle gas turbines and utility-scale solar farms dominate newbuild activity. ACWA Power and SEC anchor procurement for thermal and renewable capacity additions across the Eastern Province and Riyadh corridor.
- Transmission:High-voltage corridor investments link remote generation to load centers. Ultra high voltage infrastructure across desert geography commands premium equipment specifications and specialized installation capabilities.
- Distribution:Medium and low voltage networks serve residential and commercial clusters. Smart metering rollouts and grid automation upgrades accelerate replacement cycles for aging switchgear.
- Renewable:Utility-scale solar and wind developments attract dedicated development vehicles. Greenfield projects in high-irradiance regions exploit capacity factors above 25 percent for photovoltaic installations.
The dominant share belongs to Generation, while Renewable is closing the gap fastest through PIF-backed greenfield developments.
Technology:
Technology selection tracks resource endowment and localization mandates that favor solar deployment over imported gas turbine components.
- Solar:Photovoltaic dominates capacity additions with desert irradiance supporting competitive capacity factors. Waad Al-Shamal and similar utility-scale sites anchor domestic panel assembly requirements under Saudi renewable localization rules.
- Wind:Coastal and high-altitude sites in the north and west offer viable wind resources. Procurement concentrates on turbines meeting IEC standards for sand and dust environmental conditions.
- Gas Turbine:Combined-cycle units provide baseload and peaking flexibility. Hot gas path component lead times constrain expansion timelines for petrochemical captive power demand.
- Hydropower:Limited resource base restricts development to small-scale run-of-river projects. The technology serves niche applications in the southwest highlands rather than national grid contribution.
Solar commands the largest equipment procurement volume, with Wind gaining share fastest through coastal resource assessment and grid interconnection approvals.
End User:
Customer type determines tariff structures and service reliability requirements that flow through to equipment specification decisions.
- Industrial:Petrochemical complexes in Jubail and Yanbu drive the highest load growth. MARAFIQ integrated service contracts bundle electricity, steam, and desalinated water for captive demand.
- Residential:Urbanization in Riyadh and Jeddah expands distribution network requirements. Building code mandates from the Saudi Energy Efficiency Center influence smart metering and HVAC load specifications.
- Commercial:Retail and office developments concentrate in metropolitan centers. Saudi Building Code compliance drives demand for energy management platforms and power quality monitoring.
- Government:Public facilities and infrastructure projects anchor procurement through centralized purchasing authorities. SFDA and SASO certification requirements filter supplier qualification for institutional buyers.
Industrial offtake leads absolute consumption, though Residential connections are expanding most quickly through urban development corridors.
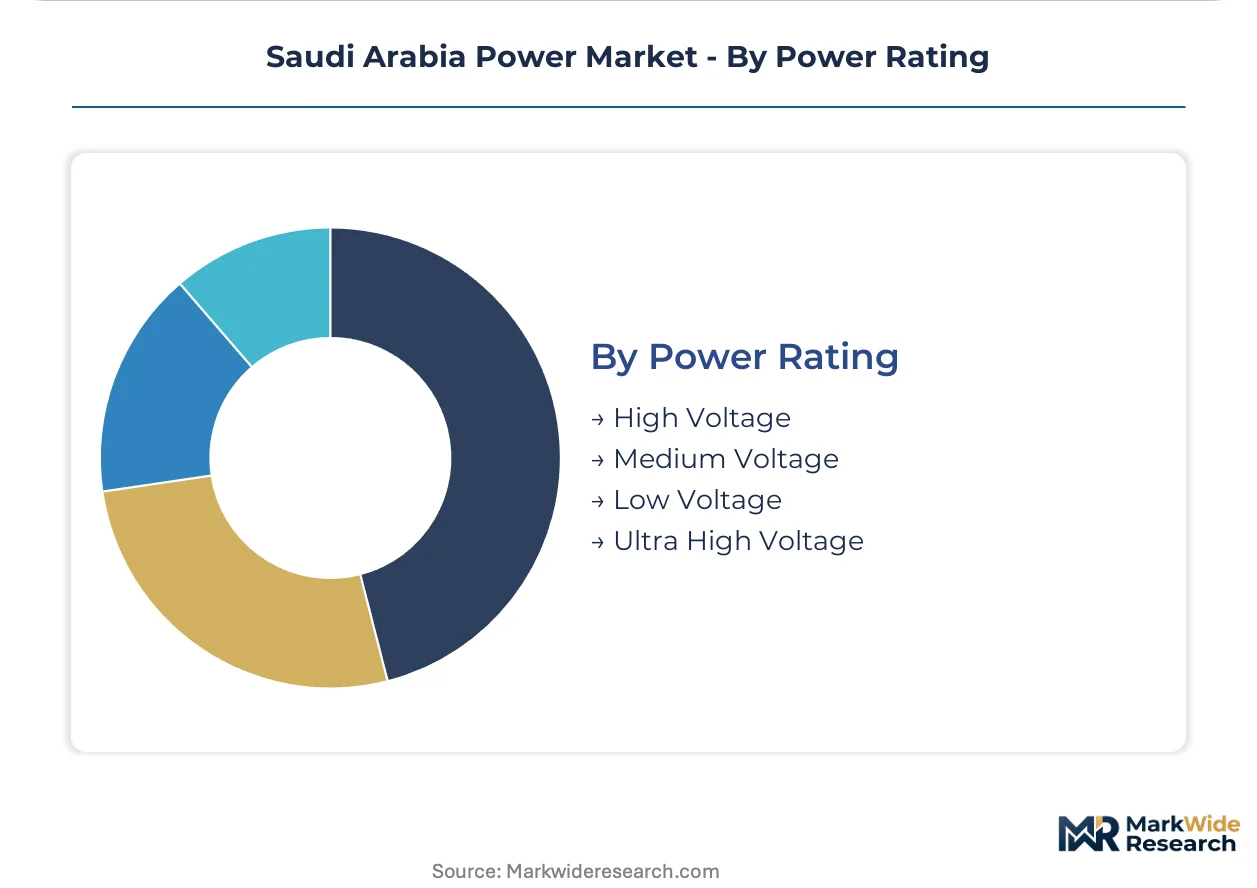
Power Rating:
Voltage class segmentation reflects geography and loss-minimization priorities across vast desert transmission distances.
- Ultra High Voltage:400 kV and above infrastructure connects remote generation to major load centers. SEC specifications prioritize GIS technology for substation footprint reduction in constrained desert sites.
- High Voltage:132 kV and 220 kV networks form the backbone of regional interconnection. Gas-insulated switchgear displaces air-insulated alternatives in coastal installations facing environmental contamination risks.
- Medium Voltage:11 kV to 33 kV distribution serves industrial zones and commercial clusters. IEC 61850 certification requirements reshape procurement toward vendors with proven digital grid integration.
- Low Voltage:Final delivery to residential and small commercial consumers. Smart meter deployment and building energy management systems concentrate replacement demand in this segment.
High Voltage infrastructure holds the dominant capital allocation, with Ultra High Voltage posting the steepest expansion trajectory as remote renewable sites reach grid parity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers concentrate in the Eastern Province's petrochemical corridor, while transmission planners prioritize desert-spanning infrastructure linking remote generation to Riyadh and Jeddah load centers.
Eastern Province
Jubail and Yanbu industrial cities anchor the kingdom's highest electricity offtake growth as integrated refining and chemical complexes expand captive power demand. MARAFIQ operates integrated power and water infrastructure under long-term service contracts that bundle electricity, steam, and desalinated water. The Electricity and Cogeneration Regulatory Authority sets tariff structures that shape independent power producer economics across this concentrated industrial zone.
Riyadh
Urbanization drives residential distribution network expansion across the capital metropolitan area. The Saudi Energy Efficiency Center mandates stricter building codes that accelerate smart metering deployment and HVAC load management retrofits. Saudi Electricity Company anchors transmission and distribution infrastructure through its regulated monopoly over the national grid serving government and commercial clusters.
Western Region
Jeddah and Mecca load centers require reliability upgrades for commercial and pilgrimage-driven seasonal demand peaks. High-voltage corridor investments connect western cities to remote generation sites across vast desert geography. SFDA and SASO govern electrical equipment safety and grid code compliance for imported medium voltage switchgear serving this coastal installation zone.
NEOM Northwest
The giga-project zone attracts utility-scale renewable developments exploiting high solar irradiance and coastal wind resources. NEOM Energy & Water Co. consolidates procurement authority for integrated power and water service contracts in this greenfield development area. Public Investment Fund capital channels into utility-scale renewable projects that prioritize domestic manufacturing capacity under localization mandates.
Saudi Arabia Power Market Competitive Landscape
Player mix skews toward state-affiliated utilities and independent power producers with concession-based development rights. The vendor base concentrates around integrated service operators and renewable-focused developers rather than fragmented equipment suppliers. Two strategic archetypes dominate: regulated national champions controlling transmission infrastructure, and IPP-led developers securing long-term power purchase agreements for greenfield generation. Competitive moves center on portfolio diversification into renewable technology segments and strategic partnerships with Public Investment Fund-backed project vehicles.
Within the state-affiliated utility tier, Saudi Electricity Company and MARAFIQ exemplify the integrated infrastructure model. ACWA Power occupies a position as the dominant independent power producer for greenfield renewable developments. Engie SA represents international technology leadership in concentrated solar power through operational experience at utility-scale installations. These three anchors illustrate how concession terms and regulatory relationships determine market access across generation, transmission, and integrated industrial service segments.
| Leading Market Players |
|---|
| Engie SA |
| Nour Energy (ASTRA Group) |
| Saudi Electricity Company (SEC) |
| Masdar Abu Dhabi Future Energy Co. |
| Arabian Electrical Transmission Line Construction Company (AETCON) |
| ACWA Power |
| EDF SA |
| NEOM Energy & Water Co. |
| MARAFIQ Power and Water Utility Company for Jubail and Yanbu (MARAFIQ) |
| Others |
Value Network & Pricing Analysis
Long-term power purchase agreements with take-or-pay structures lock in both fuel supply access and tariff visibility for Saudi independent power producers, insulating project returns from commodity volatility while binding offtakers to minimum volume commitments across multi-decade concession terms.
Pricing Analysis
Cost-plus contracts with fuel price indexation dominate thermal generation procurement, passing through natural gas costs to petrochemical offtakers while capping developer exposure. Price differentiation hinges on plant efficiency ratings and SFDA certification tier for electrical equipment. Cost compression in medium voltage switchgear intensifies as localization mandates force imported gear through extended SASO testing queues. Industrial buyers in Jubail and Yanbu exhibit lowest price sensitivity due to bundled utility service contracts, while commercial developers in Riyadh face sharper budget constraints.
Supply Chain Analysis
Strategic stockpiling of critical spares prevails over just-in-time delivery given extended lead times for gas turbine hot gas path components and GIS substation equipment. Manufacturing concentrates in Germany, South Korea, and Japan for high-efficiency turbines and ultra high voltage switchgear. Supply chains draw from copper and rare earth processing in China, specialized steel alloys from Japan, and gas turbine blade coatings from Germany. Single-source vulnerability concentrates in precision-cast turbine components. Distribution runs through EPC contractors with established Saudi project execution credentials rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi power sector rewards operators who control scarce capabilities in ultra high voltage installation and IEC 61850 digital grid integration, with talent shortages in specialized desert transmission maintenance creating persistent bottlenecks for project execution.
For Market Incumbents: Consolidate grip on Eastern Province industrial corridors by deepening captive service relationships with MARAFIQ-anchored complexes and securing exclusive maintenance contracts for existing GIS installations. Threats from renewable-focused IPPs with PIF backing demand preemptive positioning in hybrid thermal-renewable project consortia. Priority lever rests on vertical integration into substation automation software layers. For New Entrants and Emerging Players: Aftermarket digital retrofit services for legacy protection systems represent a service-layer gap where incumbents under-serve, given IEC 61850 integration complexity and technician scarcity deterring major OEMs from small-scale deployments. Most penetrable segment clusters around medium voltage distribution upgrades in Riyadh commercial developments. Go-to-market angle centers on turnkey SCADA migration with guaranteed interoperability certification. For Investors and Strategic Acquirers: Capital is best deployed toward specialized EPC contractors with demonstrated ultra high voltage desert installation track records and existing SASO laboratory relationships that accelerate equipment approval timelines. Long-term viability hinges on renewable localization mandate compliance and NEOM project pipeline access. Signal to watch is Public Investment Fund equity participation announcements in greenfield generation vehicles.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | Long-term offtake terms with SEC anchor revenue visibility for IPP developers. |
| IEC 61850 Certification Investment | Digital grid protocol credentials unlock procurement pathways with Saudi Electricity Company. |
| Localization Partnership Formation | Domestic manufacturing joint ventures satisfy PIF equity requirements for renewable projects. |
| Integrated Service Contract Expansion | Bundled power-water-steam offerings mirror MARAFIQ's industrial city model. |
| Ultra High Voltage Capability Buildout | Desert transmission expertise commands premium pricing in remote renewable interconnection. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating utility planning officers at Saudi Electricity Company, IPP project developers with active PIF relationships, EPC contractors executing ultra high voltage installations, and grid operators managing Eastern Province industrial load centers. Secondary validation drew from ECRA regulatory filings, SASO certification databases, IEA renewable energy reports, and project development tracking systems. Bottom-up equipment procurement forecasts triangulated against top-down capacity addition targets issued by the kingdom's energy planning authorities.
Across the projection horizon, analytical frameworks modeled capacity expansion by fuel source, generation scale tier, voltage class, and regulatory framework cluster. CAGRs were derived from regression analysis of historical capacity commissioning data against policy mandate trajectories. Forecast inputs incorporated solar irradiance resource assessments, gas turbine supply lead time trends, and grid interconnection queue depths for remote renewable sites.
Forecasts assume regulatory continuity in ECRA tariff structures and SASO certification protocols; material policy shifts would require re-modeling of IPP economics and equipment import timelines. Revision becomes warranted when PIF capital allocation priorities cross thresholds that redirect project development momentum between thermal and renewable technology segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Electric Arc Furnaces Market
Power
Europe Power Purchase Agreement Market
Power
Europe Power Market
Power
Single-Phase Microinverter Market
Power
Compact Substation Market
Power
Water Turbine Market
Power
Global Marine Power Systems Market
Power
Argentina Power Market
Power
Statcom Market
Power
Resonant Power Converters Market
Power
Global UPS Market
Power
Gas Freeing Fan Market
Power
Canada Thermal Power Market
Power
Green UPS Market
Power
Power Capacitors Market
Power
Asia-Pacific Power Market