
 Global Ancillary Services Power Market | 2026-2036
Global Ancillary Services Power Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ancillary Services Power Market Intelligence
Demand from Independent System Operators and Transmission Operators is bifurcating as aggregators of Distributed Energy Resources gain influence in grid balancing. General Electric Company leverages its extensive turbine and grid software portfolio to serve incumbent utilities. Meanwhile, Tesla, Inc. specializes in battery storage systems and virtual power plant software. Siemens AG competes across both domains with its comprehensive energy management solutions, serving both centralized and decentralized market participants.
Ancillary services power refers to the functions that support the reliable operation of the electric grid beyond simple energy generation and transmission. These services ensure grid stability by managing parameters like frequency within a tight band, typically 50 or 60 Hz, and maintaining voltage levels. Frequency Regulation and Spinning Reserve services constitute the largest revenue streams for providers. However, solutions for Renewable Integration and services delivered via Virtual Power Plants represent the fastest-growing application and deployment models.
Regulatory frameworks are critical in shaping market structures and compensation mechanisms for these services. Policies like FERC Order 2222 in the United States and initiatives under the EU Green Deal encourage participation from distributed energy resources. Providers must now decide whether to specialize in specific services like reactive power compensation or build integrated platforms that can participate across multiple markets.
Market Dynamics
The fundamental shift from centralized, fossil-fuel-based power generation to a decentralized grid dominated by intermittent renewables is the central force shaping the ancillary services market. This transition creates volatility in grid frequency and voltage, demanding faster, more flexible balancing solutions.
Growth Catalysts
- Supportive Regulatory Mandates:Policies like FERC Order 2222 in the United States and the EU Green Deal are actively dismantling barriers for Distributed Energy Resources (DERs) to participate in wholesale energy and ancillary service markets, expanding the supplier pool.
- Falling Battery Storage Costs:The declining cost curve for lithium-ion battery energy storage systems (BESS) makes them economically viable for providing fast-frequency response services, a high-value segment of the ancillary services market.
- Aggressive Renewable Targets:National commitments to decarbonization, particularly in China and Germany, necessitate massive investment in grid stabilization services to manage the high penetration of variable wind and solar power generation.
Market Restraints
- Archaic Market Structures:In many jurisdictions, grid operators' market rules and compensation mechanisms are designed for large, slow-moving thermal plants, creating financial and technical barriers for faster, smaller, distributed assets to participate effectively.
- High Capital Expenditure:The significant upfront investment required for grid-scale battery installations, advanced metering infrastructure, and sophisticated virtual power plant software platforms can deter new entrants and smaller utilities.
- Grid Interconnection Delays:Protracted timelines and complex technical studies for connecting new resources, especially large-scale storage projects, to the transmission system can stall projects and restrain the supply of new ancillary services.
Strategic Opportunities
- Vehicle-to-Grid (V2G) Integration:The electrification of transport presents an opportunity to use aggregated electric vehicle fleets as a massive, distributed energy storage resource, providing grid services like frequency regulation when parked and charging.
- AI-Optimized Bidding Platforms:Developing AI and machine learning software that can forecast grid needs and optimize the bidding strategy for a portfolio of diverse assets across multiple ancillary service markets represents a significant value-creation opportunity.
- Grid Modernization in Developing Nations:Emerging economies in regions like Southeast Asia are building out their electricity infrastructure, offering a chance to leapfrog legacy systems and implement modern ancillary service market designs from the outset.
Industry Challenges
- Cybersecurity Vulnerabilities:The proliferation of connected DERs and control systems expands the attack surface of the electric grid, requiring sophisticated cybersecurity measures to protect critical infrastructure from disruption by malicious actors.
- Interoperability and Standardization:A lack of universal communication protocols, such as those being developed under IEC frameworks, for diverse energy assets complicates their seamless integration into aggregated VPPs, hindering scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ancillary Services Power Market |
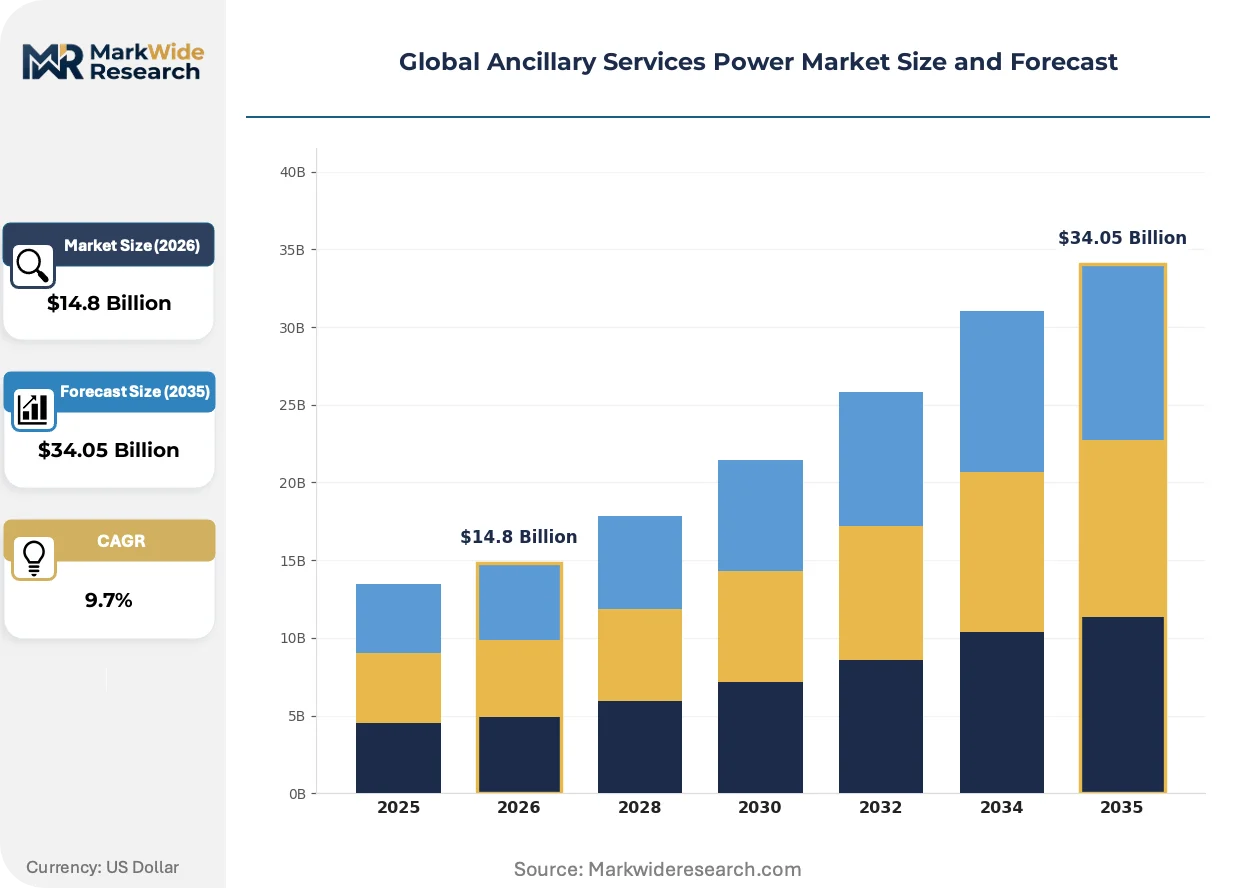
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $34.05 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Frequency Regulation, Voltage Support, Spinning Reserve, Black Start, Reactive Power Compensation Application: Grid Stabilization, Peak Load Management, Renewable Integration, Transmission Support, Emergency Power Supply Deployment: On-Premise, Cloud-Enabled, Distributed Energy Resources, Virtual Power Plants, Microgrid Systems End User: Transmission Operators, Distribution Companies, Independent System Operators, Capacity Market Operators, Generation Companies |
| Companies Covered | Schneider Electric SE, Duke Energy Corporation, General Electric Company, Tesla, Inc., NextEra Energy, Siemens AG, Enel S.p.A., Engie SA, ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ancillary Services Power Market Strategic Shifts & Innovations
Digitization is transforming ancillary services from a domain of slow mechanical reserves to one of fast, automated, and data-driven grid control. This evolution is driven by innovations in power electronics, new regulatory frameworks, and changing procurement models by grid operators.
Grid-forming inverters are a key technological advancement in power electronics. These devices enable inverter-based resources like solar and batteries to create their own voltage and frequency reference, actively stabilizing the grid. Transmission system operators and developers of battery storage projects are increasingly specifying this capability. This technology is supplanting the traditional role of synchronous generators in providing essential system inertia and fault-current support.
The European Union's network codes, particularly the Requirement for Generators (RfG) code, mandate specific technical capabilities for all new power-generating modules. This regulation forces renewable energy projects to incorporate features that can support grid stability, such as frequency response and voltage control. Wind and solar developers in EU member states like Spain and the Netherlands must now engineer these ancillary service functions into their plants from the design stage.
A notable behavioral shift is the move by system operators toward performance-based remuneration for ancillary services. This model disrupts legacy capacity-based payments, tying compensation directly to the speed, accuracy, and overall effectiveness of the service delivered. The trend is most pronounced in the fast-frequency response markets of the United Kingdom and Australia, forcing providers to invest in more agile and precise control technologies.
Global Ancillary Services Power Market Segmentation
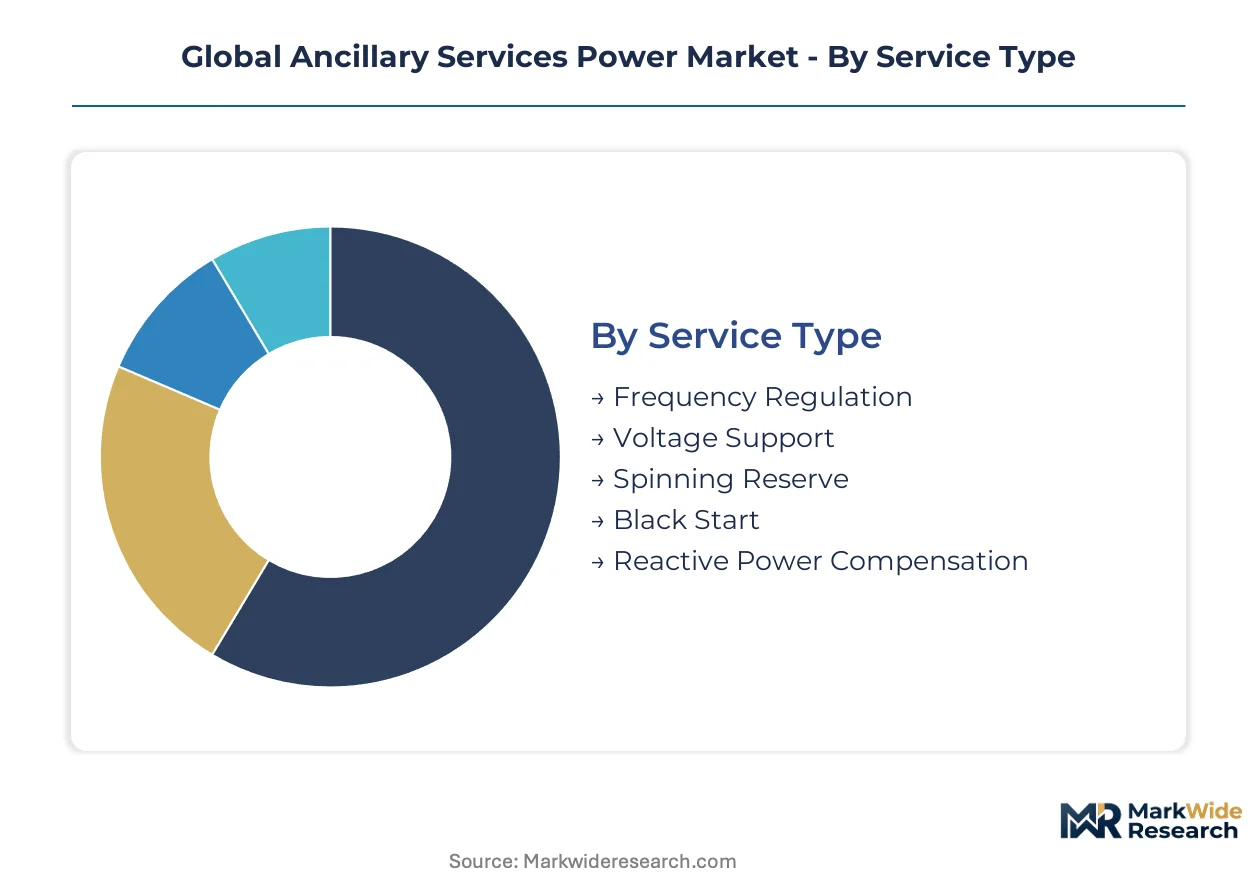
The ancillary services power market exhibits diverse segmentation based on the specific functions required for grid reliability. Understanding these categories is critical for market participants to identify lucrative niches and tailor their offerings. Segmentation also reveals how different technologies and business models are gaining traction across the evolving energy landscape.
Service Type:
Margin pools within the service type category are highest for fast-responding, critical grid stability functions. These services demand sophisticated control and rapid deployment capabilities.
- Frequency Regulation:This service continuously balances electricity supply and demand to maintain grid frequency within a tight operating band, typically 50 or 60 Hz. Demand concentrates in markets with high renewable penetration, such as Germany, where grid operators require constant correctional inputs.
- Spinning Reserve:This involves generation capacity already synchronized to the grid and ready to increase output immediately in response to a sudden loss of generation or increase in demand. The United Kingdom's National Grid procures significant spinning reserve to ensure system security.
- Voltage Support:This service maintains stable voltage levels across the transmission and distribution network, preventing sags or surges that can damage equipment. Utilities in densely populated urban areas often require robust voltage support.
- Black Start:This capability allows a power plant to restart without external electricity, restoring power to the grid after a widespread blackout.
- Reactive Power Compensation:This service manages reactive power flows to optimize grid efficiency and maintain voltage stability, often provided by specialized power electronics.
The dominant share belongs to Frequency Regulation, while Spinning Reserve is closing the gap fastest.
Application:
The application segment highlights how ancillary services address specific operational challenges within the electricity grid, with new applications expanding quickly.
- Renewable Integration:This application focuses on managing the variability and intermittency of wind and solar power generation to ensure grid stability. Countries like Spain and Australia are investing heavily in renewable integration solutions.
- Grid Stabilization:This fundamental application ensures the overall stability and reliability of the electrical grid by managing frequency, voltage, and power flows. Demand for grid stabilization is universal across all transmission operators.
- Peak Load Management:This involves deploying resources to meet periods of high electricity demand, reducing the need for expensive peaker plants. California's grid frequently utilizes ancillary services for peak load management.
- Transmission Support:These services enhance the capacity and reliability of the transmission network, preventing congestion and ensuring efficient power delivery.
- Emergency Power Supply:This application provides backup power during outages or system failures, often through distributed generation or battery storage.
Renewable Integration applications are expanding most quickly, driven by global decarbonization targets.
Deployment:
Deployment models for ancillary services are shifting from traditional centralized assets to more distributed and intelligent solutions, reflecting technological advancements.
- Virtual Power Plants:These aggregate diverse distributed energy resources, such as solar, storage, and demand response, to operate as a single power plant in energy markets. European markets, particularly in Germany, show high adoption of virtual power plant technology.
- Distributed Energy Resources:These are small-scale power generation or storage units located close to consumers, including rooftop solar, battery storage, and electric vehicles. Policies like FERC Order 2222 in the United States encourage DER participation in wholesale markets.
- On-Premise:This traditional model involves dedicated equipment installed at a utility's facility or large power plant to provide specific ancillary services. Many older grid assets still rely on on-premise solutions for voltage control.
- Cloud-Enabled:This deployment leverages cloud computing for monitoring, control, and optimization of ancillary services, offering scalability and real-time data processing.
- Microgrid Systems:These localized grids can operate independently or connected to the main grid, providing resilience and localized ancillary services.
Virtual Power Plants exhibit the steepest expansion trajectory, leveraging aggregation capabilities.
End User:
The end-user segment identifies the primary purchasers and beneficiaries of ancillary services, reflecting the various roles within the electricity market structure.
- Independent System Operators:These entities manage the flow of electricity across transmission lines, balancing supply and demand in wholesale markets. Independent System Operators in the US, like PJM, are major procurers of ancillary services.
- Transmission Operators:These companies own and maintain the high-voltage transmission infrastructure, ensuring reliable power delivery across regions. European Transmission System Operators are adapting procurement to new grid challenges.
- Distribution Companies:These utilities deliver electricity from the transmission grid to end consumers, managing local networks and voltage. Local distribution companies are increasingly exploring ancillary services for grid edge management.
- Generation Companies:These entities own and operate power plants, providing electricity and sometimes ancillary services to the grid.
- Capacity Market Operators:These organizations run markets to ensure sufficient generation capacity is available to meet future demand, often involving ancillary service providers.
Independent System Operators represent the largest segment in terms of procurement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pioneering market designs for grid stability are increasingly influencing regulatory frameworks in other nations, driving global demand for advanced ancillary services. This market expansion is critical for integrating variable renewable energy sources.
Germany
Germany exhibits high demand for frequency regulation due to its substantial renewable energy penetration. The EU Green Deal and its network codes mandate specific technical capabilities for generating modules. Bavaria's industrial clusters implement advanced microgrid solutions to enhance local grid resilience.
United States
United States demand for ancillary services grows from increasing Distributed Energy Resources and grid modernization efforts. FERC Order 2222 dismantles barriers for DERs to participate in wholesale energy and ancillary service markets. PJM Interconnection procures significant volumes of frequency regulation and spinning reserve for system security.
The United Kingdom
The United Kingdom's National Grid procures significant spinning reserve to ensure system security and manage intermittent generation. Performance-based remuneration models for fast-frequency response disrupt legacy capacity payments. London's urban infrastructure requires robust voltage support and reliable emergency power supply for critical operations.
Australia
Australia's aggressive renewable targets necessitate massive investment in grid stabilization services to manage variable wind and solar power generation. The Australian Energy Market Operator adopts performance-based remuneration for ancillary services. South Australia invests heavily in grid-scale battery storage, integrating these assets for frequency response and voltage support.
Spain
Spanish grid operators invest heavily in renewable integration solutions to manage the variability of wind and solar power generation. European Union network codes, such as the RfG, mandate specific technical capabilities for new generating modules. Andalusia, a major solar power region, engineers ancillary service functions into its renewable plants from the design stage.
Global Ancillary Services Power Market Key Industry Players
Listed leaders compete with private specialists across the full spectrum of grid ancillary services, from hardware provision to software optimization. The market exhibits a tiered structure, with established industrial conglomerates alongside agile technology providers offering specialized solutions. Strategic archetypes include traditional equipment manufacturers, energy management software developers, and battery storage system integrators. Portfolio diversification, strategic partnerships, and targeted acquisitions are dominant competitive moves.
Specialists in integrated energy management solutions include Siemens AG, a German-based AG, which serves both centralized and decentralized market participants with comprehensive offerings. General Electric Company, an Inc., leverages its extensive turbine and grid software portfolio to support incumbent utilities and large infrastructure projects globally. Tesla, Inc., another Inc., exemplifies a focus on advanced battery storage systems and virtual power plant software, representing the technology-driven segment of the market. These companies collectively demonstrate the diverse approaches to capturing value in the evolving ancillary services landscape.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Duke Energy Corporation |
| General Electric Company |
| Tesla, Inc. |
| NextEra Energy |
| Siemens AG |
| Enel S.p.A. |
| Engie SA |
| ABB Ltd. |
| Others |
Cost & Logistics Intelligence
Scale economies in advanced power electronics and software development shape both supply concentration and competitive price floors. Large-scale battery manufacturing and virtual power plant software platforms benefit from significant investment, leading to cost efficiencies that influence market entry and pricing.
Pricing Analysis
The technology-generation pricing gap between traditional synchronous generation and fast-responding inverter-based resources creates market tension. Compensation models are shifting from capacity-based payments to performance-based remuneration, linking value directly to speed and accuracy of service delivery. Price differentiation stems from asset performance, technological sophistication, and the specific regulatory market. Pricing softness runs through legacy capacity markets due to new, cheaper, faster solutions. Independent System Operators exhibit high price sensitivity, balancing reliability needs with cost-effectiveness for grid stability.
Supply Chain Analysis
Inventory management for grid-scale battery systems faces long lead times for critical raw materials and complex manufacturing processes. Geographic supply concentration for lithium-ion batteries centers in China, South Korea, and Japan. Raw material dependencies include lithium, cobalt, nickel, and specialized semiconductors for power electronics. Geopolitical tensions affecting critical mineral supply present a significant structural risk. Distribution runs through direct sales channels to large utilities, EPC contractors, and specialized VPP software integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ancillary services market is experiencing a buyer-power shift, as the proliferation of Distributed Energy Resources and Virtual Power Plants fragments the traditional procurement landscape for grid operators.
For Market Incumbents:
Compound existing grid software portfolios with advanced AI and machine learning capabilities to optimize asset utilization. Integrate battery storage solutions and VPP platforms to compete with agile specialists, countering the threat from new technology providers. Invest in grid-forming inverter technology to maintain essential grid services. Leverage established utility relationships to offer integrated energy management services.
For New Entrants and Emerging Players:
Service-layer gaps in AI-optimized bidding platforms and Vehicle-to-Grid integration present significant white-space opportunities. Target fast-frequency response markets in regions with high renewable penetration, such as the United Kingdom and Australia. Develop specialized software-as-a-service solutions for aggregating diverse DERs. Focus on interoperability and standardization to enable seamless integration into existing grid infrastructure.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors agile software developers and battery storage integrators with proven VPP capabilities. Long-term viability is strong, driven by global decarbonization targets and grid modernization needs. Target companies with strong intellectual property in AI-driven optimization or grid-forming inverter technology. The signal to watch is regulatory clarity for DER participation in emerging markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout (grid-scale batteries) | Strengthens fast-frequency response capabilities for grid operators. |
| Software Platform Integration (VPPs) | Aggregates distributed resources, enhancing market participation for DERs. |
| Strategic Partnership (V2G technology) | Unlocks electric vehicle fleets as flexible grid assets for frequency regulation. |
| Green Certification Program (renewable assets) | Signals compliance with EU network codes, attracting green investment. |
| Geographic Expansion (developing nations) | Captures first-mover advantage in modernizing grids in Southeast Asia. |
Research Approach
Desk research of regulatory filings from FERC and EU network codes, alongside academic papers on grid stability, preceded structured interviews with grid operators, VPP developers, battery storage manufacturers, and energy policy analysts. This primary research was triangulated with secondary data from corporate reports by General Electric Company, Siemens AG, and Tesla, Inc. Both bottom-up and top-down approaches validated market sizing and growth projections.
Variance decomposition isolated key drivers across the analysis window, informing the forecast framework. Segmentation dimensions modeled included service type, application, deployment model, end-user, and regional regulatory frameworks. Compound annual growth rates were extrapolated from historical growth trends and projected technology adoption curves. Key forecast inputs included renewable energy deployment targets and battery cost reduction trends.
Forecasts assume regulatory continuity in the United States (FERC) and European Union (EU Green Deal); material policy shifts would require re-modeling. Unforeseen technological breakthroughs or major geopolitical events affecting energy markets represent specific risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Direct Current Power System Market
Power
Solar UPS Market
Power
Malaysia Power EPC Market
Power
Europe Power Market
Power
Europe Submarine Power Cables Market
Power
North America Power Market
Power
Asia-Pacific Microturbine Market
Power
Argentina Power Market
Power
Mexico Power EPC Market
Power
North America CHP Market
Power
Statcom Market
Power
Gabon Power Market
Power
Uzbekistan Power Market
Power
Power Shelf Market
Power
Electric Arc Furnaces Market
Power
Substation Automation System Market