
 Global Hydraulic Turbine Market | 2026-2036
Global Hydraulic Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydraulic Turbine Market Outlook
Aftermarket service revenue is fragmenting across regional service hubs and OEM captive networks. GE Vernova leverages its installed base in North America to secure long-term refurbishment contracts. Andritz Hydro anchors European aftermarket demand through localized service centers. Voith Hydro competes on digital monitoring integration, extending turbine life cycles for utility operators.
A hydraulic turbine converts the kinetic and potential energy of flowing or falling water into rotational mechanical energy, typically driving generators at speeds from 75 to 1,000 RPM depending on head and flow conditions. Francis turbines dominate installed capacity across medium-head installations, while Pelton turbines capture high-head, low-flow sites where efficiency exceeds 90%. Pumped storage systems represent the fastest-growing application segment as grid operators prioritize frequency regulation and renewable integration buffers.
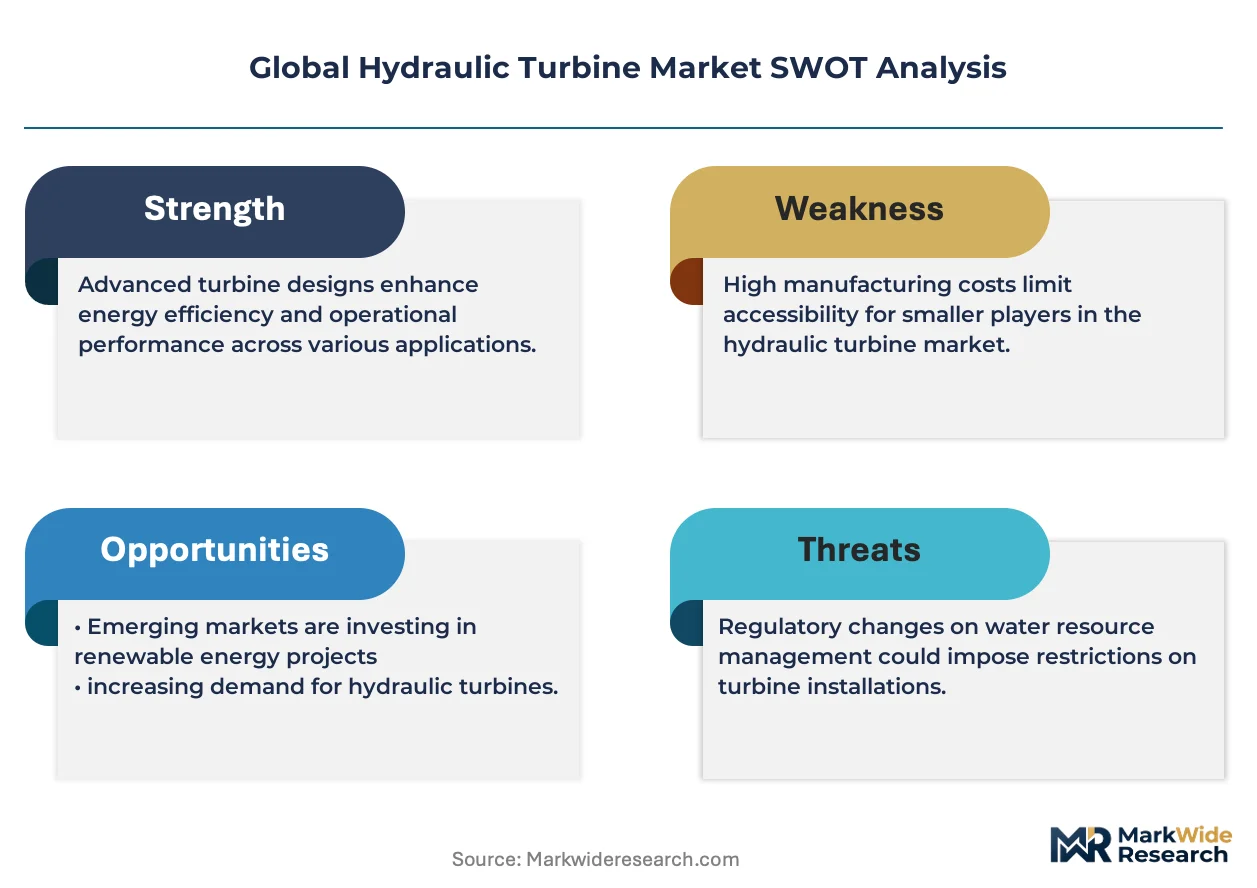
The EU Green Deal and F-Gas Regulation shape equipment standards and carbon disclosure requirements for European installations. China's MEE enforces environmental impact assessments for reservoir-based projects, affecting approval timelines. The US Federal Energy Regulatory Commission governs licensing for non-federal hydropower, creating compliance thresholds that favor established suppliers. Stakeholders must monitor evolving carbon border mechanisms and water-use regulations that will determine project economics and supplier qualification criteria.
Market Dynamics
Pumped storage deployment is concentrating utility procurement around frequency regulation capabilities, while carbon border mechanisms and water-use regulations are redrawing supplier qualification thresholds across Europe, China, and North America.
Growth Catalysts
- EU Green Deal Taxonomy:Certified sustainable hydropower assets now access preferential capital pools, redirecting institutional investment toward turbine refurbishment and greenfield reservoir projects in EU member states.
- Grid stabilization mandates:Utility operators in Germany, Spain, and Italy are procuring pumped storage capacity to buffer renewable intermittency, creating sustained order flow for reversible Francis turbine configurations.
- Digital twin integration:Real-time blade monitoring and predictive maintenance algorithms are extending operational life cycles, reducing unplanned outages for operators managing aging installed bases.
Market Restraints
- Steel and copper price volatility:Runner castings and winding assemblies face input cost swings that compress OEM margins on fixed-price EPC contracts, particularly affecting Pelton turbine producers.
- Reservoir approval timelines:China's MEE environmental impact assessments now extend project development cycles by 18-36 months, freezing capital deployment for large-scale installations.
- Alternative storage economics:Lithium-ion battery systems are capturing frequency regulation contracts at 2-4 hour durations, constraining pumped storage to longer-cycle arbitrage applications.
Strategic Opportunities
- Small hydropower rehabilitation:Norway's 1,600 aging run-of-river installations require runner replacements and generator upgrades, opening aftermarket service contracts for specialized contractors.
- Modular turbine platforms:Standardized 5-20 MW unit designs are reducing engineering lead times, enabling faster deployment across distributed hydropower sites in Brazil's isolated grid regions.
- Carbon border adjustment mechanisms:EU CBAM documentation requirements are favoring European-based casting and machining suppliers, creating localization incentives for turbine component manufacturing.
Industry Challenges
- Specialized welder scarcity:Stainless steel runner fabrication requires certified pressure vessel technicians, with training pipelines failing to match retirement rates in Germany and Austria.
- Legacy control system integration:Digital governor retrofits must interface with 1970s-era mechanical-hydraulic systems, comifying commissioning schedules for refurbishment projects.
- Extended type certification cycles:IEC 60193 model testing protocols demand 12-18 months for prototype validation, delaying commercialization of novel blade profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydraulic Turbine Market |
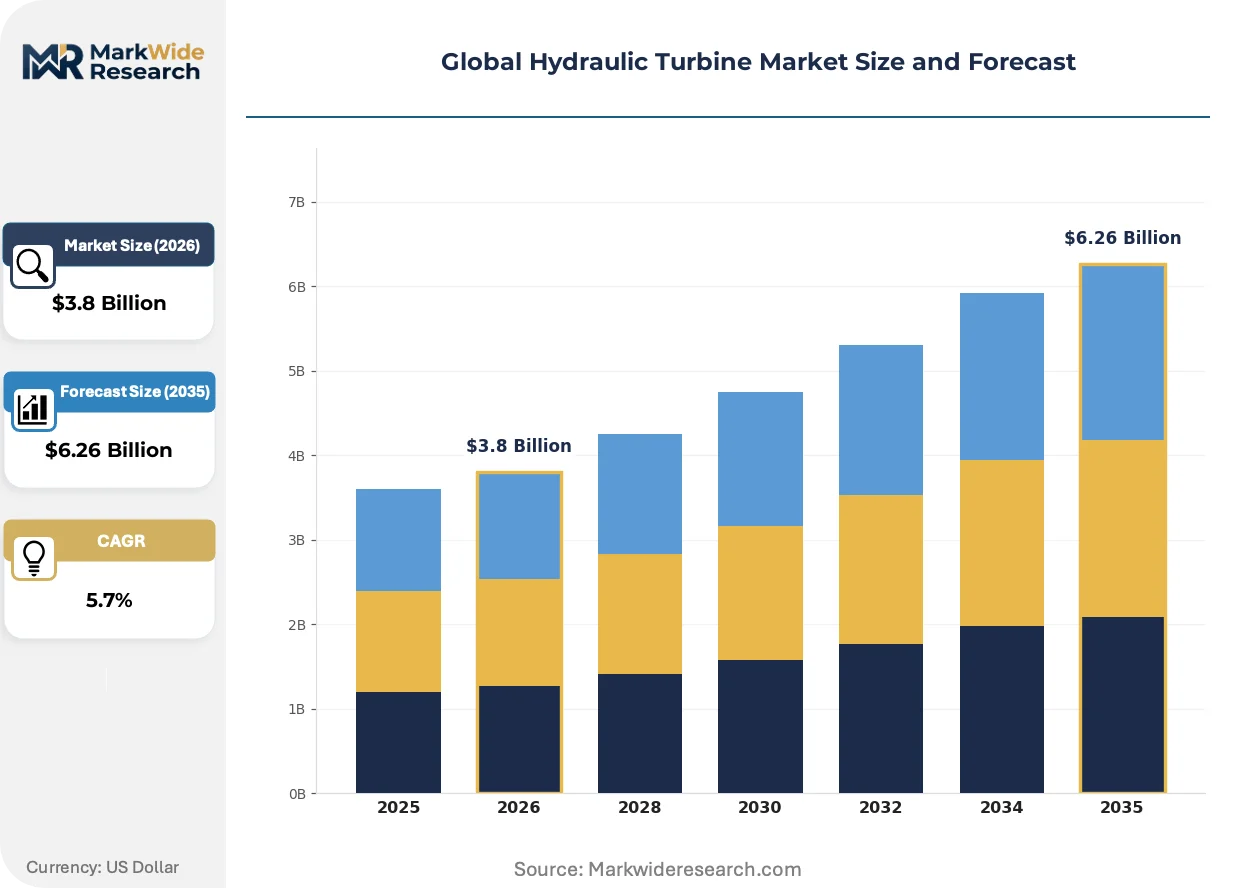
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Impulse Turbines, Reaction Turbines, Pelton Turbines, Francis Turbines Application: Hydroelectric Power Plants, Pumped Storage Systems, Water Supply Systems, Irrigation Systems End User: Utility Companies, Industrial Manufacturers, Government Agencies, Independent Power Producers Installation: Onshore, Offshore, In-Stream, Reservoir-Based |
| Companies Covered | GE Vernova, Andritz Hydro, Voith Hydro, Dongfang Electric Corporation, Harbin Electric Corporation, Toshiba Energy Systems & Solutions, Mitsubishi Heavy Industries, Power Machines, Bharat Heavy Electricals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydraulic Turbine Market Strategic Shifts
Computational fluid dynamics and additive manufacturing are compressing development timelines for blade geometries, while regulatory disclosure requirements are embedding carbon accounting into equipment procurement criteria.
Digital twin platforms are virtualizing turbine performance monitoring across the asset lifecycle. Voith Hydro and Andritz are deploying sensor arrays on Francis runners to capture blade cavitation patterns in real time. Utility operators in Switzerland and Austria are adopting these systems to optimize maintenance windows, reducing forced outage rates while extending intervals between overhauls. This virtualization is compressing the traditional reactive maintenance model into predictive intervention schedules.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in generator cooling systems, forcing OEMs to redesign heat exchange architectures. Manufacturers serving the European market must now certify alternative dielectric fluids or transition to air-cooled designs for smaller units. This regulatory pressure is most acute in the 10-50 MW segment, where project developers are absorbing retrofit costs to maintain grid connection permits.
Aftermarket service unbundling is fragmenting the traditional OEM-captive model. Independent service providers in Canada and Sweden are securing long-term operations contracts through specialized runner repair capabilities and faster response times. Regional hubs in Montreal and Gothenburg are capturing refurbishment volume that previously flowed to manufacturer service networks. This channel disruption is most visible among municipal utilities managing distributed asset portfolios across Scandinavia.
Global Hydraulic Turbine Market Segmentation
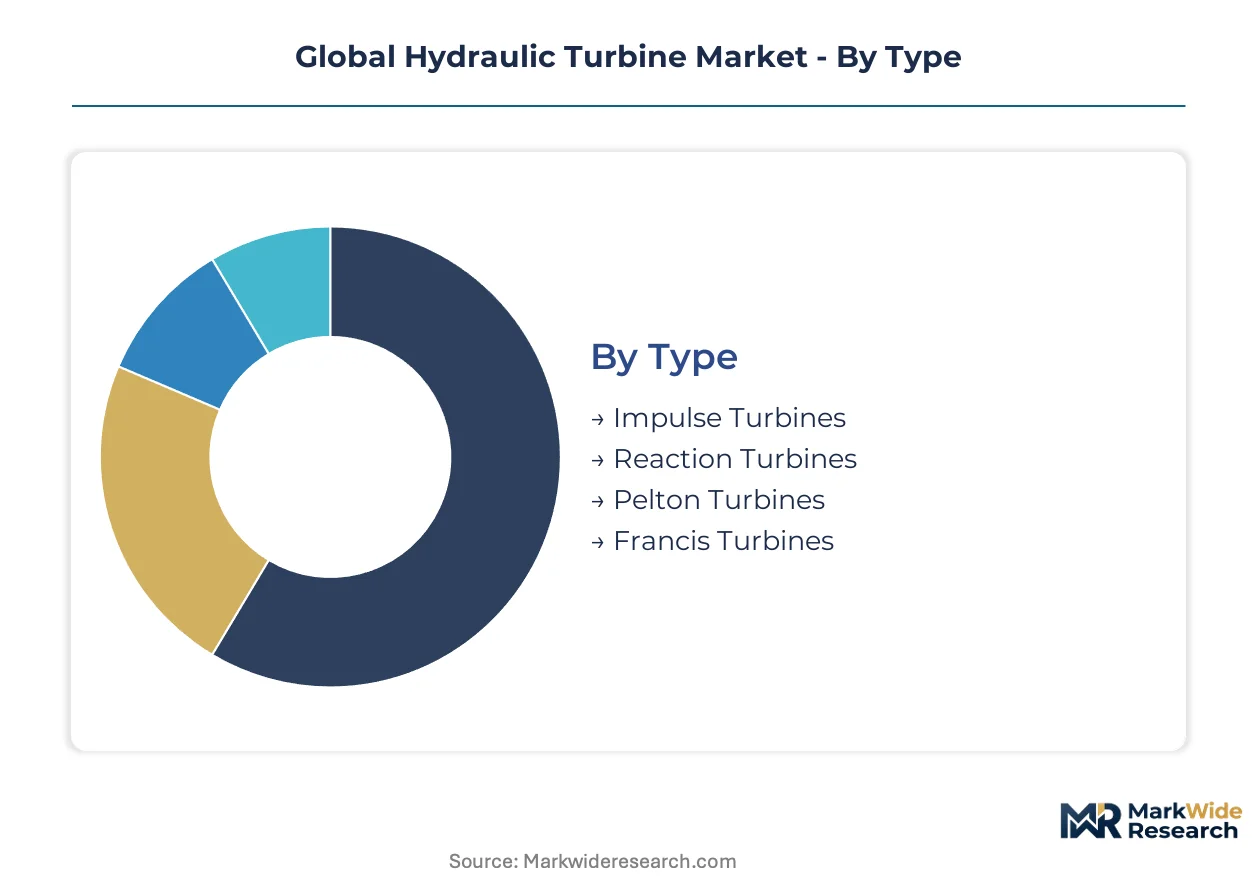
Turbine classification determines equipment selection, project economics, and aftermarket service requirements across hydropower installations. Segmentation by type, application, end user, and installation site reveals where procurement budgets concentrate and where technology gaps create supplier opportunities.
Type:
Cost tier differentiation separates impulse configurations from reaction designs based on head height and flow volume economics.
- Impulse Turbines:These units harness water velocity through jet-driven bucket mechanisms, excelling at high-head sites exceeding 300 meters. Demand concentrates in the Swiss Alps and Norwegian fjord regions where mountainous terrain creates steep hydraulic gradients, though steel casting costs for precision buckets compress margins on smaller installations.
- Reaction Turbines:Operating fully submerged with pressure differential across the runner, these systems dominate medium-head applications from 20 to 300 meters. Procurement from Brazilian utility operators and Chinese provincial power bureaus drives volume, with Francis variants capturing the bulk of new orders due to operational flexibility across variable flow conditions.
- Pelton Turbines:The precision-jet impulse design achieves efficiency above 90% at high-head, low-flow sites in the Andes and Himalayan watersheds.
- Francis Turbines:The most widely deployed reaction type serves run-of-river and reservoir projects across Germany, Austria, and Canada's British Columbia.
Francis configurations command the established base. The steepest expansion runs through Pelton installations at extreme head sites.
Application:
Application type determines duty cycle intensity and grid service revenue potential for turbine operators.
- Hydroelectric Power Plants:Conventional run-of-river and reservoir facilities provide baseload generation across Brazil's grid network and China's western provinces. These installations prioritize reliability over rapid response, with 40-year asset lifecycles driving refurbishment demand for aging runner assemblies in Norway and the United States Pacific Northwest.
- Pumped Storage Systems:Reversible turbine-pump configurations enable daily cycling between upper and lower reservoirs, delivering frequency regulation services to grid operators in Germany, Italy, and Switzerland. The EU Green Deal taxonomy certification accelerates capital deployment toward these assets as renewable penetration rises.
- Water Supply Systems:Small turbine installations recover energy from pressure reduction valves in municipal distribution networks across California and Spain.
- Irrigation Systems:Micro-hydro units embedded in canal infrastructure serve agricultural energy demand across India's Punjab region and Pakistan's Indus basin.
Hydroelectric power plants anchor installed capacity. Pumped storage systems are climbing the fastest as grid stabilization mandates tighten.
End User:
Customer type shapes procurement sophistication, contract duration, and service bundling requirements.
- Utility Companies:Vertically integrated grid operators in France, Sweden, and Japan deploy centralized procurement teams for multi-unit projects. These buyers negotiate 25-year service agreements alongside equipment supply, favoring OEMs with localized spare parts inventory.
- Industrial Manufacturers:Aluminum smelters and chemical processors in Iceland and Quebec operate captive hydropower for process energy, prioritizing uptime guarantees over capital expenditure minimization.
- Government Agencies:State-owned power developers in Ethiopia and Laos manage sovereign-funded dam projects with extended environmental approval timelines.
- Independent Power Producers:Merchant operators in Turkey and Chile seek rapid deployment of standardized units to capture renewable energy certificate revenue windows.
Utility companies dominate order flow. Independent power producers are gaining share fastest through distributed project development.
Installation:
Site configuration determines civil engineering intensity, environmental permitting complexity, and equipment access constraints.
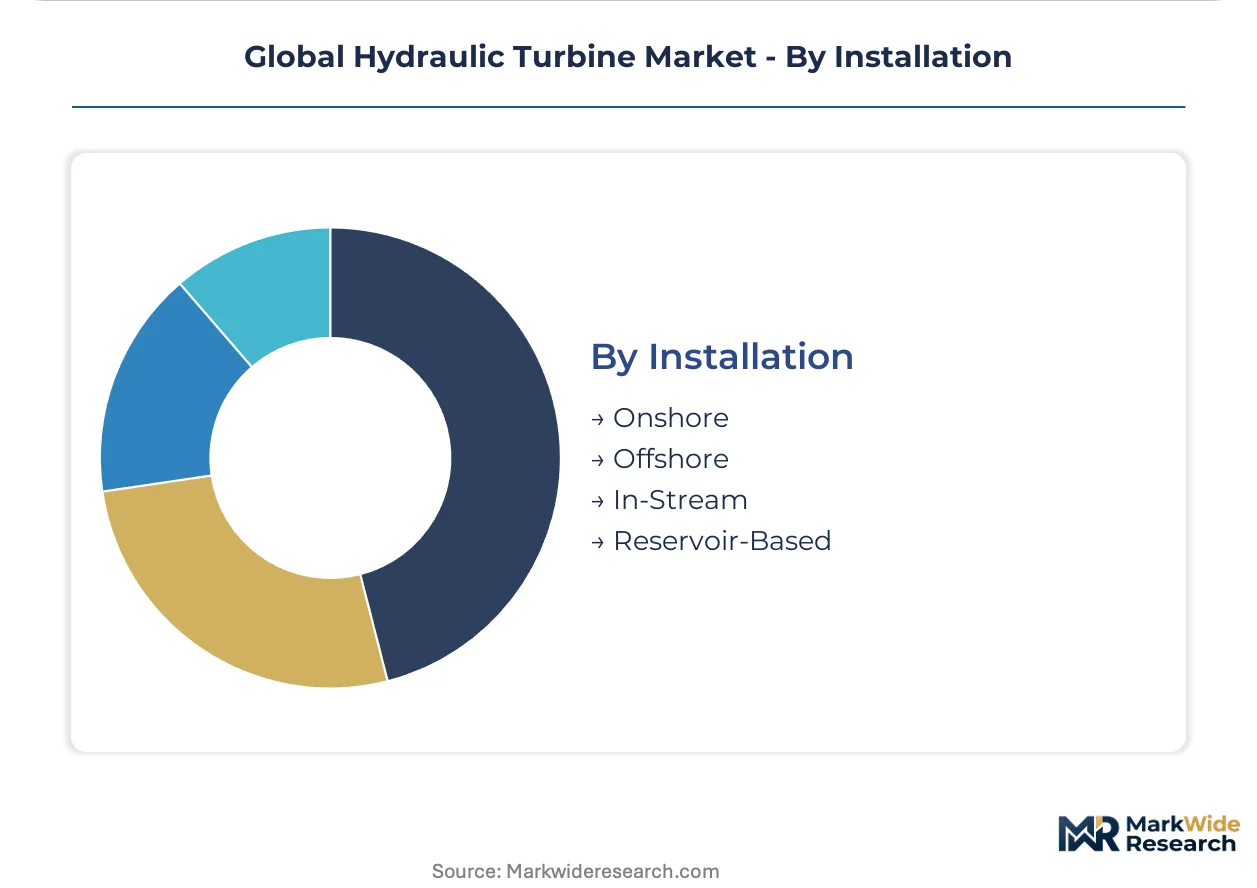
- Onshore:Conventional powerhouse installations at dam toe or diversion canal sites represent the majority of global capacity. These projects in Austria, Slovenia, and New Zealand benefit from established supply chains for heavy electrical equipment and concrete construction.
- Reservoir-Based:Large-scale dam-integrated facilities in China, Brazil, and Canada require staged turbine commissioning synchronized with reservoir filling schedules, extending project timelines.
- Offshore:Tidal barrage and submerged turbine pilots operate in France's Rance estuary and South Korea's Sihwa Lake.
- In-Stream:Run-of-river units without dam infrastructure serve remote load centers across Indonesia's outer islands and the Philippines.
Onshore installations command the established base. In-stream configurations are expanding most quickly for isolated grid electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turbine manufacturing capacity clusters where reservoir development, steel casting infrastructure, and grid interconnection requirements overlap. China, Brazil, Norway, the United States, and Germany concentrate the bulk of new orders and refurbishment demand.
China
Provincial power bureaus in Sichuan and Yunnan drive procurement for mega-dam projects along the Jinsha and Lancang rivers. The MEE enforces environmental impact assessments that extend approval timelines by 18-36 months. Manufacturing clusters in Chengdu and Harbin supply runners for domestic installations and export markets across Southeast Asia.
Brazil
State-owned utilities commission Francis turbines for run-of-river installations in the Amazon and Paraná basins. ANEEL regulates grid connection standards that favor established OEM service networks. Equipment fabrication concentrates in São Paulo state, where local content requirements shape supplier qualification for Belo Monte and other federal projects.
Norway
Statkraft and municipal operators manage 1,600 aging run-of-river sites requiring runner replacements and generator upgrades. The Norwegian Water Resources and Energy Directorate licenses reservoir operations with strict environmental flow requirements. Aftermarket service contracts concentrate around Bergen and Trondheim, where specialized contractors compete with OEM captive networks.
United States
Independent power producers and federal agencies refurbish aging infrastructure in the Pacific Northwest and Tennessee Valley. FERC governs licensing for non-federal hydropower, creating compliance thresholds that favor suppliers with established spare parts logistics. Pumped storage development in California and Virginia responds to state-level renewable integration mandates.
Germany
Utility operators in Bavaria and Baden-Württemberg procure pumped storage capacity to buffer renewable intermittency. The EU Green Deal taxonomy redirects institutional capital toward certified sustainable assets. Manufacturing and service capabilities cluster along the Rhine and Neckar valleys, where Voith Hydro maintains headquarters and model testing facilities.
Global Hydraulic Turbine Market Competitive Environment
Integrated energy conglomerates and specialized hydropower engineering groups split the market between turnkey project execution and component-focused supply. The vendor base concentrates among European, North American, and East Asian firms with century-long track records in runner design. Two archetypes dominate: full-service OEMs bundling equipment with long-term service contracts, and regional specialists capturing aftermarket refurbishment through faster response times. Competitive positioning hinges on digital monitoring integration and localized spare parts inventory rather than price alone.
Among the full-service OEM tier, GE Vernova, Andritz Hydro, and Voith Hydro occupy positions defined by installed base scale and geographic anchoring. GE Vernova leverages its North American footprint to secure long-term refurbishment contracts for aging federal and utility assets. Andritz Hydro anchors European demand through localized service centers in Austria and Germany. Voith Hydro competes on digital twin integration and predictive maintenance platforms, extending turbine life cycles for operators managing Swiss and Austrian alpine installations.
| Leading Market Players |
|---|
| GE Vernova |
| Andritz Hydro |
| Voith Hydro |
| Dongfang Electric Corporation |
| Harbin Electric Corporation |
| Toshiba Energy Systems & Solutions |
| Mitsubishi Heavy Industries |
| Power Machines |
| Bharat Heavy Electricals |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese runner casting facilities is compressing OEM margins while simultaneously enabling aggressive pricing postures for domestic EPC contractors bidding on Belt and Road hydropower projects. This utilization asymmetry between Asian forging capacity and European precision-machining bottlenecks creates divergent pricing power across supplier tiers.
Pricing Analysis
Aftermarket service revenue tiers—spanning spare parts, scheduled maintenance, and 25-year performance guarantees—now drive lifetime value capture exceeding original equipment margins. Three-tier pricing structure across premium, standard, and economy levels separates OEM-captive service networks from independent regional contractors and commodity runner repair shops. Cost compression in the economy tier is intensifying because Chinese provincial power bureaus are consolidating procurement into framework agreements. Municipal utilities in Scandinavia show highest price sensitivity due to distributed asset portfolios, while aluminum smelters in Iceland demonstrate lowest sensitivity given uptime-critical captive operations.
Supply Chain Analysis
Contract manufacturing concentration rests with Dongfang Electric Corporation and Harbin Electric Corporation in China, Voith Hydro and Andritz Hydro in Germany and Austria, and GE Vernova's captive foundries in the United States. Runner castings draw from stainless steel forging capacity in China, precision machining clusters in Germany and Switzerland, and copper winding assemblies from South Korean and Japanese suppliers. Single-source vulnerability concentrates in large-diameter Francis runner forgings exceeding 10 meters diameter, where only three global facilities maintain qualified capacity. Distribution runs through OEM-direct channels for utility-scale projects and specialized hydropower contractors for refurbishment segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards suppliers who control scarce certified welding capacity and localized model-testing infrastructure, yet training pipelines for pressure vessel technicians in Germany and Austria are failing to match retirement rates.
For Market Incumbents: Pre-empt runner repair volume migration to independent service providers by embedding digital twin diagnostics into standard maintenance contracts. Establish captive spare parts inventory in Bergen and Montreal to match regional competitor response times. Backward integration into stainless steel casting capacity insulates margin compression from commodity price volatility. For New Entrants and Emerging Players: Brazil's isolated grid regions in the Amazon basin offer underpenetrated demand for standardized 5-20 MW modular turbine platforms with shortened engineering lead times. Target run-of-river rehabilitation contracts among Norway's 1,600 aging installations where specialized welding capabilities create qualification barriers for generalist competitors. Partner with established EPC contractors to bypass OEM-captive service network relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pumped storage reversible turbine configurations as grid stabilization mandates tighten frequency regulation requirements. Long-term viability favors suppliers with demonstrated IEC 60193 model testing protocols and established digital monitoring platforms. Monitor FERC licensing approval timelines for non-federal hydropower as inflection indicator for North American refurbishment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Voith Hydro and Andritz are virtualizing blade cavitation monitoring to compress maintenance windows for Swiss and Austrian alpine operators. |
| Localized Service Center Expansion | GE Vernova leverages North American footprint to secure long-term refurbishment contracts for aging federal and utility assets. |
| Modular Turbine Platform Standardization | Brazilian OEMs are reducing engineering lead times to enable faster deployment across distributed hydropower sites in isolated grid regions. |
| Alternative Dielectric Fluid Certification | EU F-Gas Regulation is forcing redesign of generator cooling architectures for 10-50 MW segment suppliers serving European markets. |
| Independent Service Provider Capacity Buildout | Regional hubs in Montreal and Gothenburg are capturing refurbishment volume that previously flowed to manufacturer captive networks. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, EPC contractors, aftermarket service heads, and plant engineers at hydropower installations. Secondary validation drew from FERC licensing databases, IEA hydropower statistics, EIA generation capacity reports, and project development registries. Bottom-up unit economics triangulated against top-down macroeconomic indicators across the analysis window.
Calibration against historical order intake patterns and announced project pipelines anchored the analytical framework throughout the forecast period. Segmentation dimensions modeled include turbine type, application duty cycle, end-user procurement sophistication, and installation site configuration. CAGRs were derived from regression analysis of equipment shipments and refurbishment contract awards, incorporating steel and copper price indices as cost-side variables.
Practitioners should monitor MEE environmental impact assessment timelines, EU CBAM documentation requirements, and lithium-ion battery frequency regulation contract capture rates for early signals of demand inflection. Quarterly review of runner casting capacity utilization, certified welder training graduation rates, and FERC licensing approval velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Solar UPS Market
Power
Solar Plants Controllers Market
Power
Marine Thermal Fluid Heaters Market
Power
Water Turbine Market
Power
Power Rental Market
Power
Asia-Pacific Alternating Current (AC) Drive Market
Power
Global Marine Power Systems Market
Power
Controllable Shunt Reactor for UHV Market
Power
Wireless Power Receiver Market
Power
Italy Power EPC Market
Power
Sudan Power Market
Power
Denmark Power Market
Power
Oxy-Hydrogen Generators Market
Power
Middle-East and Africa Power Market
Power
Flue Gas Desulfurization Unit Market
Power
Substation Automation System Market