
 Brunei Power Market | 2026-2036
Brunei Power Market Size, Share, and Industry Trends Forecast 2026-2036
Brunei Power Market Outlook
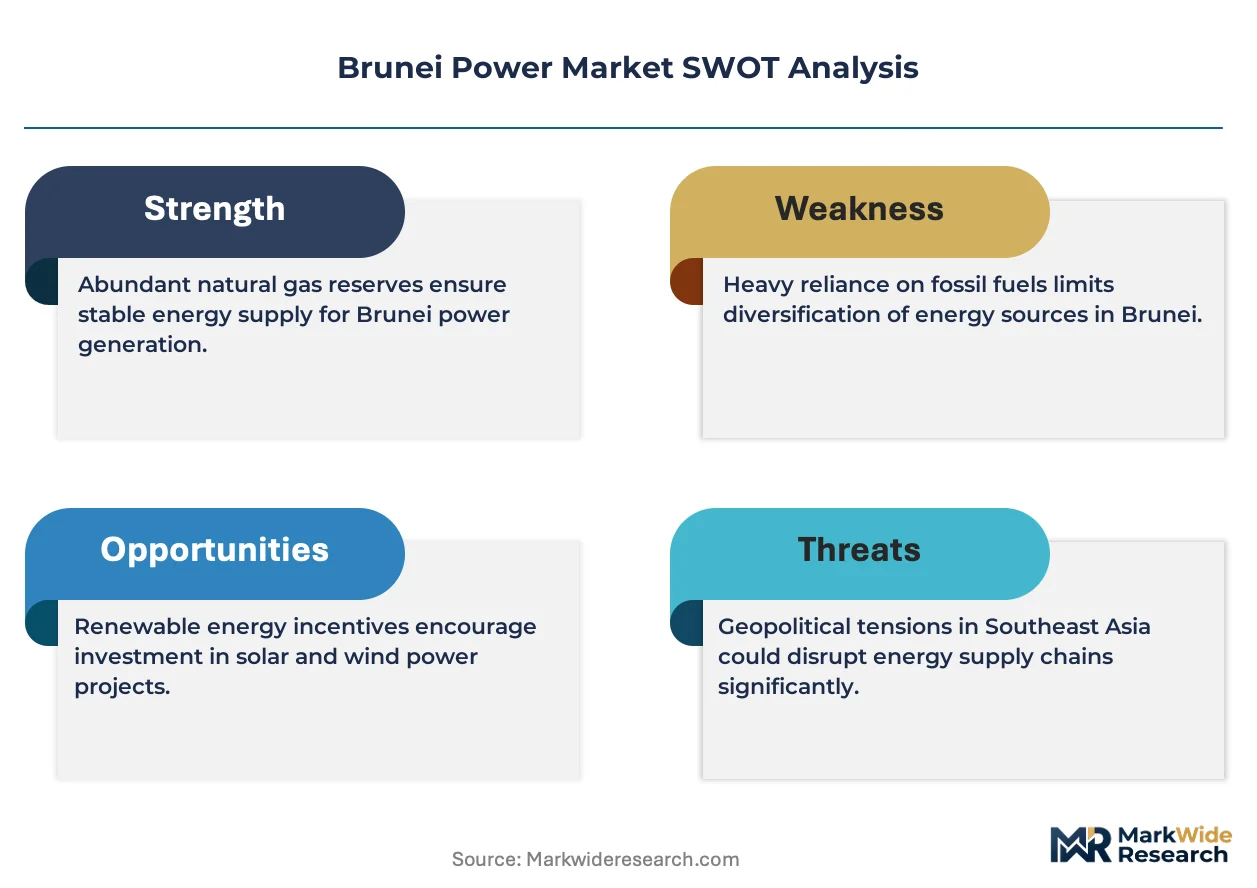
Brunei's gas-fired generation fleet is rebalancing toward efficiency upgrades and renewable integration. Berakas Power Company Sdn Bhd leverages its distribution monopoly across the Sultanate's grid infrastructure. Brunei Shell Petroleum anchors captive power supply for the Lumut refinery and LNG export complex. General Electric Company competes through advanced gas turbine technology tailored for Southeast Asian fuel profiles.
Brunei power encompasses electricity generation, transmission, and distribution services operating within a 575-megawatt national system dominated by natural gas combined-cycle plants serving industrial and residential loads. The Service Type dimension shows electricity generation commanding the value pool while renewable energy emerges as the fastest-expanding category under Brunei's renewable energy policy targets. Technology segmentation reveals gas turbine systems maintaining baseline supply dominance even as solar PV installations accelerate across government and commercial rooftops.
The Department of Electrical Services regulates grid access and tariff structures under Brunei's national energy policy, while the country's petroleum regulator oversees fuel supply security for thermal generators. Brunei's commitment to the ASEAN Power Grid initiative and domestic renewable portfolio standards is reshaping investment criteria for new capacity. Stakeholders must monitor feed-in tariff negotiations and cross-border interconnection feasibility to align capital deployment with evolving dispatch priorities.
Market Dynamics
Brunei's power sector faces a structural pivot where gas turbine efficiency mandates are compressing dispatch economics for legacy open-cycle units while solar PV integration accelerates across government rooftops. The Department of Electrical Services enforces national energy efficiency regulations that reshape generation standards and investment timelines for new capacity additions.
Growth Catalysts
- Petrochemical Load Expansion:LNG-linked industrial complexes in the Belait District anchor rising baseload electricity consumption. Brunei Shell Petroleum's captive power requirements for the Lumut refinery drive sustained capacity additions.
- Renewable Portfolio Standards:Brunei's national renewable energy policy targets accelerate solar PV deployment across commercial and government installations. Feed-in tariff negotiations under Department of Electrical Services oversight reshape project finance structures.
- ASEAN Power Grid Alignment:Cross-border interconnection feasibility studies with neighboring markets create long-term export opportunities for Brunei's gas-fired surplus capacity during off-peak domestic demand periods.
Market Restraints
- Natural Gas Supply Concentration:Brunei Shell Petroleum dominates upstream fuel supply for thermal generators, creating single-source dependency risk for the 575-megawatt national system.
- Small Market Scale:Limited domestic demand concentration in the Belait District constrains economies of scale for advanced combined-cycle technology deployments.
- Grid Integration Technical Limits:Legacy distribution infrastructure operated by Berakas Power Company Sdn Bhd presents voltage stability constraints for distributed solar PV penetration beyond current rooftop pilot programs.
Strategic Opportunities
- Industrial Energy Services:Energy-as-a-service models for petrochemical complexes offer recurring revenue streams beyond traditional kilowatt-hour sales to Brunei Shell Petroleum and downstream operators.
- Hybrid Microgrids:Solar-plus-storage configurations for remote industrial facilities reduce dependence on centralized grid extensions across Brunei's dispersed industrial zones.
- Carbon Capture Integration:Brunei's petroleum regulator oversight of fuel supply security creates regulatory pathways for blue hydrogen production linked to existing gas turbine infrastructure.
Industry Challenges
- Specialized Technician Scarcity:Grid-scale solar PV installation and maintenance expertise remains concentrated in regional contractors, constraining Brunei's domestic workforce development for renewable energy targets.
- Interconnection Standardization Delays:Absence of unified technical standards between Brunei's Department of Electrical Services and prospective ASEAN Power Grid partners complicates cross-border equipment procurement specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brunei Power Market |
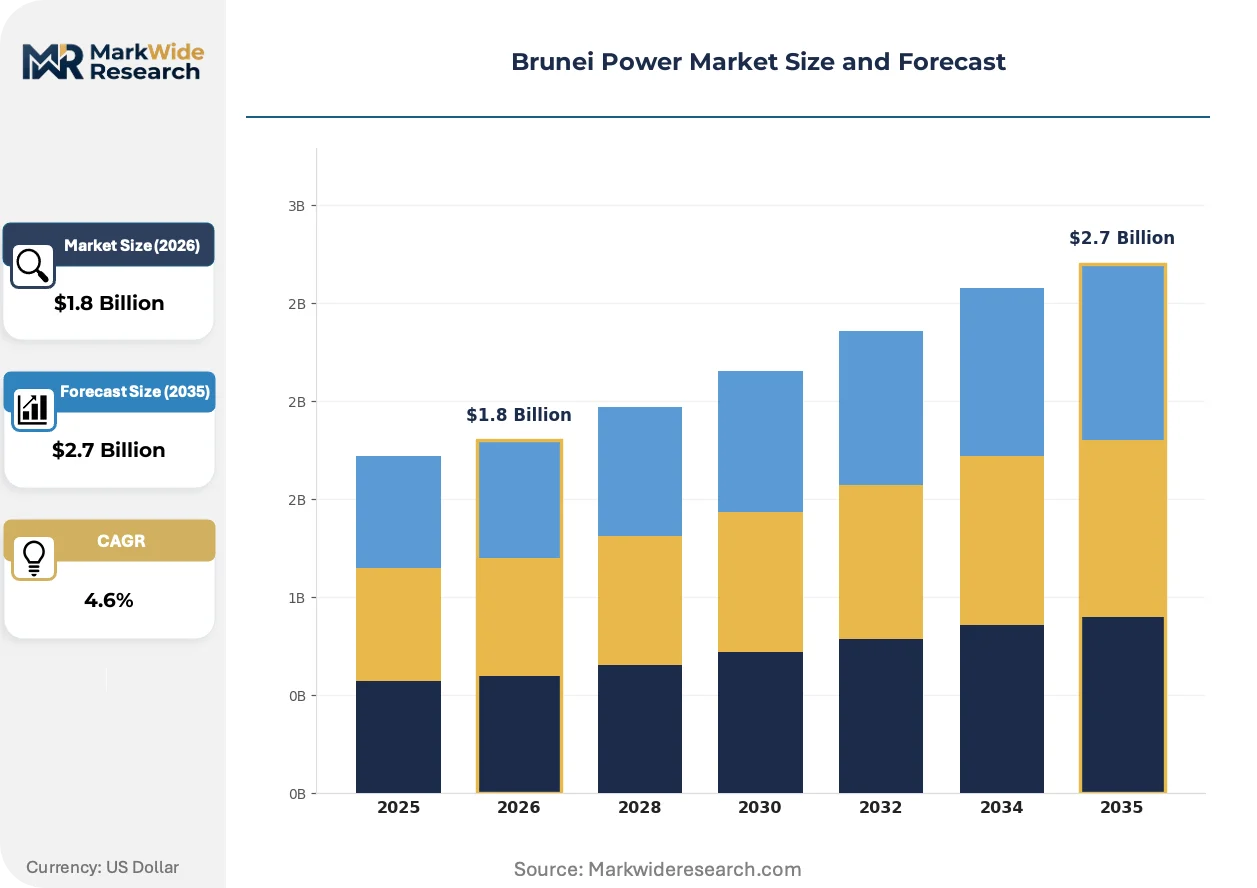
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Electricity Generation, Transmission Services, Distribution Services, Renewable Energy End User: Residential, Commercial, Industrial, Government Technology: Gas Turbine, Hydropower, Solar PV, Biomass Installation Type: On-grid, Off-grid, Hybrid, Standalone |
| Companies Covered | General Electric Company, Solarvest Holdings Berhad, Department of Electrical Services, Marubeni Corporation, Serikandi Oilfield Services Sdn Bhd, Berakas Power Company Sdn Bhd, Toshiba Corp, Brunei Shell Petroleum, Brunei LNG Sdn Bhd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brunei Power Market Strategic Shifts
Technology convergence between gas turbine efficiency upgrades and distributed renewable integration is compressing traditional generation planning cycles. Brunei's regulatory framework and industrial load profile create distinctive conditions for these shifts.
Advanced gas turbine systems with enhanced firing temperatures and improved heat recovery configurations are converging with digital plant optimization platforms. Brunei Shell Petroleum and independent power producers adopt these integrated solutions to maintain dispatch priority under tightening national energy efficiency regulations. The structural consequence is a compressed replacement cycle for legacy open-cycle units that cannot meet upgraded heat rate standards.
Brunei's renewable energy policy targets establish binding solar PV penetration thresholds for government building portfolios. The Department of Electrical Services implements feed-in tariff frameworks that restructure revenue recognition for distributed generators. Commercial rooftop installations in Bandar Seri Begawan respond fastest due to concentrated building ownership and streamlined permitting pathways.
Petrochemical operators in the Belait District increasingly unbundle energy procurement from captive generation ownership. Brunei Shell Petroleum and downstream chemical complexes evaluate third-party power purchase agreements to transfer operational risk while securing carbon accounting advantages. This behavioral shift concentrates buyer leverage among a handful of large industrial offtakers negotiating directly with independent power project developers.
Brunei Power Market Segmentation
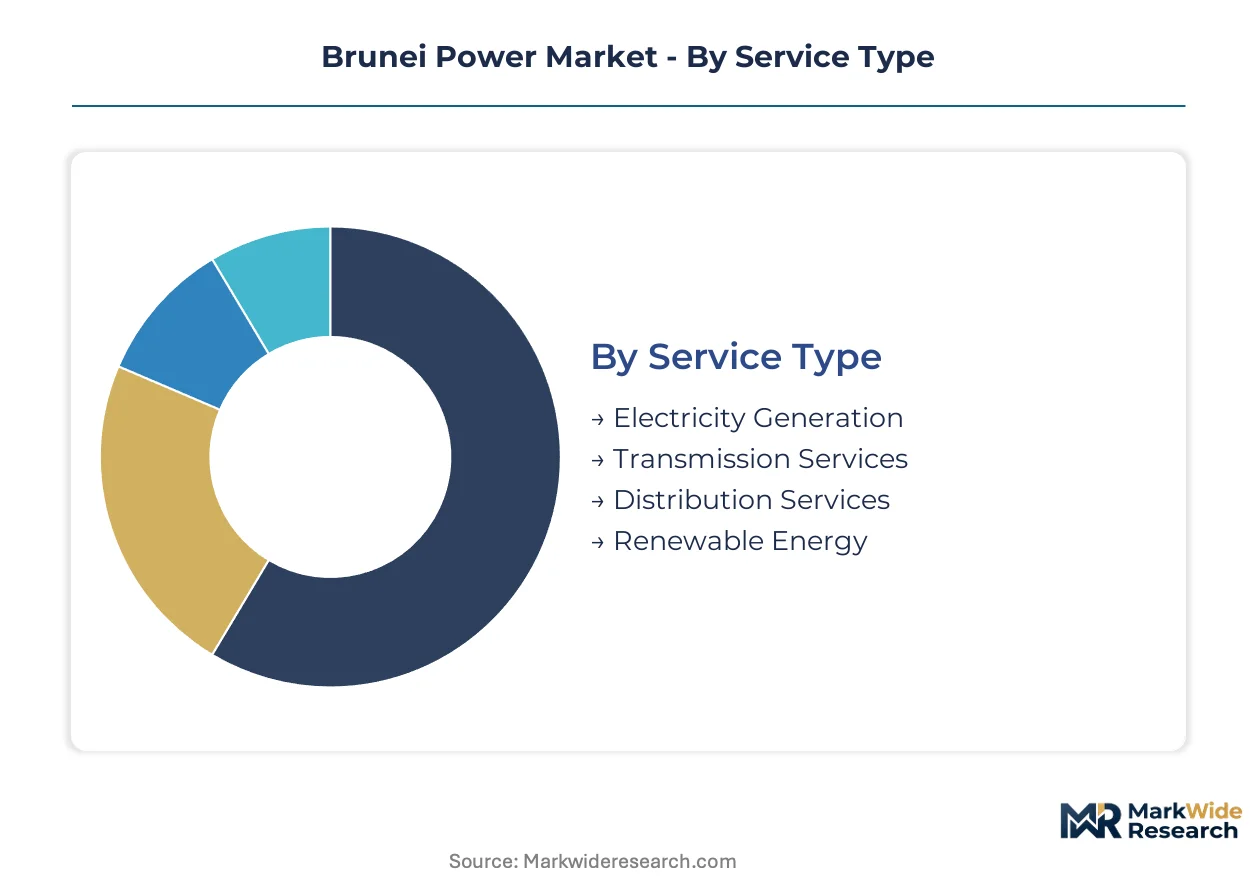
Brunei's power market segmentation reveals how capital deployment priorities differ across service layers and customer classes. The Sultanate's 575-megawatt system concentrates investment in gas-fired baseload while distributed technologies capture policy-driven growth opportunities.
Service Type:
Capital intensity peaks in generation assets requiring fuel supply infrastructure and grid-scale equipment, while distribution networks demand sustained maintenance expenditure.
- Electricity Generation:Combined-cycle gas turbine plants dominate Brunei's installed base, requiring substantial upfront investment in heat recovery steam generators and fuel handling systems. Brunei Shell Petroleum's Lumut refinery complex anchors baseload demand in the Belait District, driving capacity additions with 25-year asset lifecycles.
- Renewable Energy:Solar PV installations accelerate across government building portfolios under Department of Electrical Services feed-in tariff frameworks. Commercial rooftops in Bandar Seri Begawan concentrate near-term deployment due to streamlined permitting and concentrated ownership structures.
- Transmission Services:High-voltage infrastructure connects Belait District generation clusters to coastal demand centers through overhead lines and limited submarine cable crossings.
- Distribution Services:Berakas Power Company Sdn Bhd operates the monopoly distribution network across Brunei's four districts, managing voltage stability for dispersed industrial and residential loads.
Electricity generation absorbs the bulk of installed capacity; renewable energy is expanding most quickly.
End User:
Customer concentration shapes tariff structures and reliability requirements, with industrial offtakers commanding dedicated supply arrangements.
- Industrial:Petrochemical complexes in the Belait District consume the majority of Brunei's electricity output, with Brunei Shell Petroleum operating captive generation for the Lumut refinery and LNG export facilities.
- Government:Public building portfolios face binding solar PV penetration thresholds under national renewable energy policy targets, accelerating procurement of rooftop installations and energy efficiency retrofits.
- Residential:Subsidized tariffs for Brunei citizens limit revenue per connection, with demand concentrated in coastal urban centers around Bandar Seri Begawan.
- Commercial:Retail and hospitality operators in the capital district represent the most price-responsive customer segment for demand-side management programs.
Industrial offtakers anchor system planning; government procurement is climbing the fastest under mandatory renewable targets.
Technology:
Technology selection balances fuel security against integration complexity, with mature thermal systems competing against emerging renewable configurations.
- Gas Turbine:Advanced combined-cycle units with enhanced firing temperatures supply Brunei's baseload, with General Electric Company competing for efficiency upgrade contracts. Heat rate improvements under Department of Electrical Services regulations compress replacement cycles for legacy open-cycle assets.
- Solar PV:Distributed rooftop installations gain share fastest as feed-in tariff negotiations restructure project finance. Grid integration constraints limit penetration beyond current pilot programs due to legacy distribution infrastructure voltage stability limits.
- Hydropower:Limited run-of-river potential exists in Brunei's interior watersheds, with small-scale installations serving remote communities.
- Biomass:Agricultural residue and palm oil waste streams offer theoretical fuel supply, though collection logistics constrain commercial viability in Brunei's dispersed plantation geography.
Gas turbine technology commands the capital base; solar PV is gaining share fastest through policy-mandated deployment.
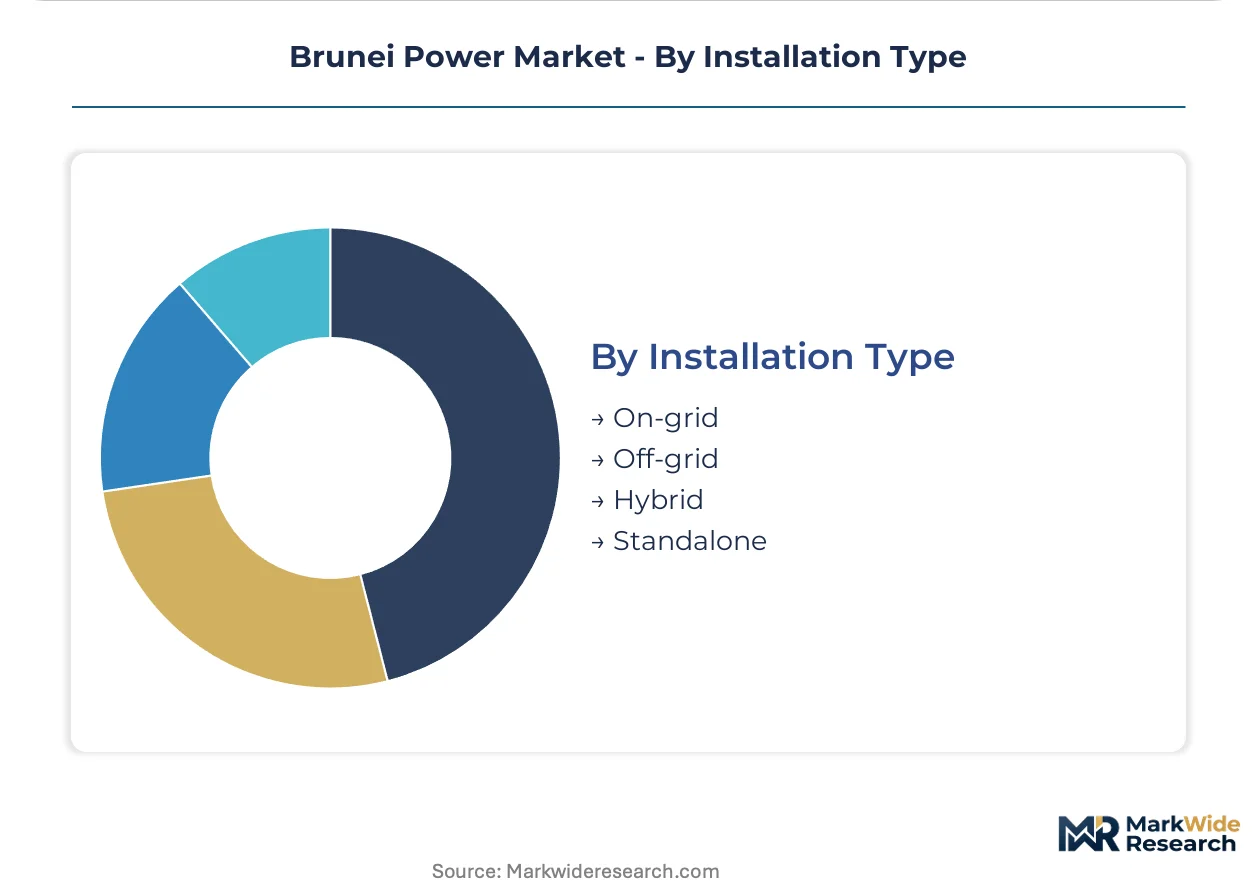
Installation Type:
Grid connection status determines equipment specifications and revenue recognition frameworks across Brunei's dispersed industrial geography.
- On-grid:Centralized connections to Berakas Power Company Sdn Bhd's distribution network serve the majority of Brunei's demand, with interconnection standards enforced by the Department of Electrical Services.
- Hybrid:Solar-plus-storage configurations for remote industrial facilities reduce dependence on centralized grid extensions across dispersed petrochemical zones.
- Off-grid:Standalone diesel and small-scale renewable systems serve isolated residential clusters and temporary construction camps in Brunei's interior.
- Standalone:Fully autonomous power systems operate at specific industrial sites with critical reliability requirements beyond grid backup capabilities.
On-grid installations dominate the asset base; hybrid configurations are expanding most quickly for remote industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brunei-Muara District hosts the capital's administrative and commercial load centers that shape national demand patterns. The Belait District's hydrocarbon processing corridor anchors industrial consumption across the Sultanate's 575-megawatt system.
Belait District
The Lumut refinery and LNG export complex drives sustained baseload requirements for combined-cycle gas turbines. Brunei Shell Petroleum operates captive generation facilities under Department of Electrical Services grid codes. Seria and Kuala Belait concentrate petrochemical load growth that reshapes transmission planning priorities.
Brunei-Muara District
Government building portfolios face binding solar PV penetration thresholds under national renewable energy policy targets. Bandar Seri Begawan's commercial rooftops respond fastest to feed-in tariff frameworks due to concentrated ownership structures. Berakas Power Company Sdn Bhd manages voltage stability constraints across the capital's distribution network.
Tutong District
Agricultural processing and light manufacturing create distributed demand pockets requiring grid extension investments. The district's interior watersheds offer limited run-of-river hydropower potential for remote community electrification. Tutong town serves as a secondary commercial hub with moderate commercial rooftop solar deployment.
Temburong District
Isolated geography drives standalone and hybrid microgrid configurations for border communities and conservation facilities. The district's negligible grid connectivity prioritizes solar-plus-storage solutions over centralized infrastructure extension. Ulu Temburong National Park operations demonstrate autonomous power system reliability requirements.
Brunei Power Market Competitive Environment
Global majors compete with regional champions across equipment supply and project development dimensions in Brunei's concentrated market structure. The vendor base stratifies between integrated technology providers and specialized service contractors serving the 575-megawatt national system. Strategic archetypes include captive industrial generators, state-affiliated distribution monopolies, and international equipment suppliers. Dominant competitive moves center on efficiency upgrade contracting and renewable integration partnerships.
Among international equipment suppliers, General Electric Company and Toshiba Corp exemplify technology providers competing for gas turbine efficiency upgrade contracts. Within the state-affiliated tier, Berakas Power Company Sdn Bhd occupies the distribution monopoly position across Brunei's four districts. Department of Electrical Services represents regulatory oversight functions that reshape competitive positioning through feed-in tariff negotiations and grid interconnection standards.
| Leading Market Players |
|---|
| General Electric Company |
| Solarvest Holdings Berhad |
| Department of Electrical Services |
| Marubeni Corporation |
| Serikandi Oilfield Services Sdn Bhd |
| Berakas Power Company Sdn Bhd |
| Toshiba Corp |
| Brunei Shell Petroleum |
| Brunei LNG Sdn Bhd |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed generation monopolies anchored by Berakas Power Company Sdn Bhd and Brunei Shell Petroleum concentrate supply-side control, translating fuel security mandates into rigid tariff structures that resist competitive price erosion. The Department of Electrical Services enforces standardized cost-recovery frameworks that tether end-user rates to natural gas import parity rather than marginal generation costs.
Pricing Analysis
Warranty and long-term service agreements bundled with gas turbine procurement contracts from General Electric Company and Toshiba Corp inflate upfront capital costs while compressing lifecycle expenditure uncertainty. Three-tier pricing structure across premium efficiency upgrades, standard combined-cycle installations, and economy open-cycle retrofits reflects heat rate performance differentials under Department of Electrical Services regulations. Cost compression in the economy tier is intensifying because legacy open-cycle units face accelerated retirement timelines. Industrial offtakers in the Belait District exhibit lowest price sensitivity due to captive generation alternatives, while commercial rooftop solar adopters in Bandar Seri Begawan demonstrate highest responsiveness to feed-in tariff adjustments.
Supply Chain Analysis
Regional distribution centers in Singapore and Kuala Lumpur serve as primary logistics hubs for gas turbine components and solar PV modules entering Brunei's 575-megawatt system. Equipment sourcing draws from Japan, South Korea, and Germany for advanced combined-cycle technology, while solar hardware originates predominantly from Chinese manufacturing clusters. Single-source vulnerability concentrates in Brunei Shell Petroleum's monopoly over natural gas feedstock supply for thermal generators. Distribution runs through Berakas Power Company Sdn Bhd's centralized procurement channels for grid-scale infrastructure, with project developers managing direct vendor relationships for distributed renewable installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brunei's power sector occupies a compressed technology-transition phase where solar PV distributed generation displaces legacy gas-fired open-cycle capacity under tightening national energy efficiency regulations.
For Market Incumbents: Anticipate regulatory acceleration of heat rate standards that will strand inefficient open-cycle assets ahead of published depreciation schedules. Consolidate service capabilities around hybrid microgrid integration to capture industrial energy-as-a-service contracts from Brunei Shell Petroleum and downstream petrochemical operators. Secure backward integration into solar PV installation expertise through regional contractor partnerships before feed-in tariff negotiations conclude. For New Entrants and Emerging Players: The gap between premium combined-cycle efficiency upgrades and economy-tier open-cycle maintenance contracts creates entry space for specialized solar-plus-storage integrators. Target remote industrial facilities in Tutong District's dispersed agricultural processing zones where grid extension costs exceed hybrid microgrid deployment economics. Pursue direct power purchase agreement structures with petrochemical operators seeking carbon accounting advantages over traditional captive generation ownership. For Investors and Strategic Acquirers: Distressed-cycle entries favor operational turnaround specialists with ASEAN Power Grid interconnection expertise in Brunei-Muara District transmission infrastructure. Long-term viability hinges on positioning for cross-border export capacity utilization during off-peak domestic demand periods. Monitor feed-in tariff negotiation outcomes as inflection indicator for distributed renewable investment viability relative to centralized gas-fired capacity additions.| Strategic Initiative | Industry Significance |
|---|---|
| Gas Turbine Efficiency Upgrade | General Electric Company and Toshiba Corp compete for heat rate improvement contracts under Department of Electrical Services mandates. |
| Solar PV Portfolio Buildout | Commercial rooftops in Bandar Seri Begawan respond fastest to feed-in tariff frameworks due to concentrated ownership structures. |
| Hybrid Microgrid Deployment | Solar-plus-storage configurations reduce dependence on Berakas Power Company Sdn Bhd grid extensions across dispersed industrial zones. |
| ASEAN Power Grid Interconnection | Cross-border feasibility studies create long-term export opportunities for Brunei Shell Petroleum's surplus gas-fired capacity. |
| Energy-as-a-Service Transition | Third-party power purchase agreements transfer operational risk from petrochemical operators to independent project developers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis of Brunei's 575-megawatt power system. Primary interviews with utility planning officers at Berakas Power Company Sdn Bhd, IPP project developers, EPC contractors, and fuel supply specialists at Brunei Shell Petroleum were combined with Department of Electrical Services tariff documentation and ASEAN energy integration reports. Bottom-up capacity installation tracking and top-down macroeconomic demand modeling were triangulated to validate segmentation outputs.
Data-stream reconciliation across generation capacity databases, feed-in tariff negotiation records, and industrial load forecasts produced integrated projections across the analysis window. Segmentation dimensions modeled include service type, end user category, technology platform, and installation configuration. CAGRs were derived from regression analysis of historical capacity additions against policy target trajectories and industrial demand growth patterns. Natural gas supply security assumptions and renewable portfolio standard compliance timelines served as key forecast inputs.
Inputs from Department of Electrical Services and Brunei Shell Petroleum operational disclosures were available through the study window; gaps in prospective ASEAN Power Grid technical standards introduce uncertainty bands around cross-border capacity utilization assumptions. Forecasts reflect documented base-case assumptions regarding feed-in tariff implementation schedules and industrial load growth trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Steam Turbine MRO Market
Power
Wind Alarm Controller Market
Power
Kuwait Power Market
Power
Substation Automation System Market
Power
Modified Sine Wave Home Inverters Market
Power
Green UPS Market
Power
Power Shelf Market
Power
Residential Portable Inverter Generator Market
Power
Italy Power EPC Market
Power
North America Power Market
Power
High Voltage DC Power System Market
Power
Russian Federation Power Market
Power
Spain Power Market
Power
Solar Plants Controllers Market
Power
Asia-Pacific Package Substation Market
Power
Europe Submarine Power Cables Market