
 Global UPS Market | 2026-2036
Global UPS Market Size, Share, and Industry Trends Forecast 2026-2036
Global UPS Market Outlook
Market Dynamics
The capital-intensity gap between transformer-based legacy producers and silicon-carbide inverter specialists is collapsing. Schneider Electric leverages integrated power distribution software to sustain premium positioning across hyperscale data centers. Eaton Corporation anchors its North American footprint through service-contract density and captive channel control. Huawei competes on modular rack-density engineering, though its geographic reach faces regulatory constraints in several Western markets.
Product Architecture
An uninterruptible power supply is an electrical apparatus that provides emergency power through stored battery energy when mains input fails, with online double-conversion topology maintaining zero transfer time through continuous AC-to-DC-to-AC rectification. The primary commercial purpose is protecting critical loads from voltage sags, frequency variation, and total power loss in facilities where downtime carries severe operational or financial consequences. Online systems dominate the above 10kVA bracket where manufacturing and healthcare facilities require seamless continuity. Modular architectures are capturing share in IT and Telecom deployments because hot-swappable power modules reduce redundancy overhead and enable right-sized capacity scaling. Offline and line-interactive units occupy the sub-5kVA retail segment, where price sensitivity limits margin expansion despite high unit volumes.
Regulatory Environment
The EU Ecodesign Directive and F-Gas Regulation shape product design by mandating efficiency thresholds and restricting refrigerants in thermal management subsystems. The US Department of Energy and EPA ENERGY STAR program influence procurement specifications across federal and enterprise accounts. India's BIS certification and Central Electricity Authority grid codes drive compliance investments for imported three-phase equipment. Stakeholders must monitor semiconductor supply constraints for silicon-carbide MOSFETs and evaluate regional assembly incentives before committing capacity expansion plans.
Market Dynamics
Silicon-carbide MOSFET adoption is collapsing the cost-performance gap between transformer-based legacy architectures and high-frequency inverter designs, forcing incumbents to reconfigure R&D roadmaps and manufacturing footprints simultaneously.
Growth Catalysts
- AI Data Center Buildout:Hyperscale operators in the United States are commissioning three-phase online UPS systems at unprecedented density to support GPU cluster power requirements.
- EU Ecodesign Directive:Standby loss thresholds below 2% are mandating efficiency upgrades across installed base replacement cycles.
- Grid Instability:India's Central Electricity Authority reports voltage fluctuation events exceeding 15% deviation in 40% of industrial zones, driving enterprise investment in double-conversion topology.
Market Restraints
- Silicon-Carbide Supply Concentration:Wolfspeed and Infineon control 70% of substrate supply, creating input cost volatility for inverter manufacturers.
- Copper and Rare-Earth Magnet Pricing:Transformer core and permanent magnet costs fluctuate with commodity cycles, compressing margin predictability.
- Technical Limitation:Double-conversion topology imposes 6-8% energy loss penalty versus line-interactive designs, limiting appeal in carbon-constrained jurisdictions.
Strategic Opportunities
- Modular Rack-Density Engineering:Hot-swappable 50kW power modules enable right-sized capacity scaling without full system redundancy in IT deployments.
- Brazilian Manufacturing Incentives:Local assembly requirements under ANVISA and customs frameworks create white space for regional production hubs serving Latin American data center growth.
- Energy Storage Convergence:Lithium-titanate battery integration with UPS inverters extends runtime while reducing thermal management footprint.
Industry Challenges
- Power Electronics Talent Scarcity:Silicon-carbide inverter design and thermal engineering expertise concentrates in Germany, Japan, and the United States, creating recruitment bottlenecks.
- Legacy System Integration Complexity:Transformer-based infrastructure in healthcare and industrial facilities requires phased retrofit protocols that extend sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global UPS Market |
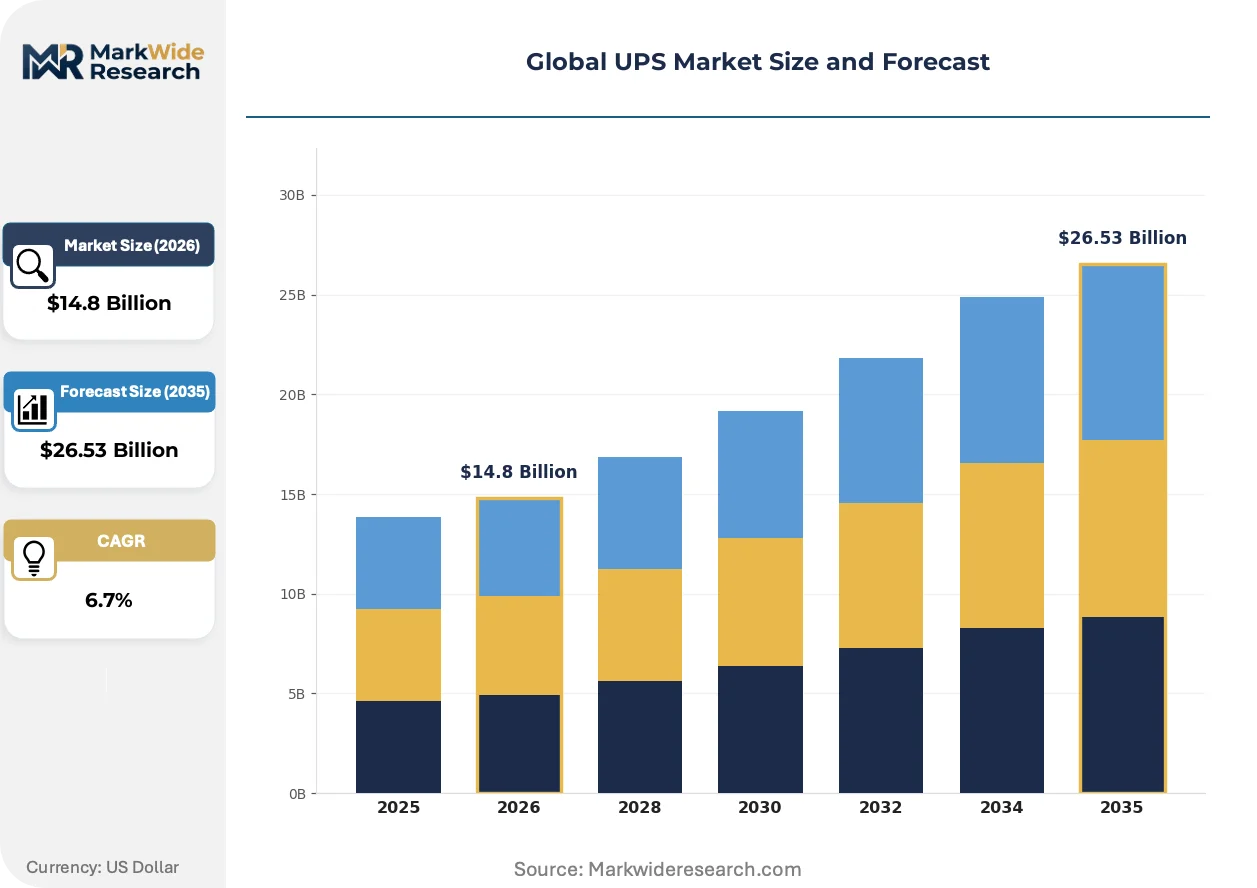
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Offline, Line-Interactive, Online, Modular Power Rating: Less than 1kVA, 1kVA-5kVA, 5kVA-10kVA, Above 10kVA End User: IT & Telecom, Healthcare, Manufacturing, Retail Installation: Rack Mounted, Wall Mounted, Floor Standing, Portable |
| Companies Covered | Schneider Electric, Eaton Corporation, Vertiv Group Corp, ABB Ltd, Huawei, Delta Electronics, Legrand, Emerson Electric Company, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global UPS Market Strategic Shifts
Power semiconductor architecture, regulatory efficiency mandates, and procurement model evolution are simultaneously restructuring how UPS systems are engineered, certified, and commercialized across end-use verticals.
Silicon-carbide power electronics is bifurcating the competitive landscape. The material enables switching frequencies above 100kHz, reducing magnetics volume by 40% versus silicon IGBT alternatives. Hyperscale data center operators are specifying SiC-based three-phase systems exclusively for new builds above 500kVA. This technology compression is eliminating the historical premium commanded by transformer-based legacy producers.
REACH and the EU F-Gas Regulation are reshaping thermal management subsystem design. The restrictions on hydrofluorocarbon refrigerants are forcing manufacturers to adopt phase-change materials and liquid cooling architectures. Medical and pharmaceutical cold chain applications in Germany and France are most affected, with procurement specifications now mandating natural refrigerant compatibility.
Enterprise buyers are unbundling hardware acquisition from service contracts. Large manufacturing facilities in India and Southeast Asia are separating capital expenditure for UPS hardware from 10-year maintenance agreements, creating channel conflict between direct OEM sales and authorized service partners. This pattern is most visible in automotive and semiconductor fabrication verticals where procurement teams optimize total cost of ownership through competitive tendering.
Global UPS Market Segmentation
UPS segmentation reveals how topology choice, power density, and deployment context determine procurement specifications across critical infrastructure verticals. Regulatory efficiency mandates and data center power density requirements are compressing legacy technology lifecycles while elevating modular architectures.
Product Type:
REACH and the EU F-Gas Regulation enforce standby loss thresholds that discriminate sharply between topologies, with double-conversion systems now mandatory for carbon-constrained enterprise accounts.
- Online:Continuous AC-to-DC-to-AC rectification eliminates transfer time entirely. Hyperscale data centers in the United States specify three-phase online systems exclusively for GPU cluster protection above 500kVA, driven by zero-tolerance downtime requirements for AI training workloads.
- Modular:Hot-swappable power modules enable right-sized capacity scaling without full system redundancy. IT and Telecom deployments in India favor 50kW rack-density units that reduce footprint while accommodating unpredictable load growth from cloud service expansion.
- Offline:Standby operation switches to battery only during mains failure, acceptable for non-critical loads. Sub-5kVA retail applications in price-sensitive markets.
- Line-Interactive:Voltage regulation through tap-changing transformer without full conversion. Small office and home office segments where 6-8% efficiency penalty of online topology is prohibitive.
Online systems handle the majority of throughput; Modular is expanding most quickly on share as data center operators prioritize scalability.
Power Rating:
Capital deployment thresholds separate consumer procurement from enterprise capital expenditure cycles, with copper and magnet costs driving nonlinear pricing across brackets.
- Above 10kVA:Three-phase industrial systems with transformer-based or silicon-carbide inverter architectures. Manufacturing facilities in Germany and healthcare campuses in France require seamless continuity for surgical robotics and pharmaceutical cold chain, with BIS certification mandatory for imported units serving Indian industrial zones.
- 5kVA-10kVA:Mid-tier commercial systems bridging small business and light industrial applications. Regional hospital networks in the United States deploy this bracket for imaging equipment protection where line-interactive designs prove inadequate.
- 1kVA-5kVA:Single-phase units dominating small office and retail point-of-sale protection. Volume concentration in Southeast Asian markets with severe voltage fluctuation exposure.
- Less than 1kVA:Desktop and consumer electronics protection with minimal runtime. Commoditized segment where lithium-ion substitution is eroding traditional lead-acid economics.
Above 10kVA commands the dominant revenue share; 5kVA-10kVA is climbing the fastest as edge computing deployments proliferate.
End User:
Application-specific runtime requirements and certification standards fragment demand across verticals with divergent risk tolerance for power interruption.
- IT & Telecom:Data center and network infrastructure requiring 99.999% availability. Hyperscale operators in the United States and cloud service providers in India drive specification for lithium-titanate battery integration to extend runtime without thermal management expansion.
- Healthcare:Life-safety systems and diagnostic imaging with regulatory-mandated backup duration. EU MDR and FDA device regulations enforce qualification protocols that extend sales cycles for new installations.
- Manufacturing:Process continuity for semiconductor fabrication and automotive assembly. Voltage sag tolerance varies sharply by automation density.
- Retail:Point-of-sale and inventory management systems with cost-optimized runtime requirements. Franchise networks prioritize standardized specifications across distributed locations.
IT & Telecom absorbs the largest hardware volume; Healthcare shows the steepest specification upgrade trajectory as digital health infrastructure expands.
Installation:
Physical deployment constraints in existing facilities versus greenfield construction determine form factor selection and service access requirements.
- Rack Mounted:Standard 19-inch enclosure integration for data center and network closet deployments. Density optimization for colocation facilities in Singapore and Frankfurt.
- Floor Standing:Industrial and healthcare applications requiring isolation transformers and extended battery cabinets. Manufacturing plants in Japan specify this configuration for heavy electrical loads.
- Wall Mounted:Space-constrained retail and small office environments. Common in European commercial buildings with premium floor space economics.
- Portable:Temporary protection and field service applications. Event infrastructure and construction sites with mobile power requirements.
Floor Standing retains the largest installed base; Rack Mounted is gaining share fastest as data center construction dominates capital allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in India exhibit the sharpest price elasticity, squeezing margins on three-phase systems, while hyperscale operators in the United States absorb premium pricing for silicon-carbide architectures without volume contraction.
United States
Hyperscale data center operators commission three-phase online UPS systems at unprecedented density to support GPU cluster power requirements. The EPA ENERGY STAR program and FERC grid reliability standards shape procurement specifications across federal and enterprise accounts. Northern Virginia's Data Center Alley concentrates new build activity, with operators specifying lithium-titanate battery integration to extend runtime.
Germany
Industrial automation and pharmaceutical cold chain applications drive specification for seamless continuity systems. The EU Ecodesign Directive mandates standby loss thresholds below 2%, forcing efficiency upgrades across installed base replacement cycles. Bavaria's manufacturing corridor anchors demand, with automotive and semiconductor fabrication facilities requiring voltage sag tolerance for robotics-intensive production lines.
India
Grid instability from the Central Electricity Authority reports voltage fluctuation events exceeding 15% deviation in 40% of industrial zones, driving enterprise investment in double-conversion topology. BIS certification and CEA grid codes drive compliance investments for imported three-phase equipment. Maharashtra and Karnataka's technology corridors concentrate cloud service provider expansion, with unpredictable load growth favoring modular 50kW rack-density units.
China
Domestic data center buildout and semiconductor fabrication facility expansion sustain demand for above-500kVA systems. MIIT efficiency standards and GB certification frameworks regulate product design and market entry. The Yangtze River Delta cluster, spanning Shanghai and Jiangsu Province, concentrates hyperscale operator activity with specifications favoring high-frequency inverter designs.
Brazil
Latin American data center growth and manufacturing reshoring create white space for regional production hubs. ANVISA local assembly requirements and customs frameworks incentivize captive manufacturing capacity. São Paulo's industrial corridor anchors demand, with automotive assembly and electronics manufacturing requiring process continuity protection.
Global UPS Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the capital-intensity gap between transformer-based legacy producers and silicon-carbide inverter specialists collapsing. The structure rewards players controlling captive channels and service contract density alongside hardware manufacturing. Two strategic archetypes dominate: integrated power distribution software providers competing on system-level optimization, and modular rack-density engineering specialists competing on scalability. M&A activity concentrates on silicon-carbide supply chain control, while capacity expansion gravitates toward regional assembly hubs with local content requirements.
Among the integrated tier, Schneider Electric and Eaton Corporation exemplify divergent geographic positioning strategies, with the former leveraging European software integration capabilities and the latter anchoring North American service density. Huawei occupies a position within the modular engineering archetype, though regulatory constraints limit its addressable market in several Western jurisdictions. Vertiv Group Corp represents the data center infrastructure specialization vector, with its name signaling vertical focus on critical power and cooling systems.
| Leading Market Players |
|---|
| Schneider Electric |
| Eaton Corporation |
| Vertiv Group Corp |
| ABB Ltd |
| Huawei |
| Delta Electronics |
| Legrand |
| Emerson Electric Company |
| Mitsubishi Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
Ninety-day lead times for silicon-carbide substrates compress pricing power at the module level while extending service-contract premiums for integrated providers. This inventory exposure concentrates margin defense in aftermarket channels rather than hardware shipment economics.
Pricing Analysis
Service revenue tiers spanning ten-year maintenance agreements and battery replacement contracts now drive lifetime value capture. Three-tier pricing structure across premium silicon-carbide systems, standard IGBT architectures, and economy transformer-based units reflects certification grade and thermal management sophistication. Cost compression in the sub-50kVA bracket intensifies as Indian and Southeast Asian buyers unbundle hardware from service agreements. Enterprise procurement teams in hyperscale data centers exhibit lowest price sensitivity, absorbing premium positioning for lithium-titanate integration and modular hot-swap capability.
Supply Chain Analysis
China and South Korea anchor battery cell fabrication while Germany and Japan concentrate silicon-carbide wafer and inverter design expertise. The assembly network draws from copper winding capacity in Mexico, transformer core steel from India, and rare-earth magnet supply from domestic Chinese processors. Single-source vulnerability in Wolfspeed and Infineon substrate allocation creates input cost volatility for high-frequency inverter manufacturers. Distribution runs through authorized service partners with captive installation crews, bypassing traditional electrical wholesale channels for enterprise accounts above 500kVA.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UPS market constitutes a high-growth infrastructure disruption as silicon-carbide power electronics collapse the historical premium commanded by transformer-based legacy architectures. The EU Ecodesign Directive's standby loss thresholds below 2% accelerate replacement cycles across carbon-constrained enterprise accounts.
For Market Incumbents: Secure captive silicon-carbide supply through long-term offtake agreements with substrate specialists before capacity allocation tightens further. Expand modular rack-density engineering teams in India and Germany to capture cloud service provider procurement cycles. Defend margin position by embedding power distribution software licensing into hardware contracts, creating switching costs against pure-play inverter competitors. For New Entrants and Emerging Players: Lead with lithium-titanate battery integration as a thermal management differentiator for healthcare and pharmaceutical cold chain verticals in France and Germany. Target Brazilian manufacturing incentives under ANVISA frameworks to establish regional assembly serving Latin American data center buildout. Build channel presence through direct service contracting rather than competing for hardware-only tenders where incumbents hold cost advantages. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because silicon-carbide inverter design talent concentrates in three geographic clusters while enterprise buyers demand integrated software-hardware-service bundles. Acquisition targets should exhibit captive channel control in North American service markets or modular engineering capabilities for hyperscale density requirements. Monitor Infineon and Wolfspeed capacity expansion announcements as the signal indicating when supply constraints will ease and hardware margin compression will accelerate.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Carbide Supply Agreement | Locks substrate allocation from Wolfspeed or Infineon before competitor contracting cycles. |
| Modular Rack-Density Engineering | Enables 50kW hot-swap configurations for cloud service provider expansion in India. |
| Regional Assembly Hub Establishment | Captures ANVISA incentives serving Brazilian automotive and electronics manufacturing demand. |
| Lithium-Titanate Battery Integration | Extends runtime without thermal footprint expansion for EU pharmaceutical cold chain compliance. |
| Power Distribution Software Licensing | Creates recurring revenue attachment and switching costs against hardware-only competitors. |
Study Parameters
The analysis maps online double-conversion, modular, line-interactive, and offline topologies, each validated through data center infrastructure directors, electrical contracting procurement leads, and aftermarket service managers. Primary fieldwork with plant engineers at semiconductor fabrication facilities and hospital biomedical equipment heads combined with secondary validation through EPA ENERGY STAR certification databases, BIS product registration filings, and EU Ecodesign Directive compliance registries. Bottom-up unit economics triangulated against top-down hyperscaler capex disclosure patterns.
Consistency checks against FERC grid reliability investment reports and Central Electricity Authority voltage fluctuation data validated capacity deployment assumptions across the projection horizon. Segmentation modeling incorporated power rating tiers, installation form factors, and regional regulatory cluster variations. CAGRs derived from installed base replacement cycle analysis and greenfield data center pipeline tracking, with silicon-carbide adoption curves and lithium-ion battery cost trajectories as primary demand elasticity inputs.
Forecasts assume regulatory continuity in EU Ecodesign and F-Gas frameworks, EPA ENERGY STAR procurement specifications, and Indian BIS certification requirements; material policy shifts would require re-modeling. Semiconductor supply constraints, copper commodity cycles, and grid instability severity represent primary revision triggers. Recalibration cycles align with material shifts in hyperscale data center commissioning schedules and silicon-carbide substrate capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Denmark Power Market
Power
Static Synchronous Compensator (STATCOM) Market
Power
North America Power Market
Power
Japan Power Market
Power
Mexico Power EPC Market
Power
Marine Thermal Fluid Heaters Market
Power
Controllable Shunt Reactor for UHV Market
Power
Europe Frequency Converter Market
Power
Japan Uninterrupted Power Supply (UPS) Market
Power
Brunei Power Market
Power
Malaysia Power EPC Market
Power
Nigeria Power Market
Power
Power Rental Market
Power
Direct Current Power System Market
Power
Resonant Power Converters Market
Power
Compact Substation Market