
 Hydrogen Boilers Market | 2026-2036
Hydrogen Boilers Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Boilers Market Insights
The EU Green Deal is broadening the addressable market for hydrogen-compatible heating systems across European member states. Worcester Bosch leverages its extensive installer network and R&D pipeline to sustain technology leadership in blended-hydrogen-ready units. BDR Thermea Group anchors its competitive position through geographic dominance across Northern European markets. Viessmann differentiates via manufacturing scale and in-house production of heat exchanger components optimized for hydrogen combustion profiles.
A hydrogen boiler is a space and water heating appliance engineered to combust hydrogen gas or hydrogen-natural gas blends, typically achieving flame temperatures exceeding conventional methane systems while producing water vapor as the primary exhaust constituent. These systems employ modified burners, specialized heat exchangers, and enhanced safety controls to manage hydrogen's higher flame speed and lower ignition energy relative to natural gas. The product type dimension shows combi and system configurations capturing the dominant share of new build installations, while retrofit applications concentrate in floor-standing units where existing infrastructure accommodates physical footprints. The end user split reveals residential segments leading absolute volume, with industrial buyers commanding premium pricing for high-capacity continuous-duty systems.
The EU F-Gas Regulation and CE marking requirements shape product certification pathways and market access timelines for hydrogen boiler manufacturers. Germany's KBA and national building codes, alongside the United Kingdom's hydrogen village trials and Ofgem oversight, create a multi-layered compliance environment that favors pre-certified suppliers. ECHA's evolving substance restrictions further constrain material selections for seals and gaskets in hydrogen service. Stakeholders must monitor hydrogen grid injection standards and regional blending percentage commitments to align product roadmaps with infrastructure deployment cadence.
Market Dynamics
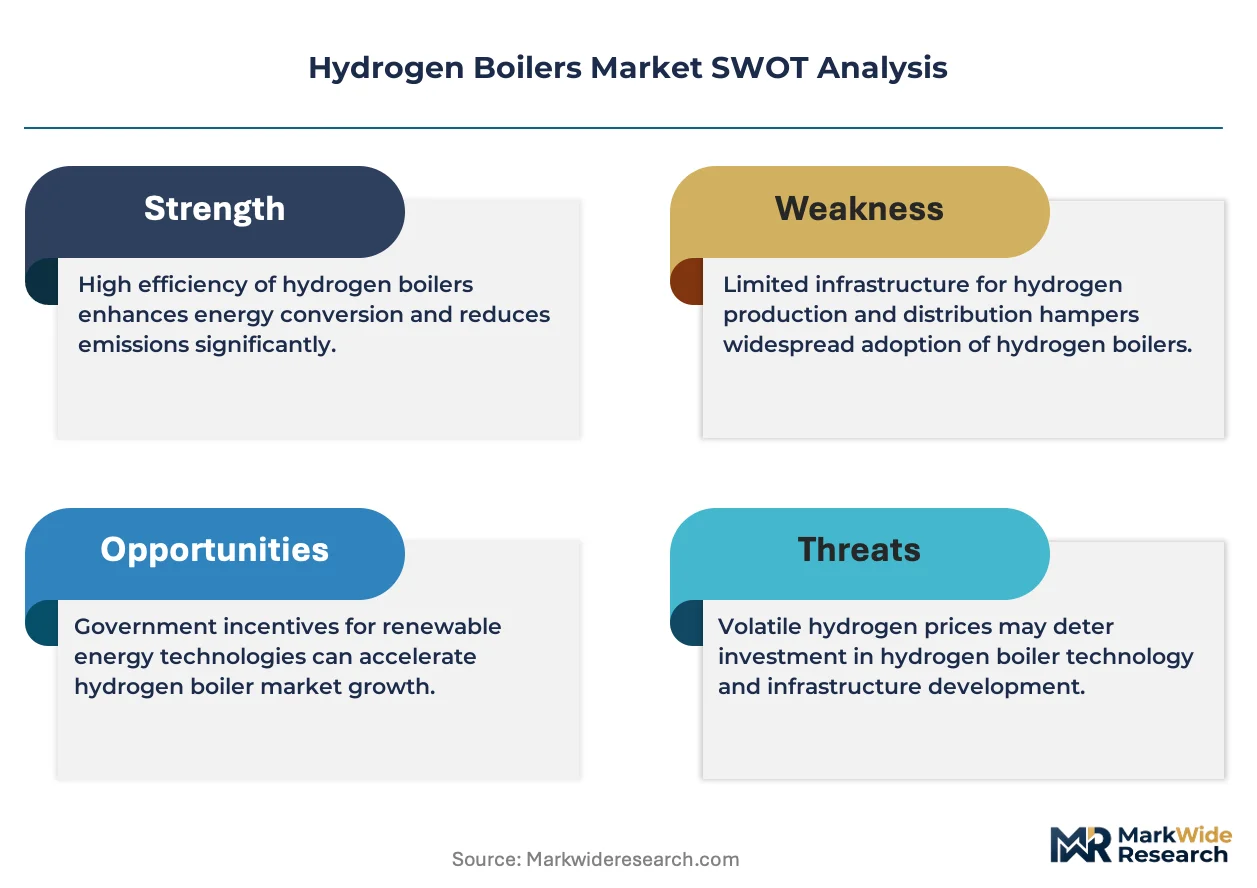
The hydrogen boiler sector faces a structural tension between infrastructure readiness and appliance deployment timelines, with hydrogen grid injection standards lagging behind manufacturer certification cycles across Northern Europe.
Growth Catalysts
- EU Green Deal building renovation mandates:Member states must decarbonize heating stock, creating replacement demand for hydrogen-ready systems in residential retrofits.
- Hydrogen blending trials in the Netherlands:Pilot programs validating 20% hydrogen injection into existing gas networks de-risk consumer adoption.
- Heat pump installation constraints:Older building envelopes and space limitations in urban German housing stock favor hydrogen boilers as drop-in replacements.
Market Restraints
- Electrolyzer capacity bottlenecks:Green hydrogen production deficits in Denmark and Sweden constrain fuel availability for heating applications.
- Copper and nickel price volatility:Heat exchanger material costs fluctuate with battery sector competition for the same mined inputs.
- Natural gas price collapse risk:Persistent LNG oversupply in European storage facilities undermines the economic case for hydrogen switching.
Strategic Opportunities
- Industrial process heat in Belgium:Chemical and food processing plants seek continuous-duty hydrogen steam systems beyond residential peak-load patterns.
- UK hydrogen village commercialization:Ofgem-sanctioned trials in Redcar and Whitby create reference sites for scaled deployment.
- AI-enabled predictive maintenance:Sensor-integrated boilers offering remote diagnostics command service contract premiums from housing associations.
Industry Challenges
- Hydrogen-safe seal certification delays:ECHA material compatibility assessments for elastomer gaskets extend product validation timelines.
- Installer retraining gaps:Gas Safe Register and DVGW certification pathways have not scaled to match manufacturer production ramps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Boilers Market |
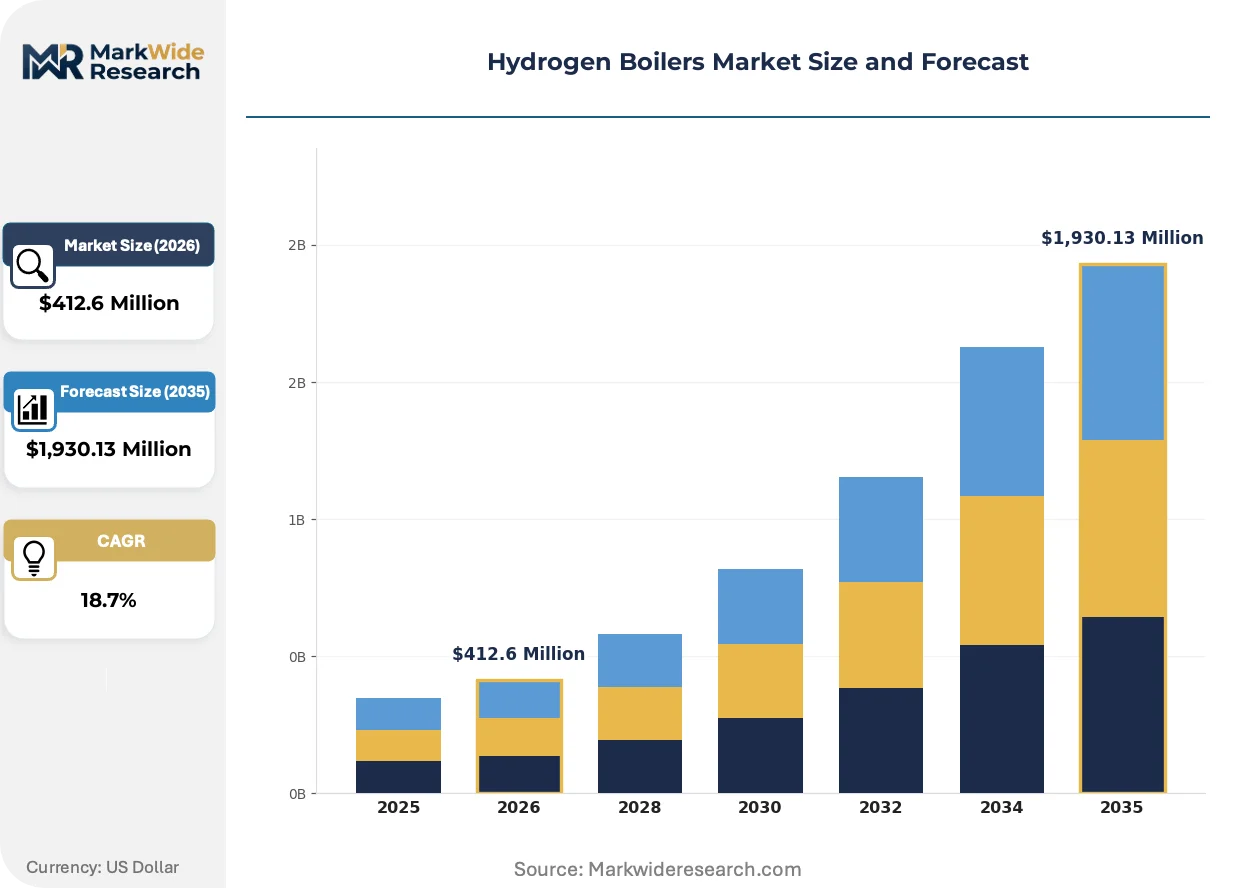
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,930.13 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Floor-Standing, Combi, System End User: Residential, Industrial, Commercial, Municipal Installation Type: New Build, Retrofit, Replacement, Upgrade Fuel Type: Pure Hydrogen, Hydrogen Blends, Biomass, Others |
| Companies Covered | Worcester Bosch, Bosch, BDR Thermea Group, Viessmann, Giacomini, Babcock & Wilcox, Fulton Boiler Works, Jericho Energy Ventures, Vaillant Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Boilers Market Trends and Innovations
Product development trajectories center on combustion optimization and system integration, with manufacturers racing to lock in standards before hydrogen grid specifications crystallize.
Condensing heat exchanger architectures with corrosion-resistant stainless steel cores are expanding into high-hydrogen blend applications. Residential developers in the Netherlands specify these units for new-build estates awaiting grid conversion. The technology is expanding into premium retrofit segments previously served by conventional natural gas systems.
The EU F-Gas Regulation phase-down schedule is accelerating refrigerant-based heat pump displacement in favor of combustion alternatives. Boiler manufacturers are repositioning hydrogen-ready lines to capture subsidy flows previously directed at electric heating. Northern European markets with district heating limitations show strongest response rates.
Housing associations are consolidating procurement through framework agreements rather than project-by-project tendering. This concentrates purchasing power among five to six major social landlords in the United Kingdom. Germany's municipal utilities respond with bundled hydrogen supply and appliance lease arrangements.
Hydrogen Boilers Market Segmentation
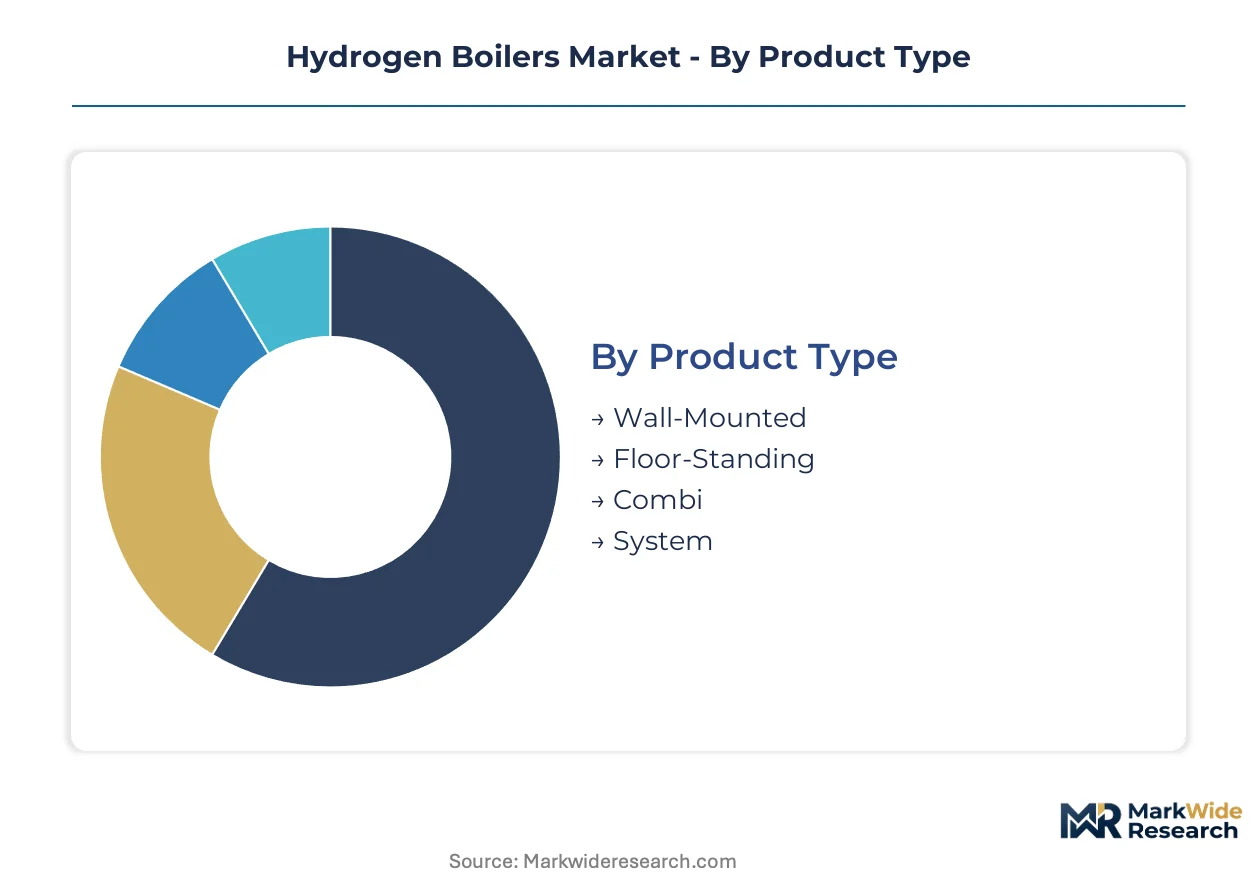
Hydrogen boiler procurement patterns diverge sharply across building typologies and fuel availability, forcing manufacturers to maintain parallel certification tracks for blended and pure hydrogen specifications. Segmentation discipline separates volume-driven residential retrofits from premium industrial continuous-duty systems with divergent margin structures.
Product Type:
Capital intensity peaks in floor-standing configurations requiring reinforced frames and industrial-grade heat exchangers, while wall-mounted variants minimize installation labor and structural modifications.
- Wall-Mounted:Compact units designed for space-constrained residential applications, typically rated below 35kW. Demand concentrates in urban German apartment stock where building envelope limitations preclude heat pump retrofit. Installer preference for standardized mounting brackets accelerates replacement cycles.
- Floor-Standing:Heavy-duty systems with cast-iron or steel heat exchanger blocks accommodating outputs exceeding 100kW. Industrial buyers in Belgian chemical processing and Dutch food manufacturing specify these for steam generation applications requiring 24-hour duty cycles.
- Combi:Integrated domestic hot water and space heating units dominating new-build specifications across Netherlands housing estates.
- System:Heat-only boilers paired with external cylinders, preferred in United Kingdom retrofit scenarios with existing hot water storage infrastructure.
Floor-standing units absorb the bulk of installed capacity in industrial settings; wall-mounted configurations are expanding most quickly through social housing framework agreements.
End User:
Customer-type segmentation reveals divergent procurement rhythms, with municipal buyers operating on electoral budget cycles and industrial purchasers locking in multi-year hydrogen supply contracts.
- Residential:Single-family and multi-unit dwellings account for absolute volume leadership, driven by EU Green Deal renovation mandates and national boiler replacement subsidies. United Kingdom hydrogen village trials in Redcar and Whitby validate consumer acceptance of pure hydrogen combustion in domestic settings.
- Industrial:Chemical, pharmaceutical, and food processing facilities command premium pricing for high-capacity systems with redundant safety architectures. Belgian process heat applications favor hydrogen steam boilers over electrification where continuous thermal output is non-negotiable.
- Commercial:Hotels, hospitals, and office complexes with centralized plant rooms specifying mid-range outputs.
- Municipal:District heating operators and public building portfolios procuring through aggregated tender processes.
Residential segments anchor absolute shipment volumes; industrial end users generate the steepest margin expansion trajectory through specification premiums.
Installation Type:
Application-based segmentation tracks infrastructure readiness, with new-build installations synchronizing to hydrogen grid deployment timelines while retrofits exploit existing natural gas piping with blending compatibility.
- New Build:Installations in construction projects designed for pure hydrogen from commissioning, prevalent in Netherlands new housing estates with dedicated hydrogen distribution networks. Developers specify hydrogen-ready appliances to future-proof against regulatory tightening.
- Retrofit:Conversions of existing natural gas systems to hydrogen blends or pure hydrogen, concentrating in German urban housing stock with aging boiler fleets. Physical footprint constraints and flue compatibility determine technical feasibility.
- Replacement:Like-for-like swaps at end-of-life, the dominant pathway in United Kingdom social housing portfolios.
- Upgrade:Premature replacements driven by efficiency regulations or subsidy windows.
Retrofit applications command the largest installed base; new-build specifications are climbing the fastest as hydrogen grid infrastructure crystallizes.
Fuel Type:
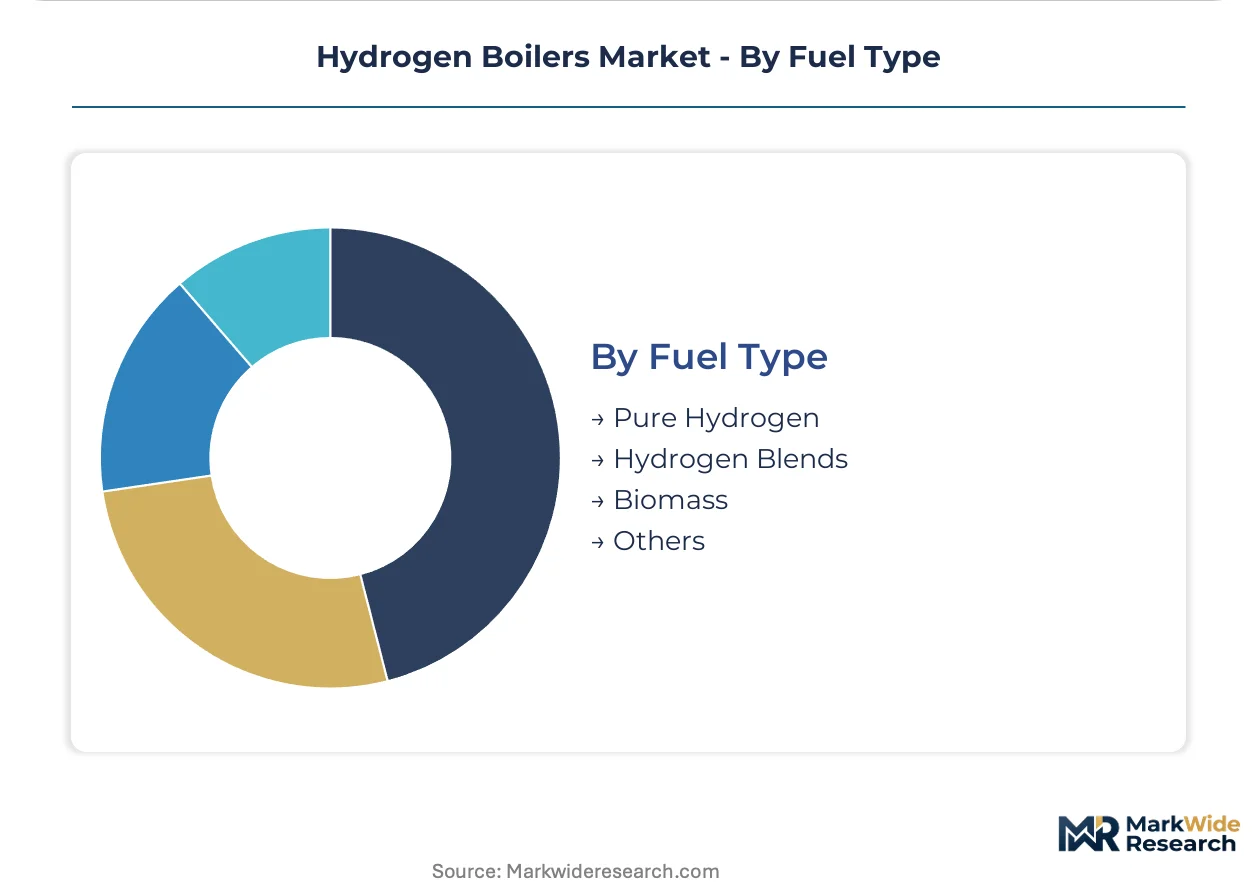
Supply-concentration dynamics favor hydrogen blend specifications where electrolyzer capacity bottlenecks constrain pure hydrogen availability in Denmark and Sweden.
- Pure Hydrogen:100% H2 combustion systems requiring specialized burners, flame sensors, and modified gas valves to manage higher flame speeds. United Kingdom Ofgem-sanctioned trials and Netherlands pilot villages validate operational safety profiles ahead of scaled deployment.
- Hydrogen Blends:Appliances engineered for 20-30% hydrogen injection into existing natural gas networks, the near-term standard across Northern European markets awaiting electrolyzer capacity expansion. Dutch grid operators lead blending mandate implementation.
- Biomass:Hybrid combustion systems for rural installations with limited hydrogen infrastructure access.
- Others:Experimental fuel combinations including synthetic methane and ammonia cracking derivatives.
Hydrogen blends dominate current procurement volumes; pure hydrogen systems are gaining share fastest as production capacity scales and grid conversion timelines accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands' Randstad corridor anchors European hydrogen boiler deployment, with Rotterdam's port hydrogen hub feeding pilot villages in Groningen and Flevoland. Infrastructure trials here outpace regulatory certification cycles elsewhere.
Germany
Residential retrofits in Berlin and Hamburg drive volume, as aging natural gas fleets face KBA-enforced efficiency deadlines. The EU Green Deal building renovation mandates accelerate replacement cycles in multi-unit housing stock. Bavaria's municipal utilities bundle hydrogen supply with appliance leases to de-risk consumer switching.
United Kingdom
Hydrogen village trials in Redcar and Whitby validate pure hydrogen combustion for Ofgem-sanctioned commercialization. Social housing associations consolidate procurement through framework agreements, concentrating purchasing power among five major landlords. The Midlands manufacturing belt supplies modified burners for these pilot programs.
Netherlands
Grid operators mandate 20% hydrogen blending in existing networks, creating immediate demand for dual-fuel appliances. New-build estates in Eindhoven specify hydrogen-ready units awaiting dedicated distribution infrastructure. Dutch building codes now require future-proof heating systems in all residential construction permits.
Belgium
Industrial process heat applications in Antwerp's chemical corridor favor hydrogen steam boilers over electrification for continuous-duty cycles. Flemish regional subsidies cover conversion costs for pharmaceutical manufacturers seeking carbon intensity reductions. Port of Antwerp-Bruges hydrogen import terminals secure fuel supply for these high-capacity installations.
Sweden
Electrolyzer capacity bottlenecks constrain pure hydrogen availability, delaying residential deployment beyond pilot phases. Stockholm's district heating operators test hydrogen-compatible peak-load boilers as backup to geothermal baseload. National building efficiency standards exclude natural gas in new construction from 2025, forcing technology selection.
Hydrogen Boilers Market Competitive Landscape
The competitive structure tilts toward diversified heating equipment conglomerates with established installer networks. Market concentration remains moderate, with no single supplier commanding dominant share across all national certification tracks. Three archetypes define positioning: legacy boiler manufacturers pivoting to hydrogen compatibility, industrial steam specialists entering residential markets, and energy utilities integrating downstream into appliance supply. Capacity expansion and strategic partnerships with hydrogen infrastructure developers represent the dominant competitive moves.
Among German-based heating conglomerates, Worcester Bosch, BDR Thermea Group, and Viessmann occupy positions reflecting divergent strategic bets. Worcester Bosch exemplifies the installer-network-dependent archetype, leveraging service relationships built over decades of natural gas dominance. BDR Thermea Group represents geographic specialization, with concentration in Northern European markets where hydrogen grid timelines are most advanced. Viessmann anchors the vertically integrated manufacturing tier, with captive production of heat exchanger components optimized for hydrogen combustion profiles.
| Leading Market Players |
|---|
| Worcester Bosch |
| Bosch |
| BDR Thermea Group |
| Viessmann |
| Giacomini |
| Babcock & Wilcox |
| Fulton Boiler Works |
| Jericho Energy Ventures |
| Vaillant Group |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between hydrogen-ready and hydrogen-blend-ready units manifests in both pricing stratification and supply chain configurations across Northern European markets. Premium pure-hydrogen systems command value-based pricing tied to Ofgem-sanctioned village trial outcomes, while blend-compatible units compete on volume through municipal utility lease programs in Germany and the Netherlands.
Pricing Analysis
Outcome-based pricing anchors hydrogen boiler valuation, with premiums scaling to demonstrated fuel-switching uptime guarantees in United Kingdom social housing frameworks. Price differentiation separates CE-marked pure-hydrogen systems from blend-ready units, with certification tier and installer network density driving spreads. Cost compression in wall-mounted residential segments intensifies as heat pump displacement subsidies redirect toward combustion alternatives. Municipal buyers in the Netherlands exhibit lowest price sensitivity through bundled hydrogen supply contracts, while United Kingdom housing associations face acute budget constraints under framework agreement consolidation.
Supply Chain Analysis
Direct-to-installer channels handle volume demand from German municipal utilities and United Kingdom social housing aggregators, bypassing traditional distribution tiers. Manufacturing concentration centers on Germany, the Netherlands, and Italy, with heat exchanger component production anchored in Viessmann's captive German facilities. Stainless steel and corrosion-resistant alloy inputs draw from German and Swedish metallurgical suppliers, with elastomer gasket materials sourced through ECHA-regulated European vendors. Single-source vulnerability in hydrogen-safe seal certification creates bottleneck risk as ECHA material compatibility assessments extend validation timelines. Distribution runs through certified installer networks rather than wholesale plumbing merchants, locking in Gas Safe Register and DVGW credential dependencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrogen boiler market sits in a technology-transition phase where pure-hydrogen combustion systems displace legacy natural gas infrastructure ahead of grid conversion timelines. Hydrogen-ready appliance deployment now outpaces electrolyzer capacity buildout, creating asynchronous adoption curves across Northern European markets.
For Market Incumbents: Anticipate margin compression in blend-ready residential segments as municipal utility bundling programs concentrate purchasing power. Defensive consolidation should prioritize captive heat exchanger production and DVGW-certified installer network expansion to lock out modular competitors. Heat pump subsidy redirection toward hydrogen combustion creates volume opportunity but threatens pricing power in standardized wall-mounted units.
For New Entrants and Emerging Players: Begin with industrial process heat applications in Belgium's Antwerp chemical corridor, where continuous-duty steam requirements and carbon intensity mandates create specification premiums beyond residential commoditization. Belgian pharmaceutical manufacturers and Dutch food processors present the most penetrable white-space, with hydrogen supply contracts already secured through Port of Antwerp-Bruges import terminals. Go-to-market positioning should emphasize redundant safety architectures and 24-hour duty cycle guarantees rather than residential efficiency metrics.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated heat exchanger specialists given electrolyzer capacity scaling and hydrogen village commercialization timelines. Long-term viability across the analysis window favors manufacturers with in-house metallurgical capabilities and pre-certified pure-hydrogen product lines ahead of Ofgem grid conversion approvals. The signal to watch is United Kingdom hydrogen village trial expansion beyond Redcar and Whitby into additional Ofgem-sanctioned sites, indicating demand inflection for 100% H2 systems.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Pre-certification for pure-hydrogen specifications ahead of ECHA seal compatibility rulings secures market access timing. |
| Installer Network Certification Scale-Up | Gas Safe Register and DVGW credential expansion matches manufacturer production ramps to avoid deployment bottlenecks. |
| Backward Integration into Heat Exchangers | Captive stainless steel component production insulates margin from battery sector competition for nickel and copper inputs. |
| Hydrogen Supply Bundling Arrangements | Municipal utility lease programs in Bavaria and the Netherlands de-risk consumer switching and lock in replacement cycles. |
| Industrial Process Heat Partnership | Belgian chemical and pharmaceutical sector alliances capture premium pricing for continuous-duty steam generation systems. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, with primary interviews conducted across heating equipment manufacturers, Gas Safe Register certified installers, municipal utility procurement officers, and ECHA regulatory affairs specialists. Bottom-up shipment data from Netherlands grid operators and United Kingdom housing association framework agreements were triangulated against top-down electrolyzer capacity buildout projections from IEA and national hydrogen strategy documents. Secondary validation drew from EU F-Gas Regulation implementation reports, KBA building code amendments, and Ofgem hydrogen village trial disclosures.
Granularity-level modeling operated at product type, end user, installation type, and fuel type dimensions, with geographic splits calibrated to national hydrogen grid injection standards and blending mandate timelines. CAGRs were derived from replacement cycle analysis of aging natural gas boiler fleets against electrolyzer capacity deployment curves across the projection horizon. Industry-specific forecast inputs incorporated EU Green Deal building renovation mandate compliance schedules and ECHA material restriction evolution for hydrogen service elastomers.
Underlying measurement precision varies by segment; industrial process heat applications carry tighter precision than residential retrofit projections given concentrated buyer visibility and long-term hydrogen supply contracting. Forecasts reflect assumptions around electrolyzer capacity scaling, hydrogen grid conversion sequencing, and ECHA certification timeline resolution that warrant periodic stress-testing of base assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Watertube Boilers Market
Boilers
Europe Residential Boiler Market
Boilers
Commercial Boiler Market
Boilers
Power Boiler Market
Boilers
US Commercial Boiler Market
Boilers
Industrial Boiler MRO Market
Boilers
Boiler Control Market
Boilers
Gas Condensing Boiler Market
Boilers
Boiler Combustion Chamber Market
Boilers
Oil-Fired Boiler Market
Boilers
Global Package Boilers Market
Boilers
Circulating Fluid Bed Boilers Market
Boilers
Superheater Tubes Market
Boilers
Middle East and Africa Power Plant Boiler Market
Boilers
Micro Combined Heat and Power (CHP) Market
Boilers
Asia-Pacific Combined Heat and Power Market