
 North America Aluminium Cans Market | 2026-2036
North America Aluminium Cans Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aluminium Cans Market Intelligence
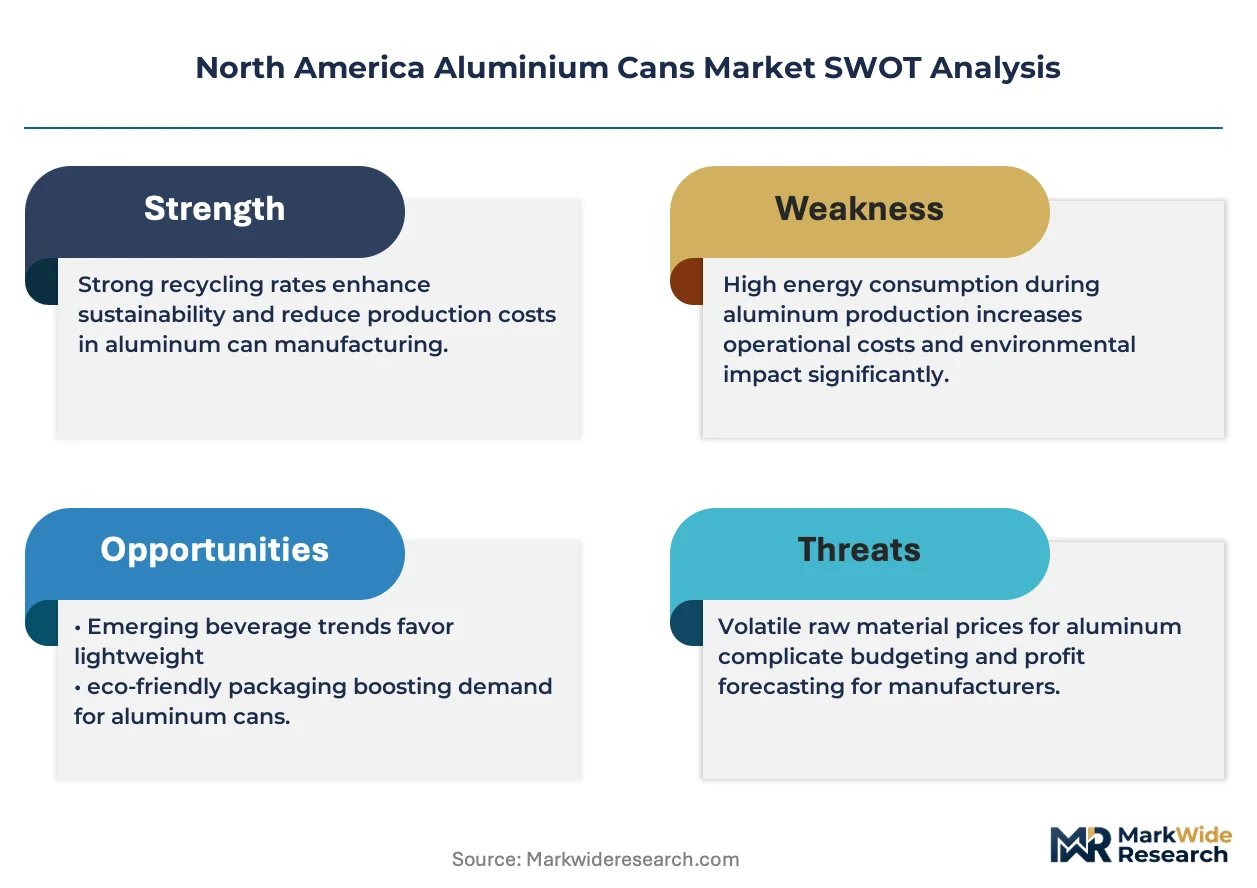
ASTM B209 qualification cycles for aluminium sheet stock is unwinding the competitive field, as mills and can makers must recertify against tighter gauge tolerances and surface finish standards. Ball Corporation leverages its captive metal supply and integrated beverage packaging network to sustain volume leadership across the United States. Crown Holdings Inc. anchors its position through deep relationships with multinational beverage brands, while Novelis competes as the continent's largest aluminium recycler, feeding closed-loop can sheet back into production.
North America aluminium cans are cylindrical single-serve containers formed from 3104-H19 or 3004-H19 aluminium alloy sheet, typically wall-ironed and drawn to achieve wall thickness below 0.004 inches with a lightweight two-piece construction. These containers serve primarily as sterile, opaque, infinitely recyclable barriers for carbonated and non-carbonated beverages, preserving shelf stability while supporting high-speed filling lines. The beverage end user segment dominates absolute volume, though specialty cans—including slim profiles and resealable formats—are capturing premium positioning and margin pools as craft and functional drink portfolios expand. Standard 355 ml and 500 ml capacity tiers remain the baseline for mass-market production, while smaller 250 ml formats are gaining traction in portion-controlled and premium sparkling water applications.
The U.S. EPA and Environment and Climate Change Canada jointly influence recyclability mandates and extended producer responsibility frameworks that dictate minimum recycled content thresholds and end-of-life collection infrastructure. OSHA and state-level environmental agencies enforce workplace and emissions standards at smelting and coating facilities, directly affecting plant location decisions and capital deployment timelines. Stakeholders must monitor evolving alloy purity requirements and cross-border harmonization of recycling certification standards to secure long-term supply agreements.
Market Dynamics
ASTM B209 recertification cycles are compressing supplier margins as mills absorb testing costs for tighter gauge tolerances and surface finish standards, while craft beverage producers accelerate order volumes for specialized can formats.
Growth Catalysts
- Extended Producer Responsibility Frameworks:EPA recycled content mandates under evolving state-level EPR programs are forcing beverage brands to source higher-recycled-content aluminium, locking in demand for closed-loop sheet suppliers.
- Craft Beverage Expansion:Small-batch producers across the southeastern United States are commissioning dedicated canning lines, creating pull-through for 250 ml slim and resealable specialty formats.
- 3104-H19 Alloy Optimization:Wall-ironing process refinements are thinning can walls below 0.004 inches while maintaining burst strength, reducing metal unit costs per container.
Market Restraints
- Primary Aluminium Price Volatility:Midwest Transaction Price swings for P1020 ingot directly compress converter margins, with limited pass-through mechanisms in annual beverage supply contracts.
- Smelter Concentration Risk:Canadian smelter curtailments in Quebec and British Columbia expose can sheet mills to ingot supply disruptions during hydroelectric capacity constraints.
- Substitution Pressure from PET:Lightweight bottle formats with recycled content claims are capturing functional water and ready-to-drink tea volumes where carbonation preservation is non-critical.
Strategic Opportunities
- Underpenetrated Mexican Beverage Packaging:Per-capita aluminium can consumption in Mexico trails U.S. levels by a significant margin, with expanding bottler investments in Monterrey and Guadalajara creating greenfield demand.
- Digital Printing Convergence:Direct-to-can inkjet systems are collapsing minimum order quantities from hundreds of thousands to tens of thousands, enabling hyper-localized craft brand runs.
- California SB 54 Implementation:The state's plastic pollution reduction mandates are accelerating aluminium can preference for single-serve beverages as brands seek compliant packaging pathways.
Industry Challenges
- Weld Technician Scarcity:Can line maintenance crews with expertise in high-speed necking and flanging equipment are concentrated among retiring cohorts, constraining plant expansion timelines.
- ASTM Recertification Backlogs:Third-party laboratory capacity for B209 mechanical testing and surface inspection is creating six-to-eight-month qualification delays for new mill entrants.
- Legacy Coating Line Integration:Epoxy-based internal spray systems face phase-out pressure from BPA-non-intent specifications, requiring capital-intensive conversion to polyester or vinyl organosol alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aluminium Cans Market |
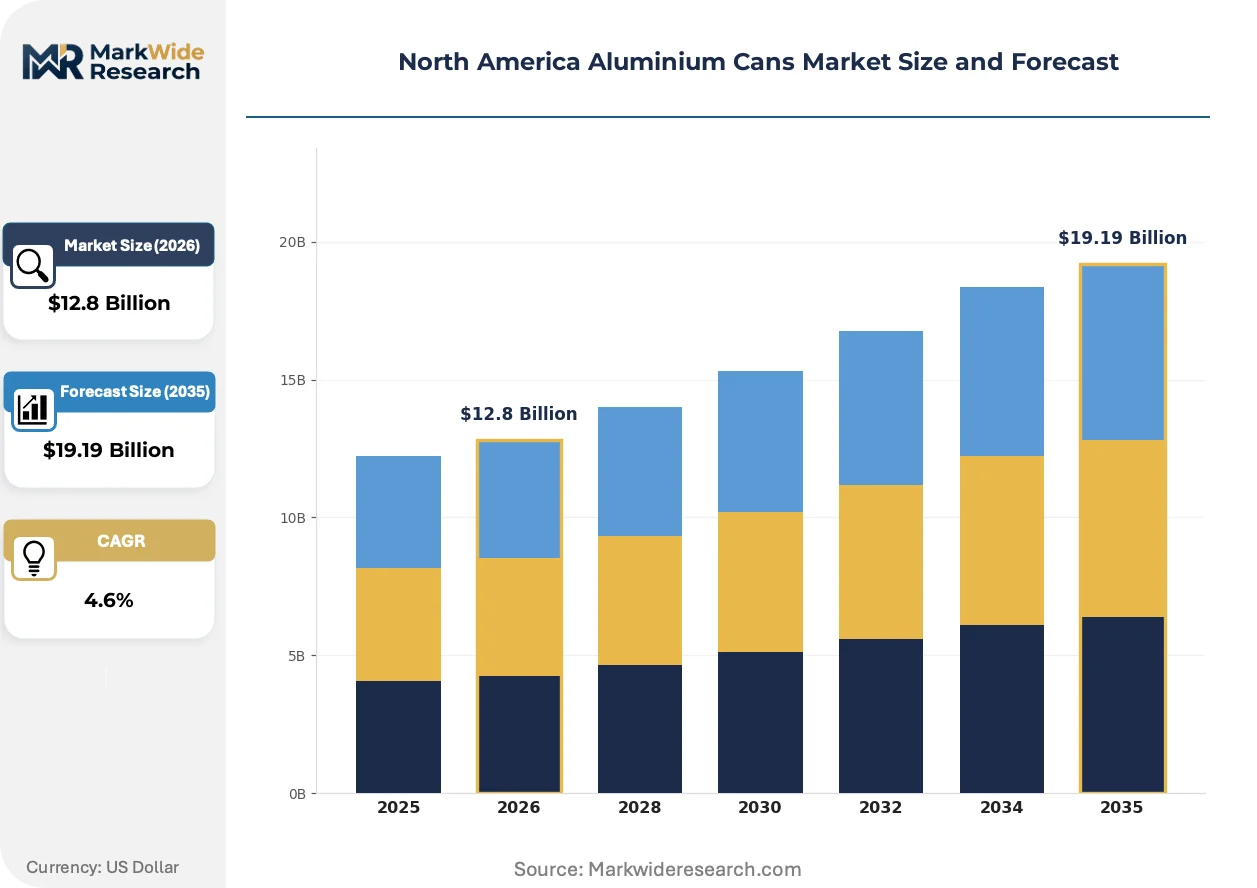
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cans, Slim Cans, Specialty Cans, Resealable Cans End User: Beverage Industry, Food Industry, Personal Care, Household Products Capacity: 250 ml, 355 ml, 500 ml, 1 L Distribution Channel: Retail, Online, Wholesale, Direct Sales |
| Companies Covered | Silgan Holdings Inc., Constellium, Ball Corporation, BWAY Corporation, Envases Universales de México S.A. de C.V., Crown Holdings Inc., Novelis, Can-Pack Group, Ardagh Group S.A., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aluminium Cans Market Strategic Shifts & Innovations
Aluminium can manufacturing is experiencing simultaneous pressure from material science advances, regulatory stringency on recyclability claims, and beverage brand demands for format differentiation at smaller production scales.
Laser-etched variable data printing is miniaturizing batch customization economics. The technology embeds QR codes and unique identifiers directly into can surfaces without label substrates. Craft breweries in Oregon and Colorado are adopting this for limited-release traceability and anti-counterfeiting. This capability is compressing minimum viable production runs and enabling direct-to-consumer verification layers previously impossible at aluminium packaging scale.
Environment and Climate Change Canada is harmonizing its recycled content verification protocols with California's SB 54 audit requirements. This cross-border alignment reduces compliance duplication for multinational beverage brands operating dual-country supply chains. The harmonization most affects can sheet suppliers serving Toronto and Vancouver bottling clusters, which must now maintain unified chain-of-custody documentation from smelter to forming plant.
Beverage brand technical buyers are consolidating supplier rosters around integrated metal-plus-converting partnerships. This procurement consolidation displaces spot-market sheet purchasing in favor of multi-year tolling agreements with volume commitments. The shift is most visible among hard seltzer and functional drink portfolios in Texas and Florida, where brands prioritize supply security over price optimization.
North America Aluminium Cans Market Segmentation
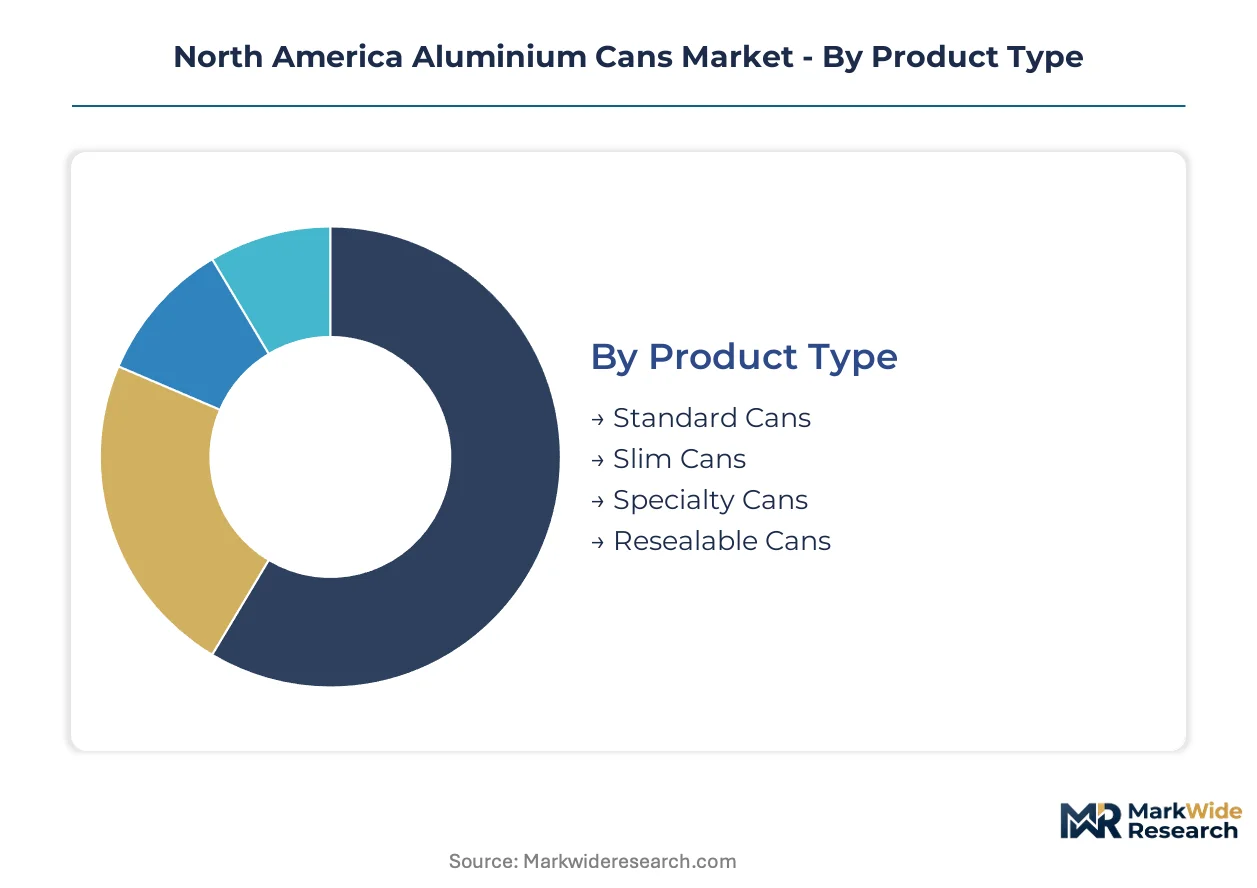
Aluminium can demand fragments across packaging formats, end-use applications, and volume tiers that each carry distinct margin profiles and supply chain requirements. Understanding these splits reveals where converter capacity investments concentrate and where specification flexibility creates competitive openings.
Product Type:
Domestic production dominates standard and slim formats, while specialty and resealable variants draw disproportionate export interest from craft beverage producers seeking differentiation.
- Standard Cans:Two-piece drawn-and-wall-ironed construction in 3104-H19 alloy serves high-speed filling lines for carbonated soft drinks and mass-market beer. Demand concentrates in Texas and Florida bottling corridors where EPA recycled content mandates lock in volume commitments from closed-loop sheet suppliers.
- Slim Cans:Narrower diameter profiles reduce aluminium unit consumption by 8-12% versus standard formats while preserving shelf differentiation for sparkling water and energy drink portfolios. Southeast U.S. craft producers in Georgia and North Carolina are accelerating dedicated line investments for 250 ml slim production.
- Specialty Cans:Shaped bodies, textured finishes, and matte coatings command premium positioning in limited-release beverage programs.
- Resealable Cans:Threaded aluminum closures and integrated lid mechanisms extend consumption occasions for premium functional drinks and wine-based beverages.
Standard cans command the established base. The steepest expansion runs through slim formats.
End User:
Cost tier stratification separates beverage applications with scale economies from industrial segments where specification tolerance drives supplier selection.
- Beverage Industry:Carbonated soft drinks, beer, hard seltzers, and ready-to-drink cocktails absorb the majority of 355 ml and 500 ml capacity. California SB 54 plastic reduction mandates are accelerating aluminium preference among brands seeking compliant single-serve pathways.
- Food Industry:Retortable and easy-open ends for ready meals, soups, and pet food require modified internal coatings and seam specifications distinct from beverage lines.
- Personal Care:Aerosol and dispensing formats for cosmetics and sun care utilize thinner gauge stock with specialized internal linings.
- Household Products:Insecticides, lubricants, and cleaning formulations demand corrosion-resistant barrier coatings and child-resistant closure compatibility.
Beverage applications absorb the volume base. Food packaging is climbing the fastest as retortable aluminium gains share from glass jars.
Capacity:
Volume concentration patterns mirror regional consumption habits and retail channel requirements across the continent.
- 250 ml:Portion-controlled formats for premium sparkling water and functional shots. Oregon and Colorado craft breweries are commissioning dedicated lines for limited-release traceability programs.
- 355 ml:The baseline North American standard for beer and carbonated soft drinks, optimized for retail six-pack configurations and vending machine compatibility.
- 500 ml:Single-serve beer and energy drink preference in Canada and northern U.S. markets where larger serving sizes dominate convenience store channels.
- 1 L:Family-size and multi-serve applications for sparkling water and value-positioned beer, concentrated in warehouse club and grocery retail formats.
355 ml holds the volume anchor. 250 ml is expanding most quickly as portion control and premium positioning reshape beverage portfolios.
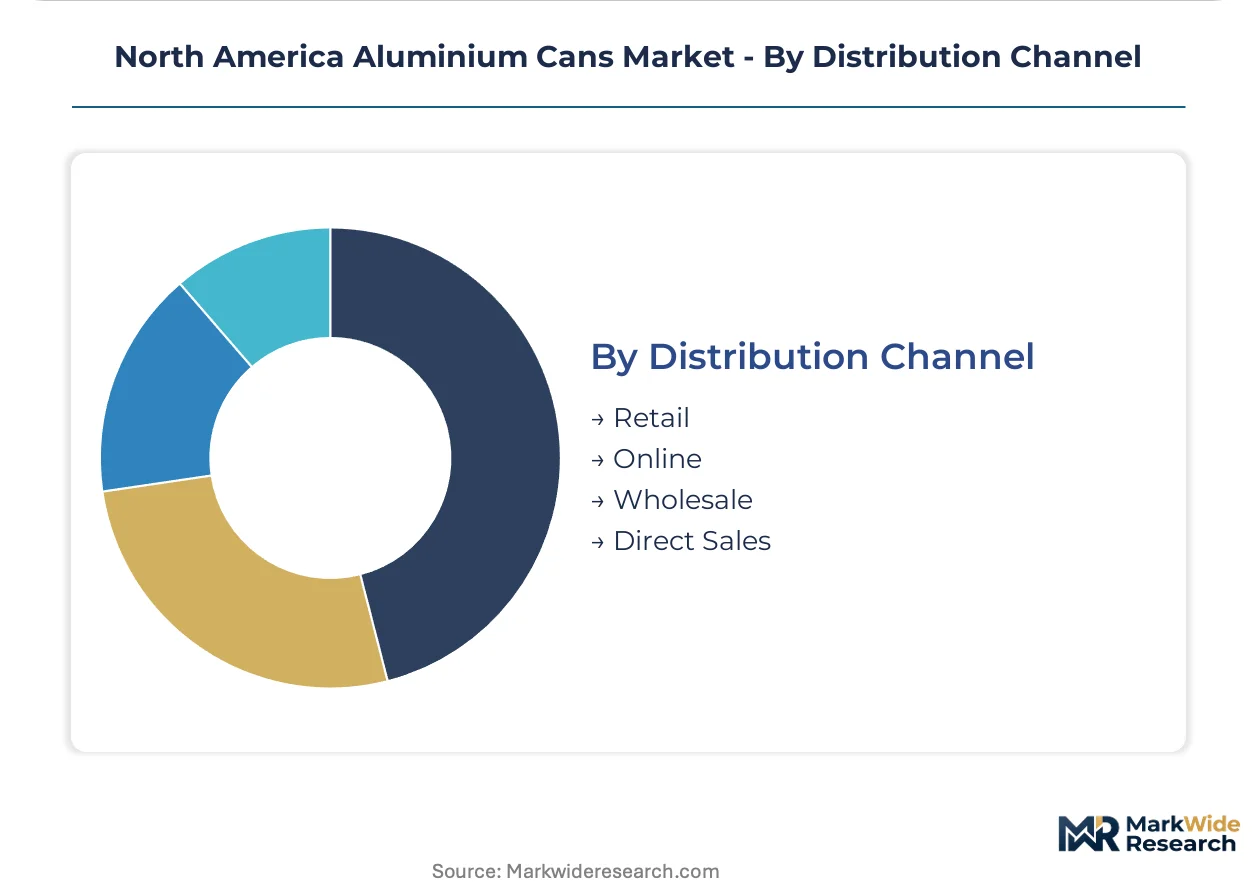
Distribution Channel:
Customer type fragmentation separates procurement patterns between multinational brands with integrated supply chains and fragmented buyers with spot-market exposure.
- Retail:Supermarkets, convenience stores, and mass merchandisers drive predictable high-volume demand with strict palletization and shelf-ready packaging requirements.
- Online:Direct-to-consumer beverage subscriptions and e-commerce grocery are collapsing minimum order quantities, pulling digital-print-ready can volumes.
- Wholesale:Distributor networks for independent craft producers concentrate in southeastern U.S. clusters near Atlanta and Charlotte canning hubs.
- Direct Sales:Toll-converting agreements between integrated metal suppliers and captive beverage brands bypass merchant sheet markets entirely.
Retail channels command the established base. Online distribution is gaining share fastest as digital printing collapses production run economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River barge network and Great Lakes-St. Lawrence Seaway system underpin aluminium can supply chain efficiency across the continent, connecting midwestern sheet mills to southeastern bottling corridors and Canadian smelter feedstock.
United States
EPA recycled content mandates under state-level extended producer responsibility programs are locking beverage brands into closed-loop sheet supply agreements. OSHA workplace standards at coating facilities influence plant siting decisions in Texas and Florida. Canning line clusters concentrate near Atlanta and Charlotte, where craft producers commission dedicated slim-format production.
Canada
Environment and Climate Change Canada harmonizes recycled content verification with California SB 54 audit requirements, reducing compliance duplication for multinational brands. Hydroelectric capacity constraints in Quebec and British Columbia expose smelter curtailment risks to can sheet mills. Toronto and Vancouver bottling clusters now maintain unified chain-of-custody documentation from smelter to forming plant.
Mexico
Per-capita aluminium can consumption trails U.S. levels significantly, creating greenfield demand as bottlers expand in Monterrey and Guadalajara. The country's national environmental regulator develops extended producer responsibility frameworks aligned with North American trade corridors. Manufacturing investments concentrate in Nuevo León and Jalisco, where proximity to U.S. border logistics supports export-oriented beverage packaging.
Southeast United States
Craft beverage producers accelerate orders for specialized 250 ml slim and resealable formats, pulling dedicated canning line investments into Georgia and North Carolina. State environmental agencies enforce emissions standards at coating facilities, affecting capital deployment timelines. The region's canning infrastructure clusters near beverage manufacturing hubs, with digital printing adoption enabling hyper-localized production runs.
North America Aluminium Cans Market Key Industry Players
Listed leaders compete with private specialists across integrated metal supply and toll-converting arrangements, producing a tiered structure where scale-driven converters anchor volume commitments while regional fabricators capture craft segment flexibility. Three archetypes dominate: captive metal suppliers with backward integration into primary production, independent converters reliant on merchant sheet markets, and specialty format specialists targeting premium beverage portfolios. Consolidation pressures intensify as beverage brands consolidate supplier rosters around multi-year tolling agreements, while digital printing investments reshape minimum order economics.
Among North American-anchored players, Ball Corporation occupies a position exemplifying integrated metal-plus-converting partnerships, while Crown Holdings Inc. represents deep multinational beverage brand relationships. Novelis sits within the closed-loop recycling archetype as the continent's largest aluminium recycler feeding can sheet production. These three anchors illustrate how competitive positioning stratifies across captive supply, brand integration, and circular material flows.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Constellium |
| Ball Corporation |
| BWAY Corporation |
| Envases Universales de México S.A. de C.V. |
| Crown Holdings Inc. |
| Novelis |
| Can-Pack Group |
| Ardagh Group S.A. |
| Others |
Cost & Logistics Intelligence
Six-to-eight-month ASTM B209 qualification delays concentrate pricing power among incumbent mills with certified laboratory relationships, while craft beverage buyers absorb premium spot-market sheet premiums for expedited delivery. This lead-time asymmetry rewards backward-integrated metal suppliers with captive smelter access and punishes merchant-market-dependent converters during hydroelectric curtailment periods in Quebec.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates closed-loop tolling agreements with volume commitments from spot-market merchant sheet purchases and distressed inventory clearances. Price differentiation hinges on recycled content certification grade under EPA state-level EPR thresholds and geographic delivery cost to southeastern U.S. canning clusters. Cost compression in spot-market tiers is intensifying because Canadian smelter curtailments during hydroelectric constraints expose merchant-dependent converters to Midwest Transaction Price volatility without pass-through protection. Mass-market beverage brands with multi-year tolling agreements demonstrate lowest price sensitivity, while independent craft producers purchasing through wholesale distributors face highest exposure to metal unit cost swings.
Supply Chain Analysis
Port congestion at Vancouver and Montreal container terminals elevates inbound logistics costs for alloy additive shipments from Australian bauxite refineries and Chinese silicon metal producers. Primary aluminium supply concentrates in Canada, the United States, and Mexico, with can sheet production drawing from Quebec hydroelectric smelters, Kentucky rolling mills, and Nuevo León forming plants. Raw material dependencies rest on P1020 primary ingot, 3104-H19 alloy chemistries, and epoxy-alternative internal coating chemistries. Single-source vulnerability runs through hydroelectric-dependent Canadian smelter corridors during drought-induced capacity constraints. Distribution runs through Mississippi River barge networks connecting midwestern sheet mills to Atlanta and Charlotte beverage manufacturing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story because EPA recycled content mandates under evolving state-level EPR programs create regulatory entrenchment that locks beverage brands into closed-loop supplier relationships with multi-year volume commitments.
For Market Incumbents: Compound captive metal supply advantages by expanding tolling agreement coverage with hard seltzer and functional drink portfolios in Texas and Florida, while accelerating ASTM B209 recertification investments to extend qualification backlogs that block new mill entrants. Address substitution pressure from PET bottle formats by embedding digital printing capabilities that collapse minimum order quantities for hyper-localized craft brand runs. For New Entrants and Emerging Players: Differentiate on digital-to-can inkjet specialization serving Oregon and Colorado craft breweries with laser-etched variable data printing for limited-release traceability programs. Target underpenetrated Mexican beverage packaging in Monterrey and Guadalajara where per-capita aluminium can consumption trails U.S. levels significantly. Pursue direct-to-consumer e-commerce channels where collapsing production run economics favor agile converters over high-volume incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a circular-material-flow play because closed-loop aluminium recycling infrastructure commands durable competitive positioning under tightening EPA and Environment and Climate Change Canada harmonized verification protocols. Acquisition targets should prioritize integrated metal-plus-converting partnerships with captive smelter relationships and established chain-of-custody documentation from smelter to forming plant. Monitor California SB 54 implementation pace as inflection indicator for aluminium can preference acceleration against plastic packaging alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Smelting | Captive P1020 ingot supply insulates converters from Midwest Transaction Price volatility during Quebec hydroelectric curtailments. |
| Digital Printing Capability Deployment | Direct-to-can inkjet systems collapse minimum order quantities from hundreds of thousands to tens of thousands for craft producers. |
| ASTM B209 Laboratory Certification Investment | Third-party mechanical testing capacity secures six-to-eight-month qualification timelines that block new mill market entry. |
| Closed-Loop Recycling Infrastructure Expansion | Novelis-style circular material flows satisfy EPA recycled content mandates under evolving state-level EPR frameworks. |
| Resealable Can Format Development | Threaded aluminum closures extend consumption occasions for premium functional drinks and wine-based beverage portfolios. |
Research Approach
Cross-validation between primary interviews with beverage procurement directors, can sheet mill technical buyers, and coating facility plant managers anchors the qualitative findings against secondary validation from EPA regulatory filings, Environment and Climate Change Canada harmonization protocols, and SEC 10-K disclosures from listed packaging converters. Bottom-up demand modeling from craft brewery canning line investments and top-down supply assessment from midwestern rolling mill capacity announcements generate convergent volume estimates. Triangulation across these independent estimation paths isolates structural assumptions from idiosyncratic data gaps.
Sensitivity analysis on primary aluminium price volatility, hydroelectric capacity availability in Quebec and British Columbia, and California SB 54 implementation pacing tests forecast stability across the projection horizon. Segmentation modeling incorporates product type fragmentation across standard, slim, specialty, and resealable formats; end-user splits between beverage, food, personal care, and household applications; capacity tier concentration from 250 ml through 1 L; and distribution channel stratification across retail, online, wholesale, and direct sales. CAGRs derive from recursive substitution of segment-level volume assumptions into consolidated market estimates, with alloy optimization trends and digital printing adoption curves as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EPA recycled content mandate enforcement, stable Midwest Transaction Price bands, and functional PET substitution limits would require recalibration. Forecasts reflect documented assumptions regarding craft beverage expansion trajectories, smelter curtailment frequency, and cross-border harmonization of recycling certification standards. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
Asia-Pacific Metal Packaging Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
Novelty Tins Market
Metal Packaging
Packaging Metallization Market
Metal Packaging
Beverage Metal Cans Market
Metal Packaging
Aluminum Foil Lids Market
Metal Packaging
Metal Containers Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
North America Metal Packaging Market
Metal Packaging
Aluminum Aerosol Cans Market
Metal Packaging
PTP Aluminum Foil Market
Metal Packaging
Germany Metal Packaging Market
Metal Packaging
Global Laminated Steel for Cans Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
Latin America Metal Packaging Market