
 GCC Metal Cans Market | 2026-2036
GCC Metal Cans Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Metal Cans Market Foresight
Distribution through GCC beverage bottlers and co-packing networks is narrowing as regional concentrate producers consolidate supplier lists. Crown Holdings leverages integrated aluminum can sheet supply from its global rolling assets to secure long-term contracts with Saudi and UAE bottlers. Ball Corporation anchors its regional position through high-speed two-piece can lines serving the carbonated soft drink segment. Gulf Cans Industries competes on proximity, operating from Saudi Arabia's Eastern Province to reduce logistics costs for domestic food manufacturers.
GCC metal cans are cylindrical containers fabricated from aluminum or tinplate steel, typically ranging from 150 mL to 1,000 mL in capacity, formed through draw-and-wall-iron or three-piece welding processes and coated with epoxy-phenolic lacquers to prevent corrosion and preserve flavor. Two-piece aluminum cans dominate beverage applications due to lighter weight and superior recyclability, while three-piece tinplate cans sustain demand in processed food and aerosol segments where structural rigidity and high-temperature retort compatibility matter. Aerosol cans represent a specialized growth pocket as personal care and household product manufacturers in the UAE expand local filling capacity. Specialty cans, including easy-open ends and shaped containers, attract premium positioning from multinational beverage brands seeking shelf differentiation in Saudi hypermarkets.
SASO's technical regulations for food-contact materials and ESMA's Emirates Conformity Assessment Scheme govern substrate purity, internal coating migration limits, and labeling requirements across Saudi Arabia and the UAE. The Gulf Standardization Organization (GSO) harmonizes these frameworks across Bahrain, Kuwait, Oman, and Qatar, creating a unified compliance pathway but also raising barriers for non-certified imports. Stakeholders must monitor evolving extended producer responsibility proposals in the UAE and Saudi Arabia, where deposit-return schemes and aluminum recovery targets could reshape raw material sourcing economics and converter investment timelines.
Market Dynamics
SASO and ESMA have tightened food-contact material compliance, forcing converters to upgrade substrate grades and internal coating specifications while consolidating supplier relationships around certified domestic producers.
Growth Catalysts
- Aluminum two-piece can adoption:Beverage bottlers across Saudi Arabia and the UAE are expanding procurement of aluminum two-piece cans for carbonated soft drinks and ready-to-drink beverages due to lighter weight and superior recyclability.
- GSO harmonization:The Gulf Standardization Organization has unified compliance pathways across Bahrain, Kuwait, Oman, and Qatar, reducing cross-border certification friction for regional converters.
- Eastern Province industrial clustering:Jubail and Dammam host integrated canmaking and filling operations that serve domestic and export markets, creating procurement gravity for domestic food manufacturers.
Market Restraints
- Aluminum sheet import dependency:Regional converters rely on imported aluminum can sheet from global rolling assets, exposing margins to LME price volatility and freight cost swings.
- Retort compatibility limitations:Two-piece aluminum cans cannot withstand high-temperature retort processing required for certain processed foods, constraining penetration in shelf-stable food segments.
- Extended producer responsibility uncertainty:Evolving deposit-return scheme proposals in the UAE and Saudi Arabia create investment timeline ambiguity for converter capacity expansion decisions.
Strategic Opportunities
- Aerosol can localization:Personal care and household product manufacturers in the UAE are expanding local filling capacity, creating demand for three-piece tinplate aerosol cans with structural rigidity specifications.
- Specialty can premium positioning:Easy-open ends and shaped containers attract multinational beverage brands seeking shelf differentiation in Saudi hypermarkets.
- SASO-ESMA certification arbitrage:Converters achieving dual certification can supply both markets without duplicate testing, capturing volume from non-certified import competitors.
Industry Challenges
- Coating migration testing capacity:Limited regional laboratory capacity for epoxy-phenolic lacquer migration testing extends product qualification timelines for new substrate formulations.
- High-speed line integration complexity:Bottlers upgrading to high-speed two-piece can lines face reconfiguration challenges with legacy filling equipment and downstream palletizing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Metal Cans Market |
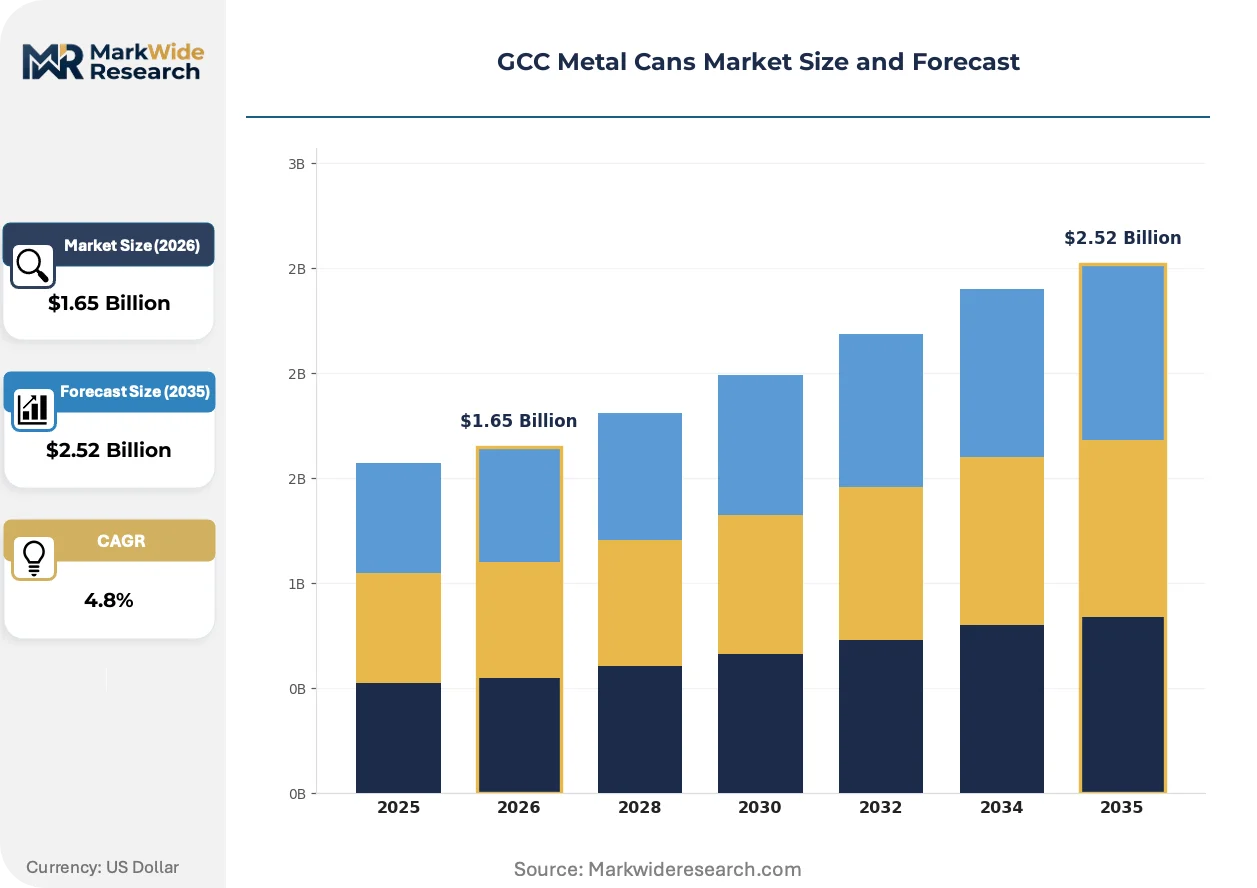
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Piece Cans, Three-Piece Cans, Aerosol Cans, Specialty Cans Material: Aluminum, Tinplate, Steel, Aluminum-Tinplate Composite Application: Beverages, Food Packaging, Pharmaceuticals, Paints & Coatings, Personal Care End User: Beverage Producers, Food Manufacturers, Pharmaceutical Firms, Chemical Companies |
| Companies Covered | Ball Corporation, Crown Holdings, SAPIN SA, CAN-PACK Middle East LLC, ARYUM Metal Alüminyum Tüp, Ardagh Group, Silgan Holdings Inc., Saudi Can Co. Ltd, Gulf Cans Industries, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Metal Cans Market Shifts & Advancements
Material science advances and regulatory tightening are compressing acceptable specifications for food-contact surfaces while reshaping how beverage and food manufacturers evaluate container suppliers.
Digital printing on metal substrates is rendering obsolete traditional pre-printed tinplate and label-applied decoration for short-run promotional and seasonal beverage campaigns. Saudi bottlers are piloting digitally printed aluminum cans for limited-edition releases. This capability is compressing minimum order quantities and enabling brand managers to execute regional flavor variants without plate changeover costs.
SASO's technical regulations for food-contact materials now mandate substrate purity thresholds and internal coating migration limits that exceed historical Gulf import standards. Converters must document supply chain traceability for aluminum and tinplate inputs. The processed food segment faces the steepest compliance burden as retort-compatible coatings require additional safety data submissions.
Beverage bottlers are consolidating supplier lists around integrated converters capable of delivering certified substrates, formed cans, and technical support through single contracts. This pattern displaces fragmented procurement of sheet metal, conversion services, and logistics from separate vendors. The UAE's co-packing networks exhibit the most visible concentration, with multinational concentrate producers reducing approved supplier counts by half.
GCC Metal Cans Market Segmentation
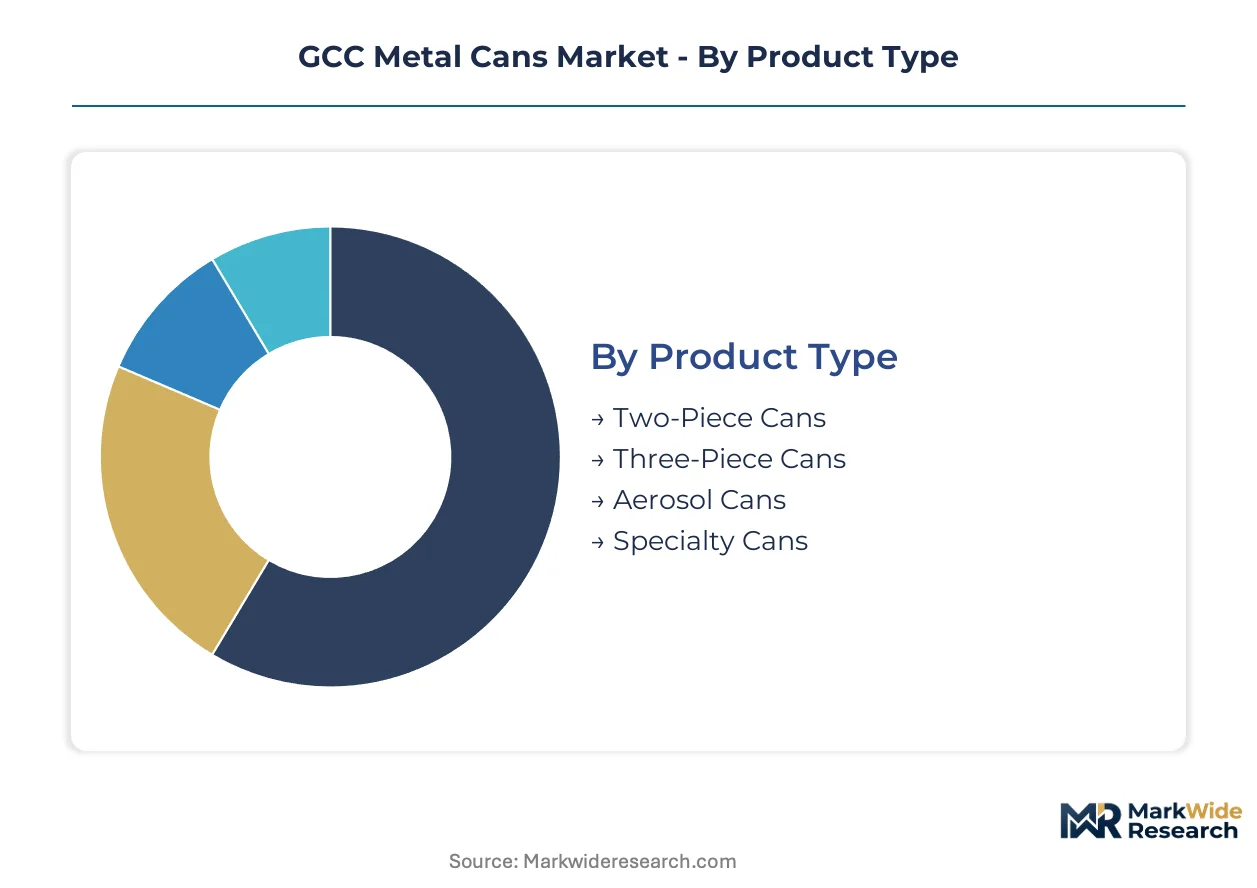
Segmentation in the GCC metal cans market reveals how substrate selection, forming technology, and end-use requirements create distinct procurement ecosystems. Each dimension carries regulatory and logistical implications that shape converter investment decisions across Saudi Arabia and the UAE.
Product Type:
Mature forming technologies dominate beverage applications while emerging configurations target premium positioning and specialized contents.
- Two-Piece Cans:Draw-and-wall-iron aluminum containers with seamless walls and integrated bottoms. Demand concentrates with Saudi and UAE carbonated soft drink bottlers seeking lighter weight and superior recyclability under tightening extended producer responsibility frameworks.
- Three-Piece Cans:Welded tinplate cylinders with separate top and bottom ends, engineered for structural rigidity. Food manufacturers in Saudi Arabia's Eastern Province rely on these for retort-processed shelf-stable products where high-temperature compatibility is non-negotiable.
- Aerosol Cans:Three-piece tinplate pressure vessels with reinforced domes and specialized valves.
- Specialty Cans:Shaped containers and easy-open end configurations for premium beverage positioning.
Two-Piece Cans handles the majority of throughput; Specialty Cans is the fastest mover on share.
Material:
Cost tier differentiation separates commodity substrates from certified grades required for food-contact compliance.
- Aluminum:Rolled can sheet with H19 temper specifications, offering weight reduction and infinite recyclability loops. Beverage producers across the GCC prioritize this substrate as SASO and ESMA tighten migration limits on internal coatings.
- Tinplate:Cold-rolled steel with electrolytic tin coating, providing corrosion resistance and solderability. Aerosol and processed food applications in the UAE sustain demand despite higher unit weight versus aluminum alternatives.
- Steel:Uncoated or polymer-coated substrates for non-food industrial applications.
- Aluminum-Tinplate Composite:Hybrid laminates combining barrier properties with forming flexibility.
Aluminum commands the dominant procurement volume; Aluminum-Tinplate Composite is expanding most quickly as converters seek compliance arbitrage.
Application:
Customer type patterns show beverage concentration in high-volume automated lines versus fragmented food and industrial procurement.
- Beverages:Carbonated soft drinks, ready-to-drink teas, and energy drinks in aluminum two-piece formats. Saudi bottlers in Jubail and Dammam anchor regional demand through integrated filling operations serving domestic and export markets.
- Food Packaging:Processed meats, vegetables, and ready meals requiring retort compatibility. Three-piece tinplate configurations prevail where high-temperature sterilization cycles exceed aluminum structural limits.
- Pharmaceuticals:Aerosol and specialty containers for metered-dose inhalants and topical preparations.
- Paints & Coatings:Industrial-grade tinplate with chemical-resistant internal linings.
- Personal Care:Deodorants, hair sprays, and household products driving UAE aerosol localization.
Beverages generates the dominant order flow; Personal Care is climbing the fastest on local filling capacity expansion.
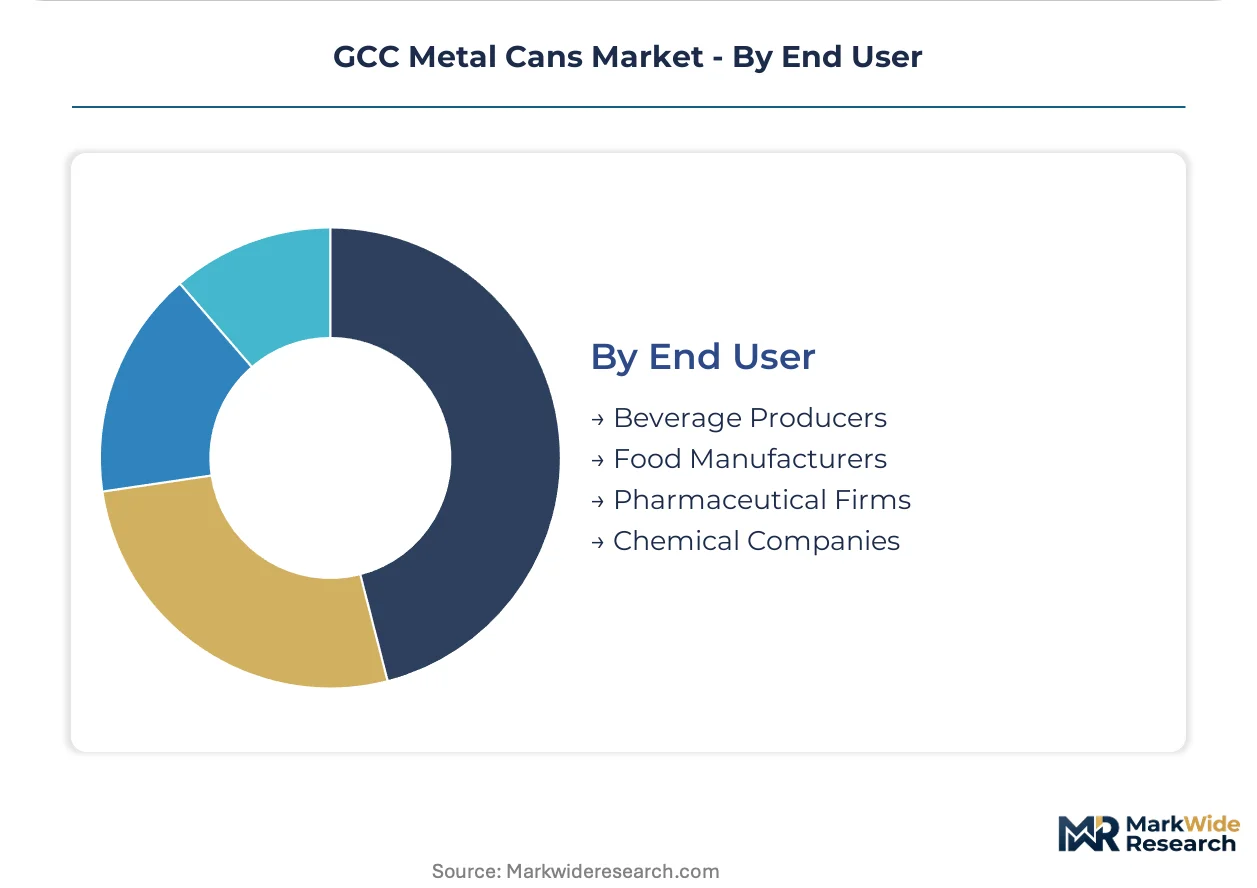
End User:
Supply concentration patterns cluster integrated beverage operations in Saudi Arabia's Eastern Province while food and pharmaceutical demand fragments across smaller converters.
- Beverage Producers:Multinational concentrate bottlers and regional soft drink manufacturers. Procurement consolidates around Crown Holdings and Ball Corporation for long-term aluminum two-piece supply contracts with embedded technical support.
- Food Manufacturers:Processed meat, dairy, and canned vegetable processors. Gulf Cans Industries captures proximity advantage from Dammam-based operations serving domestic producers with reduced logistics costs.
- Pharmaceutical Firms:Metered-dose inhaler and topical product manufacturers.
- Chemical Companies:Paint, coating, and industrial aerosol formulators.
Beverage Producers drive the bulk of contracted volume; Pharmaceutical Firms is gaining share fastest on regulatory compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Fahd Industrial Port in Jubail underwrites Saudi Arabia's dominance in GCC metal can manufacturing, handling raw aluminum sheet imports and finished can exports across the Red Sea and Indian Ocean trade lanes.
Saudi Arabia
Carbonated soft drink bottlers in the Eastern Province anchor regional aluminum two-piece procurement, with Jubail and Dammam hosting integrated canmaking and filling corridors. SASO mandates substrate purity thresholds and internal coating migration documentation that exceed historical Gulf import standards. The Dammam-based industrial cluster serves domestic food manufacturers with three-piece tinplate configurations for retort-processed shelf-stable products.
United Arab Emirates
Ready-to-drink beverage producers and personal care formulators in Dubai and Abu Dhabi drive aerosol can localization and specialty container demand. ESMA's Emirates Conformity Assessment Scheme governs food-contact material compliance, creating certification barriers for non-certified imports. Dubai's Jebel Ali free zone concentrates co-packing networks where multinational concentrate producers have halved approved supplier counts.
Kuwait
Processed food importers and regional distribution hubs sustain demand for three-piece tinplate cans re-exported to Iraq and Jordan. The Gulf Standardization Organization harmonizes Kuwait's technical regulations with Saudi and UAE frameworks, reducing cross-border certification friction. Shuwaikh Port handles bulk tinplate shipments feeding small-scale converters serving the domestic dairy and canned vegetable segments.
Qatar
Beverage bottlers serving the 2022 FIFA World Cup legacy hospitality sector prioritize lightweight aluminum two-piece formats for premium positioning. Qatar's national food security program subsidizes local canning capacity for shelf-stable meat and dairy products. The Mesaieed Industrial City hosts emerging converter operations targeting import substitution for previously re-exported containers.
Oman
Sohar Port's aluminum smelter complex supplies regional rolling mills with primary metal, though downstream can sheet conversion remains limited. Oman's food processing sector relies on imported formed cans from UAE and Saudi converters due to absent domestic capacity. The Special Economic Zone at Duqm attracts speculative investment for future beverage filling operations targeting African export markets.
GCC Metal Cans Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying certified substrates and formed containers to fragmented food manufacturers. The GCC metal cans market consolidates around multinational converters with captive aluminum rolling assets and long-term bottler contracts, while domestic fabricators compete on logistics proximity for smaller food and aerosol accounts. Two strategic archetypes dominate: integrated global converters leveraging backward control over can sheet supply, and regional proximity players optimizing Eastern Province distribution networks. Competitive moves center on dual SASO-ESMA certification arbitrage and high-speed two-piece line installation to capture carbonated soft drink volume.
Among North American-based integrated converters, Ball Corporation and Crown Holdings exemplify the platform-integrator archetype, anchoring regional supply through aluminum can sheet assets and embedded technical support contracts with Saudi and UAE bottlers. Gulf Cans Industries occupies a position within the proximity-specialist tier, representing domestic fabricators competing on logistics cost reduction for Eastern Province food manufacturers. These three entities collectively illustrate the competitive structure: global scale versus regional responsiveness, with certification capability as the dividing line.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings |
| SAPIN SA |
| CAN-PACK Middle East LLC |
| ARYUM Metal Alüminyum Tüp |
| Ardagh Group |
| Silgan Holdings Inc. |
| Saudi Can Co. Ltd |
| Gulf Cans Industries |
| Others |
Supply & Pricing Matrix
Imported aluminum can sheet from global rolling mills in North America and Europe anchors cost structures for GCC converters, concentrating margin capture with integrated multinational suppliers holding captive smelter and rolling assets while regional fabricators compete on logistics proximity for fragmented food and aerosol accounts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated global converters with dual SASO-ESMA certification from regional proximity players and uncertified import competitors. Price differentiation hinges on certification grade and volume scale, with multinational bottlers locking in long-term offtake contracts at standard tiers while smaller food manufacturers face economy-tier spot pricing. Pricing pressure stems from LME aluminum volatility and freight cost swings, with beverage producers exhibiting lowest price sensitivity due to embedded technical support requirements and food manufacturers showing highest sensitivity to logistics-driven cost variations.
Supply Chain Analysis
Export-control regimes on advanced can sheet rolling technology limit domestic capacity buildout across Saudi Arabia and the UAE, forcing reliance on imported H19-temper aluminum substrate from the United States, Germany, and South Korea. Raw material dependencies center on primary aluminum ingot, epoxy-phenolic coating resins, and electrolytic tinplate for three-piece configurations. Supply chain risk concentrates in single-source vulnerability for certified can sheet grades meeting SASO migration limits. Distribution runs through Jubail and Dammam industrial corridors for integrated beverage operations, with fragmented logistics networks serving smaller food and personal care formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC metal can procurement is consolidating around platform-integrated converters capable of delivering certified substrates, formed containers, and embedded technical support through unified contracts, with interoperability between bottler filling lines and converter specification systems becoming the decisive ecosystem battleground.
For Market Incumbents: Harden dual-certification moats by accelerating SASO-ESMA compliance documentation for emerging coating formulations before regulatory deadlines tighten. Deepen backward integration into aluminum rolling partnerships or captive sheet supply agreements to insulate margins from LME volatility and freight exposure threatening standard-tier pricing power. For New Entrants and Emerging Players: Pursue aerosol can localization opportunities in the UAE personal care segment where domestic filling capacity expansion outpaces qualified three-piece tinplate supply. Target pharmaceutical metered-dose inhaler contracts requiring retort-compatible structural specifications that multinational beverage-focused converters underserve, leveraging proximity to Dubai's Jebel Ali free zone co-packing networks for initial customer access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed regional fabricators holding Eastern Province logistics advantages but lacking integrated rolling supply and certification breadth for beverage platform economics. Long-term viability favors converters with dual regulatory approval and backward aluminum supply control. The signal to watch is deposit-return scheme implementation timelines in Saudi Arabia and the UAE, which would reshape raw material recovery economics and converter investment thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | SASO-ESMA compliance arbitrage captures volume from non-certified import competitors across Saudi and UAE markets. |
| High-Speed Line Installation | Two-piece aluminum capacity expansion secures long-term contracts with Jubail and Dammam carbonated soft drink bottlers. |
| Aerosol Localization Partnership | Three-piece tinplate supply agreements with UAE personal care formulators exploit domestic filling capacity expansion. |
| Aluminum Supply Integration | Captive can sheet sourcing from global rolling assets insulates margins from LME price volatility and freight swings. |
| Digital Printing Capability | Short-run promotional can production for Saudi hypermarket limited-edition releases compresses minimum order quantities. |
Research Methodology
A spread of perspectives from beverage procurement directors, food manufacturing supply chain managers, canmaking plant engineers, and regulatory compliance officers converged on the working assumptions underlying this analysis. Primary field engagement combined structured interviews with secondary validation through SASO technical regulation filings, ESMA conformity assessment databases, GSO harmonization protocols, customs import records for aluminum can sheet, and SEC disclosures from listed packaging converters. Bottom-up volume modeling triangulated against top-down market sizing across substrate type, forming technology, and end-use application.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning product type, material grade, application category, and end-user concentration patterns. CAGRs derived from trend extrapolation of aluminum two-piece adoption rates, aerosol localization trajectories, and regulatory compliance investment cycles. Industry-specific forecast inputs incorporated extended producer responsibility proposal timelines and beverage bottler capacity expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in oil price levels, freight rate indices, or aluminum LME pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation schedules and bottler consolidation patterns. Material shifts in deposit-return scheme adoption or GSO harmonization scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Three Piece Cans Market
Metal Packaging
Australia Metal Packaging Market
Metal Packaging
North America Metal Cans Market
Metal Packaging
Aluminum Foil Market
Metal Packaging
Metal Pails Market
Metal Packaging
Europe Food Cans Market
Metal Packaging
Converter Aluminum Foil Market
Metal Packaging
Aluminum Foil Lids Market
Metal Packaging
APAC Food Cans Market
Metal Packaging
Latin America Metal Packaging Market
Metal Packaging
Metal Aerosol Can Market
Metal Packaging
Middle East and Africa Metal Packaging Market
Metal Packaging
Vietnam Metal Packaging Market
Metal Packaging
Aluminum Aerosol Cans Market
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
United States Metal Cans Market