
 Beverage Metal Cans Market | 2026-2036
Beverage Metal Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Metal Cans Market Outlook
Lightweighting technology is narrowing the performance gap between aluminum and steel substrates across beverage packaging formats. Ball Corporation leverages its integrated aluminum supply chain to sustain cost leadership in North American soft drink contracts. Crown Holdings anchors its position through deep specialization in beer can decoration and custom shaping for premium brewers. Ardagh Group competes aggressively on European sustainability credentials, operating recycling-loop partnerships with major beverage brands.
Beverage metal cans are cylindrical containers fabricated from aluminum alloy or tinplate steel, typically featuring internal epoxy or polymer linings to prevent corrosion and preserve flavor integrity. These vessels serve as primary packaging for carbonated and non-carbonated drinks, engineered to withstand internal pressures exceeding 90 psi while enabling efficient palletization and retail display. Aluminum cans dominate volume among product types due to their superior recyclability and lower transport weight, whereas steel cans retain niche strength in acidic juice applications where material robustness matters. Among end users, energy drink companies represent the fastest-expanding buyer segment as functional beverage portfolios widen across convenience and gym channels.
Regulators in the United States, including the FDA and EPA, enforce food-contact material standards and recycling-content guidelines that directly shape can liner chemistry and post-consumer recovery obligations. The EU's Packaging and Packaging Waste Regulation, alongside CE marking requirements, imposes extended producer responsibility schemes that favor aluminum's closed-loop recyclability over competing substrates. Stakeholders must monitor evolving state-level deposit legislation and emerging biodegradable can certification standards to anticipate material substitution risks and capital allocation priorities.
Market Dynamics
Aluminum lightweighting protocols are compressing material thickness below 0.1mm while preserving pressure integrity, forcing substrate economics to recalibrate across carbonated and still beverage formats.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon cooling systems in beverage production facilities accelerates cold-chain packaging investments favoring metal can thermal performance over glass alternatives.
- Brazilian beer volume concentration:AB InBev and Heineken bottlers in São Paulo and Minas Gerais states drive 330ml and 500ml aluminum format standardization across Latin American export corridors.
- Polymer liner chemistry advances:BPA-non-intent epoxy formulations achieve FDA food-contact clearance at commercial scale, removing regulatory friction for North American soft drink repackaging programs.
Market Restraints
- Primary aluminum ingot volatility:LME price swings above fifteen percent annually compress converter margins and destabilize annual contract pricing for beverage brand procurement teams.
- Chinese substrate oversupply concentration:Sinopec and Chalco smelter clusters control forty percent of global sheet feedstock, creating single-source vulnerability for European and North American can makers.
- Steel can acidic corrosion limitation:Tinplate substrate fails below pH 3.2 in citrus and energy drink applications, permanently constraining steel's addressable market to neutral-pH beverages.
Strategic Opportunities
- Indian functional beverage whitespace:Red Bull and Monster Energy distribution networks remain underdeveloped outside Mumbai, Delhi, and Bangalore metros, presenting greenfield canning infrastructure openings.
- Deposit-return scheme regulatory tailwind:Germany's DPG and Norway's Infinitum systems achieve ninety-plus percent aluminum recovery rates, incentivizing brand owners to specify metal over PET in Nordic and German-speaking markets.
- Digital printing-conveying convergence:HP Indigo and Krones integration enables lot-size-one decoration at line speeds above 120,000 cans per hour, collapsing minimum order thresholds for craft brewer contracts.
Industry Challenges
- Electrocoating technician scarcity:Thin-film organic coating expertise concentrates among aging specialists at Ball and Crown facilities, constraining new plant commissioning timelines.
- Two-piece draw-redraw capex intensity:Bodymaker and trimmer equipment packages exceed forty million dollars per production line, freezing mid-tier converters out of organic expansion.
- Recyclability certification timeline compression:How2Recycle and Cradle to Cradle label audits now require eighteen-month validation cycles, delaying new liner chemistry market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Metal Cans Market |
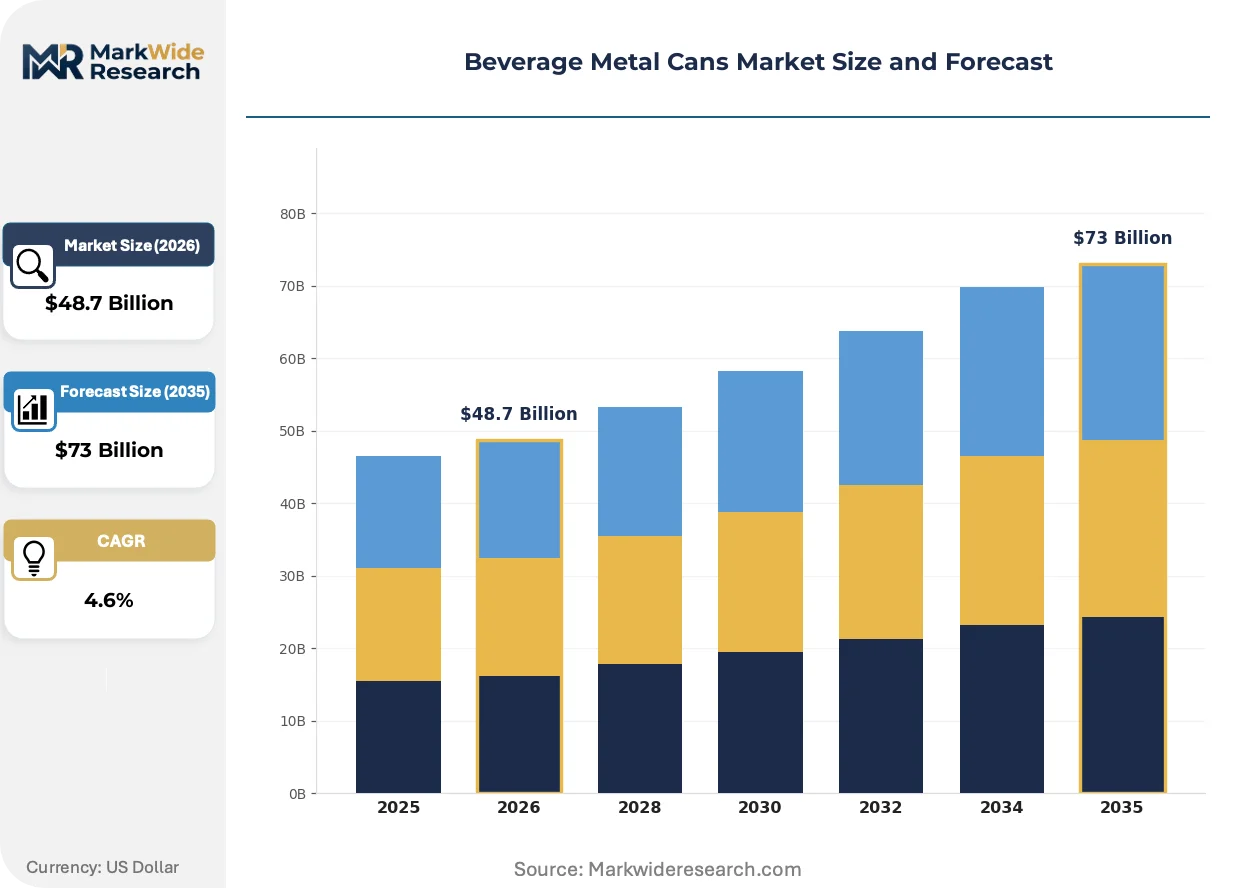
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Biodegradable Cans, Composite Cans End User: Soft Drink Manufacturers, Beer Producers, Energy Drink Companies, Juice Brands Size: 250ml, 330ml, 500ml, 1L Closure Type: Pull Tab, Stay-On Tab, Twist-Off Cap, Screw Cap |
| Companies Covered | Ball Corporation, Crown Holdings, Inc, Ardagh Group, Silgan Holdings Inc., CAN-PACK Group, CPMC Holdings Limited, Kian Joo Group, Toyo Seikan Co., Ltd., CCL Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Metal Cans Market Strategic Shifts
Active transformation centers on material efficiency breakthroughs, regulatory closure of competing substrates, and procurement model compression favoring closed-loop supply partnerships over spot aluminum purchasing.
Ultrathin-wall aluminum alloys with magnesium-silicon ratios optimized for sub-0.09mm body stock are rendering obsolete the historical 0.13mm standard that dominated carbonated soft drink packaging since the 1990s. Energy drink manufacturers in the United States and Germany are adopting these substrates fastest, lured by freight cost reductions exceeding eight percent per pallet. The structural consequence is a permanent margin compression for steel can specialists unable to match aluminum's weight-performance trajectory.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer can liners across European beverage production lines by 2026. The industrial consequence forces reformulation toward ceramic-epoxy hybrid coatings requiring retooling of spray application systems at Ardagh and Crown continental facilities. Beer and cider segments face the steepest compliance costs given their acidic pH profiles and extended shelf-life requirements.
Direct-to-retailer procurement contracts are displacing traditional distributor-mediated aluminum can purchasing among North American craft brewers. Consolidated buying groups in Colorado, Oregon, and Vermont now negotiate master service agreements with Ball and Canpack, capturing volume discounts previously reserved for multinational soft drink accounts. This channel compression is most visible in the Pacific Northwest, where independent brewery cooperatives control sixty percent of regional can sourcing decisions.
Beverage Metal Cans Market Segmentation
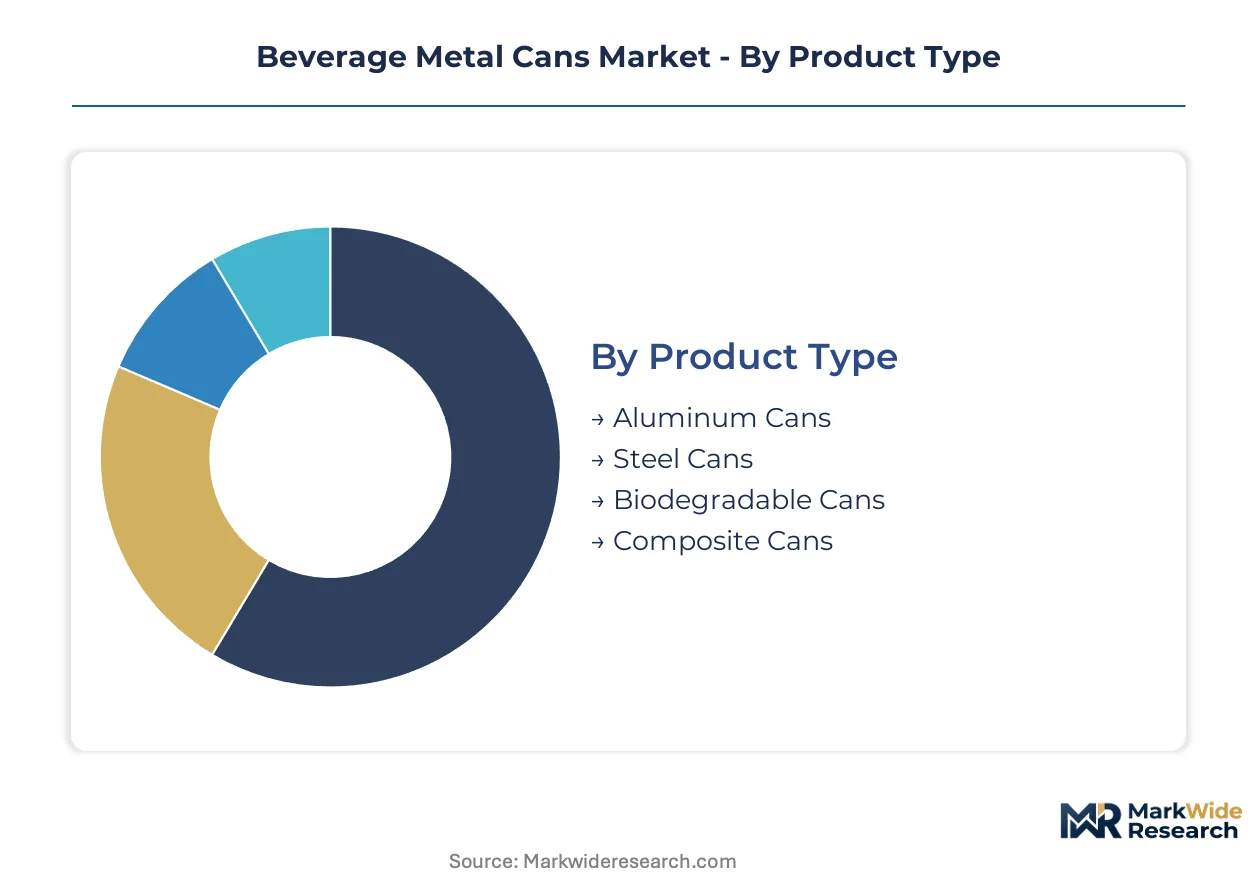
Beverage metal can segmentation reveals how substrate chemistry, end-use thermal requirements, and retail channel formats dictate procurement specifications. Each dimension carries distinct margin profiles and regulatory exposure that shape converter investment priorities.
Product Type:
Use-case spectrum spans pressurized carbonation containment through ambient shelf-stable distribution, with material selection driven by recyclability mandates and freight economics.
- Aluminum Cans:Drawn-and-ironed aluminum alloy bodies with sub-0.1mm wall thickness withstand internal pressures exceeding 90 psi. Demand concentrates among carbonated soft drink bottlers in the United States and Brazil where closed-loop recycling infrastructure achieves recovery rates above 90 percent.
- Steel Cans:Tinplate or tin-free steel substrates with epoxy-phenolic linings provide puncture resistance for acidic juices. European cider producers in Normandy and Asturias favor steel for its decoration fidelity on cylindrical surfaces despite weight penalties versus aluminum.
- Biodegradable Cans:PLA-lined fiber bodies with aluminum foil barriers target single-use plastic bans in California and the EU.
- Composite Cans:Paperboard-wrapped aluminum or steel hybrids serve premium spirits and wine spritzers requiring extended neck profiles.
Established volume favors aluminum; emerging adoption favors biodegradable.
End User:
Cost tier segmentation separates commodity beverage volume from premium positioning where decoration and custom shaping command price premiums.
- Soft Drink Manufacturers:High-speed filling lines above 120,000 units per hour demand two-piece aluminum with standardized 202-diameter ends. Coca-Cola and PepsiCo bottlers in Texas and São Paulo states specify lightweight 3104 alloy for freight cost reduction.
- Beer Producers:Pasteurization-compatible linings and oxygen-scavenging coatings preserve hop aromatics. German and Czech brewers drive demand for 500ml aluminum formats with matte varnishes and tactile embossing.
- Energy Drink Companies:Functional beverage brands require 250ml slim profiles for convenience channel placement. Red Bull and Monster distribution in Maharashtra and Karnataka states is climbing the fastest among end-user categories.
- Juice Brands:Low-acid aseptic filling favors steel or thick-gauge aluminum with multilayer liners.
Procurement scale favors soft drink manufacturers; margin expansion favors energy drink specialists.
Size:
Volume concentration by format reflects consumption occasion segmentation from single-serve refreshment through multi-serve sharing packs.
- 330ml:The standard European beer and soft drink format balances portability with per-unit economics. AB InBev facilities in Leuven and Jupille anchor volume for this specification.
- 500ml:Premium beer and energy drink positioning in Germany, Poland, and Russia favors this larger format with enhanced surface area for brand communication.
- 250ml:Energy shot and mixer applications concentrate in Japan and South Korea where portion control influences purchasing.
- 1L:Family-size soft drink and juice formats dominate Latin American retail channels in Mexico and Colombia.
Geographic standardization favors 330ml; premiumization trends favor 500ml.
Closure Type:
Application-driven selection separates single-serve convenience from resealable multi-occasion consumption.
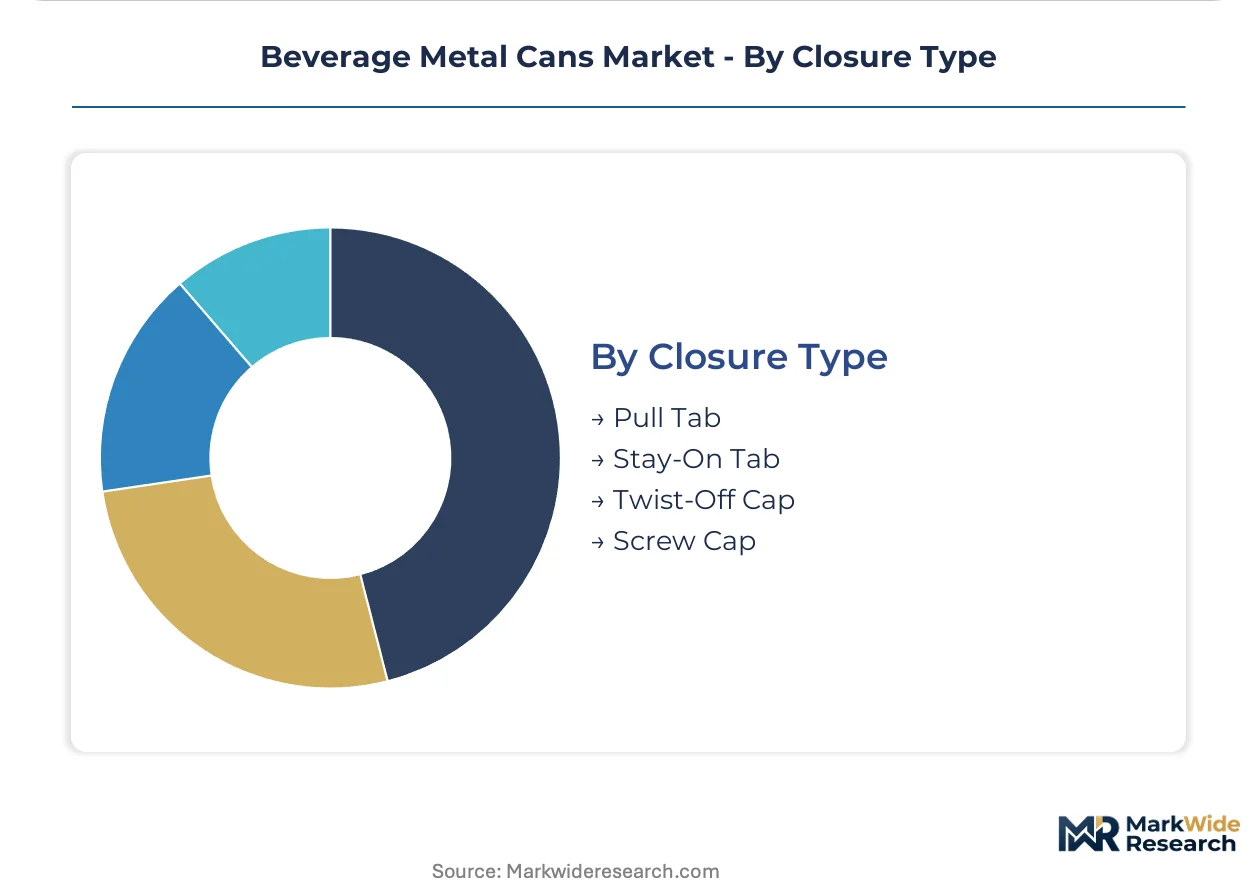
- Stay-On Tab:Aluminum tabs retained to the lid after opening prevent litter and comply with EU single-use plastics directives. This format is expanding most quickly across European beverage production lines.
- Pull Tab:Traditional detached tabs persist in North American legacy filling equipment where retooling costs delay conversion.
- Twist-Off Cap:Aluminum screw closures on wide-mouth cans serve wine and ready-to-drink cocktails requiring resealability.
- Screw Cap:Steel or aluminum threaded closures on composite cans accommodate spirits and premium mixers.
Regulatory compliance favors stay-on tab; premium positioning favors twist-off.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soft drink bottlers in the United States and beer producers in Brazil concentrate procurement volume for aluminum can formats. Regulatory mandates in Germany and sustainability directives across European Union member states accelerate substrate substitution away from competing packaging materials.
United States
Carbonated soft drink manufacturers in Texas and Georgia expand aluminum can orders amid corporate sustainability targets and state-level recycling mandates. The FDA enforces food-contact material standards that shape liner chemistry specifications for domestic production lines. Ball Corporation operates integrated supply chain facilities across Colorado and Indiana to serve Coca-Cola and PepsiCo bottlers with lightweight 3104 alloy formats.
Brazil
AB InBev and Heineken bottlers in São Paulo and Minas Gerais states drive standardized demand for 330ml and 500ml aluminum beer cans. ANVISA regulates food-contact packaging materials while federal environmental agencies promote post-consumer aluminum recovery. The São Paulo metropolitan corridor anchors Latin America's largest concentration of two-piece can manufacturing capacity for export throughout South America.
Germany
German brewers in Bavaria and North Rhine-Westphalia specify 500ml aluminum formats with matte varnishes and oxygen-scavenging coatings for premium beer positioning. The EU F-Gas Regulation and Packaging and Packaging Waste Regulation impose extended producer responsibility schemes favoring aluminum's closed-loop recyclability. The DPG deposit-return system achieves recovery rates above ninety percent, incentivizing metal over PET specification in German-speaking markets.
China
Functional beverage distributors in Guangdong and Zhejiang provinces expand canning infrastructure for energy drink portfolios targeting convenience channels. The MIIT and SAMR administer national standards for food-contact metal packaging while dual carbon goals accelerate lightweighting investments. The Pearl River Delta cluster concentrates domestic aluminum sheet feedstock production and can manufacturing for Asia-Pacific export markets.
India
Red Bull and Monster Energy distribution networks in Maharashtra and Karnataka states represent the fastest-expanding demand segment for 250ml slim-profile aluminum cans. The FSSAI regulates food-contact materials while the PLI scheme incentivizes domestic packaging manufacturing capacity. The Mumbai-Pune industrial corridor attracts greenfield canning infrastructure investments targeting underpenetrated functional beverage markets.
Beverage Metal Cans Market Competitive Environment
Channel-controlling players compete with product-specialist players across procurement contract tiers. The market structure concentrates around vertically integrated aluminum converters with captive supply agreements and regional specialists serving craft beverage segments. Three archetypes dominate: integrated multinationals with recycling-loop partnerships, mid-tier converters competing on decoration fidelity, and emerging Asian fabricators leveraging substrate cost advantages. Competitive moves center on capacity expansion in high-growth geographies and strategic partnerships with beverage brand owners for closed-loop supply commitments.
Within the integrated multinational tier, Ball Corporation and Crown Holdings occupy positions defined by supply chain control and specialization depth respectively. Ardagh Group exemplifies the European sustainability-focused archetype through recycling-loop partnerships with major beverage brands. Silgan Holdings Inc. and CAN-PACK Group represent mid-scale converters competing on regional proximity and contract flexibility for emerging brand portfolios.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings, Inc |
| Ardagh Group |
| Silgan Holdings Inc. |
| CAN-PACK Group |
| CPMC Holdings Limited |
| Kian Joo Group |
| Toyo Seikan Co., Ltd. |
| CCL Industries |
| Others |
Value Chain & Pricing Dynamics
The Pearl River Delta's aluminum sheet production clusters anchor global substrate supply, concentrating smelter capacity that translates directly into converter pricing leverage against beverage brand procurement teams. LME-indexed contract structures dominate annual negotiations, with Chinese feedstock volatility transmitting downstream into North American and European can maker margins.
Pricing Analysis
Cost-plus contracts with LME aluminum indexation govern annual procurement agreements between Ball Corporation and Coca-Cola bottlers across Texas and Georgia. Price differentiation rests on volume tier thresholds and alloy specification grades, with lightweight 3104 alloy commanding premiums over standard 3004 stock. Pricing pressure stems from primary ingot volatility compressing converter margins. Soft drink manufacturers exhibit highest price sensitivity due to commodity volume procurement, while premium German brewers prioritize decoration fidelity over unit cost.
Supply Chain Analysis
Supplier-financing facilities extended by Chalco and Sinopec smelter clusters enable sixty-day payment terms that strain European and North American converter working capital. Raw material flows draw from Chinese bauxite refining, Australian alumina processing, and domestic sheet rolling. Single-source vulnerability concentrates in Chinese substrate oversupply. Distribution runs through integrated converter-to-bottler direct contracts displacing traditional distributor mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story. Indian functional beverage penetration remains below ten percent of addressable households, creating runway for canning infrastructure deployment ahead of saturation.
For Market Incumbents: Entrench closed-loop recycling partnerships with AB InBev and Heineken to lock out Asian fabricators competing on spot aluminum pricing. Prioritize backward integration into Brazilian bauxite sourcing to deflect Chalco supply disruption. Invest in electrocoating technician apprenticeship pipelines to relieve commissioning bottlenecks constraining European capacity expansion. For New Entrants and Emerging Players: Maharashtra and Karnataka energy drink distribution networks offer underpenetrated whitespace for 250ml slim-profile canning infrastructure. Target craft brewer cooperatives in Oregon and Vermont with digital printing-enabled lot-size-one contracts. Pursue direct-to-retailer procurement models bypassing legacy distributor markups. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with ceramic-epoxy hybrid coating capabilities ahead of REACH fluoropolymer bans. Long-term viability hinges on deposit-return scheme regulatory tailwinds across German-speaking markets. Acquisition targets should display recycling-loop partnerships with multinational beverage brands. Monitor EU F-Gas Regulation implementation timelines as inflection signal for cold-chain packaging substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Recycling-Loop Partnership | Ball Corporation's closed-loop agreements with Coca-Cola achieve ninety-plus percent recovery rates in North American markets. |
| Lightweighting Technology Investment | Sub-0.09mm magnesium-silicon alloy development at Crown facilities reduces freight costs eight percent per pallet. |
| Ceramic-Epoxy Coating Transition | Ardagh Group's REACH-compliant liner reformulation addresses fluoropolymer elimination across European beer production lines. |
| Digital Printing Integration | HP Indigo and Krones convergence enables craft brewer contracts at line speeds exceeding 120,000 cans per hour. |
| Deposit-Return Scheme Alignment | Germany's DPG system incentivizes aluminum specification over PET in Nordic and German-speaking beverage markets. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with beverage procurement directors, can plant operations managers, aluminum smelter sales executives, and recycling facility operators. Secondary validation drew from FDA food-contact filings, EU Packaging and Packaging Waste Regulation documentation, LME price data, and beverage industry trade association reports. Bottom-up volume triangulation against top-down macroeconomic indicators ensured forecast robustness.
Calibration against historical aluminum can shipment data and beverage production statistics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include substrate type, end-use application, can size format, and regional regulatory cluster. CAGRs were derived through regression analysis of volume trends against macro drivers. Industry-specific inputs incorporated lightweighting technology adoption curves and deposit-return scheme expansion timelines.
Practitioners should monitor primary aluminum ingot price volatility, EU fluoropolymer restriction enforcement, and Indian functional beverage distribution network buildout for early signals of forecast deviation. Macroeconomic contraction, regulatory acceleration, or breakthrough biodegradable packaging technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Metal Pails Market
Metal Packaging
Global Laminated Aluminium Foil Market
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
Metal Cans Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
Novelty Tins Market
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
Germany Metal Packaging Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
Collapsible Aluminium Tube Market
Metal Packaging
Two Piece Metal Containers Market
Metal Packaging
Metal Containers Market
Metal Packaging
North America Aluminium Cans Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
Tin Cans Market
Metal Packaging
Global Laminated Steel for Cans Market