
 North America Metal Packaging Market | 2026-2036
North America Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Metal Packaging Market Analytics
Asset-light leasing models for can-making equipment are reshaping competitive dynamics in metal packaging, allowing mid-sized beverage brands to enter aluminum formats without capital-intensive plant ownership. Ball Corporation leverages its integrated aluminum supply chain to sustain cost leadership across North American beverage contracts. Crown Holdings anchors its position through deep specialization in aerosol and food can technologies. Silgan Holdings competes aggressively in the general line container segment through manufacturing scale and customer co-location strategies.
North America metal packaging comprises rigid and semi-rigid containers fabricated from aluminum, steel, and tinplate alloys, typically formed through deep drawing, two-piece drawing and wall-ironing, or three-piece welding and seaming processes, designed to provide barrier protection, stackability, and infinite recyclability for consumer and industrial goods. Cans dominate volume flows in beverage applications, where aluminum's lightweight properties and established recycling loops create durable margin pools for producers. Steel containers retain structural importance in food preservation, though growth tilts toward aluminum across premium beverage and personal care segments. Rigid packaging formats command the largest value share, while flexible foil applications expand in pharmaceutical blister and lidding uses where barrier precision matters.
The US EPA oversees recycling rate targets and material recovery facility standards that directly influence aluminum can collection economics, while FDA regulations govern food-contact metal coatings and migration limits that constrain formulation choices. State-level extended producer responsibility frameworks in California, Oregon, and Maine impose fee structures tied to recyclability design, pushing manufacturers toward mono-material aluminum solutions. Stakeholders must monitor how deposit-return system expansions and recycled content mandates reshape input cost structures and capital allocation across the value chain.
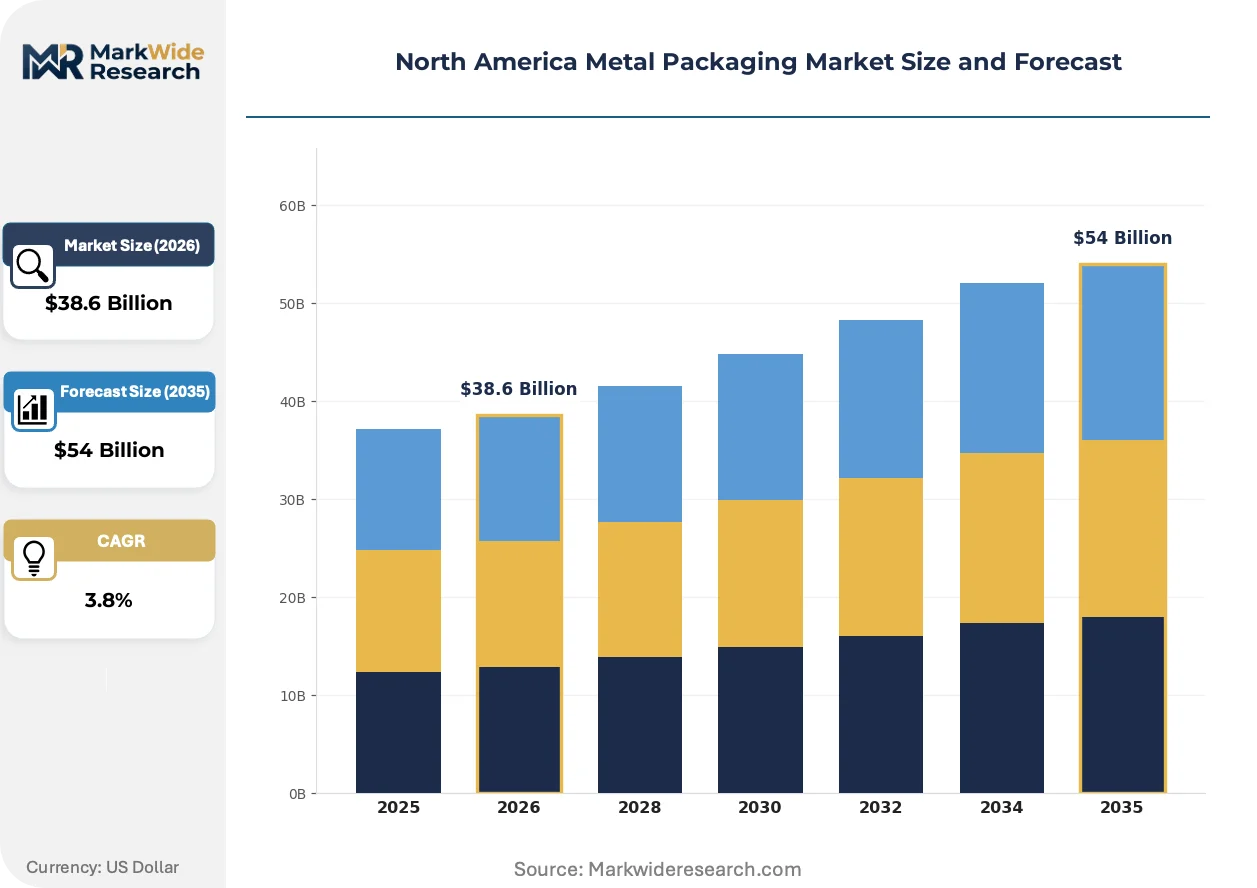
Market Dynamics
Asset-light equipment leasing models are collapsing capital barriers for mid-sized beverage brands entering aluminum formats, while state-level extended producer responsibility frameworks in California, Oregon, and Maine impose fee structures tied to recyclability design.
Growth Catalysts
- Deposit-return system expansions:Bottle bill adoptions across US states are tightening collection economics and expanding aluminum can recovery pools.
- US EPA recycling infrastructure investments:Federal material recovery facility upgrades are improving post-consumer aluminum sorting yields.
- Beverage brand plastic displacement:Carbonated soft drink and craft beer producers are accelerating aluminum format conversions.
Market Restraints
- Primary aluminum input cost volatility:LME price swings and energy-intensive smelting economics compress converter margins.
- Can manufacturing cluster concentration:Georgia and North Carolina production hubs create geographic supply vulnerability to regional disruptions.
- Steel food can substitution pressure:Retort pouch formats are displacing traditional tinplate containers in shelf-stable meals.
Strategic Opportunities
- Canadian deposit-return harmonization:Ontario and Quebec system expansions offer untapped post-consumer aluminum feedstock access.
- Pharmaceutical blister foil applications:Barrier-precision lidding demands are opening premium aluminum foil segments.
- Mono-material design mandates:California's recyclability scoring is rewarding all-aluminum container architectures.
Industry Challenges
- Deep-draw tooling specialist scarcity:Two-piece can bodymaker maintenance expertise is concentrating among retiring technician cohorts.
- FDA food-contact coating compliance timelines:Migration limit testing for new epoxy alternatives extends qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Metal Packaging Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $54 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cans, Containers, Tubes, Foil Material: Aluminum, Steel, Tinplate, Others End User: Food, Beverages, Cosmetics, Pharmaceuticals Packaging Type: Rigid Packaging, Flexible Packaging, Bulk Packaging, Custom Packaging |
| Companies Covered | Ball Corporation, Crown Holdings, Inc., Ardagh Metal Packaging S.A., Silgan Holdings, Inc., Mauser Packaging Solutions, CANPACK S.A., Greif, Inc., Cleveland Steel Container Corporation, Great Western Containers Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Metal Packaging Market Evolving Landscape
Lightweighting technologies and regulatory recyclability mandates are compressing traditional container design cycles across beverage and food applications.
Wall-ironing die advancements are collapsing thickness tolerances in two-piece aluminum beverage cans. Premium sparkling water and hard seltzer brands are adopting these gauges at accelerated rates. The technology is collapsing material intensity per unit while preserving pressure performance specifications.
California's extended producer responsibility framework is imposing fee differentials based on recyclability design scores. Mono-material aluminum solutions receive preferential rate treatment versus multi-layer alternatives. Beverage can producers are responding with coating system simplifications to qualify for lower fee tiers.
Direct equipment leasing from can-making machinery suppliers is displacing capital purchase models among mid-tier beverage brands. Contract packaging services are absorbing volume volatility that previously required owned capacity. The Southeast US craft brewery cluster is exhibiting the fastest adoption of this procurement structure.
North America Metal Packaging Market Segmentation
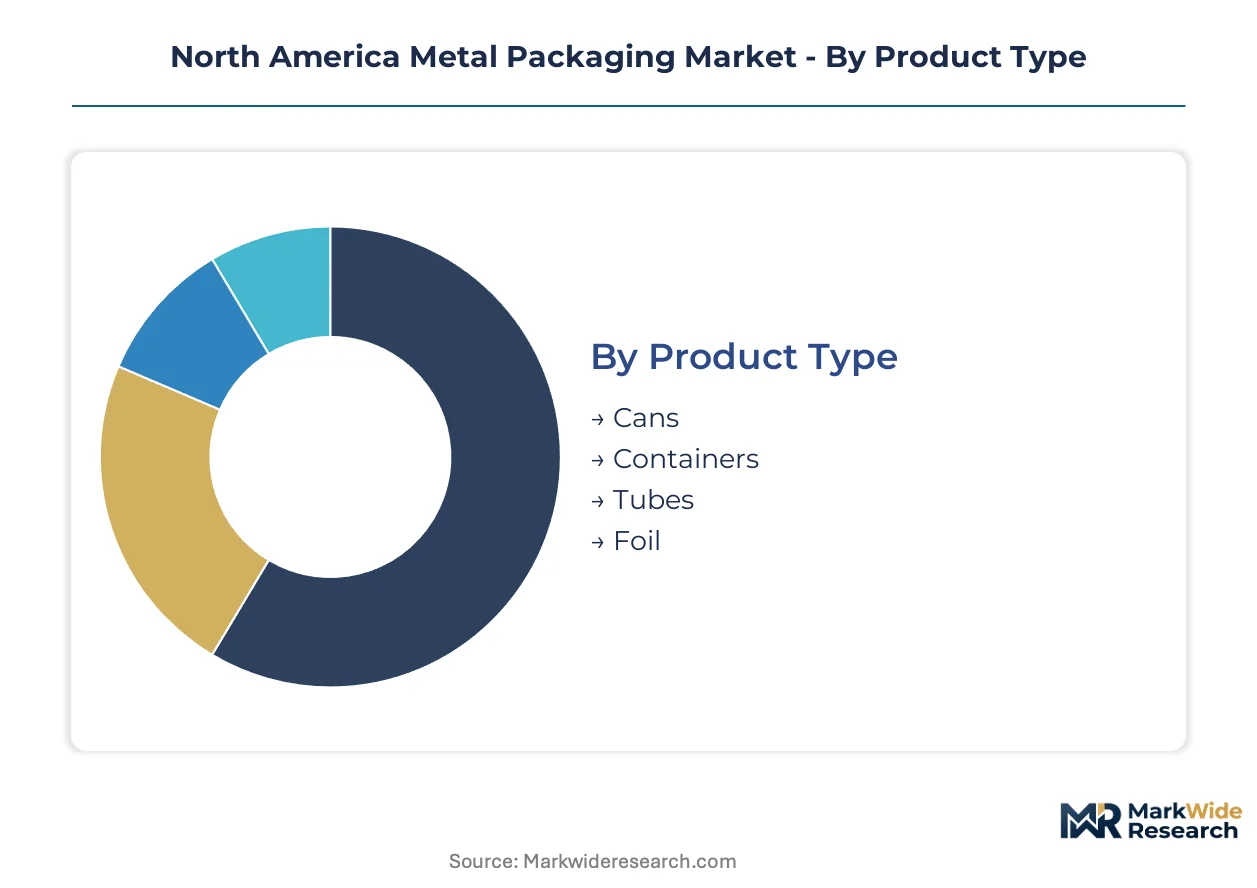
Segmentation in metal packaging reveals how material properties, end-use requirements, and regulatory constraints fragment production economics. Each dimension carries distinct margin profiles and capital intensity thresholds that shape competitive positioning.
Product Type:
Mature formats dominate volume flows while emerging configurations capture premium positioning.
- Cans:Two-piece aluminum beverage cans formed through deep drawing and wall-ironing deliver lightweight barrier protection with established recycling economics. Demand concentrates in the US Southeast craft brewery cluster and hard seltzer production hubs in Georgia and North Carolina, driven by deposit-return system expansions tightening post-consumer aluminum recovery pools.
- Containers:Three-piece welded steel food cans and general line containers provide structural integrity for retort processing and industrial chemical storage. Food preservation applications in shelf-stable meals and pet food concentrate demand, though retort pouch substitution pressure constrains growth trajectories in ready-to-eat segments.
- Tubes:Collapsible aluminum and laminate squeeze tubes serve pharmaceutical ointment and cosmetic cream dispensing with precise dosing control.
- Foil:Rolled aluminum sheet and converted foil products span lidding, blister packs, and flexible barrier applications.
Cans handle the majority of throughput; foil is the fastest mover on share.
Material:
Cost tier differentiation separates commodity inputs from premium alloy specifications.
- Aluminum:Primary and recycled-content aluminum alloys offer infinite recyclability with low embodied energy in reprocessing loops. Beverage can body and end stock specifications dominate consumption, with California's extended producer responsibility framework rewarding mono-material aluminum architectures through preferential fee structures.
- Steel:Tinplate and chrome-coated steel provide structural rigidity for food can double-seaming and industrial drum fabrication.
- Tinplate:Electrolytic tinplate with differential coating weights preserves corrosion resistance in acidic food contact applications.
- Others:Specialty alloys including nickel-plated steel and laminated metal-polymer composites address niche barrier and aesthetic requirements.
Aluminum commands the highest volume position; specialty alloys in Others are expanding most quickly in pharmaceutical blister applications.
End User:
Application-specific performance requirements fragment technical specifications and certification demands.
- Food:Shelf-stable and retort-processed food packaging demands hermetic sealing integrity and migration-compliant interior coatings. Steel can formats retain structural importance, though aluminum substitution accelerates in premium ready-to-eat segments where lightweighting and recyclability scoring influence procurement decisions.
- Beverages:Carbonated soft drinks, craft beer, and sparkling water drive aluminum can specification innovation including ultra-lightweight wall-ironing gauges. The segment exhibits the fastest format conversion velocity as brands displace plastic bottles under EPR framework incentives.
- Cosmetics:Aerosol and general line containers for personal care products emphasize shelf presence and actuation performance.
- Pharmaceuticals:Blister foil lidding and tube formats require barrier precision against moisture and oxygen ingress with FDA-validated coating systems.
Beverages handles the majority of throughput; Pharmaceuticals is climbing the fastest on regulatory-driven barrier specification upgrades.
Packaging Type:
Supply concentration varies dramatically between capital-intensive rigid formats and flexible converting operations.
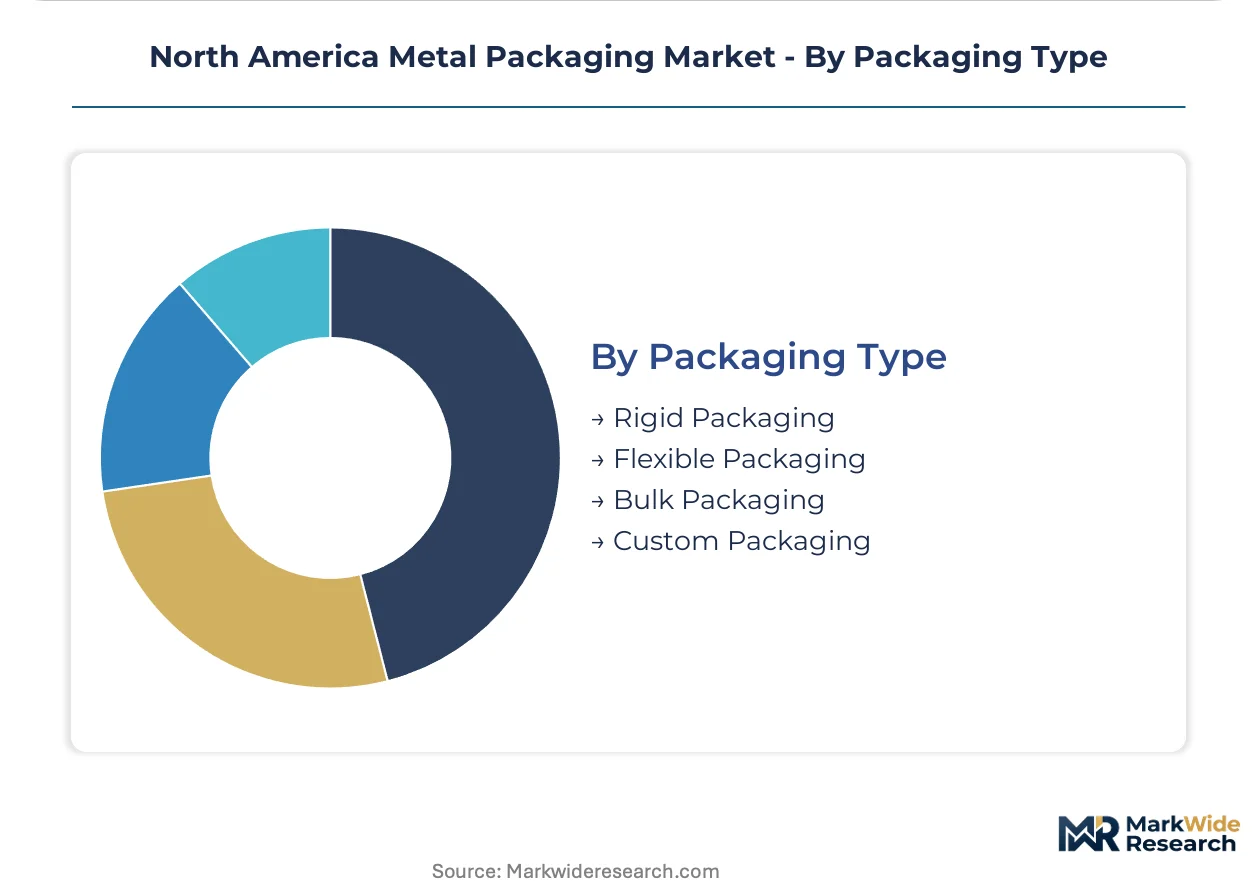
- Rigid Packaging:Formed metal containers including cans, drums, and pails provide structural protection and stackability for liquid and solid contents. Manufacturing clusters concentrate in the US Southeast near beverage production hubs, creating geographic supply vulnerability to regional logistics disruptions.
- Flexible Packaging:Converted foil laminates and lidding materials offer conformability and material efficiency for pharmaceutical and food applications.
- Bulk Packaging:Industrial drums, pails, and intermediate bulk containers serve chemical and agricultural product distribution.
- Custom Packaging:Specialty-configured containers with proprietary geometries or functional features for brand differentiation.
Rigid Packaging handles the majority of throughput; Flexible Packaging is gaining share fastest on pharmaceutical blister foil demand expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility frameworks and deposit-return system expansions are redistributing manufacturing investment across North American jurisdictions. Federal recycling infrastructure allocations and state-level fee structures are creating divergent cost environments for metal packaging producers.
United States
Carbonated soft drink and craft beer producers are accelerating aluminum format conversions in Georgia and North Carolina manufacturing clusters. The EPA's material recovery facility upgrade programs are improving post-consumer aluminum sorting yields in these Southeast hubs. California's recyclability scoring system rewards mono-material aluminum architectures with preferential fee treatment.
Canada
Ontario and Quebec deposit-return system expansions are opening untapped post-consumer aluminum feedstock pools for beverage can producers. Health Canada's food-contact coating regulations govern migration limits for interior epoxy alternatives in metal containers. Prairie Provinces industrial chemical demand sustains steel drum fabrication for agricultural distribution networks.
Mexico
Beverage brand plastic displacement campaigns are driving aluminum can specification adoption among Nuevo León and Jalisco production facilities. The country's national environmental regulator enforces material recovery standards aligned with North American trade integration. Bajío Region automotive supplier parks generate specialty steel container demand for precision component logistics.
North America Metal Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Integrated aluminum supply chain operators and regional converting specialists occupy distinct competitive strata. Three archetypes dominate: vertically integrated beverage can producers, aerosol and food can technology specialists, and general line container scale operators. Capacity expansion near beverage production hubs and coating system simplifications for EPR compliance represent the dominant competitive moves.
Among North American metal packaging producers, Ball Corporation, Crown Holdings, and Silgan Holdings exemplify the three primary strategic archetypes. Ball Corporation anchors the integrated supply chain tier through captive aluminum sourcing capabilities. Crown Holdings occupies the technology-specialist position with concentrated expertise in aerosol and food can formats. Silgan Holdings represents the scale-driven general line segment through manufacturing footprint density and customer co-location strategies.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings, Inc. |
| Ardagh Metal Packaging S.A. |
| Silgan Holdings, Inc. |
| Mauser Packaging Solutions |
| CANPACK S.A. |
| Greif, Inc. |
| Cleveland Steel Container Corporation |
| Great Western Containers Inc. |
| Others |
Value Network & Pricing Analysis
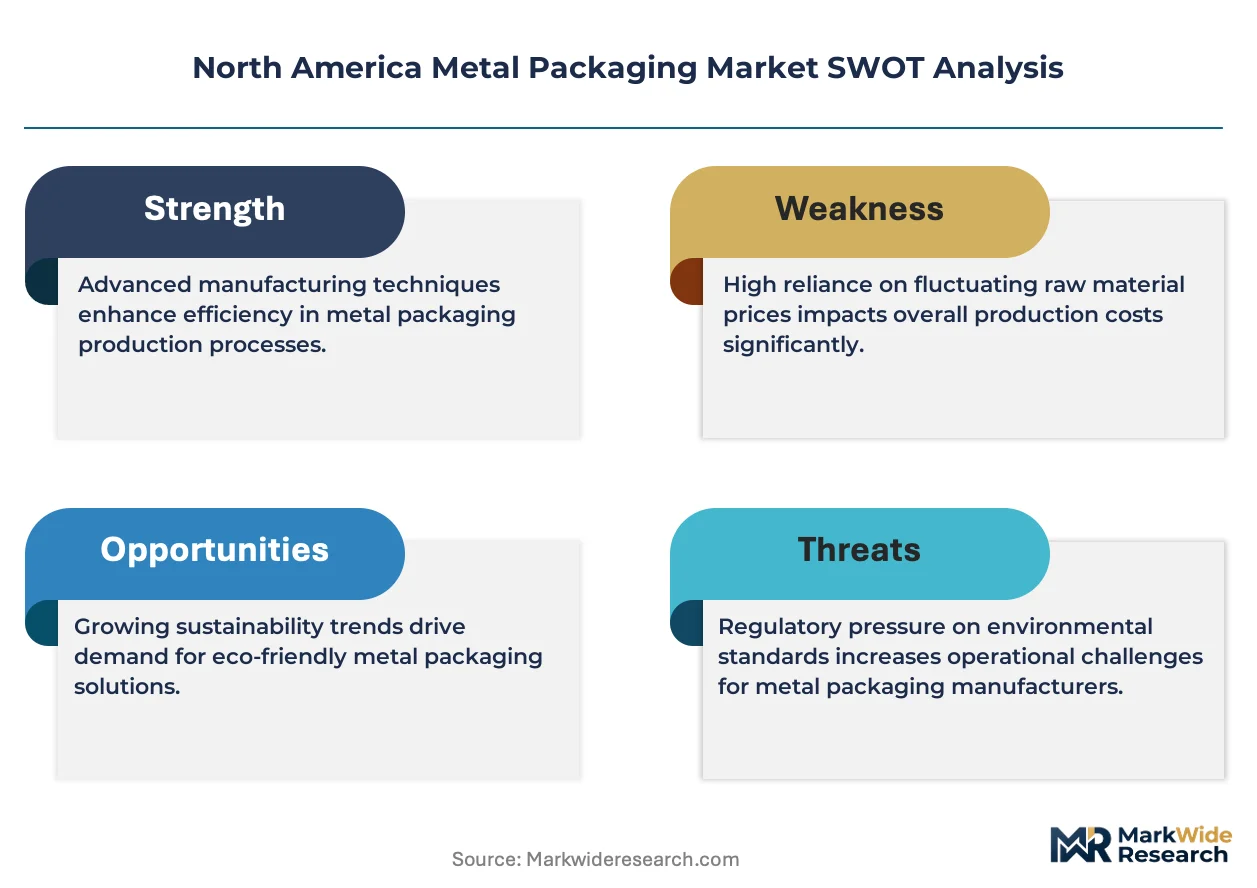
Georgia and North Carolina manufacturing clusters concentrate two-piece aluminum beverage can capacity, granting converters leverage over mid-sized craft breweries seeking format entry without capital ownership. Ball Corporation's integrated aluminum supply chain and Crown Holdings' aerosol specialization create divergent pricing power across end-use segments, while state-level extended producer responsibility frameworks in California, Oregon, and Maine impose fee differentials that reshape procurement economics.
Pricing Analysis
Certification level creates the primary spread, with FDA-validated food-contact coatings and EPA-compliant recycling content claims commanding premiums over general line specifications. Contract-based long-term offtake agreements dominate beverage can procurement, though asset-light equipment leasing is displacing capital purchase models among Southeast craft breweries. Price differentiation reflects volume scale and coating system complexity, with mono-material aluminum architectures qualifying for lower EPR fee tiers in California. Cost compression in standard-grade steel food cans is intensifying because retort pouch substitution erodes volume commitments. Mid-sized beverage brands exhibit highest price sensitivity, while pharmaceutical blister foil buyers prioritize barrier precision over unit economics.
Supply Chain Analysis
Export-control regimes on advanced wall-ironing die technologies limit equipment flows to North American converters, constraining capacity expansion outside established machinery supplier relationships. Primary aluminum supply draws from Canadian smelters and domestic recycling loops, with secondary feedstock availability tethered to deposit-return system recovery yields in Ontario, Quebec, and expanding US state programs. Deep-draw tooling specialist scarcity represents single-source vulnerability as retiring technician cohorts concentrate maintenance expertise. Distribution runs through beverage production hub co-location, with can manufacturing plants positioned within logistics radius of Georgia and North Carolina brewery clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from beverage brand plastic displacement campaigns, which splinter volume across mid-sized craft producers lacking owned can-making capacity and create serviceable niches for contract packaging specialists.
For Market Incumbents: Entrench position through captive aluminum supply arrangements and coating system simplifications that qualify for California's preferential EPR fee tiers. Deepen maintenance technician training pipelines to offset bodymaker specialist scarcity threatening operational continuity. Expand capacity within Georgia and North Carolina clusters to absorb craft brewery volume volatility that contract packagers currently intermediate. For New Entrants and Emerging Players: Asset-light leasing models for can-making equipment represent the most penetrable entry point, enabling mid-sized beverage brands to enter aluminum formats without capital-intensive plant ownership. Canadian deposit-return system expansions in Ontario and Quebec offer untapped post-consumer aluminum feedstock access for secondary alloy positioning. Target pharmaceutical blister foil applications where barrier-precision lidding demands exceed incumbent converter capacity. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underoptimized metal assets, particularly general line container divisions lacking beverage can technology integration. Long-term viability centers on mono-material aluminum architectures aligned with extended producer responsibility frameworks tightening across North American jurisdictions. Watch for deposit-return system adoption waves in additional US states as inflection indicators for secondary feedstock cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Coating System Simplification | Mono-material architectures qualify for California's preferential EPR fee tiers, reducing compliance costs. |
| Technician Training Pipeline Expansion | Deep-draw bodymaker maintenance expertise concentration among retiring cohorts threatens operational continuity. |
| Canadian Feedstock Access Agreements | Ontario and Quebec deposit-return expansions unlock untapped post-consumer aluminum pools for secondary alloy supply. |
| Pharmaceutical Blister Foil Capacity Addition | Barrier-precision lidding demands exceed incumbent converter capacity in FDA-validated coating segments. |
| Equipment Leasing Platform Development | Mid-sized craft breweries seek aluminum format entry without capital-intensive plant ownership commitments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA material recovery facility standards, FDA food-contact coating regulations, state-level extended producer responsibility filings, and aluminum industry trade data. Primary interviews engaged can manufacturing plant managers, beverage brand procurement directors, recycling facility operators, and coating system technical specialists. Secondary validation drew from SEC filings of packaging converters, American Beverage Association sustainability reports, and customs records of aluminum canstock imports. Bottom-up volume triangulation across end-use segments converged with top-down value estimates derived from converter revenue disclosures.
Forecast inputs span product type, material specification, end-use application, packaging format rigidity, and regional regulatory cluster across the analysis window. Segmentation modeling incorporated beverage format conversion velocity, pharmaceutical barrier specification upgrade rates, and steel food can substitution pressure. CAGRs were derived from trend extrapolation of historical volume flows adjusted for regulatory inflection points. Industry-specific inputs included deposit-return system expansion schedules and FDA migration limit testing timelines for epoxy coating alternatives.
Practitioners should monitor state-level extended producer responsibility adoptions and deposit-return system expansions for early signals of secondary feedstock availability shifts. Forecasts reflect assumptions regarding aluminum price volatility ranges and coating qualification cycle durations. Material shifts in federal recycling infrastructure allocation or FDA food-contact coating compliance timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Aluminum Foil Lids Market
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
Metal Containers Market
Metal Packaging
PTP Aluminum Foil Market
Metal Packaging
Tin Cans Market
Metal Packaging
Global Laminated Steel for Cans Market
Metal Packaging
Asia-Pacific Metal Packaging Market
Metal Packaging
Metal Packaging Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
Latin America Metal Packaging Market
Metal Packaging
Europe Metal Cans Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
APAC Food Cans Market
Metal Packaging
Metal Drums Market
Metal Packaging
Aluminum Cans Market