
 Metal Containers Market | 2026-2036
Metal Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Containers Market Outlook
Skilled tool-and-die craftsmanship is collapsing across traditional manufacturing bases, tightening capacity for precision metal forming and slowing new line commissioning. Ball Corporation leverages its integrated aluminum supply chain to sustain North American beverage can output despite labor shortfalls. Crown Holdings anchors European food can production through dedicated tinplate operations in Portugal and Spain. Silgan Holdings differentiates via diverse substrate expertise spanning steel, aluminum, and composite aerosol systems.
Metal containers are rigid, hermetically sealable enclosures fabricated from aluminum, steel, tinplate, or stainless steel through deep drawing, three-piece welding, or two-piece drawing-and-ironing processes, engineered to protect contents from oxidation, contamination, and mechanical damage during storage and distribution. Cans dominate volume consumption in the food and beverage end user segment, where lightweighting and recyclability specifications drive aluminum substitution over steel. Drums and barrels retain structural importance in the chemicals end user segment, where stainless steel variants command premium positioning due to corrosion resistance requirements for solvents and hazardous materials.
EPA hazardous waste container standards, EU REACH substance restrictions, and FDA food contact notifications collectively govern material eligibility, surface coating chemistry, and end-of-life recovery obligations across the major demand jurisdictions. These frameworks elevate compliance costs for tinplate epoxy coatings while accelerating investment in BPA-free and mono-material aluminum solutions. Stakeholders must monitor evolving extended producer responsibility mandates and alloy scrap purity thresholds as these will determine which substrate portfolios retain cost-competitive circularity credentials.
Market Dynamics
Aluminum is systematically displacing tinplate across beverage packaging as recyclability mandates tighten and EPR schemes penalize multi-material complexity, forcing substrate portfolio reconfigurations among legacy steel-can manufacturers.
Growth Catalysts
- EU Green Deal packaging targets:Mandatory recycled content thresholds for metal packaging accelerate aluminum can demand from carbonated beverage processors seeking mono-material compliance pathways.
- China's dual carbon goals:National emissions intensity reductions drive steel drum producers toward electric arc furnace routes and lighter-gauge specifications for chemical logistics.
- Aerosol propellant chemistry advances:Compressed gas systems enable aluminum aerosol expansion into personal care segments previously dominated by tinplate laminated alternatives.
Market Restraints
- Primary aluminum ingot volatility:Smelter energy cost pass-through in China and Europe creates margin compression for two-piece can manufacturers locked into annual supply contracts.
- Tinplate coating chemistry restrictions:REACH Annex XVII limitations on epoxy-phenolic formulations force reformulation investments without immediate price recovery mechanisms.
- Stainless steel scrap purity thresholds:Chemical drum reconditioners face yield losses from cross-contamination detection at European sorting facilities.
Strategic Opportunities
- India beverage canning infrastructure:Underdeveloped aluminum can penetration relative to PET creates white space for cold-chain beverage expansion in Gujarat and Maharashtra.
- Battery electrolyte containment:Lithium-ion supply chain localization demands corrosion-resistant stainless steel intermediate bulk containers for hazardous electrolyte transport.
- Digital printing on metal:Direct-to-shape inkjet integration enables micro-batch craft beverage runs with SKU proliferation economics previously unavailable to aluminum can users.
Industry Challenges
- Tool-and-die craftsmanship attrition:North American and European forming technician retirements outpace apprenticeship completions, delaying new line commissioning and maintenance response times.
- Coating validation timelines:FDA food contact notification reviews for BPA-free epoxy alternatives extend 18-24 months, freezing formulation transitions mid-development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Containers Market |
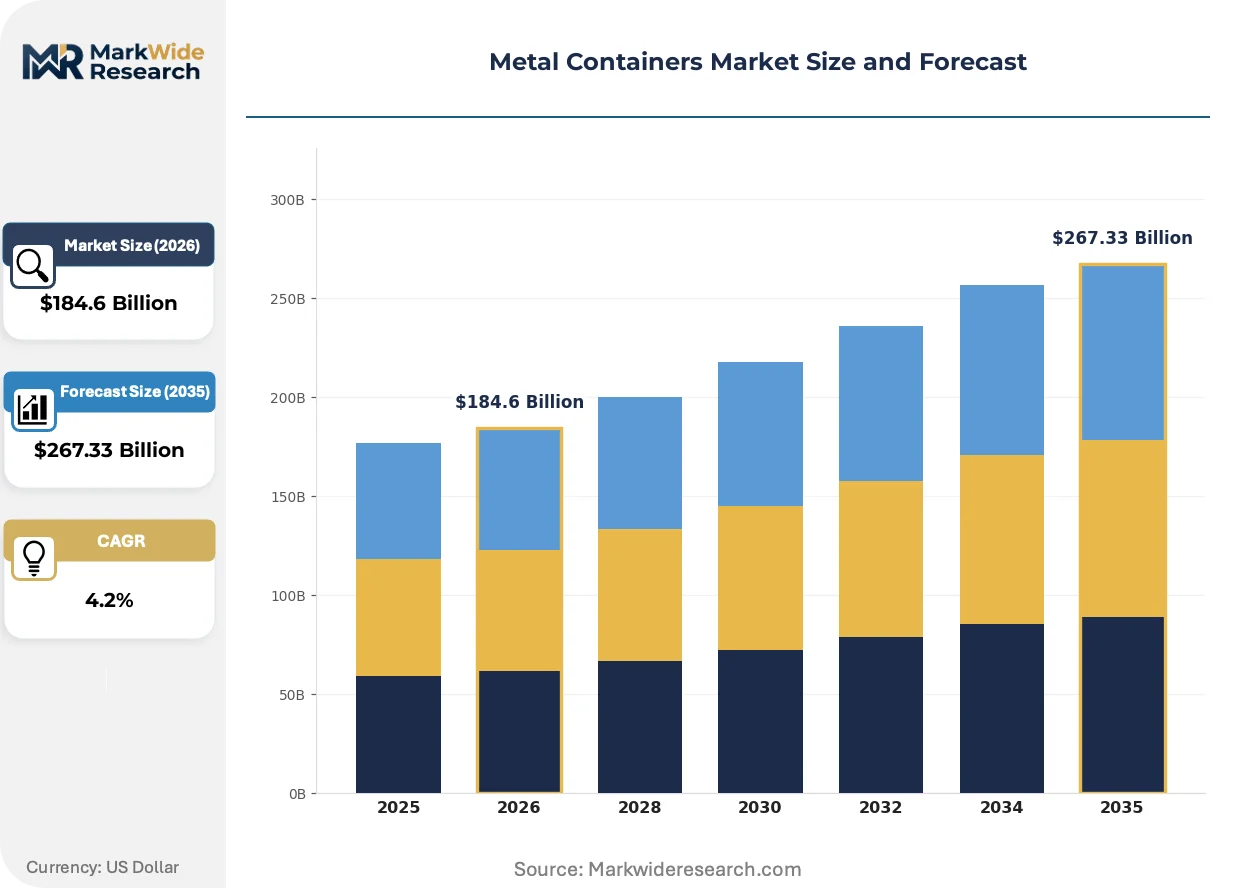
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $267.33 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cans, Drums, Barrels, Cases Material: Aluminum, Steel, Tinplate, Stainless Steel End User: Food & Beverage, Chemicals, Pharmaceuticals, Personal Care Size: Small, Medium, Large, Extra Large |
| Companies Covered | Silgan Holdings Inc., Toyo Seikan Group Holdings, Ltd., Ball Corporation, Kian Joo Can Factory Berhad, CPMC Holdings Limited, Crown Holdings, Inc., Can-Pack S.A., Daiwa Can Company, Ardagh Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Containers Market Strategic Shifts
Digital manufacturing integration and substrate chemistry evolution are compressing batch economics and circularity performance simultaneously, altering competitive differentiation beyond traditional scale advantages.
Two-piece drawing-and-ironing (D&I) aluminum can bodies is supplanting three-piece welded steel construction across mid-range beverage categories. Craft brewers and private-label carbonated water brands in Germany and the United States adopt D&I lines for sub-million-unit annual runs previously uneconomical. This substrate transition compresses minimum efficient scale thresholds and fragments tooling supplier concentration.
REACH substance restriction expansions are tightening epoxy-phenolic coating approvals for tinplate food contact applications. ECHA evaluations of bisphenol analogues force European can makers toward polyester and acrylic alternatives with inferior adhesion performance. Infant formula and acidic vegetable segments face accelerated aluminum substitution timelines as coating reformulation risks accumulate.
Direct-store-delivery beverage distributors are consolidating procurement authority previously held by fragmented regional bottlers. This buyer concentration in the United States and Mexico shifts volume toward integrated aluminum suppliers capable of national logistics coordination and inventory pooling. Smaller steel can fabricators lose shelf placement leverage as distributor technical specifications harmonize.
Metal Containers Market Segmentation
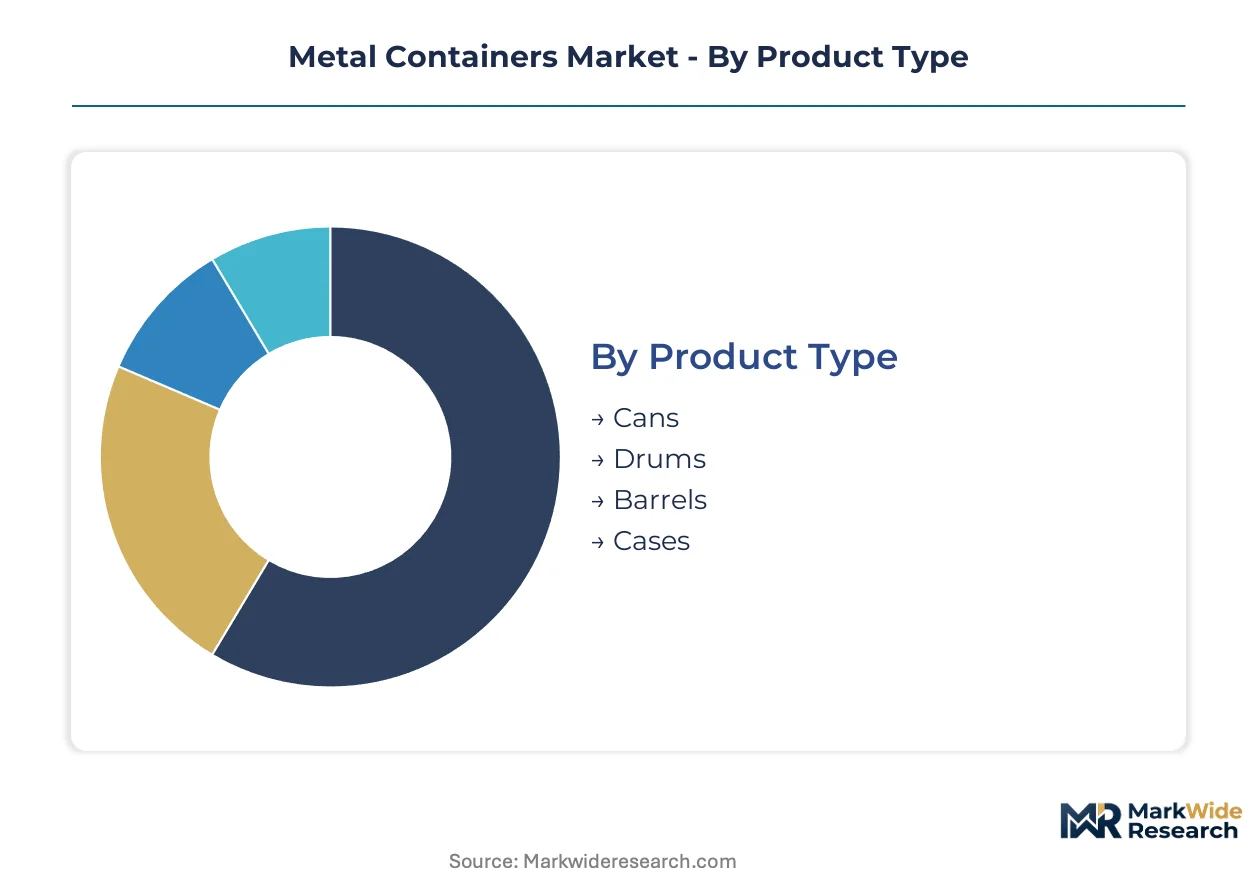
Substrate chemistry, regulatory compliance thresholds, and end-use performance requirements fragment the metal containers market into distinct procurement categories. Procurement managers prioritize material traceability and coating certifications over unit economics in regulated segments.
Product Type:
EPA hazardous waste container standards and FDA food contact notifications govern dimensional tolerances and closure integrity specifications differently across each format.
- Cans:Two-piece drawing-and-ironing aluminum bodies dominate carbonated beverage applications where lightweighting and recyclability mandates converge. Beverage processors in Germany and the United States adopt D&I lines for sub-million-unit craft runs previously uneconomical at this scale.
- Drums:Cylindrical steel or stainless steel vessels with rolling hoops and removable lids serve chemical logistics where UN certification for hazardous materials transport is mandatory. China's steel drum producers are migrating toward electric arc furnace routes and lighter-gauge specifications under national emissions intensity reduction programs.
- Barrels:Large-capacity curved-wall containers with integral rolling hoops store wine, spirits, and specialty chemicals requiring controlled oxidation or inert atmosphere maintenance.
- Cases:Rectangular multi-unit enclosures protect glass bottle clusters during distribution, with tinplate and aluminum variants competing on dent resistance and magnetic separation compatibility in recycling streams.
Established volume favors Cans; emerging adoption favors Drums.
Material:
Cost tier stratification separates premium corrosion-resistant substrates from commodity-recyclable grades.
- Aluminum:Mono-material aluminum solutions command premium positioning in beverage packaging as EU Green Deal packaging targets penalize multi-material complexity. Cold-chain beverage expansion in Gujarat and Maharashtra drives canning infrastructure investment.
- Steel:Three-piece welded construction retains cost advantage in shelf-stable food segments where epoxy-phenolic coating reformulation timelines extend 18-24 months under FDA review.
- Tinplate:Electrolytically coated steel sheet faces REACH Annex XVII limitations on bisphenol analogues, forcing European can makers toward polyester alternatives with inferior adhesion performance.
- Stainless Steel:Austenitic and ferritic grades command premium positioning in chemical drum and pharmaceutical intermediate bulk container applications where corrosion resistance determines asset lifecycle economics.
Commodity recyclability favors Aluminum; corrosion-critical applications favor Stainless Steel.
End User:
Customer type determines specification stringency from food-grade surface finish to hazardous materials UN certification.
- Food & Beverage:Acidic vegetable and infant formula segments face accelerated aluminum substitution timelines as tinplate coating reformulation risks accumulate under ECHA evaluations.
- Chemicals:Lithium-ion battery electrolyte supply chain localization demands corrosion-resistant stainless steel intermediate bulk containers for hazardous electrolyte transport between production and cell assembly facilities.
- Pharmaceuticals:Aseptic fill-finish operations specify electropolished 316L stainless steel drums with validated cleaning protocols and extractables testing documentation.
- Personal Care:Compressed gas propellant chemistry advances enable aluminum aerosol expansion into segments previously dominated by tinplate laminated alternatives.
Volume concentration favors Food & Beverage; steepest expansion trajectory favors Chemicals.
Size:
Supply concentration varies by dimensional category with dedicated tooling for non-standard formats.
- Small:Sub-100ml aluminum and tinplate formats serve single-serve beverage, pharmaceutical, and personal care samples where portability and unit dose accuracy converge.
- Medium:Standard beverage can and food can dimensions dominate procurement volumes with fully amortized forming equipment and established recycling sortation infrastructure.
- Large:200-400 liter steel and stainless steel drums anchor chemical logistics with standardized handling equipment compatibility across rail, road, and maritime intermodal networks.
- Extra Large:Intermediate bulk containers exceeding 1000 liters require custom fabrication for battery electrolyte and specialty chemical applications with limited supplier concentration.
Standardization economics favor Medium; customization premiums favor Extra Large.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: beverage processors in North America and Western Europe prioritize aluminum can lightweighting and recyclability, while chemical logistics in China and India drive steel drum demand for hazardous materials transport.
United States
Beverage canning capacity expansion concentrates in Texas and the Southeast, where cold-chain infrastructure supports craft brewery proliferation. EPA hazardous waste container standards govern steel drum specifications for chemical logistics. Ball Corporation anchors North American aluminum supply through integrated smelter relationships in the Tennessee Valley.
Germany
Carbonated water and craft beverage segments accelerate two-piece drawing-and-ironing adoption for sub-million-unit production runs. EU Green Deal packaging targets mandate recycled content thresholds that penalize multi-material complexity. The Ruhr industrial corridor retains tinplate food can fabrication despite REACH Annex XVII coating chemistry restrictions.
China
Dual carbon goals drive steel drum producers toward electric arc furnace routes and lighter-gauge specifications for chemical logistics. National emissions intensity reduction programs tighten secondary metallurgy standards. Beverage canning capacity clusters in Guangdong and Zhejiang provinces where aluminum sheet rolling mills co-locate with filling operations.
India
Underdeveloped aluminum can penetration relative to PET creates expansion opportunity in Gujarat and Maharashtra cold-chain beverage segments. BIS standards for food contact materials govern substrate eligibility and surface coating migration limits. Steel drum fabrication concentrates in Maharashtra chemical corridors serving pharmaceutical and agrochemical intermediates.
Japan
Aerosol propellant chemistry advances enable aluminum expansion into personal care segments previously dominated by tinplate laminated alternatives. METI circular economy roadmaps elevate mono-material packaging preferences. Kansai region metal forming clusters maintain precision tool-and-die capabilities for pharmaceutical and cosmetic container specifications.
Metal Containers Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with substrate portfolio breadth and geographic footprint determining competitive position. The market structure rewards backward integration into aluminum smelting and rolling capacity, while coating chemistry expertise separates food-grade from industrial-grade competitors. Three archetypes dominate: integrated aluminum suppliers, tinplate specialists with reformulation capabilities, and stainless steel drum fabricators serving chemical logistics. Capacity expansion and strategic partnerships represent the dominant competitive vectors as substrate transitions accelerate.
Among North American integrated suppliers, Ball Corporation exemplifies the aluminum-centric archetype through captive supply chain control. Crown Holdings and Silgan Holdings occupy positions spanning multiple substrate technologies, with the former anchoring European tinplate operations and the latter diversifying across steel, aluminum, and composite aerosol systems. These three represent the tiering logic: scale-driven integration versus substrate flexibility versus regional specialization.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Toyo Seikan Group Holdings, Ltd. |
| Ball Corporation |
| Kian Joo Can Factory Berhad |
| CPMC Holdings Limited |
| Crown Holdings, Inc. |
| Can-Pack S.A. |
| Daiwa Can Company |
| Ardagh Group |
| Others |
Value Chain & Pricing Dynamics
Minimum efficient scale thresholds for two-piece drawing-and-ironing aluminum can lines exceed fifty million units annually, concentrating supply among integrated producers with captive smelter access and compressing price floors for smaller fabricators dependent on merchant aluminum sheet.
Pricing Analysis
Long-term offtake contracts dominate aluminum sheet procurement between beverage can manufacturers and rolling mills, locking in volume commitments that insulate integrated producers from spot market volatility while exposing smaller buyers to energy cost pass-through from Chinese and European smelters. Price differentiation separates corrosion-grade stainless steel drums for chemical logistics from commodity tinplate food cans, with certification tier and geographic delivery cost as primary drivers. Pricing pressure stems from primary aluminum ingot energy cost volatility, with margins tightening for non-integrated fabricators locked into annual supply agreements. Regional bottlers and craft beverage processors exhibit highest price sensitivity, while pharmaceutical and battery electrolyte logistics buyers prioritize corrosion resistance over unit economics.
Supply Chain Analysis
China and Germany anchor global beverage can sheet rolling capacity, with Guangdong and Zhejiang provinces hosting co-located aluminum smelting and forming operations that feed domestic filling plants. The supply chain draws from bauxite refining in Australia and Guinea, primary smelting in China and the Middle East, and precision rolling in Germany and the United States. Single-source vulnerability concentrates in high-purity aluminum alloy supply for battery electrolyte containers, where limited qualified producers create qualification bottlenecks. Distribution runs through direct-store-delivery networks consolidating procurement authority among national beverage distributors, bypassing fragmented regional bottler intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tool-and-die craftsmanship attrition across North American and European forming clusters has collapsed apprenticeship pipelines, creating a capability scarcity that determines which producers can commission new lines and maintain precision tooling.
For Market Incumbents: Shield margin position by securing captive aluminum smelter or rolling mill relationships that insulate against merchant sheet volatility, while accelerating BPA-free coating certification investments ahead of FDA review timelines that freeze competitor reformulations. Prioritize technician apprenticeship programs in Tennessee Valley and Ruhr corridor forming clusters to defend maintenance response capabilities against retirements. For New Entrants and Emerging Players: Differentiate on digital direct-to-shape printing capabilities that enable micro-batch craft beverage runs with SKU proliferation economics previously unavailable to aluminum can users. Target underpenetrated cold-chain beverage segments in Gujarat and Maharashtra where aluminum can infrastructure lags PET penetration. Pursue battery electrolyte intermediate bulk container qualification as lithium-ion supply chains localize. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among stainless steel drum reconditioners serving chemical logistics with long-term service contracts and asset lifecycle management agreements. Long-term viability across the analysis window favors producers with backward integration into aluminum rolling or electric arc furnace steelmaking. Monitor ECHA evaluations of bisphenol analogues as inflection indicators for accelerated tinplate-to-aluminum substitution timelines in infant formula and acidic vegetable segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Smelting | Captive energy cost control insulates margin from Chinese and European power price volatility. |
| BPA-Free Coating Certification Investment | FDA food contact notification approval unlocks premium positioning ahead of REACH-driven competitor freezes. |
| Digital Direct-to-Shape Printing Adoption | Craft beverage micro-batch capability fragments tooling supplier concentration and compresses minimum efficient scale. |
| Electric Arc Furnace Steelmaking Transition | China dual carbon compliance enables lighter-gauge drum specifications with emissions intensity reduction credentials. |
| Battery Electrolyte Container Qualification | Lithium-ion supply chain localization demands corrosion-resistant stainless steel intermediate bulk containers with UN certification. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with beverage procurement directors, chemical logistics fleet managers, pharmaceutical quality assurance leads, and metal forming plant engineers. Secondary validation drew from EPA hazardous waste container filings, ECHA REACH substance restriction updates, FDA food contact notification databases, and customs trade data for aluminum sheet and tinplate imports. Bottom-up volume estimates from end-use segment procurement patterns were triangulated against top-down capacity assessments from rolling mill and drum fabrication facility disclosures.
Across the analysis window, forecasts model substrate substitution dynamics, regulatory compliance tier migration, and geographic production cluster expansion. Segmentation dimensions include product format, material chemistry, end-use industry, and regional regulatory framework. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization trends. Industry-specific inputs incorporate EU Green Deal recycled content mandates and China's dual carbon intensity reduction targets.
The analysis sits within stated boundaries; outcomes outside sustained aluminum price volatility, accelerated REACH substance restrictions, or lithium-ion supply chain localization would require recalibration. Forecasts reflect assumptions on coating reformulation timelines, apprenticeship pipeline recovery, and smelter energy cost pass-through mechanisms. Recalibration cycles align with material shifts in ECHA evaluation schedules and FDA food contact notification approval velocities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Asia-Pacific Metal Packaging Market
Metal Packaging
Middle East and Africa Food Cans Market
Metal Packaging
Collapsible Aluminium Tube Market
Metal Packaging
Middle East and Africa Metal Cans Market
Metal Packaging
Vietnam Metal Can Packaging Market
Metal Packaging
Beverage Metal Cans Market
Metal Packaging
Metal Food Cans Market
Metal Packaging
Novelty Tins Market
Metal Packaging
Cans Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
India Metal Packaging Market
Metal Packaging
Metal Aerosol Packaging Market
Metal Packaging
Germany Metal Packaging Market
Metal Packaging
Thailand Metal Packaging Market
Metal Packaging
APAC Food Cans Market
Metal Packaging
South Africa Metal Packaging Market