
 Packaging Metallization Market | 2026-2036
Packaging Metallization Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Metallization Market Insights
Aluminum oxide coating is hardening as the preferred barrier solution over conventional ethylene vinyl alcohol laminates in high-humidity climates. Amcor leverages captive film extrusion and metallization lines across Southeast Asia to secure cost positions in snack packaging. Mondi sustains leadership in paper-based metallized solutions, competing with plastic-light formats favored by European grocery retailers. Toray Industries dominates Japan's pharmaceutical blister film segment through precision sputtering technology.
Packaging metallization deposits thin metallic or metal-oxide layers onto substrates to create oxygen, moisture, and light barriers measured in angstrom-scale thicknesses, typically employing vacuum chamber processes operating below 10^-4 mbar pressure. The technique serves primarily to extend product shelf life while enabling decorative metallic aesthetics at lower material intensity than full foil laminates. Vacuum metallization occupies the largest share of installed capacity due to its maturity in flexible food packaging, though sputtering is gaining ground in electronics-grade barrier films where pinhole-free uniformity commands premium pricing. Flexible packaging applications absorb the majority of metallized film tonnage, while rigid packaging and labeling segments compete for converter investment based on shorter run lengths and faster design turnover.
The EPA regulates volatile organic compound emissions from solvent-based adhesive lamination lines tied to metallized packaging production in the United States. REACH compliance in Europe restricts certain chromium compounds historically used in decorative metallized coatings, redirecting formulation R&D toward vacuum-deposited aluminum alternatives. The FDA maintains strict extractables and leachables protocols for metallized films contacting pharmaceutical and food products. Stakeholders must monitor evolving extended producer responsibility frameworks that could impose end-of-life recovery obligations on metallized multi-layer structures currently lacking economically viable recycling pathways.
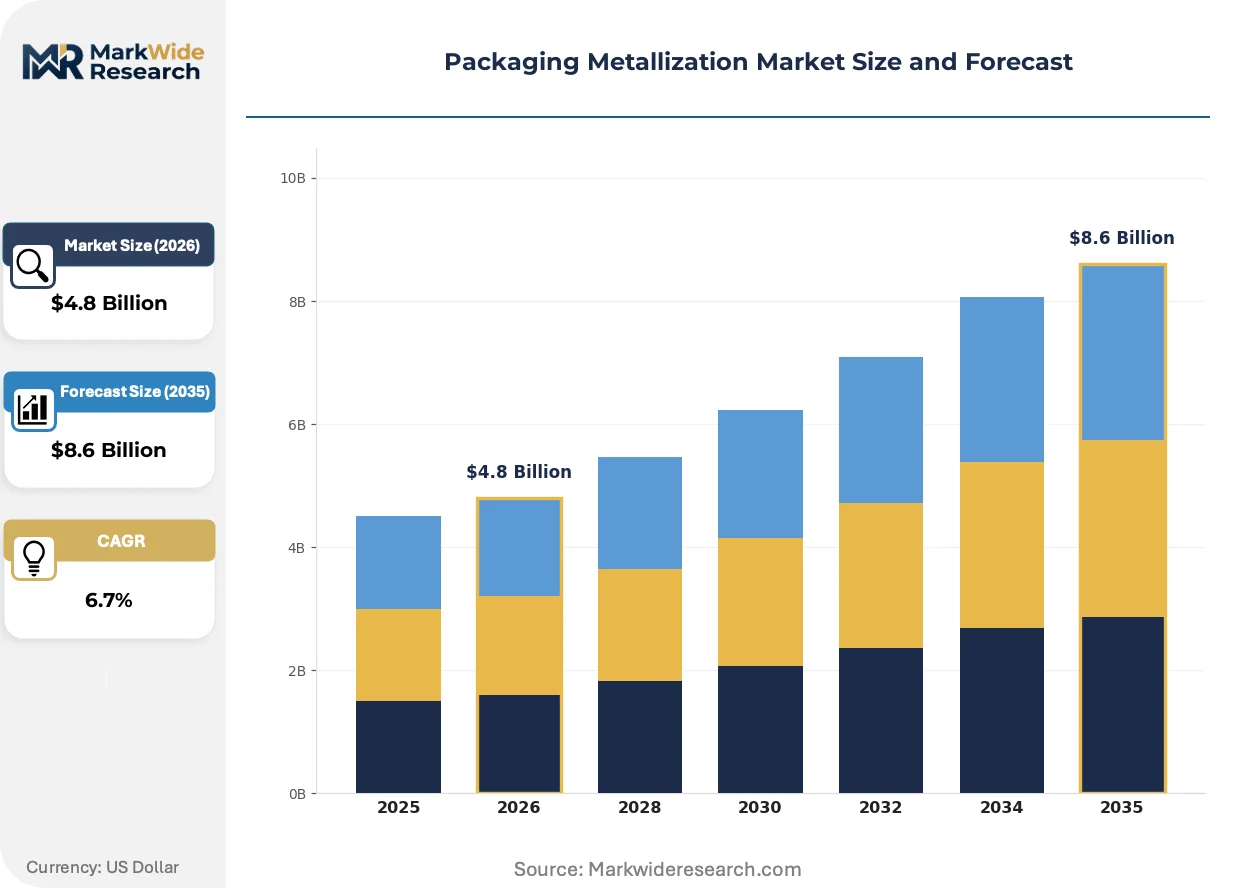
Market Dynamics
The EU F-Gas Regulation is compressing fluorinated barrier film availability and forcing converters toward aluminum oxide metallization as the compliant alternative, reshaping capacity investment patterns across European flexible packaging.
Growth Catalysts
- Aluminum oxide metallization:This vacuum-deposited barrier technology satisfies EU F-Gas Regulation compliance requirements while delivering oxygen and moisture protection equivalent to conventional ethylene vinyl alcohol laminates in high-humidity climates.
- Pharmaceutical blister packaging:Precision sputtering technology enables pinhole-free uniformity demanded by Japan's PMDA extractables and leachables protocols, expanding metallized film penetration in unit-dose pharmaceutical formats.
- Shelf-stable food demand:Snack and confectionery brands in Germany are specifying ultra-high barrier metallized films to replace multi-layer foil structures, reducing material intensity while maintaining 12-18 month shelf stability.
Market Restraints
- Aluminum ingot price volatility:Vacuum metallization consumes high-purity aluminum wire feedstock whose pricing fluctuates with London Metal Exchange spot markets, compressing converter margins during commodity spikes.
- Equipment supply concentration:Vacuum chamber systems operating below 10^-4 mbar pressure are manufactured by a limited supplier base concentrated in Germany and Japan, creating 18-24 month lead times for capacity expansion.
- Multi-layer recycling incompatibility:Metallized polyethylene terephthalate and polypropylene structures lack economically viable mechanical recycling pathways under emerging extended producer responsibility frameworks in France and Italy.
Strategic Opportunities
- Paper-based metallized solutions:European grocery retailers are sourcing plastic-light formats combining metallized paper with water-based coatings to meet packaging reduction targets under the EU Green Deal.
- Southeast Asia snack packaging:Captive film extrusion and metallization lines in Thailand and Vietnam enable cost-competitive supply to ASEAN markets with expanding processed food consumption.
- Electronics-grade barrier films:Sputtering technology convergence with atomic layer deposition is enabling hermetic encapsulation for flexible organic light-emitting diode displays and quantum dot films.
Industry Challenges
- Vacuum technology specialist scarcity:Operating and maintaining sputtering and electron beam metallization equipment requires technicians trained in thin-film physics and ultra-high vacuum systems, a skill set concentrated among aging workforces in Japan and Germany.
- Extractables testing timelines:FDA pharmaceutical contact approvals require 18-36 month extractables and leachables validation protocols, delaying commercialization of new metallized film formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Metallization Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Metallization, Electroplating, Sputtering, Chemical Vapor Deposition Application: Flexible Packaging, Rigid Packaging, Labeling, Decorative Coating Packaging Type: Plastic Films, Paperboard, Glass Containers, Metal Cans End User Industry: Food & Beverage, Personal Care, Pharmaceuticals, Electronics |
| Companies Covered | Amcor, Mondi, Sealed Air, Huhtamaki, Transcontinental, UFlex, Jindal Poly Films, Cosmo First, Toray Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Metallization Market Trends and Innovations
Barrier technology is fragmenting across multiple deposition methods as end-users trade off performance specifications against regulatory compliance and recyclability mandates.
Atomic layer deposition is modularizing barrier film manufacturing by enabling angstrom-scale thickness control of aluminum oxide layers at temperatures compatible with heat-sensitive polymer substrates. Pharmaceutical blister pack converters in Switzerland and Germany are piloting hybrid lines combining roll-to-roll vacuum metallization with spatial atomic layer deposition. This convergence is compressing the performance gap between commodity metallized films and premium sputtered electronics-grade barriers.
REACH compliance restrictions on chromium compounds in decorative coatings are redirecting formulation research toward vacuum-deposited aluminum pigments for cosmetic and luxury goods packaging. The European Chemicals Agency substance evaluation process has flagged specific hexavalent chromium salts historically used in wet metallization processes. Decorative packaging segments in Italy and France are responding by qualifying pure aluminum vacuum deposition for metallic aesthetic effects.
Buyer concentration among European grocery retailers is consolidating metallized film procurement through direct converter relationships and private-label specification ownership. Discount chains in Germany and the Netherlands are bypassing traditional distributor networks to source custom metallized structures with specified barrier properties and recyclability credentials. This disintermediation is visible most acutely in standard snack and confectionery formats where volume scale justifies dedicated production lines.
Packaging Metallization Market Segmentation
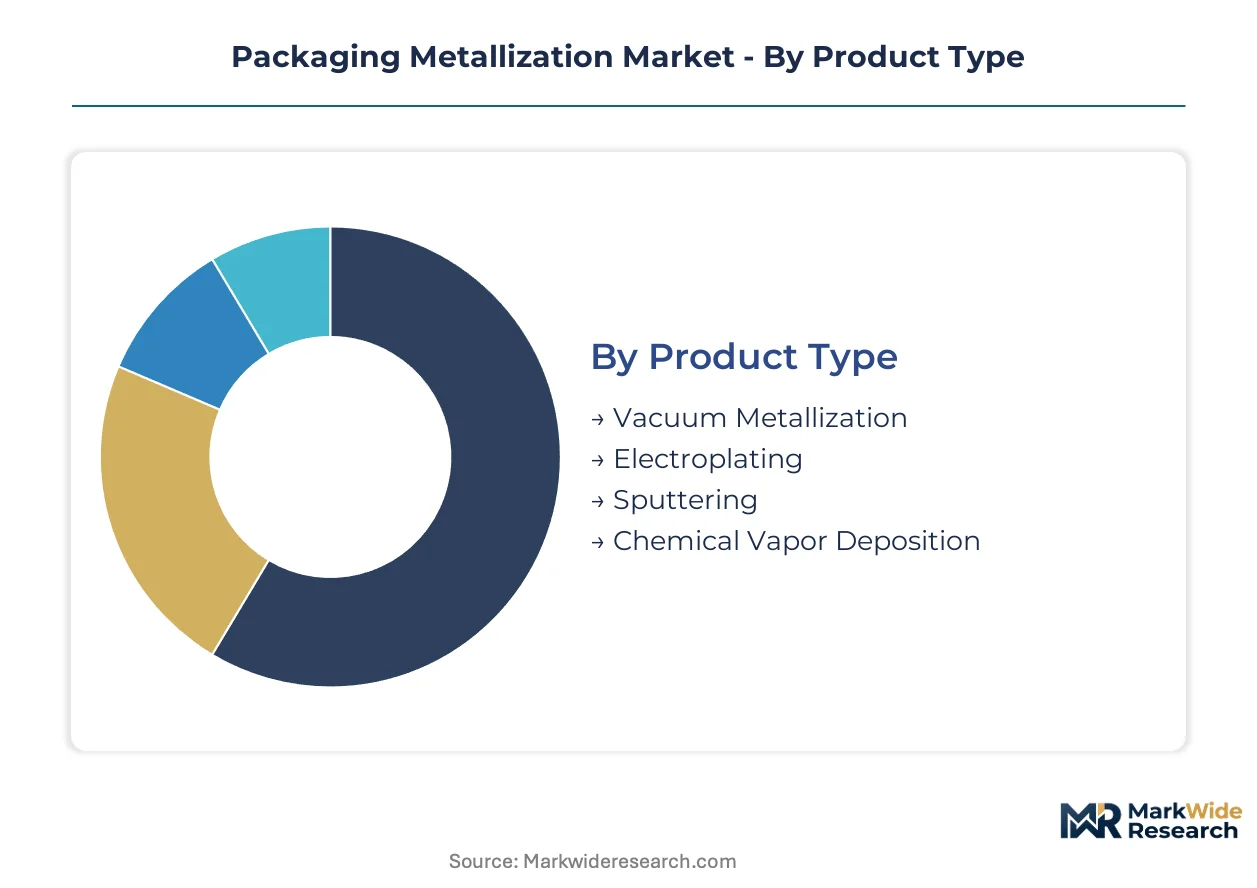
Metallization technology selection determines barrier performance, regulatory compliance, and recyclability credentials across packaging formats. Process chemistry and deposition physics create distinct cost-capability tradeoffs that shape converter procurement strategies and end-user specification patterns.
Product Type:
Deposition physics and chamber pressure regimes differentiate process economics and barrier uniformity.
- Vacuum Metallization:Aluminum evaporation in chambers below 10^-4 mbar dominates flexible food packaging through mature roll-to-roll throughput economics. German and Japanese equipment suppliers command 18-24 month lead times for capacity expansion.
- Sputtering:Ion bombardment of target materials delivers pinhole-free uniformity for pharmaceutical blister films and emerging electronics-grade barriers. Japan's PMDA extractables protocols favor sputtered aluminum oxide for unit-dose pharmaceutical formats.
- Electroplating:Wet chemical deposition of metallic layers serves decorative coating applications with established supply chains in luxury goods packaging.
- Chemical Vapor Deposition:Gas-phase precursor reactions enable conformal coatings on complex geometries for specialized electronics encapsulation.
Mature deployment sits with vacuum metallization. Newer deployment is concentrated in sputtering.
Application:
Run length economics and design turnover velocity determine converter investment allocation across packaging formats.
- Flexible Packaging:Metallized polyethylene terephthalate and polypropylene films absorb the majority of installed metallization capacity for snack, confectionery, and shelf-stable food barriers. EU F-Gas Regulation compliance is redirecting fluorinated barrier film converters toward aluminum oxide metallization.
- Labeling:Shorter run lengths and faster graphic turnover attract converter investment in narrow-web metallization lines serving beverage and personal care brands.
- Rigid Packaging:In-mold and direct-container metallization serves premium cosmetic and spirits applications with higher per-unit value.
- Decorative Coating:REACH restrictions on hexavalent chromium salts are redirecting formulation research toward vacuum-deposited aluminum pigments for cosmetic and luxury goods packaging.
Volume concentration favors flexible packaging. Margin expansion is climbing the fastest in decorative coating.
Packaging Type:
Substrate thermal tolerance and surface energy govern deposition process compatibility and adhesion chemistry.
- Plastic Films:Oriented polypropylene and polyethylene terephthalate webs constitute the primary metallization substrate for barrier packaging. Extended producer responsibility frameworks in France and Italy are creating recycling incompatibility challenges for multi-layer metallized structures.
- Paperboard:Metallized paper with water-based coatings is gaining specification from European grocery retailers targeting plastic-light formats under EU Green Deal packaging reduction targets.
- Glass Containers:Direct-surface metallization serves premium spirits and cosmetic applications with distinctive optical properties.
- Metal Cans:Internal and external decorative metallization supports beverage and food can aesthetics with established coating chemistries.
Installed capacity concentrates on plastic films. Regulatory pressure is accelerating paperboard qualification.
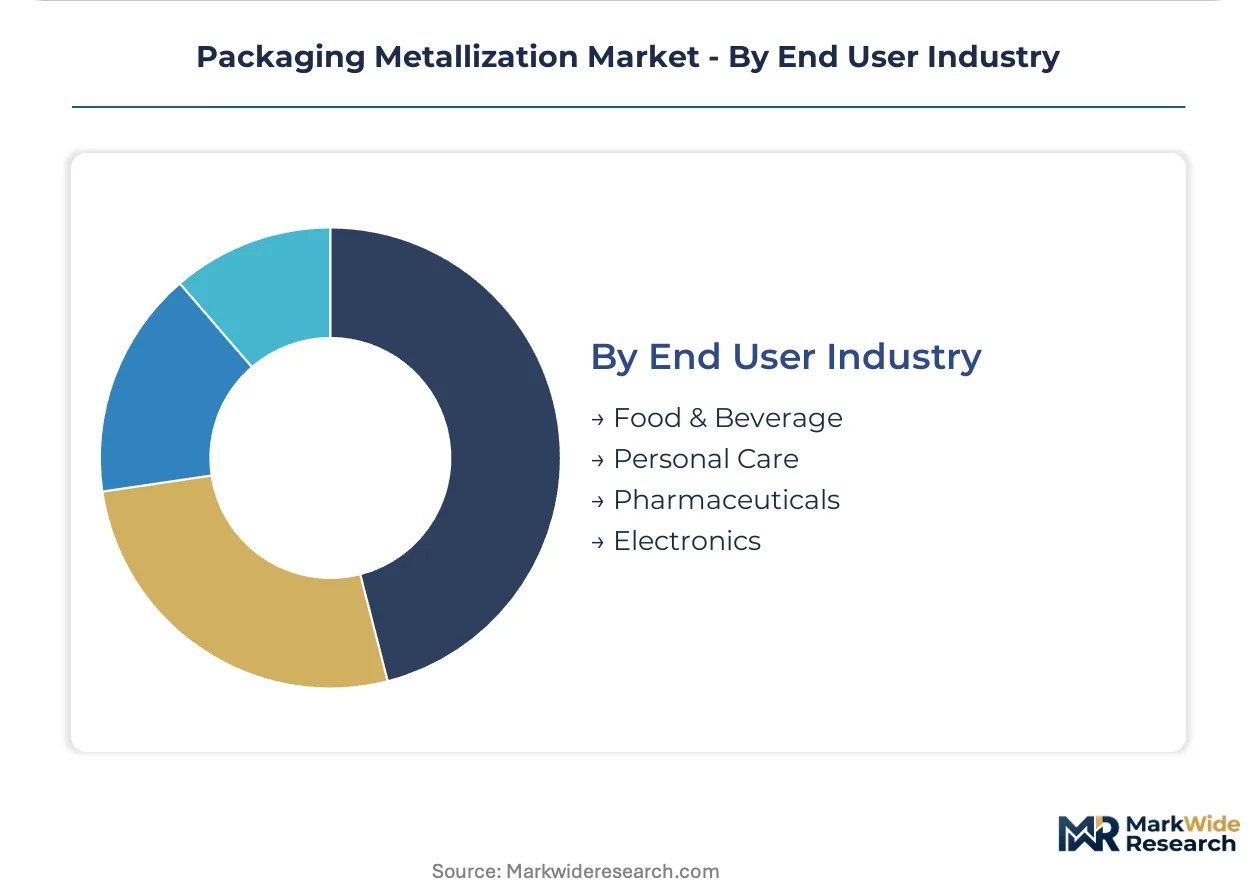
End User Industry:
Shelf stability requirements and extractables protocols create divergent specification intensity across consumer sectors.
- Food & Beverage:Snack and confectionery brands in Germany specify ultra-high barrier metallized films to replace multi-layer foil structures while maintaining 12-18 month shelf stability. Aluminum oxide coating is hardening as the preferred barrier solution over ethylene vinyl alcohol laminates in high-humidity climates.
- Pharmaceuticals:FDA extractables and leachables validation protocols require 18-36 month approval timelines for new metallized film formulations contacting drug products. Toray Industries dominates Japan's pharmaceutical blister film segment through precision sputtering technology.
- Personal Care:Cosmetic and luxury goods packaging demands decorative metallization with REACH-compliant aluminum pigments replacing restricted chromium compounds.
- Electronics:Hermetic encapsulation for flexible organic light-emitting diode displays and quantum dot films is emerging as a high-value sputtering application.
Process standardization is deepest in food and beverage. Specification intensity is steepest in pharmaceuticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for metallized barrier packaging concentrates in Germany, Japan, and the United States, where pharmaceutical blister packs and premium confectionery specifications drive ultra-high barrier film consumption. Regulatory pressure from the EU F-Gas Regulation and REACH compliance frameworks is redirecting converter investment toward aluminum oxide metallization alternatives. Equipment supply chains remain concentrated in German and Japanese manufacturing clusters.
Germany
Premium confectionery and pharmaceutical blister packs require ultra-high barrier metallized films with 12-18 month shelf stability specifications. The EU F-Gas Regulation is compressing fluorinated barrier film availability and forcing converters toward compliant aluminum oxide alternatives. Converter capacity concentrates in the North Rhine-Westphalia industrial corridor around Düsseldorf and Cologne.
Japan
Precision sputtering technology serves PMDA extractables and leachables protocols for unit-dose pharmaceutical formats. METI industrial standards govern vacuum chamber equipment specifications operating below 10^-4 mbar pressure. The Chubu region around Nagoya hosts specialized thin-film equipment manufacturing clusters.
United States
Snack and shelf-stable food brands specify metallized polyethylene terephthalate barriers for extended shelf life in high-humidity distribution environments. EPA regulations constrain volatile organic compound emissions from solvent-based adhesive lamination lines. Flexible packaging converters cluster in the Chicago metropolitan area and Southeast industrial corridors.
Switzerland
Pharmaceutical blister pack converters pilot hybrid lines combining roll-to-roll vacuum metallization with spatial atomic layer deposition. Swissmedic pharmaceutical contact material approvals require rigorous extractables validation protocols. Basel's pharmaceutical manufacturing cluster drives specification intensity for barrier uniformity.
Thailand
Captive film extrusion and metallization lines supply cost-competitive barrier films to ASEAN processed food markets. The country's Board of Investment incentives support packaging sector capacity expansion. Industrial estates around Bangkok and Rayong concentrate converter operations serving regional snack brand demand.
Packaging Metallization Market Competitive Landscape
Capacity expansion dominates the current landscape as converters respond to EU F-Gas Regulation compliance deadlines and pharmaceutical specification upgrades. The vendor base separates into three distinct tiers: integrated multinational packaging groups with captive metallization assets, regional film specialists serving single-market demand, and equipment-technology licensors supplying vacuum chamber systems. Strategic archetypes include backward-integrated converters controlling upstream film extrusion and metallization in single facilities, and technology-differentiated specialists commanding premium pricing for sputtered pharmaceutical-grade barriers. Competitive moves concentrate on geographic expansion into Southeast Asia and portfolio diversification toward paper-based metallized solutions.
Among integrated packaging groups, Amcor exemplifies the backward-integrated archetype with captive film extrusion and metallization lines spanning Southeast Asian markets. Mondi occupies a position within the paper-based metallization tier, competing with plastic-light formats favored by European grocery retailers under EU Green Deal packaging reduction targets. Toray Industries anchors the precision sputtering specialist segment, representing technology-differentiated positioning in pharmaceutical blister film applications where pinhole-free uniformity commands premium pricing.
| Leading Market Players |
|---|
| Amcor |
| Mondi |
| Sealed Air |
| Huhtamaki |
| Transcontinental |
| UFlex |
| Jindal Poly Films |
| Cosmo First |
| Toray Industries |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance deadlines gate qualified supply access and premium-tier pricing power for aluminum oxide metallization capacity serving pharmaceutical blister packs and shelf-stable food formats. Converters with verified barrier performance credentials command pricing premiums while commodity vacuum metallization faces margin compression from aluminum ingot volatility and extended equipment lead times.
Pricing Analysis
Volume concentration in flexible food packaging sits at economy-tier margins while pharmaceutical sputtering and electronics-grade barriers capture premium pricing. Three-tier pricing structure across pharmaceutical-grade sputtering, food-grade vacuum metallization, and decorative coating segments reflects certification intensity and barrier uniformity requirements. Cost compression in standard snack packaging intensifies because buyer consolidation among German and Dutch discount chains concentrates procurement leverage. Food and beverage brand procurement teams exhibit highest price sensitivity; pharmaceutical specification engineers prioritize barrier reliability over unit cost.
Supply Chain Analysis
End-of-life recovery flows for metallized multi-layer structures remain undeveloped, with mechanical recycling incompatibility forcing reliance on emerging chemical recycling pathways and extended producer responsibility fee structures. Equipment manufacturing concentrates in Germany and Japan while aluminum wire feedstock sourcing draws from London Metal Exchange spot markets. Vacuum chamber systems, high-purity aluminum feedstock, and specialized thin-film technicians constitute critical input dependencies. Single-source vulnerability sits with German and Japanese equipment suppliers commanding 18-24 month lead times. Distribution runs through converter direct relationships with European grocery retailers and pharmaceutical contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over captive film extrusion and metallization lines in single facilities determines cost position and barrier quality consistency.
For Market Incumbents: Extend aluminum oxide metallization capacity in Germany and Southeast Asia ahead of EU F-Gas Regulation enforcement deadlines. Secure long-term supply agreements for high-purity aluminum wire feedstock to hedge against London Metal Exchange volatility. Invest in spatial atomic layer deposition pilot lines to defend pharmaceutical barrier pricing against hybrid technology convergence.
For New Entrants and Emerging Players: Begin with paper-based metallized solutions for European grocery retailers executing EU Green Deal packaging reduction targets. Target Swiss and German pharmaceutical blister pack converters seeking secondary sputtering capacity sources. Qualify through Swissmedic extractables validation protocols to establish barrier uniformity credibility.
For Investors and Strategic Acquirers: Equipment supply chain bottlenecks are the leading indicator that vacuum chamber manufacturing specialists command durable scarcity rents. Frame long-term viability around converters integrating upstream film extrusion with downstream pharmaceutical and food brand relationships. Monitor EU extended producer responsibility framework implementation in France and Italy as inflection signals for recyclable metallized structure demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive polypropylene and polyethylene terephthalate supply secures cost positions in ASEAN snack packaging. |
| Aluminum Oxide Metallization Capacity Expansion | EU F-Gas Regulation compliance positions converters for fluorinated barrier film substitution demand. |
| Spatial Atomic Layer Deposition Pilot Investment | Hybrid barrier technology convergence captures pharmaceutical and electronics-grade premium pricing. |
| Paper-Based Metallized Solution Development | EU Green Deal alignment qualifies converters for European grocery retailer plastic-light procurement. |
| Thin-Film Technician Training Program | Japan and Germany workforce aging creates competitive moat for vacuum technology specialist retention. |
Research Methodology
Multi-period observation of aluminum ingot pricing volatility, EU F-Gas Regulation implementation timelines, and pharmaceutical extractables approval durations anchored the trend analysis, supplemented by interviews with vacuum metallization equipment engineers, flexible packaging procurement directors, pharmaceutical quality assurance managers, and thin-film physics researchers. Secondary validation drew from ECHA substance evaluation databases, FDA extractables guidance documents, METI industrial equipment standards, and European Chemicals Agency regulatory filings. Bottom-up capacity modeling triangulated against top-down end-use demand aggregation.
Segment-weighting across metallization technology type, packaging format, substrate material, and end-use industry shaped volume and value projections across the analysis window. Deposition physics maturity curves, regulatory compliance cost differentials, and recycling pathway economics informed CAGR derivation. Industry-specific forecast inputs included pharmaceutical blister pack unit-dose growth trajectories and processed food consumption patterns in ASEAN markets.
Underlying measurement precision varies by segment; pharmaceutical sputtering and electronics-grade barriers carry tighter precision than commodity vacuum metallization for snack packaging. Forecasts reflect assumptions about EU extended producer responsibility implementation pace and aluminum oxide barrier performance equivalence validation. Practitioners should monitor ECHA substance evaluation outcomes and French mechanical recycling infrastructure investments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Europe Food Cans Market
Metal Packaging
Pressurized Metal Containers Market
Metal Packaging
Metal Drums Market
Metal Packaging
Germany Metal Packaging Market
Metal Packaging
Honeycomb Aluminum Foil Market
Metal Packaging
United States Metal Cans Market
Metal Packaging
India Metal Cans Market
Metal Packaging
Aluminium Bottle Market
Metal Packaging
Asia-Pacific Metal Packaging Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
Thailand Metal Packaging Market
Metal Packaging
Middle East and Africa Metal Cans Market
Metal Packaging
Europe Metal Closures Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
Aluminum Cans Market
Metal Packaging
India Metal Packaging Market