
 Child Resistant Bottles Market | 2026-2036
Child Resistant Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Child Resistant Bottles Market Analysis
Pharmaceutical contract packaging demand is consolidating around fewer, larger buyers with multi-site qualification requirements. Berry Global leverages integrated blow-molding and closure capabilities to serve these consolidated accounts. Amcor sustains global film and container supply relationships that anchor its position across regulated markets. Silgan Holdings competes through metal and hybrid closure expertise that meets dual-certification standards.
Child resistant bottles are engineered containers with specialized closure mechanisms requiring coordinated dexterity to open, typically manufactured through injection blow molding or extrusion blow molding with torque-calibrated cap assemblies. Their primary purpose is preventing access by children under five years while maintaining adult usability per standardized testing protocols. Push-and-Turn closures dominate prescription pharmaceutical applications where ASTM certification is mandatory. Plastic resins, primarily HDPE and PP, lead material selection due to chemical compatibility and blow-molding efficiency. The Household Chemicals segment shows faster growth momentum driven by concentrated pod and liquid detergent formats requiring certified packaging.
The US CPSC enforces Poison Prevention Packaging Act compliance through rigorous sixteen-panel child test protocols, while FDA regulations govern pharmaceutical contact materials and container closure system integrity. ISO 8317 and ASTM D3475 provide parallel international and US testing frameworks that manufacturers must navigate for multi-market access. Stakeholders should monitor evolving state-level extended producer responsibility laws and bioplastics certification gaps that could reshape material qualification pathways and testing burdens.
Market Dynamics
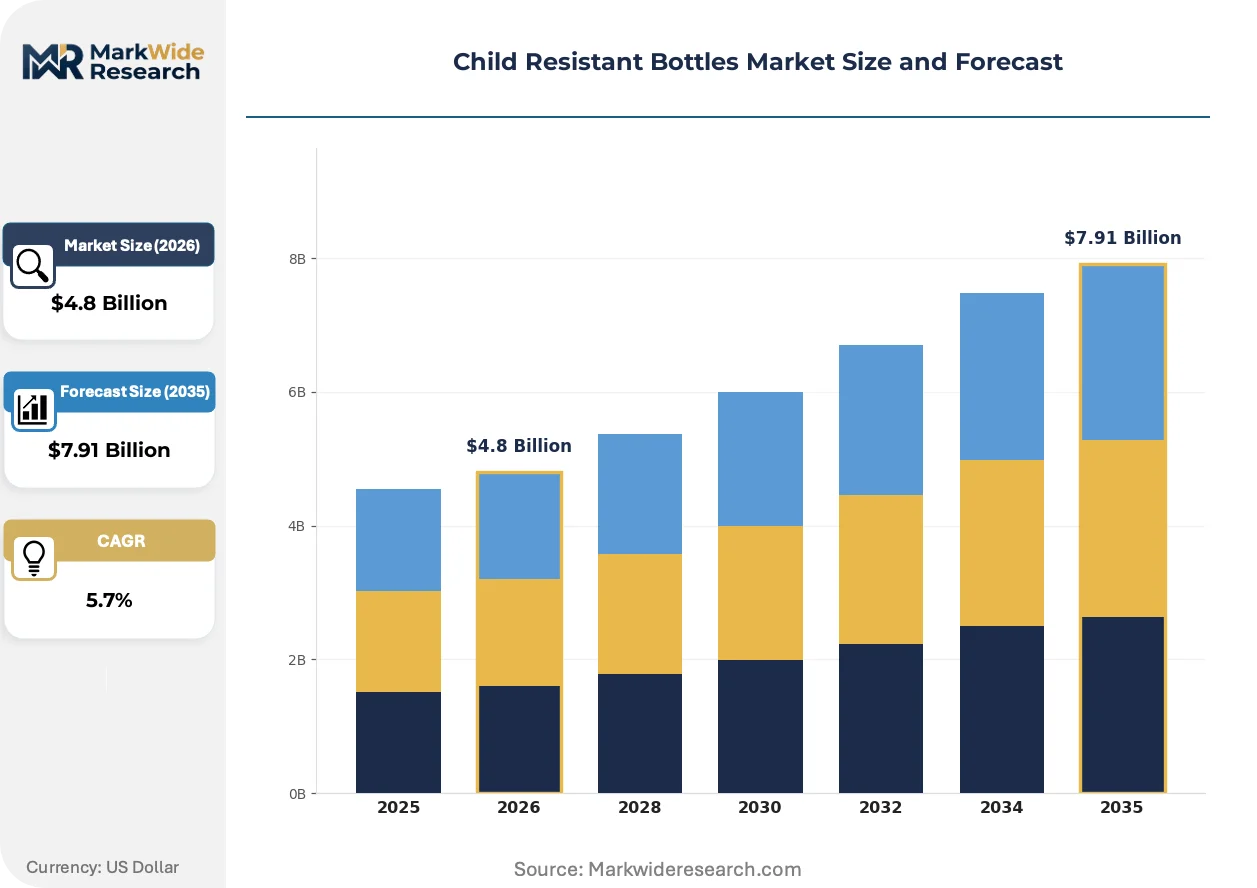
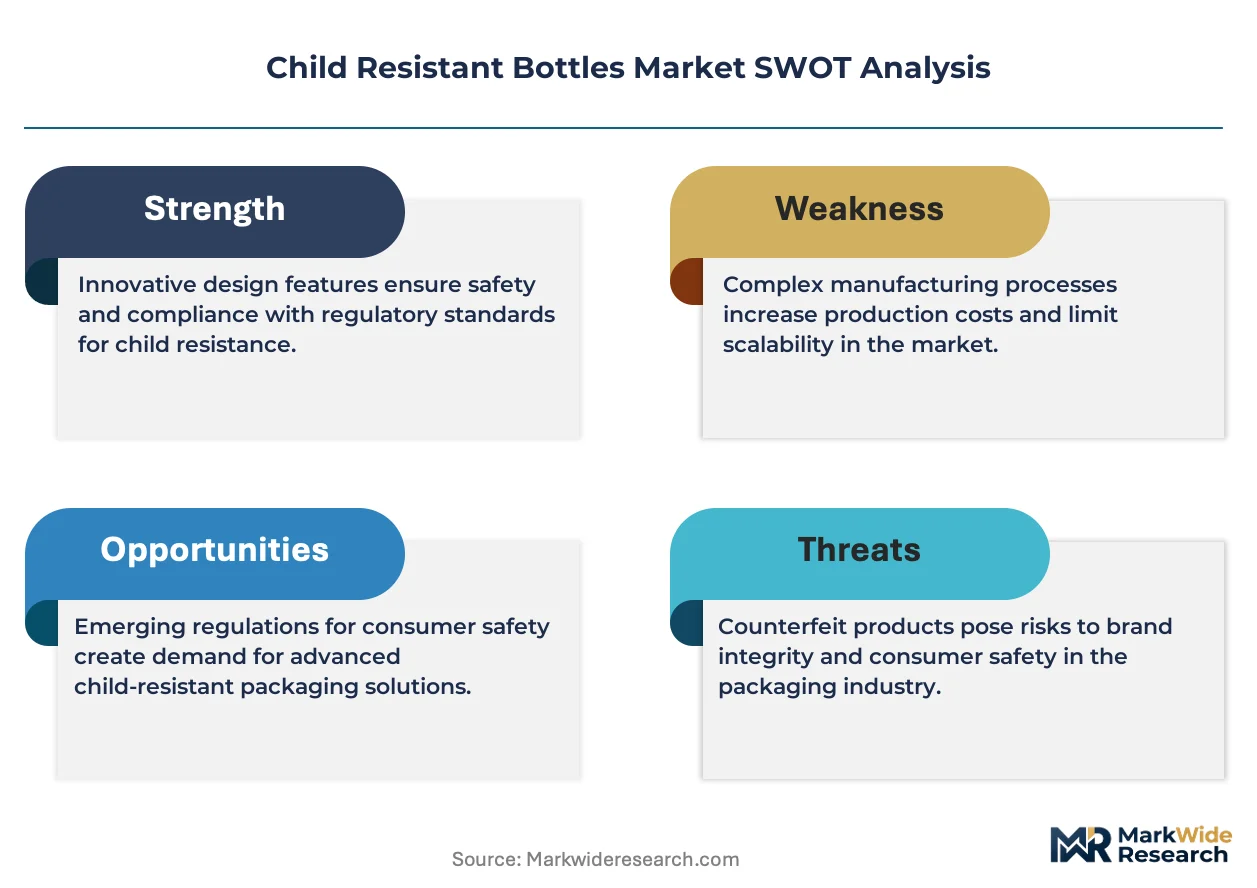
Pharmaceutical contract packaging consolidation is compressing supplier margins while simultaneously raising multi-site qualification barriers that favor integrated blow-molding and closure manufacturers.
Growth Catalysts
- Poison Prevention Packaging Act enforcement:The US CPSC's sixteen-panel child test protocols mandate certified packaging for prescription pharmaceuticals, creating non-negotiable demand for ASTM D3475 compliant closures.
- Concentrated detergent pod formats:Household chemical manufacturers require certified child resistant packaging for liquid laundry pods, expanding addressable volume beyond traditional pharmaceutical applications.
- New Jersey and Pennsylvania manufacturing clusters:North American pharmaceutical corridor concentration generates localized procurement scale that rewards qualified regional suppliers.
Market Restraints
- HDPE resin price volatility:Feedstock cost swings directly compress blow-molding margins and destabilize long-term contract pricing.
- Dual-certification testing burden:Simultaneous ISO 8317 and ASTM D3475 compliance requirements extend product development timelines and raise fixed qualification costs.
- Metal closure supply concentration:Hybrid cap assembly manufacturers face limited qualified torque-calibration component suppliers.
Strategic Opportunities
- Bioplastics certification pathways:Evolving state-level extended producer responsibility laws create first-mover positioning for bio-based HDPE and PP alternatives.
- Pod and liquid detergent segments:Household chemicals show faster growth momentum than mature pharmaceutical channels, rewarding capacity reallocation.
- Direct-to-patient pharmacy fulfillment:E-commerce distribution channels demand single-unit child resistant packaging formats distinct from traditional bulk configurations.
Industry Challenges
- Torque-calibration technician scarcity:Specialized blow-molding process engineers with closure assembly expertise command premium compensation in tight labor markets.
- Legacy equipment retooling costs:Injection blow-molding lines require substantial capital expenditure to accommodate push-and-turn closure dimensional tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Child Resistant Bottles Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Push-and-Turn, Squeeze, Snap-On, Twist-Off Material: Plastic, Glass, Metal, Composite End User: Pharmaceutical, Household Chemicals, Food & Beverage, Cosmetics Certification: ASTM, ISO, FDA, CPSC |
| Companies Covered | Amcor, Berry Global, Silgan Holdings, WestRock, AptarGroup, Gerresheimer, Comar, MJS Packaging, Origin Pharma Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Child Resistant Bottles Market Emerging Trajectories
Material science advances and regulatory harmonization pressures are reconfiguring competitive advantage around certification speed and sustainable resin compatibility rather than pure manufacturing scale.
Post-consumer recycled HDPE is expanding into pharmaceutical-grade bottle applications as chemical compatibilization techniques advance. Major contract packagers now specify minimum recycled content thresholds in procurement tenders. This shift is compressing virgin resin demand while creating new qualification protocols for batch-to-batch consistency.
REACH chemical safety registrations in Europe are tightening migration testing requirements for container closure systems. Manufacturers serving EU markets must maintain parallel documentation streams alongside FDA pharmaceutical contact material filings. Dual-jurisdiction suppliers face disproportionate compliance overhead compared to single-market competitors.
Consolidated buying desks at multi-site pharmaceutical packagers are compressing supplier rosters and extending payment terms. Smaller blow-molding operations find themselves disintermediated as procurement authority centralizes with Berry Global and Amcor-scale integrated suppliers. This concentration is most visible in New Jersey and Pennsylvania corridor negotiations where three buyers control majority volume allocation.
Child Resistant Bottles Market Segmentation
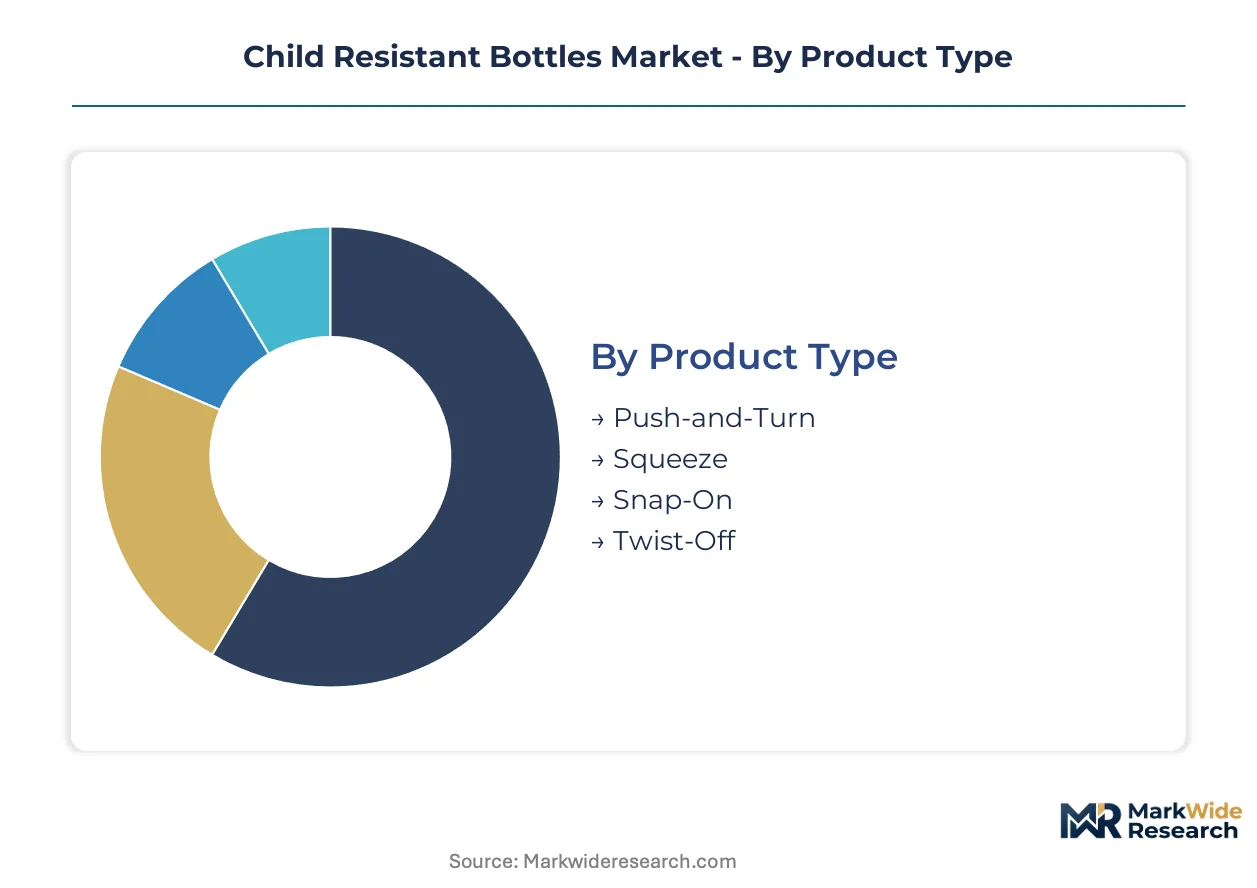
Child resistant bottles require precise alignment between closure mechanism, material compatibility, and regulatory certification. Segmentation reveals how specification choices cascade through manufacturing cost, qualification burden, and end-use access.
Product Type:
Closure engineering defines both child resistance efficacy and adult accessibility compliance.
- Push-and-Turn:The mechanism combines simultaneous downward pressure with rotational torque, creating a two-motion barrier that children under five cannot reliably execute. Pharmaceutical contract packagers in New Jersey and Pennsylvania corridors specify this format for prescription solids and liquids, driving concentrated procurement volume.
- Squeeze:Flexible sidewall compression releases interlocking tabs, requiring grip strength and coordinated finger positioning. Household chemical manufacturers favor this design for liquid laundry pods, where one-handed adult operation during dosing improves user compliance.
- Snap-On:Audible engagement confirms proper closure seating without rotational force, suiting single-use pharmaceutical samples and travel-sized formats where torque calibration is impractical.
- Twist-Off:Threaded engagement with elevated removal torque targets senior-accessible applications where child resistance must balance reduced hand dexterity.
Mature deployment sits with Push-and-Turn. Newer deployment is concentrated in Squeeze.
Material:
Resin selection governs blow-molding throughput, chemical migration resistance, and post-consumer recyclability.
- Plastic:HDPE and PP dominate through injection blow-molding efficiency and broad pharmaceutical compatibility. Post-consumer recycled HDPE is gaining specification in contract packager tenders as chemical compatibilization advances.
- Glass:Borosilicate and amber soda-lime formats serve parenteral and light-sensitive formulations where polymer permeability is unacceptable. Premium positioning limits volume to high-value biologics.
- Metal:Aluminum bottles with hybrid closure assemblies address solvent-based household chemicals where plastic stress cracking occurs.
- Composite:Multi-layer coextrusions or metallized films combine barrier performance with lightweighting, emerging in cannabis packaging where odor containment and child resistance converge.
Volume concentrates in Plastic. Fastest specification growth is occurring in Composite.
End User:
Application-driven requirements diverge sharply on certification stringency, batch size, and shelf-life demands.
- Pharmaceutical:FDA container closure system integrity and US CPSC Poison Prevention Packaging Act compliance create dual-jurisdiction qualification. New Jersey and Pennsylvania manufacturing clusters anchor North American demand.
- Household Chemicals:Concentrated detergent pods and liquid formulations require ASTM-certified packaging under CPSC enforcement, with faster volume expansion than mature pharmaceutical channels.
- Food & Beverage:Cannabis-infused edibles and high-potency supplements drive child resistant specification in jurisdictions with product-specific packaging mandates.
- Cosmetics:Premium skincare with retinol or acid concentrations adopts certified closures for liability protection, though regulatory pressure remains lighter than pharmaceutical or chemical categories.
Procurement scale favors Pharmaceutical. Steepest expansion trajectory is occurring in Household Chemicals.
Certification:
Testing protocol selection determines market access breadth and development timeline.
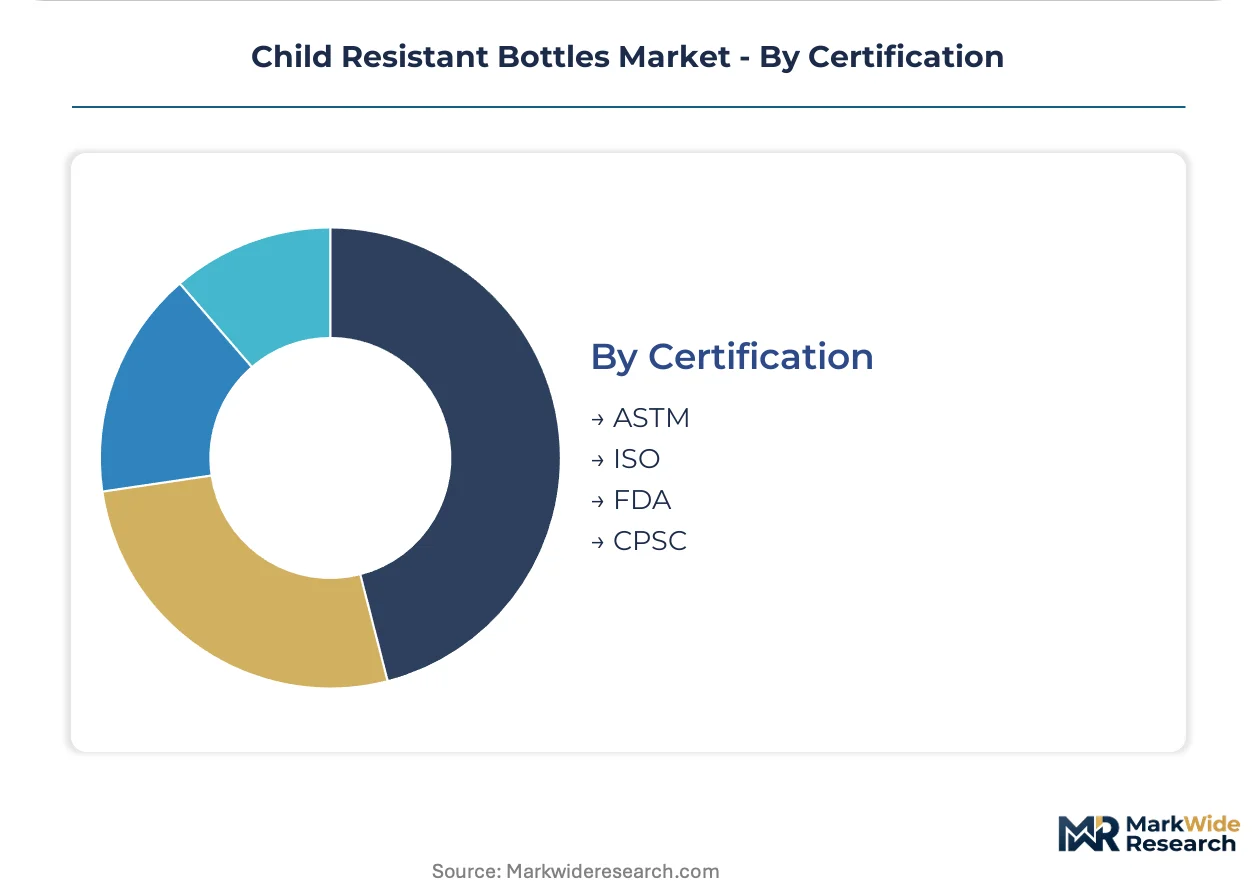
- ASTM:The US CPSC references ASTM D3475 for Poison Prevention Packaging Act compliance, with sixteen-panel child testing mandatory for prescription pharmaceuticals. Domestic market access requires this certification.
- ISO:ISO 8317 provides parallel international framework, essential for EU and Asia-Pacific market entry. Dual certification extends qualification timelines but unlocks multi-regional supply contracts.
- FDA:Container closure system integrity and pharmaceutical contact material compliance govern drug product approval, separate from child resistance testing but equally mandatory.
- CPSC:Direct enforcement authority for household chemical packaging creates distinct regulatory pathway from FDA-governed pharmaceutical applications.
Baseline requirement sits with ASTM. Multi-market positioning demands ISO.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract packaging demand concentrates in manufacturing corridors where FDA and CPSC jurisdictions overlap with dense supplier networks.
United States
New Jersey and Pennsylvania anchor North American procurement volume for ASTM D3475 certified push-and-turn closures. The US CPSC enforces sixteen-panel child testing protocols under the Poison Prevention Packaging Act. Philadelphia and Camden manufacturing clusters host integrated blow-molding operations serving consolidated pharmaceutical packagers.
Germany
REACH chemical safety registrations tighten migration testing requirements for container closure systems serving EU pharmaceutical markets. The EMA governs container integrity standards parallel to FDA filings. North Rhine-Westphalia's Düsseldorf-Cologne corridor concentrates blow-molding capacity for dual-certified export production.
China
NMPA pharmaceutical contact material regulations drive domestic certification demand for HDPE and PP bottle formats. GB standards align with ISO 8317 testing frameworks for international market access. Yangtze River Delta manufacturing zones around Shanghai supply contract packagers with torque-calibrated closure assemblies.
India
CDSCO container closure system guidelines create qualification pathways for export-oriented pharmaceutical packaging. The country's national pharmaceutical regulator harmonizes testing with ASTM protocols for US-bound shipments. Gujarat and Maharashtra industrial corridors host blow-molding operations supplying both domestic and contract manufacturing organizations.
Switzerland
Swissmedic pharmaceutical packaging requirements emphasize batch-to-batch consistency for high-value biologics. The country's regulatory framework accepts parallel ISO 8317 and ASTM D3475 certifications. Basel's pharmaceutical cluster demands premium child resistant formats for parenteral and light-sensitive formulations.
Child Resistant Bottles Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue bioplastics certification and direct-to-patient e-commerce formats. The supplier base compresses around integrated blow-molding and closure manufacturers capable of multi-site qualification. Three archetypes dominate: integrated resin-to-closure conglomerates, specialized torque-calibration component suppliers, and regional blow-molding operations serving single-market packagers. Consolidated buying desks extend payment terms while compressing supplier rosters; capacity expansion and backward integration into resin compounding represent the dominant competitive vectors.
Within the integrated conglomerate tier, Amcor and Berry Global exemplify scale-driven positioning across regulated markets. Silgan Holdings occupies a specialist position in hybrid closure assemblies. These three anchors represent contrasting approaches to multi-jurisdiction certification burden and consolidated pharmaceutical procurement consolidation.
| Leading Market Players |
|---|
| Amcor |
| Berry Global |
| Silgan Holdings |
| WestRock |
| AptarGroup |
| Gerresheimer |
| Comar |
| MJS Packaging |
| Origin Pharma Packaging |
| Others |
Supply Flow & Price Mechanics
Torque-calibration technician scarcity in the New Jersey and Pennsylvania pharmaceutical corridor widens pricing-tier spreads between integrated blow-molding operations and regional component suppliers. Labor-cost differentials between certified closure engineers and standard blow-molding operators translate directly into premium positioning for dual-certification manufacturers.
Pricing Analysis
Volume concentrates in contract-based long-term offtake agreements with multi-site pharmaceutical packagers, while margins accrue to manufacturers with captive closure-assembly capabilities. Price differentiation separates ASTM-only certified suppliers from dual ISO 8317 and ASTM D3475 qualified producers, with certification tier and volume scale as primary drivers. Cost compression in standard HDPE bottle grades is intensifying as post-consumer recycled resin specifications advance, though premium bioplastics-certified formats retain pricing power. Consolidated buying desks at three major packager groups exhibit lowest price sensitivity; single-site regional blow-molders face highest procurement pressure.
Supply Chain Analysis
Workforce-availability constraints in North Rhine-Westphalia's Düsseldorf-Cologne corridor and the Yangtze River Delta around Shanghai limit qualified torque-calibration capacity expansion. Supply concentrates in the United States, Germany, and China for integrated resin-to-closure production, with India emerging for export-oriented contract manufacturing. Raw material dependencies rest on HDPE and PP resin feedstocks, torque-calibrated metal closure components, and chemical compatibilizers for recycled content batches. Single-source vulnerability in qualified hybrid closure assemblies creates supply chain risk. Distribution runs through direct procurement relationships with consolidated pharmaceutical packagers and household chemical brand owners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-consumer recycled HDPE compatibilization technology is displacing virgin resin specifications in pharmaceutical-grade applications, compressing legacy material pathways while opening certification-first positioning for advanced recyclers.
For Market Incumbents: Acquire torque-calibration engineering teams and closure-assembly equipment pools to defend against bioplastics-certified entrants and backward-integrated resin compounders. Secure multi-site qualification status with consolidated New Jersey and Pennsylvania pharmaceutical packagers before procurement rosters finalize. Capacity addition in Germany's North Rhine-Westphalia corridor anchors EU market access under REACH migration testing requirements. For New Entrants and Emerging Players: Bioplastics certification speed serves as the primary technology-first wedge against established virgin-resin incumbents. Target household chemical pod and liquid detergent segments where ASTM D3475 compliance creates faster qualification pathways than dual-jurisdiction pharmaceutical standards. Direct-to-patient e-commerce single-unit formats represent the most penetrable white-space, with go-to-market execution through pharmacy fulfillment platform partnerships. For Investors and Strategic Acquirers: Re-rating potential sits with integrated blow-molding and closure manufacturers given procurement consolidation catalysts and bioplastics certification gaps. Long-term viability favors suppliers with backward integration into resin compounding and captive torque-calibration technician pipelines. Watch state-level extended producer responsibility law passage as inflection indicator for bio-based HDPE and PP demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Bioplastics Certification Investment | First-mover positioning under evolving state EPR laws creates material qualification barriers for virgin-resin competitors. |
| Backward Integration into Resin Compounding | Captive post-consumer recycled HDPE supply secures batch-to-batch consistency for pharmaceutical contract packager tenders. |
| Dual-Certification Testing Infrastructure | Parallel ISO 8317 and ASTM D3475 capability unlocks multi-regional supply contracts with consolidated pharmaceutical buyers. |
| Direct-to-Patient E-Commerce Format Development | Single-unit child resistant packaging addresses pharmacy fulfillment channel requirements distinct from bulk configurations. |
| Torque-Calibration Technician Training Programs | Specialized closure assembly expertise commands premium compensation in tight labor markets across manufacturing corridors. |
Methodological Framework
Independent corroboration across pharmaceutical contract packaging executives, blow-molding operations managers, regulatory affairs specialists, and resin procurement leads underwrites the qualitative findings. Secondary validation drew from FDA container closure system filings, US CPSC enforcement actions, EMA submissions, and REACH registration databases. Bottom-up volume estimates from individual manufacturing facility capacities triangulated against top-down pharmaceutical and household chemical packaging demand projections.
Rate-of-change decomposition across closure mechanism type, material grade tier, end-use application, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth trajectories weighted by procurement volume concentration in identified manufacturing corridors. Forecast inputs incorporated resin price elasticity assumptions, certification timeline distributions, and packager consolidation patterns across the projection horizon.
Several conditions sit outside the modeled scope, including unannounced regulatory harmonization between FDA and EMA testing protocols, breakthrough bioplastics cost parity events, and abrupt resin feedstock supply disruptions. Forecasts reflect assumptions about technician training pipeline expansion and recycled content specification adoption curves. Material deviation in state EPR law implementation schedules, CPSC enforcement intensity, or pharmaceutical packager merger completion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Insulated Food Containers Market
Packaging Containers
Pump Dispenser Market
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Bottles Market
Packaging Containers
Dispensing Trays Market
Packaging Containers
Shipping Mailers Market
Packaging Containers
Global Acrylic Airless Bottle Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Telescope Box Market
Packaging Containers
Global Food Re Close Pack Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Eyewear Packaging Market
Packaging Containers
North America Food Cans Market
Packaging Containers
Insulated Storage Vessel Market
Packaging Containers
VCI Bags Market
Packaging Containers
Pillow Pack Packaging Market