
 Aluminum Foil Lids Market | 2026-2036
Aluminum Foil Lids Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Foil Lids Market Outlook
Asian aluminum rolling capacity is rebalancing as Chinese smelters redirect output toward value-added foil products. Amcor Limited leverages its integrated beverage and food packaging network to secure long-term dairy processor contracts. Constantia Flexibles anchors European pharmaceutical blister lid supply through specialized cleanroom manufacturing in Austria and Germany. Huhtamaki Oyj competes in emerging markets with localized pre-cut lid production tailored to regional cup formats.
Aluminum foil lids are thin-gauge aluminum sheets, typically 20-40 micrometers thick, laminated with heat-seal coatings to create peelable or weld-sealed closures for rigid containers. Manufacturers produce these lids through cold rolling, annealing, and coating processes that control temper, thickness uniformity, and seal integrity against plastic, paper, or aluminum cups. Multi-layer constructions incorporating polyester or polypropylene films command premium positioning in pharmaceutical blister packs where moisture and oxygen barrier performance determines shelf stability. Food packaging applications dominate volume, though cosmetic and industrial segments sustain margin pools through smaller-batch custom printing and die-cut specifications.
FDA food-contact substance regulations and EU REACH compliance frameworks govern coating chemistries and migration limits for aluminum foil lids in consumer applications. Germany's national packaging regulator enforces strict dual-system recycling participation that shapes material recovery obligations for lid suppliers operating across European markets. Stakeholders must monitor evolving extended producer responsibility schemes and substrate-lightweighting mandates that could accelerate substitution toward fiber-based or mono-material alternatives in select packaging categories.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design freedom for multi-layer foil constructions while simultaneously creating premium positioning for compliant mono-material alternatives. German dairy processors and pharmaceutical blister manufacturers now face dual-system recycling participation mandates that reshape supplier qualification criteria.
Growth Catalysts
- PPWR recyclability mandates:The EU Packaging and Packaging Waste Regulation forces substrate-lightweighting redesigns that favor aluminum foil lids with improved separability, accelerating premium lid adoption across German and French food processing clusters.
- Centralized dairy processing concentration:North American co-manufacturing consolidation drives standardized cup-and-lid format adoption, creating volume pull for pre-cut lid suppliers with multi-site supply capability.
- Pharmaceutical blister expansion:Moisture-sensitive biologic drug proliferation in European markets demands high-barrier aluminum-polyester laminate lids with validated seal integrity protocols.
Market Restraints
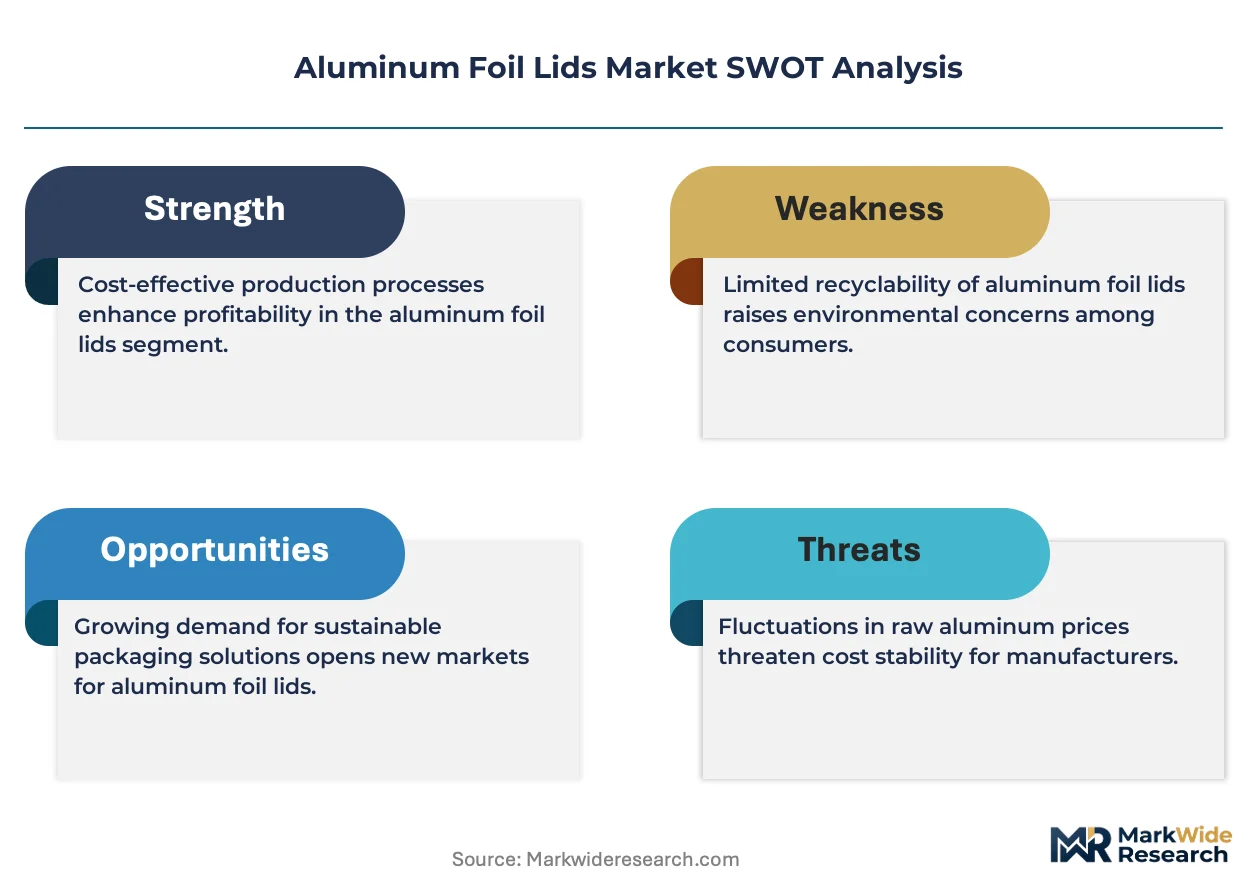
- Aluminum ingot price volatility:LME aluminum price swings transmit directly to foil lid converter margins, compressing profitability during energy-cost spikes at European smelters.
- Chinese rolling capacity concentration:Asian foil substrate supply concentrates among integrated aluminum conglomerates, creating single-source risk for European lid laminators lacking backward integration.
- Fiber-based substitution threat:Molded fiber lid prototypes from Scandinavian packaging developers threaten peelable foil dominance in ambient yogurt segments where barrier requirements moderate.
Strategic Opportunities
- Indian organized dairy emergence:India's cooperative dairy sector modernization creates first-mover advantage for lid suppliers establishing localized die-cutting operations in Gujarat and Maharashtra processing clusters.
- Cleanroom pharmaceutical expansion:Austria and Germany's specialized aseptic manufacturing zones demand validated cleanroom-produced blister lids with documented particulate control.
- Laser micro-perforation convergence:Integration of laser scoring with intelligent seal-strength detection enables controlled peel-force lids for aging-population pharmaceutical compliance.
Industry Challenges
- Migration testing timeline compression:EU REACH food-contact notification protocols extend new coating chemistry validation to 18-24 months, delaying product launches for reformulated heat-seal layers.
- Legacy thermoformer integration:Dairy processors running 1990s-era cup-forming equipment face retrofit complexity when adopting next-generation lid materials with modified seal-initiation temperatures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Foil Lids Market |
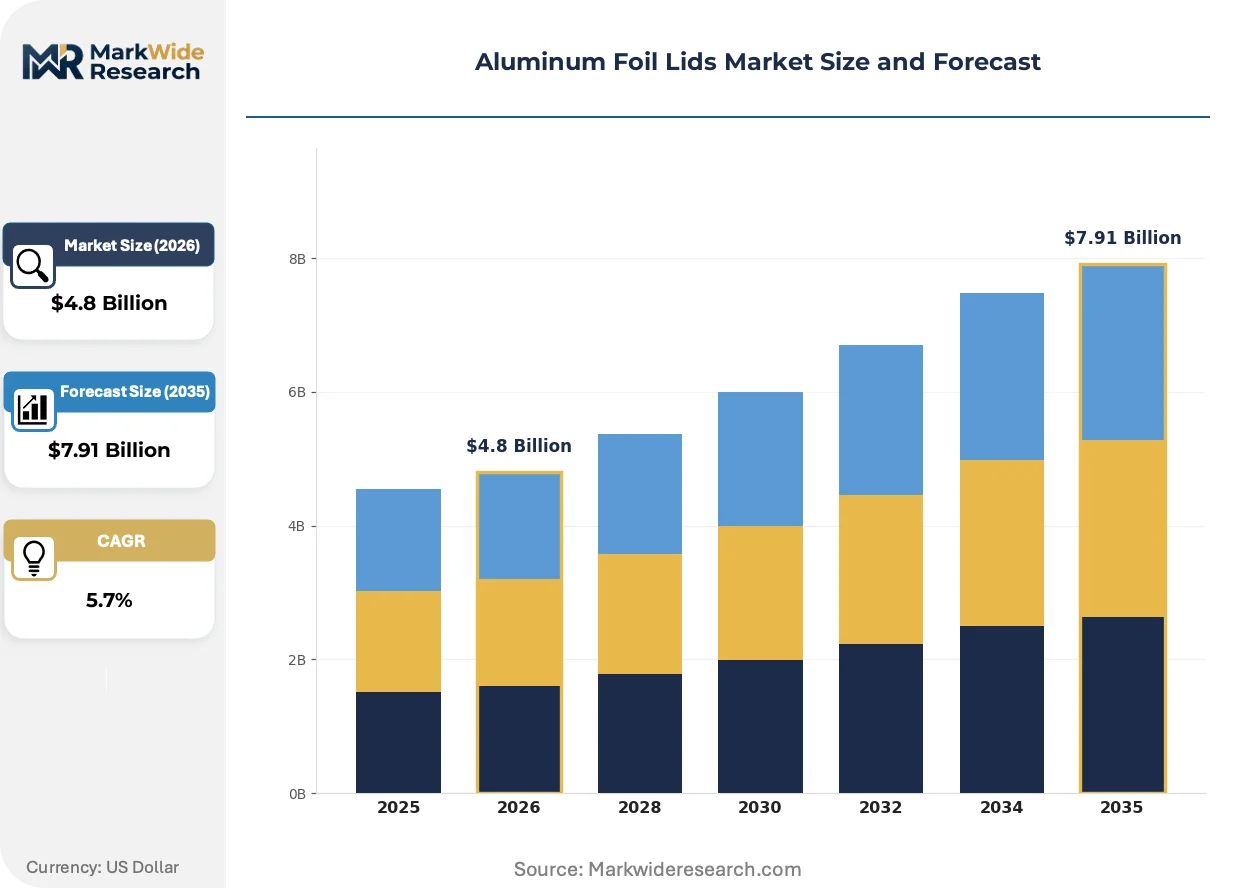
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Layer, Multi-Layer, Printed, Plain Application: Food Packaging, Pharmaceutical Packaging, Cosmetic Packaging, Industrial Packaging End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Industrial Users Form: Sheets, Roll, Pre-Cut, Custom Shapes |
| Companies Covered | Amcor Limited, Constantia Flexibles, Huhtamaki Oyj, Berry Global, ProAmpac, Quantum Packaging, Tekni-Plex, Sonoco, Novelis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Foil Lids Market Strategic Shifts
Active material science development is reconfiguring the competitive boundary between commodity foil laminates and engineered multi-layer systems. Coating chemistry, substrate gauge optimization, and intelligent packaging integration now determine supplier differentiation.
Water-based heat-seal coating chemistry is absorbing regulatory pressure from solvent-based systems across European dairy packaging. German and French processors adopting these coatings report comparable seal strength with reduced volatile organic compound emissions. The technology is absorbing market share from conventional solvent-laminated constructions as REACH compliance costs escalate.
REACH authorization requirements for specific phthalate plasticizers in food-contact applications are forcing coating reformulation across the European supply base. Laminators must validate alternative heat-seal polymers without compromising peel-force consistency. Pharmaceutical blister manufacturers in Germany and Switzerland face the tightest substitution timelines given their validated drug-product packaging configurations.
Consolidated dairy procurement is displacing fragmented regional buying across North American co-manufacturing networks. Large processors now mandate single-source lid supply with pan-continental logistics capability, squeezing regional die-cut specialists. This concentration is most visible in Wisconsin and California processing corridors where multi-plant rationalization programs consolidate supplier panels.
Aluminum Foil Lids Market Segmentation
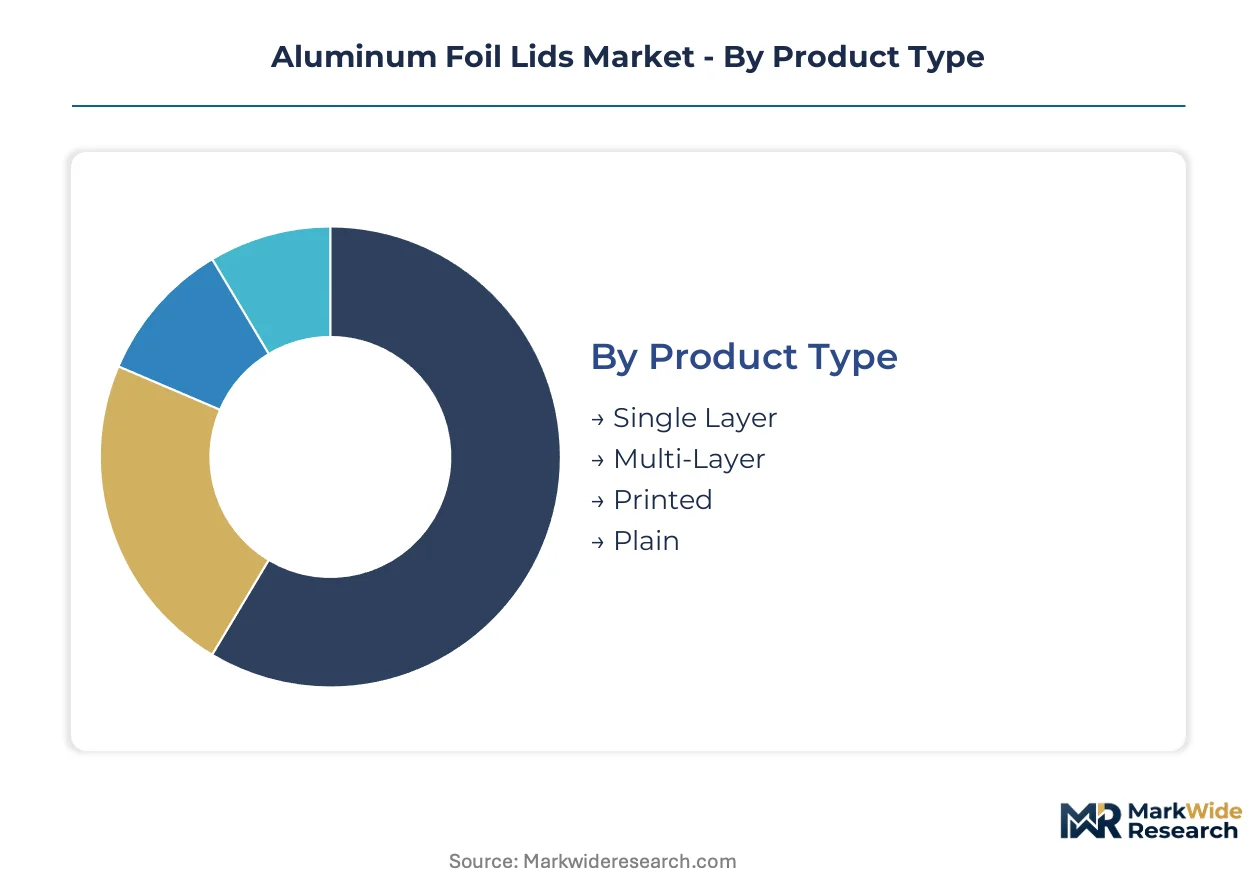
Aluminum foil lid specifications diverge sharply between commodity food service and validated pharmaceutical applications. Material thickness, coating chemistry, and dimensional precision requirements create distinct manufacturing footprints and margin structures across product categories.
Product Type:
Volume concentrates in single-layer constructions while premium positioning accrues to multi-layer barrier systems.
- Single Layer:Unlaminated aluminum foil between 20-30 micrometers thick serves ambient dairy and ready-meal segments where moisture barrier requirements remain moderate. German dairy cooperatives drive standardized procurement of these lids for yogurt and dessert cup applications, prioritizing cost efficiency over extended shelf stability.
- Multi-Layer:Aluminum-polyester-polypropylene laminates incorporate functional heat-seal coatings and printable top webs for pharmaceutical blister packs. Demand clusters in Austria and Switzerland where cleanroom manufacturing validates particulate control for moisture-sensitive biologics, with EMA compliance protocols governing coating migration limits.
- Printed:Rotogravure or flexographic surface decoration enables brand differentiation and regulatory marking for consumer-facing food packaging.
- Plain:Unprinted foil substrates serve industrial chemical containment and secondary processing applications where surface aesthetics carry no commercial value.
Today's leader: Single Layer. Tomorrow's challenger: Multi-Layer.
Application:
Food packaging absorbs the majority of foil lid tonnage while pharmaceutical applications sustain margin premiums through technical validation requirements.
- Food Packaging:Peelable and weld-sealed closures for rigid plastic and paper cups dominate consumption across dairy, ready-meal, and single-serve beverage categories. North American co-manufacturing consolidation in Wisconsin and California processing corridors drives standardized format adoption.
- Pharmaceutical Packaging:Child-resistant and senior-friendly blister lid designs with validated seal integrity protect moisture-sensitive solid dose and biologic formulations. Swissmedic and Germany's national pharmaceutical regulator enforce strict packaging material notification protocols.
- Cosmetic Packaging:Small-batch custom die-cutting and metallic decorative finishes serve premium skincare and fragrance sampling applications.
- Industrial Packaging:Chemical-resistant foil laminates seal laboratory reagent containers and automotive fluid reservoirs where solvent compatibility determines specification.
Food Packaging commands current volume leadership. Pharmaceutical Packaging climbs fastest on biologic drug proliferation.
End User:
Procurement sophistication separates multinational pharmaceutical operators from fragmented regional food processors.
- Food Manufacturers:Dairy processors and ready-meal co-manufacturers specify pre-cut lid formats matched to thermoformed cup dimensions. Centralized procurement teams at North American and European processors now mandate pan-continental supply capability, displacing regional die-cut specialists.
- Pharmaceutical Companies:Validated packaging configurations for approved drug products lock in lid suppliers for product lifecycle durations. EMA marketing authorization holders face 18-24 month revalidation timelines for any coating chemistry modification.
- Cosmetic Brands:Seasonal promotional campaigns and limited-edition sampling programs demand rapid-turn custom printing and die-cutting services.
- Industrial Users:Technical specification-driven procurement emphasizes chemical compatibility documentation and lot traceability over brand aesthetics.
Food Manufacturers anchor present demand. Pharmaceutical Companies expand most quickly on specialty barrier requirements.
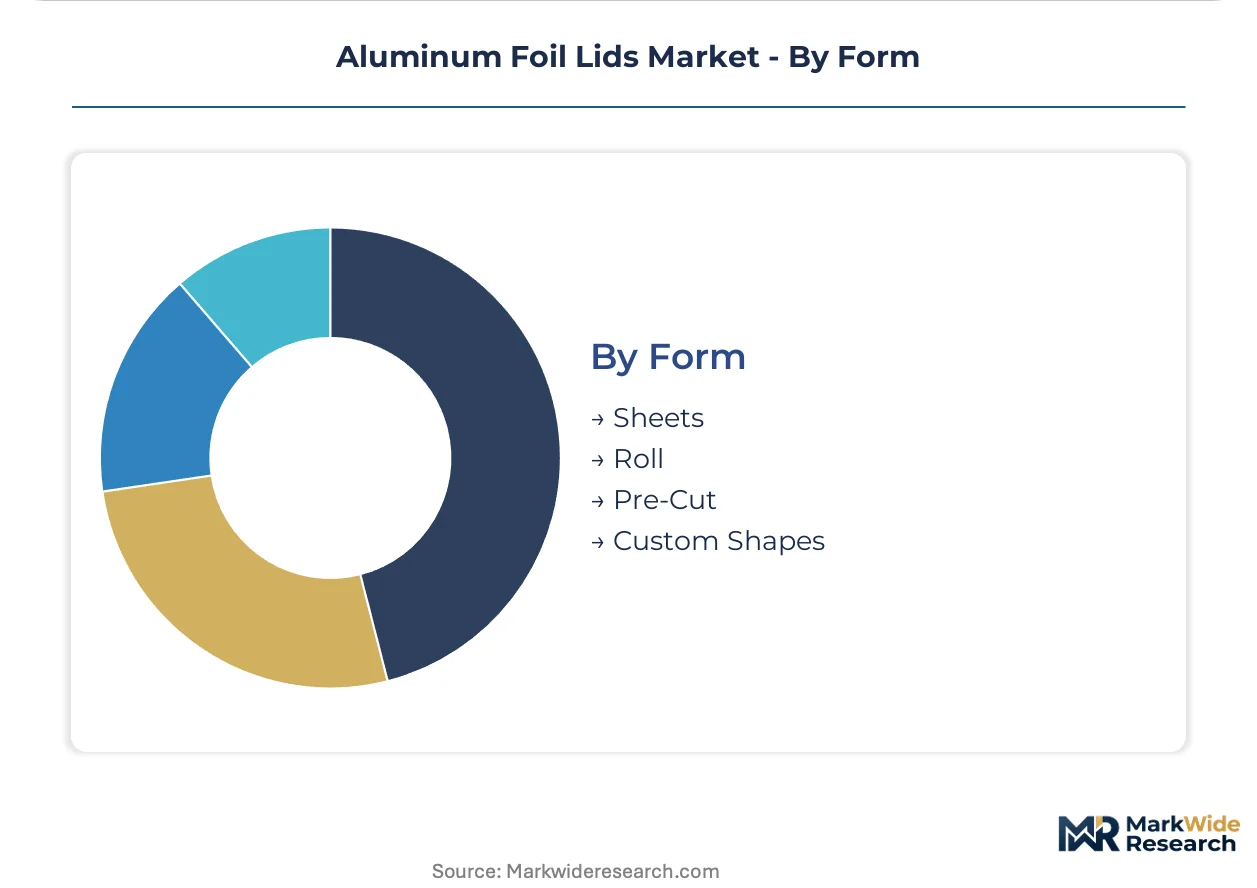
Form:
Supply chain efficiency favors pre-cut formats while roll-fed systems retain flexibility for diversified product portfolios.
- Sheets:Flat-cut aluminum blanks serve manual or semi-automated sealing operations in small-batch cosmetic and specialty food applications.
- Roll:Continuous foil webs feed high-speed form-fill-seal lines in mass-market dairy operations, with tension control and web alignment critical to seal integrity.
- Pre-Cut:Die-cut lids matched to specific cup diameters eliminate on-site cutting equipment and reduce material waste. German and French dairy processors drive adoption of standardized pre-cut formats across multi-plant networks.
- Custom Shapes:Irregular geometries and pull-tab features serve premium pharmaceutical compliance packaging and specialty cosmetic presentations.
Pre-Cut dominates current format preferences. Custom Shapes gain traction on aging-population accessibility designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping aluminum foil lid production geography. European REACH compliance costs and PPWR recyclability mandates are pushing laminators to evaluate lower-cost jurisdictions, while quality-sensitive pharmaceutical applications retain manufacturing in validated European cleanroom zones.
Germany
Centralized dairy cooperatives and pharmaceutical blister clusters in Bavaria and Baden-Württemberg drive premium multi-layer lid consumption. The national packaging regulator enforces strict dual-system recycling participation that shapes supplier qualification. Stuttgart and Munich processing corridors concentrate die-cutting operations for pan-European supply.
United States
Wisconsin and California dairy co-manufacturing consolidation creates volume pull for pre-cut lid suppliers with multi-site capability. FDA food-contact substance regulations govern coating chemistries and migration limits for consumer applications. Chicago and Milwaukee thermoforming corridors standardize cup-and-lid formats across rationalized plant networks.
China
Integrated aluminum conglomerates redirect rolling capacity toward value-added foil substrates for export laminators. GB standards and MIIT industrial policy shape domestic packaging material specifications. Zhengzhou and Shanghai processing clusters concentrate cold rolling and annealing capacity for thin-gauge lid substrates.
India
Organized dairy sector modernization in Gujarat and Maharashtra creates first-mover opportunity for localized lid production. FSSAI food safety standards govern food-contact material compliance for domestic and export markets. Anand and Mumbai processing corridors anchor cooperative dairy infrastructure expansion.
Switzerland
Swissmedic pharmaceutical packaging regulations enforce strict material notification protocols for moisture-sensitive biologic drugs. Basel and Zurich aseptic manufacturing zones demand validated cleanroom-produced blister lids with documented particulate control. High-barrier aluminum-polyester laminates command premium positioning in this quality-driven market.
Aluminum Foil Lids Market Competitive Environment
European producers anchor the premium pharmaceutical tier; Asian rolling specialists hold commodity substrate supply. The vendor base stratifies across three tiers: integrated packaging conglomerates with beverage and food networks, specialized flexible packaging laminators with cleanroom capabilities, and regional die-cut operators serving fragmented dairy processors. Two dominant competitive moves are reshaping positioning: pan-continental logistics capability expansion to serve consolidated dairy procurement, and coating chemistry reformulation to meet REACH authorization timelines.
Among integrated packaging conglomerates, Amcor Limited exemplifies the network-scale archetype through its beverage and food packaging reach. Constantia Flexibles occupies a position within the specialized flexible packaging tier, with geographic anchoring in European pharmaceutical corridors. Huhtamaki Oyj represents the emerging-market localization archetype, with production positioning tailored to regional cup formats in high-growth jurisdictions.
| Leading Market Players |
|---|
| Amcor Limited |
| Constantia Flexibles |
| Huhtamaki Oyj |
| Berry Global |
| ProAmpac |
| Quantum Packaging |
| Tekni-Plex |
| Sonoco |
| Novelis |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap die-cut specialists across Germany and Wisconsin anchor regional supply networks, their concentrated ownership structures enabling pricing discipline through long-term dairy processor relationships while limiting aggressive margin compression during aluminum ingot volatility cycles.
Pricing Analysis
Distributor margins on pre-cut lid formats absorb the primary channel economics squeeze, with direct-to-OEM contracts commanding 8-15 point discounts for pan-continental volume commitments. Pricing stratifies across premium, standard, and economy tiers based on coating chemistry complexity and cleanroom certification status. Cost compression in single-layer commodity lids intensifies as Chinese rolling capacity floods export markets with thin-gauge substrates. Food manufacturers exhibit highest price sensitivity, while pharmaceutical companies accept premium positioning for validated barrier performance.
Supply Chain Analysis
Dual-sourcing requirements from German dairy cooperatives and Swiss pharmaceutical manufacturers mandate multi-supplier qualification across at least two substrate origins. Supply concentrates in China for cold-rolled foil substrates, Germany for precision die-cutting equipment, and India for emerging localized conversion capacity. Raw material dependencies center on LME-traded aluminum ingot, solvent and water-based heat-seal coating chemistries, and polyester film laminates. Single-source vulnerability concentrates in Asian rolling mill concentration for sub-30-micrometer gauges. Distribution runs through integrated packaging conglomerates with captive logistics networks serving multi-plant dairy processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through coating chemistry reformulation, where REACH-compliant water-based systems command premium positioning against legacy solvent-laminated constructions while reducing regulatory compliance cost trajectories.
For Market Incumbents: Lock in pharmaceutical blister supply through cleanroom capacity expansion in Austria and Germany, securing validated manufacturing status before EMA notification timelines tighten further. Deepen backward integration into coating chemistry development to control reformulation cycles and accelerate REACH substitution protocols. Fiber-based lid substitution from Scandinavian developers threatens peelable foil dominance in ambient yogurt segments; counter with barrier-performance documentation and total-cost-of-ownership analytics. For New Entrants and Emerging Players: The 40-60% price-point gap between premium pharmaceutical-grade multi-layer lids and economy single-layer dairy constructions opens white-space targeting at mid-tier food processors seeking upgraded barrier performance without full pharmaceutical validation. India's organized dairy modernization in Gujarat and Maharashtra presents the most penetrable geography, with cooperative processing infrastructure expanding faster than localized lid supply. Pursue joint-venture die-cutting arrangements with existing thermoformer operators to bypass capital-intensive cleanroom requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among regional die-cut specialists lacking pan-continental logistics capability, as consolidated dairy procurement displaces fragmented buying and strands sub-scale operators. The 5-10 year viability window favors acquisition targets with coating chemistry reformulation expertise and established EMA notification track records. Watch for laser micro-perforation technology maturation as the inflection signal, where controlled peel-force capabilities could reshape senior-friendly pharmaceutical compliance packaging specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Reformulation | REACH-compliant water-based systems reduce VOC emissions while maintaining seal integrity for German dairy processors. |
| Cleanroom Manufacturing Scale-Up | Validated aseptic production in Austria and Switzerland secures EMA-compliant blister lid supply for biologic drugs. |
| Backward Integration into Substrate Rolling | In-house aluminum foil production mitigates LME price volatility exposure for European lid laminators. |
| Localized Die-Cutting Operations | Regional conversion capacity in Gujarat and Maharashtra matches India's cooperative dairy infrastructure expansion. |
| Laser Micro-Perforation Development | Controlled peel-force technology addresses aging-population pharmaceutical compliance requirements in Swiss and German markets. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dairy procurement directors, pharmaceutical packaging engineers, flexible packaging plant managers, and coating chemistry R&D leads with secondary validation against EU REACH substance databases, FDA food-contact substance notifications, FSSAI compliance circulars, and aluminum industry trade association capacity reports. Bottom-up demand modeling from end-use segment consumption patterns triangulated against top-down supply-side capacity assessments across rolling mill and laminator operations.
Segment-weighting approaches distributed volume and value projections across product type tiers, application categories, end-user procurement sophistication levels, and geographic processing cluster concentrations. CAGRs derived from fitted growth curves incorporating aluminum price elasticity estimates, regulatory compliance cost trajectories, and substitution threat assessments for fiber-based alternatives. Forecast inputs included dairy co-manufacturing consolidation rates, pharmaceutical biologic drug approval pipelines, and extended producer responsibility scheme implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for water-based heat-seal coating chemistry or laser-perforation integration would alter the outlook substantially. Forecasts reflect assumptions about REACH authorization timelines, PPWR recyclability mandate enforcement intensity, and Chinese rolling capacity export pricing discipline. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
Novelty Tins Market
Metal Packaging
Saudi Arabia Metal Packaging Market
Metal Packaging
India Metal Packaging Market
Metal Packaging
Aluminum Foil Packaging Market
Metal Packaging
Aluminum Cans Market
Metal Packaging
Vietnam Metal Can Packaging Market
Metal Packaging
North America Aluminium Cans Market
Metal Packaging
United Arab Emirates Metal Packaging Market
Metal Packaging
Cans Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
Metal Drums Market
Metal Packaging
Latin America Metal Packaging Market
Metal Packaging
Pressurized Metal Containers Market