
 Asia-Pacific Metal Packaging Market | 2026-2036
Asia-Pacific Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Metal Packaging Market Analytics
Premium decorative metal packaging is decoupling from commodity-grade industrial containers across Asia-Pacific procurement channels. Toyo Seikan Co. Ltd. leverages its Japanese manufacturing base to dominate high-barrier beverage can segments, while Crown Holdings, Inc. anchors its regional position through extensive Southeast Asian production infrastructure. Ball Corporation competes aggressively in aluminum sustainability credentials, positioning its recycling-loop technology as a procurement differentiator for multinational beverage brands.
Asia-Pacific metal packaging encompasses rigid containers, closures, and semi-rigid formats fabricated from aluminum, steel, tinplate, or metal foil, typically ranging from 0.15 mm to 0.45 mm in wall thickness depending on internal pressure requirements and corrosion resistance specifications; these structures serve primarily to protect oxygen-sensitive and light-degradable contents across food, beverage, pharmaceutical, and industrial chemical supply chains. Cans command the largest product-type volume pool, though containers extract higher per-unit margins in healthcare and personal care applications where sterilization compatibility and child-resistant functionality justify premium positioning. Recyclable technologies within the technology dimension are gaining fastest traction as brand owners respond to EPR frameworks and retailer sustainability scorecards, while direct printing is displacing labeled formats in beverage applications seeking shelf differentiation.
China's SAMR enforces GB food-contact material standards that restrict heavy metal migration limits, while Japan's METI administers container recycling laws that mandate steel and aluminum recovery quotas; India's BIS certification requirements for metal food containers create additional market access conditions that foreign suppliers must satisfy through local testing partnerships. Australia's TGA and South Korea's MFDS impose parallel pharmaceutical packaging material standards that shape export-oriented production decisions. Stakeholders must monitor how diverging national recycling infrastructure investments across the region will reshape collection economics and post-consumer scrap availability for closed-loop manufacturing.
Market Dynamics
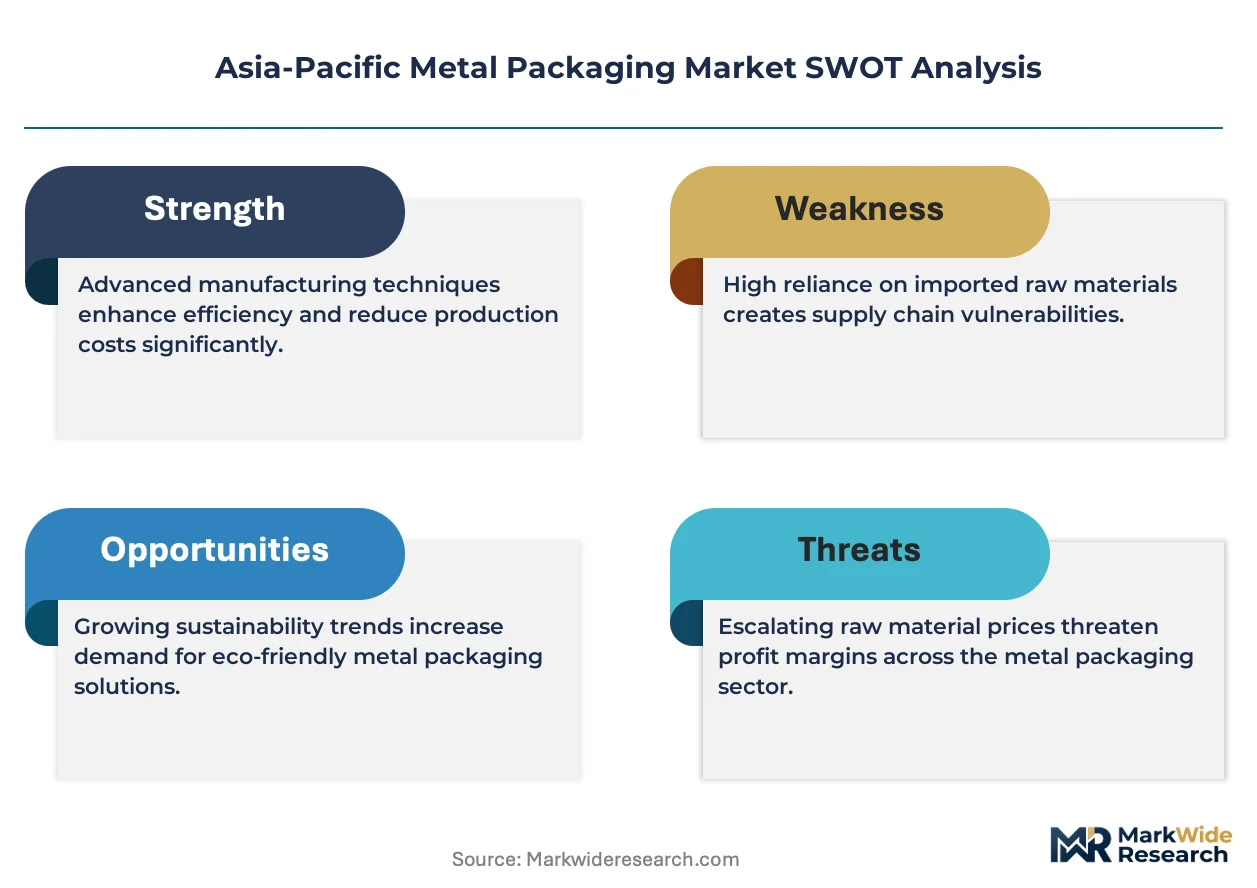
Asia-Pacific metal packaging is undergoing structural compression as beverage can demand concentrates in Southeast Asian manufacturing corridors while regulatory divergence between China's SAMR, Japan's METI, and India's BIS forces multi-standard compliance architectures.
Growth Catalysts
- Extended Producer Responsibility frameworks:Japan's container recycling laws mandate steel and aluminum recovery quotas, compelling brand owners to specify recyclable metal formats in procurement contracts.
- Beverage can demand clusters:Southeast Asian markets are scaling aluminum can adoption for carbonated drinks and ready-to-drink coffee, pulling regional capacity expansion.
- High-barrier sterilization requirements:Pharmaceutical and infant nutrition applications in Australia and South Korea are specifying corrosion-resistant tinplate for oxygen-sensitive contents.
Market Restraints
- Aluminum ingot cost volatility:Primary aluminum price swings in Shanghai and London Metal Exchange contracts compress converter margins on fixed-price annual supply agreements.
- Tinplate supply concentration:Japanese and South Korean steel mills control specialized electrolytic tinning capacity, creating single-source vulnerability for regional can makers.
- Flexible plastic substitution:Retort pouches and multilayer films are capturing shelf-stable food segments where metal cans previously dominated.
Strategic Opportunities
- India's western industrial corridor:Maharashtra and Gujarat beverage processors are scaling metal packaging procurement faster than domestic can manufacturing capacity, creating import substitution openings.
- Direct-to-can digital printing:Sleeveless decoration technology eliminates label substrate costs while enabling batch-specific customization for craft beverage brands.
- Dual carbon policy alignment:China's MEE carbon intensity targets and Japan's METI green transformation bonds are channeling capital toward closed-loop aluminum smelting and can-to-can recycling infrastructure.
Industry Challenges
- Multi-jurisdiction certification timelines:India's BIS testing protocols for food-contact metals add months to product registration, delaying market entry for new alloy formulations.
- Legacy coating chemistry transitions:Bisphenol-A epoxy replacements for internal can linings require reformulation validation across incompatible national food-contact approval systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Metal Packaging Market |
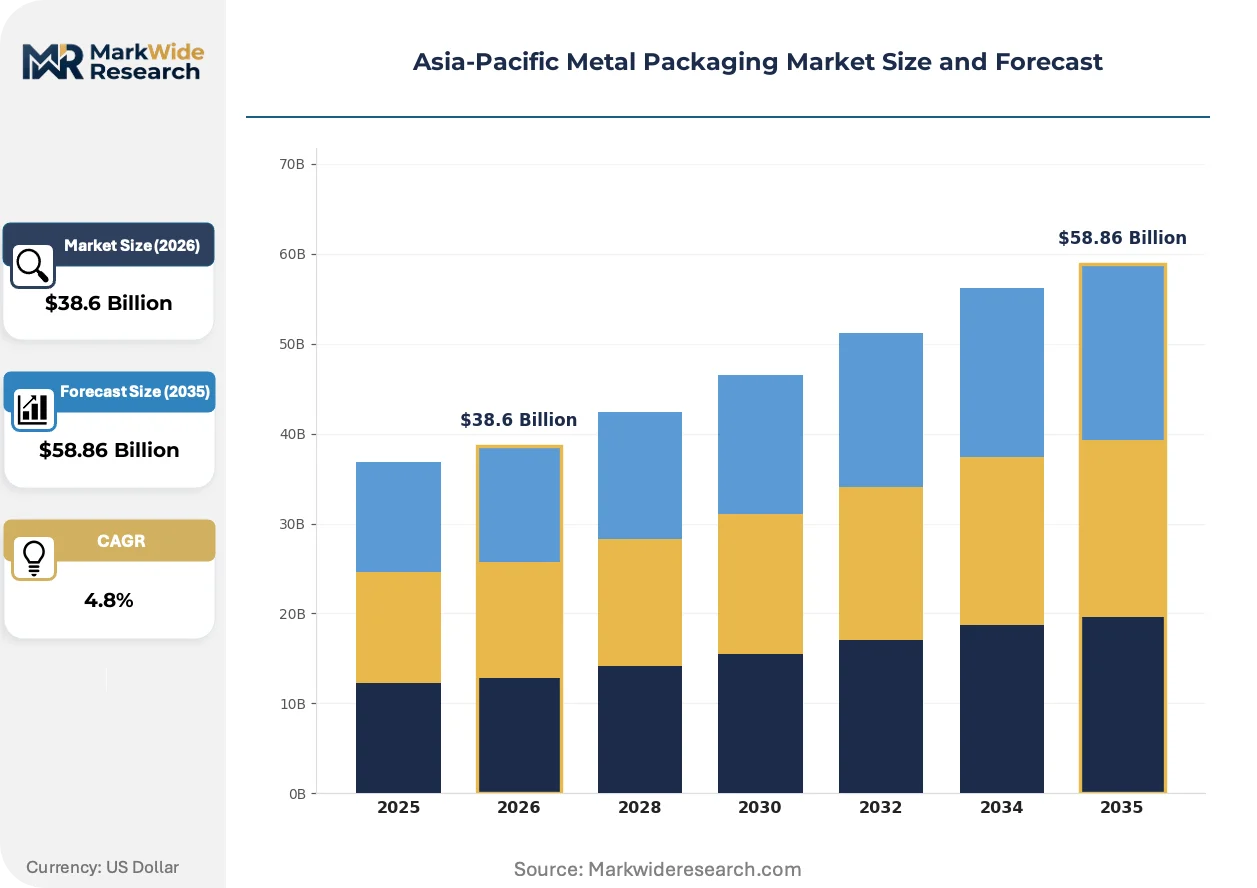
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cans, Bottles, Containers, Closures End User: Food & Beverage, Healthcare, Personal Care, Industrial Goods Material: Aluminum, Steel, Tinplate, Metal Foil Technology: Spray Coating, Direct Printing, Electrophoretic Coating, Recyclable Technologies |
| Companies Covered | Silgan Holdings Inc., Toyo Seikan Co. Ltd., Ball Corporation, Mauser Packaging Solutions, Greif Inc., Crown Holdings, Inc., Balmer Lawrie & Co. Ltd., Ardagh Group, CANPACK S.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Metal Packaging Market Evolving Landscape
Metal packaging innovation across Asia-Pacific is converging on material efficiency, regulatory pre-compliance, and supply chain traceability as brand owners face simultaneous pressure from sustainability scorecards and diverging national material standards.
Ultralight aluminum can wall technology is unifying strength-to-weight performance with sustainability metrics. Beverage multinationals operating in Thailand and Vietnam are specifying sub-0.27 mm body stock for standard cans, reducing aluminum unit consumption per thousand units. This unifying specification is compressing regional supplier differentiation toward decoration and logistics capabilities rather than metallurgical performance.
China's SAMR is tightening GB standards for heavy metal migration in food-contact materials, reducing allowable lead and cadmium thresholds in tinplate and aluminum alloys. Japanese exporters to Chinese markets are reformulating lacquer systems and substrate compositions to maintain access. Infant formula and nutritional supplement can segments are absorbing the highest compliance costs due to stricter testing frequencies.
Brand-led sustainability scorecards are reshaping supplier selection criteria in Australian and South Korean retail channels. Major supermarket chains are specifying minimum recycled content thresholds and carbon disclosure documentation for private-label metal packaging. This behavioral shift is most visible in Melbourne and Seoul procurement offices, where sustainability compliance teams now participate directly in packaging specification decisions alongside traditional purchasing functions.
Asia-Pacific Metal Packaging Market Segmentation
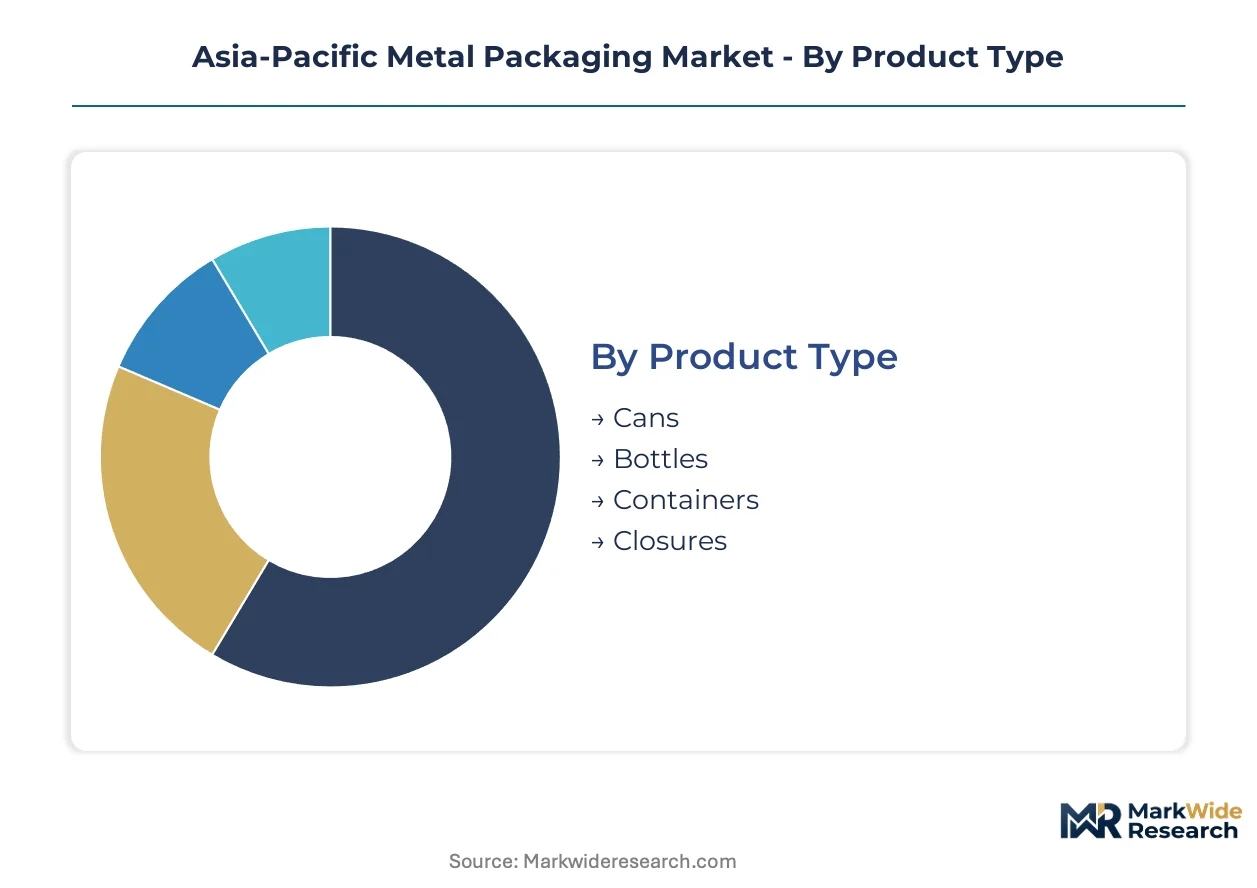
Segmentation in Asia-Pacific metal packaging reveals how procurement specifications diverge across beverage carbonation pressures, pharmaceutical sterilization requirements, and regulatory compliance thresholds for food-contact migration limits.
Product Type:
Standardization dominates high-volume beverage formats while customization concentrates in pharmaceutical and infant nutrition containers requiring tailored barrier properties.
- Cans:Aluminum and steel cylinders engineered for internal pressures from carbonated beverages, typically 0.27-0.35 mm wall thickness. Demand clusters in Thailand and Vietnam for ready-to-drink coffee and energy drinks, pulled by Southeast Asian bottling capacity expansion and aluminum can-to-can recycling infrastructure investments.
- Containers:Rigid rectangular or cylindrical formats for processed foods, chemicals, and industrial lubricants, often featuring double-seamed lids or lever closures. Maharashtra and Gujarat processors in India's western corridor are scaling procurement faster than domestic manufacturing capacity, creating supply gaps for corrosion-resistant tinplate formats.
- Bottles:Narrow-neck metal formats for specialty beverages and aerosol applications, typically aluminum with threaded or crimped closures.
- Closures:Caps, lids, and ends fabricated from tinplate or aluminum, including easy-open ends and peelable membrane seals for infant formula.
Most installed capacity flows through Cans. Expansion is steepest in Containers.
End User:
Margin structures vary sharply across end-use sectors, with healthcare and infant nutrition commanding premium positioning against commodity beverage procurement.
- Food & Beverage:The largest volume pool spanning carbonated drinks, beer, ready-to-drink coffee, processed vegetables, and pet food. Australia's supermarket sustainability scorecards and South Korean retailer carbon disclosure requirements are reshaping supplier selection criteria toward recycled content verification.
- Healthcare:Sterile primary packaging for pharmaceuticals, nutritional supplements, and medical devices requiring corrosion-resistant tinplate and Bisphenol-A-free internal coatings. Australia's TGA and South Korea's MFDS impose parallel material standards that shape export-oriented production decisions for oxygen-sensitive contents.
- Personal Care:Aerosol cans for deodorants, hairsprays, and shaving foams, plus specialty containers for cosmetics.
- Industrial Goods:Chemical drums, lubricant cans, and paint containers prioritizing structural durability over decorative finish.
Food & Beverage absorbs the majority of regional aluminum can output. Healthcare climbs fastest on sterilization compliance premiums.
Material:
Supply concentration for specialized substrates creates single-source vulnerability, while commodity aluminum faces price volatility from Shanghai and London Metal Exchange contract swings.
- Aluminum:Lightweight, corrosion-resistant substrate for beverage cans, aerosols, and collapsible tubes, favored for closed-loop recycling economics. China's MEE carbon intensity targets and Japan's METI green transformation bonds are channeling capital toward closed-loop aluminum smelting infrastructure.
- Tinplate:Steel sheet electrolytically coated with tin for food containers, offering superior corrosion resistance and solderability. Japanese and South Korean steel mills control specialized electrolytic tinning capacity, creating sourcing constraints for regional can makers serving infant formula and processed food segments.
- Steel:Uncoated or lacquered carbon steel for industrial drums, closures, and structural components where weight is secondary to cost.
- Metal Foil:Ultra-thin aluminum or steel laminates for blister packs, flexible pouch structures, and composite containers.
Aluminum commands the highest procurement volumes. Tinplate gains share fastest on food-contact compliance tightening.
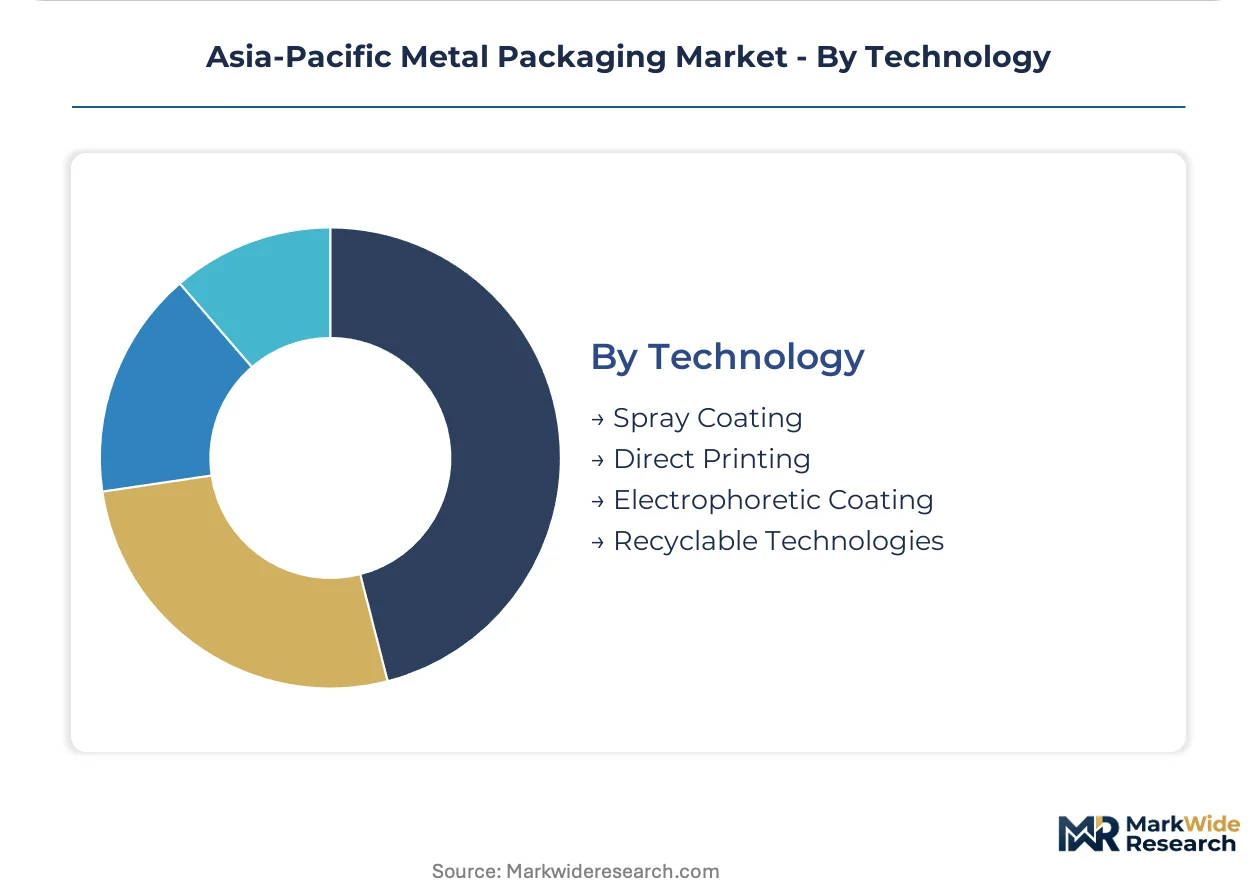
Technology:
Regulatory pre-compliance and sustainability traceability are shifting technology adoption curves away from legacy coating chemistries.
- Recyclable Technologies:Closed-loop manufacturing systems, can-to-can recycling protocols, and design-for-recovery specifications aligned with Japan's METI container recycling laws and Australia's emerging EPR frameworks. Major supermarket chains in Melbourne and Seoul procurement offices now specify minimum recycled content thresholds and carbon disclosure documentation.
- Direct Printing:Sleeveless digital decoration applied directly to can bodies, eliminating label substrate costs while enabling batch-specific customization for craft beverage brands in Thailand and Vietnam.
- Spray Coating:Atomized lacquer application for internal and external protective layers, including Bisphenol-A epoxy replacements undergoing reformulation validation.
- Electrophoretic Coating:Immersion-based deposition for uniform coverage on complex geometries, primarily for industrial and automotive components.
Spray Coating retains the largest installed base. Recyclable Technologies expand most quickly on brand-owner sustainability scorecard pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's beverage can capacity expansion outpaces Japan's recycling infrastructure investments, while India's western industrial corridor attracts procurement scale faster than domestic manufacturing can match.
China
Carbonated beverage bottlers in Guangdong and Zhejiang provinces are scaling aluminum can procurement for ready-to-drink coffee and energy drink portfolios. SAMR's tightened GB standards for heavy metal migration in food-contact materials are forcing substrate reformulation across tinplate and aluminum alloys. The Yangtze River Delta manufacturing belt is absorbing compliance costs through integrated smelting-to-can production corridors aligned with MEE carbon intensity targets.
Japan
METI's container recycling laws mandate steel and aluminum recovery quotas that reshape procurement specifications for domestic beverage brands. High-barrier sterilization demand from pharmaceutical and infant nutrition packagers in the Kanto region is pulling specialized tinplate formats. Toyo Seikan anchors domestic production capacity while exporting reformulated lacquer systems to Chinese markets facing SAMR compliance thresholds.
India
Maharashtra and Gujarat beverage processors are scaling metal packaging procurement faster than domestic can manufacturing capacity, creating import substitution openings for corrosion-resistant formats. BIS certification requirements for food-contact metals add months to product registration timelines, delaying market entry for new alloy formulations. The western industrial corridor's procurement concentration is attracting regional distribution partnerships from Southeast Asian converters.
South Korea
MFDS pharmaceutical packaging material standards are shaping export-oriented production decisions for oxygen-sensitive contents in sterile primary packaging. Seoul-based procurement offices are integrating sustainability compliance teams into packaging specification decisions alongside traditional purchasing functions. The Busan-Ulsan manufacturing cluster is channeling capital toward closed-loop aluminum recycling infrastructure under green transformation financing frameworks.
Australia
TGA pharmaceutical packaging standards parallel South Korean MFDS requirements for corrosion-resistant tinplate in healthcare applications. Melbourne supermarket sustainability scorecards are specifying minimum recycled content thresholds and carbon disclosure documentation for private-label metal packaging. Direct-to-can digital printing adoption is accelerating among craft beverage brands seeking sleeveless decoration and batch-specific customization capabilities.
Asia-Pacific Metal Packaging Market Competitive Landscape
Top-tier vendors anchor integrated beverage can production, while mid-tier specialists concentrate on regional compliance adaptation and decoration capabilities. The vendor base stratifies across three archetypes: multinational converters with Southeast Asian manufacturing footprints, Japanese high-barrier specialists leveraging domestic metallurgical expertise, and India-based distributors capturing western corridor procurement gaps. Competitive moves center on capacity expansion in Vietnam and Thailand plus strategic partnerships for BIS certification facilitation in Indian markets.
Among Japan-based high-barrier specialists, Toyo Seikan Co. Ltd. exemplifies the premium-tier metallurgical archetype through its domestic manufacturing concentration and export-oriented reformulation capabilities. Ball Corporation and Crown Holdings, Inc. represent the multinational converter archetype with extensive Southeast Asian production infrastructure positioning their recycling-loop credentials as procurement differentiators. These three companies occupy distinct competitive vectors—specialized barrier performance, scale-driven sustainability metrics, and regional compliance adaptation—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Toyo Seikan Co. Ltd. |
| Ball Corporation |
| Mauser Packaging Solutions |
| Greif Inc. |
| Crown Holdings, Inc. |
| Balmer Lawrie & Co. Ltd. |
| Ardagh Group |
| CANPACK S.A. |
| Others |
Value Network & Pricing Analysis
Premium barrier-performance divergence between pharmaceutical-grade tinplate and commodity beverage aluminum manifests in procurement contract structures and raw material sourcing footprints across Asia-Pacific manufacturing corridors. High-barrier sterilization specifications command three-tier pricing separation from standard beverage formats, while supply chain configurations concentrate electrolytic tinning capacity in Japanese and South Korean steel mills against dispersed aluminum smelting in Chinese coastal provinces.
Pricing Analysis
Capacity additions in Vietnam and Thailand are reshaping price floors for standard aluminum beverage cans as Southeast Asian converters absorb regional demand growth. Three-tier pricing structure across premium pharmaceutical tinplate, standard food-grade aluminum, and economy industrial steel reflects certification grade and corrosion resistance specifications. Cost compression in commodity beverage formats is intensifying because fixed-price annual supply agreements expose converters to Shanghai Metal Exchange aluminum volatility. Brand owners in Australia's supermarket channels exhibit lowest price sensitivity due to sustainability scorecard compliance premiums, while Indian beverage processors in Maharashtra demonstrate highest sensitivity as import substitution gaps strain working capital.
Supply Chain Analysis
Skilled technician availability constraints in Japanese Kanto and South Korean Busan-Ulsan clusters are tightening specialized electrolytic tinning output for pharmaceutical applications. Geographic supply concentration centers on China for primary aluminum smelting, Japan and South Korea for tinplate substrate, and Vietnam for emerging can manufacturing assembly. Raw material dependencies rest on aluminum ingot from Yangtze River Delta smelters, tin concentrate from Southeast Asian refineries, and lacquer chemistries from regional specialty chemical producers. Single-source vulnerability permeates electrolytic tinning capacity controlled by Japanese and South Korean steel mills. Distribution runs through integrated beverage bottler networks in Thailand and Vietnam plus third-party logistics corridors serving India's western industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific metal packaging functions as a stable compounder anchored by irreversible beverage can substitution trends and tightening food-contact regulatory compliance requirements that sustain procurement contract durability.
For Market Incumbents: Deepen backward integration into closed-loop aluminum recycling infrastructure to defend margin position against primary ingot price volatility and emerging sustainability scorecard requirements. Secure BIS certification facilitation partnerships in India to compress product registration timelines for new alloy formulations. Expand capacity in Vietnam and Thailand to capture Southeast Asian beverage bottler procurement scaling. For New Entrants and Emerging Players: Begin with corrosion-resistant container formats for India's western industrial corridor where Maharashtra and Gujarat processors outpace domestic manufacturing capacity. Target pharmaceutical and infant nutrition segments in Australia and South Korea where MFDS and TGA compliance premiums justify greenfield investment. Pursue direct-to-can digital printing capabilities as sleeveless decoration displaces labeled formats among craft beverage brands. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction certification capabilities and recycling-loop infrastructure create acquisition premiums for mid-tier regional converters. Five-to-ten-year viability favors targets with established SAMR, METI, and BIS compliance architectures plus captive aluminum recycling assets. Watch for inflection in China's MEE carbon intensity enforcement as signal for accelerated capital deployment into closed-loop smelting partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Infrastructure Investment | Captures Japan's METI container recycling law quotas and Australia's emerging EPR framework compliance premiums. |
| Direct-to-Can Digital Printing Deployment | Eliminates label substrate costs for Thailand and Vietnam craft beverage brands seeking batch customization. |
| BIS Certification Facilitation Partnership | Compresses India's food-contact metal product registration timelines from months to weeks for new alloy formulations. |
| Electrolytic Tinning Capacity Expansion | Addresses single-source vulnerability in Japanese and South Korean steel mill supply for pharmaceutical tinplate. |
| Ultralight Aluminum Body Stock Development | Reduces unit aluminum consumption per thousand cans below 0.27 mm for Southeast Asian beverage specifications. |
Research Methodology
Multiple input streams — primary interviews with beverage procurement directors, pharmaceutical packaging engineers, and steel mill technical sales leads; secondary validation through SAMR GB standard filings, METI container recycling law documentation, and BIS certification protocols; plus customs trade data and aluminum exchange price records — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured procurement specification decisions across Melbourne, Seoul, and Mumbai retail channel offices alongside converter operations in Vietnam and Thailand.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to construct analytical frameworks across product type, material substrate, end-use sector, and technology adoption dimensions throughout the forecast period. CAGRs were derived from segmented growth rate reconciliation against macroeconomic drivers and regulatory enforcement timelines. Forecast inputs incorporated beverage bottler capacity expansion pipelines, pharmaceutical sterilization compliance cost absorption rates, and recycling infrastructure investment flows under green transformation financing.
Several conditions sit outside the modeled scope, including abrupt aluminum ingot price discontinuities from exchange contract volatility, unilateral regulatory threshold revisions by SAMR or MFDS, and disruptive flexible packaging substitution acceleration in shelf-stable food segments. Forecasts reflect documented assumptions about EPR framework implementation pacing and carbon intensity target enforcement consistency. Material deviation in China's MEE enforcement rigor, Japan's METI recovery quota adjustments, or India's BIS testing protocol changes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Middle East and Africa Metal Cans Market
Metal Packaging
North America Aluminium Cans Market
Metal Packaging
Germany Metal Packaging Market
Metal Packaging
Egypt Metal Packaging Market
Metal Packaging
United States Aluminium Cans Market
Metal Packaging
North America Metal Cans Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
Australia Metal Packaging Market
Metal Packaging
Global Laminated Aluminium Foil Market
Metal Packaging
Metal Cans Market
Metal Packaging
Novelty Tins Market
Metal Packaging
India Metal Packaging Market
Metal Packaging
Collapsible Aluminium Tube Market
Metal Packaging
Metal Food Cans Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
Global Laminated Steel for Cans Market