
 Global Laminated Steel for Cans Market | 2026-2036
Global Laminated Steel for Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laminated Steel for Cans Market Outlook
Aftermarket technical service revenue is narrowing as a distinct margin pool, with producers integrating coating optimization and shelf-life testing directly into substrate supply contracts. Toyo Kohan Co., Ltd. leverages its polymer film lamination expertise to anchor premium beverage can contracts across East Asia. Tata Steel sustains cost-competitive positions through captive cold-rolling capacity and proximity to Indian food processors. JFE Steel differentiates via ultra-thin gauge development for lightweight two-piece cans.
Laminated steel for cans comprises cold-rolled steel substrate bonded with polymer or resin films through thermal lamination, typically achieving 0.15–0.25 mm finished gauges with corrosion resistance exceeding 24 months in acidic food contact. The material replaces traditional tinplate and aluminum in three-piece and draw-redraw can bodies, reducing metal content while preserving hermetic sealing integrity. Thin steel substrates dominate volume throughput in standard food cans, where cost minimization overrides premium barrier requirements. Coated steel variants command widening specification spreads in infant formula and ready-to-drink coffee segments, where oxygen ingress thresholds below 0.1 cc per can define shelf-life guarantees. Beverage packaging applications for laminated steel are expanding fastest in carbonated soft drinks and beer, driven by aluminum price volatility and circularity mandates for steel recycling loops.
The EPA regulates volatile organic compound emissions from lamination adhesive curing processes under Clean Air Act Title V permitting, while FDA 21 CFR 175.300 governs resin migration limits for food-contact polymer films in the United States. ECHA REACH restrictions on bisphenol-A epoxy coatings are accelerating polyester and polypropylene film substitution across European can stock supply chains. China's MEE enforces GB standards for heavy metal leachate testing that determine import eligibility for foreign laminated steel suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and film-to-steel separation requirements at end-of-life, as these will reshape substrate specifications and regional sourcing decisions.
Market Dynamics
Aluminum price volatility is compressing beverage can economics, forcing brand owners to requalify laminated steel substrates for carbonated applications previously reserved for aluminum. This substitution pressure cascades through specification tightening at Vietnam and Thailand canning hubs, where multinational food processors now mandate dual-source metal strategies.
Growth Catalysts
- REACH bisphenol-A restrictions:ECHA limitations on epoxy coatings accelerate polyester and polypropylene film migration across European can stock supply chains, opening specification windows for compliant laminated alternatives.
- Steel recycling circularity mandates:Extended producer responsibility frameworks in Germany and France prioritize magnetic separation of steel packaging, favoring laminated steel over aluminum in municipal sorting infrastructure.
- Infant formula barrier requirements:Oxygen ingress thresholds below 0.1 cc per can in premium nutrition segments pull ultra-thin gauge laminated steel into specification spreads previously served by tinplate.
Market Restraints
- Cold-rolled steel input volatility:Scrap metal pricing swings and energy costs at electric arc furnaces transmit directly to substrate margins, constraining price predictability in contract negotiations.
- Film-to-steel separation infrastructure gaps:End-of-life delamination capabilities remain concentrated in Japanese and Korean recycling streams, limiting circularity claims in Southeast Asian markets lacking comparable technical infrastructure.
- Aluminum incumbent lock-in:Two-piece draw-redraw beverage can lines optimized for aluminum temper specifications require substantial retooling investment to accommodate steel mechanical properties.
Strategic Opportunities
- Indian food processing corridors:Cold chain expansion in Maharashtra and Gujarat creates first-mover positioning for laminated steel suppliers with captive cold-rolling and polymer film lamination integration.
- Ready-to-drink coffee oxygen barrier specifications:Nitrogen-flushed can requirements in Japanese convenience retail pull high-barrier coated steel variants into premium shelf-stable beverage segments.
- China GB standards alignment:MEE heavy metal leachate testing protocols for import eligibility create compliance moats for foreign suppliers with established laboratory certification relationships.
Industry Challenges
- Polymer film lamination technician scarcity:Thermal bonding process control expertise concentrates at Japanese and Korean equipment OEMs, constraining knowledge transfer to emerging market greenfield installations.
- Dual certification timeline compression:Simultaneous FDA 21 CFR 175.300 and EFSA food-contact approvals require 18-24 month validation cycles that outpace customer qualification demands.
- Legacy tinplate line retrofit complexity:Three-piece can welding equipment optimized for tin-coated substrates demands substantial modification to handle polymer-laminated steel surface properties without coating damage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laminated Steel for Cans Market |
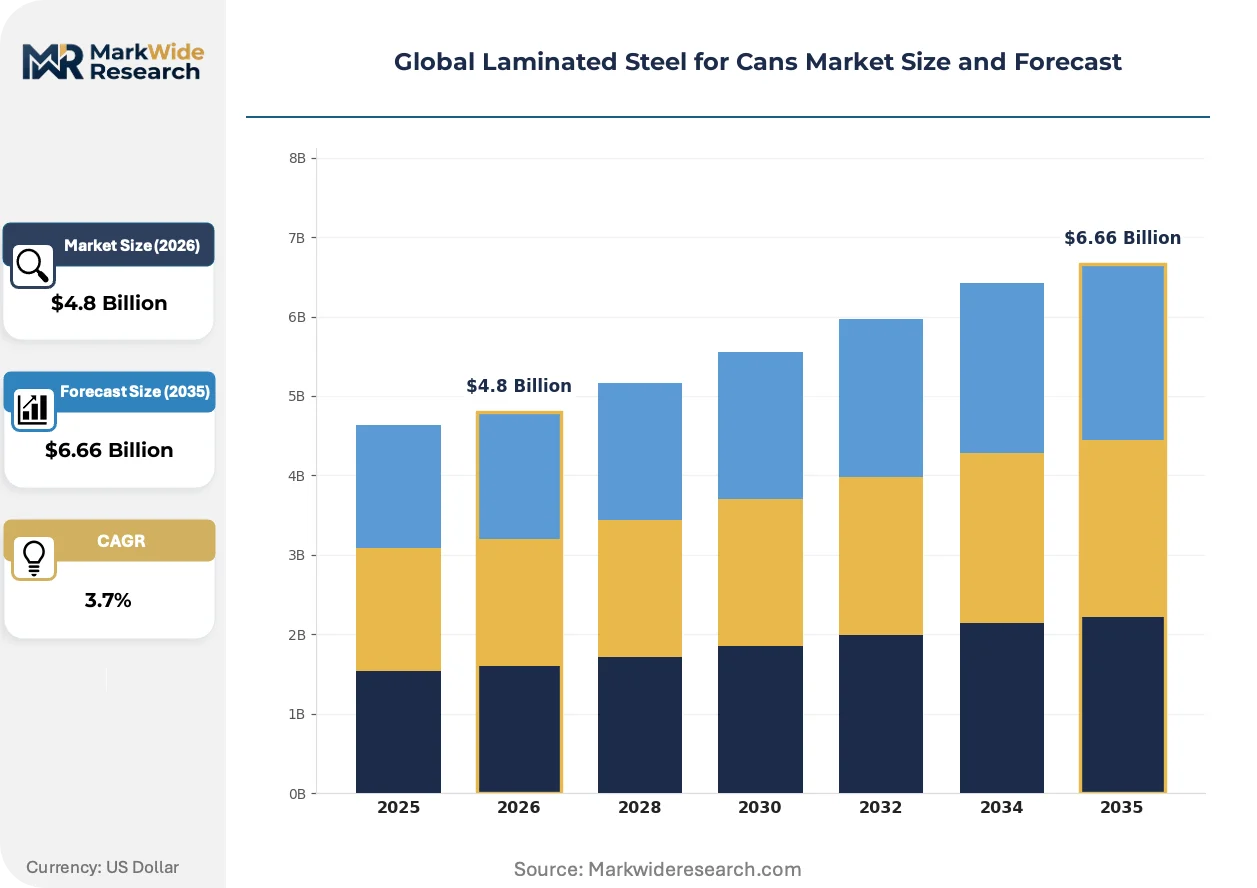
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Steel, Coated Steel, Galvanized Steel, Stainless Steel Application: Food Packaging, Beverage Packaging, Chemical Packaging, Personal Care Packaging End User: Food Manufacturers, Beverage Producers, Chemical Companies, Cosmetics Firms Distribution Channel: Direct Sales, Retail, Online Sales, Distributors |
| Companies Covered | China Gerui Advanced Materials Group Limited, Polytech America, Toyo Kohan Co., Ltd., Tata Steel, TCC Steel, JFE Steel, Metalcolour A/S, Nippon Steel, Toy Seikan Group Holdings, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laminated Steel for Cans Market Strategic Shifts
Material science convergence with regulatory chemistry restrictions is redefining competitive differentiation in can stock supply. Thermal lamination process control and film substrate bonding chemistry now determine specification access more than traditional metallurgical metrics.
Multi-layer coextruded barrier films are hybridizing polymer properties for acidic food contact. These structures combine ethylene vinyl alcohol oxygen barriers with polypropylene moisture protection in single lamination passes. Premium infant formula and ready-to-drink coffee canners in Japan and South Korea are qualifying these substrates at accelerated timelines. The technology is hybridizing formerly separate metallurgical and polymer supply chains into integrated substrate offerings.
ECHA REACH Annex XVII bisphenol-A restrictions are forcing coating chemistry transitions across European can manufacturing. Polyester and polypropylene films displace epoxy-phenolic systems in food-contact layers, requiring reformulation of adhesion promoters and thermal curing profiles. German and French can makers face compressed compliance deadlines, pulling laminated steel with pre-certified polymer layers into specification rotations faster than traditional coating conversion timelines permit.
Aftermarket technical service unbundling is reversing across laminated steel supply relationships. Brand owners previously purchased substrate and coating optimization separately; now shelf-life testing, migration analysis, and seal integrity validation consolidate into single-source supply contracts. This bundling concentrates procurement decision authority with substrate suppliers possessing in-house polymer chemistry laboratories. Vietnamese and Thai canning hubs exhibit this pattern most visibly, where multinational food processors reduce vendor management overhead through integrated technical service commitments.
Global Laminated Steel for Cans Market Segmentation
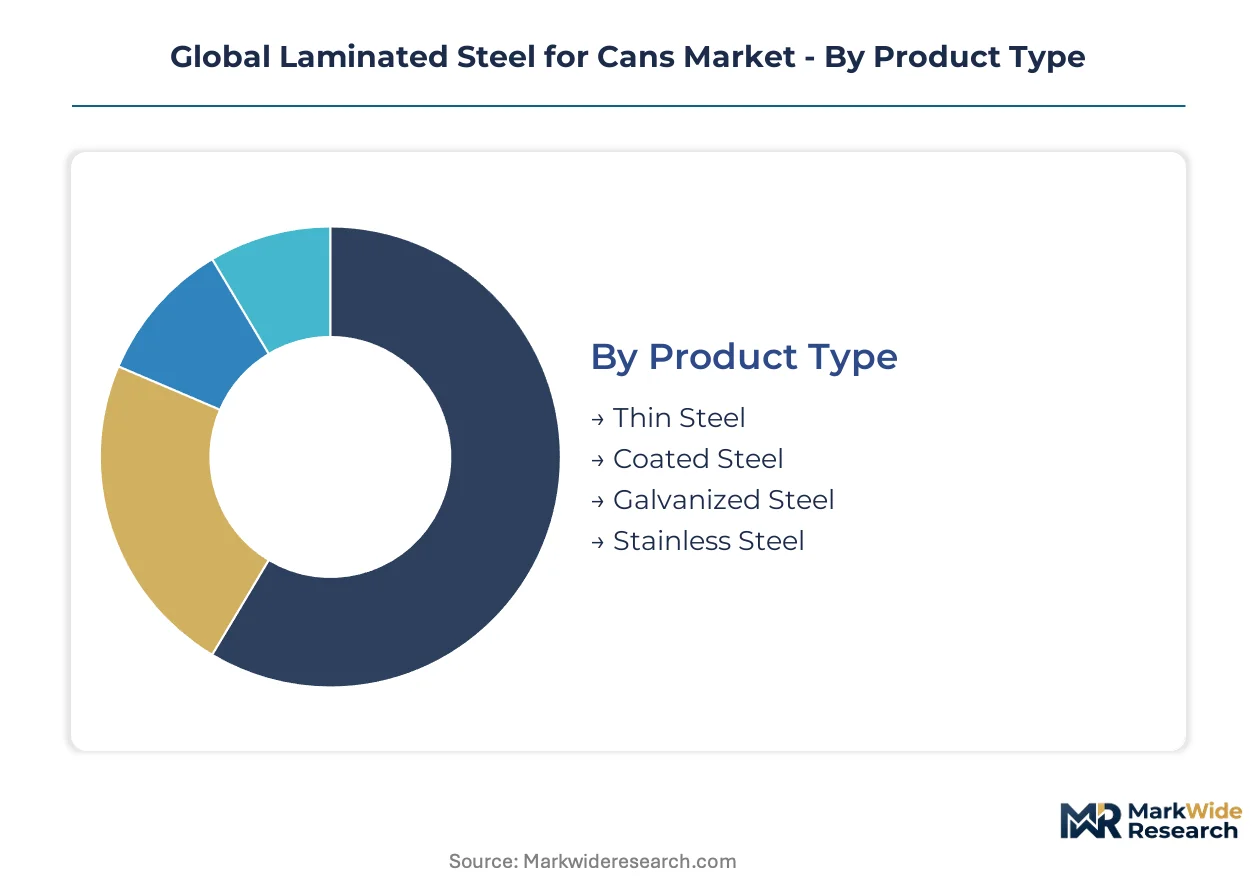
Segmentation in laminated steel for cans reveals how substrate specifications diverge across corrosion requirements, mechanical performance needs, and end-use regulatory thresholds. Each dimension carries distinct margin profiles and qualification timelines that reshape supplier-customer contracting patterns.
Product Type:
Cost tier differentiation across substrate metallurgy determines volume accessibility versus premium specification capture.
- Thin Steel:Cold-rolled substrates at 0.15–0.20 mm finished gauges dominate standard three-piece food can production. Vietnamese and Thai canning hubs absorb the majority of throughput, driven by multinational food processors pursuing dual-source metal strategies against aluminum price volatility.
- Coated Steel:Polymer-laminated variants with ethylene vinyl alcohol oxygen barriers serve infant formula and ready-to-drink coffee segments. Japan and South Korea lead qualification timelines for these high-barrier specifications where oxygen ingress must remain below 0.1 cc per can.
- Galvanized Steel:Zinc-coated substrates provide intermediate corrosion protection for chemical packaging applications with moderate acidic exposure.
- Stainless Steel:Premium-grade substrates command niche positions in high-acid food contact and pharmaceutical packaging requiring extended shelf-life guarantees.
Thin steel commands the established base. The steepest expansion runs through coated steel variants.
Application:
Application focus determines barrier specification intensity and regulatory compliance burden across end-use segments.
- Food Packaging:Acidic vegetable and tomato-based products drive polyester and polypropylene film substitution as ECHA REACH bisphenol-A restrictions eliminate epoxy-phenolic coatings. German and French can makers face compressed compliance deadlines that pull pre-certified laminated alternatives into specification rotations faster than traditional coating conversions permit.
- Beverage Packaging:Carbonated soft drinks and beer applications expand fastest as aluminum price volatility forces brand owners to requalify steel substrates for draw-redraw can lines previously reserved for aluminum temper specifications.
- Chemical Packaging:Solvent-resistant laminated barriers serve agrochemical and industrial coating containers with aggressive permeation resistance requirements.
- Personal Care Packaging:Aerosol and cosmetic can applications prioritize aesthetic surface finish and fragrance barrier properties over oxygen exclusion.
Food packaging anchors volume throughput. Beverage packaging is gaining share fastest as substitution economics shift.
End User:
Customer type concentration shapes technical service bundling requirements and contract consolidation patterns.
- Food Manufacturers:Multinational processors in Vietnam and Thailand now mandate integrated shelf-life testing and migration analysis within substrate supply contracts, reversing prior unbundled procurement approaches.
- Beverage Producers:Carbonated beverage brand owners drive the most aggressive requalification timelines as aluminum price volatility compresses can economics.
- Chemical Companies:Agrochemical formulators demand solvent resistance validation and UN-certified packaging compliance for hazardous material transport.
- Cosmetics Firms:Premium beauty brands prioritize surface aesthetic quality and fragrance stability over extended oxygen barrier specifications.
Food manufacturers command the established base. The steepest expansion runs through beverage producers.
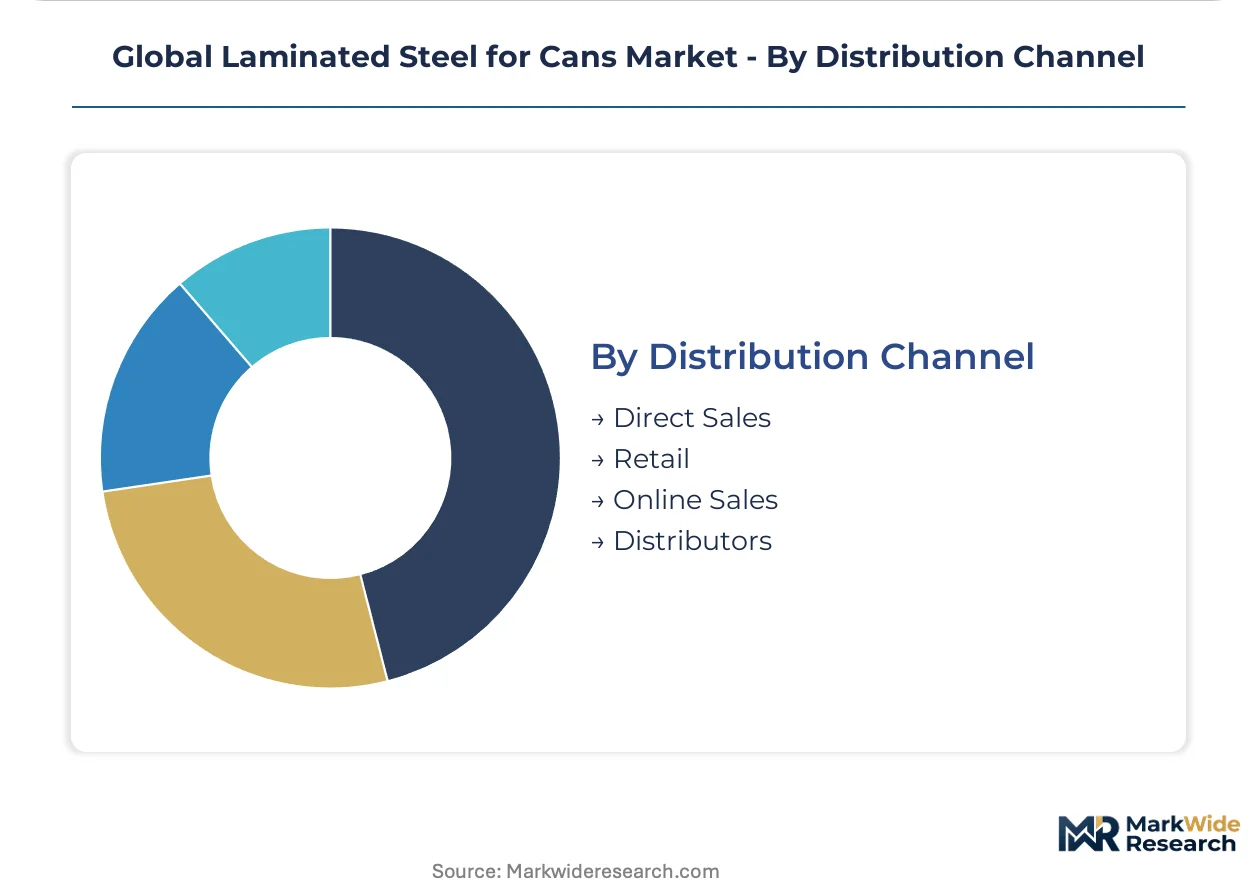
Distribution Channel:
Channel structure reflects the technical complexity of substrate qualification and the concentration of procurement decision authority.
- Direct Sales:Major can makers and multinational food processors negotiate directly with laminated steel producers for integrated technical service commitments including coating optimization and seal integrity validation.
- Distributors:Regional metal service centers handle smaller volume accounts and specialty gauge requirements for mid-tier can manufacturers lacking direct mill relationships.
- Retail:Limited to aftermarket and replacement applications for maintenance and repair operations rather than primary can production.
- Online Sales:Emerging for standardized specification samples and small-batch prototyping rather than production volume procurement.
Direct sales commands the established base. Distributors are gaining share fastest as regional can maker fragmentation persists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Vietnam and Thailand exhibit the highest price elasticity, squeezing margins on standard thin steel substrates, while Japanese and South Korean purchasers of ultra-high-barrier coated steel accept premium pricing for oxygen ingress guarantees below 0.1 cc per can.
China
Domestic cold-rolling capacity expansion in Hebei and Jiangsu provinces is displacing import reliance for standard food can substrates. MEE enforcement of GB heavy metal leachate standards creates compliance barriers for foreign suppliers without established laboratory certification relationships. The Yangtze River Delta concentration of can manufacturing is pulling laminated steel producers toward integrated technical service bundling.
Japan
Ready-to-drink coffee and infant formula segments in Tokyo-Osaka corridors are qualifying multi-layer coextruded barrier films at accelerated timelines. METI circularity guidelines prioritize magnetic steel separation infrastructure, reinforcing laminated steel positioning against aluminum in municipal sorting systems. Nagoya-area polymer lamination expertise concentrates thermal bonding process control knowledge that constrains greenfield replication elsewhere.
Germany
ECHA REACH Annex XVII bisphenol-A restrictions are compressing coating conversion timelines for can makers in Bavaria and North Rhine-Westphalia. Extended producer responsibility frameworks in Baden-Württemberg prioritize steel packaging recyclability, pulling pre-certified laminated alternatives into specification rotations faster than epoxy-phenolic reformulation permits. Frankfurt-Rhine-Main logistics hubs concentrate procurement decision authority for pan-European food processors.
United States
EPA Clean Air Act Title V permitting on adhesive curing processes is constraining lamination capacity expansion in Ohio and Indiana steel corridors. FDA 21 CFR 175.300 migration limit compliance is extending qualification cycles for European and Asian suppliers seeking beverage can contracts. Chicago-area metal service centers are gaining distributor share as mid-tier can manufacturers fragment procurement relationships.
India
Cold chain expansion in Maharashtra and Gujarat food processing corridors is creating first-mover positioning for laminated steel suppliers with captive cold-rolling integration. BIS alignment with evolving food-contact material standards is tightening substrate specifications for domestic infant nutrition producers. Mumbai-Pune industrial clusters concentrate multinational food processor demand mandating dual-source metal strategies against aluminum price volatility.
Global Laminated Steel for Cans Market Competitive Environment
Capability concentration sits with Japanese and Korean specialists possessing thermal lamination process control expertise; scale advantage sits with integrated steel producers with captive cold-rolling and polymer film lamination capacity. The market structures around three archetypes: metallurgical-integrated mills, polymer chemistry specialists, and regional toll laminators. Consolidation pressure is accelerating through backward integration moves and technical service bundling into substrate supply contracts.
Within the polymer chemistry specialist tier, Toyo Kohan Co., Ltd. and Toy Seikan Group Holdings, Ltd. exemplify Japanese players anchoring premium beverage can contracts through thermal bonding expertise. Tata Steel occupies a position among integrated mills leveraging proximity to Indian food processors, while JFE Steel represents the ultra-thin gauge development vector for lightweight two-piece can specifications. China Gerui Advanced Materials Group Limited sits within the regional toll laminator archetype serving cost-sensitive Southeast Asian canning hubs.
| Leading Market Players |
|---|
| China Gerui Advanced Materials Group Limited |
| Polytech America |
| Toyo Kohan Co., Ltd. |
| Tata Steel |
| TCC Steel |
| JFE Steel |
| Metalcolour A/S |
| Nippon Steel |
| Toy Seikan Group Holdings, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Japanese and Korean thermal lamination equipment OEMs concentrate process control expertise, anchoring margin pools in integrated technical service contracts rather than commodity substrate sales. Downstream buyers in Vietnam and Thailand extract price concessions on standard thin steel gauges while premium oxygen-barrier specifications in Tokyo-Osaka corridors sustain wider spreads.
Pricing Analysis
Aftermarket technical service revenue drives lifetime value as shelf-life testing and migration analysis consolidate into single-source supply contracts. Three-tier pricing structure across premium high-barrier, standard food-grade, and economy thin steel levels reflects oxygen ingress certification and volume scale. Cost compression in standard gauges intensifies because Vietnamese canning hubs mandate dual-source metal strategies. Multinational food processors in Southeast Asia exhibit highest price sensitivity; Japanese infant formula canners accept premium positioning for sub-0.1 cc oxygen guarantees.
Supply Chain Analysis
Export-control regimes on thermal bonding equipment limit knowledge transfer to emerging market greenfield installations, constraining supply expansion outside East Asia. Cold-rolled steel substrate draws from integrated mills in Japan, South Korea, and India; polymer films feed from petrochemical complexes in China and Thailand. Single-source vulnerability concentrates in Japanese equipment OEMs controlling lamination process parameters. Distribution runs through direct mill relationships for major can makers and regional metal service centers for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory chemistry restrictions fragment competitive positioning, creating niche windows for compliant substrate specialists as ECHA REACH deadlines compress coating conversion timelines across European can manufacturing.
For Market Incumbents: Build certification moats through simultaneous FDA 21 CFR 175.300 and EFSA food-contact approval pipelines, defending against Asian toll laminators with faster qualification cycles. Add captive cold-rolling capacity in Maharashtra and Gujarat to anchor Indian food processing corridor relationships. Prioritize backward integration into polymer film coextrusion to control barrier layer specifications. For New Entrants and Emerging Players: Pursue ready-to-drink coffee oxygen barrier specifications in Japanese convenience retail as the most penetrable premium segment, where nitrogen-flushed can requirements outpace incumbent capacity. Target Indian cold chain expansion corridors with technical service bundling that mirrors multinational processor procurement patterns. Enter through toll lamination partnerships with established cold-rolling mills to bypass capital-intensive substrate metallurgy. For Investors and Strategic Acquirers: Secondary-cycle assets sit with polymer chemistry specialists possessing thermal bonding expertise but lacking integrated steelmaking; these represent consolidation targets for metallurgical-integrated mills seeking specification access. Long-term viability hinges on circularity infrastructure deployment for film-to-steel separation capabilities. Watch for extended producer responsibility framework adoption in Southeast Asian markets as the inflection signal for regional sourcing preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Film Coextrusion | Captures oxygen barrier specification control from petrochemical suppliers in Japan and South Korea. |
| Dual-Certification Fast-Track Investment | Compresses 18-24 month FDA-EFSA validation cycles to outpace competitor qualification timelines. |
| Maharashtra-Gujarat Cold Chain Corridor Expansion | Positions captive cold-rolling capacity adjacent to multinational food processor demand concentration. |
| Thermal Lamination Equipment Partnership | Secures process control knowledge transfer from Japanese OEMs to emerging market installations. |
| Film-to-Steel Separation Infrastructure Development | Enables circularity claims in Vietnamese and Thai markets lacking comparable technical capabilities. |
Study Parameters
Initial hypotheses were tested against primary input from polymer lamination process engineers, can manufacturing procurement directors, food-contact regulatory consultants, and steel mill technical sales leads and refined through secondary validation. Customs trade data, ECHA REACH registration dossiers, FDA 21 CFR submission records, and SEC filings from integrated steel producers anchored quantitative baselines. Bottom-up volume builds across substrate gauges and top-down metallurgical capacity assessments were triangulated for convergence.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include product type tier, application barrier intensity, end-user procurement consolidation pattern, and regional regulatory cluster. CAGRs were derived from slope analysis of qualified substrate volumes against end-use demand trajectories. Forecast inputs incorporated aluminum-steel substitution elasticity coefficients and extended producer responsibility framework adoption curves.
Sensitivities concentrate around ECHA REACH enforcement intensity, scrap metal pricing volatility at electric arc furnaces, and film-to-steel separation infrastructure deployment timelines. Forecasts reflect documented assumptions regarding regulatory compliance deadlines and qualification cycle durations. Cross-checking against customs import data for laminated steel coil movements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
India Metal Cans Market
Metal Packaging
Novelty Tins Market
Metal Packaging
Beverage Metal Cans Market
Metal Packaging
Asia-Pacific Metal Packaging Market
Metal Packaging
France Metal Packaging Market
Metal Packaging
PTP Aluminum Foil Market
Metal Packaging
Converter Aluminum Foil Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
Metal Packaging Market
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
Three Piece Cans Market
Metal Packaging
Global Laminated Aluminium Foil Market
Metal Packaging
APAC Food Cans Market