
 Egypt Rigid Plastic Packaging Market | 2026-2036
Egypt Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Rigid Plastic Packaging Market Insights
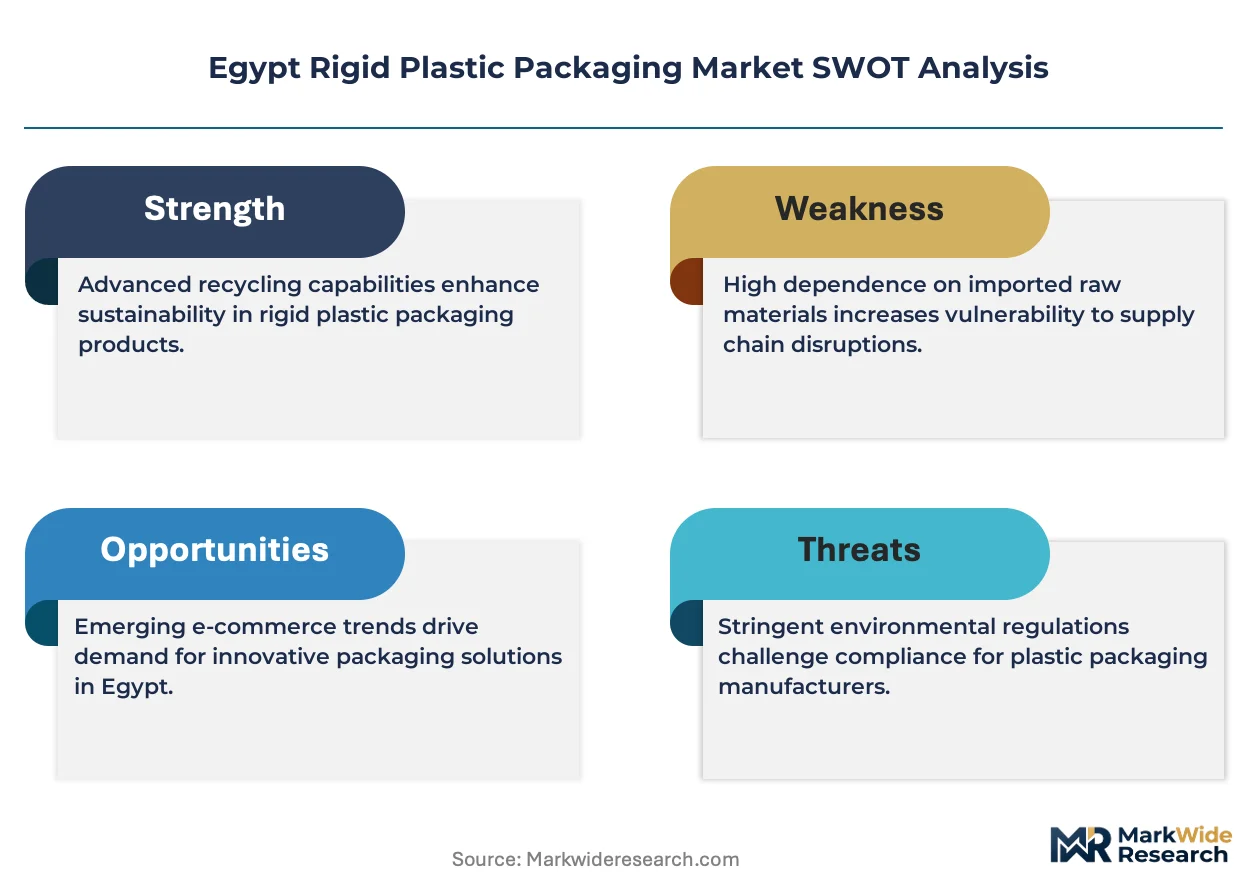
Lightweighting through mono-material PET and polypropylene designs is reconfiguring how Egyptian converters specify wall thickness, thread finish, and barrier coatings for local bottling lines. Alpla Group leverages its preform manufacturing footprint to supply dairy and beverage clients with tailored neck finishes and color-matched solutions. Egyptian Packaging & Plastic Systems anchors much of its revenue in industrial pails and jerrycans for lubricant and chemical distributors across the Suez Canal Economic Zone. Rotografia Group S.A.E. specializes in decorated containers for personal care brands, using in-mold labeling to differentiate on retail shelves in Alexandria and Tanta.
Rigid plastic packaging encompasses containers, bottles, jars, and trays formed from thermoplastic resins through injection molding, blow molding, or thermoforming, typically exceeding 0.25 mm wall thickness to provide dimensional stability and product protection during distribution. The primary purpose spans containment, preservation, and unitization of food, pharmaceuticals, chemicals, and consumer goods against moisture, oxygen, and mechanical damage. Bottles dominate volume demand from carbonated and non-carbonated beverage bottlers, while trays capture expanding share from ready-meal and fresh produce segments seeking modified-atmosphere compatibility. Polyethylene remains the workhorse material for chemical-resistant industrial containers, though polypropylene is displacing polystyrene in dairy cups and deli tubs where hot-fill tolerance matters.
Egypt's General Organization for Export and Import Control (GOEIC) enforces mandatory standards on imported resin grades and finished packaging, while the National Food Safety Authority (NFSA) regulates specific migration limits and heavy-metal thresholds for food-contact articles. These frameworks compel domestic molders to maintain batch-level compliance documentation and source from approved resin suppliers to avoid port detention or retail delisting. Stakeholders must monitor whether NFSA aligns its technical regulations with Gulf Standardization Organization (GSO) norms to preserve access to Saudi and UAE re-export channels. The decisive variable ahead is whether Egyptian resin compounders can scale food-grade polypropylene and PET chip production to reduce import dependency and stabilize input costs for converters serving Nestlé, PepsiCo, and local dairy cooperatives.
Market Dynamics
Lightweighting mandates from NFSA are compressing wall-thickness specifications across Egyptian beverage and dairy lines, forcing converters to redesign preform geometries and barrier coatings without sacrificing shelf-life performance.
Growth Catalysts
- Hot-fill polypropylene displacement:Dairy processors in the Nile Delta corridor are replacing polystyrene cups with PP alternatives that withstand pasteurization temperatures above 85°C.
- GOEIC resin-grade enforcement:Mandatory import standards are filtering substandard polyethylene out of industrial pail supply chains, elevating certified converters.
- Alexandria-Tanta retail corridor expansion:Personal care brands are commissioning decorated containers with in-mold labeling to capture shelf differentiation in Egypt's second-largest consumer market.
Market Restraints
- Food-grade resin import dependency:Egyptian compounders lack scaled virgin PET and PP chip production, exposing converters to euro-denominated raw material volatility.
- NFSA migration limit compliance costs:Batch-level documentation requirements and third-party testing are adding 8-12% to qualification expenses for small molders.
- Glass and metal substitution in premium edible oils:Exporters serving Gulf markets are switching to tinplate and amber glass for perceived quality differentiation.
Strategic Opportunities
- Suez Canal Economic Zone chemical logistics:Industrial pail demand from lubricant distributors is outpacing local blow-molding capacity, creating white space for specialized entrants.
- GSO alignment pathway:NFSA technical harmonization with Gulf Standardization Organization norms would unlock Saudi and UAE re-export channels for certified Egyptian converters.
- Mono-material design convergence:PET tray-to-film compatibility is enabling dairy and ready-meal packers to access European recycling streams.
Industry Challenges
- Barrier coating technician scarcity:Plasma-enhanced chemical vapor deposition and multi-layer coextrusion expertise is concentrated among a handful of Greater Cairo engineering teams.
- Legacy injection-blow molding retrofit costs:Converters with 1990s-era equipment face six-figure capex outlays to achieve NFSA-compliant clean-room specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Rigid Plastic Packaging Market |
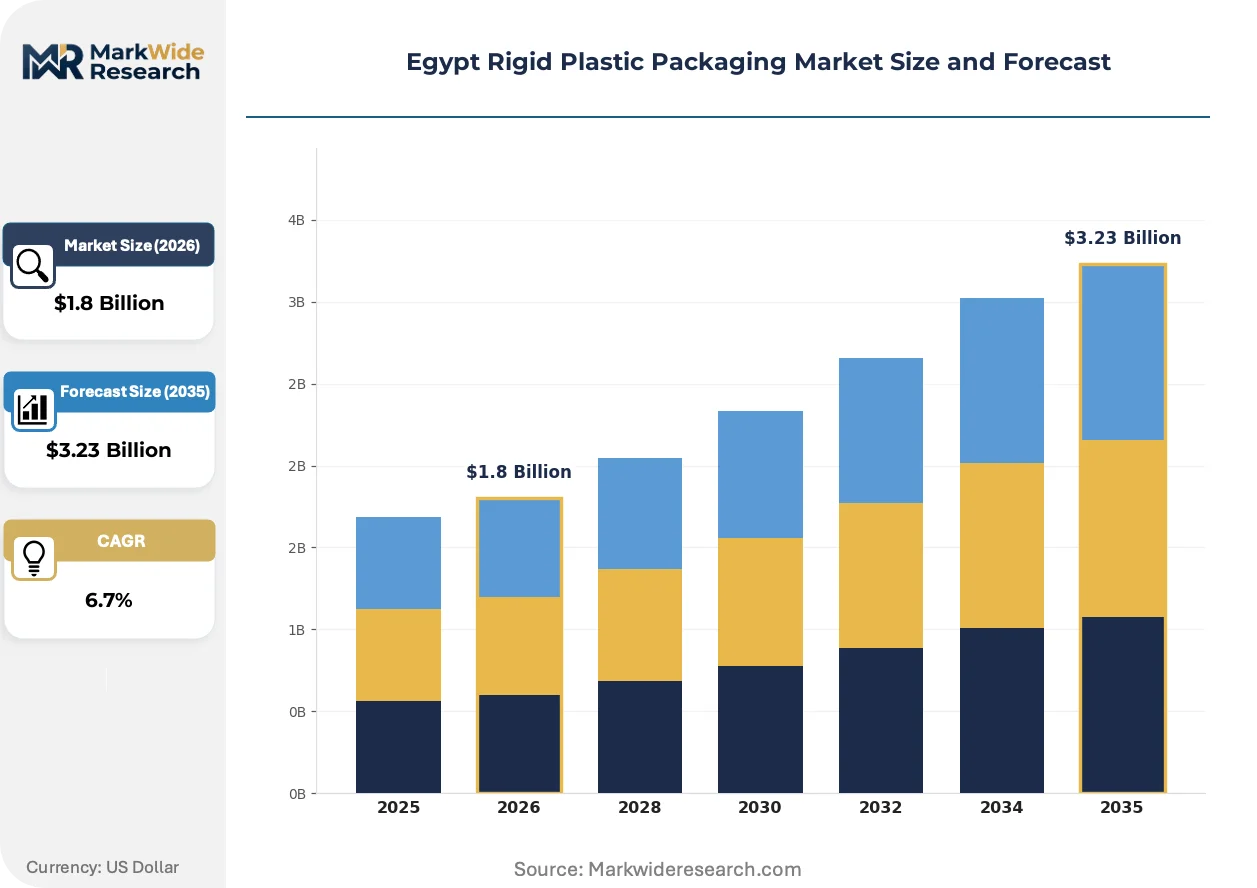
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Trays End User: Food & Beverage, Healthcare, Personal Care, Consumer Electronics Material: Polyethylene, Polypropylene, Polystyrene, PVC Application: Retail Packaging, Industrial Packaging, Food Packaging, Pharmaceutical Packaging |
| Companies Covered | Alpla Group, Bericap Holding GmbH, Amcor GmbH, NatPack, PET Egypt, Egyptian Packaging & Plastic Systems, Rotografia Group S.A.E., Modern Plast S.A.E., National Company for Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Rigid Plastic Packaging Market Trends and Innovations
Digital preform design and barrier coating virtualization are collapsing prototyping cycles for Egyptian converters serving multinational beverage and dairy accounts. These shifts are compressing time-to-market while raising technical barriers for smaller molders.
Digital twin simulation is virtualizing the traditional mold-trial process for PET bottle development. Alpla Group and Egyptian Packaging & Plastic Systems are deploying cloud-based finite element analysis to optimize wall-thickness distribution and thread-finish geometry before steel cutting. This technology is virtualizing the six-month prototype-to-production cycle that previously required multiple physical mold iterations and resin waste.
NFSA's tightened specific migration limits for heavy metals and plasticizers are triggering a compliance infrastructure buildout across the Nile Delta industrial corridor. Converters must now maintain chain-of-custody documentation from resin pellet to finished article, with third-party laboratory certification for each production batch. Dairy and edible oil segments are most affected, with several packers establishing in-house quality labs to avoid retail delisting.
Direct procurement relationships between beverage bottlers and preform specialists are disintermediating traditional distributor channels in Greater Cairo. PepsiCo and local dairy cooperatives are negotiating annual volume contracts with specified neck-finish geometries and color-matched solutions, bypassing generalist packaging traders. This pattern is most visible in carbonated soft drinks and bottled water, where SKU proliferation demands rapid specification changes that distributors cannot accommodate.
Egypt Rigid Plastic Packaging Market Segmentation
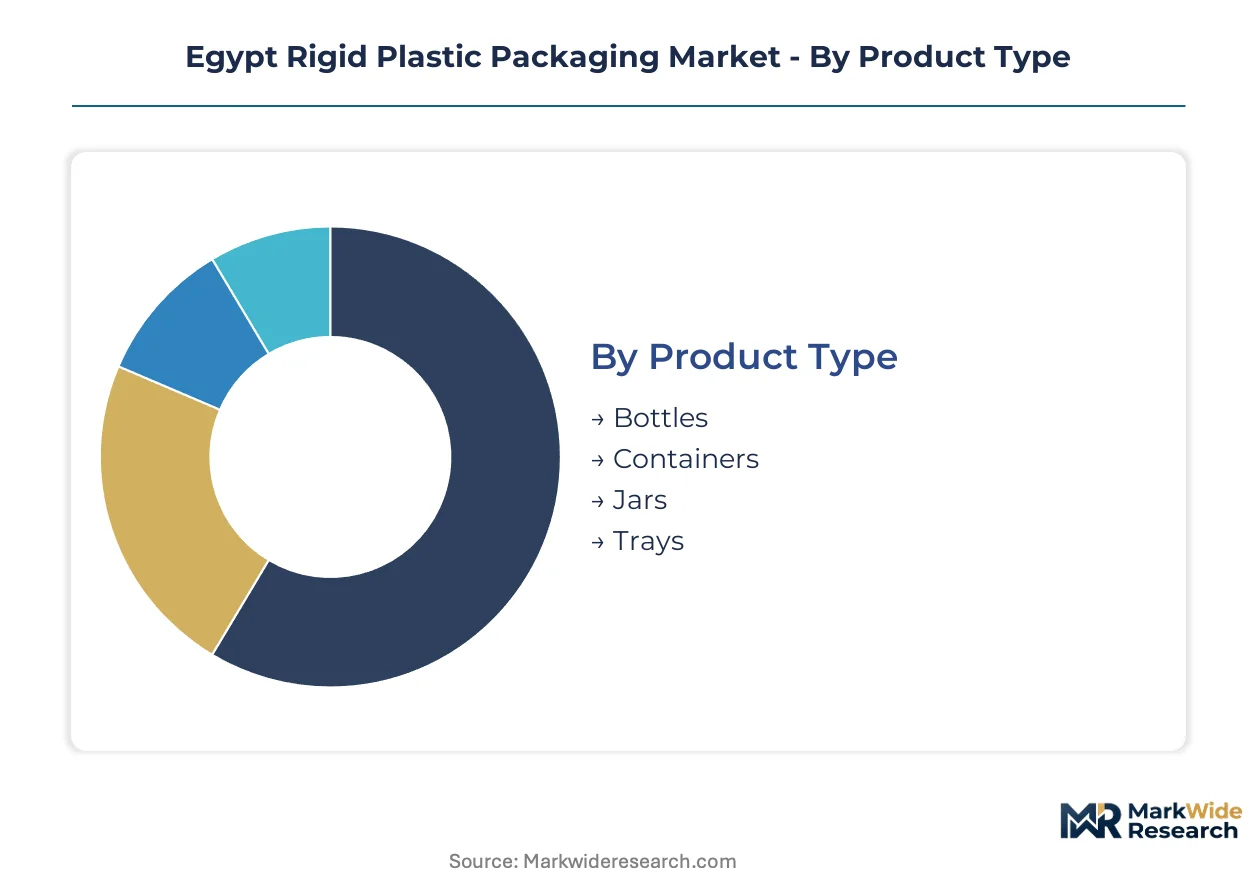
Egyptian converters configure production lines around specific product geometries and resin specifications to meet NFSA compliance requirements. Segmentation reveals where technical capabilities concentrate and which material-product combinations command premium positioning in Greater Cairo and Alexandria procurement channels.
Product Type:
After-sales service intensity varies sharply across product categories, with bottles requiring preform inventory management and thread-finish customization that jars and trays rarely demand.
- Bottles:Blow-molded or injection-stretch-blown vessels with threaded necks dominate carbonated beverage and bottled water procurement from PepsiCo and local dairy cooperatives. Demand concentrates in Greater Cairo where bottlers seek rapid specification changes for SKU proliferation. Lightweighting mandates from NFSA are compressing wall-thickness tolerances below 0.35 mm for 500 ml formats.
- Containers:Industrial pails and jerrycans formed through extrusion blow molding serve lubricant distributors across the Suez Canal Economic Zone. Egyptian Packaging & Plastic Systems anchors revenue in this segment where chemical resistance and UN certification requirements exceed consumer packaging complexity.
- Jars:Wide-mouth injection-molded vessels with snap-fit or lug closures handle spreads, sauces, and personal care creams. Alexandria processors favor in-mold labeling compatibility for retail differentiation.
- Trays:Thermoformed or injection-molded platforms with ribbed structures support modified-atmosphere packaging for fresh produce and ready-meals. Mono-material PET designs are gaining traction for European recycling stream access.
Bottles hold the largest share; momentum sits with trays as dairy and ready-meal packers seek barrier-compatible formats.
End User:
Cost tier stratification separates multinational accounts with dedicated engineering teams from price-sensitive local processors.
- Food & Beverage:Carbonated soft drinks, bottled water, dairy, and edible oil packers drive volume demand along the Nile Delta industrial corridor. NFSA migration limits and hot-fill requirements above 85°C are pushing polystyrene displacement by polypropylene in dairy cups.
- Healthcare:Pharmaceutical bottles and blister packs demand ISO-certified clean-room production and child-resistant closure compatibility. Regulatory documentation burdens exceed food-contact requirements.
- Personal Care:Decorated containers with in-mold labeling serve shampoo, lotion, and cosmetic brands in Alexandria and Tanta retail corridors. Shelf differentiation commands 15-20% price premiums over standard formats.
- Consumer Electronics:Anti-static trays and clamshells protect components during assembly and distribution. Demand tracks electronics manufacturing investment in the Suez Canal Economic Zone.
Food & Beverage commands the largest share; Healthcare is expanding most quickly as domestic pharmaceutical production scales.
Material:
Supply concentration around imported resin grades creates margin pressure that favors converters with backward integration into compounding or long-term supplier contracts.
- Polyethylene:HDPE and LDPE grades remain the workhorse for chemical-resistant industrial containers and milk bottles. GOEIC enforcement is filtering substandard imports, elevating certified converters with approved supplier documentation.
- Polypropylene:Homopolymer and random copolymer grades displace polystyrene in hot-fill dairy applications and microwaveable ready-meal trays. Egyptian compounders lack scaled food-grade chip production, exposing converters to euro-denominated volatility.
- Polystyrene:Crystal and high-impact grades retain share in cold-fill dairy and disposable cutlery where cost minimization outweighs heat tolerance. Regulatory pressure and substitution are compressing growth trajectories.
- PVC:Rigid and plasticized formulations serve pharmaceutical blister packs and specific chemical containers. Environmental scrutiny and recycling incompatibility limit expansion in food-contact applications.
Polyethylene retains the largest share; Polypropylene is gaining share fastest through hot-fill substitution and barrier tray adoption.
Application:
Customer type segmentation separates brand-owner direct procurement from distributor-mediated supply, with the former demanding faster specification turnaround and dedicated technical support.
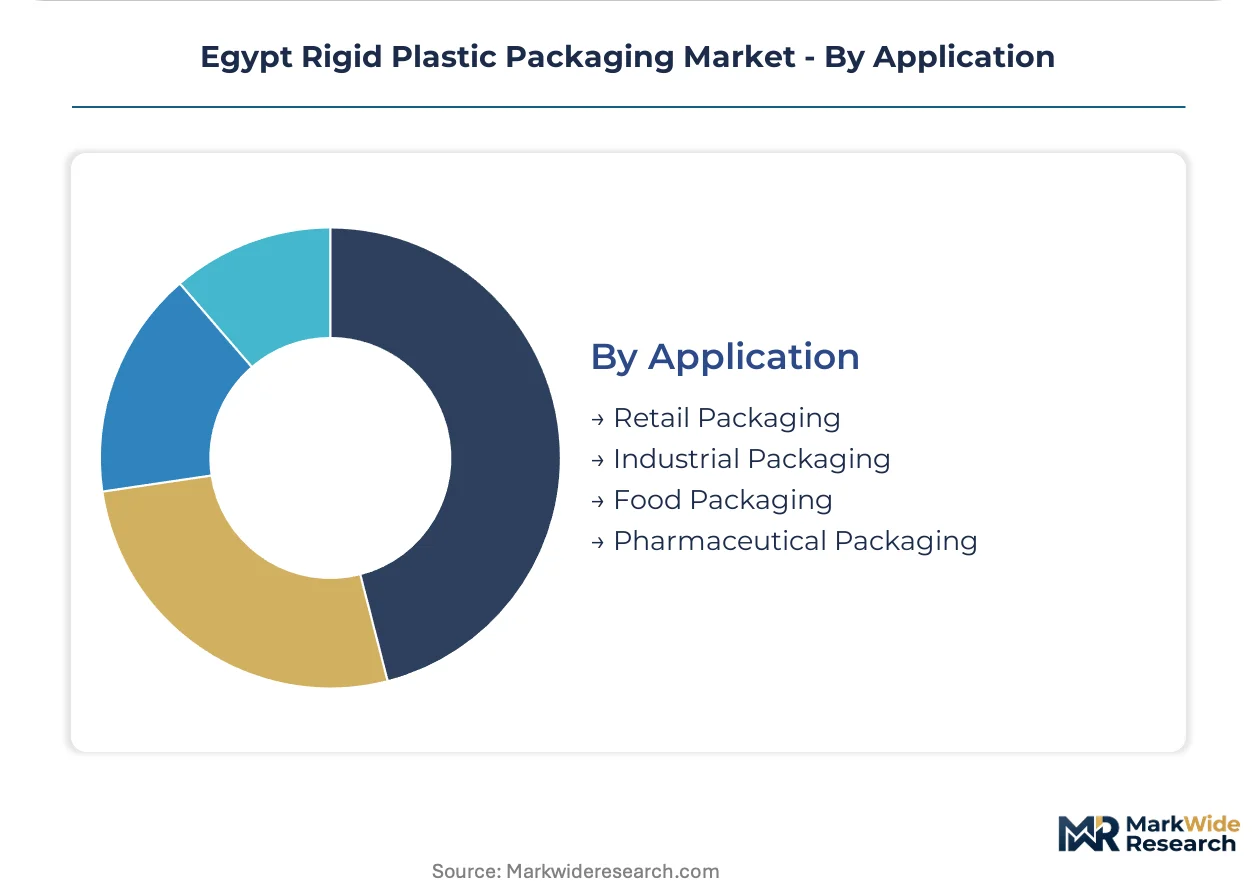
- Retail Packaging:Shelf-ready bottles, jars, and decorated containers with point-of-sale differentiation serve hypermarkets and convenience stores in Greater Cairo and Alexandria. In-mold labeling and color-matched solutions command technical collaboration between converters and brand owners.
- Industrial Packaging:Pails, drums, and jerrycans for lubricants, chemicals, and agrochemicals require UN certification and chemical compatibility testing. Suez Canal Economic Zone logistics growth is outpacing local blow-molding capacity.
- Food Packaging:Modified-atmosphere trays, barrier bottles, and dairy cups face the strictest NFSA migration limits and batch-level documentation requirements. Several packers have established in-house quality labs to avoid retail delisting.
- Pharmaceutical Packaging:Child-resistant bottles, blister packs, and compliance-prompted dispensers demand ISO 15378 certification and clean-room production environments. Regulatory compliance costs exceed other segments by 25-30%.
Retail Packaging holds the largest share; Pharmaceutical Packaging shows the steepest expansion trajectory as domestic drug manufacturing scales and export registration requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egyptian rigid plastic packaging exports flow primarily toward Saudi Arabia and the UAE, with converters in Greater Cairo and Alexandria positioning for Gulf re-export channels under potential GSO harmonization pathways.
Greater Cairo
Beverage bottlers and dairy processors cluster along the Nile Delta industrial corridor, driving concentrated demand for PET bottles and hot-fill polypropylene cups. NFSA migration limits compel batch-level compliance documentation from resin pellet to finished article. Obour City and 10th of Ramadan host the densest converter populations serving PepsiCo and Nestlé procurement teams.
Alexandria
Personal care brands commission decorated containers with in-mold labeling to capture shelf differentiation in Egypt's second-largest consumer market. The Alexandria-Tanta retail corridor expansion pulls specialized molding capacity toward cosmetic and shampoo packaging. GOEIC enforcement at Alexandria Port filters substandard resin imports, elevating certified converters with approved supplier documentation.
Suez Canal Economic Zone
Industrial pail demand from lubricant distributors outpaces local blow-molding capacity, creating white space for specialized entrants. Chemical logistics growth through Ain Sokhna and East Port Said anchors Egyptian Packaging & Plastic Systems revenue in UN-certified jerrycans. The zone's free-trade status attracts re-export-oriented packaging investment targeting African and Levantine markets.
Nile Delta Governorates
Dairy cooperatives in Sharqia, Dakahlia, and Gharbia displace polystyrene with polypropylene cups that withstand pasteurization temperatures above 85°C. Hot-fill tolerance requirements reshape procurement specifications for local milk processors. Several packers have established in-house quality labs to avoid retail delisting under tightened NFSA technical regulations.
Red Sea Coastal Belt
Hurghada and Safaga hospitality sectors generate seasonal demand for disposable rigid containers serving tourism supply chains. Limited local production capacity forces reliance on Cairo-based distributors with extended lead times. The segment remains price-sensitive, with cost minimization outweighing barrier performance or decoration requirements.
Egypt Rigid Plastic Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where multinational preform suppliers and local industrial pail molders occupy distinct competitive spaces. The market segments into three strategic archetypes: international preform specialists with direct bottler relationships, domestic industrial packaging generalists serving chemical distributors, and decorated container specialists targeting personal care shelf differentiation. Competitive moves concentrate on GSO certification pursuit for Gulf market access and mono-material design convergence for European recycling stream eligibility.
Among Austria-based packaging multinationals, Alpla Group exemplifies the preform-specialist archetype through its manufacturing footprint supplying tailored neck finishes and color-matched solutions. German rigid packaging conglomerates represented by Bericap Holding GmbH and Amcor GmbH occupy positions emphasizing closure systems and barrier technologies. Egyptian Packaging & Plastic Systems anchors the domestic industrial packaging tier, while Rotografia Group S.A.E. exemplifies the decorated-container specialization path. These named entities represent competitive positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Alpla Group |
| Bericap Holding GmbH |
| Amcor GmbH |
| NatPack |
| PET Egypt |
| Egyptian Packaging & Plastic Systems |
| Rotografia Group S.A.E. |
| Modern Plast S.A.E. |
| National Company for Packaging |
| Others |
Pricing and Supply Chain Analysis
Greater Cairo converter clusters wield disproportionate pricing power over Nile Delta dairy processors due to concentrated blow-molding capacity and NFSA-compliant clean-room scarcity. Euro-denominated virgin PET and PP chip imports transmit currency volatility directly into converter cost structures, forcing margin compression onto price-sensitive local packers.
Pricing Analysis
Legacy injection-blow molding equipment versus digital twin-enabled preform design creates a three-tier pricing structure across premium, standard, and economy levels. Certification grade and volume scale drive price differentiation, with NFSA-compliant batch documentation adding qualification premiums. Cost compression in economy tiers is intensifying because small molders lack backward integration into resin compounding. Local dairy cooperatives exhibit highest price sensitivity; multinational beverage bottlers with direct preform contracts show lowest.
Supply Chain Analysis
Extended payment terms from Suez Canal lubricant distributors are reshaping working capital requirements for industrial pail molders. Resin supply concentrates in Saudi Arabia, UAE, and Turkey as re-export channels for Egyptian converters. Raw material dependencies rest on imported virgin PET chips, food-grade polypropylene, and certified barrier additives. Single-source vulnerability around European resin suppliers exposes converters to euro volatility. Distribution runs through Alexandria Port clearance and Greater Cairo converter direct-to-bottler relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's rigid plastic packaging sector is accelerating through NFSA regulatory tightening and mono-material design convergence, creating structural advantages for compliant converters.
For Market Incumbents: Build certification moats around GSO-aligned quality infrastructure to defend against Gulf re-export competitors. Invest in captive barrier coating capability to offset technician scarcity in Greater Cairo. Expand clean-room capacity in 10th of Ramadan to capture pharmaceutical packaging migration from food-contact segments. For New Entrants and Emerging Players: Suez Canal Economic Zone chemical logistics present the most penetrable white space, where industrial pail demand outstrips local blow-molding capacity. Target UN-certified jerrycan supply to lubricant distributors with specialized chemical resistance engineering. Establish direct procurement relationships with Ain Sokhna logistics operators to bypass Cairo distributor intermediation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because NFSA migration limits and GSO harmonization pathways are consolidating market share toward certified converters. Acquisition targets include mid-cap molders with existing clean-room infrastructure and approved resin supplier documentation. Watch for NFSA alignment announcements with Gulf Standardization Organization norms as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive food-grade PP production reduces euro-denominated import exposure for Nile Delta converters. |
| GSO Certification Investment | Unlocks Saudi and UAE re-export channels for Egyptian Packaging & Plastic Systems and similar certified molders. |
| Digital Twin Preform Design Deployment | Collapses prototyping cycles for Alpla Group beverage clients seeking rapid SKU proliferation support. |
| Barrier Coating Capability Buildout | Addresses plasma-enhanced CVD technician scarcity constraining NFSA-compliant dairy packaging expansion. |
| Suez Canal Economic Zone Capacity Expansion | Captures industrial pail demand from lubricant distributors outpacing local blow-molding supply. |
Research Methodology
Operator-level perspectives from preform manufacturing engineers, dairy procurement managers, NFSA compliance officers, and Suez Canal logistics coordinators anchored the qualitative base. Primary interviews combined with secondary validation from GOEIC import standards documentation, NFSA technical regulations, customs trade records, and SEC filings of multinational packaging suppliers. Bottom-up converter capacity assessments and top-down demand modeling from beverage bottler procurement data were triangulated.
Scenario-bracketing framed volume and value outputs across the analysis window, with segmentation by product type, material grade, end-use industry, and geographic production cluster. CAGRs derived from resin consumption trends, bottler capacity expansion announcements, and regulatory compliance cost trajectories. Forecast inputs included NFSA migration limit implementation timelines and GSO harmonization probability assessments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by resin compounders or Gulf packaging multinationals would shift outcomes. Macroeconomic currency volatility, regulatory deviation from GSO norms, or breakthrough barrier coating technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
Mexico Rigid Plastic Packaging Market
Rigid Packaging
Vietnam Rigid Plastic Packaging Market
Rigid Packaging
Rigid Packaging Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
Rigid Food Containers Market
Rigid Packaging
Europe Rigid Bulk Packaging Market
Rigid Packaging
Rigid Boxes Market
Rigid Packaging
Rigid Trays Market
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Plastic Packaging Market
Rigid Packaging
United States Rigid Plastic Packaging Market
Rigid Packaging
Mono-Material Trays Market