
 Novelty Tins Market | 2026-2036
Novelty Tins Market Size, Share, and Industry Trends Forecast 2026-2036
Novelty Tins Market Analytics
Aftermarket collectible resale and licensed commemorative editions is tilting margin pools away from mass-production commodity tins. Tinshine leverages vertical integration across stamping and lithography to control cost structures in decorative storage. Hallmark Cards anchors seasonal gift tin cycles through proprietary design partnerships with entertainment licensors. Allstate Can Corporation competes on manufacturing scale, supplying steel containers to private-label food programs across North American retail channels.
Novelty tins are rigid metal or compostable containers engineered through deep-draw stamping, offset lithography, and food-safe interior coating processes, primarily serving brand differentiation, collectible retention, and premium packaging functions in consumer goods. Gift tins and collectible variants carry the highest margin concentration due to licensed imagery and limited-edition scarcity mechanics. Food containers remain the volume base, though steel material specifications face substitution pressure from aluminum and eco-friendly compostable alternatives as sustainability procurement standards tighten among European retailers and event planners.
The FDA governs direct food-contact coatings and substrates for tin containers distributed in the United States, while REACH and RoHS constrain heavy metal content and chemical composition across European supply chains. The EU Green Deal and emerging extended producer responsibility frameworks are forcing material transitions toward recyclable or compostable substrates, reshaping supplier qualification requirements. Stakeholders must monitor how dual regulatory tracks for food safety and circularity converge to determine which material platforms retain market access.
Market Dynamics
REACH compliance across the European Union is collapsing the supplier base for coated metal containers, forcing material transitions toward recyclable substrates and reshaping qualification requirements for heritage biscuit tin producers and seasonal gift packaging programs.
Growth Catalysts
- EU Green Deal Extended Producer Responsibility:Mandates for recyclable packaging accelerate demand for steel and aluminum alternatives in confectionery gift programs across Germany, France, and Italy.
- Heritage Collectible Retention:United Kingdom consumers sustain premium pricing for limited-edition commemorative tins, creating recurring seasonal revenue cycles for biscuit and confectionery brands.
- Deep-Draw Stamping Automation:Precision manufacturing advances reduce per-unit lithography costs for short-run decorative storage containers serving event planning and corporate gifting verticals.
Market Restraints
- Steel Input Cost Volatility:Cold-rolled steel pricing fluctuations compress margins for mass-production food container programs serving private-label retail channels.
- Coating Chemistry Constraints:REACH and RoHS heavy metal restrictions eliminate legacy epoxy-phenolic interior coatings, requiring costly reformulation of food-safe barrier systems.
- Aluminum Substitution Pressure:Lightweight metal alternatives displace steel in travel retail and airline catering applications where weight reduction drives procurement decisions.
Strategic Opportunities
- Compostable Substrate White Space:Fiber-based molded containers with metallized finishes capture sustainability-driven event planning contracts in Scandinavia and the Netherlands.
- Licensed Entertainment Convergence:Cross-property commemorative editions combining streaming content, sports franchises, and heritage brands unlock collector premiums in North American and Asian markets.
- Direct-to-Consumer Channel Expansion:Subscription-box curation models bypass traditional retail markups for limited-run artisan confectionery packaging.
Industry Challenges
- Food-Safe Coating Certification Timelines:EFSA novel food contact substance approvals extend 18-24 months, delaying product launches for reformulated interior barriers.
- Lithographic Skill Compression:Offset printing expertise for metallic substrates concentrates among aging workforce cohorts in Sheffield, England and Solingen, Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Novelty Tins Market |
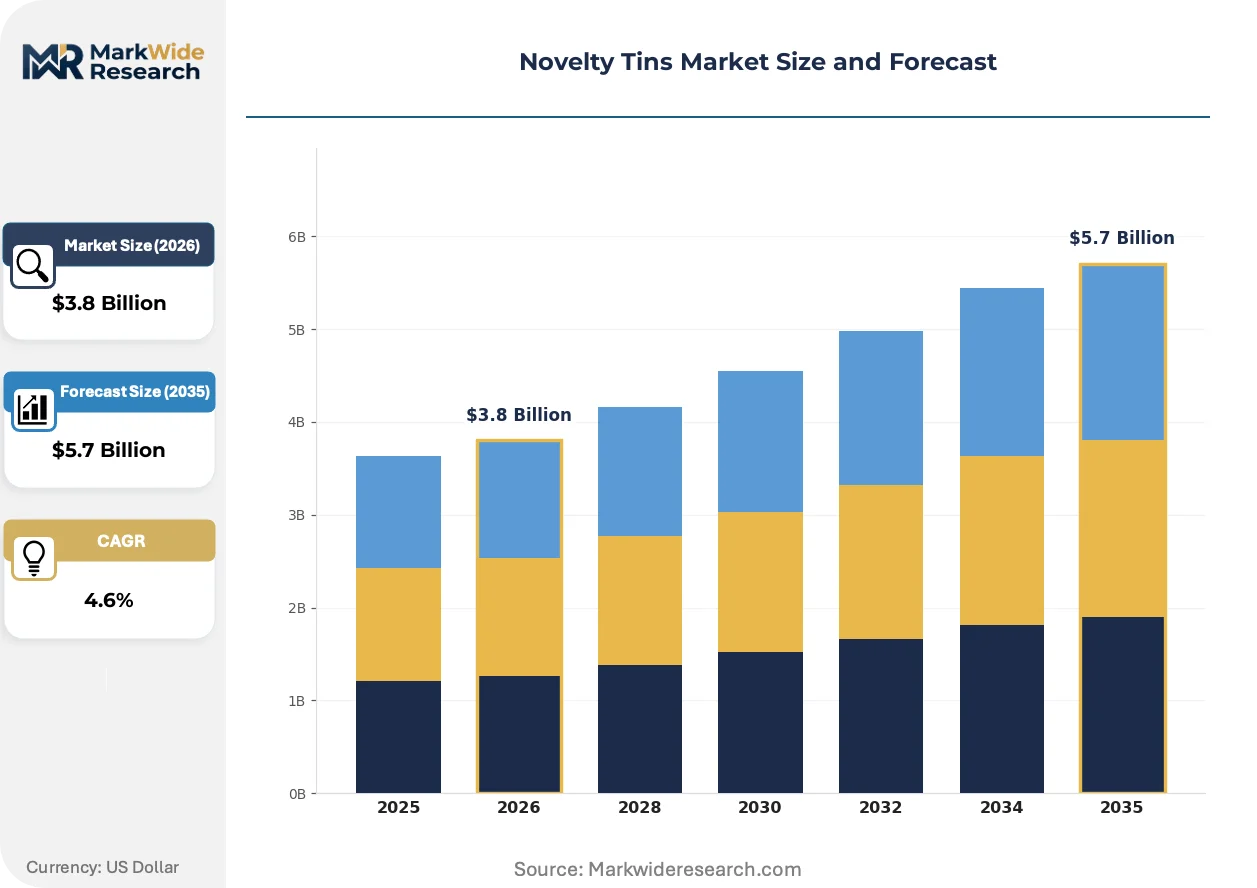
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Containers, Collectible Tins, Gift Tins, Decorative Storage Material: Steel, Aluminum, Plastic, Eco-friendly Compostable End User: Retailers, Manufacturers, Individual Consumers, Event Planners Design Style: Vintage, Modern, Themed, Minimalistic |
| Companies Covered | Tinshine, Allstate Can Corporation, Hallmark Cards, Ganz, DesignWorks Ink, Pavilion, Huntley & Palmers, Peek Frean, McVitie's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Novelty Tins Market Evolving Landscape
Digital printing integration and material science advances are collapsing traditional boundaries between mass-production food containers and premium collectible packaging, enabling economically viable short runs that previously required manual artisan processes.
Water-based UV-curable inks for metallic substrates is collapsing the minimum order quantity threshold for custom lithography. Mid-sized confectionery brands in Belgium and Switzerland now commission 5,000-unit runs with photographic image reproduction previously reserved for 100,000-unit programs. This compression erodes the volume advantage of integrated stamping-lithography facilities.
The EU Green Deal's packaging and packaging waste regulation revision tightens recycled content mandates for single-use containers. Steel producers in Spain and Poland must certify post-consumer scrap percentages, while coating suppliers reformulate to eliminate BPA-based epoxies. Food-contact compliance documentation now requires third-party verification through ECHA-recognized laboratories.
Collector behavior has pivoted toward unboxing experience and social media documentation. Limited-edition tin releases from heritage British biscuit manufacturers generate secondary market premiums within 48 hours of sellout. This rotation toward speculative acquisition compresses traditional retail inventory cycles and forces brands to manage scarcity signaling through numbered certificates and regional allocation limits.
Novelty Tins Market Segmentation
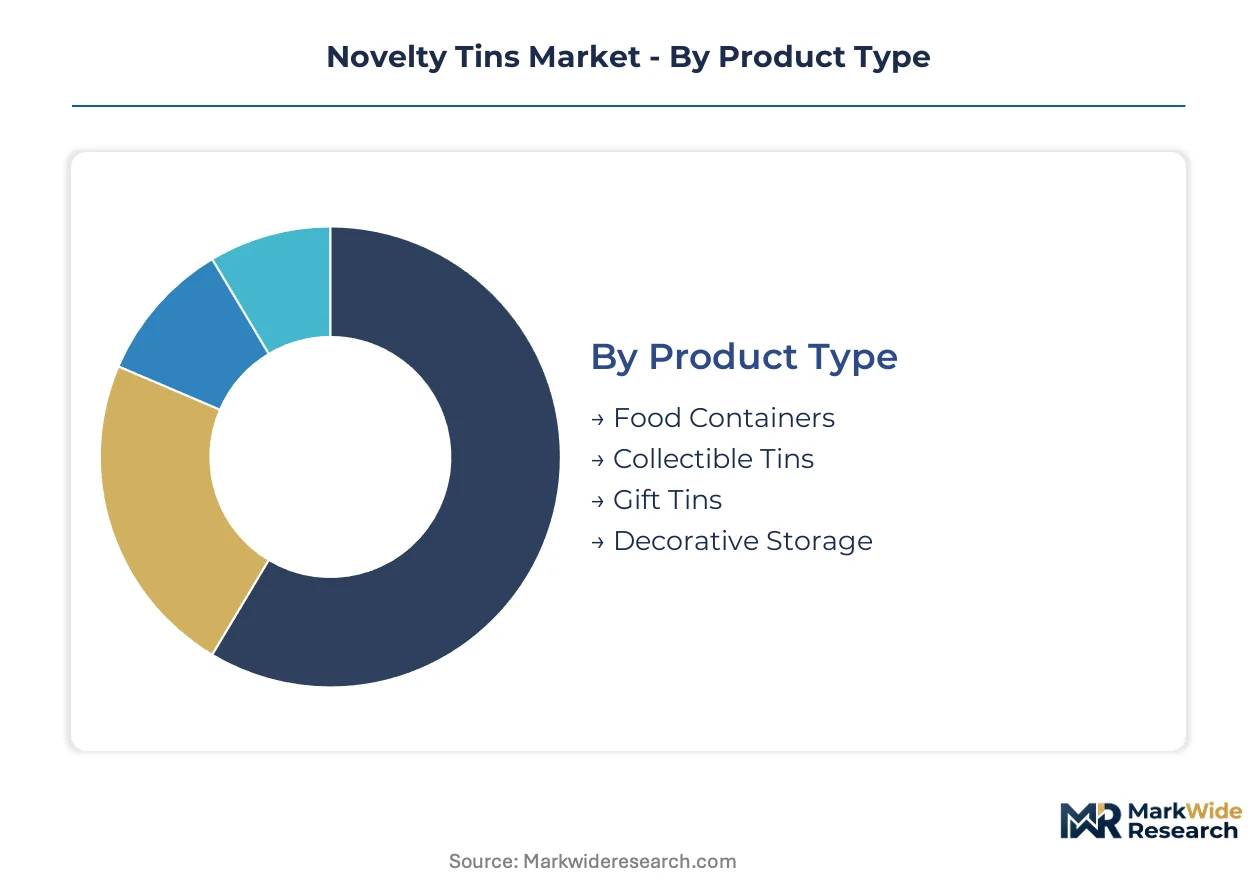
Segmentation in the novelty tins market reveals how functional requirements diverge across food safety mandates, collector retention mechanics, and sustainability procurement standards. Understanding these splits enables suppliers to align stamping capacity and coating certification investments with margin-concentrated demand pockets.
Product Type:
Mature commodity formats coexist with emerging premium categories that command scarcity-driven pricing power.
- Food Containers:Deep-drawn steel cylinders and rectangular formats with epoxy-phenolic interior barriers serve biscuit, confectionery, and tea packaging programs. Mass-production scale dominates private-label retail channels in Germany and France where EFSA-compliant coating documentation is mandatory for market access.
- Collectible Tins:Limited-edition commemorative formats leverage numbered certificates and regional allocation limits to sustain secondary market premiums. United Kingdom heritage biscuit manufacturers rotate seasonal releases that generate speculative acquisition behavior and compress traditional inventory cycles.
- Gift Tins:Licensed imagery partnerships with entertainment properties drive margin concentration through proprietary design exclusivity.
- Decorative Storage:Short-run artisan formats serve event planning and corporate gifting verticals enabled by digital printing compression of minimum order quantities.
Food Containers handles the majority of throughput; Collectible Tins is the fastest mover on share.
Material:
Cost tier stratification separates legacy metal substrates from emerging compostable alternatives reshaping qualification requirements.
- Steel:Cold-rolled tinplate and electrolytic chromium-coated steel (ECCS) remain the volume foundation for food-contact applications. REACH and RoHS compliance constraints are eliminating legacy coating chemistries and forcing costly reformulation of barrier systems across European supply chains.
- Aluminum:Lightweight rolled metal displaces steel in travel retail and airline catering procurement where weight reduction drives specification decisions. Deep-draw stamping automation advances reduce per-unit lithography costs for aluminum formats serving Scandinavian sustainability-driven retailers.
- Plastic:Thermoformed and injection-molded polymers retain niche positioning in non-food decorative applications.
- Eco-friendly Compostable:Fiber-based molded containers with metallized finishes capture event planning contracts in the Netherlands and Denmark under EU Green Deal extended producer responsibility mandates.
Steel retains the dominant cost position; Eco-friendly Compostable is expanding most quickly as procurement standards tighten.
End User:
Volume concentration versus margin capture splits across institutional procurement and direct-to-consumer acquisition patterns.
- Retailers:Supermarket chains and specialty food stores drive seasonal gift tin cycles through inventory commitments that anchor manufacturing planning. Private-label programs in North American mass-market channels prioritize unit cost over lithographic complexity.
- Manufacturers:Confectionery and biscuit brands commission custom formats where licensed imagery and heritage design partnerships differentiate shelf positioning. Belgian and Swiss mid-sized brands now execute 5,000-unit photographic reproduction runs previously reserved for 100,000-unit programs.
- Individual Consumers:Collector behavior has pivoted toward unboxing experience documentation and speculative secondary market participation.
- Event Planners:Corporate gifting and wedding verticals demand short-run customization with compressed lead times.
Retailers handle the dominant volume share; Individual Consumers is climbing the fastest as direct-to-subscription models bypass traditional markups.
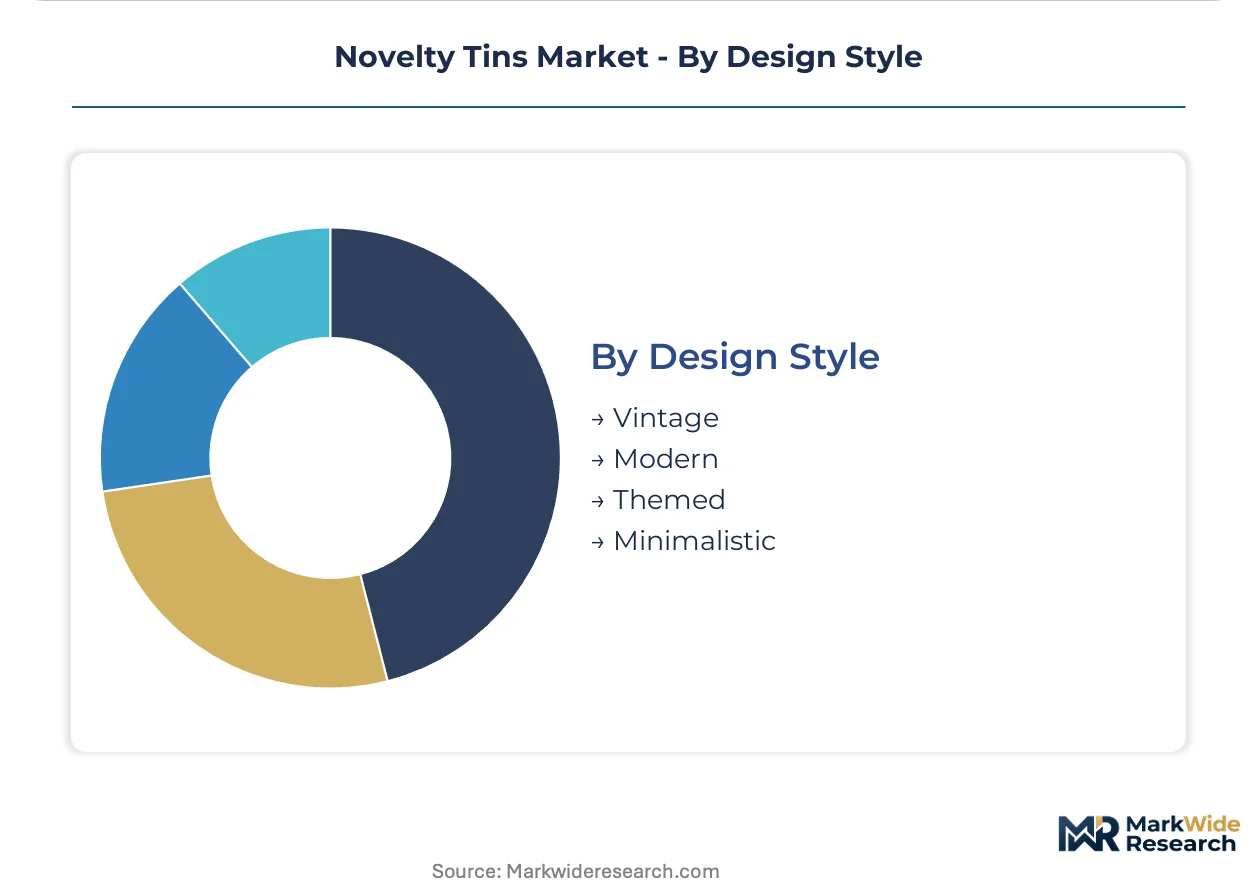
Design Style:
Margin stratification separates heritage nostalgia formats from contemporary minimalism serving distinct demographic acquisition patterns.
- Vintage:Nostalgia-driven lithography reproducing Victorian typography and pastoral imagery sustains premium pricing in United Kingdom heritage collections. Sheffield and Solingen printing expertise for metallic substrates concentrates among aging workforce cohorts, creating capability scarcity.
- Modern:Clean geometric patterns and photographic image reproduction serve confectionery brands targeting younger demographics through social media documentation behavior.
- Themed:Cross-property entertainment licensing combining streaming content, sports franchises, and heritage properties unlocks collector premiums in North American and Asian markets.
- Minimalistic:Unadorned or single-color formats align with sustainability signaling and reduced coating complexity for compostable substrate transitions.
Vintage commands the highest margin per unit; Themed is gaining share fastest through licensed convergence strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies: United Kingdom collectors absorb substantial premiums for heritage commemorative releases while German private-label buyers drive hard bargains on food-container contracts. This demand bifurcation shapes where suppliers deploy lithographic sophistication versus mass-production scale.
United Kingdom
Heritage biscuit manufacturers command collector premiums through seasonal limited editions that generate secondary market speculation within 48 hours. REACH compliance documentation now requires ECHA-recognized laboratory verification for all food-contact coatings. Sheffield's aging lithographic workforce concentrates scarce metallic-substrate printing expertise that sustains Victorian nostalgia reproduction.
Germany
Confectionery brands commission mid-sized 5,000-unit runs enabled by digital printing compression that erodes traditional volume advantages. The EU Green Deal's extended producer responsibility mandates accelerate recyclable packaging transitions across retail channels. Solingen retains specialized offset printing capability for metallic substrates amid workforce compression.
United States
FDA food-contact coating regulations govern tinplate distribution while private-label mass-market channels prioritize unit cost over decorative complexity. Seasonal gift cycles anchor manufacturing planning through supermarket inventory commitments. Midwest steel-container fabricators supply North American retail programs at manufacturing scale.
France
Belgian and Swiss mid-sized brands now access photographic lithography previously reserved for 100,000-unit programs, compressing minimum order thresholds. ANSM oversees food-contact substance safety alongside EU-wide EFSA compliance requirements. Paris-based event planners drive short-run corporate gifting demand with compressed lead-time expectations.
Netherlands
Scandinavian sustainability procurement standards penetrate Dutch retail channels, accelerating fiber-based molded container adoption with metallized finishes. EU packaging waste regulation revisions tighten recycled content certification requirements for single-use formats. Amsterdam event planning verticals capture compostable substrate contracts under circular economy frameworks.
Novelty Tins Market Competitive Landscape
Capability concentration sits with heritage lithography specialists; scale advantage sits with integrated stamping-lithography facilities. The supplier base splits between premium collectible producers wielding licensed design partnerships and mass-production fabricators serving private-label food programs. Three archetypes dominate: vertically integrated decorative storage manufacturers, seasonal gift-cycle anchors with entertainment licensing relationships, and steel-container scale suppliers to retail channels. Competitive moves center on coating chemistry reformulation for regulatory compliance and digital printing adoption to collapse short-run economics.
Within the heritage collectible tier, Huntley & Palmers and McVitie's exemplify United Kingdom-based manufacturers leveraging seasonal commemorative releases to sustain speculative secondary markets. Tinshine occupies a position representing integrated stamping-lithography control over decorative storage cost structures. Allstate Can Corporation sits within the scale-driven archetype supplying steel containers to North American private-label programs. Hallmark Cards anchors the seasonal gift-cycle vector through proprietary design partnerships with entertainment licensors.
| Leading Market Players |
|---|
| Tinshine |
| Allstate Can Corporation |
| Hallmark Cards |
| Ganz |
| DesignWorks Ink |
| Pavilion |
| Huntley & Palmers |
| Peek Frean |
| McVitie's |
| Others |
Value Network & Pricing Analysis
Sheffield's concentrated lithographic workforce anchors premium pricing for metallic-substrate reproduction, translating scarce Victorian nostalgia expertise into sustained collector premiums for United Kingdom heritage manufacturers while compressing margins for mass-production food container programs elsewhere.
Pricing Analysis
Aftermarket collectible resale and licensed commemorative editions now command lifetime value multiples exceeding original retail. Three-tier pricing structure across premium, standard, and economy levels separates heritage numbered-certificate releases from private-label food programs and commodity decorative storage. Pricing pressure stems from cold-rolled steel input volatility compressing margins for mass-production channels. Private-label retail buyers in Germany and France exhibit highest price sensitivity; United Kingdom collectors absorb substantial premiums for limited-edition scarcity mechanics.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates raw material procurement risk for coating chemistry inputs. Supply concentration rests on China for cold-rolled steel substrates, Germany for specialized offset printing equipment, and the United Kingdom for heritage lithographic expertise. Deep-draw stamping automation and food-safe interior coating formulations constitute critical component dependencies. Single-source vulnerability concentrates in Sheffield and Solingen for metallic-substrate printing capability. Distribution runs through supermarket seasonal inventory commitments, direct-to-consumer subscription channels, and event planning corporate gifting verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Novelty tins represent an early-cycle expansion story as EU Green Deal extended producer responsibility mandates accelerate material transitions toward recyclable and compostable substrates, creating new qualification requirements that favor adaptive suppliers.
For Market Incumbents: Entrench lithographic sophistication advantages by capturing aging workforce knowledge through apprenticeship programs in Sheffield and Solingen before capability scarcity intensifies. Pursue backward integration into coating chemistry reformulation to secure EFSA-compliant barrier systems ahead of certification bottlenecks. Aluminum substitution pressure in travel retail and airline catering demands proactive material platform diversification.
For New Entrants and Emerging Players: Build out fiber-based molded container capabilities with metallized finishes to capture Scandinavian and Dutch event planning contracts under circular economy frameworks. The Netherlands and Denmark offer most penetrable geography for compostable substrate adoption. Pursue direct-to-consumer subscription-box curation models that bypass traditional retail markups and compress customer acquisition costs.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated decorative storage manufacturers with in-house stamping and lithography control over cost structures. Long-term viability hinges on coating chemistry reformulation capabilities and digital printing adoption for short-run economics. Watch EFSA novel food contact substance approval timelines as inflection indicator for product launch velocity and competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Reformulation | REACH and RoHS compliance eliminates legacy epoxy-phenolic barriers, requiring ECHA-recognized laboratory verification. |
| Digital Printing Integration | Water-based UV-curable inks collapse minimum order quantities from 100,000 to 5,000 units for Belgian and Swiss brands. |
| Compostable Substrate Development | Fiber-based molded containers with metallized finishes capture EU Green Deal-driven event planning contracts in Scandinavia. |
| Licensed Entertainment Convergence | Cross-property commemorative editions combining streaming content and sports franchises unlock collector premiums in North America. |
| Direct-to-Consumer Channel Expansion | Subscription-box curation models bypass traditional retail markups for limited-run artisan confectionery packaging programs. |
Research Methodology
Initial hypotheses were tested against primary input from heritage biscuit manufacturer brand managers, coating chemistry R&D directors, steel container procurement leads at confectionery brands, and event planning corporate gifting specialists, then refined through secondary validation against ECHA regulatory filings, EFSA food contact substance databases, EU packaging waste regulation revisions, and customs trade data for cold-rolled steel and aluminum inputs, with bottom-up segment sizing triangulated against top-down market construction.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling novelty tin consumption by product type, material substrate, end-user channel, and design style segmentation, with CAGRs derived from elasticity-adjusted volume trajectories and value-per-unit evolution, incorporating steel and aluminum price forecasting, coating certification timeline assumptions, and digital printing adoption curves as industry-specific inputs.
Stress conditions across raw material price volatility, regulatory approval delays, and workforce retirement rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about substitution elasticities and sustainability procurement acceleration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Australia Metal Packaging Market
Metal Packaging
Honeycomb Aluminum Foil Market
Metal Packaging
United Arab Emirates Metal Packaging Market
Metal Packaging
Global Laminated Steel for Cans Market
Metal Packaging
Saudi Arabia Metal Packaging Market
Metal Packaging
Metal Drums Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
Aluminum Foil Packaging Market
Metal Packaging
Europe Metal Closures Market
Metal Packaging
Asia Pacific Metal Cans Market
Metal Packaging
Aluminum Foil Lids Market
Metal Packaging
Household Aluminum Foils Market
Metal Packaging
North America Metal Cans Market
Metal Packaging
Metal Cans Market
Metal Packaging
Three Piece Cans Market
Metal Packaging
France Metal Packaging Market