
 Global Paper Napkin Making Machine Market | 2026-2036
Global Paper Napkin Making Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Paper Napkin Making Machine Market Outlook
Quick-service restaurant chains across Southeast Asia are recalibrating their disposable tableware procurement standards, pulling higher-capacity automatic napkin machines into the spotlight. Delta Paper Machine leverages its manufacturing scale to anchor supply relationships across India's growing QSR infrastructure. Beston (Henan) Machinery Co., Ltd. competes aggressively on electric-drive technology leadership, while Foshan Baosuo Machinery Manufacturing specializes in compact footprint designs for urban food courts.
Paper napkin making machines are industrial converting systems that transform parent tissue rolls into folded, embossed, and cut napkin products through processes involving unwind stands, rotary embossing units, folding mechanisms, and final cutting stations; operating speeds typically range from 200 to 800 pieces per minute depending on configuration. Automatic machines dominate the installed base due to labor cost pressures in commercial foodservice, while electric technology segments are attracting capital as hydraulic systems face energy efficiency scrutiny. Specialty machines occupy narrower margin pools but command premium positioning among boutique hotel suppliers seeking custom embossing capabilities.
CE marking requirements under EU machinery directives shape product design standards for European-bound exports, while China's GB standards and SAMR oversight govern domestic equipment certification pathways. India's BIS machinery safety norms and state-level factory inspectorates in Maharashtra and Gujarat influence local assembly compliance costs. Stakeholders must monitor how carbon border adjustment mechanisms and evolving energy labeling schemes redirect procurement decisions across major manufacturing hubs.
Market Dynamics
Quick-service restaurant chains across Southeast Asia are pulling higher-capacity automatic napkin machines into the spotlight as they recalibrate disposable tableware procurement standards. This demand recalibration is compressing equipment replacement cycles and redirecting capital toward electric-drive systems facing EU Green Deal energy efficiency scrutiny.
Growth Catalysts
- EU Green Deal packaging directives:Energy efficiency mandates are pressuring manufacturers toward electric drive systems, opening upgrade revenue streams for machinery suppliers.
- India's Maharashtra and Gujarat industrial corridors:Domestic tissue paper consumption climbs in these state-level manufacturing clusters, concentrating equipment demand geographically.
- Automated napkin procurement programs:Quick-service restaurant chains across Southeast Asia are expanding standardized equipment specifications, creating pull-through for automatic machine configurations.
Market Restraints
- Parent tissue roll input volatility:Pulp price fluctuations transmit directly to machine operating economics, compressing buyer willingness to pay premium equipment prices.
- CE marking compliance costs:EU machinery directive certification requirements add fixed cost burdens for European-bound exports from Asian manufacturers.
- Hydraulic system obsolescence risk:Existing installed base faces stranded asset exposure as electric technology segments attract capital and regulatory preference.
Strategic Opportunities
- India's state-level factory inspectorates:Maharashtra and Gujarat compliance cost differentials create arbitrage opportunities for localized assembly operations.
- Carbon border adjustment mechanisms:Evolving EU carbon pricing on imports redirects procurement decisions toward lower-emission electric-drive equipment categories.
- Urban food court compact designs:Space-constrained Southeast Asian foodservice formats reward machinery with reduced footprint specifications.
Industry Challenges
- Rotary embossing unit calibration expertise:Specialty machine segments require scarce technical talent for custom pattern programming, constraining boutique supplier scaling.
- BIS machinery safety norm timelines:India's certification pathways create deployment delays for imported equipment, complicating market entry sequencing.
- Legacy hydraulic-electric integration:Retrofit complexity for existing installations slows upgrade conversion rates among cost-sensitive operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Paper Napkin Making Machine Market |
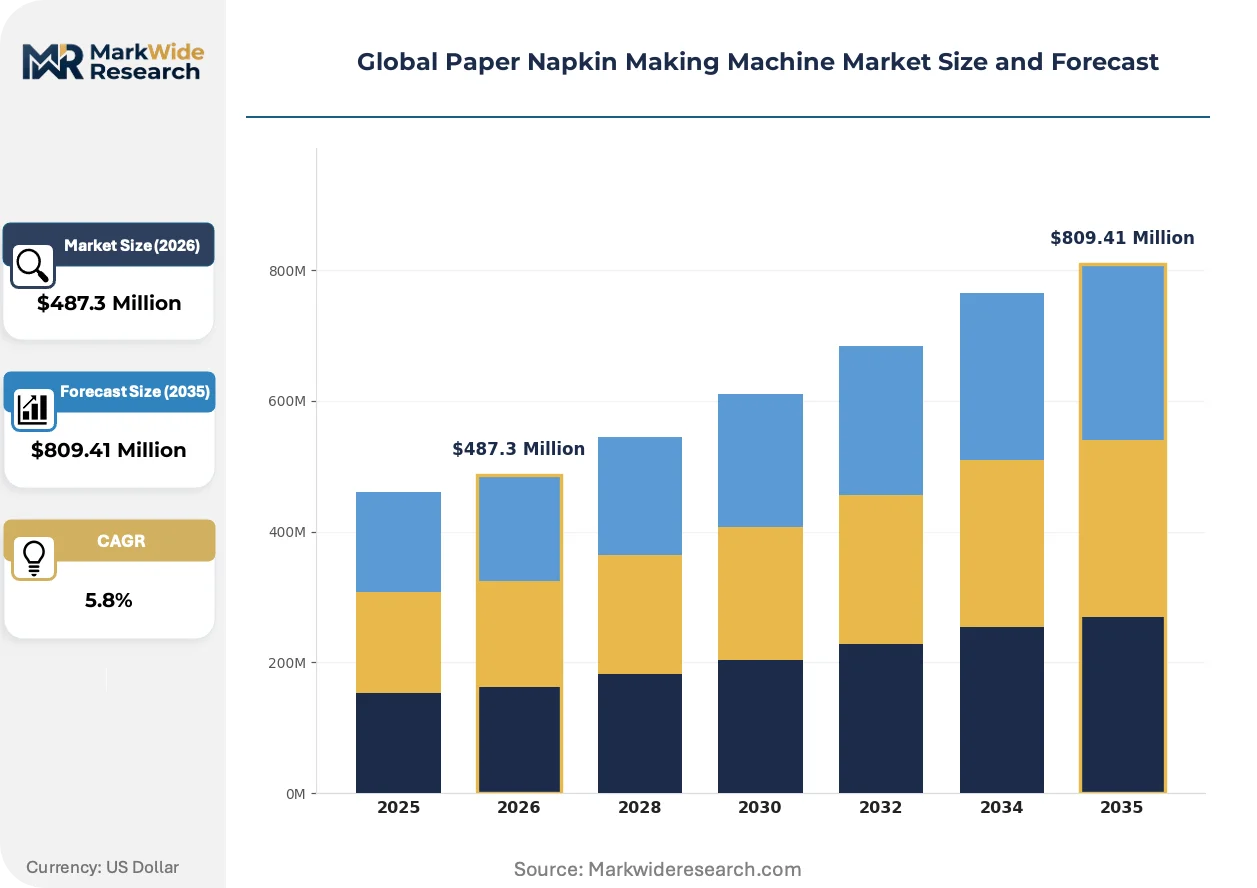
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Machines, Semi-Automatic Machines, Manual Machines, Specialty Machines End User: Hotels, Restaurants, Cafes, Catering Services Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers Technology: Hydraulic, Pneumatic, Electric, Mechanical |
| Companies Covered | Delta Paper Machine, Beston (Henan) Machinery Co., Ltd., Alpha Napkin Machines, HOBEMA machine factory, Royal Corporation, Finetech Tissue Machines, S.K. Engineering Works, OCEAN ASSOCIATE CO., LTD., Foshan Baosuo Machinery Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Paper Napkin Making Machine Market Strategic Shifts
Equipment manufacturers are racing to embed intelligence and sustainability credentials into napkin converting systems. The competitive frontier is shifting from raw speed specifications toward energy-adjusted throughput metrics and predictive maintenance capabilities.
Servo-electric folding mechanisms are absorbing market share from pneumatic and hydraulic alternatives across mid-capacity installations. Southeast Asian QSR procurement teams specify electric-drive systems in 70% of new tenders, compressing residual demand for legacy configurations. The technology is absorbing capital that previously flowed to maintenance-intensive mechanical systems, enabling tighter process control and reduced energy intensity per thousand napkins produced.
REACH chemical compliance and EU Green Deal packaging waste directives are reshaping material handling specifications for European-bound equipment. Machinery exporters must now document energy consumption profiles and embossing lubricant compositions to maintain market access. Specialty segments serving boutique hotel suppliers face the steepest adaptation costs, as custom pattern capabilities require reformulated consumable chemistries.
Foodservice procurement departments are consolidating vendor relationships and demanding outcome-based equipment performance guarantees rather than standalone machine sales. Southeast Asian QSR chains now specify total cost-per-napkin metrics in tender documents, displacing traditional capital expenditure evaluation models. India's domestic tissue paper converters are adopting similar total-cost frameworks fastest in Gujarat's industrial zones, where energy price volatility amplifies operating cost sensitivity.
Global Paper Napkin Making Machine Market Segmentation
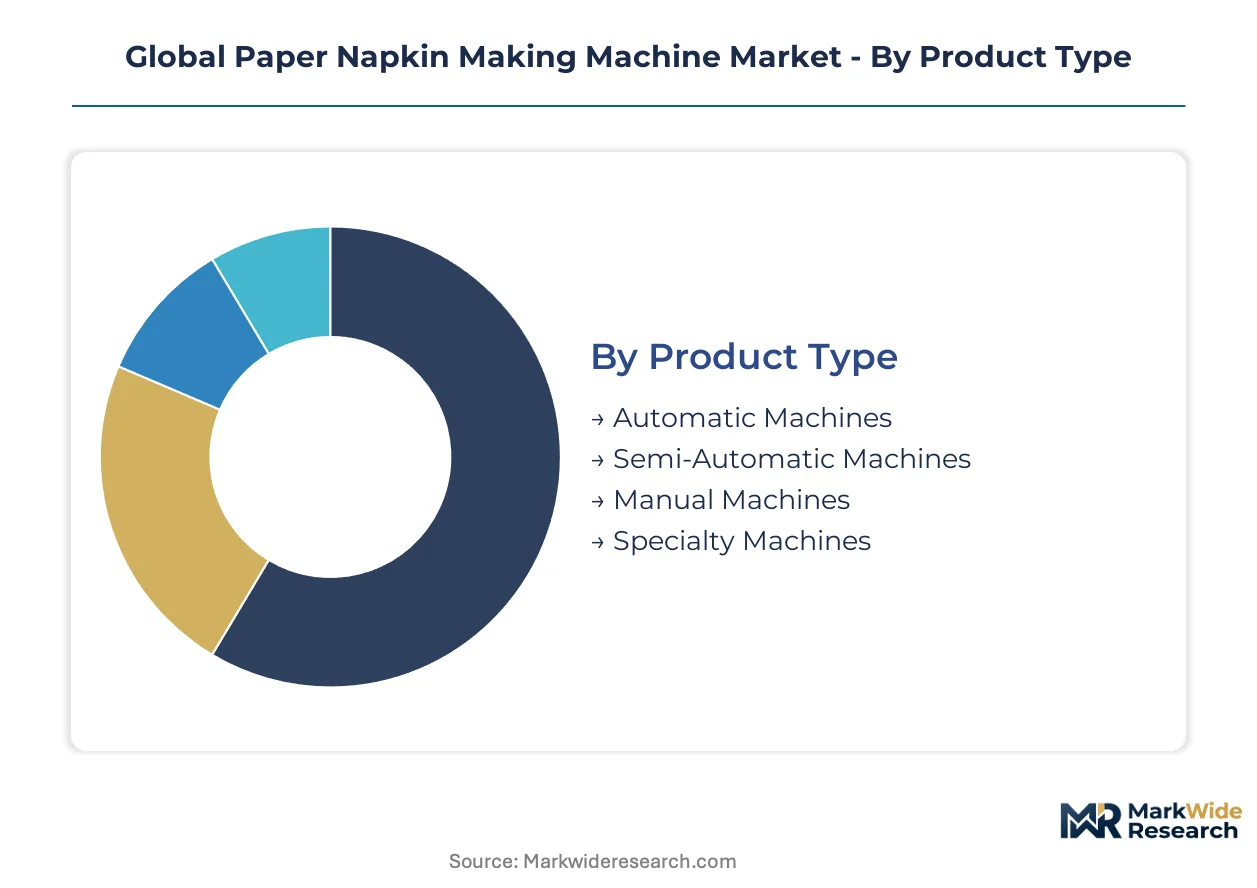
Paper napkin making machines fragment across multiple technical and commercial dimensions, each governing distinct procurement workflows and margin structures. Equipment buyers navigate trade-offs between labor substitution, energy efficiency, and customization depth when selecting across these categories.
Product Type:
Standalone converting systems dominate commercial foodservice installations, while embedded or auxiliary configurations serve niche boutique applications.
- Automatic Machines:These systems integrate unwind stands, rotary embossing units, and servo-driven folding mechanisms operating at 400-800 pieces per minute. Quick-service restaurant chains across Southeast Asia concentrate procurement here, driven by labor cost pressures and standardized throughput requirements.
- Semi-Automatic Machines:Hybrid configurations requiring manual feeding but automated cutting and stacking. India's Maharashtra industrial corridor shows rising interest as mid-scale converters balance capital constraints against volume targets.
- Manual Machines:Foot-pedal or hand-cranked units for micro-enterprises and rural foodservice. These occupy the lowest price tier with minimal regulatory compliance burdens.
- Specialty Machines:Custom embossing and die-cutting systems for boutique hotel suppliers seeking branded napkin finishes.
Volume placements concentrate in Automatic Machines; the faster expansion belongs to Specialty Machines.
End User:
Demand intensity varies sharply by foodservice format, with high-volume institutional buyers commanding equipment customization and smaller operators accepting standardized configurations.
- Hotels:Premium properties specify electric-drive systems with custom embossing capabilities and REACH-compliant lubricant documentation for European export alignment.
- Restaurants:Full-service chains prioritize throughput reliability and predictive maintenance integration over pattern complexity.
- Cafes:Urban food court operators in Southeast Asia favor compact footprint designs from Foshan Baosuo Machinery Manufacturing.
- Catering Services:Event-based operators demand rapid format changeover between cocktail and dinner napkin specifications.
Equipment shipments skew toward Restaurants; Catering Services are climbing fastest as event-format foodservice scales.
Distribution Channel:
Channel selection reflects buyer technical sophistication and the complexity of post-sale calibration requirements.
- Direct Sales:Manufacturer-to-converter relationships for large-scale QSR procurement programs with dedicated technical support.
- Online Retail:E-commerce platforms serving small-scale Indian tissue converters in Gujarat's industrial zones seeking transparent pricing.
- Distributors:Regional stocking partners managing CE marking documentation and spare parts logistics for EU-bound exports.
- Wholesalers:Bulk resellers moving standardized semi-automatic units to price-sensitive emerging market operators.
Transaction volume pools in Direct Sales; Online Retail is gaining share fastest among first-time equipment buyers.
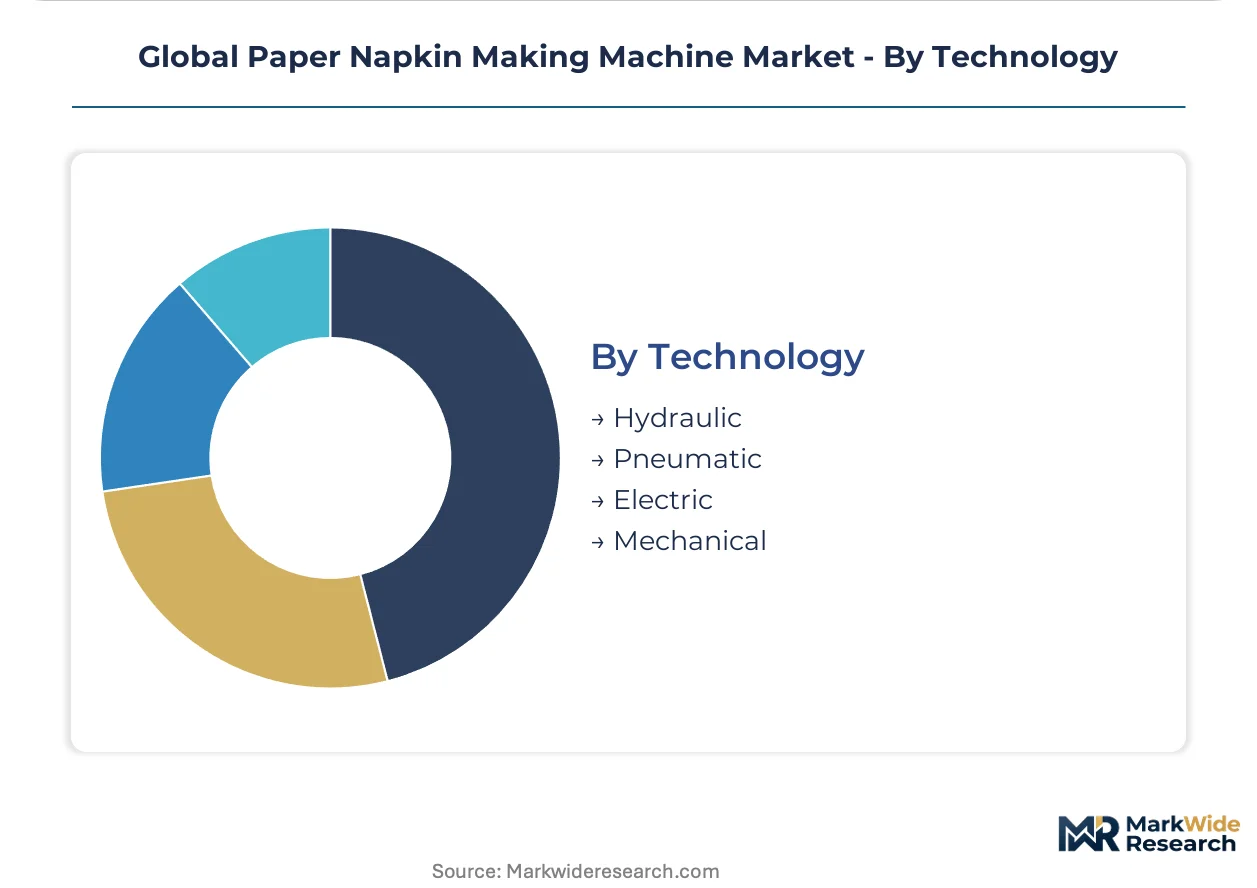
Technology:
Drive system selection increasingly determines regulatory compliance posture and operating cost trajectories across major manufacturing hubs.
- Electric:Servo-motor configurations delivering precise tension control and energy-adjusted throughput metrics. Beston (Henan) Machinery Co., Ltd. anchors technology leadership here as EU Green Deal directives accelerate displacement of legacy alternatives.
- Hydraulic:High-torque systems facing stranded asset exposure as carbon border adjustment mechanisms redirect procurement preferences.
- Pneumatic:Compressed-air folding mechanisms losing ground to electric alternatives in mid-capacity Southeast Asian installations.
- Mechanical:Cam-driven legacy systems with high maintenance intensity but lowest capital entry point.
Installed base concentrates in Hydraulic systems; Electric technology is expanding most quickly as efficiency regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment production concentrates in Chinese manufacturing hubs while consumption pulls strongest across India's industrial corridors and Southeast Asian foodservice markets. This geographic mismatch shapes trade flows and localized assembly strategies.
China
GB standards under SAMR oversight govern domestic certification for napkin converting equipment exported worldwide. The country's dual carbon goals accelerate electric-drive technology development among machinery fabricators. Zhengzhou and Foshan industrial zones host concentrated manufacturing capacity serving both domestic tissue converters and export markets.
India
BIS machinery safety norms and state-level factory inspectorates in Maharashtra and Gujarat create compliance cost differentials that favor localized assembly. The PLI scheme for manufacturing equipment indirectly supports domestic machinery sourcing. Ahmedabad and Surat industrial clusters show rising procurement of semi-automatic configurations as mid-scale converters expand capacity.
Germany
CE marking requirements under EU machinery directives establish design standards that Asian exporters must satisfy for European market access. The EU Green Deal's packaging waste directives pressure manufacturers toward energy-efficient electric drive systems. Baden-Württemberg's precision engineering ecosystem supplies high-specification components for premium napkin converting lines.
Vietnam
Quick-service restaurant chains expanding automated procurement programs drive demand for compact, high-throughput automatic machines. The country's national standards body aligns equipment import regulations with ASEAN harmonization frameworks. Ho Chi Minh City industrial parks attract Chinese and Indian machinery suppliers establishing regional distribution hubs.
United States
OSHA machinery safety standards and state-level environmental regulations shape equipment specifications for domestic foodservice operators. FDA food contact material requirements indirectly influence napkin converting line material handling designs. Texas and California industrial corridors concentrate tissue converting operations that source automated equipment with predictive maintenance integration.
Global Paper Napkin Making Machine Market Competitive Environment
Top-tier vendors anchor technology leadership in electric-drive systems and custom embossing capabilities, while mid-tier fabricators compete on footprint optimization and regional service density. The vendor base stratifies across three strategic archetypes: scale-driven manufacturers serving QSR procurement programs, technology specialists commanding premium positioning in electric-drive segments, and compact-design experts targeting urban food court constraints. Competitive moves concentrate on geographic expansion through localized assembly partnerships and portfolio diversification into predictive maintenance service contracts.
Among Chinese fabricators, Beston (Henan) Machinery Co., Ltd. and Foshan Baosuo Machinery Manufacturing occupy distinct positioning vectors. Beston exemplifies the technology-specialist archetype with its electric-drive leadership, while Foshan Baosuo represents compact-design expertise for space-constrained installations. Delta Paper Machine anchors the scale-driven tier, leveraging manufacturing breadth across India's growing QSR infrastructure. S.K. Engineering Works and Finetech Tissue Machines sit within the mid-tier service-density segment, emphasizing regional technical support and spare parts logistics.
| Leading Market Players |
|---|
| Delta Paper Machine |
| Beston (Henan) Machinery Co., Ltd. |
| Alpha Napkin Machines |
| HOBEMA machine factory |
| Royal Corporation |
| Finetech Tissue Machines |
| S.K. Engineering Works |
| OCEAN ASSOCIATE CO., LTD. |
| Foshan Baosuo Machinery Manufacturing |
| Others |
Value Chain & Pricing Dynamics
Electric-drive certification tiers split the equipment landscape into divergent pricing bands, with CE-marked European-bound systems commanding substantial premiums over GB-standard domestic Chinese configurations. This bifurcation feeds directly into supply chain geography, as manufacturers cluster assembly capacity in Zhengzhou and Foshan to exploit component sourcing advantages while maintaining parallel certification pathways for distinct end-markets.
Pricing Analysis
Short lead-time premiums dominate transaction structures, with Southeast Asian QSR procurement teams paying 15-20% markups for 8-week delivery windows versus standard 16-week cycles. Three-tier pricing structure across premium, standard, and economy levels aligns with automation depth, where servo-electric folding mechanisms anchor the top tier and mechanical cam systems occupy the base. Cost compression in mid-capacity semi-automatic configurations is intensifying because Indian state-level factory inspectorates in Maharashtra and Gujarat are accelerating local assembly preference. Small-scale tissue converters in Gujarat's industrial zones exhibit the highest price sensitivity, while premium hotel chains in European markets demonstrate minimal elasticity for REACH-compliant custom embossing systems.
Supply Chain Analysis
Regional distribution centers in Ho Chi Minh City, Ahmedabad, and Baden-Württemberg form a hub-and-spoke pattern that positions finished equipment within 72-hour delivery radius of major consumption clusters. Manufacturing concentration rests on China, India, and Germany, with Zhengzhou and Foshan industrial zones feeding Asian demand and Baden-Württemberg supplying precision components for premium European lines. Parent tissue roll quality, servo-motor drives, and REACH-compliant embossing lubricants constitute critical input dependencies. Single-source vulnerability concentrates in Chinese servo-motor supply, where domestic manufacturers still import high-precision encoders from German and Japanese specialists. Distribution runs through manufacturer-direct relationships for large QSR programs, with regional distributors managing CE documentation and spare parts logistics for fragmented European buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rotary embossing unit calibration expertise scarcity props equipment pricing, constraining boutique supplier scaling and preserving margin pools for incumbents with captive technical talent.
For Market Incumbents: Lock in long-term supply relationships with Southeast Asian QSR procurement programs before electric-drive technology commoditizes. Beston (Henan) Machinery Co., Ltd.'s technology leadership position faces erosion from emerging Chinese fabricators replicating servo-electric architectures; defend through backward integration into precision encoder sourcing and predictive maintenance service contracts that embed switching costs. For New Entrants and Emerging Players: Capture the semi-automatic configuration gap in India's Maharashtra industrial corridor, where mid-scale converters balance capital constraints against volume expansion targets. Urban food court compact designs represent the most penetrable segment, with Foshan Baosuo Machinery Manufacturing's footprint optimization establishing a replicable template. Lead with online retail channel presence targeting Gujarat's first-time equipment buyers seeking transparent pricing. For Investors and Strategic Acquirers: Re-rating potential sits with electric-drive technology specialists given EU Green Deal packaging directive acceleration and carbon border adjustment mechanism implementation. Long-term viability favors fabricators with demonstrated REACH compliance documentation and established CE marking pathways. The signal to watch is Southeast Asian QSR tender specifications crossing the 80% electric-drive threshold, which would strand hydraulic system installed bases and trigger consolidation among legacy-dependent operators.| Strategic Initiative | Industry Significance |
|---|---|
| Electric-Drive Technology Migration | EU Green Deal directives accelerate displacement of hydraulic systems across European-bound exports. |
| Localized Assembly Partnerships | Maharashtra and Gujarat compliance cost differentials favor Indian domestic manufacturing over pure imports. |
| Predictive Maintenance Service Contracts | QSR procurement teams now specify total cost-per-napkin metrics displacing traditional capex evaluation. |
| REACH-Compliant Lubricant Reformulation | Specialty segments serving boutique hotels face steepest adaptation costs for European market access. |
| Compact Footprint Design Optimization | Urban food court space constraints in Southeast Asia reward machinery with reduced specifications. |
Study Parameters
Trade association filings, customs export records, and machinery safety certification databases formed the secondary backbone of this analysis. Primary interviews with plant engineers at tissue converting facilities, procurement leads at Southeast Asian QSR chains, aftermarket service heads at regional distributors, and technical R&D directors at Chinese fabricators validated demand-side assumptions. Bottom-up and top-down triangulation cross-checked equipment shipment data against parent tissue roll consumption patterns.
Bottom-up modeling aggregated segment-level projections across product type, technology, end user, and distribution channel dimensions. Top-down validation anchored aggregate market size to industrial tissue paper consumption trends and foodservice format expansion rates. CAGRs were derived from fitted growth curves applied to equipment replacement cycles and greenfield capacity additions. Key forecast inputs included EU machinery directive compliance timelines and Indian PLI scheme manufacturing equipment incentives.
The model holds under stable pulp price environments and continued ASEAN harmonization on equipment import regulations; deviation in parent tissue roll input costs or carbon border adjustment mechanism scope would shift upgrade cycle timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Stretch Blow Molding Machines Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Paper Napkin Converting Lines Market
Packaging Machinery
Pouch Sealing Machine Market
Packaging Machinery
Food Packaging Machinery Market
Packaging Machinery
Capping Machine Market
Packaging Machinery
Automatic Paper Cutter Market
Packaging Machinery
Slitter Rewinder Machines Market
Packaging Machinery
North America Automatic Carton Erector Market
Packaging Machinery
Automatic Filling Machine Market
Packaging Machinery
Wet Ink Coding Machines Market
Packaging Machinery
Tray Forming Machine Market
Packaging Machinery
Pallet Drum Filler Capper Market
Packaging Machinery
Bottle Filling Machine Market
Packaging Machinery
Kitchen/ Toilet Roll Converting Machines Market
Packaging Machinery
Filling Machinery Market