
 Converting Paper Market | 2026-2036
Converting Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Converting Paper Market Analysis
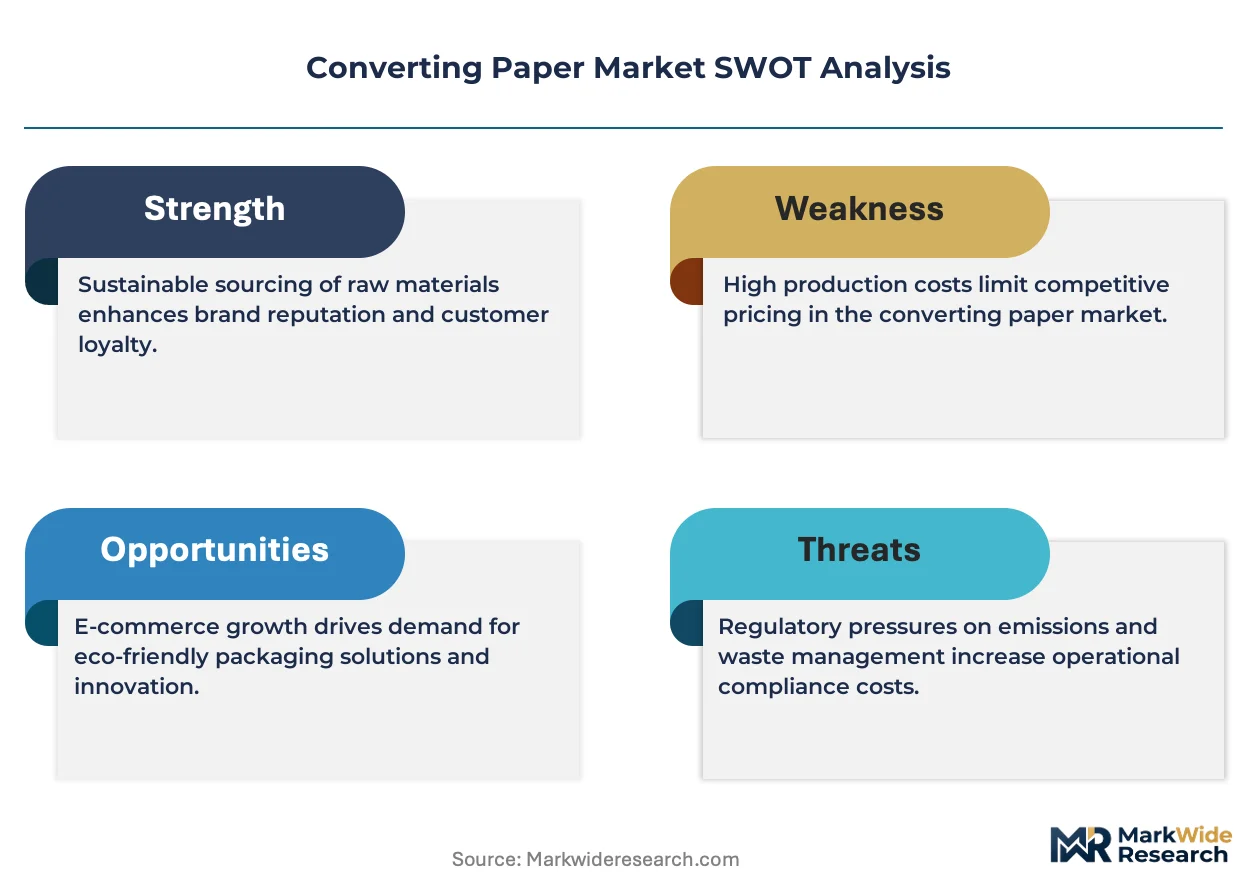
The capital-intensity divergence between integrated pulp-to-paper operators and merchant converters is bifurcating competitive returns in the sector. International Paper leverages its captive fiber supply and massive mill network to sustain cost leadership across North American containerboard. Stora Enso anchors its position through biobased material innovation and strategic Nordic timber access. Georgia-Pacific competes via scale dominance in towel and tissue converting, backed by extensive distribution infrastructure.
Converting paper encompasses mechanically or chemically processed wood pulp sheets that undergo further manufacturing—coating, laminating, slitting, or die-cutting—to achieve specified grammage, caliper, and surface properties for end-use functionality. The process typically targets basis weights between 40 and 400 gsm, with coating applications employing kaolin or calcium carbonate layers to enhance print receptivity. Specialty paper commands the thickest margin pools due to technical barriers and custom formulation requirements, while uncoated grades retain volume leadership in publishing and general printing. Packaging applications across labels and boxes are expanding faster than stationery segments, driven by direct-to-consumer fulfillment demand.
The EPA enforces effluent limitations under the Cluster Rules that constrain mill-level chemistry and water discharge, directly elevating compliance costs for integrated producers. REACH and the EU Green Deal mandate carbon footprint disclosure and restrict certain coating chemistries, reshaping import competitiveness for European converters. Stakeholders must monitor regulatory divergence between North American and European frameworks when siting new converting capacity or reformulating product lines.
Market Dynamics
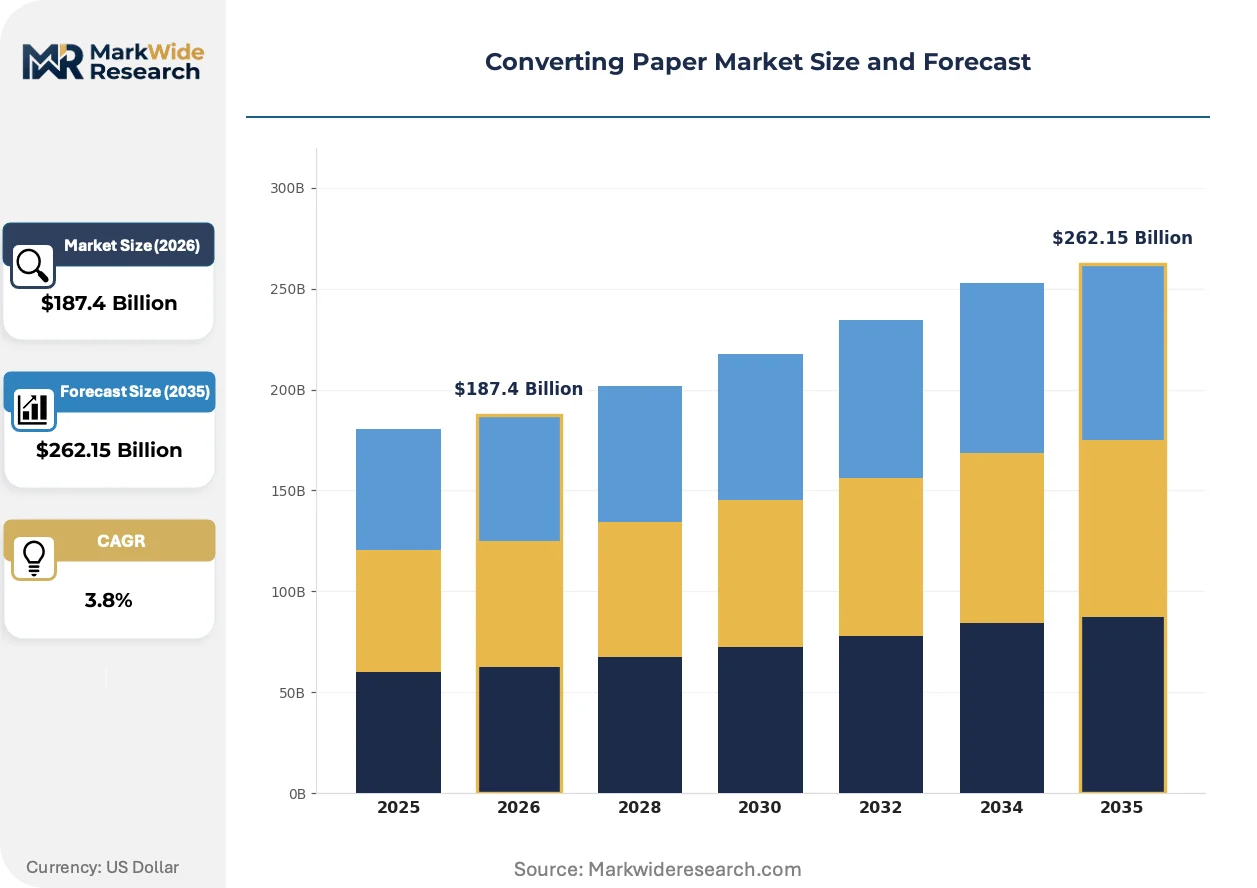
Capital-intensity divergence between integrated pulp-to-paper operators and merchant converters is bifurcating competitive returns across the sector. The EPA's Cluster Rules and REACH compliance burdens are elevating fixed costs for integrated producers while specialty paper margins concentrate with technical-formulation leaders.
Growth Catalysts
- E-commerce fulfillment packaging:Direct-to-consumer order volumes are pulling demand for corrugated boxboard and pressure-sensitive label stock across North American distribution networks.
- REACH carbon-footprint disclosure mandates:European converters reformulating coating chemistries are creating first-mover advantages in bio-based barrier coatings for food-contact applications.
- Digital print compatibility:Inkjet-optimized surface treatments are expanding addressable demand from short-run commercial print into personalized packaging.
Market Restraints
- Pulp cost volatility:Hardwood fiber supply concentration in Nordic and Brazilian timber basins transmits price shocks directly to uncoated freesheet margins.
- F-Gas Regulation coating restrictions:Fluorinated chemistry phase-outs under EU rules are forcing reformulation of grease-resistant food wraps without fully mature substitutes.
- Plastic film substitution:Polypropylene and polyethylene barrier films retain cost advantages in moisture-sensitive pharmaceutical blister packs.
Strategic Opportunities
- India's industrial packaging underpenetration:Organized retail expansion and FMCG distribution formalization are creating virgin demand for containerboard and kraft paper.
- EU Green Deal biobased procurement incentives:Public-sector purchasing mandates for renewable content are opening premium pricing windows for certified-sustainable grades.
- Near-infrared sorting compatibility:Converters integrating detectable black pigments and barrier coatings are capturing demand from closed-loop recycling commitments by beverage brands.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise in mineral-polymer hybrid barriers is concentrating at a handful of European and Japanese research centers.
- Mill-scale capital intensity:Rebuilding aging Fourdrinier wire sections to handle lighter basis weights requires eight-figure investments with decade-long payback horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Converting Paper Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $262.15 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Paper, Uncoated Paper, Specialty Paper, Recycled Paper End User: Publishing, Packaging, Printing, Stationery Application: Labels, Books, Boxes, Wrapping Distribution Channel: Direct Sales, Retail, Wholesale, Online |
| Companies Covered | International Paper, Georgia-Pacific, Stora Enso, Domtar Corporation, Billerud, UPM, Smurfit WestRock, Cascades Inc., Burgo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Converting Paper Market Emerging Trajectories
Active reformulation of surface chemistry and fiber sourcing is compressing legacy grade distinctions while opening specialty niches. Technical barriers are migrating from mechanical pulping toward coating-layer functionality and end-of-life recoverability.
Water-based barrier coatings incorporating nanocellulose and starch-polymer laminates are decomposing the traditional polyethylene extrusion layer in food packaging. Quick-service restaurant chains and fresh-produce shippers are piloting these substitutes at scale in Germany and California. The technology is decomposing integrated film-converter margins while concentrating value with specialty chemical formulators.
REACH restrictions on per- and polyfluoroalkyl substances are accelerating phase-outs of oil-grease-resistant treatments in bakery and fast-food wraps. European converters are retrofitting coating lines to handle plant-based wax and clay alternatives. Food-contact paper segments in France and Italy are absorbing compliance costs through specification tightening rather than price elasticity.
Brand-led sustainability scorecards are compressing supplier qualification cycles and unbundling volume commitments from long-term contracts. Major beverage and personal-care purchasers are consolidating vendor panels while demanding chain-of-custody documentation. This pattern is most visible in Nordic markets where retailer private-label penetration drives procurement centralization.
Converting Paper Market Segmentation
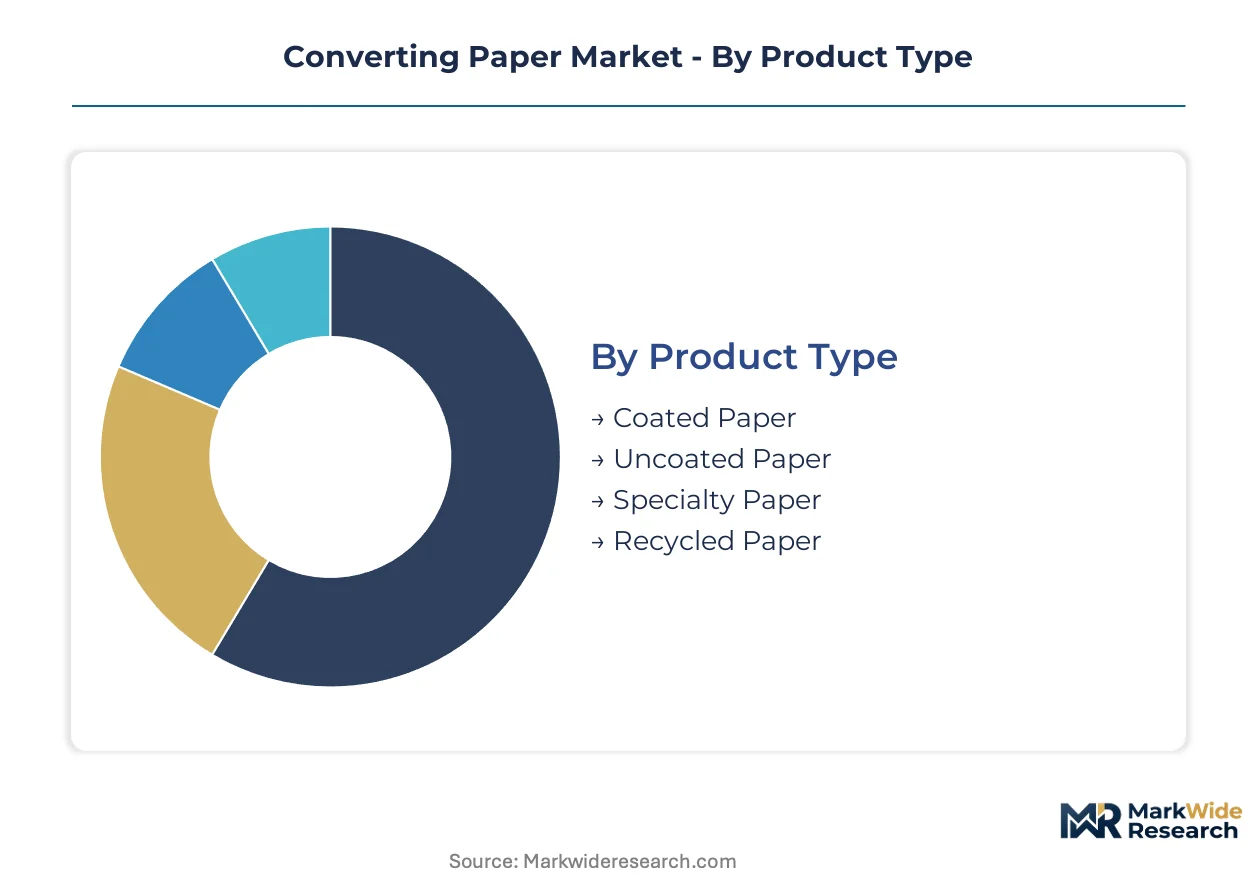
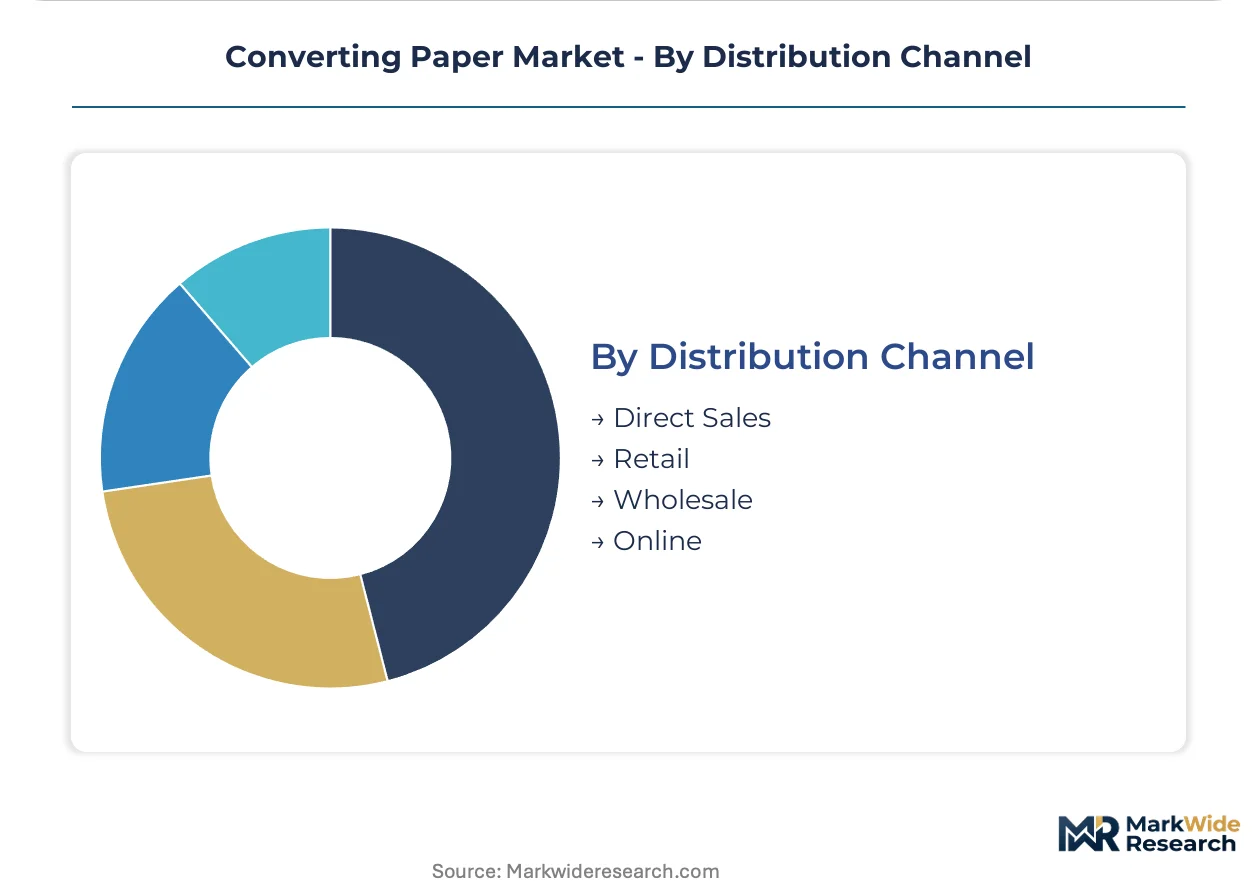
Converting paper flows through distinct channel architectures that reshape margin capture and technical requirements. Product specifications diverge sharply between merchant converter networks and integrated mill direct sales, with coating chemistry and basis weight determining route-to-market economics.
Product Type:
Channel mix varies dramatically by surface treatment—coated grades concentrate in mill-direct contracts with major publishers, while specialty papers flow through technical distributors serving niche formulators.
- Coated Paper:Kaolin or calcium carbonate surface layers enable high-resolution print receptivity for commercial publishing and advertising inserts. Demand concentrates in German magazine printing clusters where REACH-compliant coating chemistries command specification premiums.
- Specialty Paper:Custom-formulated barrier layers and fiber blends serve pharmaceutical inserts, thermal labels, and electrical insulation with technical entry barriers. Food-contact certification requirements in France and Italy are pulling reformulation investment toward bio-based wax alternatives.
- Uncoated Paper:Standard freesheet grades for general printing and office applications with thinner margin pools.
- Recycled Paper:Post-consumer fiber content for corrugated medium and packaging linerboard with near-infrared detectability requirements.
Uncoated paper dominates installed base. Specialty paper is where expansion concentrates.
End User:
Cost tier stratification separates commodity volume from formulation-intensive premium positioning across converting value chains.
- Packaging:Corrugated boxboard and pressure-sensitive label stock for e-commerce fulfillment networks. Direct-to-consumer order volumes in North American distribution hubs are accelerating specification tightening for recycled content and print compatibility.
- Publishing:Magazine, catalog, and book paper with declining run lengths pushing demand toward digital-print-optimized surfaces.
- Printing:Commercial sheetfed and web offset applications with inkjet compatibility emerging as a technical differentiator.
- Stationery:Writing and copying grades with premium positioning tied to cotton fiber content and watermarking.
Publishing retains volume leadership. Packaging is climbing the fastest on fulfillment demand.
Application:
Supply concentration in folding carton and corrugated substrate mills dictates regional sourcing patterns for brand owners.
- Boxes:Corrugated containerboard for shipping and retail-ready packaging with basis weights calibrated to automated fulfillment line specifications. California quick-service restaurant chains are piloting nanocellulose barrier coatings at scale.
- Labels:Pressure-sensitive and wet-glue facestock for beverage and logistics applications with silicone release liner compatibility requirements.
- Books:Text and cover stock for trade and educational publishing with durability specifications varying by distribution channel.
- Wrapping:Tissue and decorative papers with grease-resistance mandates driving fluorinated chemistry phase-outs under EU F-Gas Regulation.
Boxes command the largest volume footprint. Labels are gaining share fastest on logistics traceability requirements.
Distribution Channel:
Customer type segmentation separates specification-driven contract buyers from spot-market purchasers with diverging service requirements.
- Direct Sales:Mill-direct contracts with major publishers and national retailers specifying chain-of-custody documentation and volume commitments. Nordic beverage brand consolidation is compressing supplier qualification cycles.
- Wholesale:Merchant converter networks aggregating demand from regional printers and packaging converters with inventory buffering services.
- Retail:Office supply and craft store channels for small-format stationery and consumer wrapping with premium positioning.
- Online:E-procurement platforms for standardized grades with price transparency and smaller minimum order quantities.
Direct sales anchor contract volume. Online channels are expanding most quickly on procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in converting paper concentrates with German industrial buyers while US Gulf Coast mills absorb fiber cost volatility. This asymmetry reshapes capacity siting decisions across both continents.
United States
E-commerce fulfillment networks in California and Texas drive containerboard consumption for corrugated shipping boxes. EPA Cluster Rules enforce effluent limitations that elevate compliance costs for integrated pulp-to-paper operators. The Pacific Northwest timber basin supplies softwood fiber to Washington and Oregon mills with captive sawmill residual access.
Germany
Industrial packaging demand from automotive and machinery exporters in Baden-Württemberg and Bavaria sustains specialty paper volumes. EU Green Deal procurement mandates require carbon footprint disclosure for public-sector purchasing, favoring certified-sustainable grades. The Rhine-Ruhr corridor concentrates converting capacity with integrated logistics for Benelux distribution.
China
Express delivery packaging for domestic e-commerce platforms consumes linerboard and medium grades at unprecedented scale. MIIT dual carbon goals pressure mills to retrofit coal-fired boilers and reduce energy intensity per ton. The Yangtze River Delta around Shanghai hosts folding carton converters serving multinational FMCG brand owners.
India
Organized retail expansion and FMCG distribution formalization create virgin demand for kraft paper and containerboard. BIS standards govern food-contact paper specifications, accelerating domestic testing laboratory investment. Maharashtra and Gujarat industrial corridors attract greenfield converting investments from integrated paper groups.
Japan
Premium stationery and specialty packaging applications sustain higher basis-weight grades with technical barriers. METI circular economy roadmaps mandate recycled content thresholds for government procurement contracts. The Kansai region around Osaka maintains legacy coating expertise for thermal label and release liner applications.
Converting Paper Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the converting paper sector. Integrated pulp-to-paper operators command scale economies in commodity containerboard while merchant converters capture specialty margins through formulation expertise. Three archetypes dominate: captive-fiber giants with mill networks, specialty chemical formulators with coating IP, and regional converters with distribution density. Competitive moves concentrate on M&A for fiber access and strategic partnerships for bio-based barrier development.
Among North American integrated operators, International Paper and Georgia-Pacific exemplify the scale-driven archetype with extensive mill infrastructure and captive timber supply. Stora Enso represents the European biobased innovation vector, anchoring Nordic timber access with renewable material formulation capabilities. These three occupy positions across the cost-technology spectrum without overlapping strategic territory.
| Leading Market Players |
|---|
| International Paper |
| Georgia-Pacific |
| Stora Enso |
| Domtar Corporation |
| Billerud |
| UPM |
| Smurfit WestRock |
| Cascades Inc. |
| Burgo Group |
| Others |
Supply Flow & Price Mechanics
Mill-scale capacity utilization in integrated pulp-to-paper operations shapes both supply concentration and price floors across converting paper markets. Nordic and Brazilian timber basins anchor fiber supply, transmitting cost volatility through uncoated freesheet grades while specialty coating formulations command specification premiums in German industrial corridors.
Pricing Analysis
Configured-to-order specialty paper commands spreads of 40-60% above standard uncoated grades due to custom barrier-layer formulation and food-contact certification requirements. Contract-based long-term offtake dominates mill-direct sales to major publishers, while spot-market merchant converters absorb pulp cost volatility. Price differentiation hinges on REACH-compliant coating chemistry and chain-of-custody certification tiers. Cost compression in commodity containerboard intensifies as e-commerce fulfillment volumes concentrate buying power among national retailers. Small-format stationery purchasers show highest price sensitivity; pharmaceutical and food-contact buyers prioritize technical compliance over unit economics.
Supply Chain Analysis
Finland and Sweden anchor softwood pulp supply through integrated Nordic timber networks, while Brazil's eucalyptus plantations feed hardwood fiber to Asian and European mills. Coating chemistry inputs draw from German and Japanese specialty chemical formulators, with kaolin and calcium carbonate supply resting on mineral extraction in China and the United States. Single-source vulnerability concentrates in fluorinated grease-resistant barrier formulations facing EU F-Gas Regulation phase-outs. Distribution runs through Rhine-Ruhr corridor logistics hubs serving Benelux and Central European converting clusters, with Pacific Northwest rail networks feeding California and Texas fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Converting paper markets function as a defensive-moat industry where regulatory entrenchment in food-contact certification and REACH compliance creates durable switching costs for qualified suppliers.
For Market Incumbents: Consolidate coating formulation expertise through captive R&D investment in bio-based barrier layers, defending against specialty chemical formulators encroaching on food-packaging margins. Add capacity in Maharashtra and Gujarat industrial corridors to capture India's organized retail expansion. Deepen backward integration into Nordic timber basins to insulate uncoated freesheet margins from Brazilian hardwood price shocks.
For New Entrants and Emerging Players: Technical distributor service gaps in nanocellulose barrier coating application support offer white-space entry points. Target California quick-service restaurant pilot programs requiring closed-loop recycling compatibility and near-infrared detectable pigments. Pursue partnership-based go-to-market models with European converters retrofitting coating lines for fluorinated chemistry phase-outs.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty chemical formulators with plant-based wax IP and coating-line retrofit capabilities over commodity containerboard operators. Long-term viability concentrates in assets with food-contact certification moats and EU Green Deal procurement eligibility. Monitor REACH per- and polyfluoroalkyl substance restriction timelines as inflection indicators for barrier coating substitution demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Timber | Captive softwood fiber supply insulates International Paper and Stora Enso from spot pulp volatility. |
| Bio-Based Barrier Coating Development | Plant-based wax and nanocellulose formulations capture EU Green Deal procurement premium windows. |
| Coating Line Retrofit Partnerships | European converters collaborating with specialty chemical formulators accelerate fluorinated chemistry phase-out compliance. |
| Near-Infrared Detectability Certification | Black pigment and barrier coating integration meets Coca-Cola and PepsiCo closed-loop recycling commitments. |
| Maharashtra-Gujarat Greenfield Expansion | Domestic containerboard capacity captures India's FMCG distribution formalization and BIS standards evolution. |
Methodological Framework
A standing panel of mill operations directors, merchant converter procurement leads, specialty coating formulators, and beverage brand sustainability officers provided ongoing calibration across primary interview rounds. Secondary validation drew from EPA effluent discharge databases, ECHA REACH registration dossiers, EU Green Deal procurement directive texts, and customs trade data for pulp and coated paper flows. Bottom-up segment sizing triangulated against top-down macroeconomic demand drivers.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product type, end-use industry, application format, and distribution channel, with regional regulatory clusters as a cross-cutting dimension. CAGRs derived from elasticity-adjusted demand curves incorporating e-commerce fulfillment growth rates and pulp cost pass-through coefficients.
Forecasts assume regulatory continuity in EPA Cluster Rules enforcement and EU F-Gas Regulation phase-out schedules; material policy shifts would require re-modeling. Pulp cost volatility, coating chemist talent scarcity, and brand-led sustainability scorecard acceleration represent specific revision risks. Recalibration cycles align with material shifts in REACH restriction timelines and closed-loop recycling commitment adoption by major beverage purchasers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Ultraflute Paper Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Paper Cup Lids Market
Paper & Paperboard Packaging
Disposable Paper Plates Market
Paper & Paperboard Packaging
Parchment Paper Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
Paperboard Protectors Market
Paper & Paperboard Packaging
Release Paper Market
Paper & Paperboard Packaging
Micro Flute Paper Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
Kitchen Roll Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
Insulated Corrugated Boxes Market
Paper & Paperboard Packaging
Paper Bottles Market
Paper & Paperboard Packaging
Paper Bag Box Market
Paper & Paperboard Packaging
Hanging Box Market