
 Latin America Metal Packaging Market | 2026-2036
Latin America Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Metal Packaging Market Insights
Subscription-based predictive maintenance for canning line equipment is restructuring how packaging converters monetize long-term customer relationships. Crown Holdings, Inc. leverages its regional manufacturing footprint to sustain supply continuity across multiple Latin American markets. Ball Corporation anchors its position through aluminum sourcing partnerships that secure input material for beverage can production. CANPACK S.A. competes on two-piece can technology leadership, differentiating its output through lightweighting innovations that reduce metal content per unit.
Latin America metal packaging comprises rigid containers fabricated from aluminum, steel, tinplate, or stainless steel through deep drawing, stamping, or extrusion processes, engineered to protect contents from oxygen, light, and mechanical damage across food, beverage, and industrial supply chains. Cans dominate volume throughput in the region, reflecting the structural importance of carbonated soft drinks and beer in Latin American consumption patterns. Aluminum commands premium positioning among material segments due to its infinite recyclability and lower transport cost profile, while steel food containers retain stable demand in shelf-stable vegetable and fish preservation. Food and beverages as an end-user category channels the majority of regional metal packaging offtake, with personal care aerosol cans representing a higher-margin but smaller-volume application.
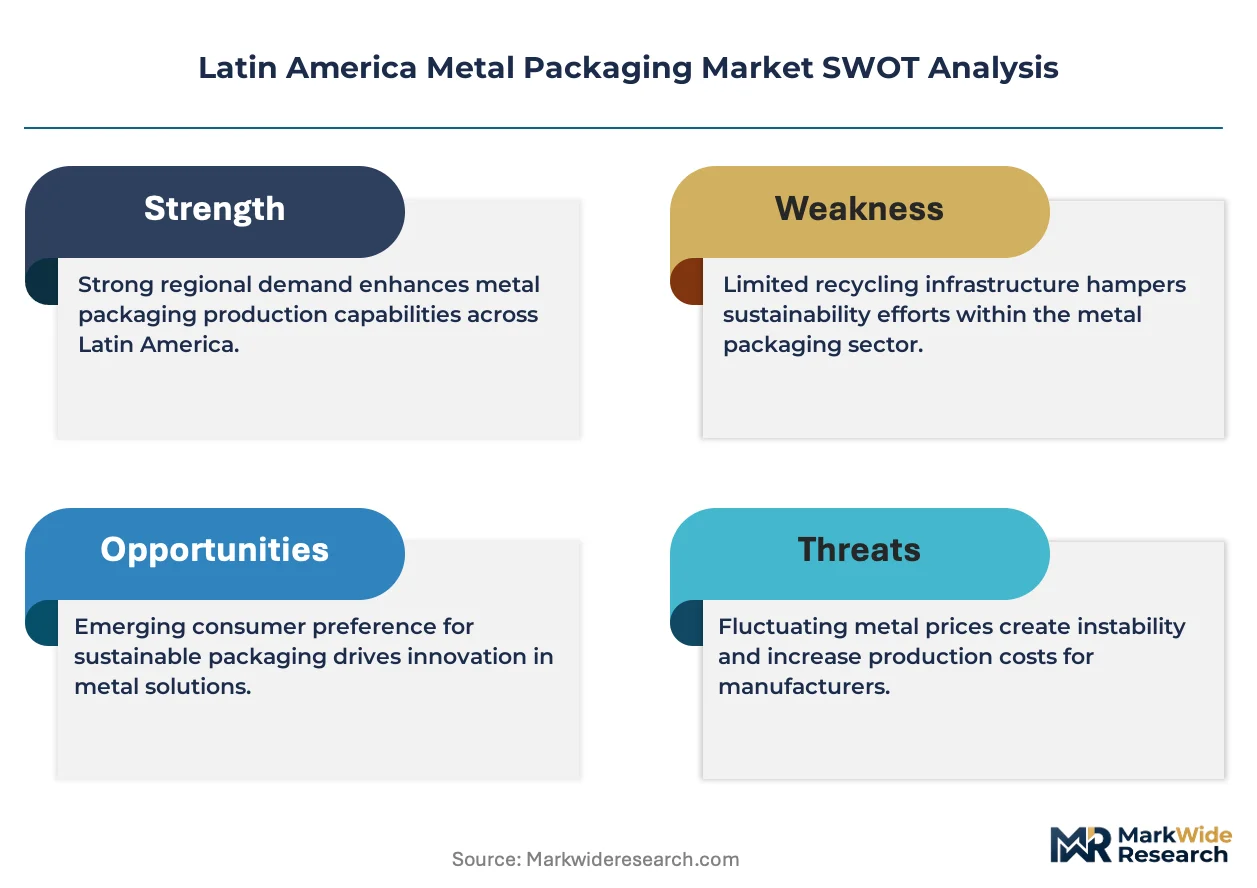
Brazil's ANVISA sets migration limits and sanitary requirements for food-contact metal surfaces, while Mexico's COFEPRIS enforces parallel standards that shape cross-border product formulation and coating chemistry decisions. The EU Green Deal's extraterritorial influence on Latin American export-oriented producers is accelerating investment in reduced-carbon aluminum smelting and water-based coating systems. Stakeholders must monitor how pending extended producer responsibility frameworks across Colombia, Chile, and Argentina will reconfigure collection infrastructure economics and metal scrap valuation chains.
Market Dynamics
Aluminum recycling mandates across Brazil and Mexico are compressing specification tolerances for can stock, forcing converters to requalify coating chemistries and migrate toward reduced-carbon smelter supply. This regulatory pressure is concentrating procurement power among converters with verified low-carbon input chains.
Growth Catalysts
- ANVISA migration limits:Brazil's tightening sanitary requirements for food-contact metal surfaces are accelerating coating system upgrades, creating replacement demand for legacy lacquered steel containers in processed food applications.
- Beverage can lightweighting:Two-piece aluminum can technology is reducing metal content per unit by 10-15% versus three-piece alternatives, cutting transport costs for carbonated soft drink and beer bottlers across the region.
- Southeastern Brazil manufacturing belt:Concentrated demand from São Paulo and Minas Gerais states is generating scale economies for domestic can production, reducing import dependency for beverage packaging.
Market Restraints
- Primary aluminum price volatility:Input cost swings for LME-linked aluminum ingot compress margin predictability for converters lacking long-term smelter offtake agreements.
- Steel food can substitution:Retort pouches and aseptic cartons are displacing tinplate containers in shelf-stable vegetable and fish segments, particularly in Mexican export-oriented processing.
- COFEPRIS formulation complexity:Mexico's parallel sanitary standards create cross-border product fragmentation, requiring dual coating qualifications for producers serving both Brazilian and Mexican markets.
Strategic Opportunities
- Colombian extended producer responsibility:Pending packaging waste frameworks will reconfigure collection infrastructure economics, creating first-mover advantage for integrated metal scrap recovery systems.
- Personal care aerosol premiumization:Higher-margin aluminum aerosol cans for cosmetics and household products remain underpenetrated versus beverage applications, offering margin expansion potential.
- Water-based coating convergence:EU Green Deal extraterritorial influence is aligning Latin American export producers with reduced-VOC coating technologies, opening premium shelf space in European retail.
Industry Challenges
- Deep-draw technician scarcity:Specialized die maintenance and stamping press operation skills are concentrated among aging workforces in São Paulo state, constraining line utilization rates.
- Legacy coating line stranded assets:Solvent-based lacquer systems require capital-intensive retrofit or replacement to meet emerging water-based specifications, compressing free cash flow for mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Metal Packaging Market |
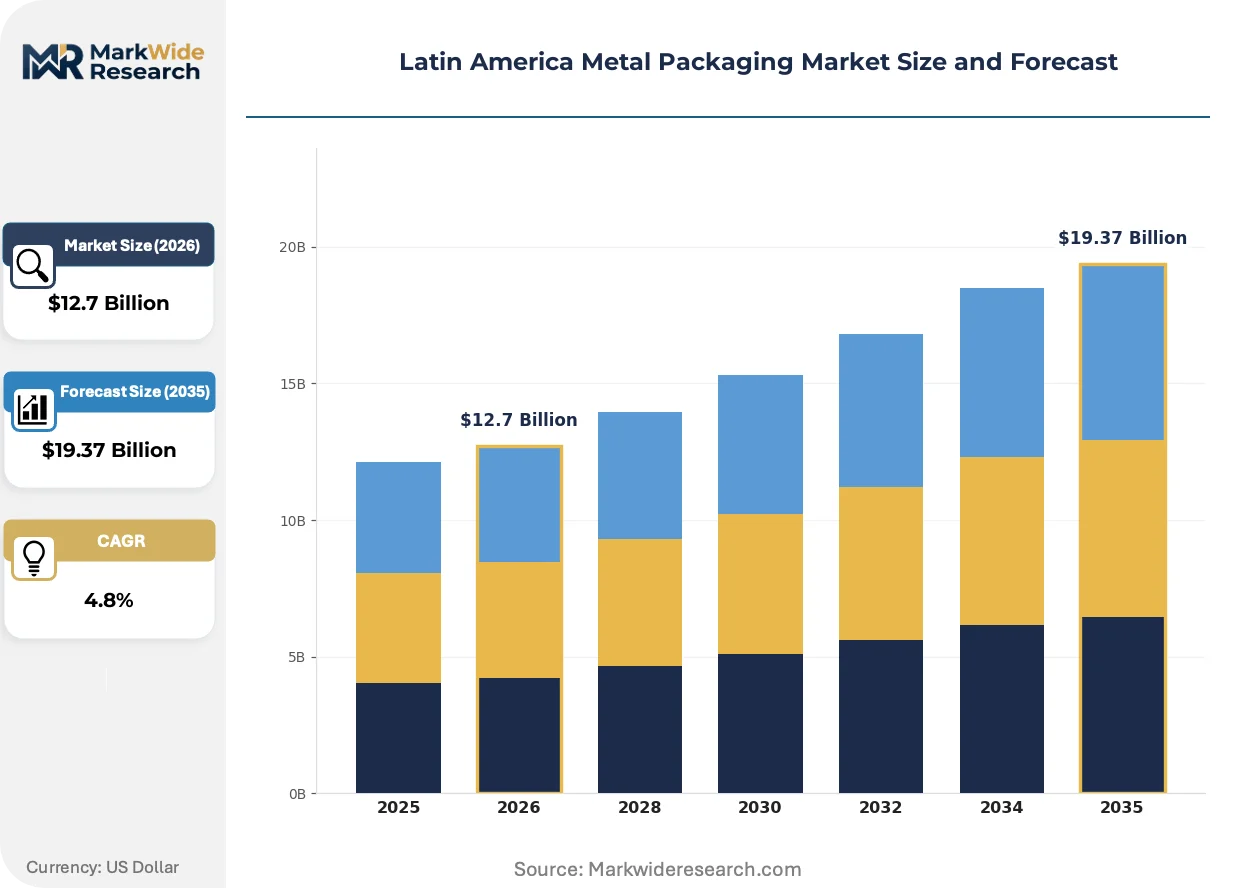
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $19.37 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cans, Bottles, Closures, Food Containers Material: Aluminum, Steel, Tinplate, Stainless Steel End User: Food & Beverages, Personal Care, Household Products, Industrial Application: Packaging, Storage, Transportation, Distribution |
| Companies Covered | Ardagh Metal Packaging S.A., Ball Corporation, Crown Holdings, Inc., CANPACK S.A., Greif, Inc., Mauser Packaging Solutions, Trivium Packaging, Closure Systems International, Inc., Guala Closures S.p.A., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Metal Packaging Market Trends and Innovations
Digital printing and smart packaging interfaces are reshaping how metal containers communicate brand differentiation and supply chain provenance. These technologies are compressing minimum order quantities and enabling regionalized SKU proliferation.
Digital printing on aluminum beverage cans is integrating variable data capabilities that support batch-level traceability and promotional customization. Mid-sized craft breweries in Argentina and Chile are adopting this technology at accelerating pace. This capability is integrating regional brand managers into design workflows previously controlled by centralized marketing functions.
ANVISA and COFEPRIS are harmonizing migration limit testing protocols for epoxy-phenolic and polyester coatings on food-contact metal surfaces. This convergence reduces dual-qualification burdens for multinational converters operating across the Mercosur-Pacific Alliance corridor. Aerosol and processed fish can segments are most affected, with leading producers accelerating third-party laboratory certification timelines.
Subscription-based predictive maintenance contracts are displacing traditional break-fix service models for high-speed canning line equipment. Brazilian beverage bottlers are consolidating vendor relationships around converters offering integrated uptime guarantees. This shift is most visible in São Paulo state's carbonated soft drink bottling corridor, where line stoppage costs exceed $50,000 per hour.
Latin America Metal Packaging Market Segmentation
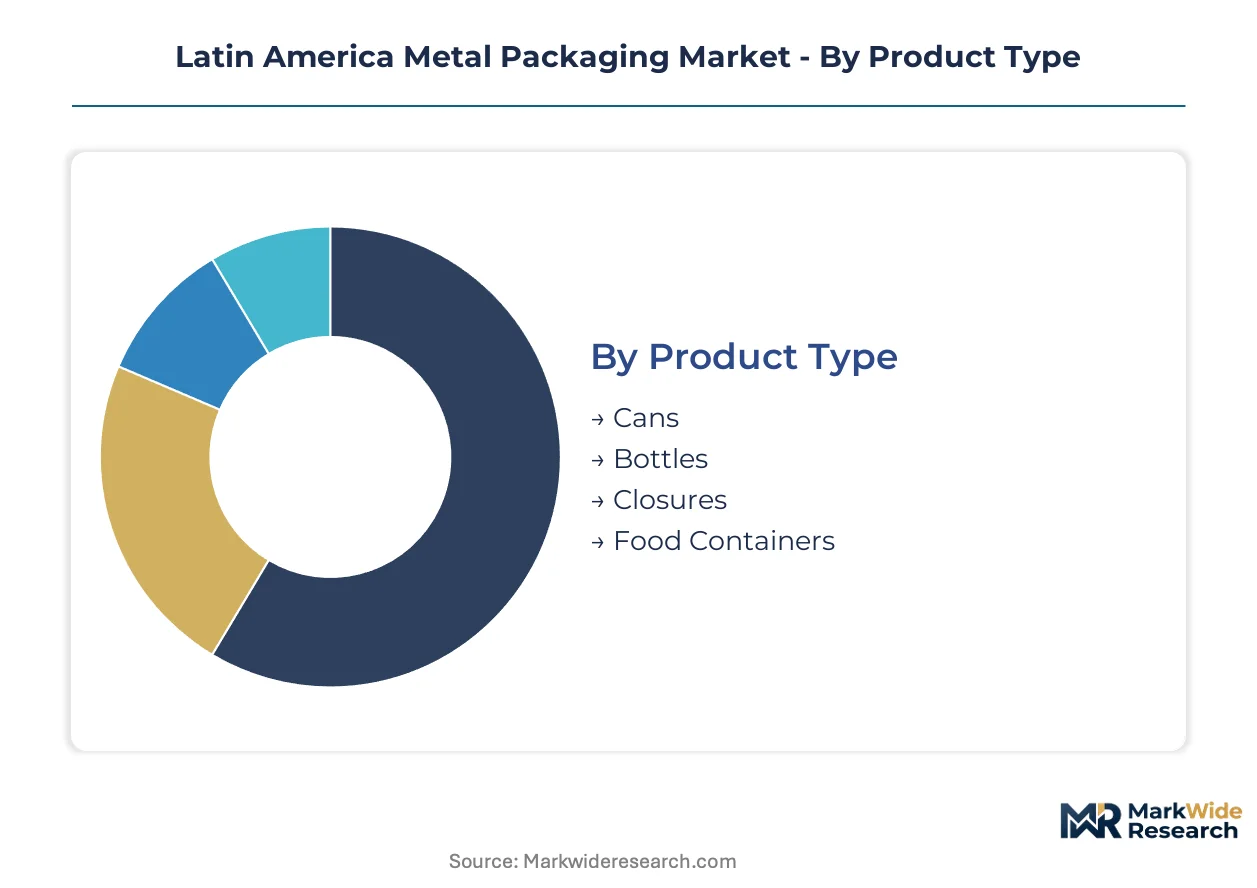
Metal packaging converters in Latin America configure production assets around distinct demand profiles that vary sharply by product geometry, material specification, and end-use sanitation requirements. Segmentation discipline separates high-velocity beverage can lines from batch-oriented food container operations with diverging capital recovery timelines.
Product Type:
Capital intensity peaks with two-piece aluminum can lines requiring precision stamping presses and necking equipment, while three-piece steel food container operations demand lower upfront tooling investment but carry higher per-unit labor content.
- Cans:Two-piece aluminum beverage cans dominate volume throughput across Brazil's southeastern manufacturing belt. São Paulo state bottlers absorb the majority of regional can output for carbonated soft drinks and beer. ANVISA migration limits are accelerating coating system upgrades, creating replacement cycles for legacy lacquered formats.
- Food Containers:Three-piece tinplate cans for shelf-stable vegetables and fish preservation retain stable demand in Brazilian and Mexican processing corridors. Retort pouch substitution is compressing growth in Mexican export-oriented segments. Steel food can lines require less capital than aluminum beverage equivalents but face higher scrap rates in deep-draw operations.
- Bottles:Aluminum bottles for premium personal care and craft beverage applications occupy niche positioning with higher per-unit margins than standard cans.
- Closures:Crown corks and screw caps represent lower capital barrier entry points for mid-tier converters, with demand tied to beverage bottler consolidation patterns.
Most installed capacity flows through Cans. Expansion is steepest in Food Containers as ANVISA compliance deadlines force coating line replacements.
Material:
Raw material selection locks converters into distinct supply chain configurations, with aluminum tying procurement to LME price exposure and recycled content mandates while steel offers more localized sourcing options.
- Aluminum:Infinite recyclability and lower transport cost profile command premium positioning in beverage applications. Brazilian recycling mandates are compressing specification tolerances for can stock, forcing requalification of coating chemistries. Crown Holdings and Ball Corporation anchor procurement through long-term smelter offtake agreements.
- Steel:Tinplate and chromium-coated steel retain cost advantages in food preservation segments where opacity and mechanical strength outweigh weight considerations. Mexican processors favor steel for export-oriented fish canning due to COFEPRIS formulation stability.
- Tinplate:Traditional lacquered tinplate faces stranded asset risk as water-based coating specifications displace solvent-based systems.
- Stainless Steel:Aerosol and industrial drum applications absorb limited volumes at premium price points.
Aluminum commands the majority of new capital deployment. Steel maintains share in food processing corridors where coating migration costs deter format switching.
End User:
Customer concentration patterns determine contract structures, with beverage bottlers demanding integrated uptime guarantees and food processors accepting longer lead times for batch-oriented production.
- Food & Beverages:Carbonated soft drink and beer bottlers channel the majority of regional metal packaging offtake. Subscription-based predictive maintenance contracts are restructuring converter-customer relationships in São Paulo state's bottling corridor. ANVISA and COFEPRIS compliance costs are raising barriers for mid-tier converters serving multinational beverage brands.
- Personal Care:Aluminum aerosol cans for cosmetics and household products represent higher-margin but smaller-volume applications. Underpenetration versus beverage segments offers margin expansion potential for converters with dedicated aerosol line capabilities.
- Household Products:Insecticide and cleaning product aerosols demand corrosion-resistant internal coatings with specialized qualification protocols.
- Industrial:Drum and pail applications for chemicals and lubricants operate on project-based procurement with volatile demand cycles.
Food & Beverages absorbs the bulk of converter capacity. Personal Care is gaining share fastest as premiumization drives aluminum aerosol adoption.
Application:
Functional use case determines performance specifications, with packaging applications demanding decorative surface quality and transportation segments prioritizing structural integrity over aesthetics.
- Packaging:Primary containment functions dominate value capture, with digital printing integration enabling variable data capabilities for batch traceability. Argentine and Chilean craft breweries are adopting digitally printed aluminum cans at accelerating pace.
- Storage:Shelf-stable food preservation requires hermetic sealing performance validated through accelerated aging protocols.
- Transportation:Industrial drum and intermediate bulk container applications emphasize stack strength and UN certification compliance.
- Distribution:Secondary and tertiary packaging configurations optimize pallet density for export logistics.
Packaging commands the preponderance of specification engineering resources. Storage applications are climbing the fastest as processed food export volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's export-oriented food processing corridors generate can demand that rivals Brazil's domestic beverage concentration, yet each country channels metal packaging investment toward distinct regulatory and supply chain configurations.
Brazil
São Paulo state's carbonated soft drink bottling corridor absorbs the majority of regional two-piece aluminum can output. ANVISA migration limits for food-contact metal surfaces are accelerating coating system upgrades across Minas Gerais processing facilities. The southeastern manufacturing belt spanning these states generates scale economies that reduce import dependency for beverage packaging converters.
Mexico
Export-oriented fish canning in Baja California and retort pouch substitution pressures are reshaping tinplate demand in shelf-stable vegetable segments. COFEPRIS sanitary standards create cross-border formulation complexity for producers serving both Mexican and Brazilian markets. Jalisco's tequila bottling cluster is adopting aluminum bottle formats for premium export positioning.
Argentina
Mendoza's wine region and Buenos Aires province craft breweries are adopting digitally printed aluminum cans for promotional customization and batch traceability. The country's national food safety regulator enforces migration limit testing protocols that align with Mercosur harmonization efforts. Argentine converters are consolidating vendor relationships around integrated uptime guarantees.
Chile
Santiago's personal care manufacturing base is expanding aluminum aerosol can adoption for cosmetics and household products. Extended producer responsibility frameworks pending in the national legislature will reconfigure collection infrastructure economics for metal scrap recovery. Valparaíso's port logistics cluster supports export-oriented canning line equipment imports.
Colombia
Bogotá's beverage bottling corridor is attracting predictive maintenance service contracts from regional equipment vendors. Pending packaging waste legislation will create first-mover advantage for integrated metal scrap recovery systems. Antioquia's manufacturing base is evaluating water-based coating technologies to meet EU Green Deal extraterritorial requirements for European export markets.
Latin America Metal Packaging Market Competitive Landscape
Top-tier vendors anchor integrated converter operations with smelter offtake agreements and multi-country manufacturing footprints, while mid-tier specialists concentrate on single-format excellence or geographic niche capture. The competitive structure rewards scale in beverage can production alongside coating chemistry qualification capabilities. Two archetypes dominate: aluminum sourcing integrators securing input material chains, and technology-focused lightweighting specialists reducing metal content per unit. Capacity expansion and strategic partnerships constitute the primary competitive moves, with converters prioritizing long-term customer relationships through subscription-based service models.
Within the integrated multinational tier, Crown Holdings, Inc., Ball Corporation, and CANPACK S.A. exemplify distinct strategic positioning. Crown Holdings occupies a position anchored by regional manufacturing footprint breadth. Ball Corporation represents aluminum sourcing partnership archetypes securing input material for beverage production. CANPACK S.A. sits within the technology leadership segment, with its corporate structure suggesting Polish-based operational origins. These three entities collectively illustrate how scale, supply chain control, and manufacturing technology differentiate competitive positioning across Latin American metal packaging.
| Leading Market Players |
|---|
| Ardagh Metal Packaging S.A. |
| Ball Corporation |
| Crown Holdings, Inc. |
| CANPACK S.A. |
| Greif, Inc. |
| Mauser Packaging Solutions |
| Trivium Packaging |
| Closure Systems International, Inc. |
| Guala Closures S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Deep-draw technician scarcity in São Paulo state's southeastern manufacturing belt compresses labor-cost differentials between premium coating-qualified converters and mid-tier legacy operators, widening pricing-tier spreads as ANVISA compliance deadlines force capability premiums.
Pricing Analysis
Capacity additions in Brazil's southeastern manufacturing belt are reshaping price floors for two-piece aluminum beverage cans as scale economies from new press installations compress per-unit conversion costs. Three-tier pricing structure across premium, standard, and economy levels separates smelter-linked converters with verified low-carbon chains from solvent-based legacy operators facing stranded asset risk. Price differentiation hinges on coating chemistry qualification status and volume scale commitments from São Paulo bottlers. Pricing pressure stems from primary aluminum LME volatility squeezing converters lacking long-term offtake agreements, with multinational beverage brands least price-sensitive and mid-tier craft brewers most exposed to pass-through volatility.
Supply Chain Analysis
Aluminum can stock supply rests on Brazilian smelter output, Mexican rolling mill capacity, and Argentine secondary recovery streams. Raw material feeds draw from bauxite refining corridors, LME-linked primary ingot, and post-consumer scrap collection networks. Supply chain risk centers on single-source vulnerability for low-carbon smelter output as recycling mandates tighten specification tolerances. Distribution runs through São Paulo state's bottling corridor for domestic beverage demand and Valparaíso port logistics for Chilean export-oriented equipment imports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America metal packaging market functions as a stable compounder anchored by beverage can demand concentration in Brazil's southeastern manufacturing belt, where carbonated soft drink and beer consumption patterns generate recurring replacement cycles for coating line upgrades.
For Market Incumbents: Anchor procurement power through long-term smelter offtake agreements securing low-carbon aluminum input chains before recycling mandate specifications tighten further. Accelerate water-based coating line retrofits to preempt ANVISA and COFEPRIS harmonization deadlines, converting stranded asset risk into compliance premiums. Defend against retort pouch substitution in Mexican fish canning segments by emphasizing steel food container hermetic sealing performance validated through accelerated aging protocols.
For New Entrants and Emerging Players: Colombian craft beverage bottlers represent an underserved buyer archetype with limited domestic two-piece aluminum can capacity and pending extended producer responsibility frameworks creating collection infrastructure gaps. Target Antioquia's manufacturing base with water-based coating capabilities aligned to EU Green Deal export requirements, leveraging first-mover positioning in integrated metal scrap recovery systems. Pursue equipment-as-a-service models with predictive maintenance contracts displacing traditional break-fix relationships in Bogotá's emerging bottling corridor.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier converters with solvent-based coating lines facing capital-intensive retrofit requirements but holding established customer relationships in São Paulo state's beverage bottling corridor. Five-to-ten-year viability favors operators with backward integration into aluminum sourcing or forward integration into subscription-based maintenance services. Watch ANVISA-COFEPRIS harmonization implementation timelines as inflection indicators for coating chemistry requalification spending waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Coating Line Retrofit | ANVISA migration limit compliance protects market access for Brazilian food-contact metal packaging converters. |
| Long-Term Smelter Offtake Agreement | Low-carbon aluminum supply security anchors procurement power as Brazilian recycling mandates tighten specification tolerances. |
| Predictive Maintenance Service Contract | Subscription-based uptime guarantees restructure converter-customer relationships in São Paulo's bottling corridor. |
| Integrated Scrap Recovery System | Pending Colombian extended producer responsibility creates first-mover advantage in collection infrastructure economics. |
| Digital Printing Capability Addition | Variable data integration captures Argentine and Chilean craft brewery demand for promotional customization and batch traceability. |
Research Methodology
Direct dialogue with coating line engineers, beverage bottler procurement directors, ANVISA regulatory compliance officers, and aluminum smelter commercial managers grounded qualitative assessments in operational reality. Secondary validation drew from ANVISA migration limit publications, COFEPRIS sanitary standard updates, Brazilian aluminum recycling mandate documentation, and customs records tracking can stock import flows. Bottom-up and top-down triangulation cross-checked converter capacity estimates against end-use demand absorption in São Paulo state's bottling corridor.
Bottom-up modeling aggregated individual converter production capacity, coating line qualification status, and customer contract structures across Brazil, Mexico, Argentina, Chile, and Colombia. Segmentation dimensions spanned product type, material specification, end-use category, and application function throughout the projection horizon. CAGRs derived from historical volume trajectories adjusted for regulatory compliance spending cycles and substitution threat intensity from retort pouches and aseptic cartons. Industry-specific inputs included ANVISA implementation timelines, LME aluminum price volatility bands, and craft brewery digital printing adoption curves.
Underlying measurement precision varies by segment; two-piece aluminum beverage can volumes carry tighter precision than personal care aerosol niche applications given concentrated demand visibility in São Paulo state's bottling corridor. Forecasts reflect assumptions around regulatory harmonization pace, smelter capacity expansion schedules, and substitution technology penetration rates. A small set of triggers warrants ongoing watch: ANVISA-COFEPRIS testing protocol convergence implementation, Colombian extended producer responsibility legislative passage, and EU Green Deal extraterritorial enforcement intensity on Latin American export-oriented producers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Metal Cans Market
Metal Packaging
United States Metal Cans Market
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
Europe Metal Cans Market
Metal Packaging
Saudi Arabia Metal Packaging Market
Metal Packaging
APAC Food Cans Market
Metal Packaging
Metal Drums Market
Metal Packaging
Egypt Metal Packaging Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
Middle East and Africa Food Cans Market
Metal Packaging
Europe Metal Closures Market
Metal Packaging
Vietnam Metal Can Packaging Market
Metal Packaging
Europe Food Cans Market
Metal Packaging
Middle East and Africa Metal Cans Market
Metal Packaging
Honeycomb Aluminum Foil Market
Metal Packaging
3-Piece Metal Cans Market