
 Food Tins and Drink Cans Market | 2026-2036
Food Tins and Drink Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Food Tins and Drink Cans Market Foresight
Ready-to-drink beverages is rebalancing the end-use mix away from traditional processed food tins as brands chase portability and chill-chain compatibility. Crown Holdings leverages its global footprint to dominate aluminum beverage can supply across North America and Europe. Ball Corporation anchors its position through deep R&D intensity in lightweight alloy formulations and infinitely recyclable can designs. Silgan Containers LLC specializes in three-piece tinplate food cans for shelf-stable proteins and vegetables, sustaining long-term contracts with major processors.
Food tins and drink cans are hermetically sealed metal containers fabricated from aluminum alloy, tinplate, or electrolytic chromium-coated steel, typically ranging from 150 mL to 5 L in nominal volume, engineered to provide oxygen barrier protection, thermal process compatibility, and extended shelf stability for consumable goods. Aluminum two-piece cans lead beverage packaging by volume due to their superior strength-to-weight ratio and compatibility with high-speed filling lines, while tinplate three-piece cans retain dominance in processed food segments where retort sterilization demands higher seam integrity. Drawn tins and impact extruded cans capture premium aerosol and specialty beverage applications where dimensional precision and decorative surface quality command price premiums.
The US EPA and FDA jointly govern can coatings and food-contact substance safety through 21 CFR regulations, while the EU REACH framework restricts bisphenol-A and other epoxy-based lining chemistries, compelling manufacturers to migrate toward polyester and oleoresin alternatives. China's SAMR enforces GB standards for heavy metal migration limits, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and lining material substitutions as these regulatory trajectories increasingly determine market access and capital allocation priorities.
Market Dynamics
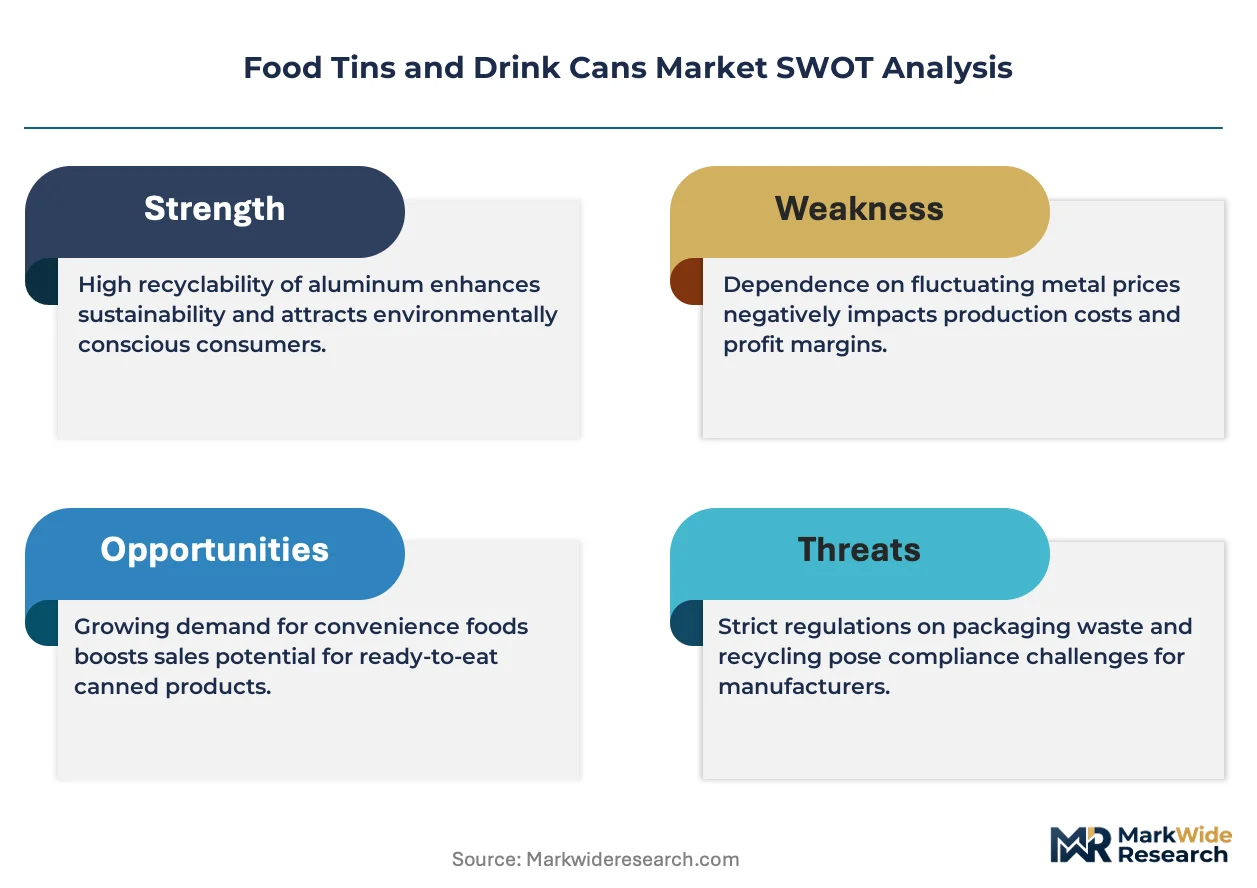
Deposit-return schemes and circular packaging mandates are restructuring procurement priorities across the food tins and drink cans value chain, forcing manufacturers to reconfigure alloy sourcing and lining chemistries ahead of compliance deadlines.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility frameworks in Germany, France, and Italy compel brands to source infinitely recyclable aluminum cans, accelerating can-to-can closed-loop systems.
- Lightweighting alloy advances:High-strength aluminum formulations reduce material intensity per unit, cutting freight costs for beverage bottlers operating high-speed filling lines.
- Southeast Asian manufacturing clusters:Vietnam and Thailand attract new canning line investments serving regional ready-to-drink brands with localized supply.
Market Restraints
- Primary aluminum price volatility:Smelter energy costs and LME price swings compress margins for two-piece beverage can producers locked into annual supply contracts.
- Tinplate supply concentration:Three-piece food can manufacturers depend on concentrated electrolytic tinplate capacity in China and Japan, exposing procurement to export quota disruptions.
- Bisphenol-A lining restrictions:EU REACH and state-level US prohibitions on epoxy-based coatings force costly polyester and oleoresin migrations without full performance parity.
Strategic Opportunities
- India beverage can penetration:Per-capita aluminum can consumption remains below regional benchmarks, creating expansion room for bottlers serving urban convenience retail.
- Aseptic canning convergence:Integration of high-pressure processing with metal packaging extends shelf-stable protein applications beyond traditional retort segments.
- Digital deposit-return infrastructure:Smart reverse vending systems in South Korea and Australia enable real-time tracking, reducing fraud and improving collection economics for recyclers.
Industry Challenges
- Coating chemist talent scarcity:Migration from epoxy to polyester and acrylic linings demands specialized formulators familiar with food-contact migration testing protocols.
- Retort seam validation timelines:Three-piece can manufacturers face 18-24 month certification cycles for new lining systems under FDA 21 CFR and EU EFSA parallel review tracks.
- Legacy canning line retrofit costs:High-speed beverage fillers require mechanical and controls upgrades to handle lighter-gauge aluminum without damage rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Tins and Drink Cans Market |
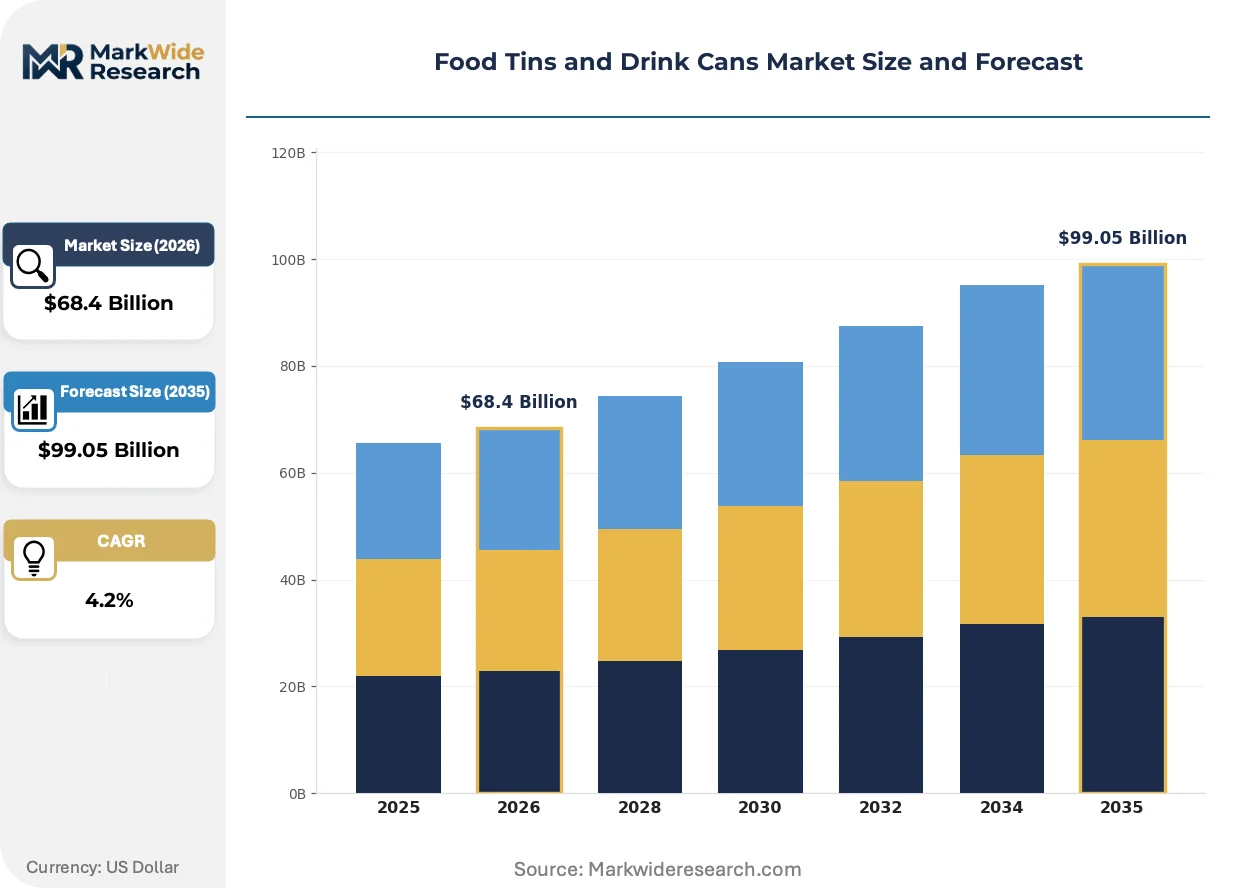
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $99.05 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Tinplate, Steel, Aluminum Composite, PET Lining Packaging Type: Drawn Tins, Impact Extruded Cans, Two-Piece Cans, Three-Piece Cans, Aerosol Cans End Use Industry: Beverage, Processed Food, Confectionery, Personal Care, Household Products Closure Type: Easy-Open End, Snap-On Lid, Peel-Off Cap, Press-On Cap, Welded Lid |
| Companies Covered | Crown Holdings, Ball Corporation, Silgan Containers LLC, Ardagh Group, CAN-PACK Group, Kian Joo Can Factory Bhd, CPMC Holdings Limited, Cansmart, Jamestrong Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Tins and Drink Cans Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry bans are simultaneously enabling lighter packaging formats and forcing rapid manufacturing process reinvention across metal container production.
High-strength aluminum alloys with modified magnesium-silicon ratios are consolidating beverage can wall thickness reductions below 90 microns while maintaining axial crush resistance. Premium sparkling water and craft beer brands in the United States and United Kingdom have adopted these gauges for 330 mL and 500 mL formats. The technology is consolidating supplier tiers as only integrated smelter-to-can makers control alloy formulation IP and casting precision.
EU REACH restrictions on bisphenol-A diglycidyl ether migrate into national implementations across France, Belgium, and Austria with staggered effective dates. Manufacturers must qualify polyester- and vinyl-organosol-based internal spray coatings under EFSA migration limit protocols, extending new product introduction cycles. Food can segments requiring aggressive retort sterilization face the steepest compliance burden, driving joint development programs between lining suppliers and can makers.
Beverage brand procurement departments now specify recycled content certificates and carbon footprint disclosures as standard vendor qualification criteria. Large-format retailers in Germany and the Netherlands audit aluminum can suppliers against EU Green Deal circularity benchmarks, displacing price-only sourcing models. This behavioral shift concentrates contract awards toward integrated recyclers with verified post-consumer scrap feedstock chains in Spain and Italy.
Food Tins and Drink Cans Market Segmentation
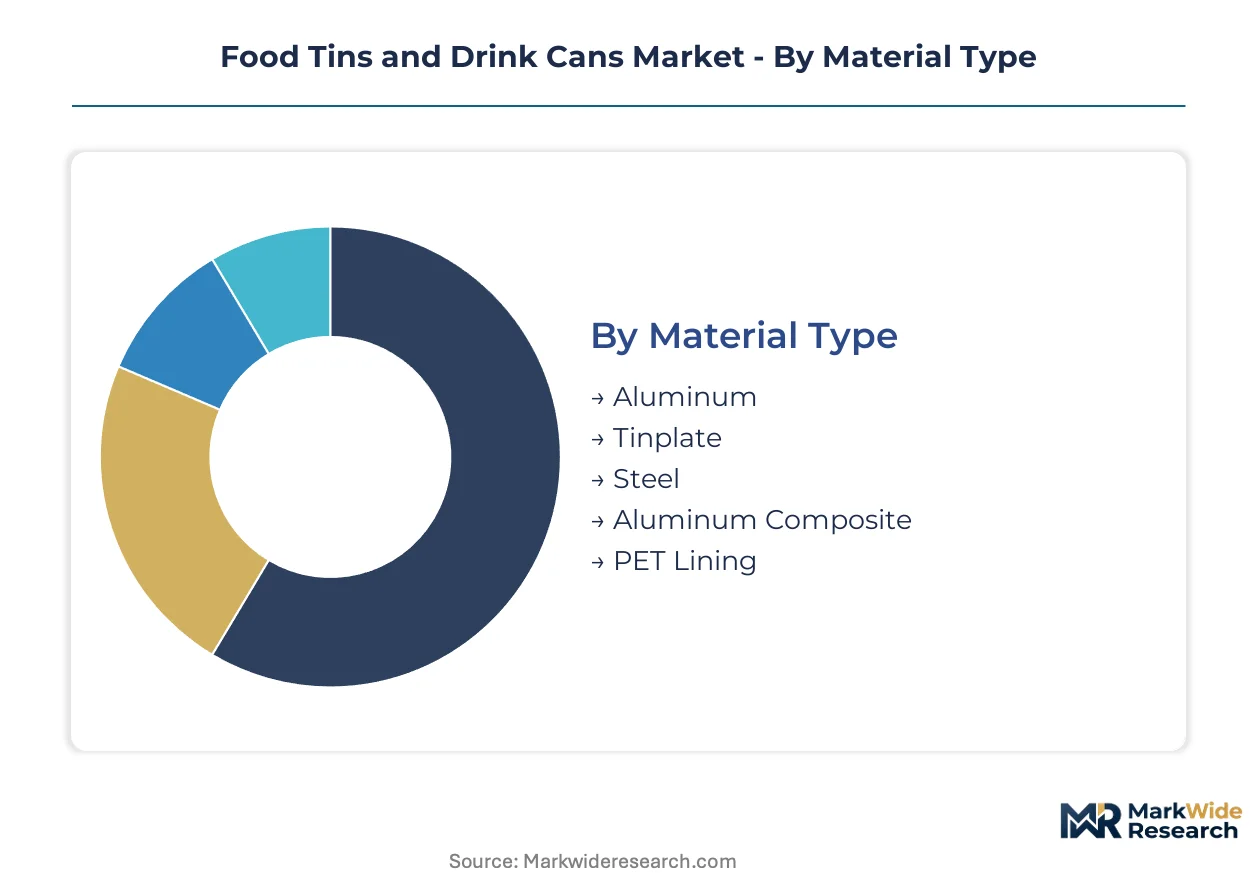
Segmentation in the food tins and drink cans market reveals how material chemistry, forming geometry, and end-use sterilization requirements dictate supplier capabilities and capital allocation. Buyers select formats based on thermal process compatibility, filling line speed, and regulatory migration limits for internal coatings.
Material Type:
Buyers prioritize strength-to-weight ratios and recycling infrastructure access when specifying base metals for can bodies and ends.
- Aluminum:High-purity alloy sheets with modified magnesium-silicon ratios enable wall thickness below 90 microns while maintaining axial crush resistance. Beverage bottlers in the United States and United Kingdom specify these gauges for 330 mL and 500 mL formats to cut freight costs.
- Tinplate:Electrolytic tin-coated steel provides superior seam integrity for three-piece food cans undergoing retort sterilization at 121°C. Processors of shelf-stable proteins and vegetables in Germany and Italy specify tinplate for long-duration thermal processes where hermetic seal failure risks spoilage.
- Steel:Chromium-coated steel variants offer cost positioning for commodity food segments with moderate barrier requirements.
- Aluminum Composite:Laminated aluminum-polymer structures capture niche applications requiring puncture resistance with reduced metal mass.
- PET Lining:Internal polyester barrier layers address EU REACH bisphenol-A restrictions in beverage cans with acidic contents.
Aluminum leads on scale; PET Lining gains share fastest as coating chemistry migrations accelerate.
Packaging Type:
Forming method determines capital intensity, line speed compatibility, and decorative surface quality available to brand owners.
- Two-Piece Cans:Draw-and-wall-ironed aluminum construction dominates high-speed beverage filling above 1,200 units per minute. Integrated smelter-to-can makers in Spain and Italy control alloy formulation IP for these formats.
- Three-Piece Cans:Rolled cylindrical bodies with seamed top and bottom ends retain dominance in processed food where retort sterilization demands higher seam integrity. Can makers serving French and Belgian vegetable processors face extended EFSA certification cycles for new lining systems.
- Drawn Tins:Deep-drawn single-piece construction serves premium confectionery and gift applications requiring seamless sidewalls.
- Impact Extruded Cans:High-pressure aluminum extrusion produces dimensional precision for aerosol valves and specialty beverage neck profiles.
- Aerosol Cans:Three-piece tinplate or aluminum construction with internal epoxy or vinyl-organosol linings withstands propellant pressure for personal care and household formulations.
Three-Piece Cans anchor food volume; Two-Piece Cans expand most quickly into ready-to-drink categories.
End Use Industry:
Application sterilization protocols and shelf-stability requirements fragment demand across divergent technical specifications.
- Beverage:Aluminum two-piece cans for carbonated soft drinks, beer, and sparkling water require compatibility with high-speed filling lines and chill-chain distribution. Brands in Vietnam and Thailand are expanding canning line orders as regional bottlers localize supply.
- Processed Food:Tinplate three-piece cans for retorted proteins, vegetables, and ready meals demand 18-24 month FDA 21 CFR and EU EFSA certification cycles for lining migrations. Major processors sustain long-term contracts with specialized can makers.
- Confectionery:Decorative drawn tins with lithographed exteriors serve seasonal and premium gifting segments.
- Personal Care:Aerosol formats for deodorants and hair sprays require pressure-rated seams and valve compatibility.
- Household Products:Larger-diameter tinplate cans for cleaners and polishes prioritize cost positioning over premium surface finish.
Processed Food leads on scale; Beverage climbs the fastest as aluminum lightweighting advances.
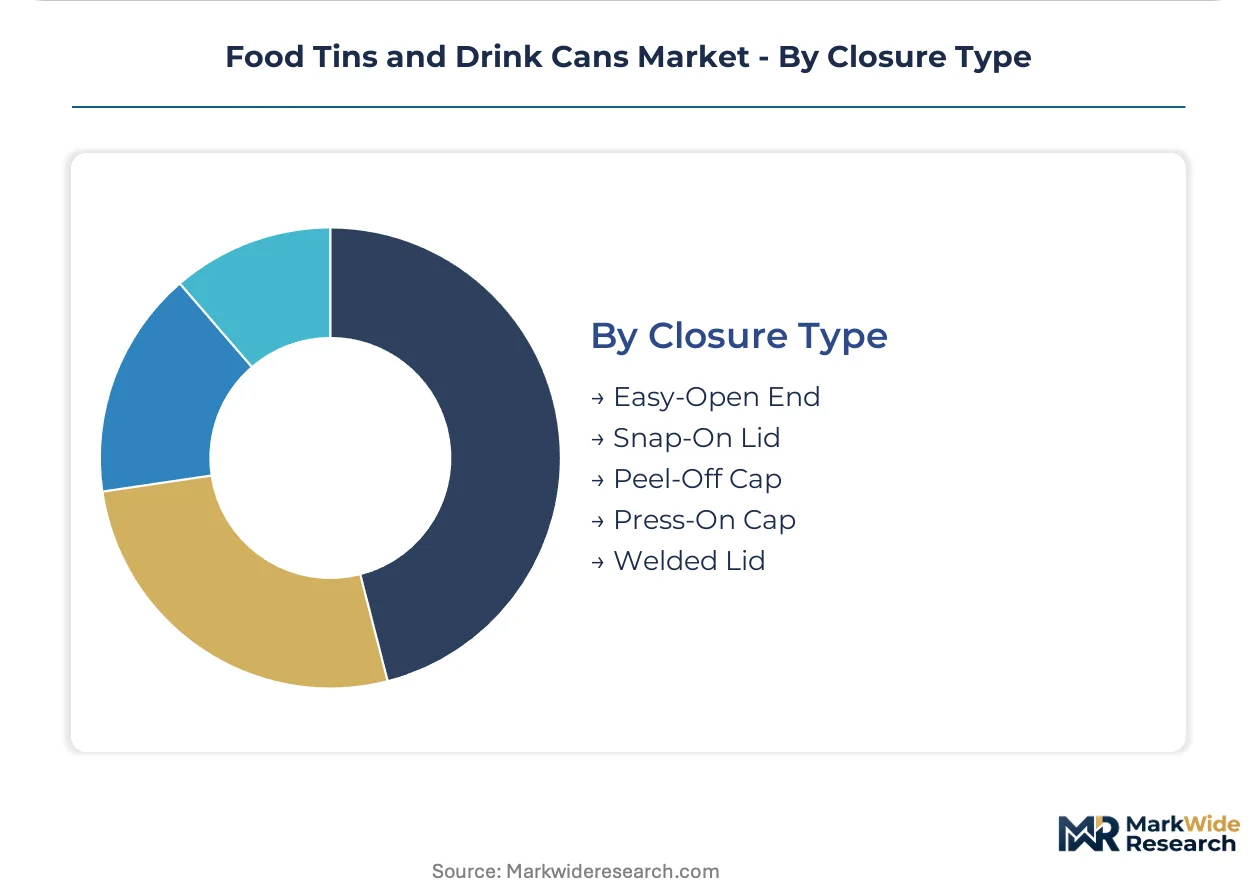
Closure Type:
Opening experience and resealability determine consumer convenience ratings and retail channel placement.
- Easy-Open End:Score-and-rupture aluminum tabs dominate beverage cans for single-serve consumption. German retailers audit suppliers against EU Green Deal circularity benchmarks for recycled content verification.
- Snap-On Lid:Reclosable plastic or metal lids for larger food tins enable partial consumption and refrigeration.
- Peel-Off Cap:Foil membrane seals for dairy and nutritional beverages provide tamper evidence with clean opening.
- Press-On Cap:Crimped metal caps for aerosol and specialty chemical cans ensure pressure retention.
- Welded Lid:Laser or resistance-welded seams for industrial and military-specification containers provide maximum integrity.
Easy-Open End leads on scale; Peel-Off Cap shows steepest expansion trajectory in nutritional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting can manufacturing toward jurisdictions with favorable extended producer responsibility frameworks and lower energy costs for primary aluminum smelting. Producers in Southeast Asia and Southern Europe capture contract flows as Northern European brands seek compliant supply with reduced carbon intensity.
Germany
Beverage bottlers in Bavaria and North Rhine-Westphalia are expanding aluminum can orders under the national deposit-return scheme administered by the Federal Environment Agency. The EU Green Deal packaging mandates compel brands to source infinitely recyclable formats with verified post-consumer content. New canning lines in the Stuttgart industrial corridor serve regional craft beer and sparkling water brands.
United States
Ready-to-drink beverage brands in Texas and the Pacific Northwest are accelerating aluminum lightweighting adoption as freight costs pressure distribution economics. The FDA and EPA jointly govern can coatings through 21 CFR regulations, creating compliance complexity for lining chemistry migrations. Crown Holdings and Ball Corporation anchor beverage can supply across multiple Midwestern and Southeastern manufacturing clusters.
Vietnam
Regional bottlers in the Red River Delta and Ho Chi Minh City metropolitan area are localizing can supply through new two-piece aluminum production investments. The Ministry of Industry and Trade enforces national standards for food-contact materials that parallel ASEAN harmonization frameworks. Canning lines in Binh Duong Province serve expanding ready-to-drink tea and coffee brands targeting domestic and export markets.
Italy
Processed food processors in Emilia-Romagna and Lombardy sustain long-term tinplate contracts for retorted vegetable and protein applications. The EU REACH framework restricts bisphenol-A in epoxy-based linings, compelling polyester and oleoresin qualification cycles under EFSA protocols. Three-piece can manufacturers in the Po Valley face extended certification timelines for new coating systems.
Thailand
Beverage bottlers in the Eastern Economic Corridor and Greater Bangkok are scaling aluminum can procurement as regional demand for carbonated soft drinks and beer climbs. The Thai Industrial Standards Institute enforces GB-aligned heavy metal migration limits for imported and domestic canstock. New canning investments in Chonburi Province supply ASEAN regional markets with reduced logistics costs.
Food Tins and Drink Cans Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated alloy-to-can producers commanding beverage volumes while tinplate fabricators anchor processed food supply. The market structure concentrates around three global packaging conglomerates with smelter partnerships, mid-tier regional specialists serving single geographies, and niche coating technology providers. Two strategic archetypes dominate: integrated recyclers with verified closed-loop scrap chains, and lightweighting innovators controlling proprietary alloy formulations. Competitive moves center on backward integration into primary aluminum casting and strategic partnerships with beverage brands for recycled content certification.
Among North American packaging conglomerates, Crown Holdings and Ball Corporation occupy positions as archetypal integrated producers with alloy formulation capabilities. Silgan Containers LLC represents the specialized tinplate fabricator segment focused on three-piece food can applications. These three companies exemplify how scale and material specialization stratify competitive positioning across beverage and processed food end-uses.
| Leading Market Players |
|---|
| Crown Holdings |
| Ball Corporation |
| Silgan Containers LLC |
| Ardagh Group |
| CAN-PACK Group |
| Kian Joo Can Factory Bhd |
| CPMC Holdings Limited |
| Cansmart |
| Jamestrong Packaging |
| Others |
Supply & Pricing Matrix
Coating chemist talent concentration in Germany's Rhine-Ruhr industrial basin widens pricing-tier spreads between premium linings and commodity alternatives, as specialized formulators familiar with EFSA migration testing command wage premiums that feed into finished can costs.
Pricing Analysis
Distributor margins for three-piece tinplate food cans absorb the steepest compression as retort-compatible polyester lining qualifications extend new product introduction cycles. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified coating systems from transitional vinyl-organosol alternatives and legacy epoxy formulations still permitted in non-EU markets. Pricing pressure stems from primary aluminum smelter energy costs feeding into two-piece beverage can base prices. Ready-to-drink bottlers operating high-speed filling lines exhibit lowest price sensitivity, while commodity vegetable processors in Southern Europe negotiate aggressively on volume contracts.
Supply Chain Analysis
Domestic-content mandates in Vietnam's Ministry of Industry and Trade circulars are reshaping sourcing patterns for ASEAN-bound canstock, compelling foreign suppliers to establish local slitting and coating operations. Primary aluminum supply concentrates in China, Russia, and Canada, while electrolytic tinplate capacity clusters in China and Japan. Raw material dependencies rest on alumina refining, tin electrolysis, and chromium plating chemistries. Single-source vulnerability runs through concentrated Japanese tinplate export quotas. Distribution feeds from integrated smelter-to-can makers in Spain and Italy through regional beverage bottler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU Green Deal compliance costs and Southeast Asian manufacturing labor rates positions Vietnam and Thailand as cost-advantaged supply bases for brands serving both ASEAN and export markets.
For Market Incumbents: To counter bisphenol-A lining restrictions compressing margin structures, backward integration into polyester coating formulation in Germany and Italy secures supply continuity. Captive supply of high-strength aluminum alloy casting in Spain locks in lightweighting IP for 90-micron wall gauges. For New Entrants and Emerging Players: Regional bottlers in Vietnam's Red River Delta present the most penetrable channel partner type for two-piece aluminum can supply, given localized demand expansion and import substitution tailwinds. White-space targets include aseptic canning convergence for shelf-stable protein applications and digital deposit-return infrastructure partnerships in South Korea. A certification-first go-to-market angle accelerates EFSA qualification timelines. For Investors and Strategic Acquirers: Beverage packaging conglomerates with smelter partnerships are the most active acquirer in this space, consolidating alloy-to-can capabilities. Long-term viability centers on closed-loop recycling economics and carbon intensity disclosure credibility. Acquisition target archetypes are regional coating technology providers with EFSA-validated polyester systems. The signal to watch is EU member state implementation timelines for REACH bisphenol-A restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Casting | Crown Holdings and Ball Corporation control magnesium-silicon formulation IP for sub-90-micron gauges. |
| Polyester Lining Qualification Investment | Silgan Containers LLC faces 18-24 month EFSA cycles for retort-compatible coating migrations. |
| Southeast Asian Manufacturing Footprint | CAN-PACK Group and Kian Joo Can Factory Bhd capture ASEAN beverage demand from Vietnam and Thailand clusters. |
| Digital Deposit-Return Infrastructure | Smart reverse vending systems in South Korea and Australia reduce collection fraud for recyclers. |
| Recycled Content Certification Program | German retailers audit aluminum can suppliers against EU Green Deal circularity benchmarks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with coating R&D directors, beverage procurement managers, food can plant engineers, and regulatory affairs leads at EFSA and FDA with secondary validation. Sources included EU REACH implementation databases, FDA 21 CFR food-contact notifications, customs records for aluminum and tinplate trade flows, and SEC filings from packaging conglomerates. Bottom-up segment sizing and top-down macroeconomic anchoring were cross-checked for consistency.
Segment-weighting approaches modeled material type, packaging geometry, end-use sterilization requirements, and closure configuration across the projection horizon. CAGRs were derived from elasticity-adjusted volume projections and value-chain margin compression assumptions. Industry-specific forecast inputs incorporated LME aluminum price volatility scenarios and EU member state lining restriction implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to smelter energy cost trajectories and REACH chemistry ban enforcement variance. Forecasts reflect documented assumptions about alloy lightweighting adoption rates and coating migration timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
United Kingdom Metal Packaging Market
Metal Packaging
Global Laminated Steel for Cans Market
Metal Packaging
Germany Metal Packaging Market
Metal Packaging
Aluminium Bottle Market
Metal Packaging
Tin Cans Market
Metal Packaging
Europe Food Cans Market
Metal Packaging
Brass Foils Market
Metal Packaging
Europe Metal Cans Market
Metal Packaging
United States Aluminium Cans Market
Metal Packaging
Europe Metal Closures Market
Metal Packaging
Honeycomb Aluminum Foil Market
Metal Packaging
North America Aluminium Cans Market
Metal Packaging
Australia Metal Packaging Market
Metal Packaging
Cans Market
Metal Packaging
Metal Aerosol Can Market
Metal Packaging
Metal Cans Market