
 Aluminum Aerosol Cans Market | 2026-2036
Aluminum Aerosol Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Aerosol Cans Market Analysis
REACH compliance is consolidating the European supplier base as smaller coaters exit the market. Trivium Packaging leverages integrated aluminum sourcing to control input costs across its European footprint. Ball Corporation sustains technology leadership through advanced lightweighting programs that reduce metal content per unit. Exal Corporation anchors North American supply through dedicated personal care and pharmaceutical filling partnerships.
Aluminum aerosol cans are cylindrical pressure containers fabricated from aluminum alloy slugs through impact extrusion or drawing and ironing, typically featuring internal epoxy or polyester coatings to prevent chemical interaction with contents, designed to dispense products via compressed or liquefied gas propellants. The standard product type dominates volume shipments across mass-market personal care applications, while specialty configurations command premium positioning in pharmaceutical and high-end cosmetic segments. Hair care applications lead absolute demand within the application dimension, whereas surface cleaning formulations represent the fastest-growing use case as household brands convert from trigger sprayers to aerosol formats for convenience positioning.
EMA stability testing guidelines and FDA container closure system requirements shape pharmaceutical aerosol qualification protocols, extending development timelines but creating durable supplier relationships. The EU Green Deal circular economy action plan mandates minimum recycled content thresholds that reshape aluminum sourcing strategies across European converters. Stakeholders must monitor evolving propellant regulations and recycled aluminum certification schemes to secure long-term formulation and sourcing flexibility.
Market Dynamics
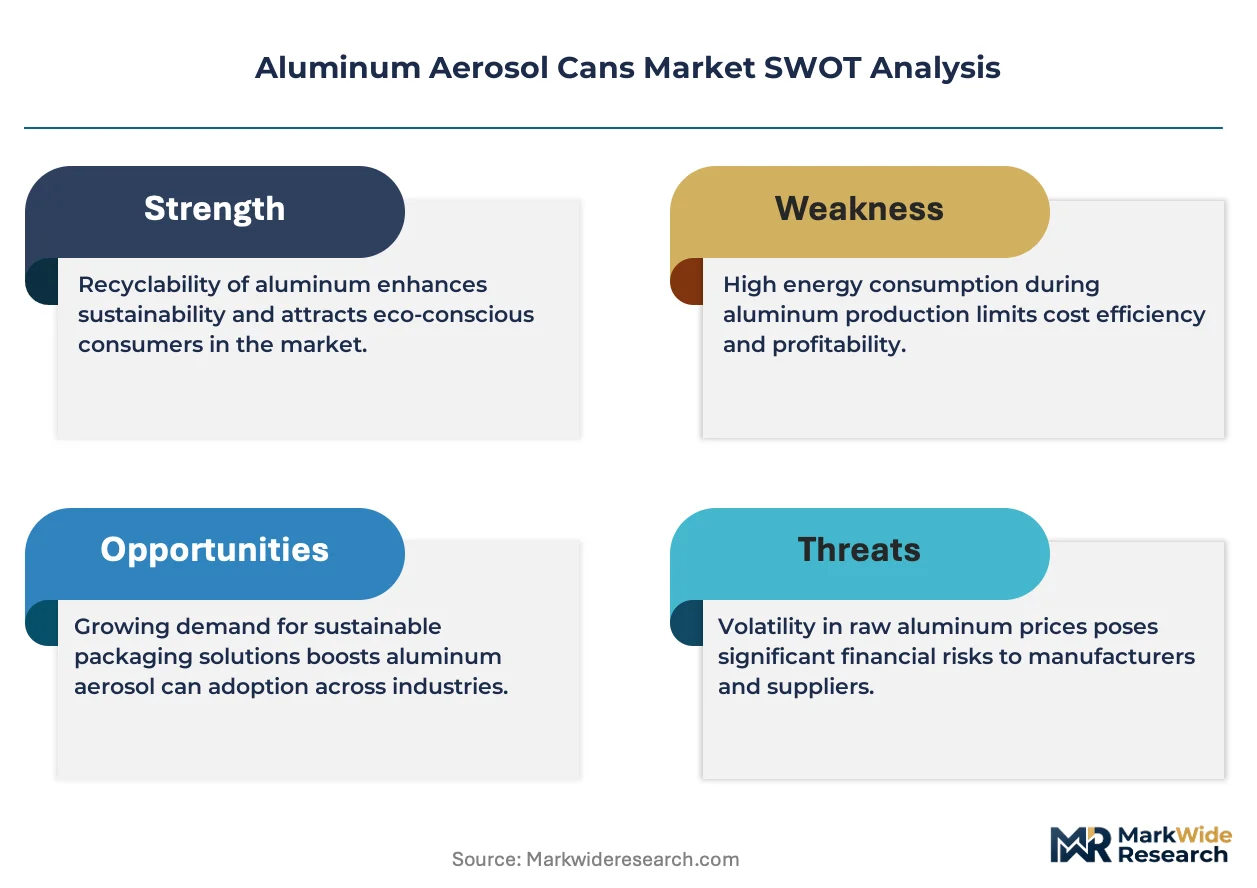
The EU F-Gas Regulation is forcing converters across Europe to abandon high-global-warming-potential propellants, triggering a wholesale retooling of filling infrastructure and coating chemistries that reshapes supplier qualification criteria.
Growth Catalysts
- Personal care line expansion:Formulators in India and Brazil are launching aerosol variants of dry shampoos, sunscreens, and body sprays, creating pull for domestic can production.
- REACH compliance consolidation:Smaller European coating suppliers are exiting the market, concentrating volume among qualified converters with certified epoxy and polyester lining capabilities.
- Household format conversion:Surface cleaning brands are abandoning trigger sprayers for aerosol formats, driving demand for standard-diameter cans with corrosion-resistant internal coatings.
Market Restraints
- Primary aluminum volatility:LME price swings and European smelter energy costs compress converter margins and destabilize annual contract negotiations with personal care multinationals.
- Specialty coating concentration:Three European chemical suppliers control the majority of pharmaceutical-grade epoxy formulations, creating single-source risk for CDSCO and FDA-compliant can production.
- Compressed gas substitution:Bag-on-valve systems and mechanical pumps are capturing niche personal care segments that previously relied on liquefied gas propellants.
Strategic Opportunities
- Indian domestic capacity scaling:Greenfield extrusion and ironing lines in Gujarat and Maharashtra are positioning to serve local pharmaceutical formulators seeking import substitution.
- EU Green Deal circular mandates:Minimum recycled content thresholds are creating first-mover advantage for converters with certified post-consumer aluminum sourcing and mass-balance documentation.
- Pharmaceutical qualification partnerships:EMA stability testing and FDA container closure requirements favor long-term supplier relationships with dedicated filling line validation protocols.
Industry Challenges
- Coating technician scarcity:Qualified specialists for spray-applied epoxy and polyester internal lining application are concentrated among aging workforces in Germany and Italy.
- Propellant system revalidation:Converters face compressed timelines to qualify hydrofluoroolefin and dimethyl ether alternatives under evolving EPA SNAP and EU F-Gas implementation schedules.
- Lightweighting tooling capex:Advanced impact extrusion presses capable of sub-10-gram weight reduction require capital commitments that strain mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Aerosol Cans Market |
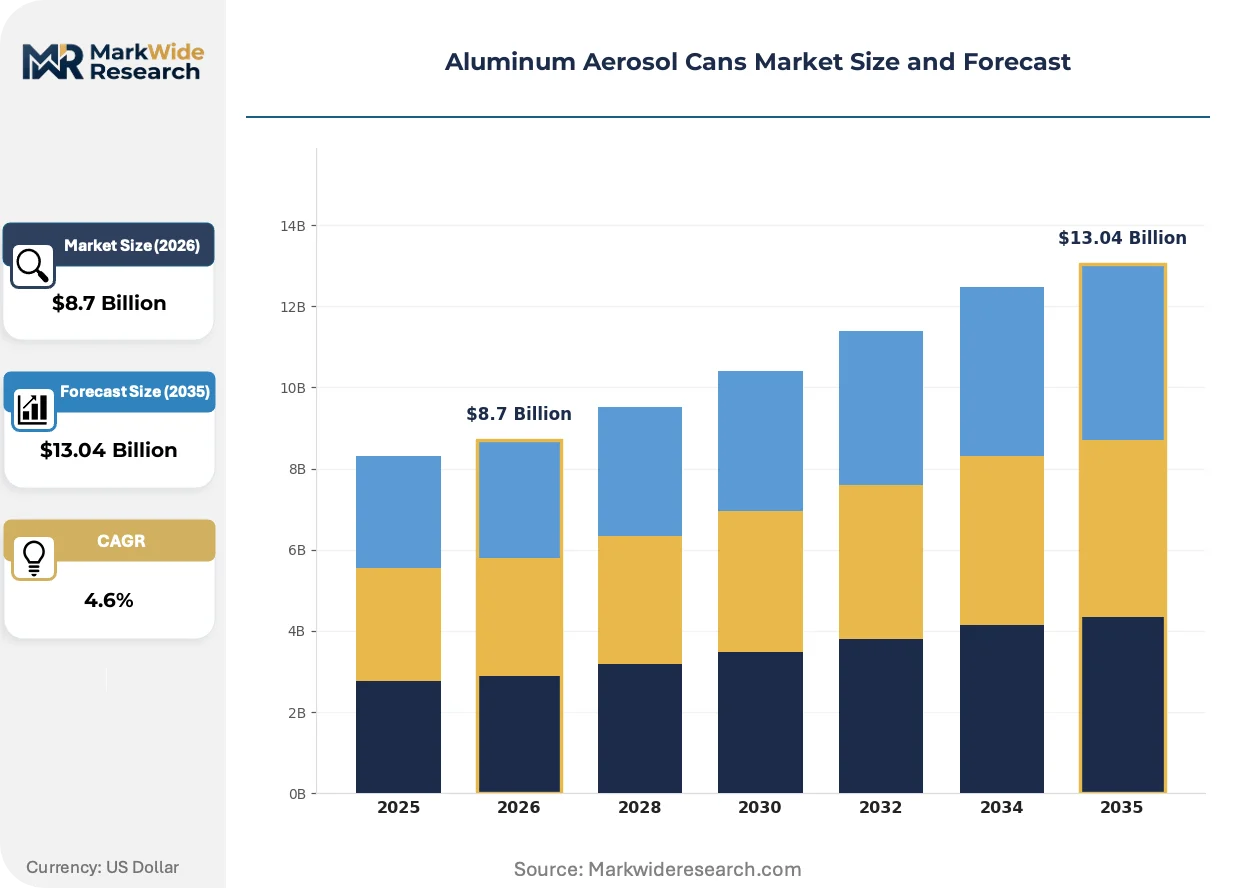
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Biodegradable, Refillable, Specialty Capacity: 50ml, 100ml, 200ml, 300ml End User: Personal Care, Household, Food & Beverage, Pharmaceuticals Application: Hair Care, Surface Cleaning, Insect Repellent, Paint |
| Companies Covered | Trivium Packaging, Exal Corporation, Ball Corporation, Bharat Containers, TUBEX GmbH, Crown Holdings, Colep Packaging, CCL Container, Ardagh Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Aerosol Cans Market Emerging Trajectories
Digital printing and smart packaging integration are transforming how aluminum aerosol cans communicate with consumers and supply chain partners, shifting value capture from commodity metal forming to data-enabled brand engagement.
Direct-to-can digital printing technology is rewriting decoration economics for short-run cosmetic and pharmaceutical launches. Niche beauty brands in France and South Korea are adopting digitally printed variable designs with batch-specific QR codes for anti-counterfeiting. This capability is compressing minimum order quantities from hundreds of thousands to tens of thousands, enabling regional formulation strategies.
The EU F-Gas Regulation is mandating propellant transitions that cascade through coating chemistry specifications. Converters must revalidate internal linings against new solvent and surfactant interactions, extending pharmaceutical qualification timelines. German and Italian filling partnerships are absorbing these compliance costs through multi-year supply agreements with personal care multinationals.
Household brands are consolidating aerosol procurement through direct converter relationships, bypassing traditional can distributors. Large cleaning product manufacturers in the United States and United Kingdom are negotiating specification control directly with Ball Corporation and Trivium Packaging. This disintermediation is visible most acutely in North American private label surface cleaner launches.
Aluminum Aerosol Cans Market Segmentation
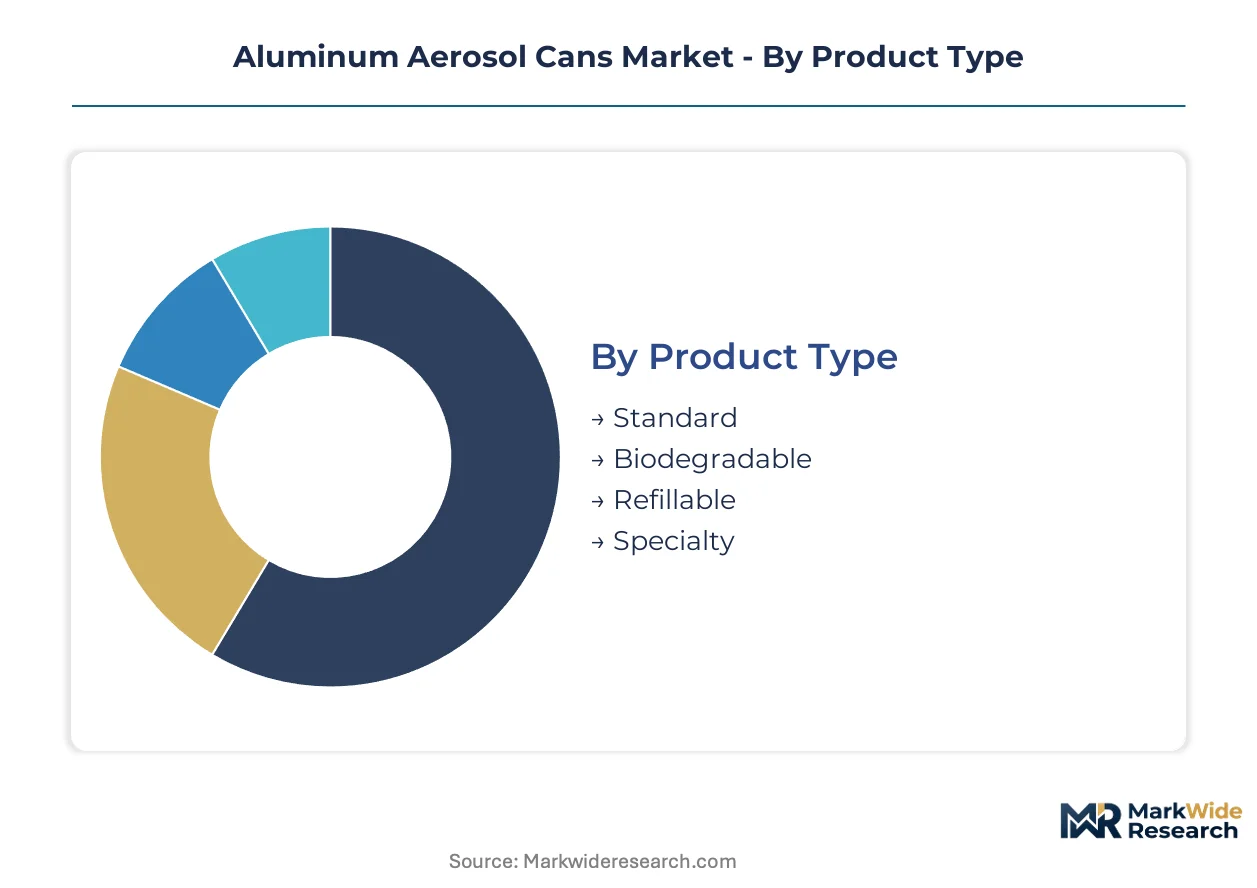
Segmentation in aluminum aerosol cans reveals how capital deployment, regulatory compliance, and end-use performance requirements fragment manufacturing capabilities across converter tiers. Each dimension—product type, capacity, end user, and application—carries distinct tooling, coating, and qualification thresholds that shape competitive positioning.
Product Type:
Capital intensity peaks with specialty configurations requiring multi-layer internal linings and custom extrusion tooling, while standard formats amortize equipment costs across high-volume personal care contracts.
- Standard:Single-layer epoxy or polyester internal coating on drawn-and-ironed or impact-extruded bodies serves mass-market personal care and household brands. Demand concentrates in India and Brazil where domestic converters scale capacity to serve local formulators seeking import substitution.
- Specialty:Multi-layer barrier coatings, shaped shoulders, and precision orifice designs address pharmaceutical sterility requirements and high-end cosmetic differentiation. European converters with EMA-validated filling partnerships capture premium positioning as CDSCO and FDA qualification timelines extend.
- Biodegradable:Experimental bio-based internal lining chemistries and end-of-life degradation triggers target sustainability-positioned brands in France and South Korea.
- Refillable:Threaded valve interfaces and reinforced sidewall structures support circular economy pilots under EU Green Deal circular economy action plan mandates.
Most installed capacity flows through Standard. Expansion is steepest in Specialty.
Capacity:
Volume scale determines converter equipment configuration, with smaller diameters requiring dedicated mini-extrusion presses and larger formats demanding reinforced ironing stations.
- 200ml:The workhorse diameter for hair care and surface cleaning applications balances material efficiency with shelf presence. Indian greenfield extrusion lines in Gujarat and Maharashtra target this format for domestic pharmaceutical and personal care formulators.
- 300ml:Reinforced wall thickness and enhanced dome profiles serve household cleaning and paint applications where propellant load and internal pressure specifications exceed personal care norms. North American private label surface cleaner launches drive specification negotiations directly with integrated converters.
- 50ml:Miniature impact-extruded formats for travel-size cosmetics and pharmaceutical metered-dose applications.
- 100ml:Mid-range diameter for premium body sprays and sunscreen aerosols with digital printing decoration compatibility.
Converter utilization rates peak at 200ml. 300ml gains share fastest in household format conversion.
End User:
Customer qualification protocols separate pharmaceutical-grade suppliers from commodity converters, with EMA stability testing and FDA container closure requirements creating durable switching costs.
- Personal Care:Dry shampoos, sunscreens, and body sprays dominate absolute volume, with Indian and Brazilian formulators expanding aerosol product lines. REACH compliance consolidation in Europe concentrates volume among qualified converters with certified epoxy and polyester lining capabilities.
- Pharmaceuticals:Inhalers, topical sprays, and metered-dose systems require validated coating chemistries and dedicated filling line partnerships. Three European chemical suppliers control majority pharmaceutical-grade epoxy formulations, creating single-source risk for CDSCO and FDA-compliant production.
- Household:Surface cleaning brands abandoning trigger sprayers for aerosol formats demand corrosion-resistant internal coatings and standard-diameter can geometries.
- Food & Beverage:Whipped cream and cooking spray applications require food-contact-compliant lining systems and specialized valve configurations.
Personal Care commands the largest share of installed capacity. Pharmaceuticals shows the steepest margin expansion trajectory.
Application:
Functional performance requirements—corrosion resistance, spray pattern precision, and propellant compatibility—determine coating specification and valve integration complexity.
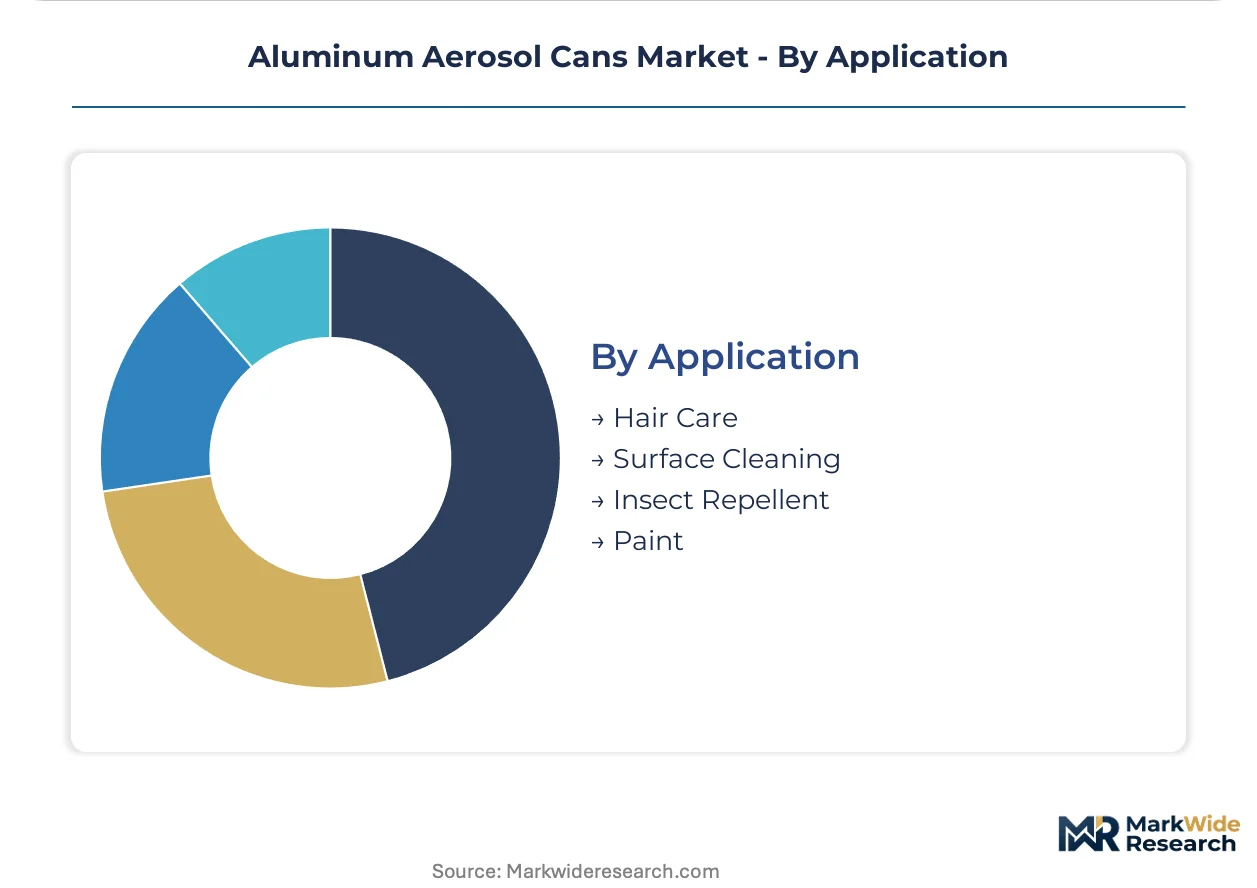
- Hair Care:Dry shampoos and styling sprays lead absolute demand, with formulations requiring solvent-resistant internal linings and consistent actuator spray patterns. EU F-Gas Regulation propellant transitions cascade through coating chemistry revalidation for this high-volume segment.
- Surface Cleaning:Converting from trigger sprayers to aerosol formats drives fastest demand growth, with corrosion-resistant epoxy linings essential for alkaline and acidic formulations. Direct converter relationships bypass traditional distributors in the United States and United Kingdom.
- Insect Repellent:DEET and picaridin formulations demand aggressive-chemical barrier coatings and specialized valve seals.
- Paint:High-solvent content and pigment suspension requirements push internal lining specifications toward multi-layer polyester systems.
Hair Care anchors converter volume commitments. Surface Cleaning climbs the fastest as household brands consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized coating technicians in Germany and Italy anchor the industry's technical workforce, while extrusion press operators in Gujarat and Maharashtra form a rapidly scaling talent pool serving domestic pharmaceutical formulators.
United States
Household cleaning brands negotiate directly with integrated converters for surface cleaner aerosol specifications, bypassing traditional distributors. EPA SNAP regulations drive hydrofluoroolefin propellant transitions across filling infrastructure. The Midwest industrial corridor hosts lightweighting programs that reduce metal content per can unit.
Germany
EMA-validated filling partnerships concentrate pharmaceutical aerosol qualification among converters with certified epoxy lining capabilities. REACH compliance consolidates the European coating supplier base as smaller formulators exit. The Baden-Württemberg cluster absorbs EU F-Gas Regulation compliance costs through multi-year supply agreements.
India
Domestic personal care brands expand aerosol product lines for dry shampoos and sunscreens, creating pull for local can production. CDSCO pharmaceutical qualification protocols extend development timelines but secure durable supplier relationships. Greenfield extrusion and ironing lines in Gujarat and Maharashtra scale capacity to serve import substitution demand.
Brazil
Formulators launch aerosol variants of body sprays and sunscreens, driving demand for standard-diameter cans with corrosion-resistant internal coatings. ANVISA pharmaceutical container requirements shape local qualification standards. São Paulo-based converters position to capture Latin American personal care volume.
France
Niche beauty brands adopt digitally printed variable designs with batch-specific QR codes for anti-counterfeiting. EU Green Deal circular economy mandates create first-mover advantage for converters with certified post-consumer aluminum sourcing. The Île-de-France region hosts sustainability-positioned pilots for bio-based internal lining chemistries.
Aluminum Aerosol Cans Market Vendor Landscape
The competitive structure tilts toward integrated metal forming specialists with captive aluminum sourcing and certified coating capabilities. Tiered differentiation separates EMA-validated pharmaceutical suppliers from mass-market personal care converters. Two strategic archetypes dominate: integrated giants controlling upstream metal supply, and regional specialists with dedicated filling partnerships. Capacity expansion and coating chemistry revalidation constitute the dominant competitive moves as propellant regulations cascade through qualification requirements.
Among integrated packaging conglomerates, Ball Corporation and Trivium Packaging occupy positions exemplifying scale-driven metal forming and supply chain control. TUBEX GmbH represents the European specialist archetype with concentrated coating expertise. These three entities anchor the competitive landscape across distinct strategic vectors—integrated sourcing, lightweighting technology, and pharmaceutical-grade validation—without exclusive segment capture.
| Leading Market Players |
|---|
| Trivium Packaging |
| Exal Corporation |
| Ball Corporation |
| Bharat Containers |
| TUBEX GmbH |
| Crown Holdings |
| Colep Packaging |
| CCL Container |
| Ardagh Group |
| Others |
Supply Flow & Price Mechanics
Impact extrusion press modernization simultaneously compresses per-unit metal costs and concentrates converter tiering, as only integrated operators with captive aluminum sourcing absorb the capital burden of sub-10-gram lightweighting programs while smaller competitors face margin erosion from LME volatility and European smelter energy premiums.
Pricing Analysis
Coating-and-filling bundled service contracts dominate pharmaceutical and high-end cosmetic segments, while standard personal care volumes trade on per-unit transactional terms with annual price negotiations. Price differentiation separates EMA-validated specialty configurations from mass-market standard formats, with certification grade and volume scale as primary levers. Cost compression in the standard tier is intensifying because Indian domestic capacity scaling creates oversupply pressure for commodity diameters. Household brands exhibit highest price sensitivity due to direct converter procurement bypassing distributor margins, whereas pharmaceutical formulators accept premium positioning for validated filling partnerships.
Supply Chain Analysis
Qualified coating technicians for spray-applied epoxy and polyester internal lining concentrate in aging workforces across Germany and Italy, constraining capacity expansion for pharmaceutical-grade production. Raw material flows draw from primary aluminum smelters in Germany and India, specialty epoxy resin formulators in Europe, and valve component manufacturers in China. Single-source vulnerability pervades pharmaceutical-grade epoxy formulations where three European chemical suppliers control majority supply. Distribution runs through direct converter relationships with household multinationals in North America and filling partnerships with personal care brands in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in aluminum aerosol cans rests on lightweighting-driven metal cost reduction and premium-tier shift toward pharmaceutical validation, where EMA and FDA qualification timelines create durable supplier switching costs.
For Market Incumbents: To counter Indian domestic capacity scaling in standard-diameter formats, accelerate backward integration into certified post-consumer aluminum sourcing to capture EU Green Deal circular mandate premiums, and consolidate coating technician training pipelines in Germany and Italy to defend pharmaceutical-grade positioning. For New Entrants and Emerging Players: Regional filling partners in Brazil and India offer the most penetrable channel for white-space capture, targeting personal care formulators seeking import substitution with standard-format supply, and pursuing direct specification control with household brands converting from trigger sprayers to aerosol formats. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier converters lacking pharmaceutical validation but possessing extrusion press capacity in India or Brazil, with long-term viability hinging on coating chemistry revalidation capabilities for hydrofluoroolefin and dimethyl ether propellant transitions; monitor EPA SNAP and EU F-Gas implementation schedules as inflection signals for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting Technology Investment | Sub-10-gram metal reduction programs at Ball Corporation and Trivium Packaging compress input costs per unit. |
| Pharmaceutical Qualification Partnership | EMA-validated filling agreements with German and Italian converters extend CDSCO and FDA-compliant supply relationships. |
| Recycled Aluminum Sourcing Certification | Mass-balance documentation for post-consumer aluminum secures first-mover advantage under EU Green Deal mandates. |
| Digital Printing Capability Expansion | Direct-to-can variable decoration at French and South Korean converters compresses minimum order quantities for niche beauty launches. |
| Greenfield Capacity in India | Extrusion and ironing lines in Gujarat and Maharashtra serve domestic pharmaceutical formulators seeking import substitution. |
Methodological Framework
Multiple input streams — converter production data, regulatory filing repositories, and primary stakeholder interviews — were reconciled through bottom-up and top-down triangulation. Conversations with plant managers at European and Indian extrusion facilities, procurement leads at personal care multinationals, coating chemistry specialists in Germany and Italy, and regulatory affairs directors navigating EMA and FDA qualification protocols informed demand and supply-side assumptions. Secondary validation drew from EU F-Gas Regulation implementation documents, EPA SNAP program updates, CDSCO pharmaceutical container guidelines, customs trade data for aluminum alloy slugs, and SEC filings from integrated packaging conglomerates.
Historical volume trajectories were cross-referenced against expert panel inputs across product type, capacity tier, end-user segment, and application dimensions to model expansion paths over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro aluminum demand indicators and regional manufacturing capacity buildout announcements. Industry-specific forecast inputs included propellant transition timelines under evolving regulatory schedules, pharmaceutical qualification pipeline visibility, and greenfield extrusion press installation tracking in India.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to LME price volatility, European energy cost trajectories, and coating technician workforce attrition. Forecasts reflect documented assumptions regarding regulatory implementation schedules and capacity expansion completion rates. Material deviation in EPA SNAP or EU F-Gas enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Three Piece Cans Market
Metal Packaging
Global Laminated Steel for Cans Market
Metal Packaging
Converter Aluminum Foil Market
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
Metal Containers Market
Metal Packaging
Two Piece Metal Containers Market
Metal Packaging
India Metal Cans Market
Metal Packaging
Specialty Tin Cans Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
Aluminum Cans Market
Metal Packaging
Middle East and Africa Metal Cans Market
Metal Packaging
North America Metal Packaging Market
Metal Packaging
United Kingdom Metal Packaging Market
Metal Packaging
PTP Aluminum Foil Market
Metal Packaging
Thailand Metal Packaging Market