
 Germany Metal Packaging Market | 2026-2036
Germany Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Metal Packaging Market Foresight
Digital printing on metal substrates is fragmenting traditional batch-run economics across German can lines. Ball Corporation leverages its beverage can specialization to anchor supply relationships with major German brewers. Silgan Holdings Inc. sustains diversified exposure across food and aerosol formats, while Trivium Packaging B.V. differentiates through decorated specialty tinplate for premium confectionery brands.
Germany metal packaging comprises rigid and semi-rigid containers fabricated from electrolytic tinplate, cold rolled steel, or aluminum sheet, typically formed through drawing, ironing, or three-piece welding processes with interior lacquer coatings for corrosion resistance. These structures protect oxygen-sensitive contents, enable high-speed filling lines, and support closed-loop recycling via established German dual systems. Aluminum cans capture the fastest growth trajectory within product type segments, driven by beverage industry lightweighting targets and magnetically separable recovery streams. Beverage applications dominate volume demand, while personal care aerosol cans retain higher margin pools due to technical barrier specifications and smaller batch complexity.
Germany's Federal Environment Agency enforces VerpackG compliance thresholds, and the EU F-Gas Regulation constrains propellant choices for aerosol formats, together elevating design-for-recycling investments across converter R&D programs. KBA vehicle-type approval standards indirectly shape steel drum specifications for automotive coatings and lubricants logistics. Stakeholders must monitor pending EU Packaging and Packaging Waste Regulation revisions, as these will recalibrate minimum recycled content mandates and alter competitive positioning between domestic tinplate and imported aluminum supply.
Market Dynamics
Digital printing on metal substrates is fragmenting traditional batch-run economics across German can lines, forcing converters to retool for shorter runs and faster changeovers while VerpackG compliance costs escalate.
Growth Catalysts
- Beverage lightweighting mandates:Aluminum can adoption accelerates across Bavarian craft breweries and North Rhine-Westphalia carbonated drink bottlers seeking magnetically separable recovery streams.
- VerpackG recyclability thresholds:Extended producer responsibility rules push converters toward closed-loop aluminum systems and lighter tinplate designs with measurable recycling performance.
- Hamburg port logistics cluster:Concentrated food and beverage processing demand around this northern hub creates dense procurement pools for regional metal packaging suppliers.
Market Restraints
- Primary aluminum price volatility:Input cost swings for aluminum sheet strain converter margin structures, particularly for beverage can specialists with limited pass-through mechanisms.
- Tinplate supply concentration:Dependence on integrated steel mill complexes in the Ruhr region elevates vulnerability to energy cost shocks and production curtailments.
- F-Gas Regulation constraints:EU limits on hydrofluorocarbon propellants complicate aerosol can formulations for personal care manufacturers, requiring reformulation investments.
Strategic Opportunities
- Premium confectionery decoration:Specialty tinplate with high-definition lithography captures margin pools from Stuttgart's chocolate and luxury food processors seeking shelf differentiation.
- Automotive coatings logistics:KBA vehicle-type approval standards for steel drum specifications create captive demand from chemical suppliers serving Germany's automotive belt.
- Digital print convergence:Combination of inkjet deposition and inline inspection technologies enables economical runs below ten thousand units, opening craft beverage segments previously closed to metal.
Industry Challenges
- Electrocoating chemistry expertise:Lacquer formulation for high-acid food compatibility requires specialized polymer science talent that German technical universities produce insufficiently.
- Dual system certification timelines:VerpackG registration and recyclability testing for new container geometries extend product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Metal Packaging Market |
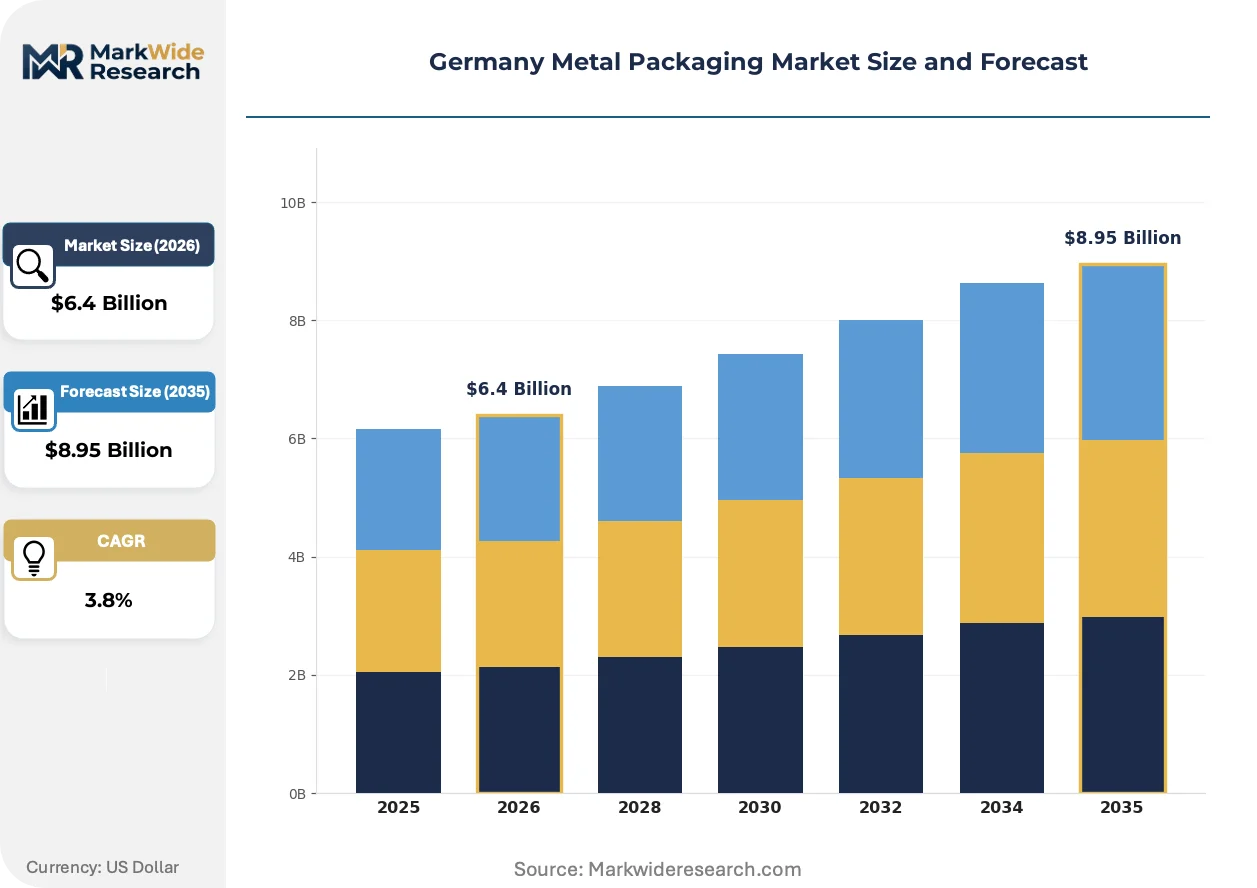
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $8.95 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tinplate Cans, Aluminum Cans, Steel Drums, Aerosol Cans, Aluminum Foil Containers Material: Electrolytic Tinplate, Cold Rolled Steel, Aluminum Sheet, Stainless Steel, Galvanized Steel Application: Beverages, Foodstuff, Chemicals, Paints & Coatings, Personal Care End User: Food & Beverage Manufacturers, Chemical Producers, Cosmetic Companies, Pharmaceutical Firms, Paints Manufacturers |
| Companies Covered | LK-PremiumPack GmbH, Silgan Holdings Inc., Ball Corporation, Trivium Packaging B.V., KLANN Packaging GmbH, Ardagh Metal Packaging S.A., HUBER Packaging Group GmbH, Muller und Bauer GmbH & Co KG, Crown Holdings Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Metal Packaging Market Shifts & Advancements
Digital workflows are compressing the traditional moat of long-run economies in metal decoration, while regulatory pressure on material circularity accelerates design-for-recycling investments across converter R&D programs.
High-speed inkjet deposition systems for cylindrical metal substrates are virtualizing the conventional lithographic setup that dominated beverage can decoration for decades. Craft breweries in Bavaria and North Rhine-Westphalia now specify digitally printed aluminum cans for seasonal and limited releases at run lengths below fifty thousand units. This technology is virtualizing the volume thresholds that previously locked small brands out of metal packaging, fragmenting batch economics and forcing traditional lithography houses to defend position through speed rather than minimum order size.
Pending EU Packaging and Packaging Waste Regulation revisions will recalibrate minimum recycled content mandates for metal containers sold across member states. German converters anticipate stricter thresholds than current VerpackG requirements, prompting accelerated investment in closed-loop aluminum sorting infrastructure. Beverage applications face the steepest compliance ramps, as food-contact safety specifications limit the share of post-consumer recycled content permitted in tinplate food cans.
Consolidated procurement by multinational beverage groups is compressing supplier rosters and extending contract durations for surviving converters. Hamburg's port logistics cluster and Stuttgart's industrial food processing belt now concentrate purchasing decisions among three to four major brewers and dairy processors, displacing fragmented regional buying patterns. This concentration is most visible in aluminum can supply, where annual volume commitments exceeding five hundred million units now determine converter capacity planning.
Germany Metal Packaging Market Segmentation
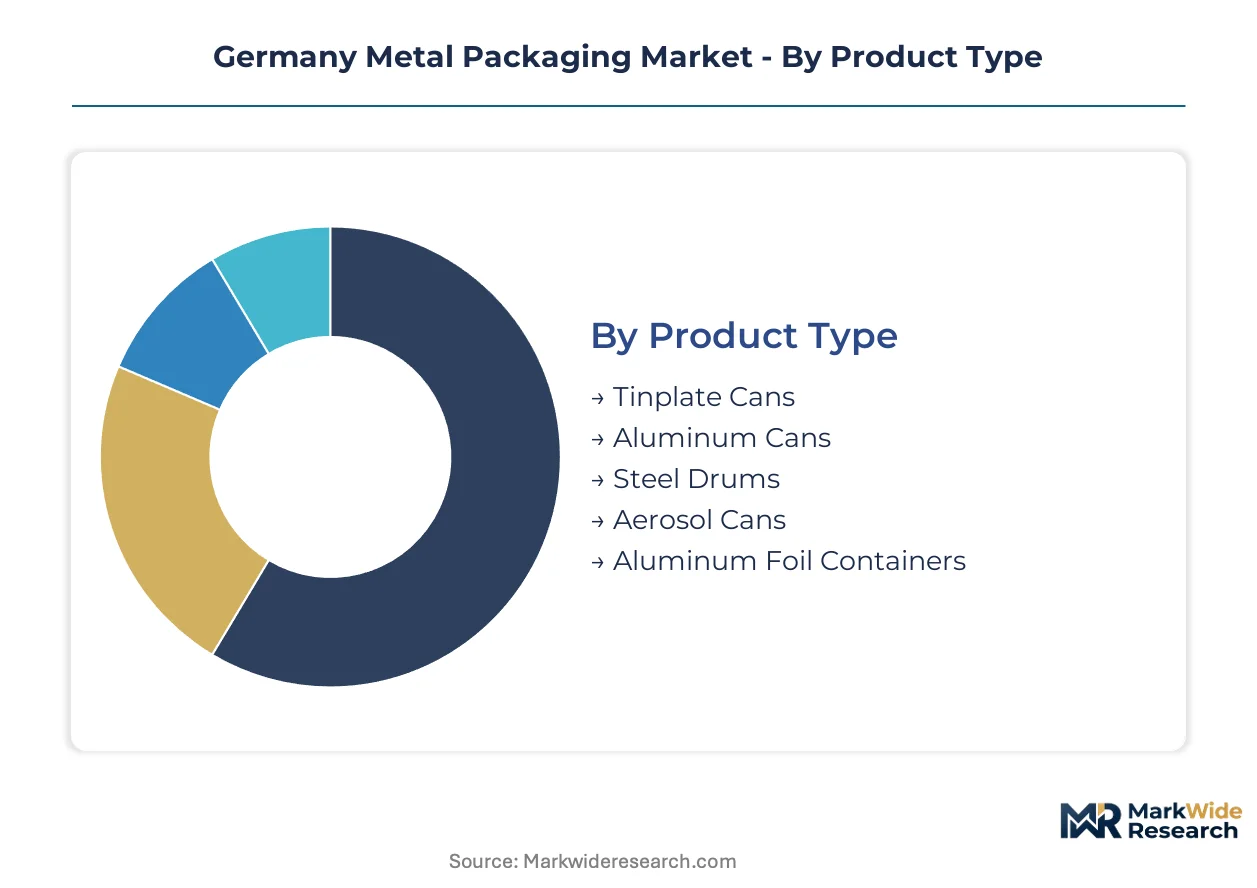
German metal packaging segmentation reveals how material science and regulatory pressure fragment converter capabilities across distinct technical domains. Each dimension carries divergent compliance burdens and capital intensity thresholds that reshape competitive positioning.
Product Type:
Mature formats dominate volume while emerging configurations capture reformulation-driven demand shifts.
- Aluminum Cans:Drawn and ironed from aluminum sheet with interior epoxy phenolic lacquer systems, these containers achieve sub-13 gram lightweighting targets for beverage applications. Bavarian craft breweries and North Rhine-Westphalia carbonated drink bottlers drive procurement concentration as VerpackG recyclability thresholds favor magnetically separable recovery streams.
- Tinplate Cans:Three-piece welded construction from electrolytic tinplate with sulfur-resistant enamel coatings protects oxygen-sensitive food contents. Stuttgart's industrial food processing belt and Hamburg's port logistics cluster anchor demand for corrosion-resistant vegetable and fish preservation formats.
- Steel Drums:Cold rolled steel shells with triple-seam closures and interior phenolic linings serve chemical logistics. KBA vehicle-type approval standards indirectly shape specifications for automotive coatings and lubricants distribution.
- Aerosol Cans:Tinplate or aluminum monobloc construction with internal epoxy coatings and crimped valve assemblies. EU F-Gas Regulation constraints on hydrofluorocarbon propellants force continuous reformulation investments from personal care manufacturers.
- Aluminum Foil Containers:Semi-rigid formed trays for ready-meal and takeaway applications. Food-contact safety specifications limit post-consumer recycled content integration, constraining closed-loop economics.
Tinplate Cans retain volume leadership; Aluminum Cans hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity steel inputs from premium aluminum and specialty alloys with divergent energy intensity profiles.
- Aluminum Sheet:3xxx and 5xxx series alloys optimized for deep drawability and corrosion resistance. Primary aluminum price volatility strains converter margin structures, particularly for beverage can specialists with limited pass-through mechanisms.
- Electrolytic Tinplate:Low-carbon steel with tin electrodeposition and chromium passivation layers. Dependence on integrated Ruhr region steel mill complexes elevates vulnerability to energy cost shocks and production curtailments.
- Cold Rolled Steel:Annealed and temper-rolled sheet for drum and pail fabrication. Automotive belt chemical suppliers specify KBA-compliant gauges for coatings and lubricants logistics.
- Stainless Steel:Austenitic grades for aggressive chemical and pharmaceutical containment. Premium pricing reflects nickel content and electropolished surface finishes.
- Galvanized Steel:Zinc-coated substrates for outdoor storage and construction-adjacent packaging. Lower unit economics serve price-sensitive industrial segments.
Electrolytic Tinplate commands the largest installed base; Aluminum Sheet is expanding most quickly.
Application:
Volume concentration in beverage and food channels contrasts with margin capture in technical specialty segments.
- Beverages:Carbonated soft drinks, beer, and energy drinks in aluminum and tinplate formats. Hamburg's port logistics cluster concentrates procurement decisions among three to four major brewers with annual commitments exceeding five hundred million units.
- Foodstuff:Preserved vegetables, fish, meat, and ready-meals in tinplate and foil containers. Stuttgart's chocolate and luxury food processors specify high-definition lithography for shelf differentiation.
- Chemicals:Industrial coatings, lubricants, and agricultural formulations in steel drums and pails. KBA standards create captive demand from automotive belt suppliers.
- Paints & Coatings:Architectural and industrial finishes in lever-lid cans and pails. Solvent compatibility requirements drive specialized interior lacquer formulations.
- Personal Care:Deodorants, hairsprays, and shaving foams in aerosol formats. EU F-Gas Regulation limits hydrofluorocarbon propellant choices, requiring continuous reformulation.
Beverages retain volume leadership; Personal Care holds the steepest margin curve.
End User:
Customer type segmentation maps procurement scale against technical specification complexity.
- Food & Beverage Manufacturers:Multinational brewers, dairy processors, and preserved food specialists. Consolidated procurement compresses supplier rosters and extends contract durations for surviving converters.
- Chemical Producers:Coatings, lubricants, and agricultural chemical suppliers. KBA vehicle-type approval standards shape steel drum specifications for automotive logistics.
- Cosmetic Companies:Personal care and fragrance houses with aerosol and specialty tinplate requirements. Smaller batch complexity supports higher margin pools than commodity beverage formats.
- Pharmaceutical Firms:Drug and medical device packaging with stringent barrier specifications. Stainless steel and specialized tinplate formats serve sterile containment needs.
- Paints Manufacturers:Architectural and industrial coatings suppliers. Solvent resistance specifications drive electrocoating chemistry expertise requirements.
Food & Beverage Manufacturers retain volume leadership; Cosmetic Companies hold the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's metal packaging sector maintains a modest export surplus in tinplate containers while importing aluminum sheet from Nordic smelters. Regional demand patterns concentrate in industrial corridors where beverage and food processing clusters anchor procurement volumes.
North Rhine-Westphalia
Carbonated drink bottlers and industrial chemical suppliers drive drum and can demand across the Ruhr industrial belt. VerpackG extended producer responsibility rules force converters toward closed-loop aluminum systems with measurable recycling performance. Düsseldorf and Cologne host dense procurement pools where annual volume commitments exceed five hundred million units for surviving suppliers.
Bavaria
Craft breweries in Munich and Nuremberg specify lightweight aluminum cans for seasonal releases below fifty thousand units. KBA vehicle-type approval standards shape steel drum specifications for automotive coatings logistics serving BMW and Audi supply chains. Ingolstadt's chemical processing corridor generates captive demand for corrosion-resistant container formats.
Baden-Württemberg
Stuttgart's chocolate and luxury food processors specify high-definition lithography on specialty tinplate for shelf differentiation. The state's precision engineering culture elevates technical specifications for electrocoating chemistry in high-acid food compatibility. Heidelberg and Mannheim anchor pharmaceutical metal packaging demand with stringent barrier requirements.
Hamburg
Port logistics clusters concentrate preserved fish and vegetable processing demand for corrosion-resistant three-piece welded cans. EU F-Gas Regulation constraints on hydrofluorocarbon propellants complicate aerosol formulations for personal care manufacturers based in the metropolitan region. Blankenese and Harburg harbor districts facilitate raw material imports for regional converter operations.
Lower Saxony
Agricultural chemical suppliers in Hanover and Braunschweig specify KBA-compliant steel drums for coatings and lubricants distribution. The state's food processing belt around Oldenburg generates steady demand for tinplate vegetable preservation formats. Wolfsburg's automotive presence indirectly shapes container specifications through chemical logistics requirements.
Germany Metal Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around beverage can specialists with multinational scale and diversified converters spanning food and aerosol formats. Three strategic archetypes dominate: aluminum beverage can specialists with annual commitments exceeding five hundred million units, diversified tinplate converters serving food and personal care segments, and regional fabricators capturing craft beverage short-run demand. Competitive moves center on digital printing retooling for sub-fifty-thousand-unit runs and closed-loop aluminum sorting infrastructure investments ahead of pending EU Packaging and Packaging Waste Regulation revisions.
Within the diversified converter tier, Silgan Holdings Inc. and Trivium Packaging B.V. exemplify portfolio breadth across multiple metal packaging formats. Ball Corporation anchors the beverage can specialization archetype with Ruhr region supply relationships. KLANN Packaging GmbH and HUBER Packaging Group GmbH occupy positions among German-based fabricators serving regional industrial demand. These five entities collectively represent the competitive spectrum from multinational scale to sub-regional procurement concentration.
| Leading Market Players |
|---|
| LK-PremiumPack GmbH |
| Silgan Holdings Inc. |
| Ball Corporation |
| Trivium Packaging B.V. |
| KLANN Packaging GmbH |
| Ardagh Metal Packaging S.A. |
| HUBER Packaging Group GmbH |
| Muller und Bauer GmbH & Co KG |
| Crown Holdings Inc. |
| Others |
Supply & Pricing Matrix
Ruhr region steel mill concentration determines both pricing tier spreads and supply chain shape across German metal packaging. VerpackG compliance costs and primary aluminum volatility compress margins for beverage can specialists while elevating premiums for closed-loop certified converters.
Pricing Analysis
Digital-native versus legacy lithography pricing gaps separate craft beverage short-run premiums from mass-market commodity tiers. Three-tier pricing structure across premium, standard, and economy levels captures differentiation by volume scale and decoration complexity. Cost compression in standard-grade tinplate is intensifying because energy cost pass-through from Ruhr integrated mills remains incomplete. Multinational brewers with five-hundred-million-unit commitments exhibit lowest price sensitivity; regional fabricators serving sub-fifty-thousand-unit craft runs face acute margin pressure.
Supply Chain Analysis
Extended payment terms from Hamburg port logistics clusters now reach ninety days for regional tinplate converters. Primary aluminum draws from Norwegian and Icelandic smelters; electrolytic tinplate rests on Ruhr region integrated steel complexes; cold rolled steel sources from German and Polish rolling mills. Single-source vulnerability concentrates in Ruhr tinplate electrodeposition capacity. Distribution runs through converter direct-to-brewery contracts and chemical distributor networks for drum formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German metal packaging sits in a cyclical recovery phase driven by beverage industry restocking and VerpackG-driven equipment replacement cycles.
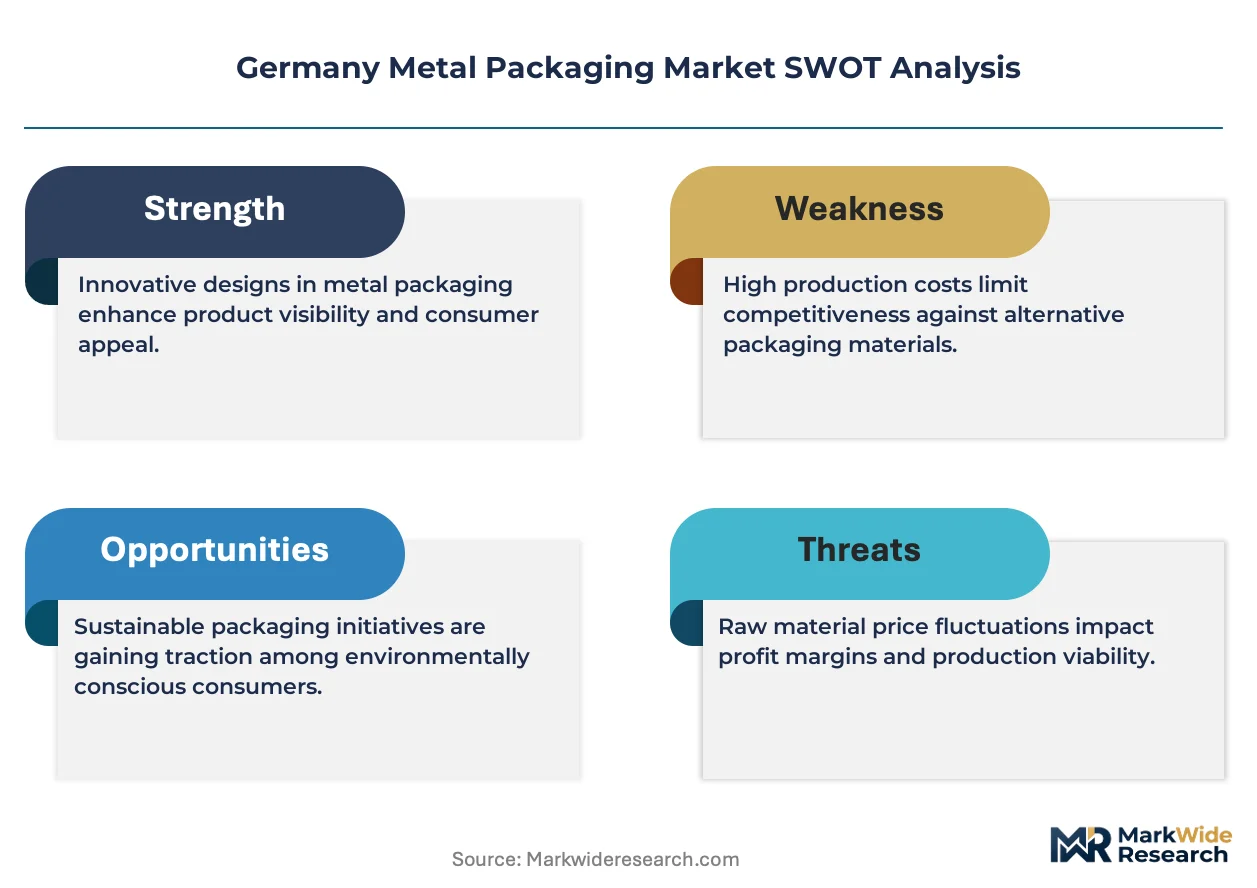
For Market Incumbents: Pre-empt digital print disruption by retooling Düsseldorf and Cologne lines for sub-fifty-thousand-unit runs before craft brewery procurement shifts entirely to regional fabricators. Backward integration into closed-loop aluminum sorting infrastructure defends margin position against pending EU Packaging and Packaging Waste Regulation recycled content mandates. Capacity consolidation in Bavaria captures Ingolstadt automotive coatings logistics demand. For New Entrants and Emerging Players: Mid-market confectionery processors in Stuttgart seeking high-definition lithography for shelf differentiation represent the most penetrable entry point for specialty tinplate converters. North Rhine-Westphalia chemical distributors requiring KBA-compliant steel drums for automotive logistics offer second white-space anchor. Go-to-market execution partners with established VerpackG registration consultants to compress fourteen-month certification timelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified converters with food and aerosol format breadth over pure-play beverage can specialists. Long-term viability across the next decade hinges on closed-loop aluminum infrastructure ownership and digital print capability. Monitor EU Packaging and Packaging Waste Regulation final recycled content thresholds as the critical inflection signal for tinplate versus aluminum competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Print Line Retrofit | Enables economical sub-fifty-thousand-unit runs for Bavarian craft breweries. |
| Closed-Loop Aluminum Sorting Investment | Secures VerpackG compliance ahead of EU Packaging and Packaging Waste Regulation thresholds. |
| Backward Integration into Lacquer Formulation | Captures electrocoating chemistry expertise scarce from German technical universities. |
| Regional Fabricator Acquisition | Consolidates craft beverage procurement relationships in North Rhine-Westphalia. |
| KBA-Compliant Drum Capacity Expansion | Serves automotive coatings logistics from Wolfsburg and Ingolstadt supply chains. |
Research Methodology
Operator-level perspectives from converter plant managers, brewer procurement directors, chemical distributor logistics heads, and VerpackG compliance consultants anchored the qualitative base. Primary interviews combined with secondary validation from German Federal Environment Agency filings, EU F-Gas Regulation implementation reports, KBA vehicle-type approval documentation, and dual system operator recyclability data. Bottom-up volume triangulation across aluminum can, tinplate can, steel drum, and aerosol format production lines cross-checked against top-down value estimates from converter revenue disclosures.
Scenario-bracketing around VerpackG enforcement intensity and EU Packaging and Packaging Waste Regulation final provisions shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, application end-use, and regional production cluster. CAGRs derived from volume-weighted average growth across format-specific demand drivers with aluminum lightweighting adoption curves and tinplate food can stability assumptions as core inputs.
Macroeconomic conditions sit as an overlay; deviation in energy cost trajectories for Ruhr steel mills or primary aluminum LME pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation timelines and recycling infrastructure deployment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
Tin Cans Market
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
Collapsible Aluminium Tube Market
Metal Packaging
Indonesia Metal Packaging Market
Metal Packaging
Bi-Metal Cans Market
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
Egypt Metal Packaging Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
Vietnam Metal Can Packaging Market
Metal Packaging
Beverage Metal Cans Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
Aluminum Foil Market
Metal Packaging
Global Laminated Aluminium Foil Market
Metal Packaging
Asia-Pacific Metal Packaging Market
Metal Packaging
Europe Food Cans Market