
 Italy Metal Packaging Market | 2026-2036
Italy Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Metal Packaging Market Foresight
Market Context with Strategic Players
Italy's own manufacturing base is reshaping competitive dynamics in European metal packaging. Ardagh Metal Packaging Italy S.r.l. anchors its position through extensive beverage can production serving domestic brewers and soft drink bottlers. Silgan Holdings Inc. leverages its scale in closures and specialty containers to serve multinational food brands operating from Italian plants. Tecnocap S.p.A. specializes in metal caps and closures, sustaining R&D intensity in lug cap designs for preserved foods.
Technical Definition and Structural Segments
Italy Metal Packaging encompasses rigid and semi-rigid containers fabricated from aluminum, steel, tinplate, or brass alloys, typically formed through deep drawing, two-piece drawing and ironing, or three-piece welding and seaming processes, engineered to provide hermetic sealing, mechanical protection, and extended shelf stability for consumer and industrial goods. Cans dominate product type demand, driven by beverage carbonation retention requirements and food sterilization compatibility, while containers capture premium positioning in olive oil and specialty food segments. Aluminum leads material consumption due to lightweighting advantages and established recycling infrastructure, though tinplate retains share in corrosion-sensitive food applications where barrier performance commands priority.
Regulatory Frame and Forward-Looking Close
Italy's metal packaging sector operates under EU REACH chemical safety standards, the EU Green Deal's circular economy action plan, and national transpositions of the Packaging and Packaging Waste Directive, all of which mandate minimum recycled content thresholds and extended producer responsibility schemes that directly influence material sourcing decisions and design specifications. BIS-equivalent Italian standardization through UNI norms further governs food contact material compliance, creating a dual-layer compliance architecture that shapes product development cycles and market access conditions. Stakeholders must monitor how forthcoming EU-wide packaging waste reduction targets will alter minimum unit weights and recyclability design standards before committing to capacity investments.
Market Dynamics
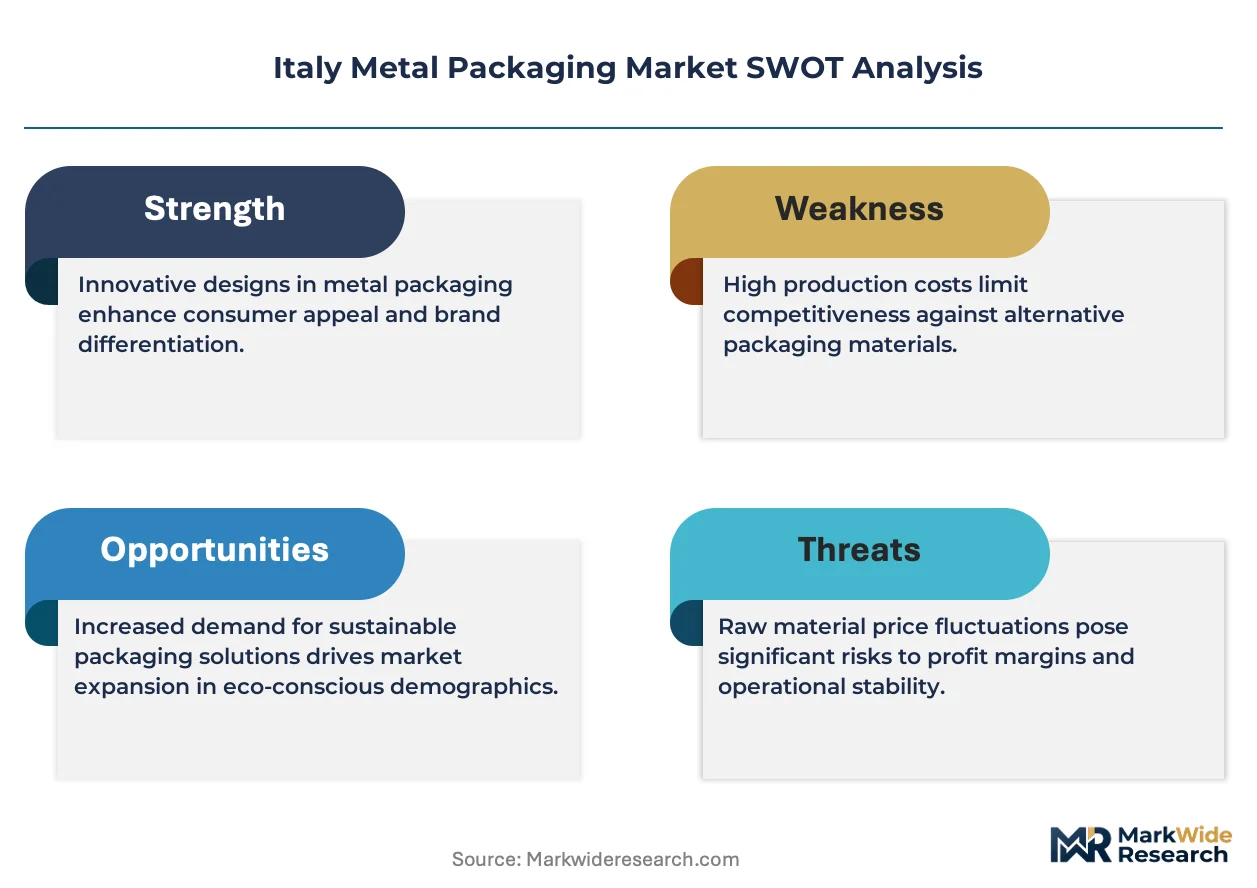
Italy's metal packaging sector faces acute pressure from the EU Packaging and Packaging Waste Regulation's tightening recycled content mandates, forcing converters to reengineer alloy specifications and supplier relationships simultaneously.
Growth Catalysts
- EU Green Deal circular economy mandates:Mandatory recycled aluminum thresholds in beverage cans are pulling investment into domestic sorting and remelting capacity across Lombardy and Emilia-Romagna.
- Shelf-stable food processors:Italian preserved tomato and legume exporters are expanding tinplate container orders to secure supply chain resilience against glass and plastic volatility.
- Two-piece drawing and ironing:This manufacturing process is capturing share from three-piece welded formats in carbonated soft drinks due to material efficiency and line-speed advantages.
Market Restraints
- Aluminum ingot price volatility:LME price swings above 15% annually compress converter margins and complicate long-term contract pricing with beverage bottlers.
- Tinplate supply concentration:European steel mill consolidation leaves Italian canmakers dependent on a narrowing supplier base in Germany and the Netherlands for corrosion-resistant substrates.
- Flexible pouch substitution:Retortable multilayer films are displacing metal cans in single-serve pet food and ready-meal segments where microwave convenience commands priority.
Strategic Opportunities
- Southern Italy underpenetration:Campania and Sicily food processors show 40% lower metal packaging intensity than northern counterparts, creating white space for regional logistics optimization.
- Aerosol personal care convergence:Aluminum bottle-necker technology is hybridizing with traditional three-piece tinplate construction for cosmetic and pharmaceutical spray applications.
- Extended producer responsibility credits:Italy's CONAI packaging consortium is introducing bonus-malus mechanisms that reward higher recycled content with reduced compliance fees.
Industry Challenges
- Deep-die toolmaking expertise gap:Retirement waves among specialized press technicians in Bologna's industrial belt are delaying new product qualification timelines.
- UNI food contact recertification:Updated migration testing protocols for epoxy-phenolic lacquers are extending approval cycles from 12 to 18 months for reformulated interior coatings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Metal Packaging Market |
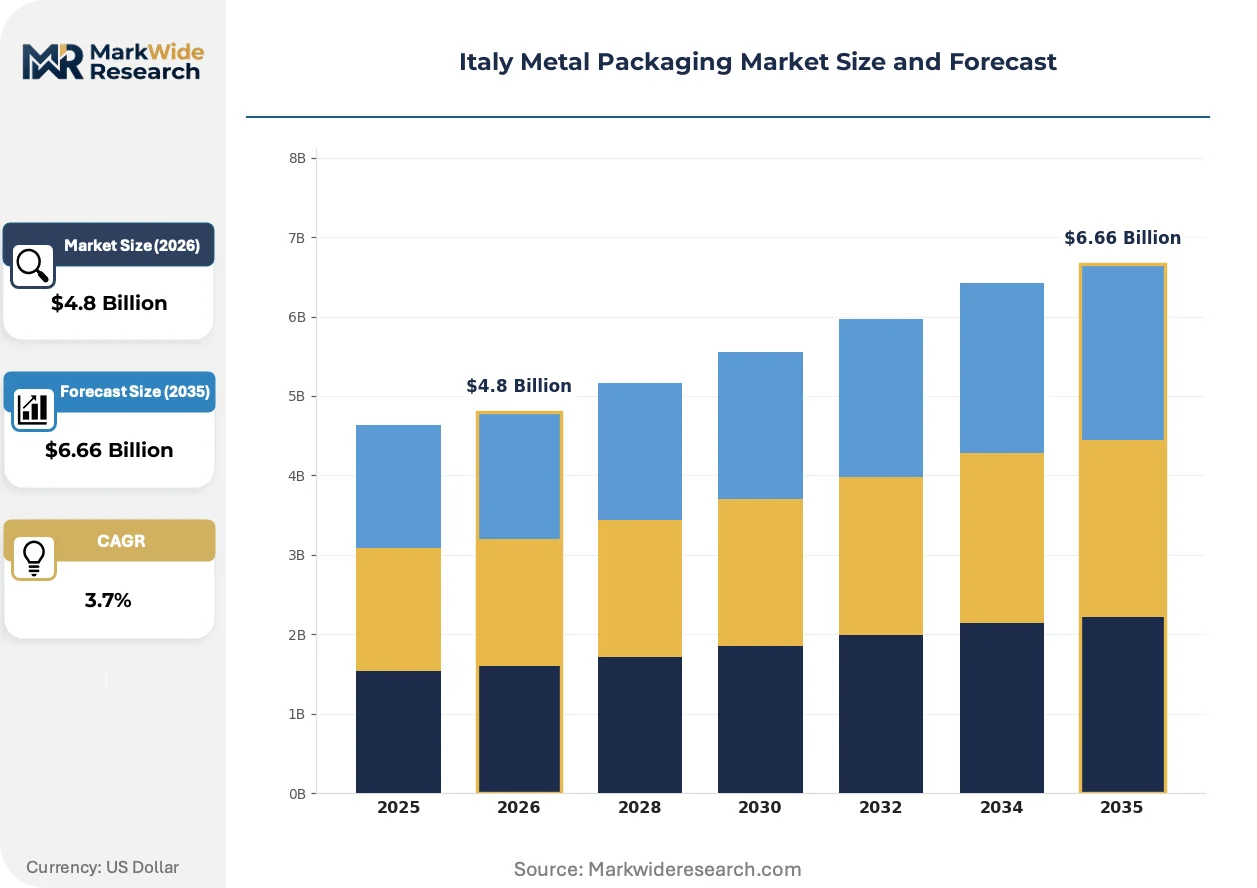
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cans, Containers, Lids, Foils End Use Industry: Food & Beverage, Personal Care, Pharmaceuticals, Chemicals Material: Aluminum, Steel, Tinplate, Brass Form: Rigid, Flexible, Composite, Others |
| Companies Covered | Gruppo ASA S.p.A., Silgan Holdings Inc., Ardagh Metal Packaging Italy S.r.l., Nespak S.p.A., Trivium Packaging Italy S.p.A., Ball Beverage Packaging Italia S.r.l., Tecnocap S.p.A., Massilly Italia S.r.l., Crown Packaging Manufacturing UK Limited – Italian Operations, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Metal Packaging Market Shifts & Advancements
Material science advances and regulatory compression are forcing Italian converters to rethink alloy-lacquer combinations and manufacturing footprints simultaneously.
Digital printing on metal substrates is hybridizing decoration workflows across Italian beverage and specialty food segments. Ardagh and Crown Holdings pilot facilities near Milan are retrofitting UV-cured inkjet lines alongside traditional offset coating stations. This convergence is compressing minimum order quantities from 50,000 to 5,000 units and enabling seasonal promotional runs that were economically unviable under cylinder-based systems.
REACH authorization requirements for chromium VI in tinplate passivation layers are accelerating conversion to trivalent chromium and chrome-free alternatives. ECHA's sunset date enforcement is forcing Italian steel drum and food can manufacturers to qualify new surface treatments with pasta sauce and olive oil packers. Smaller regional converters in Piedmont are pooling testing costs through industry associations to manage compliance burden.
Consolidated procurement by multinational beverage brands is compressing supplier rosters and extending contract durations. Heineken and Coca-Cola bottling partners in Italy are shifting from spot purchasing to three-year framework agreements with volume guarantees and indexed aluminum pricing. This concentration is visible most acutely in the Po Valley corridor, where four brewers now represent 60% of two-piece can demand and are demanding dedicated line capacity commitments.
Italy Metal Packaging Market Segmentation
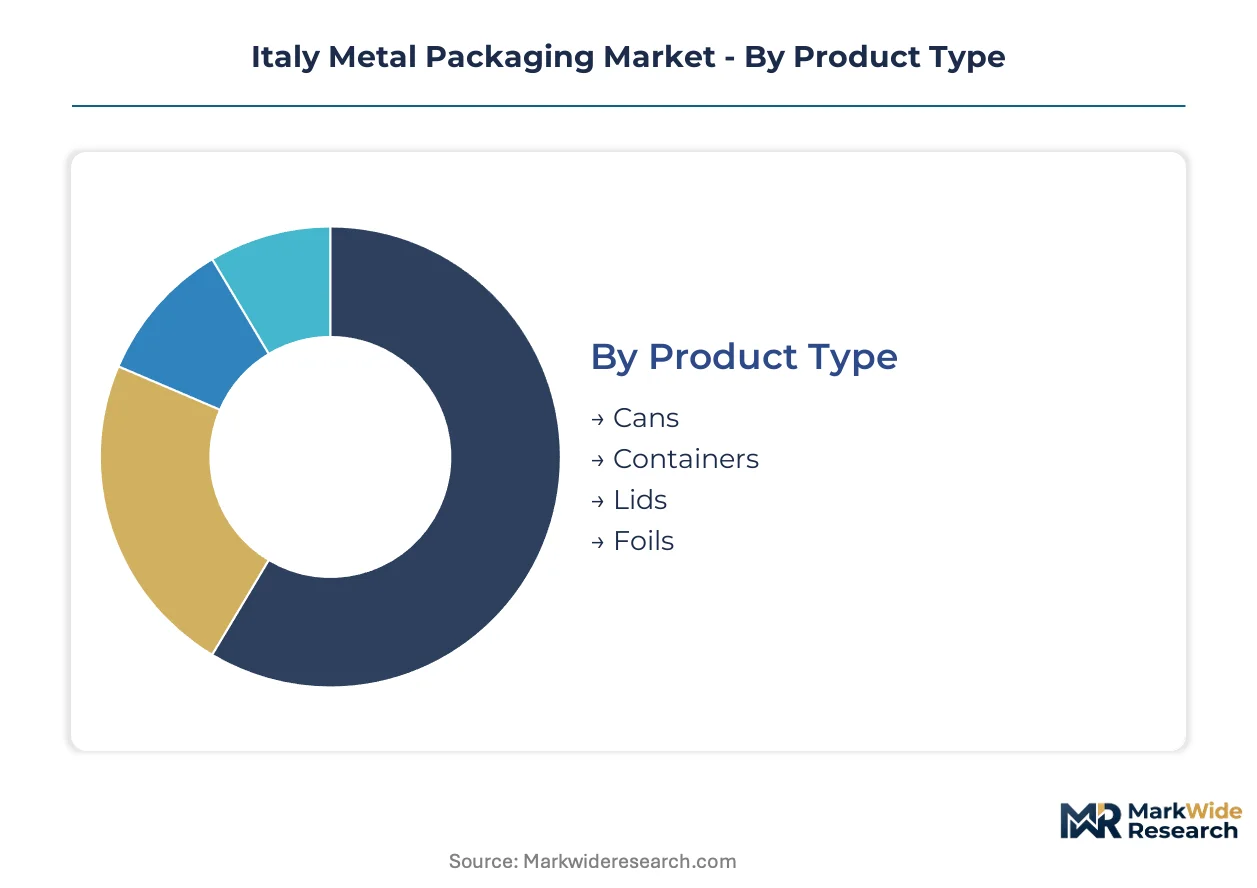
Segmentation in Italy's metal packaging market reveals how converter capacity, alloy sourcing, and end-use specifications interlock. Each dimension carries distinct procurement rhythms and margin structures that shape investment decisions across Lombardy and Emilia-Romagna.
Product Type:
Cans turn inventory fastest at beverage bottlers, while specialty containers sit longer with preserved food exporters negotiating seasonal contracts.
- Cans:Two-piece aluminum beverage cans dominate unit volumes through deep drawing and ironing processes optimized for carbonation retention. Milan and Bologna bottlers pull weekly replenishment cycles for beer and soft drink brands. Cans anchor the volume base while containers gain share at the steepest rate.
- Containers:Three-piece welded tinplate construction serves sterilized tomato paste, legume, and olive oil packers with hermetic sealing requirements. Emilia-Romagna food processors specify epoxy-phenolic interior coatings for acid food compatibility.
- Lids:Metal closures for glass jars and composite cans range from lug caps for pasta sauces to pry-off lids for craft beer.
- Foils:Aluminum foil laminations and formed trays serve chocolate, dairy, and ready-meal segments with barrier flexibility.
Containers command the longest production lead times due to custom tooling, while cans operate on near-continuous press schedules.
End Use Industry:
Cost tiers separate commodity beverage contracts from pharmaceutical validation requirements that absorb compliance overhead.
- Food & Beverage:Processed tomato, legume, and olive oil exporters in Parma and Modena drive tinplate demand for shelf-stable formats. EU Green Deal recycled content mandates are pulling aluminum can investment.
- Personal Care:Aerosol deodorant and hair spray brands specify aluminum bottle-necker hybrids or tinplate three-piece construction for propellant compatibility.
- Pharmaceuticals:Metal tubes and strip packs for ointments and unit-dose medications require UNI food contact migration testing and ECHA REACH compliance for interior lacquers.
- Chemicals:Steel drums and pails for coatings, solvents, and agrochemicals prioritize UN dangerous goods certification over decorative specifications.
Food and beverage absorbs the highest absolute tonnage while personal care aerosols climb fastest on premium positioning.
Material:
Supply concentration varies sharply: aluminum recycling loops through domestic Lombardy remelters, while tinplate depends on German and Dutch steel mill consolidation.
- Aluminum:Lightweight beverage can bodies and ends dominate consumption, supported by CONAI extended producer responsibility credits for post-consumer scrap content.
- Steel:General line drums and pails for industrial chemicals use cold-rolled carbon steel with exterior phenolic protection.
- Tinplate:Tin-coated steel provides corrosion resistance for acidic foods where barrier performance outweighs lightweighting priorities.
- Brass:Niche applications in cosmetic closures and specialty aerosol valves exploit machinability and corrosion resistance.
Aluminum holds the widest application span while tinplate defends share in corrosion-sensitive food formats.
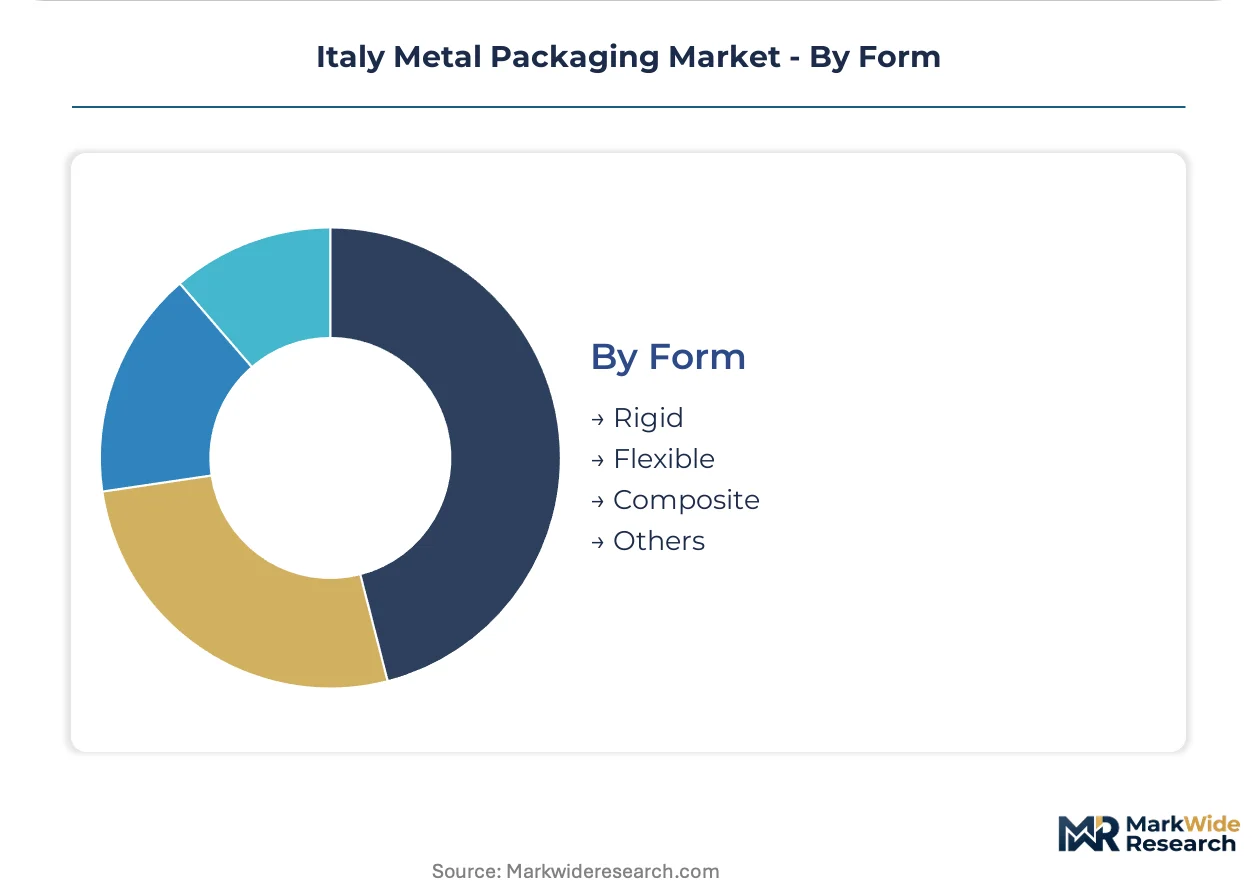
Form:
Customer type splits between high-volume beverage brands demanding rigid format consistency and flexible food processors experimenting with hybrid structures.
- Rigid:Deep-drawn and welded cans, drums, and containers provide structural integrity for carbonated beverages and hazardous chemicals.
- Flexible:Aluminum foil laminations and peelable lidding materials compete with retortable films in single-serve segments.
- Composite:Paperboard-metal-plastic hybrids for dry foods and snacks balance barrier performance with sustainability signaling.
- Others:Semi-rigid formed trays and specialty shapes for premium confectionery and gift packaging.
Rigid formats command the production footprint while composite structures expand most quickly on sustainability positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metal packaging consumption across Italy diverges sharply between the industrialized north and the agricultural south, with northern regions driving beverage can demand while southern processors favor tinplate containers for shelf-stable food exports.
Lombardy
Milan anchors beverage can demand through carbonated soft drink and beer bottling clusters, with two-piece aluminum lines running near-continuous press schedules. EU Green Deal recycled content mandates are pulling investment into domestic aluminum remelting capacity around Brescia. The Po Valley corridor concentrates procurement power among four major brewers representing the majority of regional can offtake.
Emilia-Romagna
Parma and Modena food processors drive tinplate container orders for sterilized tomato paste, legumes, and specialty exports to North African and Middle Eastern markets. ECHA REACH authorization requirements for chromium VI in passivation layers are accelerating conversion to trivalent alternatives among regional canmakers. Bologna's industrial belt hosts deep-die toolmaking expertise critical for new product qualification timelines.
Piedmont
Turin-based confectionery and chocolate manufacturers sustain demand for aluminum foil laminations and formed trays with barrier flexibility requirements. Smaller regional converters are pooling testing costs through industry associations to manage ECHA compliance burdens for reformulated interior coatings. The region's metal packaging intensity runs below Lombardy levels but above southern benchmarks.
Veneto
Verona and Vicenza wine bottlers are expanding metal closure adoption for sparkling and still wines, competing with traditional cork in premium segments. CONAI extended producer responsibility credits are rewarding post-consumer scrap content in aluminum lug caps. The region's logistics infrastructure supports just-in-time delivery to Adriatic port facilities for export-oriented producers.
Campania
Naples and Salerno food processors show metal packaging intensity roughly forty percent below northern counterparts, creating white space for regional logistics optimization. Preserved tomato and olive oil exporters are gradually shifting from glass to tinplate containers for supply chain resilience. Southern underpenetration reflects infrastructure gaps rather than demand absence, with converters exploring hub-and-spoke distribution models.
Italy Metal Packaging Market Competitive Landscape
Capability concentration sits with specialized closure and container fabricators; scale advantage sits with multinational beverage can producers with integrated European networks. The market structures around three tiers: global packaging conglomerates with dedicated Italian subsidiaries, mid-cap regional specialists with backward integration into toolmaking, and family-owned converters serving niche food contact segments. Dominant competitive moves include capacity commitments to beverage bottlers under multi-year framework agreements and collaborative testing pools to manage ECHA REACH compliance costs.
Among Italy-based specialists, Gruppo ASA S.p.A. and Tecnocap S.p.A. exemplify the mid-cap regional archetype with concentrated expertise in metal caps and closures for preserved foods. Ardagh Metal Packaging Italy S.r.l. anchors the multinational tier through extensive beverage can production serving domestic brewers and soft drink bottlers. These three occupy positions reflecting the market's bifurcation between scale-driven beverage packaging and capability-driven specialty containers.
| Leading Market Players |
|---|
| Gruppo ASA S.p.A. |
| Silgan Holdings Inc. |
| Ardagh Metal Packaging Italy S.r.l. |
| Nespak S.p.A. |
| Trivium Packaging Italy S.p.A. |
| Ball Beverage Packaging Italia S.r.l. |
| Tecnocap S.p.A. |
| Massilly Italia S.r.l. |
| Crown Packaging Manufacturing UK Limited – Italian Operations |
| Others |
Supply & Pricing Matrix
Overcapacity in Lombardy's aluminum remelting sector is compressing converter margins while simultaneously pulling beverage can pricing toward indexed long-term contracts that lock in volume commitments from Milan-based bottlers.
Pricing Analysis
Long-term offtake agreements dominate procurement between Italian canmakers and Po Valley beverage bottlers, replacing spot purchasing with three-year frameworks featuring aluminum LME-linked indexing and minimum volume guarantees. Price differentiation separates premium two-piece beverage cans with customized digital printing from standard tinplate food containers with conventional offset decoration. Pricing pressure stems from volatile aluminum ingot costs that squeeze converter margins when LME swings exceed fifteen percent annually. Small regional food processors in Campania exhibit the highest price sensitivity due to limited scale and infrastructure gaps, while multinational brewers in Lombardy prioritize supply security over unit cost.
Supply Chain Analysis
Export-control regimes on steelmaking technology limit European tinplate capacity expansion, constraining Italian canmakers to a narrowing supplier base concentrated in Germany and the Netherlands for corrosion-resistant substrates. Raw material dependencies center on primary aluminum ingots, tin-coated steel coils, and epoxy-phenolic lacquers for interior food contact coatings. Supply chain risk manifests as single-source vulnerability for tinplate given European steel mill consolidation and limited alternative corrosion-resistant substrate suppliers. Distribution runs through hub-and-spoke logistics networks radiating from Milan and Bologna industrial corridors, with southern Italy served through regional consolidation points in Naples.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's metal packaging sector is entering a cyclical recovery phase as EU Green Deal recycled content mandates trigger capital expenditure cycles across Lombardy and Emilia-Romagna processing corridors.
For Market Incumbents: Build switching-cost moats through dedicated line capacity commitments to major beverage bottlers under multi-year framework agreements with indexed pricing. Incumbents should deepen backward integration into aluminum remelting to secure post-consumer scrap supply chains against CONAI bonus-malus mechanisms. Threats from retortable flexible pouch substitution in single-serve segments demand accelerated R&D investment in hybrid composite formats that blend metal barrier performance with microwave convenience. For New Entrants and Emerging Players: Southern Italy's forty percent metal packaging intensity gap versus northern benchmarks offers white-space expansion for regional logistics optimization targeting Campania and Sicily food processors. New entrants should prioritize tinplate container supply to preserved tomato and olive oil exporters shifting from glass for supply chain resilience. A hub-and-spoke distribution model with consolidation points in Naples reduces capital requirements versus greenfield northern capacity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aluminum beverage can remelting as EU recycled content mandates require domestic sorting and secondary smelting investments. Long-term viability over the next decade hinges on positioning within circular economy infrastructure rather than commodity conversion margins. Acquisition targets should emphasize mid-cap regional specialists with captive toolmaking expertise in Bologna's industrial belt. The signal to watch is CONAI extended producer responsibility credit pricing, which will determine scrap feedstock economics.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Aluminum Remelting Capacity | EU Green Deal recycled content thresholds pull investment into Lombardy secondary smelting infrastructure. |
| Digital Printing Line Retrofit | UV-cured inkjet adoption near Milan compresses minimum order quantities from fifty thousand to five thousand units. |
| Trivalent Chromium Conversion | ECHA REACH sunset date enforcement accelerates qualification of chrome-free tinplate passivation alternatives. |
| Southern Hub-and-Spoke Distribution | Campania logistics optimization addresses forty percent metal packaging intensity underpenetration versus northern benchmarks. |
| Composite Format R&D Investment | Hybrid paperboard-metal-plastic development counters retortable film substitution in single-serve ready-meal segments. |
Research Methodology
The analysis maps beverage cans, food containers, metal closures, and industrial drums, each validated through converter plant managers, procurement leads at preserved food exporters, beverage bottler supply chain directors, and ECHA regulatory affairs specialists. Primary fieldwork combined structured interviews with secondary validation against EU Packaging and Packaging Waste Directive filings, CONAI extended producer responsibility reports, UNI food contact standard documentation, and Lombardy regional industrial census data. Bottom-up capacity assessments triangulated against top-down demand modeling from end-use industry consumption patterns.
Forecast assumptions held EU Green Deal recycled content mandates and ECHA REACH authorization timelines fixed while varying aluminum LME price trajectories and tinplate supply availability across the projection horizon. Segmentation modeling incorporated product type, material alloy specification, end-use industry, and regional production cluster dimensions. CAGRs derived from unit volume and value output convergence across demand-side and supply-side estimation approaches. Industry-specific inputs included beverage bottler capacity utilization rates and preserved food export contract seasonal patterns.
Practitioners should monitor EU Packaging and Packaging Waste Regulation enforcement timelines and aluminum scrap price spreads for early signals of forecast deviation. Material shifts in German and Dutch steel mill consolidation patterns or ECHA authorization sunset date delays would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
North America Metal Packaging Market
Metal Packaging
Pressurized Metal Containers Market
Metal Packaging
Metal Packaging Market
Metal Packaging
Bi-Metal Cans Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
Europe Food Cans Market
Metal Packaging
Metal Drums Market
Metal Packaging
Vietnam Metal Can Packaging Market
Metal Packaging
Aluminium Bottle Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
Thailand Metal Packaging Market
Metal Packaging
Global Metal Print Packaging Market
Metal Packaging
Germany Metal Packaging Market
Metal Packaging
Global Laminated Aluminium Foil Market
Metal Packaging
Middle East and Africa Food Cans Market
Metal Packaging
United Arab Emirates Metal Packaging Market