
 3-Piece Metal Cans Market | 2026-2036
3-Piece Metal Cans Market Size, Share, and Industry Trends Forecast 2026-2036
3-Piece Metal Cans Market Insights
Modular packaging configurations is shifting how buyers specify 3-piece metal cans, with food processors unbundling standard formats from premium specialty lines to match SKU proliferation. Crown Holdings leverages in-house steel sourcing to anchor its cost position across North American beverage accounts. Ardagh Group competes through decorated specialty can capacity in European craft beer markets. Silgan Holdings dominates the medium-capacity segment for shelf-stable food applications through integrated manufacturing scale.
3-piece metal cans consist of separate cylindrical bodies, bottom ends, and lid components joined through seaming or welding, typically manufactured from tinplate or chromium-coated steel with interior epoxy-phenolic coatings to prevent corrosion and flavor contamination. The construction permits high-pressure processing and extended shelf stability for thermally sterilized contents. Specialty cans and easy-open configurations are capturing margin pools as brand owners trade up from standard formats, while small-capacity induction-sealed designs are expanding fastest in pharmaceutical and personal care applications where tamper evidence commands premium positioning. Medium-capacity food cans remain the volume backbone but face substitution pressure from aluminum 2-piece alternatives in beverage end uses.
EPA guidelines on volatile organic compound emissions from can coating operations are tightening compliance costs for U.S. manufacturers, while REACH restrictions on bisphenol-A derivatives are reformulating interior coating specifications across European production lines. FDA food contact substance notifications govern epoxy-based coatings for domestic food can applications, creating divergence in approved material systems across jurisdictions. Stakeholders must monitor coating chemistry transitions and regional certification timelines to avoid supply discontinuities as regulatory thresholds tighten.
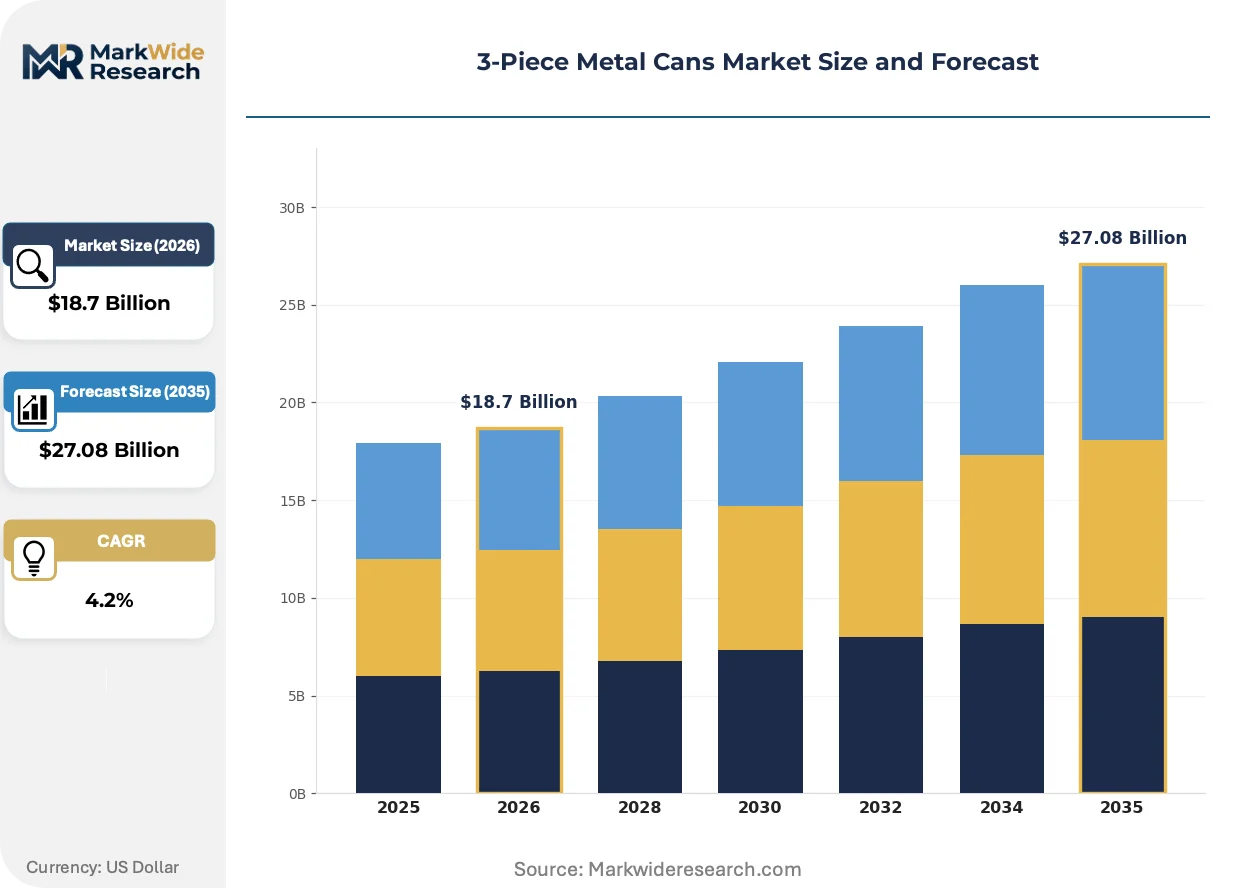
Market Dynamics
REACH restrictions on bisphenol-A derivatives and EPA volatile organic compound guidelines are forcing simultaneous coating chemistry transitions across European and North American production lines, compressing formulation certification timelines and tightening supplier qualification windows.
Growth Catalysts
- Southeast Asian Manufacturing Concentration:Vietnam and Thailand are attracting food and beverage processors expanding easy-open and specialty format procurement. These clusters offer integrated steel-tinplate supply chains and seaport logistics for export-oriented canning operations.
- F-Gas Regulation Compliance:Europe's fluorinated gas phase-down mandates are accelerating interior coating reformulation toward lower-emission curing systems. Can manufacturers investing in compliant lines secure preferential supplier status with pan-European food brands.
- Induction Sealing Technology:Pharmaceutical and personal care applications are adopting small-capacity induction-sealed 3-piece designs where tamper evidence commands premium positioning. This process innovation opens margin pools beyond traditional food and beverage end uses.
Market Restraints
- Tinplate Price Volatility:Raw material cost swings in electrolytic tinplate and chromium-coated steel directly compress manufacturer margins. Long-term supply agreements with integrated steel mills provide partial hedging but lock working capital.
- Aluminum 2-Piece Substitution:Beverage applications are migrating toward drawn-and-ironed aluminum cans that eliminate the side seam and reduce metal weight. This technical displacement threatens the volume backbone of medium-capacity 3-piece lines.
- Coating Certification Bottlenecks:FDA food contact substance notification timelines and EFSA re-evaluations of epoxy-phenolic systems create regulatory friction. Divergent approval schedules across jurisdictions fragment formulation standardization.
Strategic Opportunities
- Modular SKU Architecture:Food processors are unbundling standard formats from premium specialty lines to match retail SKU proliferation. Can suppliers offering configurable body-diameter and end-combination platforms capture specification share.
- Decorated Specialty Capacity:European craft beer markets are trading up from undecorated commodity cans to high-definition printed formats. Investments in dry-offset and digital decoration lines access margin premiums unavailable in standard beverage contracts.
- Pharmaceutical Compliance Tailwinds:FDA drug master file requirements for primary packaging materials are elevating documentation standards. 3-piece can manufacturers with established pharmaceutical-grade quality systems exploit barriers to entry against generalist competitors.
Industry Challenges
- Coating Chemistry Talent Scarcity:Formulation chemists with expertise in non-BPA epoxy alternatives and polyester-based interior coatings command premium compensation. Recruitment competition from adjacent packaging segments stretches technical staffing.
- Legacy Seaming Equipment Retrofit Costs:Welded side-seam lines require capital-intensive conversion to accommodate thinner-gauge steel substrates. Manufacturers face compressed payback periods against accelerating substrate specification changes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3-Piece Metal Cans Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cans, Specialty Cans, Induction Cans, Easy-Open Cans End Use Industry: Food & Beverage, Chemicals, Personal Care, Pharmaceuticals Capacity: Small (up to 250ml), Medium (251ml - 1000ml), Large (1001ml - 3000ml), Extra Large (3001ml and above) Manufacturing Stage: Raw Material Sourcing, Production, Printing, Quality Control |
| Companies Covered | Crown Holdings, Ardagh Group, Ball Corporation, CPMC Holdings Limited, CanPack, Silgan Holdings, Toyo Seikan Group Holdings, Can-One Berhad, Universal Can Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3-Piece Metal Cans Market Trends and Innovations
Digital printing and laser-based quality inspection are compressing changeover economics and defect detection thresholds. These technologies enable shorter production runs and tighter specification compliance demanded by brand owners managing proliferating SKUs.
Water-based interior coating systems are consolidating as the dominant alternative to solvent-borne epoxy-phenolic formulations in North American and European canning operations. Major food processors are mandating these systems in supplier qualification protocols to preempt regulatory liability. The transition is compressing formulation supplier margins while rewarding integrated coating manufacturers with captive resin production.
REACH Annex XVII restrictions on bisphenol-A in thermal paper and food contact materials are cascading into can coating specifications across EU member states. ECHA substance evaluation timelines are accelerating reformulation commitments ahead of formal authorization requirements. German and French canning lines are most affected, with coating suppliers front-loading certification investments to maintain supply continuity.
Brand owner specification teams are consolidating vendor relationships from multi-source commodity purchasing toward single-source partnership models for decorated specialty formats. This concentration transfers inventory risk to can manufacturers while securing dedicated capacity and design collaboration access. The shift is most visible in North American craft beverage and European premium pet food segments where packaging differentiation drives shelf positioning.
3-Piece Metal Cans Market Segmentation
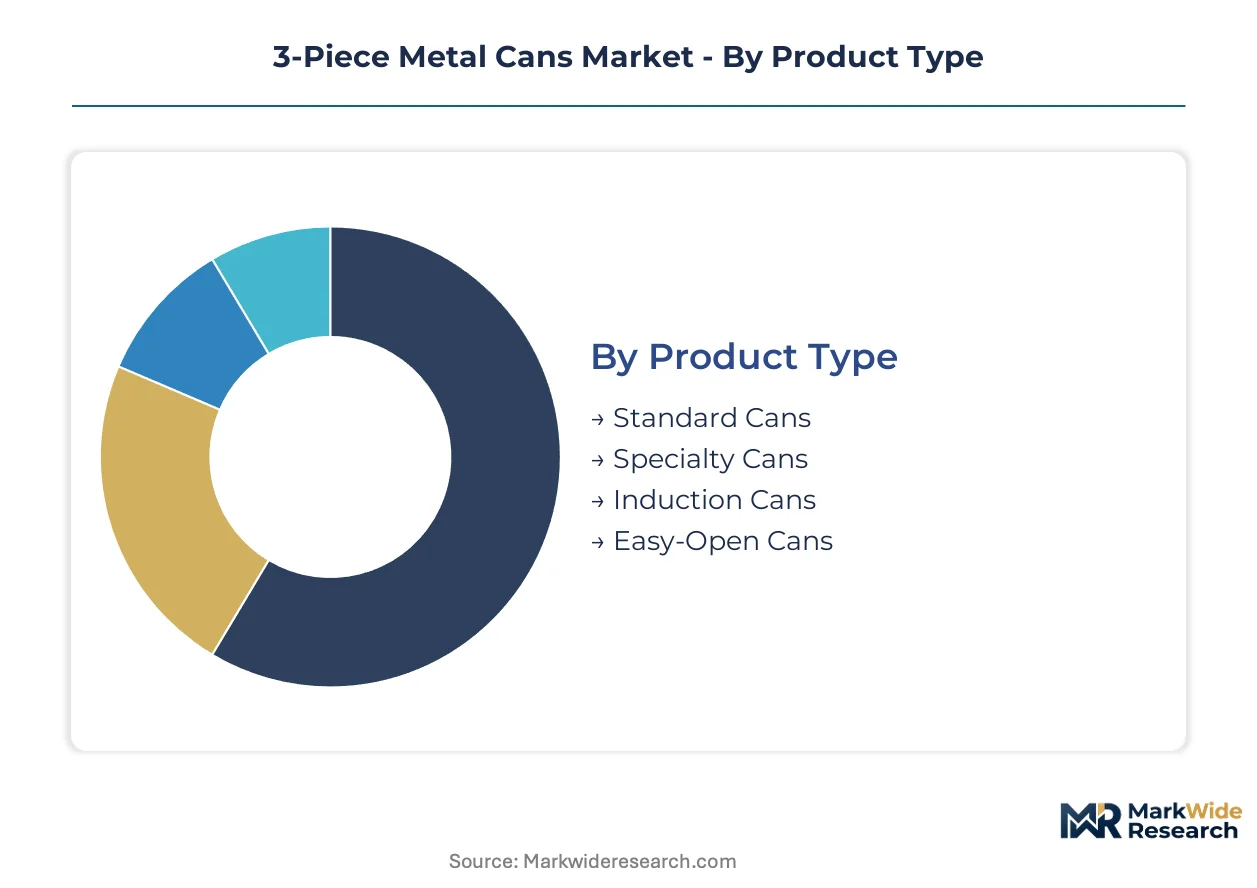
Segmentation in 3-piece metal cans reveals how procurement patterns split between commodity volume plays and premium specification tiers. Brand owners unbundle standard formats from specialty lines to match retail SKU proliferation, creating distinct margin pools across construction types.
Product Type:
Construction complexity separates standalone commodity formats from embedded premium systems requiring specialized seaming and coating protocols.
- Standard Cans:Basic cylindrical bodies with welded side seams and plain ends serve high-volume shelf-stable food applications. Vietnam and Thailand manufacturing clusters anchor procurement for export-oriented processors seeking cost-efficient thermal sterilization packaging.
- Specialty Cans:Custom body profiles, shaped ends, and enhanced decoration capabilities command premium positioning in European craft beer markets. Crown Holdings and Ardagh Group compete through dedicated specialty capacity investments that access margin pools unavailable in commodity contracts.
- Induction Cans:Small-capacity designs with hermetic foil sealing serve pharmaceutical and personal care applications where tamper evidence justifies premium pricing. FDA drug master file documentation requirements elevate supplier qualification barriers.
- Easy-Open Cans:Score-resist ends with integrated pull-tab mechanisms reduce consumer tool dependence for food and beverage access. Southeast Asian processors are expanding procurement of these formats to match convenience-oriented retail positioning.
Standard cans lead volumes today; specialty formats are gaining share fastest.
End Use Industry:
Application-driven cost tiers separate mass-market food packaging from regulated pharmaceutical and personal care systems requiring certified coating chemistries.
- Food & Beverage:Thermally processed shelf-stable products dominate volume, with epoxy-phenolic interior coatings preventing corrosion and flavor contamination. EPA volatile organic compound guidelines and REACH bisphenol-A restrictions are forcing simultaneous coating transitions across U.S. and European production lines.
- Chemicals:Industrial and agricultural chemical packaging demands enhanced corrosion resistance through specialized interior lining systems. Silgan Holdings targets this segment through medium-capacity integrated manufacturing scale.
- Personal Care:Aerosol and non-aerosol formats for cosmetics and household products require compatibility with propellant systems and fragrance compounds. Induction-sealed small-capacity designs are expanding fastest in this channel.
- Pharmaceuticals:Primary packaging for oral solid dose and topical applications demands FDA food contact substance notification compliance and drug master file documentation. Manufacturers with established pharmaceutical-grade quality systems exploit barriers to entry against generalist competitors.
Food and beverage anchors revenue today; pharmaceutical applications show the steepest expansion trajectory.
Capacity:
Volume bands align with distinct supply chain configurations, from precision small-batch pharmaceutical runs to high-speed food canning lines.
- Small (up to 250ml):Precision formats for single-serve beverages, pharmaceutical doses, and sample-size personal care products. Induction sealing technology penetration is highest in this band.
- Medium (251ml - 1000ml):The volume backbone for shelf-stable vegetables, soups, and ready meals. Faces substitution pressure from aluminum 2-piece alternatives in beverage end uses.
- Large (1001ml - 3000ml):Institutional and family-size food service packaging. Integrated steel-tinplate supply chains in Southeast Asian clusters support cost-competitive procurement.
- Extra Large (3001ml and above):Industrial chemical and bulk food ingredients requiring reinforced body construction and specialized end-seaming equipment.
Medium capacity dominates unit volumes today; small capacity is climbing the fastest.
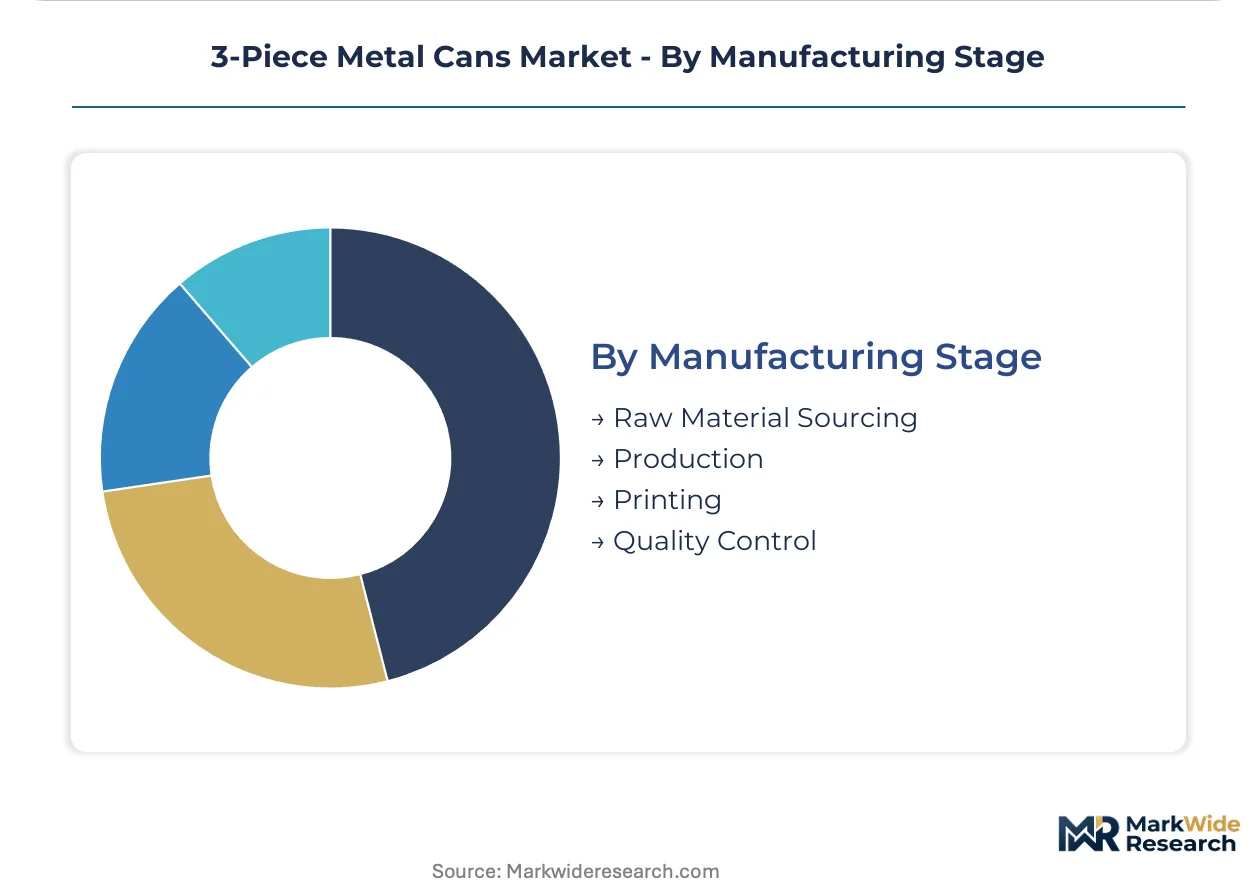
Manufacturing Stage:
Value capture potential concentrates in stages with proprietary technology or regulatory certification requirements.
- Raw Material Sourcing:Electrolytic tinplate and chromium-coated steel procurement with long-term mill agreements. Tinplate price volatility directly compresses manufacturer margins.
- Production:Body forming, welding, and seaming operations where legacy equipment retrofit costs complicate thinner-gauge steel adoption.
- Printing:Dry-offset and digital decoration lines enabling high-definition specialty formats. European craft beer markets trade up from undecorated commodity cans to access shelf differentiation.
- Quality Control:Laser-based inspection systems compressing defect detection thresholds. Digital quality systems enable shorter production runs demanded by SKU proliferation.
Production commands the largest cost share today; printing delivers the fastest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three-piece metal can manufacturing originated in Europe and North America during the early twentieth century, with industrial-scale production first achieving maturity in the United States and Germany before diffusing to Asia-Pacific manufacturing clusters.
United States
Food and beverage processors drive specification demand for easy-open and specialty formats across Midwestern canning corridors. EPA volatile organic compound guidelines tighten compliance costs for domestic coating operations. Chicago and Milwaukee manufacturing clusters anchor procurement relationships with shelf-stable food brands seeking thermal sterilization packaging.
Germany
REACH Annex XVII restrictions on bisphenol-A derivatives accelerate interior coating reformulation across Rhineland production lines. ECHA substance evaluation timelines compress supplier qualification windows for epoxy-phenolic alternatives. Bavarian canning facilities front-load certification investments to maintain supply continuity with pan-European food brands.
Vietnam
Export-oriented food processors expand procurement of easy-open formats through integrated steel-tinplate supply chains. The country's national environmental regulations align with regional sustainability mandates for industrial manufacturing. Ho Chi Minh City and Binh Duong province manufacturing clusters offer seaport logistics for regional canning operations.
Thailand
Beverage and processed food sectors concentrate demand for medium-capacity shelf-stable packaging in Bangkok metropolitan manufacturing zones. The country's national industrial standards govern food contact material specifications for interior coating systems. Eastern Economic Corridor facilities attract foreign direct investment in decorated specialty can capacity.
Japan
Pharmaceutical and personal care applications adopt small-capacity induction-sealed designs where tamper evidence commands premium positioning. The country's national pharmaceutical regulator enforces drug master file documentation requirements for primary packaging materials. Kanto region manufacturing maintains precision quality systems for regulated end uses.
3-Piece Metal Cans Market Competitive Landscape
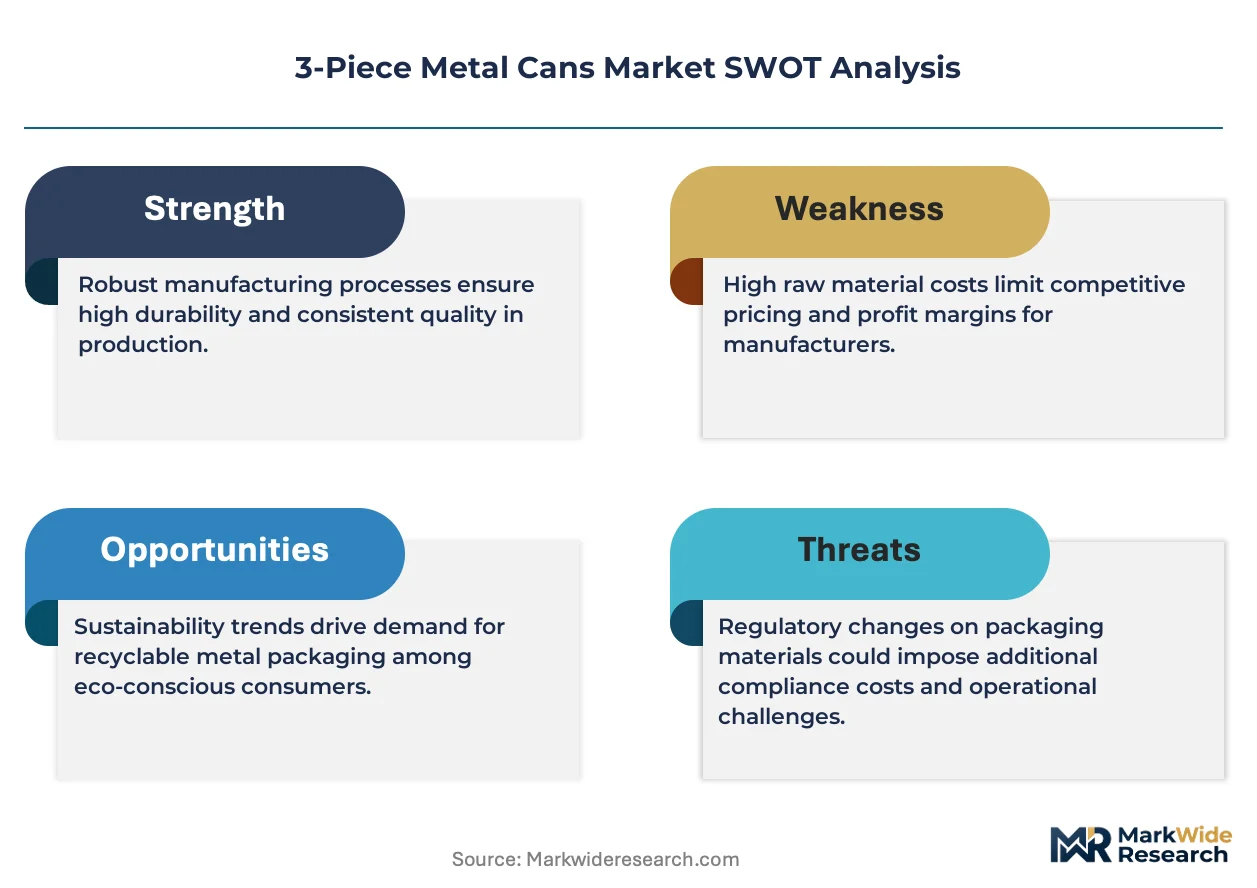
The competitive structure tilts toward integrated multinationals with captive steel supply and regional specialists with decorated specialty capacity. Crown Holdings, Ardagh Group, and Silgan Holdings anchor the consolidated tier alongside diversified packaging conglomerates. Three strategic archetypes dominate: steel-integrated volume players, specialty decoration specialists, and pharmaceutical-grade compliance leaders. Capacity expansion and coating chemistry certification represent the dominant competitive moves as regulatory timelines compress.
Among North American and European integrated manufacturers, Crown Holdings, Ardagh Group, and Silgan Holdings exemplify distinct positioning archetypes within the consolidated tier. Crown Holdings represents steel-integrated volume scale through backward control over raw material sourcing. Ardagh Group occupies a position as a specialty decoration specialist serving craft beverage differentiation requirements. Silgan Holdings anchors the medium-capacity food segment through manufacturing scale integration. These three entities collectively illustrate how competitive advantage fragments across supply chain control, technical specification capability, and regulatory compliance depth.
| Leading Market Players |
|---|
| Crown Holdings |
| Ardagh Group |
| Ball Corporation |
| CPMC Holdings Limited |
| CanPack |
| Silgan Holdings |
| Toyo Seikan Group Holdings |
| Can-One Berhad |
| Universal Can Corporation |
| Others |
Pricing and Supply Chain Analysis
Food and beverage processors with consolidated procurement volumes negotiate contract-based long-term offtake agreements that anchor pricing stability across medium-capacity standard can tiers. These anchor buyers shift pricing power toward manufacturers with backward integration into steel-tinplate sourcing, while specialty format purchasers absorb premium positioning costs for decorated and easy-open configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates decorated specialty cans from plain medium-capacity formats and commodity undecorated lines. Price differentiation rests on certification grade for pharmaceutical compliance and volume scale for food service contracts. Cost compression in standard beverage cans is intensifying because aluminum 2-piece substitution threatens volume backbones. Small pharmaceutical buyers exhibit highest price sensitivity to coating certification costs, while European craft brewers show lowest sensitivity for shelf-differentiation formats.
Supply Chain Analysis
Vietnam's national domestic-content mandates for industrial manufacturing are reshaping sourcing patterns across Southeast Asian steel-tinplate procurement. Supply concentrates in Vietnam, Thailand, and Germany, with raw material dependencies on electrolytic tinplate, chromium-coated steel, and epoxy-phenolic resin systems. Single-source vulnerability in European coating chemistry suppliers exposes manufacturers to REACH reformulation bottlenecks. Distribution runs through integrated mill-to-canplant direct delivery for volume accounts and regional warehousing for specialty format distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory coating transitions create recurring certification revenue streams for compliant manufacturers. Shelf-stable food demand and pharmaceutical packaging expansion provide durable volume foundations.
For Market Incumbents: Hedge tinplate price volatility through long-term mill agreements while accelerating water-based coating line conversion ahead of EPA volatile organic compound enforcement. Aluminum 2-piece substitution in beverage end uses threatens medium-capacity volume; defend position through specialty decoration capacity expansion in European craft beer corridors and pharmaceutical-grade quality system certification. For New Entrants and Emerging Players: Contract manufacturers serving regional food processors represent the most accessible channel partner type for market entry. Pharmaceutical and personal care induction-sealed formats offer the most penetrable white-space target given FDA drug master file barriers against generalist competitors. Pursue white-label supply agreements with Southeast Asian export-oriented processors seeking easy-open format diversification. For Investors and Strategic Acquirers: Steel-integrated packaging conglomerates are the most active acquirer in this space, seeking coating chemistry capabilities and regional manufacturing footprints. The five-to-ten-year viability window favors targets with established REACH-compliant formulation portfolios and Southeast Asian production assets. Watch ECHA substance evaluation timelines for bisphenol-A derivatives as the inflection signal for accelerated industry consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Certification Investment | REACH-compliant epoxy-phenolic alternatives secure preferential supplier status with pan-European food brands. |
| Backward Integration into Steel-Tinplate Sourcing | Captive mill relationships hedge raw material volatility and anchor cost position across North American beverage accounts. |
| Specialty Decoration Capacity Expansion | Dry-offset and digital printing lines access margin premiums in European craft beer shelf-differentiation markets. |
| Pharmaceutical-Grade Quality System Implementation | FDA drug master file documentation elevates barriers against generalist competitors in regulated packaging segments. |
| Southeast Asian Manufacturing Footprint Expansion | Ho Chi Minh City and Binh Duong province clusters offer integrated steel supply chains and seaport logistics for export-oriented canning. |
Research Methodology
Bottom-up food and beverage processor demand modeling reconciled against top-down steel-tinplate supply tracking forms the analytical core of this analysis. Primary interviews with coating formulation chemists, can manufacturing plant managers, food processor procurement directors, and pharmaceutical packaging engineers combined with secondary validation from EPA emission filings, ECHA substance evaluation databases, FDA food contact substance notifications, and customs trade records. Triangulation across these sources ensures demand estimates align with raw material flow data.
Historical trendline analysis of volume and value trajectories informs the projection framework across the modeling period. Segmentation dimensions include product construction type, end-use industry application, capacity band, and manufacturing stage value capture. CAGRs derive from fitted growth curves applied to disclosed production capacity expansions and regulatory-driven coating transition timelines. Forecast inputs incorporate tinplate price volatility assumptions and substitution elasticity estimates for aluminum 2-piece alternatives.
Revisions become necessary when REACH authorization requirements accelerate, EPA enforcement timelines shift, or Southeast Asian manufacturing cluster investments materially alter regional supply balances. Forecasts reflect documented assumptions about regulatory compliance schedules and raw material cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Food and Beverages Metal Can Market
Metal Packaging
Vietnam Metal Packaging Market
Metal Packaging
Europe Metal Closures Market
Metal Packaging
Converter Aluminum Foil Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
Metal Food Cans Market
Metal Packaging
Metal Cans Market
Metal Packaging
United States Metal Cans Market
Metal Packaging
Metal Containers Market
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
Latin America Metal Packaging Market
Metal Packaging
Middle East and Africa Food Cans Market
Metal Packaging
Saudi Arabia Metal Packaging Market
Metal Packaging
North America Metal Packaging Market
Metal Packaging
United Arab Emirates Metal Packaging Market
Metal Packaging
Two Piece Metal Containers Market