
 Nordic Solar Shades Market | 2026-2036
Nordic Solar Shades Market Size, Share, and Industry Trends Forecast 2026-2036
Nordic Solar Shades Market Intelligence
Multi-source procurement for motorization components is pivoting toward vertically integrated supply chains as Nordic installers seek shorter lead times. Hunter Douglas N.V. anchors its position through captive manufacturing of proprietary fabrics. Somfy Systems Inc. competes on actuator technology leadership across the residential channel. Renson Ventilation nv differentiates via climate-responsive facade integration that extends beyond basic shading.
Nordic solar shades are fenestration control systems engineered with optical performance coatings, typically achieving solar heat gain coefficients below 0.35 and visible light transmittance calibrated to latitude-specific angles, designed to modulate glare and thermal load in high-latitude buildings with extreme seasonal variation. Roller shades dominate volume through standardization in commercial fit-outs, while cellular shades command premium positioning in residential applications where thermal insulation features justify higher price points. Fabric materials sustain the largest share of specification activity, though aluminum gains ground in industrial and hospitality sectors demanding durability and fire resistance compliance.
EU Green Deal building renovation targets, CE marking under the Construction Products Regulation, and national energy codes in Denmark, Sweden, Norway, and Finland collectively mandate improved envelope performance that directly expands addressable demand for certified solar shading. ECHA REACH compliance for coated textiles and polymer components shapes material selection and supplier qualification protocols across the value chain. Stakeholders must monitor evolving national implementation timelines for the EU Energy Performance of Buildings Directive to align product development and channel investments with enforcement trajectories.
Market Dynamics
EU Green Deal building renovation targets are compressing specification timelines across Denmark, Sweden, Norway, and Finland, forcing installers to pre-certify shading systems before envelope retrofit contracts close.
Growth Catalysts
- EU Energy Performance of Buildings Directive:National implementation timelines in Denmark and Sweden mandate solar shading integration in commercial retrofits, expanding specification volumes for certified systems.
- Øresund corridor concentration:Copenhagen-Malmö cross-border office development generates synchronized demand for climate-responsive facade systems in high-performance buildings.
- Optical coating advances:Low-SHGC fabrics below 0.35 solar heat gain coefficient enable compliance with tightening envelope standards without daylight penalty.
Market Restraints
- Actuator supply concentration:Nordic installers depend on centralized European motorization suppliers, exposing projects to lead time volatility during peak retrofit seasons.
- REACH compliance costs:ECHA substance restrictions on coated textiles and polymer components force reformulation cycles that extend supplier qualification timelines.
- Seasonal installation windows:Extreme latitude weather compresses facade access periods, limiting annual contractor capacity and project throughput.
Strategic Opportunities
- Finnish residential underpenetration:Cellular shade adoption lags Danish and Swedish levels, creating white space for thermal insulation positioning in single-family construction.
- Climate-responsive facade convergence:Integration of solar shading with natural ventilation and automated lighting controls opens specification pathways beyond standalone shading.
- Norwegian hospitality expansion:Fjord-region tourism infrastructure investment drives demand for fire-rated aluminum systems in boutique hotel development.
Industry Challenges
- Certification timeline compression:CE marking under the Construction Products Regulation requires accelerated testing protocols to match retrofit procurement cycles.
- Facade integration complexity:Legacy building stock in Stockholm and Copenhagen presents structural constraints for motorized system retrofit without envelope modification.
- Specialized installer scarcity:Climate-responsive system commissioning demands cross-trained technicians proficient in both shading hardware and building automation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nordic Solar Shades Market |
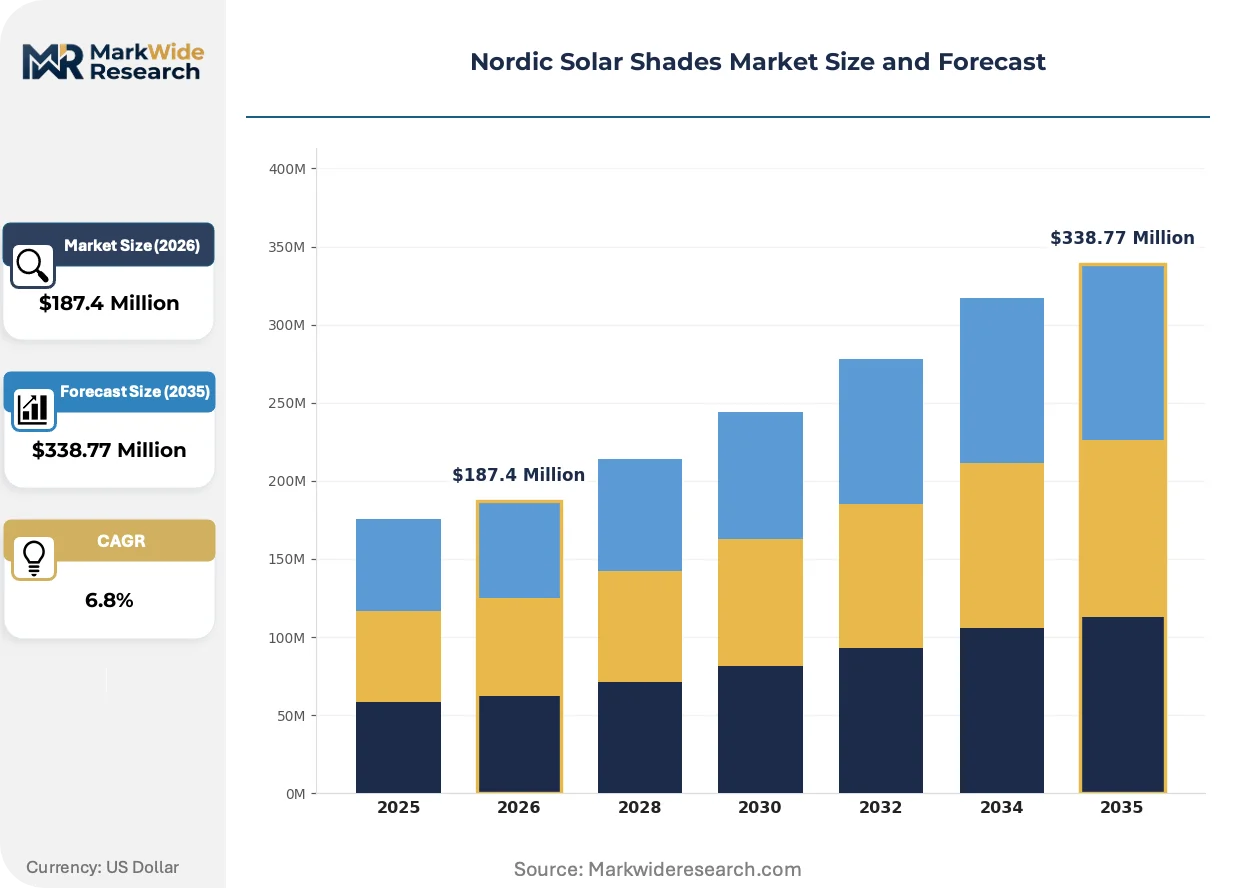
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Shades, Roman Shades, Panel Track Shades, Cellular Shades Material: Fabric, Vinyl, Wood, Aluminum Application: Residential, Commercial, Industrial, Hospitality Feature: Blackout, Light Filtering, Thermal Insulation, UV Protection |
| Companies Covered | LUTRON Electronics Co. Inc, Somfy Systems Inc, Hunter Douglas N.V, VELUX Group, Busch-Jaeger Elektro GmbH, Chamberlain Group Inc, Renson Ventilation nv, Gira Giersiepen GmbH & Co. KG, Griesser AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nordic Solar Shades Market Strategic Shifts & Innovations
Automation and material science are converging to redefine performance benchmarks across Nordic solar shading, with specification criteria shifting from static optical properties to dynamic, building-integrated responsiveness.
Electrochromic glazing is absorbing specification share from conventional roller systems in premium Copenhagen commercial developments. Asset managers prioritize real-time tint adjustment over fixed-fabric solutions. This capability is compressing the addressable market for basic motorized shades in Class A office retrofits.
EU Green Deal building renovation targets are tightening enforcement trajectories across member states. Denmark's national energy code now mandates solar shading in envelope upgrades exceeding threshold square footage. Commercial retrofit contractors are pre-qualifying integrated facade systems to accelerate compliance documentation.
Specification authority is migrating from general contractors to facade engineering consultants. Stockholm and Oslo projects now route shading decisions through envelope performance modelers rather than interior fit-out teams. This shift elevates thermal simulation credentials over traditional distributor relationships in vendor selection.
Nordic Solar Shades Market Segmentation
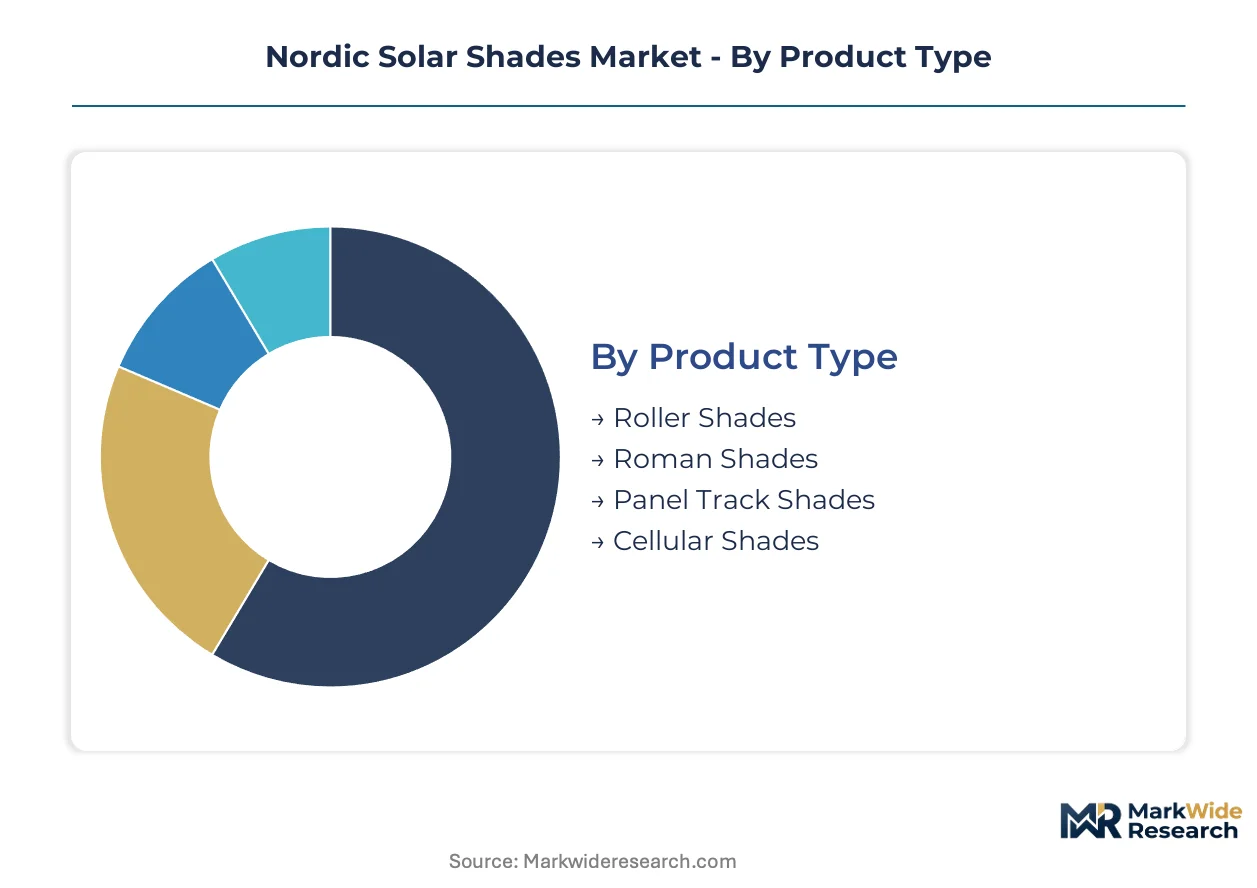
Specification authority in Nordic solar shading has migrated toward performance-driven selection criteria. Buyers now prioritize optical coefficients and automation compatibility over aesthetic differentiation alone.
Product Type:
Commercial retrofit timelines favor standardization that reduces installation complexity and accelerates compliance documentation.
- Roller Shades:Cylindrical fabric systems with aluminum or steel roller tubes achieve SHGC ratings below 0.35 through metallized coatings. Copenhagen and Stockholm office retrofits specify these for standardized facade modules where rapid procurement cycles dominate.
- Cellular Shades:Honeycomb-structured fabrics trap air layers to deliver R-value improvements of 3.0-4.0, commanding premium positioning in Danish and Swedish residential construction where thermal bridging regulations are strictest.
- Roman Shades:Soft-fold fabric systems with cord-lock or motorized lift mechanisms suit hospitality interiors requiring textile aesthetics alongside basic glare control.
- Panel Track Shades:Vertical fabric panels on ceiling-mounted tracks address oversized glazing in Norwegian fjord-region tourism properties where sliding door systems predominate.
Roller shades lead on scale; cellular shades lead on momentum.
Material:
REACH substance restrictions and fire safety codes are reshaping supplier qualification protocols across specification channels.
- Fabric:Woven polyester, fiberglass, and metallized composites dominate specification activity through optical tunability. Denmark's Øresund corridor concentrates demand for low-emissivity coated textiles in high-performance commercial envelopes.
- Aluminum:Extruded slat and perforated systems deliver Class A fire ratings and corrosion resistance for industrial and hospitality applications. Norwegian boutique hotel development in Bergen and Stavanger drives specification of anodized finishes.
- Vinyl:Extruded polymer slats offer moisture resistance and cleanability for healthcare and institutional retrofits where infection control protocols apply.
- Wood:FSC-certified timber slats serve residential segments in Finland and Sweden where biophilic design specifications intersect with sustainability certification requirements.
Fabric leads on scale; aluminum climbs the fastest on regulatory tailwinds.
Application:
End-use differentiation separates volume-driven retrofit markets from premium new construction segments.
- Commercial:Office, retail, and institutional fit-outs in Copenhagen, Stockholm, and Oslo constitute the largest specification volume. EU Energy Performance of Buildings Directive mandates compress procurement timelines toward pre-certified integrated systems.
- Residential:Single-family and multi-family construction in Denmark and Sweden drives cellular shade adoption for thermal performance compliance. Finnish residential penetration remains below regional benchmarks.
- Hospitality:Fjord-region tourism infrastructure investment in Norway creates demand for fire-rated facade systems with automated control integration.
- Industrial:Manufacturing and logistics facilities prioritize aluminum durability and low-maintenance operation in high-dust environments.
Commercial leads on scale; hospitality gains share fastest on tourism investment cycles.
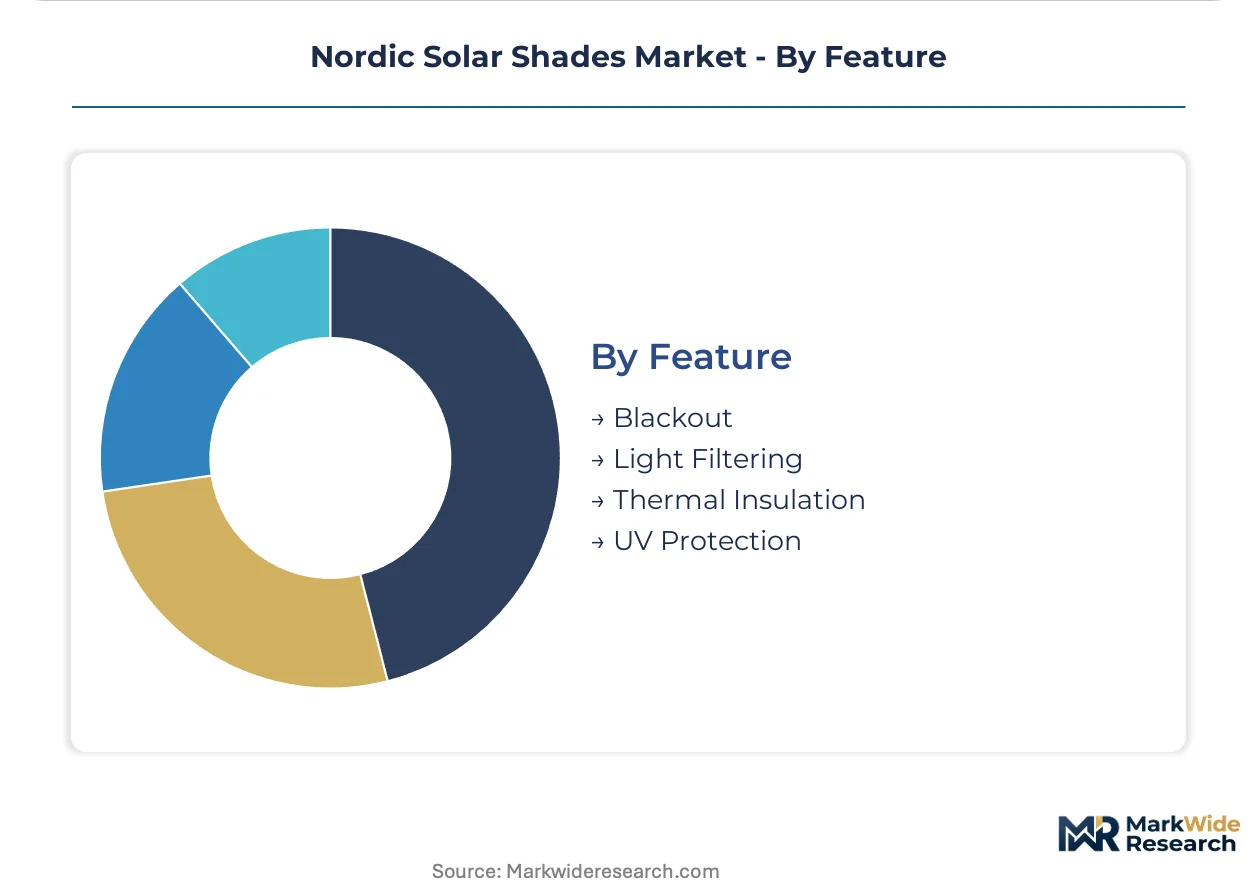
Feature:
Performance certification tiers now segment pricing and procurement channels more sharply than aesthetic attributes.
- Thermal Insulation:Cellular construction and low-emissivity coatings address envelope performance targets in Swedish and Danish energy code compliance. Specification authority rests with facade engineering consultants rather than interior designers.
- Blackout:Opaque fabric systems with side-channel sealing achieve total light elimination for hospitality and healthcare sleep environments. Oslo and Helsinki hotel developers specify these for premium room categories.
- Light Filtering:Sheer and semi-opaque fabrics balance daylight penetration with glare reduction in Danish commercial retrofits where daylight autonomy targets apply.
- UV Protection:Acrylic and polyester fabrics with UV stabilizers protect interior furnishings in high-latitude buildings where summer solar angles create intense exposure.
Thermal insulation leads on scale; blackout expands most quickly on hospitality development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Øresund corridor anchors Nordic solar shade demand through Copenhagen-Malmö cross-border commercial development. National energy codes across Denmark, Sweden, Norway, and Finland mandate envelope performance upgrades that expand specification volumes. Each country presents distinct regulatory timelines and cluster concentrations.
Denmark
Copenhagen office retrofits and Øresund corridor development drive commercial specification volumes. The Danish Building Regulation (BR18) mandates solar shading integration in envelope renovations exceeding threshold square footage. Aarhus and Odense concentrate installer capacity for climate-responsive facade systems.
Sweden
Stockholm's legacy building stock requires motorized retrofit solutions compatible with structural constraints. The Swedish National Board of Housing, Building and Planning enforces energy performance standards that compress certification timelines. Malmö synchronizes demand with Copenhagen through cross-border procurement frameworks.
Norway
Fjord-region tourism infrastructure investment creates hospitality demand for fire-rated aluminum systems. The Norwegian Building Authority implements EU Energy Performance of Buildings Directive requirements through national technical standards. Bergen and Stavanger concentrate boutique hotel development with automated control integration.
Finland
Cellular shade penetration lags regional benchmarks in single-family residential construction. The Finnish Ministry of the Environment administers building code updates that tighten thermal bridging requirements. Helsinki hotel developers specify blackout systems for premium room categories.
Nordic Solar Shades Market Key Industry Players
Global majors compete with regional champions across motorization technology and fabric engineering. The vendor base separates into three tiers: integrated building automation suppliers, specialized shading fabricators, and facade system generalists. Strategic archetypes include captive manufacturers controlling proprietary material supply, actuator technology licensors, and climate-responsive envelope integrators. M&A activity concentrates on automation capability acquisition, while geographic expansion targets underpenetrated Finnish residential channels.
Within the integrated automation tier, Lutron Electronics Co. Inc and Somfy Systems Inc represent technology-forward positioning through control system architecture. Hunter Douglas N.V anchors the captive manufacturing archetype with proprietary fabric production. Renson Ventilation nv exemplifies facade integration specialists extending beyond standalone shading into envelope performance systems. These three occupy distinct competitive vectors without direct product overlap.
| Leading Market Players |
|---|
| LUTRON Electronics Co. Inc |
| Somfy Systems Inc |
| Hunter Douglas N.V |
| VELUX Group |
| Busch-Jaeger Elektro GmbH |
| Chamberlain Group Inc |
| Renson Ventilation nv |
| Gira Giersiepen GmbH & Co. KG |
| Griesser AG |
| Others |
Cost & Logistics Intelligence
Captive fabric production by Hunter Douglas and Somfy's actuator technology licensing anchor supply positions while compressing margin pressure points for independent distributors. This upstream control over metallized coating formulations and motorization components concentrates pricing power among integrated manufacturers serving Copenhagen and Stockholm retrofit contractors.
Pricing Analysis
Metallized polyester and fiberglass input costs pass through to finished shade pricing with limited lag, compressing margins for non-integrated fabricators during REACH reformulation cycles. Pricing stratifies across premium cellular systems with R-value certification, standard roller configurations for commercial fit-outs, and economy vinyl slats for institutional retrofits. Cost compression in standard roller tiers intensifies as electrochromic glazing absorbs Class A office specification share. Residential buyers in Denmark and Sweden show lowest price sensitivity due to thermal performance code compliance requirements, while Norwegian hospitality developers negotiate aggressively on volume contracts.
Supply Chain Analysis
Freight costs from centralized European motorization hubs in France and Belgium amplify lead time volatility during peak Nordic retrofit seasons, forcing installers to hold buffer inventory. Manufacturing concentration in the Netherlands, Germany, and Belgium supplies metallized fabrics, aluminum extrusions, and actuator components to regional fabricators. Single-source vulnerability in specialized low-SHGC coating formulations creates qualification bottlenecks when ECHA substance restrictions trigger reformulation. Distribution runs through facade engineering consultants and certified installer networks rather than traditional building materials wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Nordic solar shades market compounds regulatory tailwinds from EU Green Deal building renovation targets into sustained specification volume growth. Denmark's BR18 mandate for solar shading in envelope renovations above threshold square footage exemplifies the demand architecture driving this market.
For Market Incumbents: Cement proprietary fabric supply positions through backward integration into metallized coating production, insulating margin structures from REACH-driven reformulation cycles. Expand captive actuator assembly capacity in Denmark's Øresund corridor to compress lead times for Copenhagen-Malmö cross-border projects. Electrochromic glazing substitution in premium commercial segments demands accelerated climate-responsive facade system development to defend specification relevance.
For New Entrants and Emerging Players: Finnish single-family residential developers represent an underserved buyer archetype with cellular shade penetration trailing Danish benchmarks by substantial margins. Target thermal insulation positioning in Helsinki and Tampere construction markets where national building code updates tighten thermal bridging requirements. Pursue partnership pathways with regional HVAC contractors already specifying envelope performance upgrades to bypass established distributor relationships.
For Investors and Strategic Acquirers: Roll-up economics work for climate-responsive facade integrators because installer scarcity and cross-training requirements in shading hardware and building automation protocols create fragmented local service markets. Five-to-ten year viability hinges on automation capability depth rather than commodity fabric production. Watch electrochromic glazing cost curves as the signal indicating potential demand displacement for conventional motorized systems in Class A office retrofits.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallized Coating Production | Captive supply of low-SHGC formulations insulates margins from ECHA reformulation cycles. |
| Climate-Responsive Facade System Development | Integration with natural ventilation and automated lighting extends specification beyond standalone shading. |
| Finnish Residential Channel Expansion | Underpenetrated cellular shade demand in Helsinki construction creates white-space growth. |
| Installer Network Certification Investment | Cross-trained technician scarcity elevates certified commissioning capabilities as competitive moats. |
| Electrochromic Glazing Partnership | Collaboration with smart glass manufacturers preserves relevance in premium Copenhagen commercial developments. |
Research Approach
Bottom-up commercial and residential construction modeling reconciled against top-down motorization component and fabric supply tracking forms the analytical core of this study. Primary interviews with facade engineering consultants, certified shading installers, building automation integrators, and procurement officers at Copenhagen and Stockholm retrofit contractors combined with secondary validation from EU Energy Performance of Buildings Directive implementation documents, ECHA REACH substance restriction databases, Danish Building Regulation BR18 technical standards, Swedish National Board of Housing planning bulletins, and Norwegian Building Authority technical guidelines. Triangulation between specification volume estimates and supplier shipment data tested forecast sensitivity.
Historical trendline analysis of retrofit cycle timing, energy code enforcement trajectories, and motorization technology adoption patterns informed projection mechanics across the analysis window. Segmentation dimensions modeled include product type, material composition, application end-use, and feature certification tier alongside latitude-specific optical performance requirements. CAGRs derived from fitted trend extrapolation adjusted for regulatory milestone timing and construction cycle seasonality. Industry-specific forecast inputs encompassed Øresund corridor development pipeline tracking and Finnish residential construction permit flows.
Inputs from national building authorities and EU regulatory databases were available through the study window; gaps in real-time installer capacity utilization data introduce uncertainty bands around peak-season throughput assumptions. Forecasts reflect documented assumptions about regulatory enforcement timelines and technology substitution rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Commercial Glazing Market
Building & Construction Materials
Cladding Systems Market
Building & Construction Materials
Insulated Wall Panels Market
Building & Construction Materials
India UPVC Doors and Windows Market
Building & Construction Materials
Spray Foam Market
Building & Construction Materials
Artificial Marble Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Concrete Protective Liners Market
Building & Construction Materials
US Exterior Wall Systems Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Global Cool Roofs Market
Building & Construction Materials
Door Hardware Market
Building & Construction Materials
Concrete Cooling Market
Building & Construction Materials
Japan Oriented Strand Board Market
Building & Construction Materials
North America Wood Based Panel Market