
 Drilling Stabilizers Market | 2026-2036
Drilling Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Drilling Stabilizers Market Analysis
API 7-1 specification-grade stabilizers is rotating toward premium hardfacing and non-magnetic alloy configurations as operators push deeper into high-pressure, high-temperature formations. Schlumberger Limited leverages integrated drilling systems to bundle stabilizer placement with directional advisory services. Halliburton Company sustains manufacturing scale through captive forging capacity in Houston and Aberdeen. Baker Hughes Company differentiates via proprietary tungsten carbide hardfacing recipes that extend downhole wear life.
Drilling stabilizers are thick-walled, spiral-bladed or straight-bladed downhole tools manufactured from AISI 4145H modified steel or non-magnetic stainless grades, heat-treated to 285-341 Brinell hardness, designed to centralize the drillstring, reduce vibration, and maintain borehole trajectory in vertical, directional, and horizontal wells. Steel stabilizers anchor the component mix due to proven fatigue resistance and repairability, though composite stabilizers are gaining share in corrosive sour-gas environments where weight reduction extends reach. Onshore drilling occupies the largest application volume, while directional drilling commands the fastest growth as laterals exceed 15,000 feet in North American shale plays.
API 7-1 standards, the US EPA's New Source Performance Standards for oil and gas, and NORSOK D-002 well integrity requirements collectively dictate material certification, traceability, and environmental compliance for stabilizer suppliers. The US EPA mandates drive investment in low-emission manufacturing processes and recycled steel feedstocks. Stakeholders must monitor how digital twin technology and real-time downhole telemetry reshape stabilizer design cycles and replacement economics.
Market Dynamics
Directional drilling economics now hinge on stabilizer durability in extended-reach laterals, where blade wear rates dictate non-productive time and replacement frequency. The shift toward 15,000-foot-plus laterals in unconventional shale has elevated stabilizer hardfacing from commodity specification to performance differentiator.
Growth Catalysts
- EPA methane regulations:Tightening New Source Performance Standards force operators toward premium stabilizer alloys that reduce leak paths and extend seal integrity in high-pressure gas formations.
- Permian Basin concentration:Unconventional drilling intensity in West Texas and New Mexico sustains procurement volume for API 7-1 certified stabilizers with enhanced tungsten carbide hardfacing.
- Digital twin integration:Real-time downhole telemetry enables predictive replacement scheduling, converting stabilizer procurement from reactive spot-buying to planned maintenance contracts.
Market Restraints
- Alloy input volatility:Nickel and cobalt price swings in specialty stainless grades compress margin predictability for non-magnetic stabilizer production.
- Forging capacity concentration:Captive heat-treatment and forging infrastructure clusters in Houston and Aberdeen create geographic supply risk for independent distributors.
- Composite substitution ceiling:Sour-gas corrosion resistance in fiber-reinforced polymer stabilizers remains unproven above 150°C, limiting displacement of steel in HPHT zones.
Strategic Opportunities
- Gulf of Mexico ultra-deepwater:Subsea tieback projects in 10,000-foot water depths create demand for non-magnetic stabilizers with enhanced fatigue resistance in salt-dominated formations.
- Remanufacturing services:Hardfacing reapplication and blade reconditioning capture value from installed base rather than new-build competition.
- NORSOK D-002 alignment:Norwegian well integrity standards provide certification pathway for suppliers seeking premium positioning in North Sea decommissioning and redevelopment cycles.
Industry Challenges
- API 7-1 audit timelines:Third-party certification delays of 12-18 months constrain speed-to-market for new hardfacing formulations.
- Legacy drillstring integration:Digital telemetry compatibility with existing BHA configurations requires custom engineering that fragments standardization gains.
- Welder qualification scarcity:Tungsten inert gas certification for hardfacing deposition remains concentrated among aging specialist workforces in Houston and Aberdeen.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drilling Stabilizers Market |
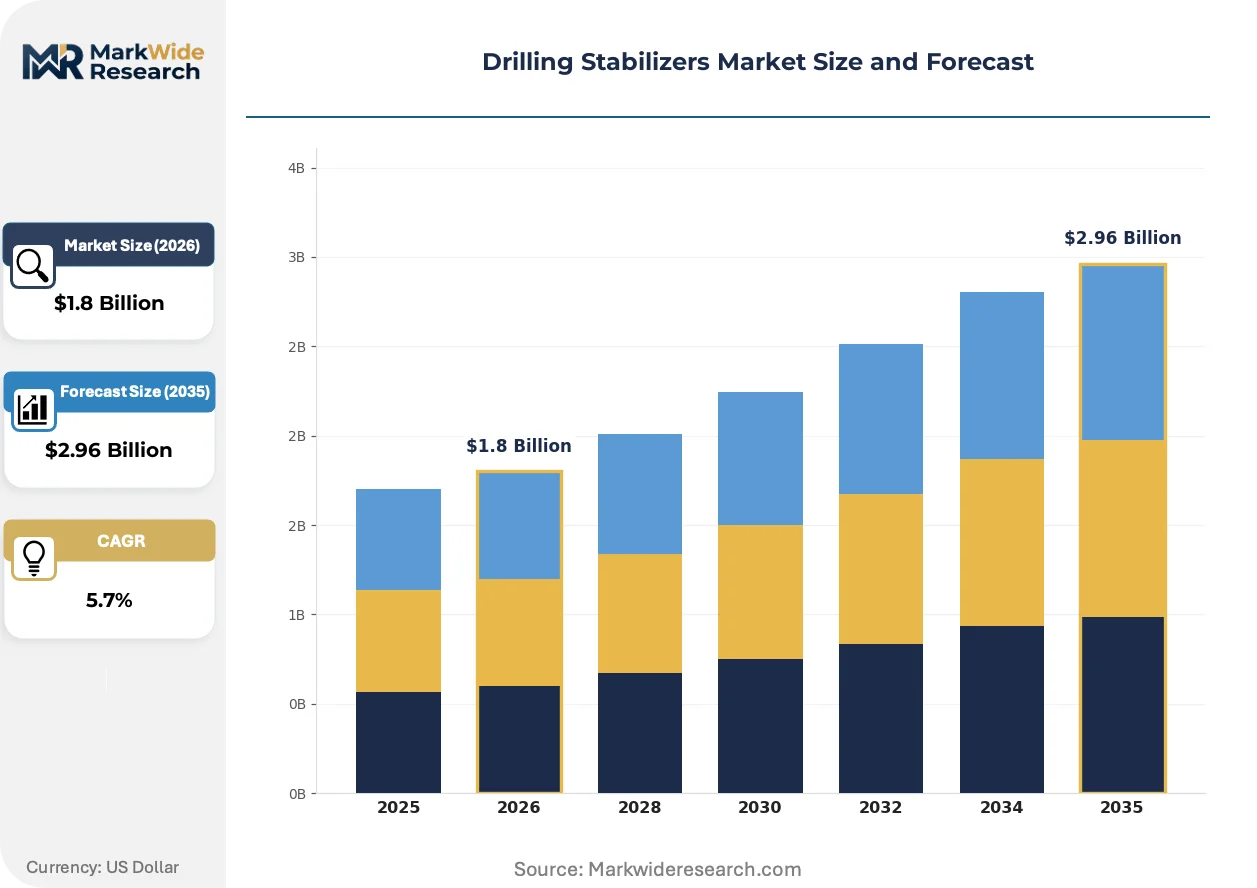
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Steel Stabilizers, Composite Stabilizers, Hybrid Stabilizers, Others Application: Onshore Drilling, Offshore Drilling, Directional Drilling, Horizontal Drilling End User: Oil & Gas, Mining, Water Well, Geothermal Technology: Conventional Technology, Advanced Technology, Digital Technology, Automated Technology |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, National Oilwell Varco, Weatherford International plc, Stabil Drill LLC, Drillstar Industries, Cougar Drilling Solutions, ACE Downhole LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drilling Stabilizers Market Emerging Trajectories
Stabilizer design cycles are compressing as real-time downhole data feeds directly into blade geometry optimization. Three converging developments are restructuring how operators specify, procure, and deploy these tools.
Non-magnetic stainless grades are fragmenting the traditional AISI 4145H market as directional drilling in magnetic interference zones demands gyroscopic survey accuracy. Operators in the Permian and Bakken now specify 316L or proprietary Cr-Mn-N alloys for MWD compatibility. This material divergence is fragmenting supplier specialization between magnetic and non-magnetic production lines.
The US EPA's methane detection and repair mandates are accelerating investment in low-emission manufacturing processes for downhole components. Stabilizer suppliers must document recycled steel feedstocks and reduced furnace emissions to maintain operator procurement eligibility. Gulf of Mexico offshore contractors face the strictest compliance timelines, with some mandating supplier ESG scorecards by 2026.
Integrated drilling service contracts are compressing standalone stabilizer procurement as operators bundle BHA components with directional advisory. This bundling displaces spot purchasing through independent distributors in favor of long-term performance agreements. The shift is most visible in North American shale plays where drilling contractors consolidate vendor relationships to reduce administrative overhead.
Drilling Stabilizers Market Segmentation
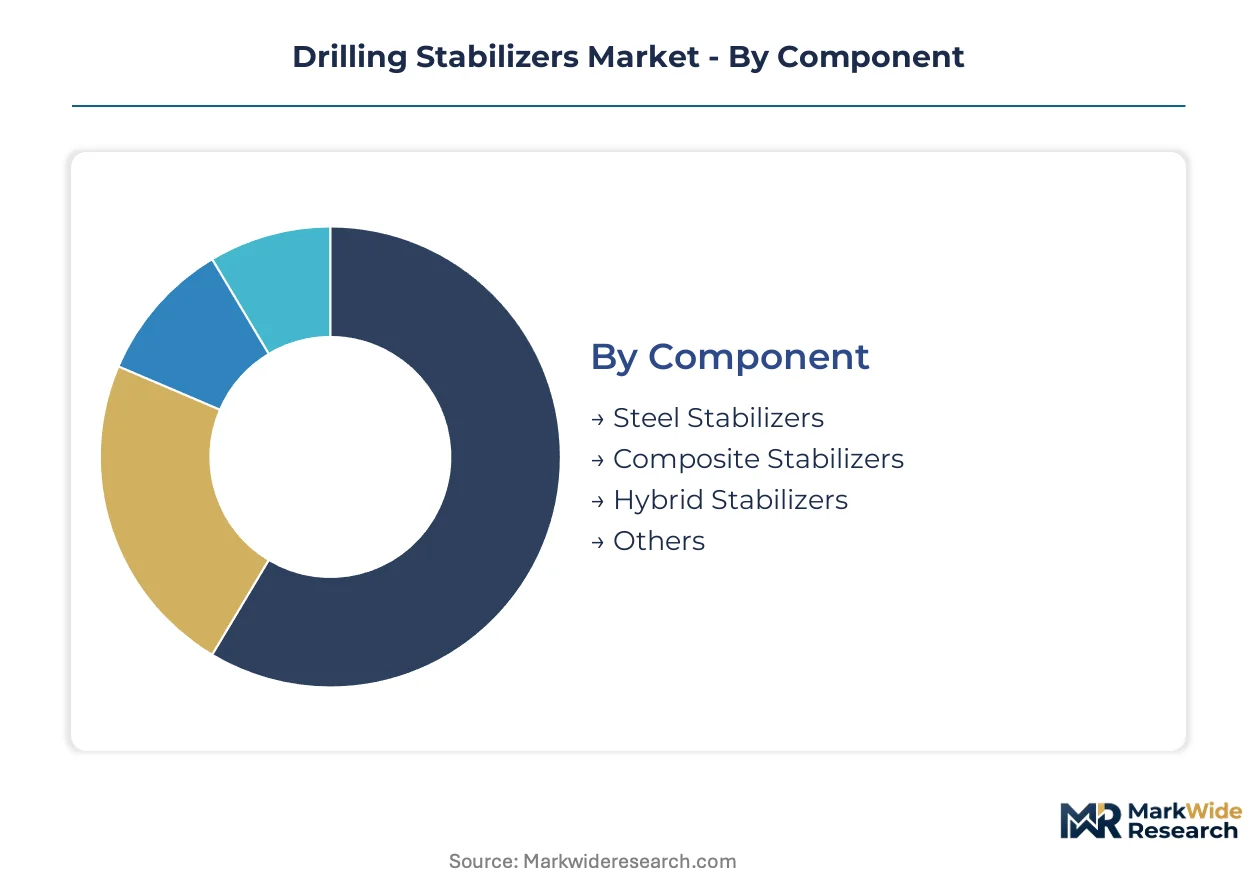
Stabilizer procurement patterns diverge sharply across material grades, well architectures, and operator technology maturity. Segment boundaries are blurring as integrated drilling contracts bundle formerly discrete component categories.
Component:
Composite formulations pose the most acute substitution threat to legacy steel configurations, particularly in corrosive environments where weight reduction extends lateral reach.
- Steel Stabilizers:AISI 4145H modified steel heat-treated to 285-341 Brinell hardness dominates fatigue-critical applications. Demand clusters in Permian Basin extended-reach laterals where repairability and blade reconditioning economics favor steel over disposable alternatives.
- Composite Stabilizers:Fiber-reinforced polymer constructions gain traction in sour-gas corridors where galvanic corrosion accelerates steel fatigue. Temperature ceilings near 150°C constrain penetration into HPHT zones, limiting displacement of metallics in ultra-deep formations.
- Hybrid Stabilizers:Steel bodies with composite blade inserts balance wear resistance and weight reduction for marginal well economics.
- Others:Experimental ceramic-matrix and titanium alloy prototypes serve niche aerospace-derived drilling programs.
Steel stabilizers anchor the volume base while composite stabilizers gain share at the steepest rate.
Application:
Cost tier stratification separates commoditized vertical drilling from premium directional services where stabilizer placement determines trajectory precision.
- Onshore Drilling:Vertical and deviated well programs in conventional reservoirs consume high-volume, standard-hardfacing configurations. Procurement runs through independent distributors serving regional rig fleets in West Texas and New Mexico.
- Directional Drilling:Extended-reach laterals exceeding 15,000 feet demand non-magnetic stabilizers compatible with gyroscopic MWD surveys. Blade wear rates in abrasive shale formations elevate hardfacing specifications from commodity to performance differentiator.
- Offshore Drilling:Subsea tiebacks in Gulf of Mexico salt-dominated formations require enhanced fatigue resistance and API 7-1 certification with full material traceability.
- Horizontal Drilling:Lateral sections in unconventional plays stress stabilizer durability through prolonged rotating hours in high-torque environments.
Onshore drilling commands the largest procurement volume while directional drilling expands most quickly as lateral lengths stretch beyond 15,000 feet.
End User:
Customer type concentration shapes specification rigor, with oilfield operators demanding certification depth that mining and water well contractors rarely match.
- Oil & Gas:Exploration and production companies drive API 7-1 compliance, EPA methane regulation alignment, and digital telemetry integration. Procurement shifts from spot purchasing to multi-year performance contracts bundled with directional advisory.
- Mining:Blast hole and raise bore applications prioritize abrasion resistance over precision trajectory control, accepting lower-grade hardfacing at reduced cost points.
- Water Well:Municipal and agricultural drilling programs favor repairable steel configurations over premium alloys given shallow depth requirements and intermittent utilization.
- Geothermal:High-temperature formations above 200°C test material limits, creating demand for specialized non-magnetic grades beyond standard AISI specifications.
Oil and gas operators dominate specification-setting while geothermal applications climb the fastest as renewable baseload projects multiply.
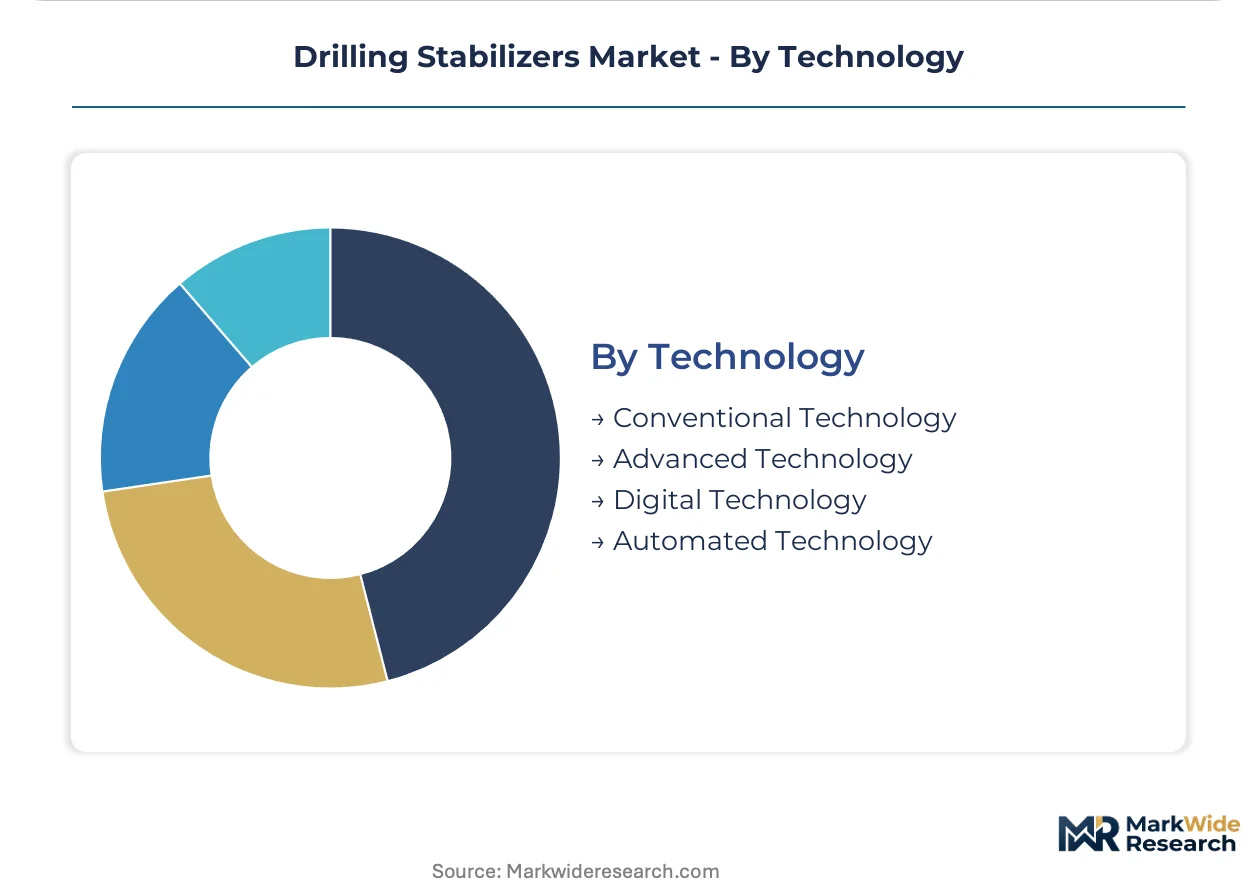
Technology:
Supply concentration in legacy forging infrastructure slows adoption velocity for digital and automated categories despite operator interest.
- Conventional Technology:Mechanical blade designs without integrated sensors constitute the installed base majority. Replacement cycles follow reactive failure protocols rather than predictive scheduling.
- Advanced Technology:Proprietary tungsten carbide recipes and optimized blade geometries extend wear life in abrasive formations. Baker Hughes and Halliburton captive manufacturing scales these configurations across North American shale plays.
- Digital Technology:Embedded accelerometers and temperature sensors feed real-time telemetry for blade condition monitoring. Integration with legacy BHA configurations requires custom engineering that fragments standardization.
- Automated Technology:Self-adjusting blade clearances and autonomous trajectory correction remain developmental, constrained by API certification timelines and welder qualification scarcity.
Conventional technology retains the largest installed base while digital technology gains share at the steepest rate as real-time telemetry proves economic value in extended-reach programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in drilling stabilizers track closely to oilfield service procurement patterns, with the United States running a structural deficit in specialty forgings that European and Asian fabricators partially offset. Demand geography concentrates where unconventional drilling intensity intersects with local content requirements and environmental enforcement.
United States
Permian Basin operators in West Texas and southeastern New Mexico consume the majority of API 7-1 certified stabilizers for extended-reach laterals exceeding 15,000 feet. The EPA's New Source Performance Standards for methane emissions tighten material traceability requirements for downhole tools. Houston anchors domestic forging capacity, though specialty heat-treatment for non-magnetic grades remains concentrated among a limited supplier base.
Norway
North Sea decommissioning and redevelopment cycles sustain demand for NORSOK D-002 compliant stabilizers with full material certification. The Norwegian Petroleum Safety Authority mandates well integrity documentation that exceeds standard API specifications. Stavanger and Bergen host engineering clusters where suppliers align certification pathways for premium offshore positioning.
Saudi Arabia
Aramco's drilling intensity in the Ghawar and Safaniya fields drives procurement of high-fatigue stabilizers for carbonate formations. The Saudi Standards, Metrology and Quality Organization enforces localization requirements that favor joint ventures with international oilfield service firms. Dhahran's industrial corridor concentrates hardfacing reconditioning capacity serving regional rig fleets.
China
Domestic shale development in Sichuan and Xinjiang provinces expands demand for cost-optimized stabilizer configurations. The Ministry of Ecology and Environment enforces dual carbon goals that pressure foundries toward electric furnace conversion and recycled steel feedstocks. Shanghai and Tianjin port zones handle import logistics for specialty nickel alloys unavailable from domestic mills.
United Arab Emirates
Adnoc's offshore expansion in the Upper Zakum and Lower Zakum fields creates demand for corrosion-resistant stabilizers in high-salinity environments. The Abu Dhabi National Oil Company's in-country value requirements steer procurement toward local fabrication partnerships. Jebel Ali free zone clusters oilfield service logistics serving Gulf of Mexico and East African export markets.
Drilling Stabilizers Market Vendor Landscape
Concentration sits with integrated oilfield service conglomerates that bundle stabilizer procurement within broader drilling system contracts. Three to five captive forging operations in Houston and Aberdeen anchor supply-side capacity, while independent distributors face margin compression from direct operator relationships. Strategic archetypes separate integrated drilling service providers, specialty hardfacing shops, and regional fabrication contractors. Competitive moves center on backward integration into heat-treatment infrastructure and technology licensing for proprietary alloy formulations.
Among integrated service providers, Schlumberger Limited, Halliburton Company, and Baker Hughes Company exemplify the bundled-contract model where stabilizer placement merges with directional advisory and real-time telemetry services. These entities occupy positions that independent fabricators struggle to replicate without captive BHA integration capabilities. Specialty hardfacing and reconditioning services remain fragmented among regional operators, though API 7-1 certification timelines create barriers to rapid scale.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| National Oilwell Varco |
| Weatherford International plc |
| Stabil Drill LLC |
| Drillstar Industries |
| Cougar Drilling Solutions |
| ACE Downhole LLC |
| Others |
Supply Flow & Price Mechanics
Composite blade inserts displacing solid steel configurations in sour-gas corridors simultaneously fragment supplier specialization between magnetic and non-magnetic production lines and compress margin predictability for legacy forging operations. This substitution dynamic redistributes procurement power toward operators bundling BHA components under integrated drilling contracts.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with API 7-1 certification grade and tungsten carbide hardfacing specification serving as primary differentiation drivers. Cost compression in standard-grade configurations is intensifying because captive forging capacity at integrated service providers squeezes independent distributor margins. National oil companies exhibit lowest price sensitivity due to well integrity mandates, while municipal water well contractors demonstrate highest sensitivity given shallow depth requirements and intermittent rig utilization.
Supply Chain Analysis
Houston heat-treatment infrastructure and Aberdeen forging clusters constitute twin chokepoints that tether global supply for non-magnetic grades and specialty hardfacing deposition. Raw material flows draw from domestic AISI 4145H mills, imported nickel alloys through Shanghai and Tianjin ports, and cobalt-bearing stainless from European specialty metal suppliers. Single-source vulnerability concentrates in TIG welder qualification scarcity across aging specialist workforces. Distribution runs through oilfield service conglomerates bundling stabilizers within integrated BHA contracts, displacing spot purchasing through independent channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin integration with legacy drillstring telemetry is transforming stabilizer procurement from reactive component purchasing into predictive platform economics, with real-time blade condition monitoring creating interoperability lock-in between hardware vendors and drilling advisory services.
For Market Incumbents: Consolidate captive forging capacity in Houston and Aberdeen through selective facility acquisitions, insulating against welder qualification scarcity while hardening backward integration into heat-treatment infrastructure. Defend against composite substitution in sour-gas corridors by accelerating proprietary Cr-Mn-N alloy R&D and securing NORSOK D-002 certification ahead of North Sea redevelopment cycles. For New Entrants and Emerging Players: Differentiate on hardfacing reconditioning services targeting the installed base of steel stabilizers in Permian Basin extended-reach laterals, where blade wear economics favor repair over replacement. Target geothermal drilling applications above 200°C as the most penetrable segment, leveraging temperature ceiling limitations in fiber-reinforced polymer alternatives to justify premium non-magnetic grade positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty hardfacing shops holding API 7-1 certification but lacking integrated BHA capabilities, presenting roll-up opportunities ahead of bundled-contract consolidation. Long-term viability hinges on digital telemetry compatibility rather than standalone component manufacturing. Watch EPA methane regulation enforcement timelines as the critical inflection signal for low-emission manufacturing process valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Treatment Infrastructure | Captive forging capacity insulates margin position against specialty alloy price volatility and welder scarcity. |
| NORSOK D-002 Certification Investment | Norwegian well integrity standards unlock premium positioning in North Sea decommissioning and redevelopment procurement cycles. |
| Digital Twin Platform Integration | Real-time telemetry compatibility converts stabilizer procurement from spot purchasing to recurring performance contracts. |
| Hardfacing Reconditioning Service Expansion | Blade reconditioning economics in Permian extended-reach laterals capture value from installed base rather than new-build competition. |
| Non-Magnetic Alloy R&D Partnership | Proprietary Cr-Mn-N formulations address MWD compatibility requirements in magnetic interference zones of unconventional shale plays. |
Methodological Framework
Desk research of API specification databases, EPA regulatory filings, and oilfield service procurement disclosures preceded structured interviews with drilling engineers, BHA procurement managers, hardfacing shop supervisors, and directional advisory specialists. Primary fieldwork combined telephone interviews and facility observations across Houston, Aberdeen, and Stavanger engineering clusters with secondary validation through customs trade records, SEC 10-K equipment expenditure disclosures, and NORSOK certification registries. Bottom-up stabilizer unit economics and top-down oilfield service revenue allocation were triangulated to constrain estimate variance.
Variance decomposition across material grade, application architecture, and end-user technology maturity shaped the analytical framework throughout the forecast period. CAGRs were derived from segment-level unit projections calibrated against rig count trajectories and lateral length expansion curves. Modeled dimensions span steel versus composite versus hybrid component formulations, onshore versus offshore versus directional drilling applications, and conventional versus digital versus automated technology tiers. Industry-specific inputs include EPA methane regulation compliance timelines and Permian Basin drilling intensity forecasts.
The analysis sits within stated boundaries; outcomes outside sustained unconventional shale development, stable nickel-cobalt alloy pricing, or continued API 7-1 specification adherence would require recalibration. Forecasts reflect documented assumptions regarding digital telemetry adoption rates and integrated drilling contract penetration. Practitioners should keep alternative scenarios live as EPA enforcement intensity, composite material temperature thresholds, and Gulf of Mexico ultra-deepwater project sanctions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
North America Underground Mining Equipment Market
Mining Equipment
Borehole Enlargement System Market
Mining Equipment
Stone Crushing Equipment Market
Mining Equipment
Underground Mining Equipment Market
Mining Equipment
Surface Drilling Rig Market
Mining Equipment
Global Connected Mining Market
Mining Equipment
DTH Drill Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Kazakhstan Mining Market
Mining Equipment
Rock-Socketed Drilling Rig Market
Mining Equipment
Mining Machinery Battery Market
Mining Equipment
Drilling Rigs Market
Mining Equipment
Mining Collectors Market
Mining Equipment
Digger Machinery Market
Mining Equipment
Mobile Blasting Systems Market
Mining Equipment
Underground Mining Automation Market