
 India UPVC Doors and Windows Market | 2026-2036
India UPVC Doors and Windows Market Size, Share, and Industry Trends Forecast 2026-2036
India UPVC Doors and Windows Market Foresight
Aluminum is pivoting toward replacement by UPVC across mid-rise residential projects due to superior thermal insulation and lower lifecycle maintenance costs. Fenesta Building Systems leverages extensive dealer networks across South and West India to sustain market presence. Encraft India anchors its position through specialized fabrication capabilities in custom architectural profiles. Koemmerling differentiates via German-engineered extrusion technology adapted for tropical climate performance.
India UPVC doors and windows comprise rigid polyvinyl chloride profiles reinforced with galvanized steel inserts, extruded into multi-chambered hollow sections that achieve thermal transmittance values below 2.0 W/m²K. These assemblies serve primarily as weather-resistant, low-maintenance building envelopes for climate-controlled interiors in hot-humid and hot-dry zones. Casement windows and sliding doors together constitute the dominant product pairing, with sliding doors capturing expanding share in compact urban apartments where swing clearance is constrained. Residential buildings remain the deepest application pool, though commercial properties represent the fastest-growing segment as green building certification requirements tighten across metro projects.
BIS mandates IS 17037 compliance for UPVC profile dimensional stability and impact resistance, while state-level energy conservation building codes in Maharashtra and Gujarat prescribe specific U-value thresholds for fenestration. CDSCO does not regulate this sector directly, but the Bureau of Energy Efficiency's star-labeling program for windows shapes procurement specifications in government housing schemes. Stakeholders must monitor evolving state urban development authority mandates on fire-retardant additives and recyclability quotas as these will determine which extrusion formulations qualify for large-scale public infrastructure contracts.
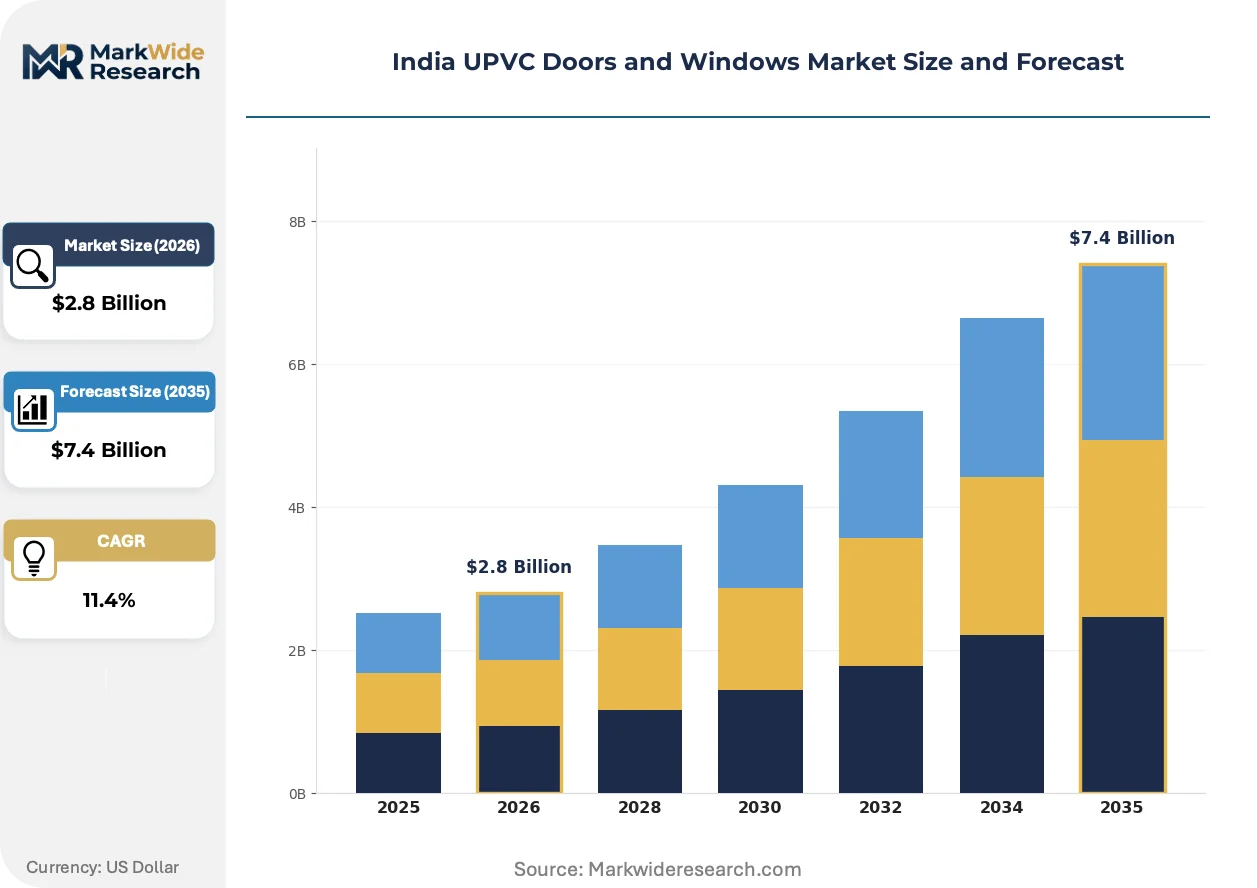
Market Dynamics
The transition from aluminum to UPVC across Maharashtra, Gujarat, and Karnataka mid-rise residential stock is compressing specification cycles and forcing extruders to retool for multi-chamber thermal profile production.
Growth Catalysts
- Affordable Housing Mission:Central and state-sanctioned projects in tier-2 and tier-3 cities specify UPVC fenestration for maintenance cost containment over 25-year asset lifecycles.
- BIS IS 17037 Mandate:Compulsory certification for dimensional stability and impact resistance is filtering out unorganized extruders and consolidating demand toward compliant fabricators.
- Multi-chamber extrusion:Adoption of five and six-chamber profile designs achieving sub-2.0 W/m²K thermal transmittance is opening specification in green-certified commercial envelopes.
Market Restraints
- Galvanized steel reinforcement volatility:Price swings in zinc-coated steel inserts directly compress fabrication margins on standard profile grades.
- Unorganized sector concentration:Non-certified workshops across Uttar Pradesh and Rajasthan undercut certified fabricators on upfront pricing, fragmenting procurement decisions.
- Fire-retardant additive scarcity:Limited domestic production of brominated or phosphorus-based compounds forces import dependency, extending lead times for high-rise compliant profiles.
Strategic Opportunities
- Commercial green building pipeline:IGBC and GRIHA certification mandates across Bangalore, Pune, and Hyderabad metro projects create specification pull for low-U-value assemblies.
- Recyclability quota anticipation:Draft urban development authority circulars on post-consumer PVC recovery are positioning early movers for public infrastructure contract eligibility.
- Sliding door retrofit channel:Compact apartment configurations in Mumbai and Delhi NCR are driving replacement demand through modular installation services bypassing traditional dealer networks.
Industry Challenges
- Fabrication technician scarcity:Skilled operators for CNC corner cleaning and automated welding stations are concentrated in Gujarat and Maharashtra, constraining capacity expansion elsewhere.
- Multi-agency compliance sequencing:Simultaneous BIS factory audits, state energy code submissions, and municipal fire safety clearances extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India UPVC Doors and Windows Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casement Windows, Sliding Doors, Bi-fold Doors, Fixed Windows Application: Residential Buildings, Commercial Properties, Industrial Facilities, Institutional Structures End User: Homeowners, Contractors, Builders, Architects Size: Standard Size, Custom Size, Large Panels, Small Panels |
| Companies Covered | Encraft India, Simta Astrix, Fenesta Building Systems, PSP Dynamic Limited, Prominance Window Systems, VEKA India, Koemmerling, Lingel Windows & Doors Technologies, Aparna Venster, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India UPVC Doors and Windows Market Shifts & Advancements
Fabrication technology and procurement specifications are converging to compress delivery cycles while raising thermal performance floors across residential and commercial segments.
Automated CNC corner cleaning and welding lines are automating quality consistency in high-volume residential orders. Tier-1 fabricators in Ahmedabad and Pune are deploying robotic welding stations for casement frame production. This automation is compressing defect rates and enabling just-in-time delivery contracts with project developers.
Bureau of Energy Efficiency star-labeling for windows is mandating disclosure of U-values and air infiltration rates. State nodal agencies in Maharashtra and Gujarat are incorporating these labels into technical bid evaluations for government housing. Large developers are responding by pre-specifying 3-star minimum ratings in tender documents.
Direct procurement from extrusion plants is displacing traditional three-tier distribution for volume residential projects. Mumbai and Bangalore-based developers are negotiating annual rate contracts with profile manufacturers, bypassing regional distributors. This channel shift is most visible in projects exceeding 500-unit phases where logistics consolidation yields freight savings.
India UPVC Doors and Windows Market Segmentation
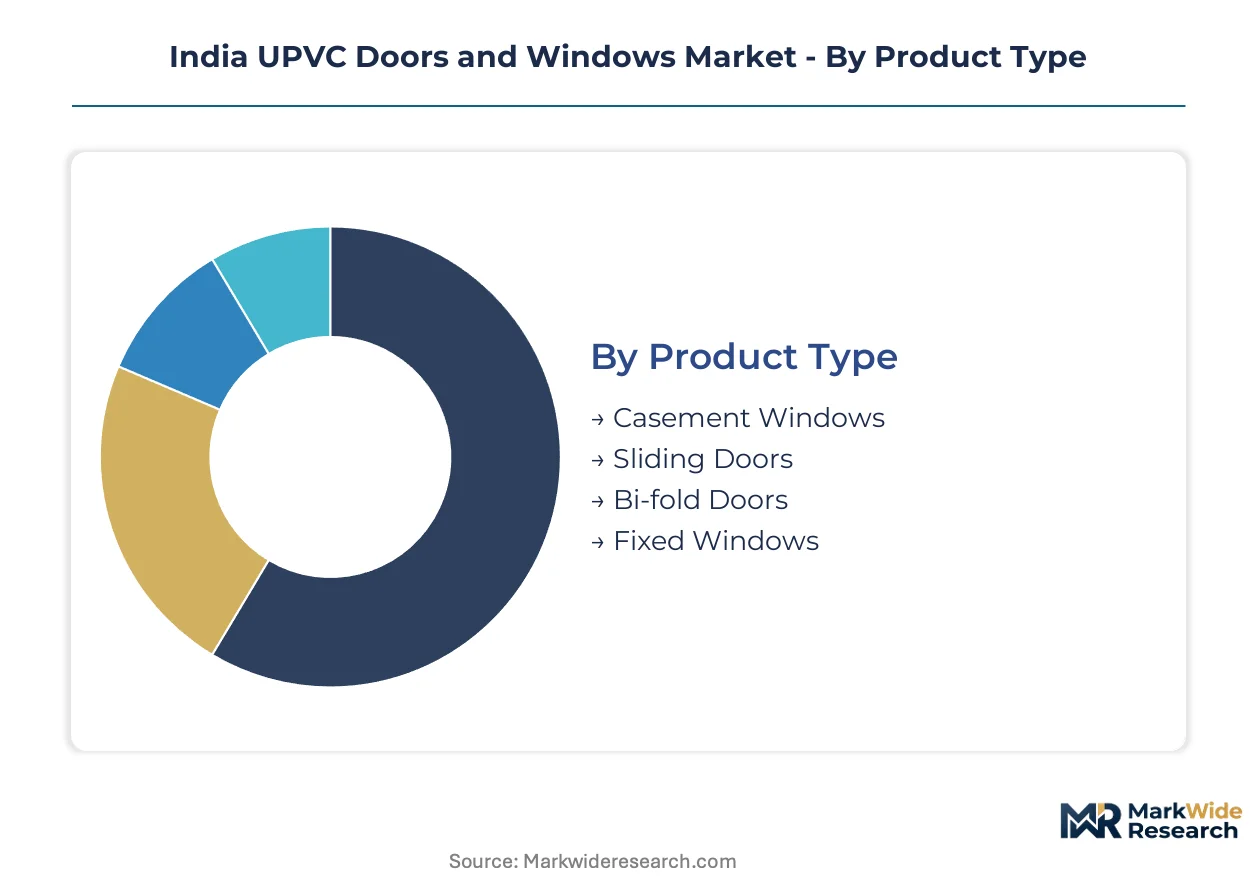
UPVC fenestration procurement splits across technical specifications, project scale, and decision-maker type. Each segmentation axis determines pricing leverage, installation complexity, and compliance pathway for fabricators competing in Maharashtra, Gujarat, and Karnataka construction corridors.
Product Type:
Capital intensity concentrates in multi-chamber extrusion dies and automated welding lines for high-volume casement and sliding configurations.
- Casement Windows:Hinged sash assemblies with multi-point locking hardware achieve sub-2.0 W/m²K thermal transmittance through five and six-chamber profiles. Demand clusters in Pune and Hyderabad green-certified mid-rise residential where swing clearance is available and acoustic insulation is specified.
- Sliding Doors:Horizontal roller systems with tandem wheel carriages and brush pile seals dominate Mumbai and Delhi NCR compact apartment retrofits where floor space optimization overrides thermal performance priorities. Installation services are modularizing around bypass dealer networks.
- Bi-fold Doors:Accordion-fold panels with bottom-hung or top-guided hardware serve premium villa and penthouse segments in Bangalore.
- Fixed Windows:Non-operable picture windows with minimal hardware content anchor cost-sensitive affordable housing specifications across tier-2 Gujarat towns.
Most installed capacity flows through casement windows. Expansion is steepest in sliding doors.
Application:
Project type determines thermal code stringency and procurement decision velocity, with commercial envelopes requiring extended compliance sequencing.
- Residential Buildings:Single-family homes and multi-unit apartments constitute the deepest volume pool, with affordable housing missions in tier-2 and tier-3 cities specifying UPVC for 25-year lifecycle cost containment. BIS IS 17037 compliance is becoming mandatory in state technical sanctions.
- Commercial Properties:Office towers and retail complexes represent the steepest expansion trajectory as IGBC and GRIHA certification mandates tighten across Bangalore, Pune, and Hyderabad metro developments. Low-U-value assemblies command specification premiums.
- Industrial Facilities:Factory envelopes and warehouse structures prioritize dust exclusion and basic weathering over thermal performance, sourcing from standard profile grades.
- Institutional Structures:Schools and hospitals in Maharashtra incorporate fire-retardant additive specifications that extend lead times due to import-dependent chemistry.
Residential buildings absorb the majority of extrusion tonnage. Commercial properties are climbing the fastest.
End User:
Decision authority fragments across project phases, with architects wielding specification power in early design and contractors controlling procurement execution.
- Homeowners:Individual purchasers in replacement and renovation channels prioritize visible finish quality and hardware aesthetics over certified thermal performance, creating price competition from non-certified Uttar Pradesh workshops.
- Contractors:Project execution firms in Ahmedabad and Pune aggregate volume for annual rate contracts with profile manufacturers, consolidating logistics and compressing per-unit freight costs.
- Builders:Large developers exceeding 500-unit phases negotiate direct extrusion plant procurement, bypassing regional distributors and capturing channel margin.
- Architects:Design-phase influencers in green-certified commercial projects specify U-value thresholds and air infiltration rates that filter fabricator qualification.
Builders command the largest order values. Architects are gaining specification influence fastest.
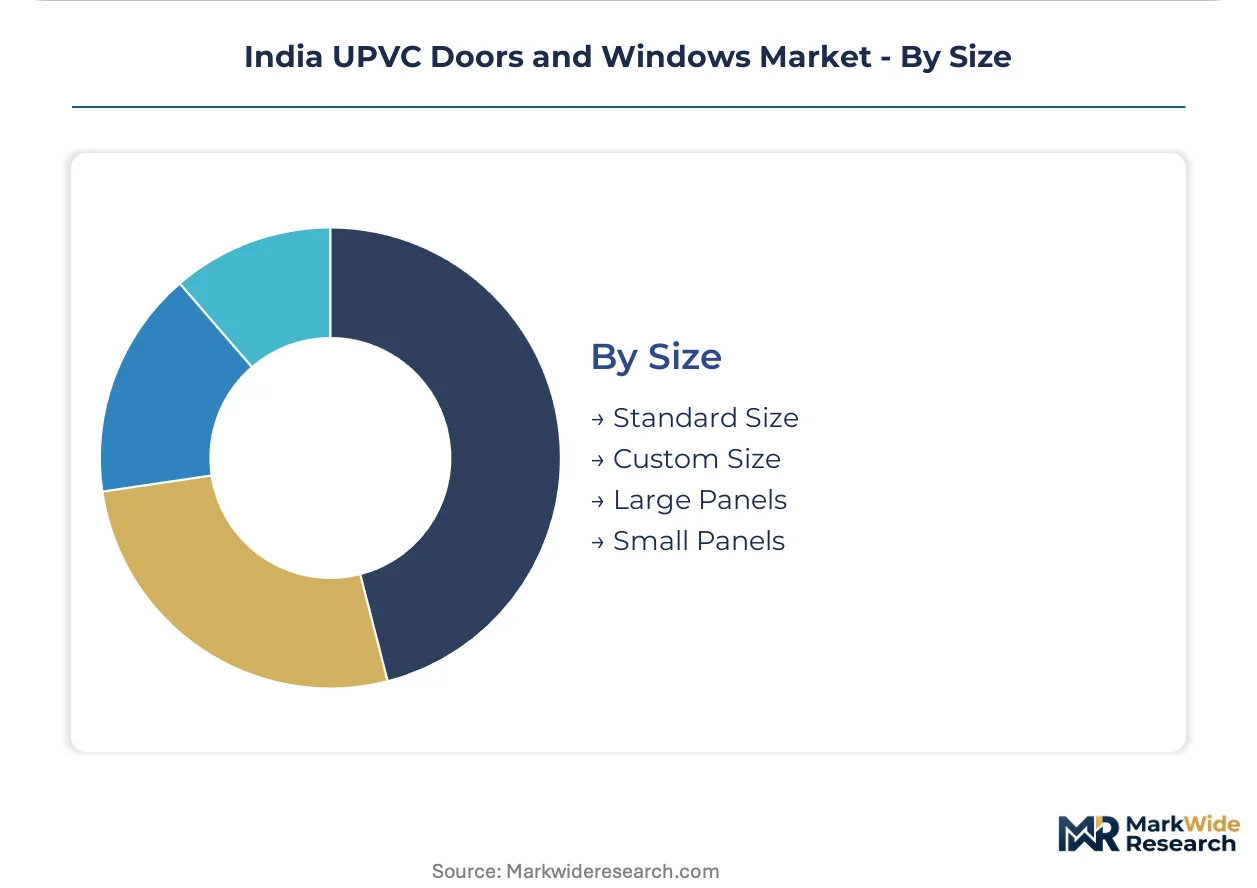
Size:
Panel dimension determines logistics complexity and installation crew specialization, with custom sizing requiring CNC fabrication capabilities concentrated in Gujarat and Maharashtra.
- Standard Size:Mass-produced dimensions from 600mm to 1500mm module widths enable inventory stocking and rapid fulfillment for affordable housing scale.
- Custom Size:Architectural project-specific dimensions demand automated corner cleaning and welding stations, constraining supplier base to tier-1 fabricators with capital equipment.
- Large Panels:Floor-to-ceiling glazing assemblies for commercial lobbies require reinforced steel inserts and specialized lifting equipment.
- Small Panels:Bathroom and utility window formats serve renovation replacement channels with minimal lead times.
Standard sizes dominate production throughput. Custom sizing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's chemical-industrial corridor anchors UPVC extrusion capacity, with Ahmedabad-Surat fabrication clusters supplying Maharashtra and Karnataka construction corridors through dedicated logistics networks.
Maharashtra
Mumbai's compact apartment stock drives sliding door retrofits where floor space optimization overrides thermal priorities. BIS IS 17037 compliance is mandatory in state technical sanctions for affordable housing missions. Pune fabrication units deploy automated welding stations for green-certified mid-rise residential projects.
Gujarat
Petrochemical feedstock proximity enables cost-competitive profile extrusion for pan-India distribution. State energy conservation building codes prescribe specific U-value thresholds for fenestration in commercial envelopes. Ahmedabad hosts the densest concentration of CNC-equipped fabricators serving western India.
Karnataka
Bangalore's green building pipeline creates specification pull for low-U-value assemblies in IGBC-certified office towers. Bureau of Energy Efficiency star-labeling shapes procurement in government housing schemes. Hyderabad fabrication capacity is expanding to capture Telangana and Andhra Pradesh demand.
Tamil Nadu
Chennai's coastal humidity accelerates replacement cycles from corroded aluminum frames toward UPVC weather resistance. State urban development authority mandates on fire-retardant additives are tightening for high-rise profiles. Coimbatore industrial clusters are emerging as secondary fabrication nodes.
Delhi-NCR
Noida and Gurgaon contractor networks aggregate volume for direct extrusion plant procurement, bypassing regional distributors. Municipal fire safety clearances extend product launch timelines for imported additive-dependent profiles. Ghaziabad workshops serve renovation replacement channels with minimal lead times.
India UPVC Doors and Windows Market Competitive Landscape
Capacity expansion dominates the current landscape as tier-1 fabricators deploy automated CNC lines to compress defect rates and enable just-in-time delivery contracts. The vendor base stratifies across three tiers: organized extruders with BIS certification, regional fabricators with automated welding capabilities, and non-certified workshops competing on upfront pricing. Two strategic archetypes have emerged: German-engineered technology licensors adapted for tropical climates, and domestic specialists with extensive dealer networks across South and West India. Competitive moves concentrate on geographic expansion through dealer network densification and backward integration into profile extrusion.
Among India-based fabricators, Fenesta Building Systems, Encraft India, and Koemmerling occupy distinct positioning vectors. Fenesta Building Systems exemplifies the scale-driven archetype with extensive distribution infrastructure. Encraft India represents specialized fabrication capabilities in custom architectural profiles. Koemmerling anchors the technology-licensor tier with German-engineered extrusion systems. These three collectively illustrate the competitive tension between domestic network scale and imported technical positioning.
| Leading Market Players |
|---|
| Encraft India |
| Simta Astrix |
| Fenesta Building Systems |
| PSP Dynamic Limited |
| Prominance Window Systems |
| VEKA India |
| Koemmerling |
| Lingel Windows & Doors Technologies |
| Aparna Venster |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap fabricators across Gujarat and Maharashtra anchor pricing discipline through captive extrusion capacity and long-term resin offtake agreements with Reliance and Chemplast Sanmar. Their ownership structure insulates margin targets from quarterly earnings pressure, allowing sustained investment in automated welding lines that compress per-unit conversion costs while BIS certification requirements filter out price-only competitors.
Pricing Analysis
Galvanized steel reinforcement and PVC resin pass-through clauses dominate contract structures, with zinc price volatility transmitted directly to project developers through quarterly adjustment mechanisms. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified fabricators with CNC capabilities from regional assemblers and non-certified Uttar Pradesh workshops. Pricing pressure stems from unorganized sector undercutting in replacement channels where homeowners prioritize visible finish over certified thermal performance. Affordable housing contractors exhibit highest price sensitivity, while green-certified commercial developers accept premiums for sub-2.0 W/m²K assemblies.
Supply Chain Analysis
Post-consumer profile recovery networks remain nascent, with draft urban development authority circulars on recyclability quotas forcing early movers to establish collection infrastructure ahead of mandate enforcement. Raw material dependencies center on petrochemical feedstock from Jamnagar and Hazira complexes, galvanized steel inserts from JSW and Tata Steel, and imported brominated fire-retardant compounds from Germany and China. Single-source vulnerability concentrates in specialty additive chemistry, where domestic production gaps extend lead times for high-rise compliant profiles. Distribution runs through three channels: direct extrusion plant procurement for 500-plus unit developers, regional fabricator networks for mid-scale contractors, and dealer-retail for renovation replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automation-driven conversion cost compression and specification migration toward thermal performance tiers create margin expansion headroom for positioned players. BIS IS 17037 compliance investments now differentiate sustainable returns from commodity trap exposure.
For Market Incumbents: Deepen backward integration into profile extrusion to capture resin-to-finished-goods margin stack currently surrendered to specialized extruders. Expand CNC-equipped fabrication capacity in Karnataka and Telangana to preempt Hyderabad demand growth. Defend against unorganized sector erosion by bundling installation warranties with BIS certification documentation that state housing boards now mandate. For New Entrants and Emerging Players: Launch via modular sliding door installation services targeting Mumbai and Delhi NCR compact apartment retrofits, bypassing traditional dealer networks with direct-to-contractor digital procurement platforms. Target fire-retardant additive formulation partnerships with institutional projects in Maharashtra, where import dependency creates specification bottlenecks that domestic chemistry capabilities could resolve. Prioritize technician training partnerships with Gujarat fabrication institutes to overcome skilled operator scarcity constraining capacity expansion. For Investors and Strategic Acquirers: Building material conglomerates with fenestration adjacencies represent the most active acquirer category in this space, seeking thermal envelope capabilities for integrated project offerings. Long-term viability hinges on positioning for recyclability mandate enforcement and green building certification proliferation across southern and western metro corridors. Monitor Bureau of Energy Efficiency star-labeling adoption velocity in state government housing technical sanctions as the signal for specification pull timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Extrusion | Captures resin-to-profile margin currently surrendered to specialized suppliers in Gujarat's chemical corridor. |
| CNC Fabrication Capacity Expansion | Enables just-in-time delivery contracts with Pune and Bangalore developers specifying sub-2.0 W/m²K assemblies. |
| Fire-Retardant Additive Localization | Reduces import dependency for high-rise profiles facing extended municipal clearance timelines in Maharashtra. |
| Recyclability Infrastructure Pre-positioning | Qualifies early movers for public infrastructure contracts under anticipated urban development authority recovery mandates. |
| Direct Procurement Platform Launch | Bypasses distributor margin capture in 500-plus unit residential phases across Mumbai and Bangalore. |
Research Methodology
Coverage spans Maharashtra, Gujarat, Karnataka, Tamil Nadu, and Delhi-NCR, with primary inputs from each region's fabrication clusters and construction corridors. The analysis combines structured interviews with extrusion plant technical directors, affordable housing project procurement leads, state urban development authority officials, and CNC equipment operators with secondary validation through BIS certification registries, Bureau of Energy Efficiency star-labeling disclosures, and state energy conservation building code submissions. Bottom-up profile production estimates triangulate against top-down construction sector fenestration demand modeled from affordable housing mission sanction data and green building certification pipelines.
Rate-of-change decomposition separates volume growth from value-per-unit shifts across the projection horizon. Segmentation dimensions include product configuration, application type, end-user decision authority, and panel sizing tier. CAGRs derive from installed base replacement cycles, new construction pipeline analysis, and specification migration toward multi-chamber thermal profiles. Industry-specific forecast inputs incorporate Bureau of Energy Efficiency label adoption curves and state-level energy code enforcement trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under galvanized steel price spike scenarios or accelerated fire-retardant additive import restrictions. Practitioners should monitor BIS factory audit clearance backlogs and state urban development authority circular finalization timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
EPS Sandwich Panels Market
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
Foldable Houses Market
Building & Construction Materials
Education Building Design Market
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
Household Mosaic Tiles Market
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
Mexico Oriented Strand Board Market
Building & Construction Materials
Prefabricated Building System Market
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
Cladding Systems Market
Building & Construction Materials
Windows and Doors Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Global Concrete Block and Brick Manufacturing Market
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
North Africa Cement Market